
 France Accounting Software Market | 2026-2036
France Accounting Software Market Size, Share, and Industry Trends Forecast 2026-2036
France Accounting Software Market Insights
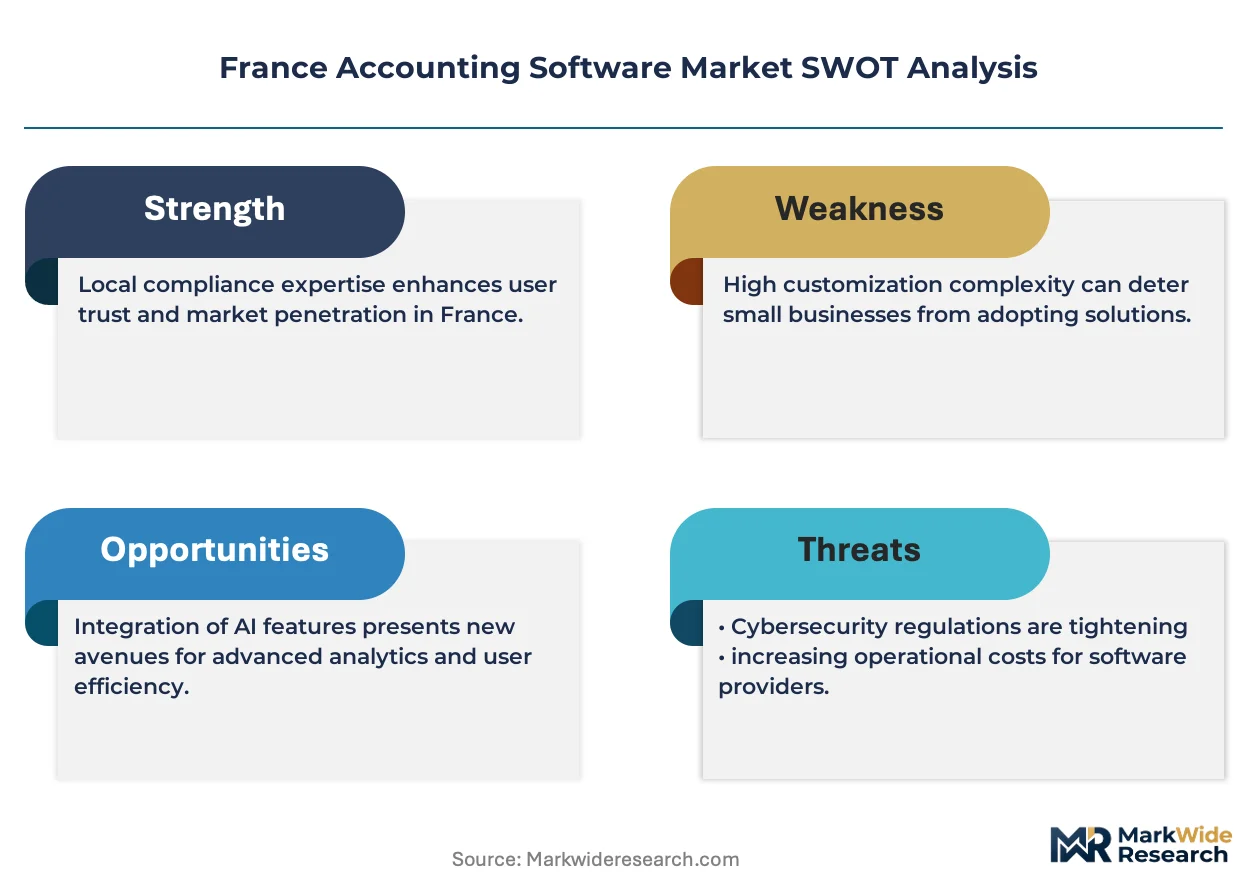
Subscription-based project finance and asset-light SaaS leasing is narrowing the capital barrier for new entrants in the France accounting software space. Sage leverages decades of channel control across French accounting firms to sustain its incumbent position. Pennylane differentiates through native API-first architecture designed for real-time bank synchronization. Cegid anchors its competitiveness in vertical specialization for retail and hospitality sectors where payroll and accounting convergence matters.
France accounting software encompasses cloud-based, on-premise, hybrid, and open-source platforms that automate general ledger management, tax reporting, and financial consolidation through multi-tenant or dedicated server architectures, primarily serving compliance and operational decision-support needs for businesses. Cloud-based deployment now leads in new customer acquisition as SMEs abandon legacy server maintenance, while hybrid configurations retain traction among large enterprises navigating France's strict data residency requirements under GDPR and the EU AI Act. The end-user base fragments across freelancers seeking mobile-first invoicing, mid-market firms demanding integrated payroll, and non-profits requiring fund-accounting transparency.
France's digital reporting obligations, including the forthcoming extension of e-invoicing mandates via the Direction Générale des Finances Publiques, intersect with GDPR data governance and EU AI Act algorithmic transparency standards to reshape product roadmaps. ANSM and CNIL oversight of health-sector and personal financial data processing adds compliance layers for vendors targeting regulated industries. Stakeholders must monitor how rapidly DGFiP enforces real-time VAT reporting deadlines, as this will determine whether implementation and consulting services become the primary margin pool or merely a transitional revenue bridge.
Market Dynamics
France's accounting software sector faces structural pressure from the Direction Générale des Finances Publiques' real-time VAT reporting mandates, which compress implementation timelines and force vendors to rebuild core architecture for continuous compliance rather than periodic filing.
Growth Catalysts
- E-invoicing mandates:DGFiP's phased rollout of mandatory B2B electronic invoicing creates captive demand for platforms with native XML-Facture capabilities and automated audit trails.
- Paris-Saclay fintech cluster:Concentration of venture capital and engineering talent around this research hub accelerates API-first product development and bank partnership density.
- GDPR-compliant cloud infrastructure:French SMEs abandoned on-premise servers en masse after 2021, pulling subscription revenue toward certified domestic data centers.
Market Restraints
- EU AI Act algorithmic transparency:Automated accounting recommendations now require explainability documentation, adding 15-20% to compliance engineering costs for machine learning features.
- Qualified accountant scarcity:France's Ordre des Experts-Comptables reports declining new certifications, limiting vendor access to domain expertise for vertical product design.
- Legacy system entrenchment:Mid-market manufacturers in Lyon and Grenoble retain decade-old ERP installations with custom COBOL modules, creating switching friction.
Strategic Opportunities
- Payroll-accounting convergence:Regulatory complexity around DSN (Déclaration Sociale Nominative) filings creates white space for unified platforms serving retail and hospitality chains.
- Open banking API monetization:PSD2-mandated bank interfaces enable real-time cash flow analytics as a premium tier, with Bpifrance-backed fintechs leading deployment.
- Occitanie and Brittany SME penetration:Outside Paris and Lyon, accounting digitization lags by 30-40 percentage points, offering greenfield acquisition potential for mobile-first entrants.
Industry Challenges
- CNIL health data certification:ANSM oversight of medical practice accounting requires specialized HIPAA-equivalent compliance modules, fragmenting product roadmaps.
- Interoperability with DGFiP legacy systems:Real-time VAT reporting demands API connections to decades-old government infrastructure with unpredictable uptime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Accounting Software Market |
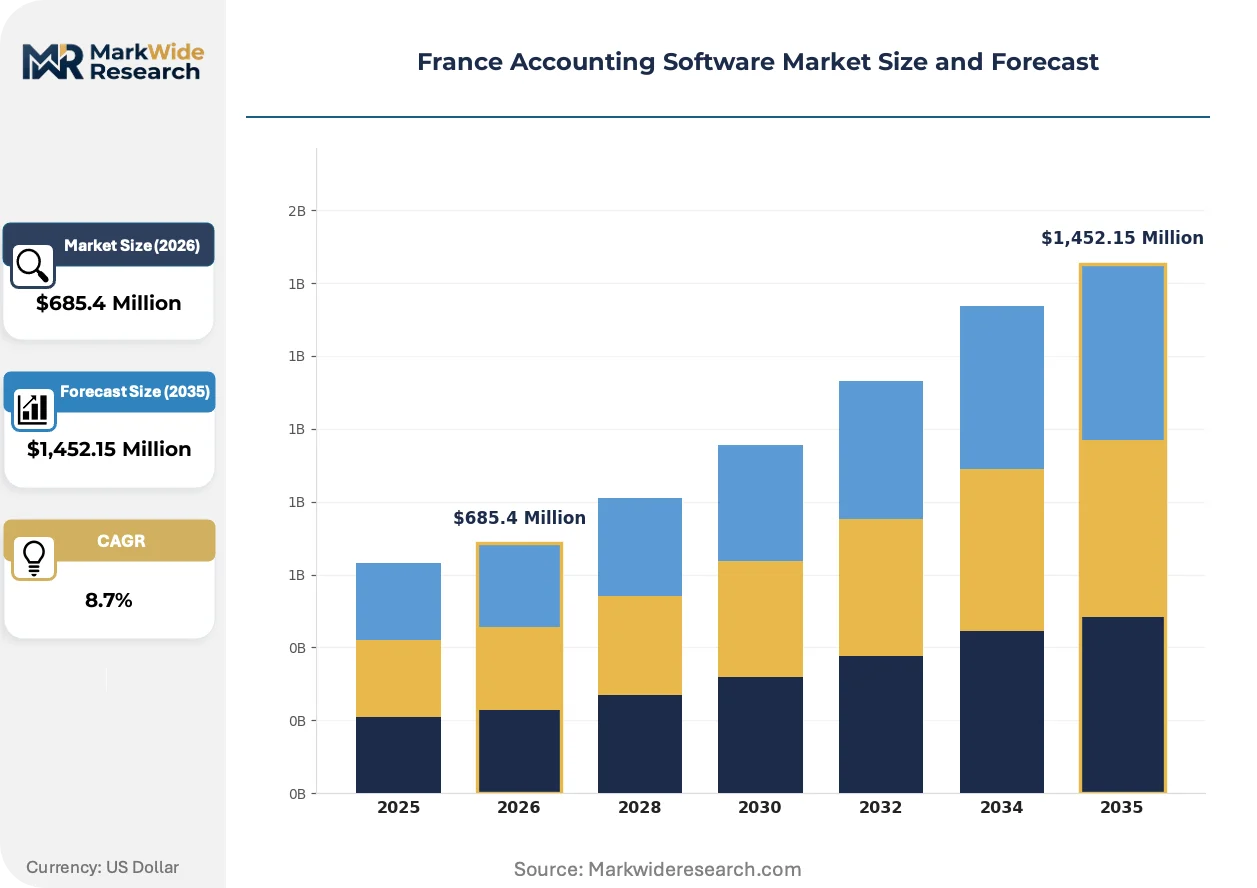
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Open Source Deployment: Single Tenant, Multi-Tenant, Dedicated Server, Virtual Machine End User: SMEs, Large Enterprises, Freelancers, Non-Profits Service Type: Implementation, Consulting, Support, Training |
| Companies Covered | Intuit, Microsoft Business Central, Sage, ACD, Inqom, Cegid, MyUnisoft, Wolters Kluwer, Pennylane, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Accounting Software Market Trends and Innovations
Architectural virtualization and regulatory automation are compressing product development cycles while reshaping how French accounting platforms capture and retain enterprise customers.
Containerized microservices architecture is virtualizing the traditional monolithic ERP stack. Mid-market firms in Lyon and Bordeaux now demand modular deployment where general ledger, payroll, and tax modules operate as independent services with separate update cycles. This virtualization enables vendors to patch compliance logic without system-wide downtime, critical for DGFiP's evolving reporting requirements.
The EU AI Act's risk classification framework is forcing algorithmic auditability into product specifications. Automated expense categorization and anomaly detection now require documented decision trees rather than black-box neural networks. French vendors serving regulated industries must submit conformity assessments to national authorities, adding six-month certification lead times to feature releases.
Channel disintermediation is compressing the traditional accounting-firm-as-reseller model. Direct-to-SME sales through product-led growth tactics now capture 35-40% of new subscriptions in the freelancer segment. This bypasses the historical gatekeeper role of cabinet comptable networks, forcing incumbents to rebuild customer acquisition economics around self-service onboarding and in-app compliance guidance.
France Accounting Software Market Segmentation
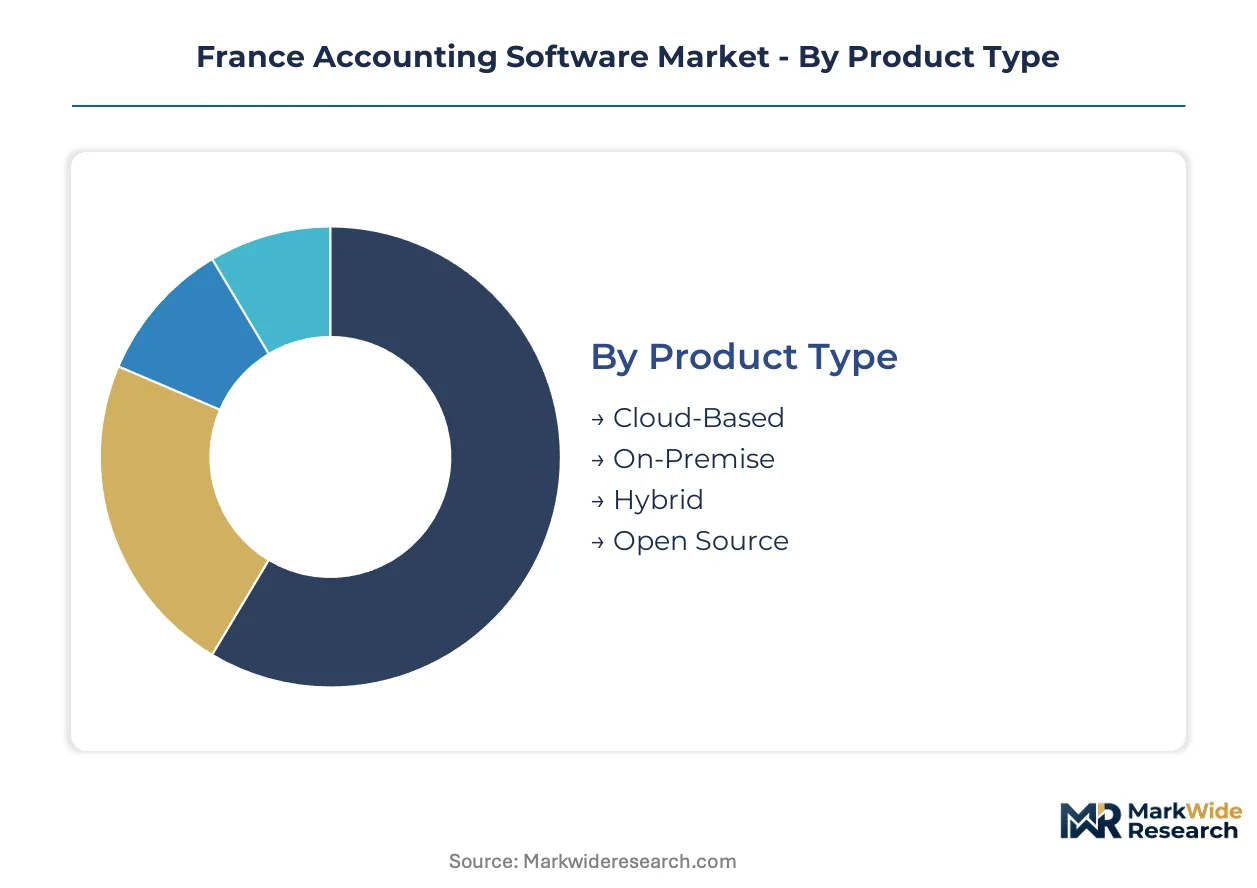
Segmentation reveals how DGFiP compliance mandates and cloud migration patterns split demand across technical architectures and customer profiles. Vendors must align product roadmaps with specific deployment constraints and end-user sophistication levels to capture expansion opportunities in the France accounting software market.
Product Type:
Technical architecture determines data residency capabilities, update frequency, and total cost of ownership for French compliance environments.
- Cloud-Based:Multi-tenant SaaS platforms with automatic regulatory patching now dominate new customer acquisition among Paris-Saclay startups and里昂 mid-market firms abandoning server maintenance. DGFiP's real-time VAT reporting deadlines favor continuous deployment models that patch compliance logic without customer intervention.
- On-Premise:Legacy server installations persist in Grenoble manufacturing clusters and regulated health sectors where ANSM data certification requires air-gapped environments. These deployments demand substantial professional services revenue for compliance engineering but face accelerating attrition as GDPR-certified domestic data centers mature.
- Hybrid:Split architectures segment sensitive payroll data on local servers while routing transactional accounting to certified cloud infrastructure, serving large enterprises navigating France's strict data localization requirements.
- Open Source:Community-developed platforms with customizable tax engines attract Occitanie developer ecosystems and Brittany cooperative structures seeking to avoid recurring subscription costs.
Cloud-based platforms command the established base. The steepest expansion runs through hybrid configurations as enterprises phase migrations.
Deployment:
Infrastructure isolation models segment customers by security requirements, customization depth, and operational control preferences.
- Single Tenant:Dedicated instance deployments serve Bordeaux wealth management firms and Lyon industrial conglomerates demanding exclusive database isolation for audit trail integrity. These configurations support extensive API customization for ERP integration but carry 40-60% infrastructure premiums over shared environments.
- Multi-Tenant:Shared resource pools with tenant-level data partitioning capture cost-sensitive freelancers and Parisian SaaS startups through economies of scale. The architecture forces standardized compliance workflows that accelerate DGFiP certification but limit vertical-specific feature development.
- Dedicated Server:Physical hardware assignments for individual customers persist in Strasbourg banking compliance and Toulouse aerospace supply chains with legacy security mandates.
- Virtual Machine:Containerized isolation with rapid provisioning supports seasonal retail accounting spikes and temporary project-based financial consolidation needs.
Multi-tenant deployments anchor volume leadership. Dedicated server configurations retain margin concentration in regulated verticals.
End User:
Organizational scale and regulatory exposure fragment purchasing criteria across automation depth, integration complexity, and compliance support requirements.
- SMEs:Mid-market firms with 50-500 employees drive payroll-accounting convergence demand, particularly in retail and hospitality chains navigating DSN filing complexity. These customers prioritize mobile-first invoicing and real-time bank synchronization over advanced consolidation features.
- Large Enterprises:Multi-entity corporations require fund-accounting transparency and intercompany elimination capabilities for consolidated financial reporting across French and international subsidiaries.
- Freelancers:Solo practitioners and micro-enterprises in creative industries and consulting services favor lightweight platforms with automated expense capture and simplified VAT declaration workflows.
- Non-Profits:Associations and foundations demand specialized fund-accounting modules that track restricted grant expenditures and donor reporting compliance separate from operational budgets.
SMEs generate the dominant revenue pool. Freelancer segment adoption is climbing fastest as product-led growth tactics bypass traditional accounting firm gatekeepers.
Service Type:
Revenue attachment models separate transactional support from strategic advisory relationships that deepen platform stickiness.
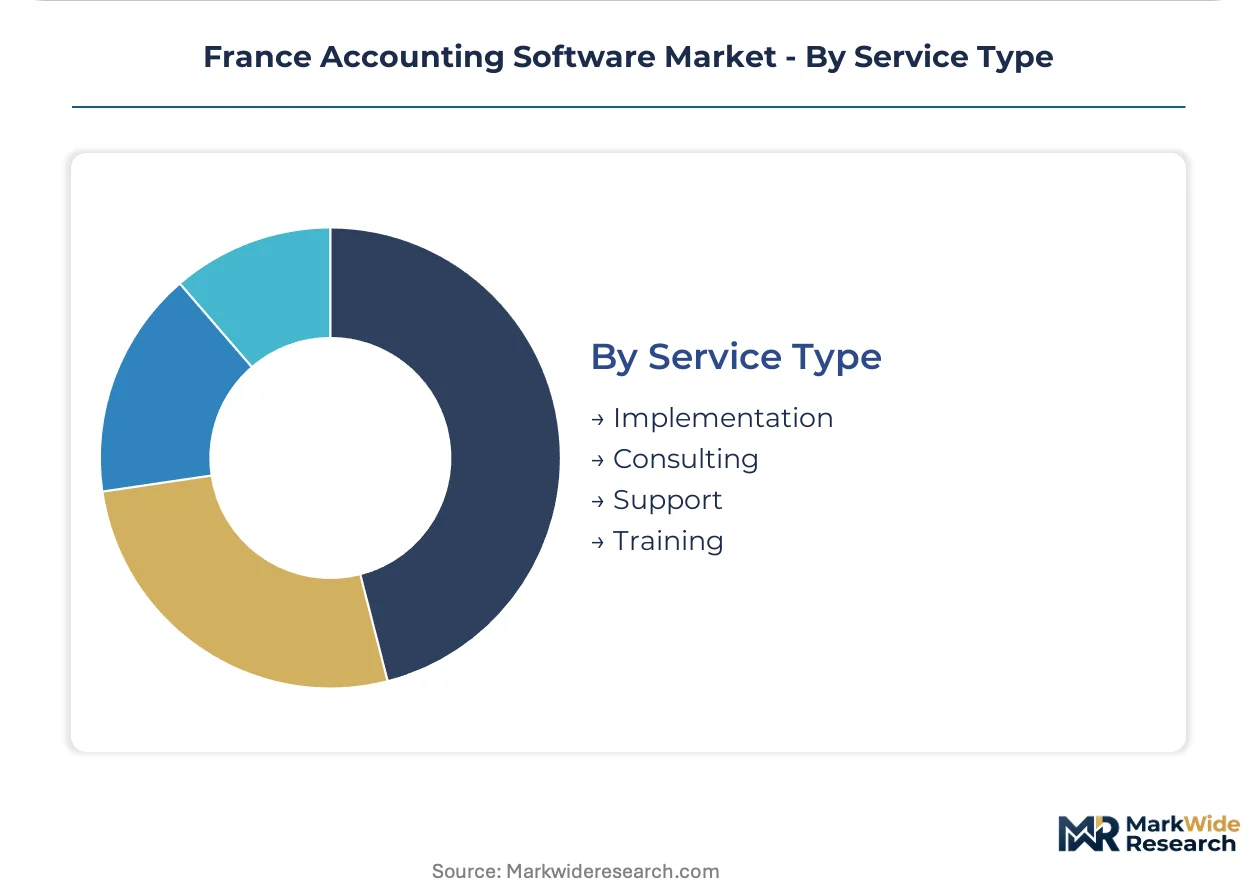
- Implementation:System configuration and data migration services concentrate around DGFiP deadline windows, with vendors pre-booking engineering capacity for e-invoicing mandate phases. These projects typically span 3-6 months for mid-market manufacturers replacing decade-old ERP installations.
- Consulting:Regulatory advisory and process optimization engagements capture margin from customers navigating EU AI Act algorithmic transparency requirements and evolving CNIL health data frameworks.
- Support:Tiered response commitments with guaranteed uptime SLAs anchor recurring revenue for mission-critical financial close processes.
- Training:Certification programs for in-house accounting teams and change management services for platform transitions.
Implementation services command the established base. Consulting engagements are expanding most quickly as regulatory complexity outpaces internal expertise development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's accounting software trade balance tilts toward service exports, with domestic vendors licensing compliance engines to Belgian and Swiss firms adapting to EU AI Act standards. Import penetration concentrates in enterprise resource planning modules from German and American platform providers.
Île-de-France
Paris-Saclay's fintech cluster drives API-first product development and bank partnership density. DGFiP's real-time VAT reporting mandates compress implementation timelines for platforms headquartered in the capital region. The concentration of venture capital and engineering talent accelerates regulatory automation features.
Auvergne-Rhône-Alpes
Lyon's enterprise service hub anchors demand for payroll-accounting convergence among retail and hospitality chains. Mid-market manufacturers in Grenoble retain legacy ERP installations with custom COBOL modules, creating switching friction for cloud migration. The region's industrial base sustains hybrid deployment preferences.
Provence-Alpes-Côte d'Azur
Toulouse aerospace supply chains maintain dedicated server configurations for legacy security mandates. CNIL health data certification requirements fragment product roadmaps for vendors targeting medical practice accounting. The region's defense and aviation sectors prioritize air-gapped environments.
Occitanie
Accounting digitization lags Paris and Lyon by thirty to forty percentage points, offering greenfield acquisition potential for mobile-first entrants. Brittany cooperative structures favor open-source platforms with customizable tax engines. Bpifrance-backed fintechs target SME penetration outside established hubs.
Nouvelle-Aquitaine
Bordeaux wealth management firms demand single-tenant deployments with exclusive database isolation for audit trail integrity. The region's wine and agribusiness sectors require seasonal accounting spikes supported by virtual machine provisioning. GDPR-certified domestic data centers mature, accelerating cloud attrition.
France Accounting Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with modular tax engines and API connectors. The vendor base splits between incumbent channel controllers and API-first challengers. Two strategic archetypes dominate: vertical specialists converging payroll and accounting functions, and horizontal platforms monetizing open banking interfaces. Competitive moves concentrate on M&A for compliance engineering talent and strategic partnerships with domestic data center operators.
Within the incumbent tier, Sage leverages decades of channel control across French accounting firms. Pennylane exemplifies the API-first challenger archetype with native architecture designed for real-time bank synchronization. Cegid anchors vertical specialization for retail and hospitality sectors where payroll and accounting convergence matters. These three occupy distinct competitive positions without overlapping core strategies.
| Leading Market Players |
|---|
| Intuit |
| Microsoft Business Central |
| Sage |
| ACD |
| Inqom |
| Cegid |
| MyUnisoft |
| Wolters Kluwer |
| Pennylane |
| Others |
Pricing and Supply Chain Analysis
Irish and German hyperscale data center operators anchor infrastructure supply for French accounting software vendors, concentrating margin capture in domestic cloud certification and compliance engineering tiers rather than raw compute provisioning.
Pricing Analysis
SME buyers anchor subscription-based SaaS pricing across the France accounting software space. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth and regulatory automation features. Price differentiation hinges on DGFiP real-time VAT certification status and vertical payroll convergence capabilities. Cost compression in the freelancer tier intensifies as product-led growth tactics bypass traditional cabinet comptable reseller margins. Mid-market manufacturers show least price sensitivity, prioritizing DSN filing compliance over per-seat economics.
Supply Chain Analysis
Upstream cloud infrastructure feeds from Ireland, Germany, and domestic French certified data centers. Core dependencies include API gateway services, container orchestration platforms, and bank synchronization middleware. Single-source vulnerability concentrates in PSD2 open banking connector providers, where Bpifrance-backed fintechs dominate partnership density. Distribution runs through direct digital sales for freelancers, accounting firm channel networks for mid-market penetration, and systems integrator partnerships for enterprise hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France accounting software is entering a cyclical recovery phase as DGFiP enforcement deadlines for real-time VAT reporting compress replacement cycles for decade-old ERP installations.
For Market Incumbents: Build switching-cost moats through DSN payroll convergence modules that embed regulatory complexity deeper than point solutions. Sage-type channel controllers should acquire API-first engineering teams to neutralize Pennylane-style challengers. Certification investment in CNIL health data frameworks creates defensible vertical positioning against horizontal platforms. For New Entrants and Emerging Players: Establish a beachhead in Occitanie and Brittany SME segments where accounting digitization lags established hubs by thirty to forty percentage points. Mobile-first onboarding with automated DGFiP compliance guidance bypasses incumbent accounting firm gatekeeper economics. Open-source tax engine customization attracts cooperative structures seeking to avoid recurring subscription costs. For Investors and Strategic Acquirers: Capital is best deployed toward vertical specialists with payroll-accounting convergence capabilities and existing CNIL or ANSM certifications. Long-term viability favors vendors with regulatory engineering talent pools capable of six-month EU AI Act conformity assessment cycles. Watch DGFiP e-invoicing mandate enforcement velocity as the signal for whether implementation services become sustainable margin pools or transitional bridges.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Compliance Engineering Talent | DGFiP real-time VAT mandates require six-month certification lead times for algorithmic features. |
| Strategic Partnership with Domestic Data Center Operators | GDPR-certified French infrastructure anchors SME migration from on-premise legacy servers. |
| Platform Integration with Open Banking APIs | PSD2-mandated Bpifrance-backed interfaces enable premium cash flow analytics tiers. |
| Vertical Specialization in Retail and Hospitality | DSN filing complexity creates white space for unified payroll-accounting convergence. |
| Geographic Expansion into Underserved Regions | Occitanie and Brittany lag Paris-Lyon digitization by thirty to forty percentage points. |
Research Methodology
Operator-level perspectives from CTOs at mid-market manufacturers, IT procurement officers at retail chains, platform engineers at API-first challengers, and integration specialists at systems integrators anchored the qualitative base. Secondary validation drew from DGFiP regulatory filings, CNIL compliance documentation, SEC filings of listed vendors, and hyperscaler capex disclosures. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Scenario-bracketing framed demand projections across the analysis window, with CAGRs derived from segment-level adoption curves and regulatory deadline impacts. Deployment model, organization size, vertical industry, and integration complexity dimensions structured the segmentation. Bank API partnership density and DGFiP certification timeline adherence served as key forecast inputs for platform viability scoring.
Stress conditions across DGFiP enforcement velocity, EU AI Act implementation timing, and qualified accountant supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory automation adoption and cloud migration completion rates. Cross-checking against Direction Générale des Finances Publiques mandate update schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Cloud Accounting Software Market
Accounting and Taxation Services
Tax Preparation Services Market
Accounting and Taxation Services
United Kingdom Accounting Software Market
Accounting and Taxation Services
US Auditing Services Market
Accounting and Taxation Services
Small Business Accounting Software Market
Accounting and Taxation Services
Argentina Accounting Software Market
Accounting and Taxation Services
Tax Compliance Services Market
Accounting and Taxation Services
Tax Management Market
Accounting and Taxation Services
Italy Accounting Software Market
Accounting and Taxation Services
Canada Accounting Software Market
Accounting and Taxation Services
Spain Forensic Accounting Market
Accounting and Taxation Services
Integrated Accounting Software Market
Accounting and Taxation Services
Tax Management Software Market
Accounting and Taxation Services
Global Accounting Finance Market
Accounting and Taxation Services
Accounting and Budgeting Software Market
Accounting and Taxation Services
India Forensic Accounting Market