
 India Accounting Professional Services Market | 2026-2036
India Accounting Professional Services Market Size, Share, and Industry Trends Forecast 2026-2036
India Accounting Professional Services Market Foresight
Maharashtra is narrowing its talent gap with dedicated accounting technology incubators in Mumbai and Pune. Deloitte India leverages its forensic accounting practice to anchor complex cross-border investigations for multinational subsidiaries. Grant Thornton Bharat sustains competitive density through mid-market corporate audit specialization across tier-two cities. TCS competes by embedding robotic process automation into compliance workflows for banking clients.
India Accounting Professional Services encompasses independent assurance of financial statements, tax computation and advisory, management consulting on financial operations, and statutory compliance management delivered by chartered accountant firms and professional services networks. Practitioners apply Indian Accounting Standards converged with IFRS, GST legislation, and the Companies Act framework to produce audit opinions, transfer pricing documentation, and regulatory filings. Audit services occupy the largest revenue pool given mandatory statutory requirements for listed and large unlisted entities under the Companies Act and SEBI regulations. Cloud-based delivery represents the fastest-expanding technology segment as MCA mandates digital submission of financial returns and tax portals demand real-time data integration.
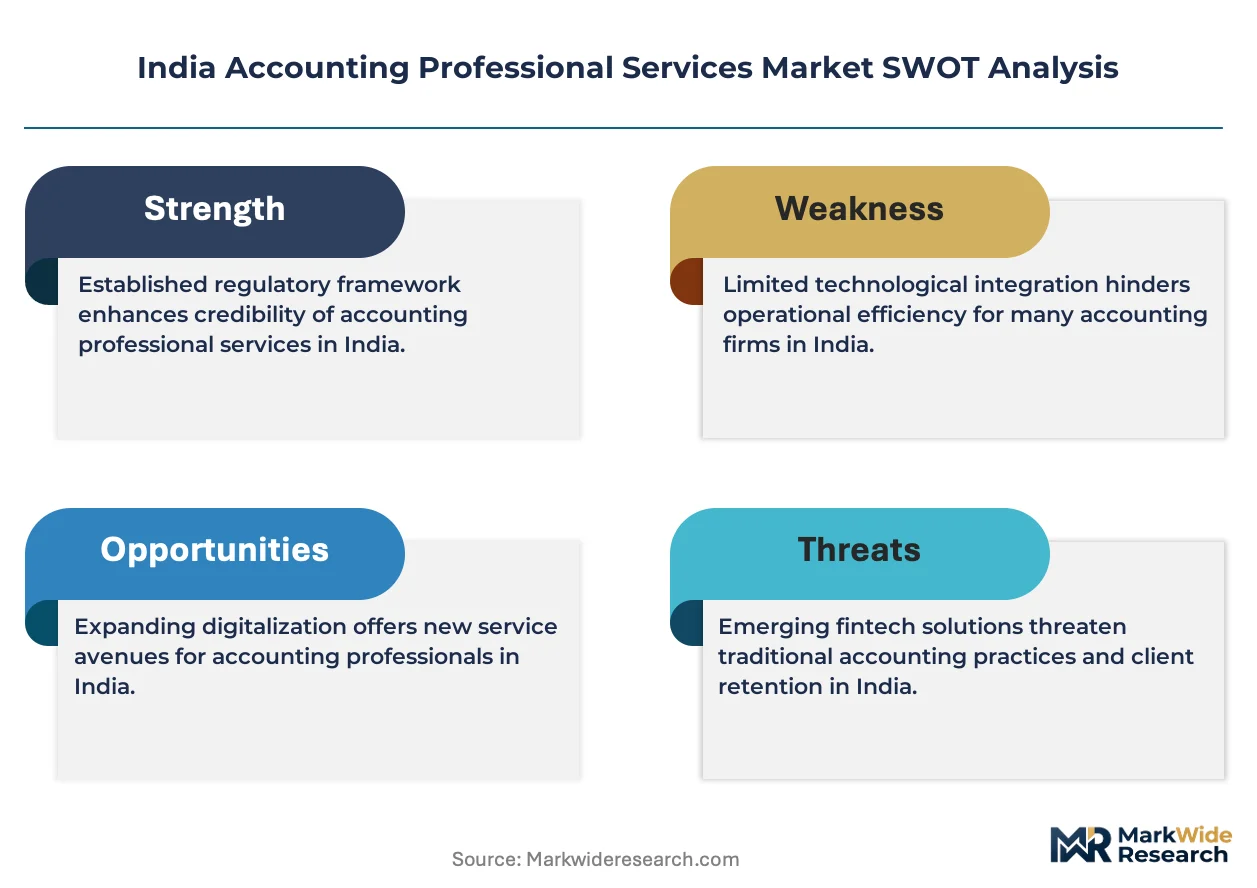
MCA, ICAI, and CBDT collectively govern market entry, ethical standards, and tax practice scope for accounting professionals in India. SEBI's LODR regulations mandate quarterly reviewer rotations and enhanced disclosure standards, directly expanding recurring audit engagement volumes. Stakeholders must monitor whether ICAI's proposed multidisciplinary firm regulations alter partnership structures and foreign firm participation rules.
Market Dynamics
MCA's XBRL mandate and GST audit expansion are compressing service delivery timelines while forcing firms to restructure talent deployment around technology-enabled workflows rather than traditional labor-intensive models.
Growth Catalysts
- Statutory Audit Mandates:SEBI's LODR regulations require quarterly reviewer rotations for listed entities, mechanically expanding recurring engagement volumes for statutory audit services.
- Cloud Compliance Infrastructure:MCA's digital submission requirements for financial returns are pulling mid-market firms toward integrated compliance platforms that bundle audit, tax, and regulatory filing functions.
- Manufacturing Outsourcing:Indian manufacturing conglomerates are externalizing internal audit and compliance functions to specialist firms as operational complexity exceeds captive capability.
Market Restraints
- Chartered Accountant Supply Bottleneck:ICAI's annual membership growth trails demand expansion, creating wage pressure that compresses margin structures for audit-heavy engagements.
- Technology Capex Burden:Cloud-based audit platforms and data analytics tools require upfront investment that disadvantages sole practitioners and small partnerships against network-affiliated competitors.
- Regulatory Fragmentation:Divergent state-level GST enforcement practices create compliance friction for firms serving clients across multiple Indian states.
Strategic Opportunities
- Tier-Two City Penetration:Audit and tax advisory services remain underdeveloped in cities like Indore, Kochi, and Chandigarh, offering first-mover positioning for mid-tier firms.
- Forensic Accounting Integration:Cross-border investigation demand from multinational subsidiaries creates premium service tiers that escape commodity pricing pressure.
- PLI Scheme Advisory:Production-linked incentive beneficiaries require transfer pricing documentation and tax optimization structuring that specialized practices can capture.
Industry Challenges
- Data Analytics Skill Scarcity:Traditional chartered accountant training inadequately prepares practitioners for AI-assisted audit sampling and anomaly detection.
- Legacy System Integration:Client ERP heterogeneity forces firms to maintain multiple data extraction protocols, inflating engagement setup costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Accounting Professional Services Market |
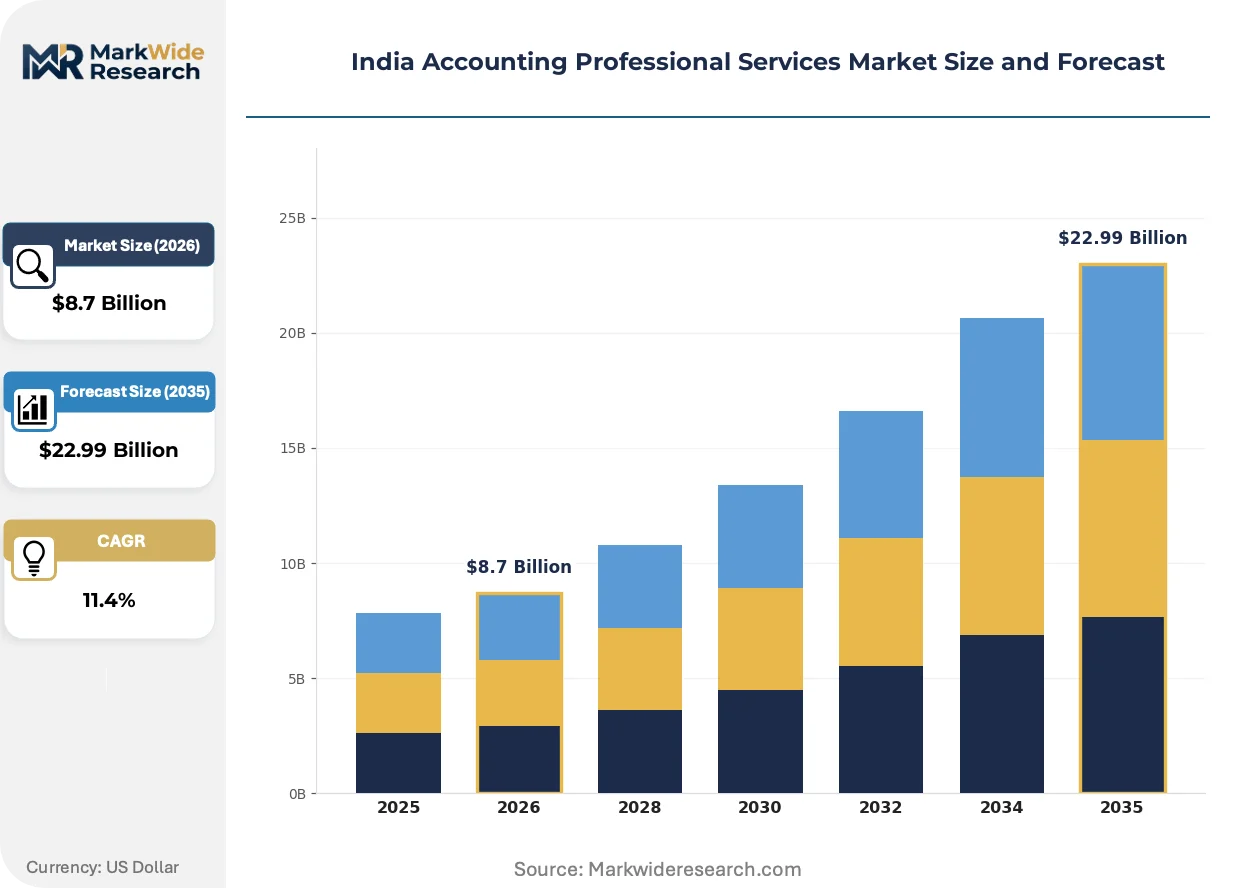
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Audit, Tax Advisory, Consulting, Compliance Client Type: Corporates, SMEs, Startups, Non-Profits Technology: Cloud-Based, On-Premises, Hybrid, Outsourced Industry Vertical: Manufacturing, Retail, Healthcare, IT |
| Companies Covered | EY (Ernst & Young) India, Genpact, Deloitte India, WNS Global Services, TCS (Tata Consultancy Services), PwC India, Grant Thornton Bharat, SS Kothari Mehta & Co, KPMG India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Accounting Professional Services Market Shifts & Advancements
Robotic process automation and machine learning are restructuring how compliance workflows execute, compressing manual review hours while elevating analytical judgment as the core value proposition.
AI-powered audit sampling is digitizing transaction-level testing for banking and financial services clients. Large private-sector banks are deploying these tools across statutory and internal audit functions within eighteen-month implementation cycles. The technology is digitizing document verification and exception flagging, reallocating senior staff hours toward judgment-intensive risk assessment.
SEBI's enhanced disclosure standards under LODR regulations are expanding quarterly review scope and documentation depth. Listed entities must now disclose granular segment-wise financials and related-party transactions with greater frequency. Mid-cap companies are responding by consolidating audit relationships with full-service networks capable of integrated assurance and advisory delivery.
Subscription-based compliance retainers are displacing project-based audit engagements among growth-stage technology companies. These firms prefer fixed-fee arrangements covering year-round GST filings, TDS compliance, and provisional tax estimates over discrete annual engagements. Bengaluru's SaaS and fintech clusters exhibit the strongest migration toward this model.
India Accounting Professional Services Market Segmentation
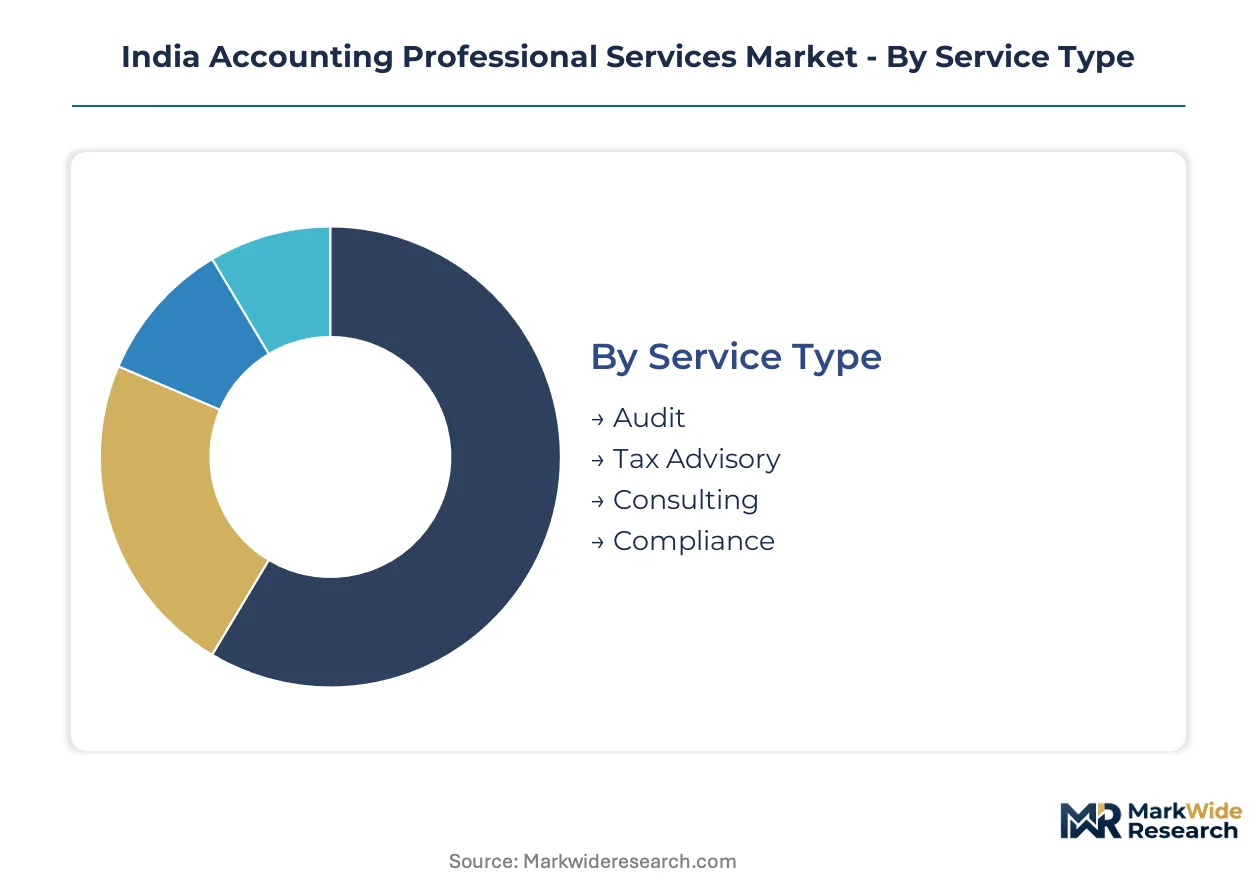
Segmentation reveals how MCA mandates and client complexity reshape service packaging across India's accounting landscape. Firms calibrate delivery models around statutory intensity, technology readiness, and vertical specialization rather than one-size-fits-all engagement structures.
Service Type:
Client needs span from mandatory statutory filings to discretionary advisory, with complexity tiers determining pricing architecture and talent deployment intensity.
- Audit:Statutory assurance of financial statements under Companies Act and SEBI LODR requirements consumes the largest revenue pool. Listed entities in Mumbai's financial district drive recurring quarterly engagement volumes through mandatory reviewer rotations.
- Tax Advisory:GST computation, transfer pricing documentation, and international tax structuring for multinational subsidiaries. Bengaluru's technology corridor generates concentrated demand for cross-border tax optimization and PLI scheme structuring.
- Consulting:Management advisory on financial operations, M&A due diligence, and forensic accounting investigations.
- Compliance:Year-round statutory filings, TDS management, and regulatory liaison with MCA and CBDT portals.
The dominant share belongs to Audit, while Tax Advisory is closing the gap fastest through GST expansion and cross-border complexity.
Client Type:
Engagement economics diverge sharply between large corporates with captive complexity and smaller entities seeking bundled, price-predictable service tiers.
- Corporates:Listed and large unlisted entities requiring integrated audit, tax, and advisory delivery under SEBI-mandated disclosure standards. Manufacturing conglomerates in Maharashtra externalize internal audit functions to specialist networks.
- SMEs:Mid-market companies adopting subscription-based compliance retainers covering GST filings, TDS compliance, and provisional tax estimates.
- Startups:Growth-stage technology companies in Bengaluru's SaaS and fintech clusters preferring fixed-fee arrangements over discrete annual engagements.
- Non-Profits:Charitable trusts and section 8 companies requiring specialized FCRA compliance and donor reporting frameworks.
Corporates anchor revenue concentration, though SMEs are expanding most quickly through cloud-based compliance platform adoption.
Technology:
Delivery infrastructure choices determine margin structure and competitive positioning against technology-enabled challengers.
- Cloud-Based:Integrated platforms enabling real-time data submission to MCA portals and automated GST return filing. TCS embeds robotic process automation into banking client workflows, compressing manual review hours.
- On-Premises:Legacy ERP-integrated audit tools maintained by conservative manufacturing clients with data sovereignty requirements.
- Hybrid:Mixed deployment combining cloud compliance submission with on-site document verification for sensitive engagements.
- Outsourced:Third-party technology partnerships allowing smaller firms to access analytics capabilities without upfront capex burden.
Cloud-Based deployment commands expanding share, while Outsourced models are climbing fastest among tier-two city practitioners seeking capability parity.
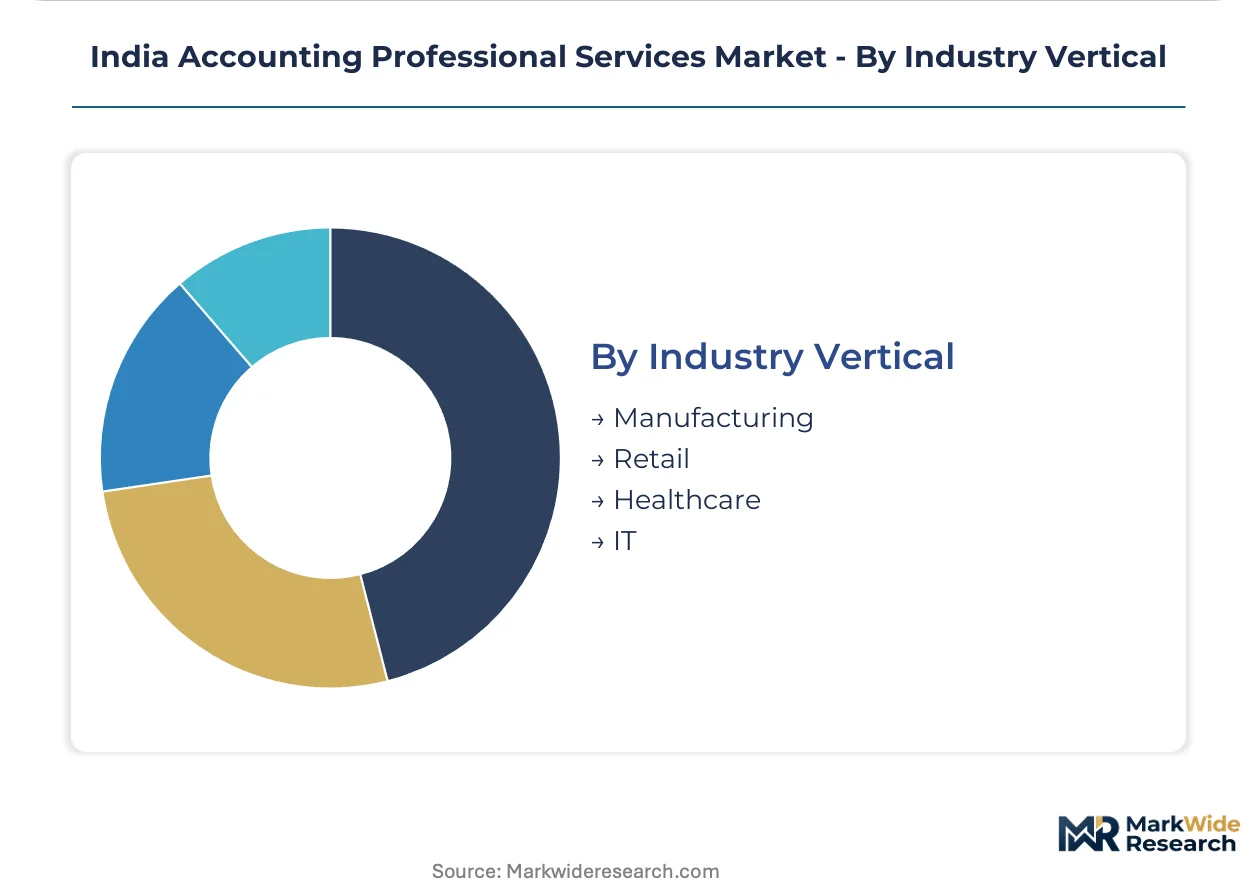
Industry Vertical:
Vertical specialization creates defensible positioning as regulatory complexity and transaction patterns diverge across sectors.
- Manufacturing:Inventory valuation, cost audit mandates, and GST input credit reconciliation for production-linked incentive beneficiaries. Indian manufacturing conglomerates drive rising demand for outsourced audit and compliance functions.
- Retail:High-velocity transaction testing, POS system integration, and multi-state GST compliance for organized retail chains.
- Healthcare:Hospital revenue recognition, pharmaceutical pricing compliance, and CDSCO-related financial disclosures.
- IT:Software revenue recognition under Ind AS 115, export incentive documentation, and SEZ unit compliance for technology service exporters.
Manufacturing retains the deepest engagement volumes, while IT is gaining share fastest through SaaS revenue recognition complexity and cross-border service delivery structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Big Four networks and domestic specialists cluster in Maharashtra and Karnataka, where regulatory density and corporate headquarters concentration create premium service demand. Tier-two cities are emerging as cost-competitive delivery nodes as firms rebalance talent deployment. State-level GST enforcement variation creates operational friction for multi-state practitioners.
Maharashtra
Mumbai's financial district hosts the deepest concentration of statutory audit mandates for listed manufacturing conglomerates and banking institutions. SEBI's LODR quarterly reviewer rotation requirements mechanically expand engagement volumes for firms with Mumbai-based signing partners. Pune's technology incubators are narrowing the analytics talent gap through dedicated accounting technology programs.
Karnataka
Bengaluru's SaaS and fintech clusters drive subscription-based compliance retainer adoption among growth-stage technology companies. The state's startup policy framework accelerates externalization of finance functions as companies prioritize capital efficiency over captive accounting teams. Whitefield and Electronic City sub-clusters concentrate demand for Ind AS 115 revenue recognition advisory.
Telangana
Hyderabad's pharmaceutical and life sciences corridor generates specialized audit demand around CDSCO-related financial disclosures and R&D tax credit documentation. The state's life sciences infrastructure policy attracts multinational subsidiary operations requiring transfer pricing documentation. Genome Valley and HITEC City house concentrated advisory relationships with export-oriented formulation manufacturers.
Gujarat
Ahmedabad and Surat industrial belts sustain demand for cost audit mandates and GST input credit reconciliation among production-linked incentive beneficiaries. The state's manufacturing incentive schemes attract textile and chemical conglomerates requiring inventory valuation expertise. GIFT City's international financial services center creates cross-border tax structuring opportunities for specialized practices.
Tamil Nadu
Chennai's automotive and electronics manufacturing base drives outsourced internal audit demand as operational complexity exceeds captive capability. The state's industrial policy framework expands statutory compliance requirements for component suppliers integrated into global supply chains. Sriperumbudur and Oragadam industrial corridors concentrate mid-market audit relationships.
India Accounting Professional Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in narrow compliance niches. The market structures around three tiers: Big Four networks with integrated audit-tax-advisory delivery, mid-tier domestic firms with sectoral specialization, and technology-enabled challengers embedding automation into workflow layers. Competitive moves concentrate on talent acquisition in tier-two cities and technology partnerships that compress manual review hours.
Among the Big Four archetype, EY India, Deloitte India, and PwC India occupy positions defined by cross-border investigation capabilities and forensic accounting depth for multinational subsidiary clients. KPMG India and Grant Thornton Bharat exemplify mid-tier competitive density through manufacturing audit specialization and tier-two city penetration. Genpact, WNS Global Services, and TCS represent technology-enabled challengers embedding robotic process automation into banking compliance workflows.
| Leading Market Players |
|---|
| EY (Ernst & Young) India |
| Genpact |
| Deloitte India |
| WNS Global Services |
| TCS (Tata Consultancy Services) |
| PwC India |
| Grant Thornton Bharat |
| SS Kothari Mehta & Co |
| KPMG India |
| Others |
Supply & Pricing Matrix
The Mumbai-Pune Expressway freight corridor carries specialized audit talent and compliance documentation between Maharashtra's financial centers, with logistics costs compressing margins for tier-two city practitioners while enabling premium pricing for Mumbai-based statutory assurance services. This infrastructure dynamic concentrates pricing power among Big Four networks with established Mumbai presence, while forcing mid-tier firms to absorb delivery cost differentials or surrender market share.
Pricing Analysis
SEBI's LODR regulations dictate the pricing tier structure across India's accounting professional services landscape. Three-tier pricing structure across premium, standard, and economy levels separates Big Four forensic and cross-border investigation practices from mid-tier manufacturing audit specialists and commodity compliance providers. Price differentiation hinges on signing partner seniority and technology-enabled delivery capabilities. Cost compression in standard-tier statutory audit engagements is intensifying because ICAI membership growth trails demand expansion, inflating wage bills. SMEs exhibit highest price sensitivity, gravitating toward subscription-based compliance retainers; multinational subsidiaries demonstrate lowest sensitivity, prioritizing forensic depth and cross-border coordination.
Supply Chain Analysis
Extended payment terms from manufacturing conglomerates and supply-chain finance facilities from banking clients are restructuring cash flow dynamics for accounting networks. Talent supply concentrates in India, with secondary sourcing from the United Kingdom and Singapore for specialized forensic and international tax expertise. Raw material dependencies include cloud infrastructure subscriptions, data analytics software licenses, and ERP integration modules. Single-source vulnerability sits with ICAI-qualified chartered accountant supply, where membership bottlenecks constrain capacity expansion. Distribution runs through partner-led relationship networks anchored in Mumbai and Bengaluru, with tier-two city coverage via satellite offices and technology-enabled remote delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's accounting professional services market represents a compelling service-attach opportunity, with cloud-based compliance platforms and subscription retainers expanding faster than traditional project-based audit engagements. Recurring revenue layers around year-round GST filings and automated TDS management are displacing discrete annual engagements among growth-stage technology companies.
For Market Incumbents: Build certification moats around SEBI LODR compliance specialization and forensic accounting credentials that emerging technology challengers cannot replicate. Defensive moves center on acquiring tier-two city boutiques to preempt mid-tier expansion, and embedding robotic process automation into banking client workflows to compress manual review hours. Threat from technology-enabled challengers like TCS and Genpact demands accelerated cloud platform investment.
For New Entrants and Emerging Players: Tier-two pharmaceutical and life sciences corridors in Hyderabad and Ahmedabad represent the most penetrable entry point, where CDSCO-related financial disclosure expertise remains underdeveloped and multinational subsidiary demand for transfer pricing documentation outstrips specialist supply. Manufacturing clusters in Tamil Nadu's Sriperumbudur corridor offer secondary white-space for outsourced internal audit functions. Go-to-market execution should anchor in sector-specific compliance complexity rather than competing on statutory audit scale.
For Investors and Strategic Acquirers: Carve-out targets emerge from domestic mid-tier networks with concentrated manufacturing audit relationships and underexploited technology infrastructure. Long-term viability over the coming decade rests on capability to bundle assurance with advisory and automate compliance workflows. Acquisition archetypes include tier-two city specialists with PLI scheme beneficiary relationships and forensic practices with cross-border investigation credentials. Signal to monitor: ICAI's proposed multidisciplinary firm regulations altering partnership structures and foreign firm participation rules.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | MCA's digital submission mandates pull mid-market firms toward bundled audit-tax-filing platforms. |
| Tier-Two City Expansion | Indore, Kochi, and Chandigarh offer first-mover positioning as audit penetration lags corporate formation. |
| Forensic Practice Acquisition | Cross-border investigation demand from multinational subsidiaries escapes commodity pricing pressure. |
| PLI Scheme Advisory Specialization | Production-linked incentive beneficiaries require transfer pricing documentation and tax optimization structuring. |
| Robotic Process Automation Deployment | TCS demonstrates workflow compression for banking clients, reallocating senior hours toward judgment-intensive risk assessment. |
Research Methodology
The analysis maps audit, tax advisory, consulting, and compliance service lines, each validated through engagement with audit partners at Big Four and mid-tier networks, CFOs at listed manufacturing conglomerates, technology company finance controllers, and MCA regulatory affairs specialists. Primary intelligence combined structured interviews with secondary validation against SEBI LODR circulars, MCA XBRL filing directives, ICAI membership statistics, and GST Council enforcement notifications. Bottom-up service-line sizing and top-down market aggregation provided triangulation.
Assumption sets held regulatory mandate timelines and technology adoption curves fixed while varying manufacturing output growth and startup formation rates across the projection horizon. Segmentation dimensions modeled encompass service type, client category, delivery technology, and industry vertical complexity. CAGRs derived from historical engagement volume trajectories and statutory expansion mechanics, with specific inputs including SEBI quarterly review rotation requirements and MCA digital filing penetration curves.
Macroeconomic conditions sit as an overlay; deviation in manufacturing capital expenditure cycles, startup funding availability, or rupee volatility against service export revenues would shift the trajectory. Forecasts assume continuity in current regulatory frameworks; ICAI structural reforms, GST rate restructuring, or SEBI disclosure standard amendments would prompt revision. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Finance and Accounting Outsourcing (FAO) Market
Accounting and Taxation Services
Bookkeeping Services Market
Accounting and Taxation Services
United Kingdom Accounting Software Market
Accounting and Taxation Services
Tax Advisory Services Market
Accounting and Taxation Services
Global Auditing Services Market
Accounting and Taxation Services
Europe Accounting Software Market
Accounting and Taxation Services
Spain Accounting Software Market
Accounting and Taxation Services
Europe Auditing Services Market
Accounting and Taxation Services
Global Accounting Finance Market
Accounting and Taxation Services
Europe Forensic Accounting Market
Accounting and Taxation Services
Tax Management Market
Accounting and Taxation Services
Saudi Arabia Forensic Accounting Market
Accounting and Taxation Services
Sales Tax Software Market
Accounting and Taxation Services
Global Fund Accounting Software Market
Accounting and Taxation Services
Accounting Software Market
Accounting and Taxation Services
China Forensic Accounting Market