
 Asia-Pacific Accounting & Budgeting Software Market | 2026-2036
Asia-Pacific Accounting & Budgeting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Accounting & Budgeting Software Market Analytics
Direct software sales through value-added resellers is fragmenting across Southeast Asia as vendors build hybrid routes combining self-service digital marketplaces with local implementation partners. SAP SE leverages its established partner certification program to sustain enterprise loyalty across manufacturing hubs in Thailand and Vietnam. Zoho Corporation Pvt. Ltd. competes aggressively on price while anchoring its growth in India's vernacular-language interface capabilities. Kingdee International Software Group Co., Ltd. dominates Greater China through deep integration with domestic banking protocols and state-owned enterprise procurement frameworks.
Asia-Pacific accounting and budgeting software encompasses modular platforms that automate general ledger consolidation, budget variance analysis, and multi-currency financial reporting through API-connected data pipelines. These systems process structured transactional data from ERP subsystems to generate statutory filings compliant with jurisdiction-specific tax codes and audit standards. Cloud-based deployment leads absolute revenue contribution as hyperscale infrastructure from Alibaba Cloud and AWS Asia-Pacific reduces latency for real-time consolidation across distributed subsidiaries. Small businesses and medium enterprises represent the fastest-expanding user type as subscription tiers below five hundred dollars annually displace spreadsheet-based bookkeeping. Within functionality segments, expense management modules capture disproportionate vendor investment due to their direct linkage with corporate card ecosystems and reimbursement automation.
India's Central Board of Direct Taxes mandates digital invoice reporting through its GST Network, forcing software vendors to maintain continuous compliance updates. China's MIIT enforces cybersecurity review requirements for financial data processing platforms, creating certification barriers for foreign-hosted solutions. Australia's Australian Taxation Office Single Touch Payroll protocol shapes product specifications for vendors serving Anglophone Pacific markets. Stakeholders must monitor evolving data residency rulings across Association of Southeast Asian Nations member states as these determine whether regional cloud hubs or in-country instances become the default architecture.
Market Dynamics
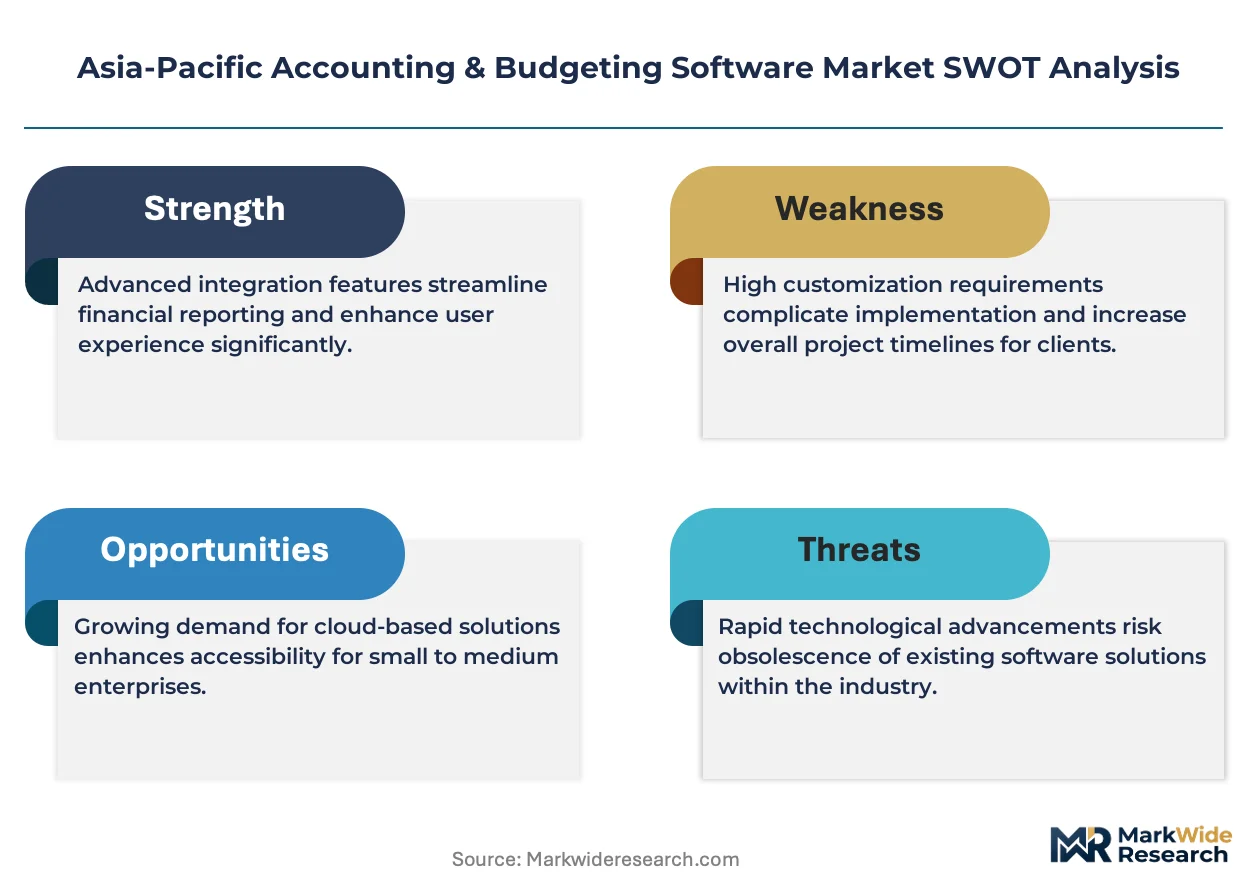
Cloud infrastructure hyperscalers are compressing deployment timelines across Southeast Asia, forcing traditional on-premise vendors to rearchitect delivery models around API-first platforms that enable real-time multi-entity consolidation.
Growth Catalysts
- GST Network Mandates:India's Central Board of Direct Taxes requires digital invoice reporting through its GST Network, compelling software vendors to build continuous compliance engines that update automatically as tax codes evolve.
- Manufacturing Hub Expansion:Thailand and Vietnam's electronics and automotive clusters are deploying integrated budgeting modules to manage multi-currency procurement across Japanese, Korean, and Chinese supplier bases.
- API-Connected Data Pipelines:Real-time general ledger consolidation through open banking interfaces is eliminating batch-processing delays that previously required end-of-month manual reconciliation.
Market Restraints
- Data Localization Requirements:China's MIIT cybersecurity review mandates create certification barriers for foreign-hosted solutions, fragmenting vendor architectures between regional cloud hubs and in-country instances.
- Implementation Talent Scarcity:Certified consultants capable of configuring multi-entity consolidation for state-owned enterprise procurement frameworks command premium rates that extend payback periods for mid-market buyers.
- Spreadsheet Persistence:Free alternatives embedded within productivity suites continue serving micro-enterprises with annual transaction volumes below statutory audit thresholds.
Strategic Opportunities
- Vernacular Interface Expansion:India's tier-2 cities present white space where Hindi, Tamil, and Telugu localizations can capture first-time digital filers migrating from manual bookkeeping.
- Expense Management Convergence:Corporate card ecosystem integration with reimbursement automation creates attach-rate expansion beyond core general ledger modules.
- ASEAN Data Residency Clarity:Pending Association of Southeast Asian Nations cross-border data flow agreements will determine whether Singapore-based regional hubs or country-specific instances become the default architecture.
Industry Challenges
- Legacy ERP Integration Complexity:Decades-old on-premise systems in Japanese and Korean manufacturing subsidiaries resist API connectivity, requiring costly middleware development for real-time consolidation.
- Continuous Compliance Engineering:Vendors must maintain dedicated teams to track Australia's Single Touch Payroll protocol updates alongside India's quarterly GST rule modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Accounting & Budgeting Software Market |
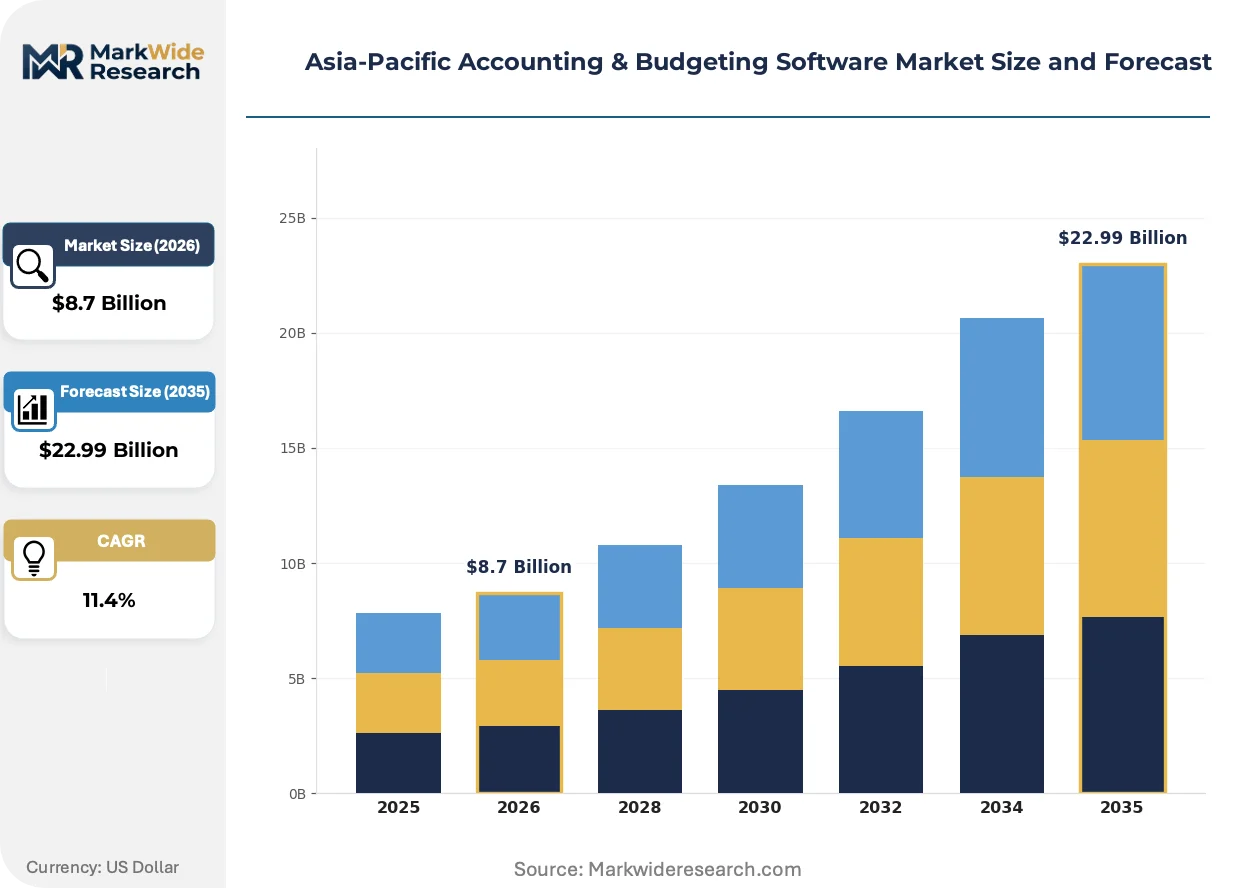
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Multi-Tenant User Type: Small Businesses, Medium Enterprises, Large Enterprises, Startups Functionality: Financial Planning, Expense Management, Forecasting, Reporting End User: Corporations, Non-Profits, Government Entities, Educational Institutions |
| Companies Covered | Kingdee International Software Group Co., Ltd., Zoho Corporation Pvt. Ltd., Sage Group plc, SAP SE, Oracle Corporation, Infor, Inc., Epicor Software Corporation, Workday, Inc., Xero, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Accounting & Budgeting Software Market Evolving Landscape
Artificial intelligence is embedding predictive capabilities directly into forecasting workflows, compressing the cycle between variance detection and budget reallocation from weeks to hours across distributed finance teams.
Embedded machine learning for anomaly detection is migrating from standalone business intelligence tools into core accounting platforms. Mid-market manufacturers in Vietnam and Thailand are adopting these capabilities fastest as they manage volatile commodity input costs. This migration is compressing the competitive window for point-solution analytics vendors that previously sold separately from ledger systems.
Australia's Single Touch Payroll protocol now mandates real-time wage reporting to the Australian Taxation Office, forcing product specification changes for vendors serving Anglophone Pacific markets. Payroll modules must now capture granular time-and-attendance data at source rather than aggregating at period-end. Small professional services firms in Sydney and Melbourne are experiencing the steepest compliance cost increases as they retrofit workflows.
Self-service digital marketplaces are displacing traditional value-added reseller relationships across Southeast Asia. Indonesian and Philippine accounting practices that previously relied on local implementation partners now purchase subscription tiers directly through vendor portals. This channel compression is most visible among sub-five-hundred-dollar annual subscriptions targeting freelance consultants and single-location retailers.
Asia-Pacific Accounting & Budgeting Software Market Segmentation
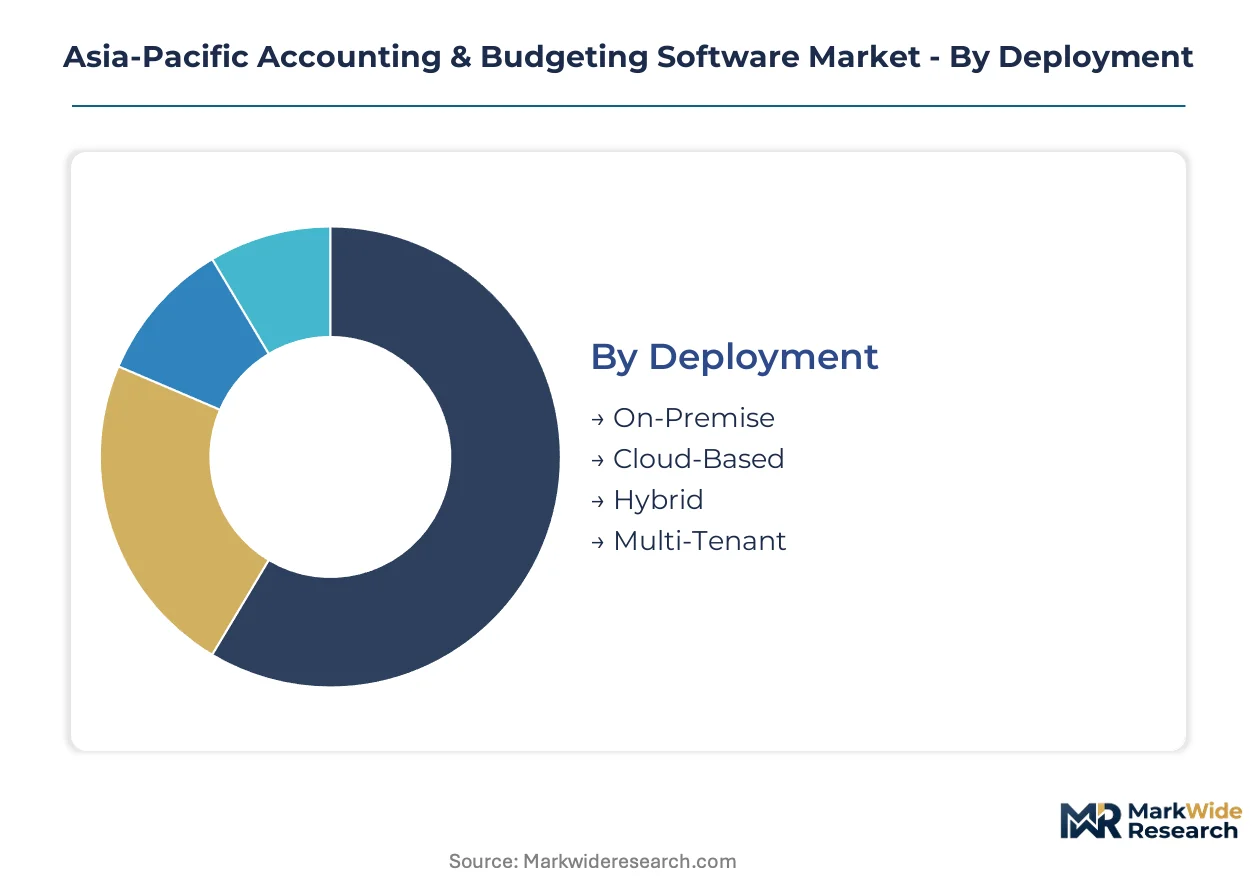
Segmentation reveals how procurement velocity varies dramatically across deployment modes and organizational scale. Cloud-based subscriptions for small businesses turn over fastest as annual renewals drive vendor switching, while on-premise installations at state-owned enterprises lock in decade-long cycles.
Deployment:
Cloud-based deployments compress sales cycles to weeks, whereas on-premise implementations extend across quarters due to infrastructure provisioning and security audits.
- On-Premise:Perpetual-license software running on customer-managed servers behind corporate firewalls. State-owned enterprises in China and defense contractors in Australia maintain these installations for air-gapped compliance with MIIT and national security protocols.
- Cloud-Based:Subscription-accessed platforms hosted on hyperscale infrastructure from Alibaba Cloud, AWS Asia-Pacific, or Tencent Cloud. Small businesses across India's tier-2 cities adopt these most aggressively as GST Network mandates force digital migration from spreadsheets.
- Hybrid:Split architectures keeping sensitive payroll data on-premise while pushing expense management to cloud tiers. Japanese automotive suppliers in Thailand deploy these configurations to satisfy parent-company data governance while enabling real-time supplier collaboration.
- Multi-Tenant:Shared infrastructure instances where multiple customers operate on logically partitioned databases. SaaS-native vendors serving Philippine freelance consultants and Indonesian micro-retailers rely on this model to hit sub-five-hundred-dollar annual price points.
On-premise systems dominate installed base across manufacturing conglomerates. Cloud-based deployment is where expansion concentrates most steeply.
User Type:
Procurement authority and implementation complexity create four distinct buying profiles with radically different sales motion requirements.
- Small Businesses:Owner-operated firms with under fifty employees purchasing through self-service marketplaces. Vietnamese family-owned manufacturers and Indian trading houses in Surat and Coimbatore represent the steepest adoption curve as vernacular-language interfaces remove literacy barriers.
- Medium Enterprises:Regional subsidiaries and standalone companies with fifty to five hundred employees requiring implementation partners. Thai electronics clusters and Malaysian palm-oil processors drive disproportionate module attach rates for expense management and multi-currency consolidation.
- Large Enterprises:Multi-entity conglomerates with dedicated IT procurement functions and security review boards. Korean chaebol manufacturing arms and Australian banking groups mandate API-first architectures for real-time subsidiary consolidation.
- Startups:Venture-funded technology companies prioritizing speed-to-live over customization. Singaporean fintech incubators and Bengaluru SaaS founders select lightweight tiers integrating directly with corporate card ecosystems.
Large enterprises anchor vendor revenue stability through multi-year commitments. Startups are climbing the fastest despite higher churn exposure.
Functionality:
Module selection follows organizational maturity, with basic ledger automation preceding predictive capabilities.
- Financial Planning:Budget construction, scenario modeling, and variance analysis tools. Australian professional services firms and Singaporean logistics operators invest here as interest rate volatility demands rolling forecast capabilities.
- Expense Management:Corporate card integration, receipt capture, and reimbursement workflow automation. This module captures disproportionate vendor R&D investment due to direct linkage with banking partnerships and employee adoption friction.
- Forecasting:Predictive algorithms consuming historical ledger data and external macroeconomic indicators. Vietnamese manufacturers managing commodity input costs adopt these capabilities fastest as margin pressure intensifies.
- Reporting:Statutory filing generation, audit trail documentation, and board presentation dashboards. Indian tier-2 city accountants prioritize GST-compliant reporting above all other functionality as enforcement tightens.
Reporting modules dominate current installed base due to regulatory compulsion. Expense management is gaining share fastest through banking ecosystem convergence.
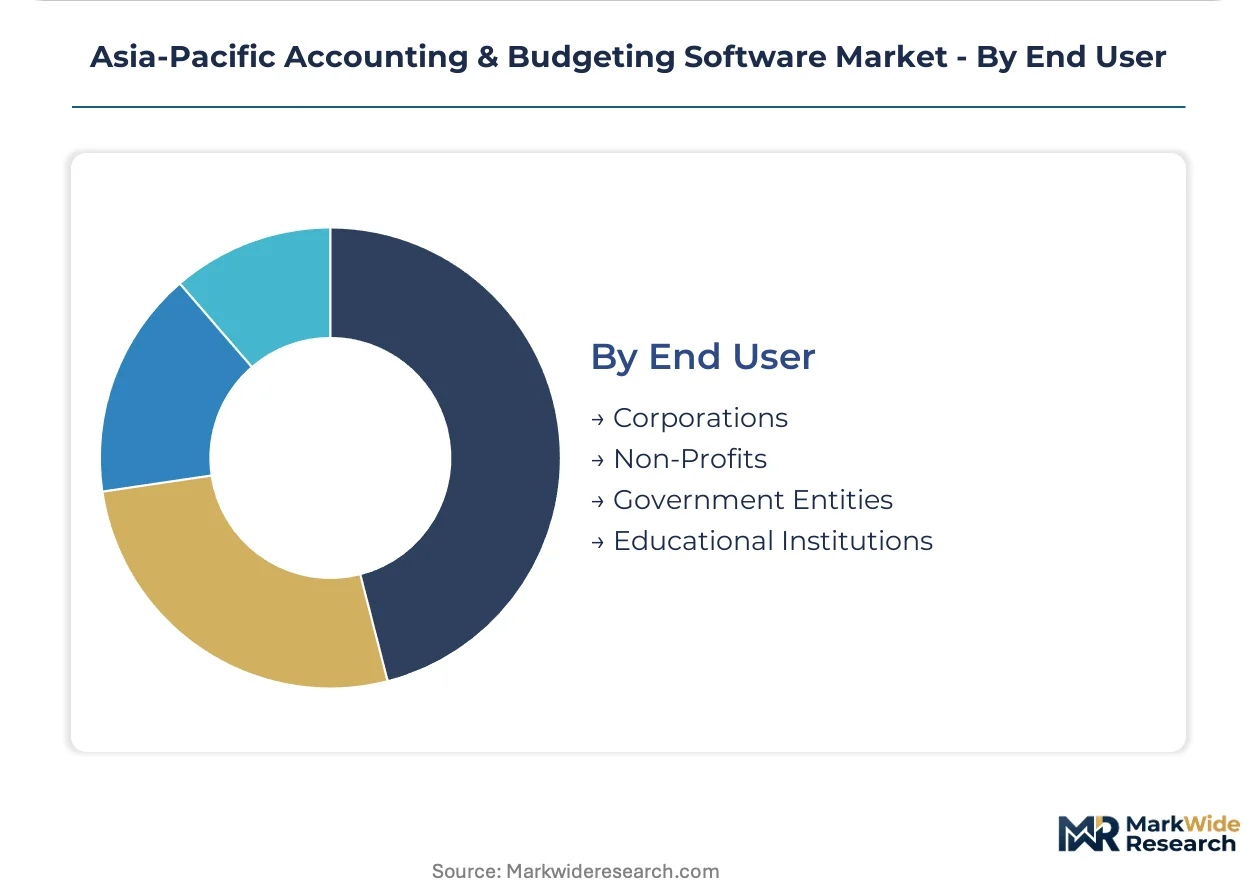
End User:
Organizational purpose shapes security requirements, approval workflows, and integration complexity.
- Corporations:For-profit entities across manufacturing, services, and technology verticals. Japanese automotive suppliers in Thailand and Korean electronics manufacturers in Vietnam drive integrated budgeting module demand for multi-currency procurement management.
- Non-Profits:Charitable foundations and international development organizations with donor reporting obligations. Australian aid organizations and Indian microfinance institutions require fund-accounting capabilities segregating restricted and unrestricted net assets.
- Government Entities:Central and provincial agencies with public procurement transparency mandates. China's state-owned enterprises and Indian public sector undertakings enforce domestic vendor preferences and data localization requirements.
- Educational Institutions:Universities and vocational training centers with grant management and student fee processing needs. Philippine private universities and Indonesian polytechnic institutes adopt cloud tiers for rapid deployment without capital expenditure approval.
Corporations anchor vendor development roadmaps through volume concentration. Government entities are expanding most quickly as digital transformation mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Asia-Pacific Submarine Cable Network carries over 99 percent of intercontinental data traffic, underwriting the region's cloud infrastructure expansion and SaaS delivery capabilities across accounting software vendors.
China
Domestic hyperscalers Alibaba Cloud and Tencent Cloud anchor data residency compliance for financial platforms under MIIT cybersecurity review mandates. Kingdee International Software Group leverages deep integration with state-owned enterprise procurement frameworks across manufacturing hubs in Shenzhen and Dongguan. The Yangtze River Delta concentration of electronics exporters demands multi-entity consolidation tools for Japanese and Korean supplier management.
India
GST Network digital invoice reporting requirements compel continuous compliance engineering from software vendors serving tier-2 cities. The Central Board of Direct Taxes mandates real-time tax filing integration, accelerating cloud migration among Surat diamond traders and Coimbatore textile manufacturers. Vernacular-language interfaces in Hindi, Tamil, and Telugu remove literacy barriers for first-time digital adopters.
Japan
METI industrial digitization incentives support manufacturing subsidiary deployment of hybrid cloud architectures. Automotive suppliers in Nagoya and Osaka resist API connectivity with decades-old on-premise ERP systems, requiring costly middleware development. Parent-company data governance requirements force split configurations keeping sensitive payroll data on-premise.
Australia
The Australian Taxation Office Single Touch Payroll protocol mandates real-time wage reporting, reshaping product specifications for Anglophone Pacific vendors. Sydney and Melbourne professional services firms face steep compliance cost increases from granular time-and-attendance capture requirements. Payroll modules must now process source-level data rather than period-end aggregates.
Vietnam
Electronics and automotive clusters in Ho Chi Minh City and Hanoi deploy integrated budgeting modules for multi-currency procurement across Chinese, Japanese, and Korean supplier bases. Manufacturing hub expansion drives disproportionate adoption of machine learning-enabled forecasting for volatile commodity input cost management. Vietnamese family-owned enterprises represent the steepest adoption curve for vernacular-interface cloud tiers.
Asia-Pacific Accounting & Budgeting Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with modular APIs. The vendor base concentrates around three structural tiers: multinational enterprise suites, regional cloud-native platforms, and vertical specialists. Two dominant competitive moves are reshaping positioning—API-first architectural rewrites for real-time consolidation, and vernacular localization investments for tier-2 city penetration.
Within the enterprise platform tier, SAP SE and Oracle Corporation occupy positions defined by manufacturing hub presence and state-owned enterprise certification depth. Zoho Corporation Pvt. Ltd. exemplifies the regional cloud-native archetype through aggressive price positioning and India's vernacular-language interface capabilities. Kingdee International Software Group Co., Ltd. anchors the domestic China specialist position through banking protocol integration and SOE procurement framework alignment.
| Leading Market Players |
|---|
| Kingdee International Software Group Co., Ltd. |
| Zoho Corporation Pvt. Ltd. |
| Sage Group plc |
| SAP SE |
| Oracle Corporation |
| Infor, Inc. |
| Epicor Software Corporation |
| Workday, Inc. |
| Xero |
| Others |
Value Network & Pricing Analysis
Bengaluru's SaaS engineering clusters anchor capacity for cloud-native accounting platforms, compressing development costs and enabling aggressive subscription pricing that undercuts legacy on-premise vendors across Southeast Asian markets. This supply concentration grants regional cloud providers pricing power against multinational suites while forcing incumbent rearchitecting around API-first delivery models.
Pricing Analysis
Volume-discount tiering structures dominate, with three-tier pricing separating enterprise multi-entity deployments from mid-market bundled suites and sub-five-hundred-dollar annual subscriptions for micro-businesses. Price differentiation rests on vernacular-language interface depth and GST Network compliance certification grade. Cost compression in the startup tier is intensifying as Zoho Corporation and local competitors race for India's tier-2 city first-time digital filers. Small businesses exhibit highest price sensitivity, while state-owned enterprises prioritize data localization certification over subscription cost.
Supply Chain Analysis
Contract-manufacturing concentration sits with hyperscale infrastructure providers: Alibaba Cloud, AWS Asia-Pacific, and Tencent Cloud hold dominant capacity for SaaS delivery across the region. Software development draws from engineering talent pools in India, Vietnam, and the Philippines, with implementation consulting anchored in Singapore and Sydney. Single-source vulnerability runs through China's MIIT cybersecurity review mandates that fragment architectures between regional hubs and in-country instances. Distribution runs through self-service digital marketplaces displacing traditional value-added reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as India's GST Network mandates force digital migration from spreadsheets among tier-2 city enterprises previously below statutory audit thresholds.
For Market Incumbents: Harden API-first architectural moats against cloud-native challengers by accelerating real-time multi-entity consolidation capabilities. Invest in continuous compliance engineering teams to track India's quarterly GST rule modifications alongside Australia's Single Touch Payroll protocol updates. Vertical integration into vernacular-language interface development protects against Zoho Corporation's aggressive tier-2 city penetration. For New Entrants and Emerging Players: Mid-market manufacturers in Vietnam's electronics clusters represent the most penetrable entry point, with volatile commodity input cost management creating attach-rate expansion for machine learning-enabled forecasting modules. Indonesian freelance consultants and Philippine micro-retailers offer white space through multi-tenant SaaS delivery at sub-five-hundred-dollar annual price points. Go-to-market execution should prioritize direct digital marketplace presence over traditional reseller channel cultivation. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate software divisions lacking cloud-native rearchitecting capabilities. Long-term viability favors vendors with demonstrated continuous compliance engineering infrastructure and hyperscaler partnership depth. Watch for MIIT cybersecurity review mandate expansion into additional Association of Southeast Asian Nations member states as inflection signal for regional cloud hub versus in-country instance architecture decisions.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Real-time multi-entity consolidation compresses month-end close cycles for Thai manufacturing subsidiaries. |
| Vernacular Interface Expansion | Hindi, Tamil, and Telugu localizations capture Surat diamond traders migrating from manual bookkeeping. |
| Strategic Partnership with Hyperscalers | Alibaba Cloud and AWS Asia-Pacific infrastructure partnerships reduce latency for distributed subsidiaries. |
| Acquisition of Compliance Specialist Firm | GST Network engineering capabilities accelerate India's tier-2 city penetration against spreadsheet persistence. |
| Geographic Expansion into Vietnam | Ho Chi Minh City electronics clusters drive integrated budgeting module demand for multi-currency procurement. |
Research Methodology
Desk research of regulatory filings from India's Central Board of Direct Taxes, China's MIIT guidance documents, and hyperscaler infrastructure disclosures preceded structured interviews with SaaS product managers, enterprise IT procurement officers, channel implementation partners, and compliance engineering leads. Secondary validation drew from vendor pricing documentation, SEC filings for listed competitors, and ASEAN cross-border data flow policy drafts. Bottom-up subscription volume estimates triangulated against top-down market sizing from cloud infrastructure spend allocations.
Assumptions held fixed include current GST Network reporting protocols, existing MIIT cybersecurity review scope, and prevailing hyperscaler regional hub configurations. Variables tested across the analysis window encompass ASEAN data residency agreement finalization, vernacular-language interface adoption curves, and expense management module attach rates. Segmentation modeling incorporated deployment mode, organizational scale, functionality tier, and end-user vertical. CAGRs derived from logistic diffusion curves fitted to cloud migration penetration patterns, with inputs from API connectivity adoption in Japanese manufacturing subsidiaries and real-time payroll reporting compliance cost trajectories.
Practitioners should monitor India's GST rule modification frequency, China's MIIT cybersecurity review expansion scope, and ASEAN cross-border data flow agreement negotiations for early signals of architectural preference shifts. Forecasts reflect these assumptions alongside continuous compliance engineering cost trajectories and hyperscaler pricing dynamics. Quarterly review of vendor product roadmap disclosures and regulatory filing update cadences is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Saudi Arabia Forensic Accounting Market
Accounting and Taxation Services
Europe Accounting Software Market
Accounting and Taxation Services
Germany Accounting Software Market
Accounting and Taxation Services
South Korea Accounting & Budgeting Software Market
Accounting and Taxation Services
Forensic Accounting Market
Accounting and Taxation Services
South Korea Accounting Software Market
Accounting and Taxation Services
China Forensic Accounting Market
Accounting and Taxation Services
South Korea Forensic Accounting Market
Accounting and Taxation Services
Japan Accounting Software Market
Accounting and Taxation Services
Global Fund Accounting Software Market
Accounting and Taxation Services
Tax Software Market
Accounting and Taxation Services
UK Forensic Accounting Market
Accounting and Taxation Services
Italy Forensic Accounting Market
Accounting and Taxation Services
Bookkeeping Services Market
Accounting and Taxation Services
Integrated Accounting Software Market
Accounting and Taxation Services
Global Accounting Finance Market