
 Tourism Security Market | 2026-2036
Tourism Security Market Size, Share, and Industry Trends Forecast 2026-2036
Tourism Security Market Analytics
The Middle East is narrowing its reliance on imported security architecture as domestic sovereign wealth vehicles fund local command center build-outs. GardaWorld leverages its protective services heritage to anchor government-adjacent contracts across the Gulf Cooperation Council corridor. Constellis sustains competitive positioning through specialized risk assessment protocols for high-threat travel zones. Securitas AB dominates European hospitality security outsourcing through standardized service-level frameworks.
Tourism security encompasses the integrated systems, personnel protocols, and surveillance technologies deployed to protect travelers, hospitality assets, and transport infrastructure from criminal, terrorist, and operational threats, typically operating across 24/7 monitoring cycles with sub-second alert thresholds. Its primary commercial purpose centers on liability reduction, brand protection, and regulatory compliance for travel-dependent enterprises. Surveillance services command the largest revenue share within service type segmentation due to persistent staffing costs and equipment refresh cycles. AI surveillance within the technology dimension represents the fastest-expanding margin pool as computer vision vendors displace legacy analog review workflows. Cloud-based deployment models are capturing share from on-premise installations among mid-market hotel chains seeking capital expenditure flexibility.
The EU AI Act imposes conformity assessment obligations on biometric surveillance vendors serving European hospitality and transport clients, while GDPR data processing agreements constrain cross-border passenger data flows. The UAE's MOHAP and federal security frameworks mandate specific staff-to-guest ratios and perimeter hardening standards for new tourism developments. Stakeholders must weigh sovereign content requirements against interoperability standards when selecting technology partners for multi-jurisdiction portfolios.
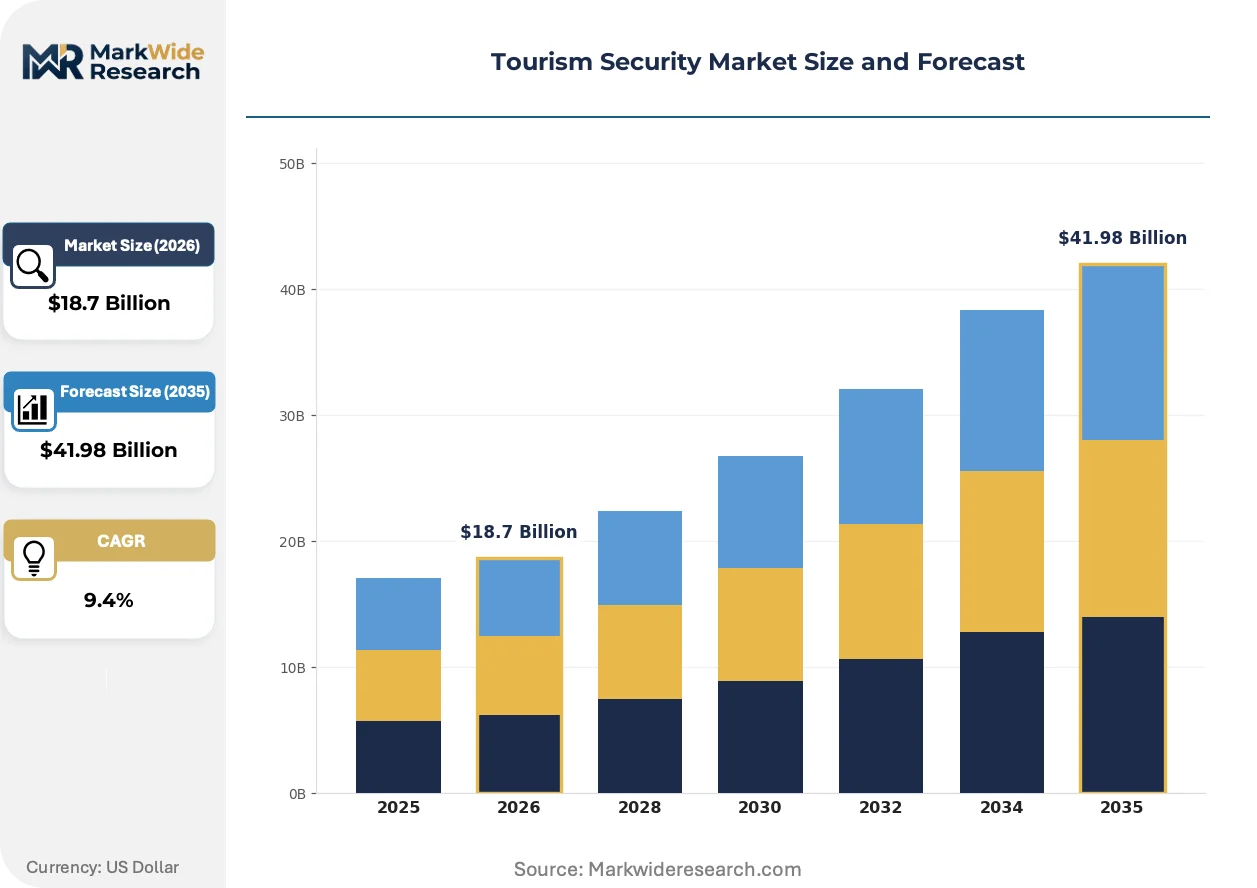
Market Dynamics
Computer vision vendors are virtualizing legacy analog surveillance review workflows across hospitality and transport infrastructure, compressing alert response times while forcing legacy equipment refresh cycles among mid-market hotel chains seeking capital expenditure flexibility.
Growth Catalysts
- EU AI Act conformity assessments:Biometric surveillance vendors serving European hospitality clients face mandatory certification requirements, accelerating compliant product development pipelines and creating vendor consolidation incentives.
- UAE sovereign tourism mandates:Federal security frameworks and MOHAP staffing ratio requirements for new developments are standardizing protective service procurement across mega-event infrastructure build-outs.
- Cloud deployment flexibility:Mid-market hotel chains are migrating from on-premise installations to subscription-based security operations, reducing upfront capital barriers and expanding addressable vendor pools.
Market Restraints
- GDPR cross-border data friction:Passenger biometric data processing agreements constrain centralized monitoring architectures, fragmenting vendor service delivery models across European jurisdictions.
- Specialized personnel scarcity:Protective services command centers require cleared staff with hospitality-specific threat assessment training, creating recruitment bottlenecks in Gulf Cooperation Council corridors.
- Equipment refresh cost concentration:Surveillance services carry persistent hardware replacement cycles, pressuring operating margins for outsourced security providers serving price-sensitive independent hotel operators.
Strategic Opportunities
- Southeast Asia luxury expansion:Protective service procurement is accelerating among hospitality chains building integrated resort complexes in Vietnam and Indonesia, creating first-mover positioning for vendors with regional command center infrastructure.
- AI-biometric convergence:Computer vision vendors integrating facial recognition with behavioral analytics are capturing premium pricing from high-threat travel zone operators seeking sub-second alert thresholds.
- Performance-based contracting:Sovereign wealth-funded developments in the United Arab Emirates are piloting outcome-linked security service agreements, shifting vendor compensation from fixed fees to incident prevention metrics.
Industry Challenges
- Interoperability standard gaps:Multi-jurisdiction hotel portfolios face integration friction between sovereign content-mandated systems and global brand security protocols, complicating centralized threat monitoring architectures.
- Biometric data governance complexity:Vendors must maintain parallel compliance frameworks across EU AI Act conformity assessments, GDPR processing agreements, and UAE federal security certifications, stretching legal and engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tourism Security Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Surveillance, Access Control, Risk Assessment, Threat Management Technology: Biometrics, GPS Tracking, AI Surveillance, Mobile Apps End User: Hotels, Travel Agencies, Tour Operators, Transportation Services Deployment Model: Cloud-Based, On-Premise, Hybrid, Managed Services |
| Companies Covered | Control Risks, GardaWorld, Constellis, Triple Canopy, International SOS, G4S, Allied Universal, Securitas AB, Pinkerton Consulting & Investigations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tourism Security Market Evolving Landscape
Three distinct vectors are compressing procurement cycles and reconfiguring vendor competitive advantage: virtualization of physical security operations, tightening biometric governance frameworks, and outcome-based contracting models displacing traditional service-level agreements.
Edge-based computer vision analytics is virtualizing centralized monitoring workflows by processing threat detection at camera nodes rather than transmitting feeds to command centers. Large hospitality chains with distributed property portfolios are deploying these systems fastest, reducing bandwidth costs and enabling real-time response without geographic concentration of analyst staff. This virtualization is compressing the market for traditional video review services while elevating demand for edge hardware maintenance and algorithm retraining contracts.
The EU AI Act imposes conformity assessment obligations on biometric surveillance vendors before deployment in European transport and hospitality environments. Industrial consequence includes mandatory documentation of training data provenance and algorithmic bias testing, extending product launch timelines by 8-14 months for non-compliant vendors. Airport operators and high-speed rail authorities in France, Germany, and the Netherlands are responding by consolidating vendor relationships with established European certification holders, marginalizing newer market entrants lacking notified body relationships.
Buyer contracting preferences are rotating from fixed-fee protective services toward incident-prevention performance guarantees. Large resort developers in the United Arab Emirates and Saudi Arabia are piloting contracts where vendor compensation ties directly to measurable security outcomes rather than guard-hours deployed. This rotation is most visible among sovereign wealth-funded mega-projects where liability exposure from security incidents exceeds service cost optimization as a procurement priority, compressing margins for traditional staffing-heavy operators while rewarding technology-integrated providers with predictive analytics capabilities.
Tourism Security Market Segmentation
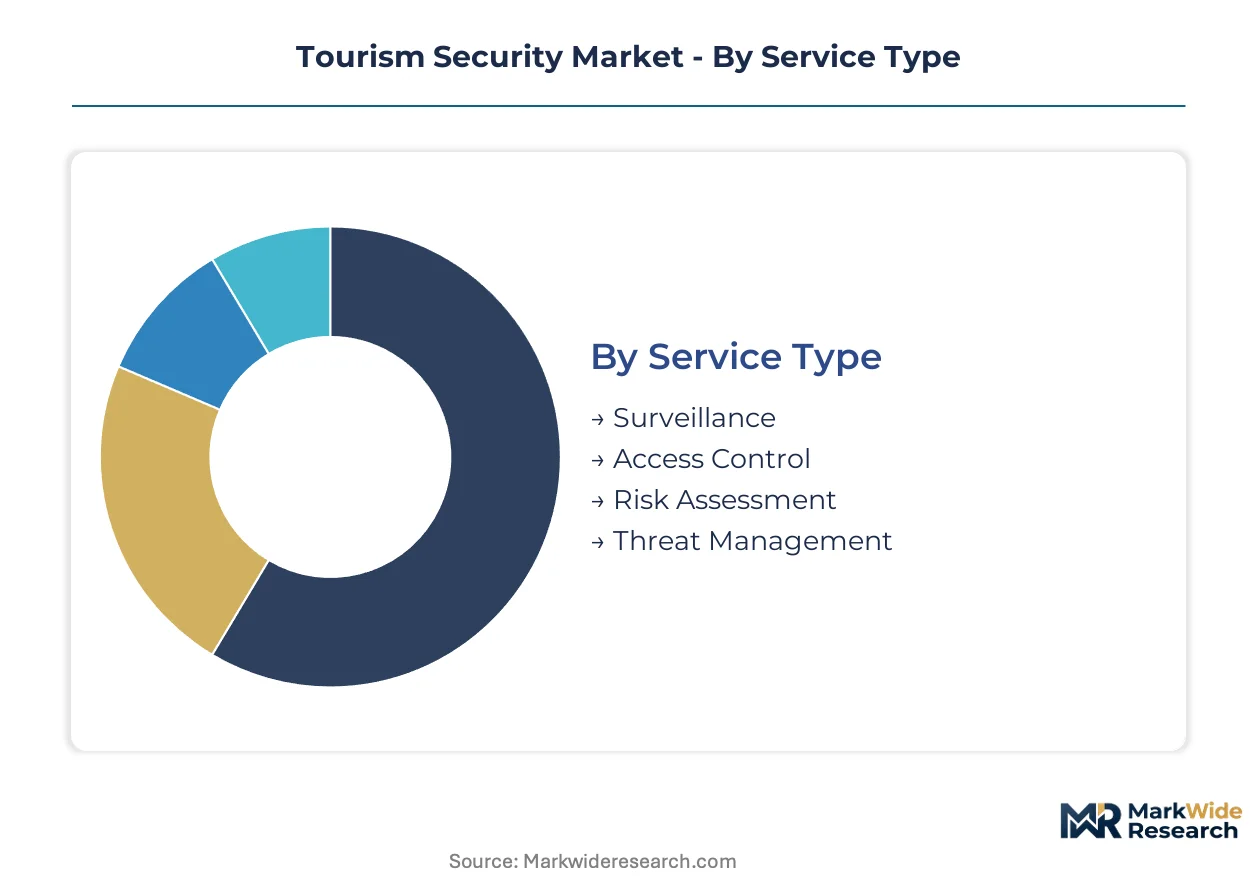
Tourism security procurement varies sharply by operational scale and threat exposure, with luxury hospitality chains prioritizing integrated surveillance systems while independent operators favor modular service bundles. Understanding these segment boundaries clarifies where technology vendors can command premium pricing versus where cost optimization dominates purchasing decisions.
Service Type:
Protective service procurement spans discrete operational functions from perimeter monitoring to crisis response, with each service tier carrying distinct staffing models and capital intensity profiles.
- Surveillance:Continuous visual monitoring through camera networks and command center operations requires persistent hardware refresh cycles and 24/7 analyst staffing. Demand concentrates among UAE mega-event infrastructure developments where MOHAP mandates specific staff-to-guest ratios and perimeter hardening standards for new tourism assets.
- Access Control:Credential verification systems and physical entry management encompass biometric readers, keycard infrastructure, and visitor screening protocols. Procurement is accelerating across Southeast Asia luxury resort complexes in Vietnam and Indonesia as integrated developments seek standardized protective frameworks across multiple property types.
- Risk Assessment:Pre-travel threat evaluation and destination security profiling for corporate and high-net-worth traveler segments.
- Threat Management:Active crisis response coordination including evacuation protocols and liaison with local law enforcement.
The dominant share belongs to Surveillance, while Access Control is closing the gap fastest as biometric infrastructure becomes standard in new hospitality developments.
Technology:
Technology selection hinges on regulatory compliance burden versus operational efficiency gains, with European operators facing stricter conformity requirements than Gulf-based counterparts.
- AI Surveillance:Computer vision systems processing threat detection at camera nodes compress alert response times while reducing bandwidth costs for distributed property portfolios. Edge-based analytics are displacing legacy analog review workflows across mid-market hotel chains seeking capital expenditure flexibility through subscription-based security operations.
- Biometrics:Facial recognition and behavioral pattern identification systems face EU AI Act conformity assessment obligations before European deployment. Airport operators in France, Germany, and the Netherlands are consolidating vendor relationships with established certification holders, extending product launch timelines for non-compliant market entrants.
- GPS Tracking:Real-time location monitoring for traveler safety and asset recovery in remote or high-threat destinations.
- Mobile Apps:Guest-facing safety alerts and direct communication channels with protective services command centers.
AI Surveillance captures the largest technology investment share, though Biometrics is expanding most quickly where regulatory frameworks permit rapid deployment.
End User:
Buyer sophistication ranges from sovereign wealth-funded mega-projects with outcome-based contracting preferences to independent operators prioritizing fixed-fee service predictability.
- Hotels:Property-specific protective services spanning guest safety, asset protection, and brand reputation management. Cloud-based deployment models are capturing share from on-premise installations among mid-market chains seeking to reduce upfront capital barriers.
- Transportation Services:Airports, rail authorities, and cruise operators with centralized monitoring requirements and cross-border passenger data flows. GDPR processing agreements constrain centralized architectures, fragmenting vendor service delivery models across European jurisdictions.
- Travel Agencies:Pre-trip advisory services and traveler tracking for corporate account management.
- Tour Operators:On-ground protective accompaniment and route security for group travel in emerging destinations.
Hotels retain the largest end-user share, while Transportation Services is gaining ground fastest as airport biometric modernization accelerates.
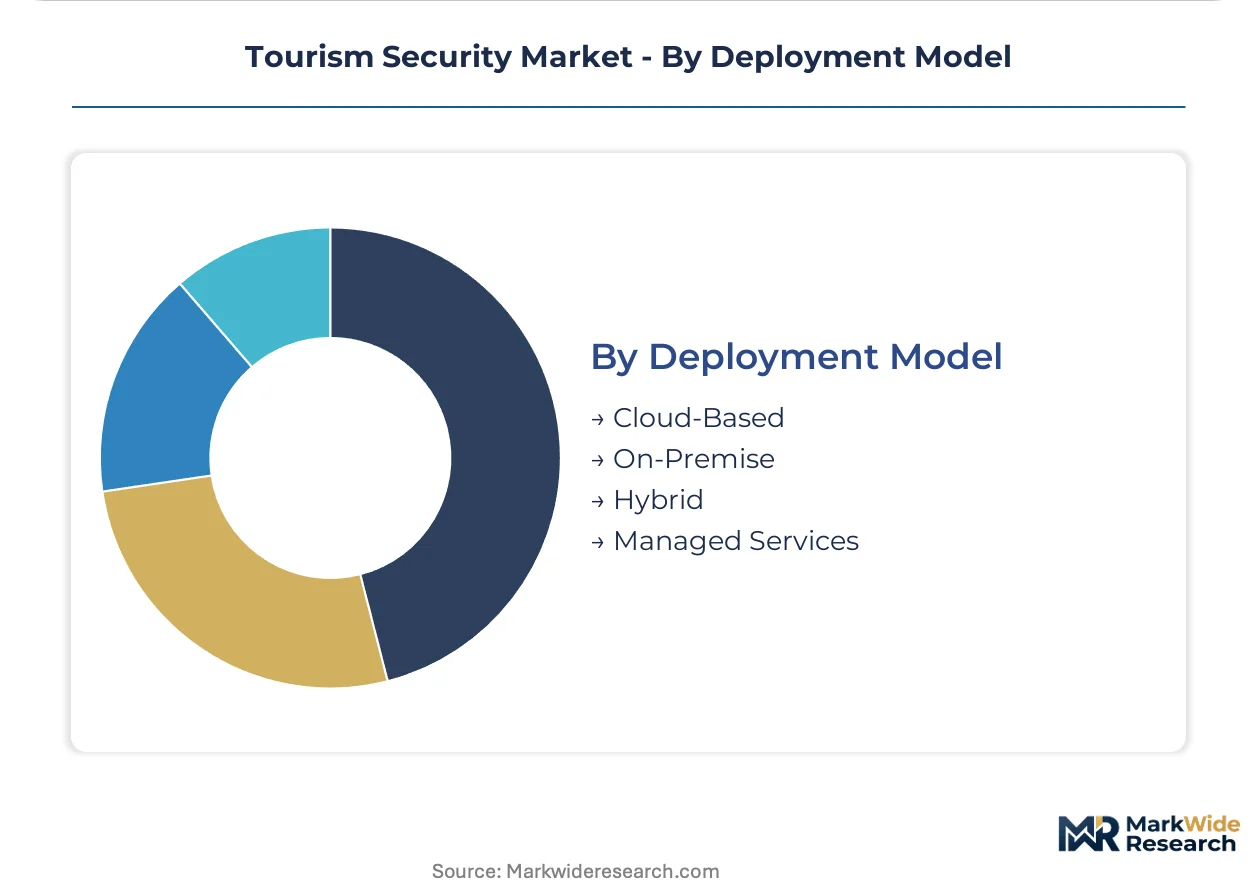
Deployment Model:
Infrastructure ownership preferences reflect capital availability and internal technical capacity, with sovereign-funded developments piloting alternative compensation structures.
- Cloud-Based:Subscription security operations with remote command center management and automatic software updates. Mid-market hotel chains are migrating fastest as they seek capital expenditure flexibility and expanded vendor pool access.
- Managed Services:Outcome-linked security agreements where vendor compensation ties to measurable incident prevention metrics. Large resort developers in the United Arab Emirates and Saudi Arabia are piloting these contracts where liability exposure from security incidents exceeds service cost optimization priorities.
- On-Premise:Locally hosted systems with dedicated hardware and internal IT management responsibility.
- Hybrid:Mixed architecture combining edge processing with cloud-based analytics and storage.
Cloud-Based deployment holds the leading position, though Managed Services is climbing the fastest as performance-based contracting gains traction among institutional buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor contract concentration clusters around sovereign wealth-funded developments and biometric regulatory enforcement zones. The United Arab Emirates and European Union jurisdictions generate disproportionate procurement volume through mandatory compliance frameworks and mega-event infrastructure commitments.
United Arab Emirates
Federal security frameworks and MOHAP staffing ratio mandates drive protective service procurement for mega-event infrastructure. Dubai's sovereign tourism mandates accelerate security modernization across hospitality developments. Abu Dhabi's command center build-outs reduce reliance on imported security architecture through domestic sovereign wealth funding.
Germany
Airport biometric modernization and high-speed rail security upgrades concentrate demand among transport operators. The EU AI Act conformity assessment obligations extend product launch timelines for biometric surveillance vendors. Frankfurt and Munich airport authorities consolidate vendor relationships with established European certification holders.
United States
Corporate traveler risk assessment services and hospitality chain protective outsourcing sustain demand across major metropolitan markets. FAA security protocols and TSA coordination requirements shape airport perimeter hardening procurement. Las Vegas and Orlando resort corridors deploy integrated surveillance systems for high-volume tourism assets.
France
CNIL biometric data governance and EU AI Act compliance requirements constrain cross-border passenger data architectures. Paris airport operators and high-speed rail authorities prioritize conformity-certified surveillance vendors. The Île-de-France region concentrates hospitality security outsourcing among luxury hotel chains.
Saudi Arabia
Sovereign wealth-funded mega-projects pilot outcome-linked security service agreements with incident-prevention performance guarantees. NEOM and Red Sea Project developments mandate specific perimeter hardening standards for new tourism assets. Riyadh-based command centers anchor protective service procurement for religious tourism infrastructure.
Tourism Security Market Competitive Landscape
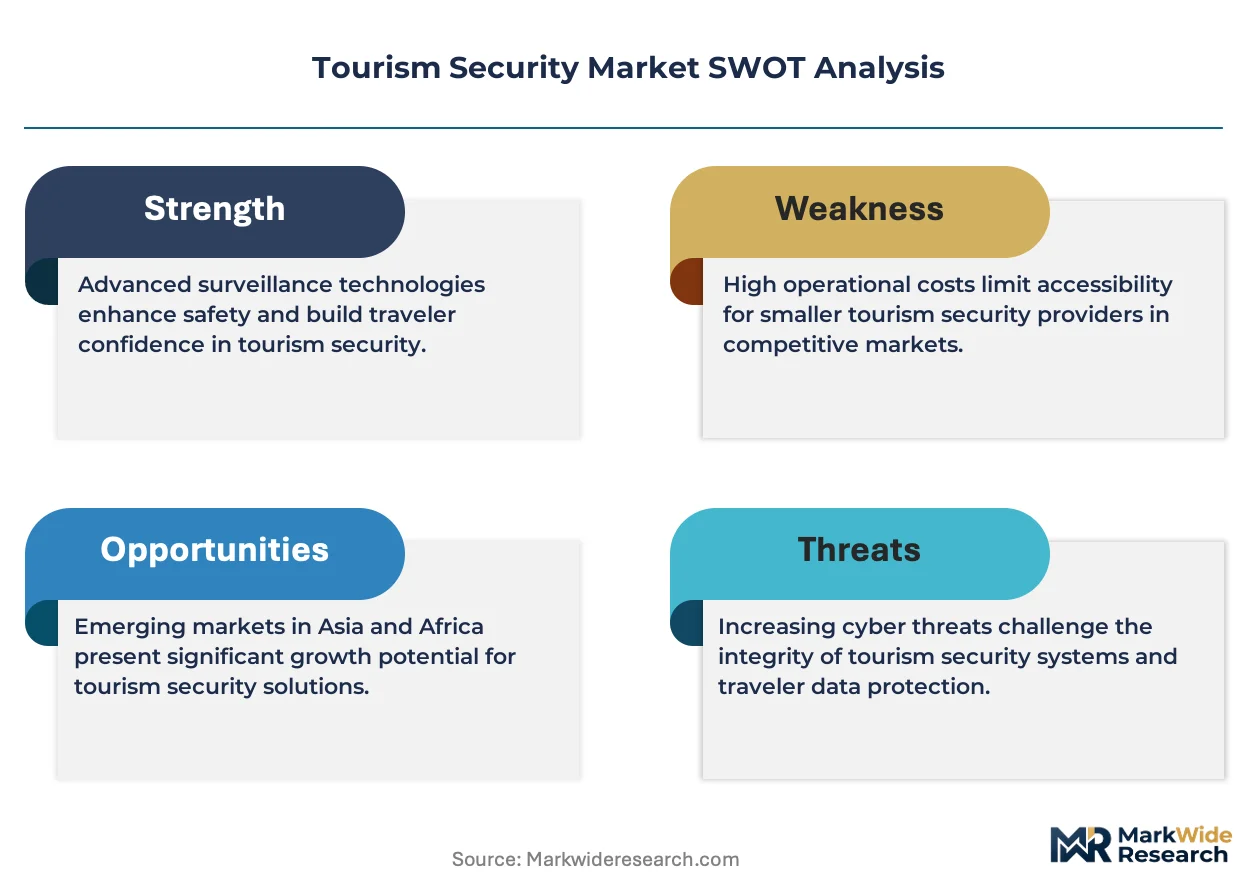
Integrated protective service providers and specialized risk assessment firms split the market between staffing-heavy operations and technology-augmented surveillance. The vendor base organizes around three strategic archetypes: global security conglomerates with government-adjacent contract heritage, regional specialists with sovereign wealth relationships, and technology-integrated challengers with AI-biometric convergence capabilities. Dominant competitive moves include portfolio diversification into adjacent risk services and geographic expansion through sovereign-funded development corridors.
Within the government-contract heritage tier, GardaWorld and Constellis exemplify positioning anchored to protective services specialization and high-threat zone protocols. Securitas AB occupies a position representing standardized service-level frameworks for European hospitality outsourcing. These three entities illustrate how competitive advantage concentrates around either sovereign relationship depth or regulatory compliance infrastructure.
| Leading Market Players |
|---|
| Control Risks |
| GardaWorld |
| Constellis |
| Triple Canopy |
| International SOS |
| G4S |
| Allied Universal |
| Securitas AB |
| Pinkerton Consulting & Investigations |
| Others |
Value Network & Pricing Analysis
Chinese edge-computing hardware manufacturers anchor the upstream tier, concentrating margin capture in algorithm retraining and maintenance service contracts rather than camera hardware itself. This supplier concentration forces downstream security operators toward subscription-based compensation models to preserve cash flow flexibility.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across biometric surveillance procurement, separating conformity-certified European vendors from non-compliant market entrants facing 8-14 month launch delays. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and algorithmic bias testing documentation depth. Cost compression in the standard tier is intensifying because mid-market hotel chains prioritize capital expenditure flexibility over performance specifications. Independent operators exhibit highest price sensitivity, while sovereign wealth-funded mega-projects in the United Arab Emirates prioritize liability reduction over unit cost optimization.
Supply Chain Analysis
Extended payment terms from semiconductor distributors have become standard for edge-analytics hardware procurement, stretching working capital cycles for mid-tier security integrators. Manufacturing concentrates in China, Taiwan, and South Korea for image sensors and processing chipsets. The supply chain draws from specialized glass optics, thermal imaging components, and encrypted storage modules. Single-source vulnerability persists for advanced computer vision chipsets. Distribution runs through systems integrators with sovereign wealth relationships in Gulf Cooperation Council corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithm retraining and edge-hardware maintenance contracts expand faster than camera hardware sales, positioning service-attach revenue as the primary margin pool for vendors with deployed infrastructure footprints.
For Market Incumbents: Build regulatory certification moats by accelerating EU AI Act conformity assessment completion ahead of smaller competitors. Anchor government-adjacent contract heritage through sovereign wealth vehicle partnerships in the United Arab Emirates and Saudi Arabia. Invest in backward integration into edge-computing hardware distribution to reduce supplier concentration risk. For New Entrants and Emerging Players: Build out regional command center infrastructure in Vietnam and Indonesia before luxury resort complex build-outs accelerate protective service procurement. Target mid-market hotel chains migrating from on-premise to cloud-based deployment models. Pursue white-label algorithm licensing to established security operators lacking in-house computer vision capabilities. For Investors and Strategic Acquirers: Capital is best deployed toward technology-integrated challengers with AI-biometric convergence capabilities and existing notified body relationships in Europe. Long-term viability hinges on predictive analytics competencies that enable outcome-based contracting traction. Watch for consolidation signals when non-compliant vendors face extended product launch timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Conformity assessment completion opens procurement channels with Frankfurt and Munich airport authorities. |
| Regional Command Center Build-Out | Vietnam and Indonesia infrastructure positions vendors for Southeast Asia luxury resort contract flows. |
| Algorithm Retraining Service Launch | Recurring revenue layer captures margin from deployed edge-analytics hardware across distributed hotel portfolios. |
| Sovereign Wealth Partnership Formation | UAE and Saudi relationships enable outcome-linked contract pilots with incident-prevention performance guarantees. |
| Edge Hardware Distribution Control | Upstream integration reduces supplier concentration exposure for mid-tier security integrators. |
Research Methodology
Operator-level perspectives from protective services command center directors, hospitality security procurement managers, biometric surveillance vendor product leads, and sovereign wealth fund infrastructure officers anchored the qualitative base. Primary interview data combined with secondary validation from EU AI Act conformity assessment databases, MOHAP federal security framework documentation, GDPR processing agreement filings, and hospitality chain SEC disclosures. Bottom-up property-level security spend estimates triangulated against top-down market sizing from customs trade data.
Scenario-bracketing across regulatory enforcement intensity, sovereign tourism mandate acceleration, and cloud migration pace shaped the projection framework. Segmentation dimensions modeled include service type, technology tier, deployment model, end-user scale, and regional regulatory cluster. CAGRs derived from installed base growth, equipment refresh cycle compression, and service-attach rate expansion. Forecast inputs incorporated edge-analytics hardware shipment data and protective services staffing ratio mandates.
Stress conditions across EU AI Act implementation timelines, Gulf Cooperation Council recruitment bottlenecks, and mid-market hotel chain capital availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and sovereign infrastructure commitment durability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Japan Sports Tourism Market
Travel and Tourism
Wellness Tourism Market
Travel and Tourism
MICE Travel Service Market
Travel and Tourism
Yacht Charter Service Market
Travel and Tourism
Hong Kong Tourism Market
Travel and Tourism
India Outbound Tourism Market
Travel and Tourism
Camping and Caravanning Market
Travel and Tourism
Asia-Pacific Tourism Market
Travel and Tourism
Global Home Exchange Service Market
Travel and Tourism
Cycle Tourism Market
Travel and Tourism
China Outbound Travel Market
Travel and Tourism
France Culinary Tourism Market
Travel and Tourism
New Zealand Sustainable Tourism Market
Travel and Tourism
France Outbound Tourism Market
Travel and Tourism
Global Duty-Free and Travel Retail Market
Travel and Tourism
South Africa Sports Tourism Market