
 Latin America Inflight Services Market | 2026-2036
Latin America Inflight Services Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Inflight Services Market Insights
Capital-intensity divergence between centralized galley automation and manual assembly operations is collapsing as mid-tier caterers face equipment upgrade cycles. LSG Sky Chefs leverages its continental kitchen network to sustain cold-chain reliability across multiple climate zones. Gategroup anchors its position through specialized wide-body provisioning at São Paulo and Mexico City hubs. Newrest Group differentiates via integrated business-jet catering that controls last-mile logistics to secondary airports.
Latin America inflight services encompass the design, preparation, delivery, and execution of passenger-facing amenities aboard commercial and private aircraft, with food and beverage operations requiring HACCP-compliant preparation at altitude-adjusted palatability standards. The primary purpose centers on airline brand differentiation and ancillary revenue capture during the flight experience. Food and beverage provisioning leads service type revenue as full-service carriers restore pre-pandemic meal standards on trunk routes. Connectivity and entertainment segments represent the fastest-growing structural category as satellite-enabled broadband becomes standard on narrow-body retrofits across the region's major flag carriers.
Brazil's ANAC enforces stringent catering facility audits that shape vendor qualification timelines and capital requirements for market entry. Mexico's COFEPRIS food safety protocols and Argentina's ANMAT pharmaceutical controls for onboard medical kits create layered compliance obligations for multi-country operators. Stakeholders must monitor regulatory harmonization progress under IATA's regional safety initiatives while calibrating investment between automation and flexible labor models.
Market Dynamics
Satellite-enabled broadband retrofits on narrow-body fleets are compressing service differentiation windows as carriers race to match connectivity parity across Brazil and Mexico trunk routes. This technological forcing function cascades through catering procurement, entertainment bundling, and ground-handling coordination requirements.
Growth Catalysts
- Brazil ANAC Safety Mandates:Facility audit standards for food handling and cold-chain storage are elevating operational baselines and disqualifying subscale vendors from hub airport contracts.
- Full-Service Carrier Premium Expansion:Lie-flat cabin rollouts on São Paulo-Miami and Mexico City-Madrid routes are generating specialized catering demand for altitude-adjusted meal presentation.
- Narrow-Body Connectivity Retrofits:Satellite broadband hardware installation across LATAM, Aeromexico, and Gol fleets is creating integrated entertainment-catering package opportunities.
Market Restraints
- Jet Fuel Price Volatility:Aviation kerosene cost swings compress airline ancillary spending budgets and delay galley equipment upgrade cycles at mid-tier caterers.
- Hub Airport Concentration Risk:São Paulo Guarulhos and Mexico City Benito Juárez control 60% of regional wide-body turns, creating single-point dependency for provisioning vendors.
- Multi-Country Regulatory Friction:Divergent COFEPRIS, ANAC, and ANMAT compliance timelines extend vendor qualification periods and inflate legal overhead for cross-border operators.
Strategic Opportunities
- Secondary Airport Business-Jet Catering:Underpenetrated routes to Florianopolis, Merida, and Bariloche lack cold-chain infrastructure, rewarding operators with captive last-mile logistics.
- Regional IATA Harmonization Initiatives:Proposed safety standard alignment could collapse multi-jurisdiction audit costs and accelerate vendor certification portability across Mercosur.
- Plant-Based Menu Convergence:HACCP-compliant vegan protein preparation at altitude is opening ancillary revenue streams as LATAM and Avianca pilot sustainable catering tiers.
Industry Challenges
- Galley Automation Talent Scarcity:Robotics maintenance and IoT cold-chain monitoring expertise concentrates in São Paulo and Mexico City, inflating wage premiums for skilled technicians.
- Legacy Reservation System Integration:Catering order management platforms must interface with Sabre and Amadeus passenger manifests, creating API complexity and real-time synchronization failures.
- Altitude Palatability Certification Delays:Sensory testing protocols for reduced-pressure cabin environments extend new menu item approval timelines by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Inflight Services Market |
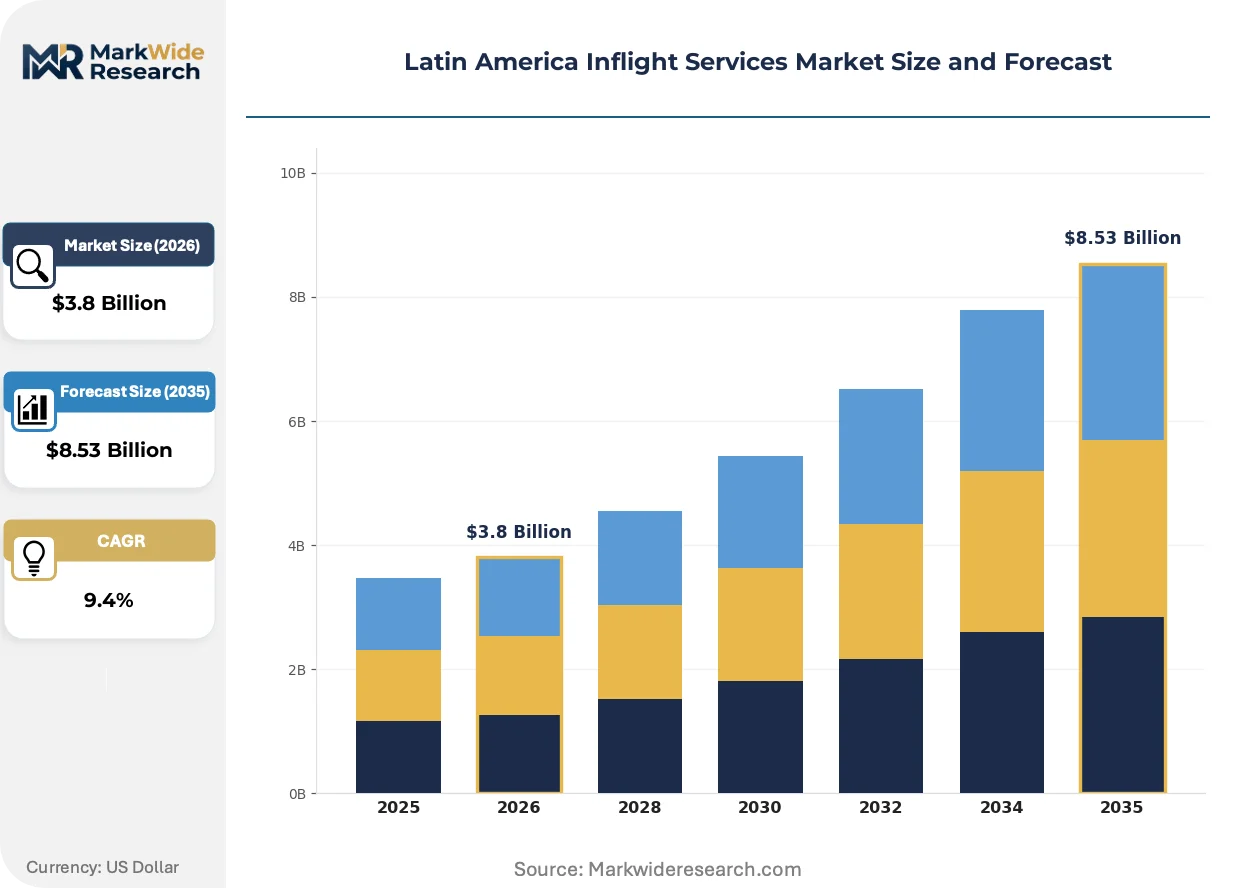
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Food & Beverage, Entertainment, Connectivity, Duty-Free Aircraft Type: Narrow-Body, Wide-Body, Regional, Business Jets Customer Segment: Leisure Travelers, Business Travelers, Government Clients, Charter Services Distribution Channel: Direct Sales, Third-Party Vendors, Onboard Sales, Partnerships |
| Companies Covered | LSG Sky Chefs, Gategroup, Newrest Group, GCG Catering, Air Culinaire Worldwide LLC, Gate Gourmet, Marcia's Catering, Manny Caterin, GateGourmet, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Inflight Services Market Trends and Innovations
Digital integration across the passenger journey is collapsing traditional boundaries between ground-based hospitality and airborne service delivery. Three structural shifts are reconfiguring how Latin American carriers source, bundle, and monetize inflight amenities.
Blockchain-enabled food provenance tracking is decomposing opacity in multi-tier supply chains. LATAM and Gol are piloting distributed-ledger systems that trace ingredient origins from farm to tray table. Full-service carriers in Brazil are mandating supplier adoption to preempt ANAC audit findings. This transparency architecture is compressing price premiums for certified organic and allergen-free meal categories.
COFEPRIS digital submission pathways for food facility registrations are accelerating compliance documentation turnaround. Mexico's pharmaceutical and food safety regulator implemented cloud-based inspection scheduling that reduces physical audit queuing. Caterers operating across Mexico City, Cancun, and Monterrey hubs are consolidating quality management systems to exploit this procedural streamlining. Regional operators without Mexican legal entities face exclusion from this expedited track.
Subscription-based lounge-to-seat service bundling is fragmenting traditional per-flight procurement. Frequent flyer program tiers at Aeromexico and Avianca now incorporate pre-ordered meal preferences and priority galley loading. Corporate travel managers in São Paulo and Mexico City are negotiating annual catering allowances rather than route-specific contracts. This consumption-pattern shift is most visible among financial services and technology sector accounts with consolidated travel spend.
Latin America Inflight Services Market Segmentation
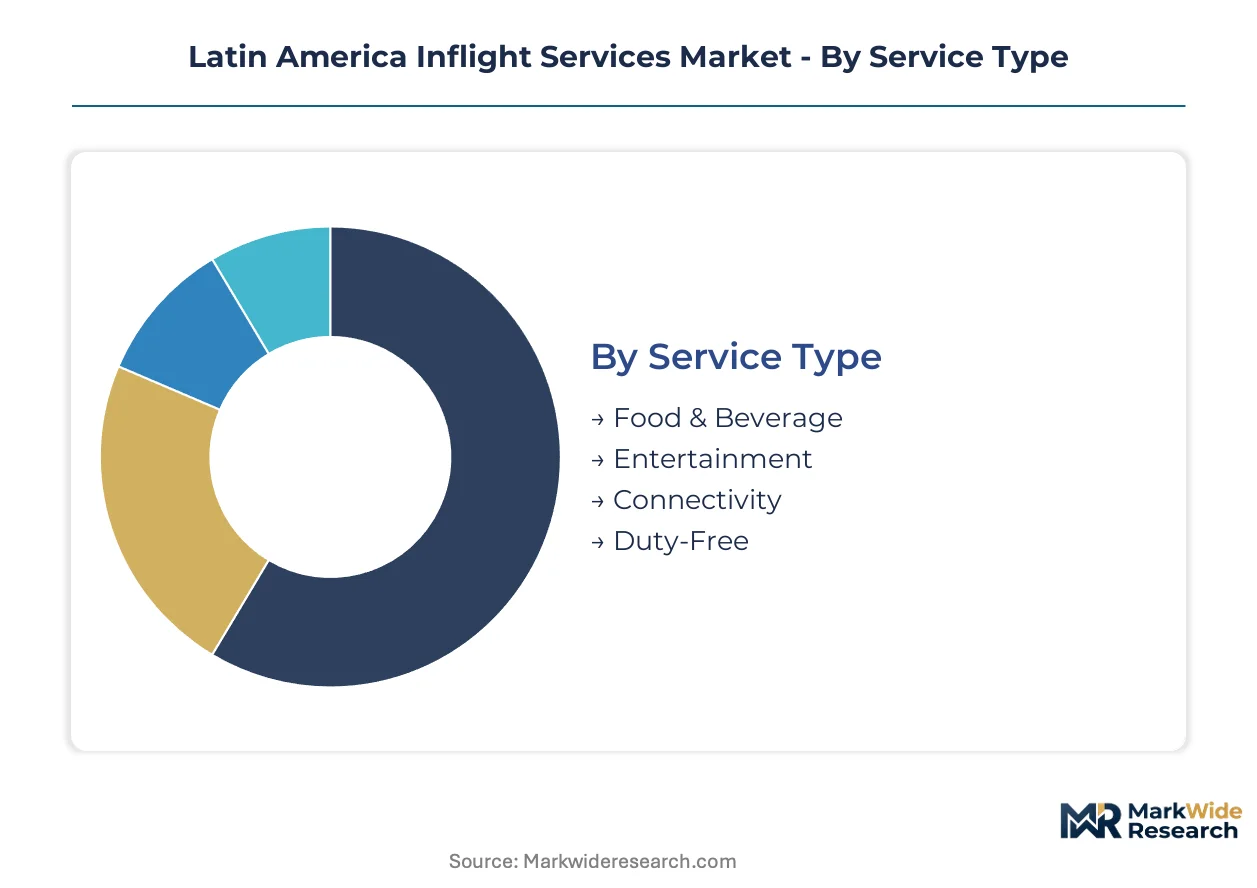
Segmentation in Latin American inflight services reveals how procurement priorities diverge across carrier types and route economics. Each dimension exposes distinct margin structures, from hub-based catering contracts to satellite-enabled entertainment bundles on narrow-body retrofits.
Service Type:
Margin pools concentrate in food and beverage provisioning, where altitude-adjusted preparation and cold-chain compliance create defendable positions for certified operators.
- Food & Beverage:HACCP-compliant meal preparation at reduced-pressure palatability standards dominates revenue. Demand clusters at São Paulo Guarulhos and Mexico City Benito Juárez, where ANAC and COFEPRIS facility audits disqualify subscale vendors from wide-body contracts.
- Entertainment:Seatback streaming hardware and content licensing generates recurring ancillary revenue. LATAM and Aeromexico fleet retrofits are driving procurement of integrated entertainment-catering packages on Brazil-Mexico trunk routes.
- Connectivity:Satellite broadband installation across Gol and Avianca narrow-body fleets is compressing service differentiation windows.
- Duty-Free:Onboard retail operations face margin pressure from e-commerce pre-order platforms and airport duty-free consolidation.
The dominant share belongs to Food & Beverage, while Connectivity is closing the gap fastest.
Aircraft Type:
Volume flows track fleet deployment patterns, with narrow-body operations commanding procurement scale across domestic and short-haul international networks.
- Narrow-Body:Single-aisle aircraft dominate Latin American fleet composition, driving standardized galley configurations and bulk purchasing leverage for Brazil's GOL and Mexico's Volaris.
- Wide-Body:Twin-aisle provisioning at São Paulo and Mexico City hubs requires specialized catering infrastructure for lie-flat cabin meal presentation on long-haul routes to Madrid and Miami.
- Regional:Turboprop and small-jet operations concentrate in secondary Brazilian and Colombian markets with limited cold-chain infrastructure.
- Business Jets:Fractional ownership and charter demand from São Paulo and Mexico City executives rewards operators with captive last-mile logistics to Florianopolis and Merida.
Narrow-Body captures the volume base, though Business Jets deliver the highest per-passenger service yields.
Customer Segment:
Application context determines service specifications, from corporate travel procurement standards to government tender compliance requirements.
- Leisure Travelers:Price-sensitive demand from VFR and vacation segments shapes buy-on-board and pre-order meal economics on low-cost carriers.
- Business Travelers:Corporate account consolidation in São Paulo and Mexico City financial services sectors drives subscription-based lounge-to-seat bundling and priority galley loading.
- Government Clients:State-owned carrier procurement at Aerolineas Argentinas and Conviasa imposes localized content requirements and extended payment terms.
- Charter Services:Ad-hoc provisioning for sports teams and entertainment tours demands rapid menu customization and flexible scheduling.
Business Travelers anchor premium service development, while Charter Services exhibit the most volatile procurement patterns.
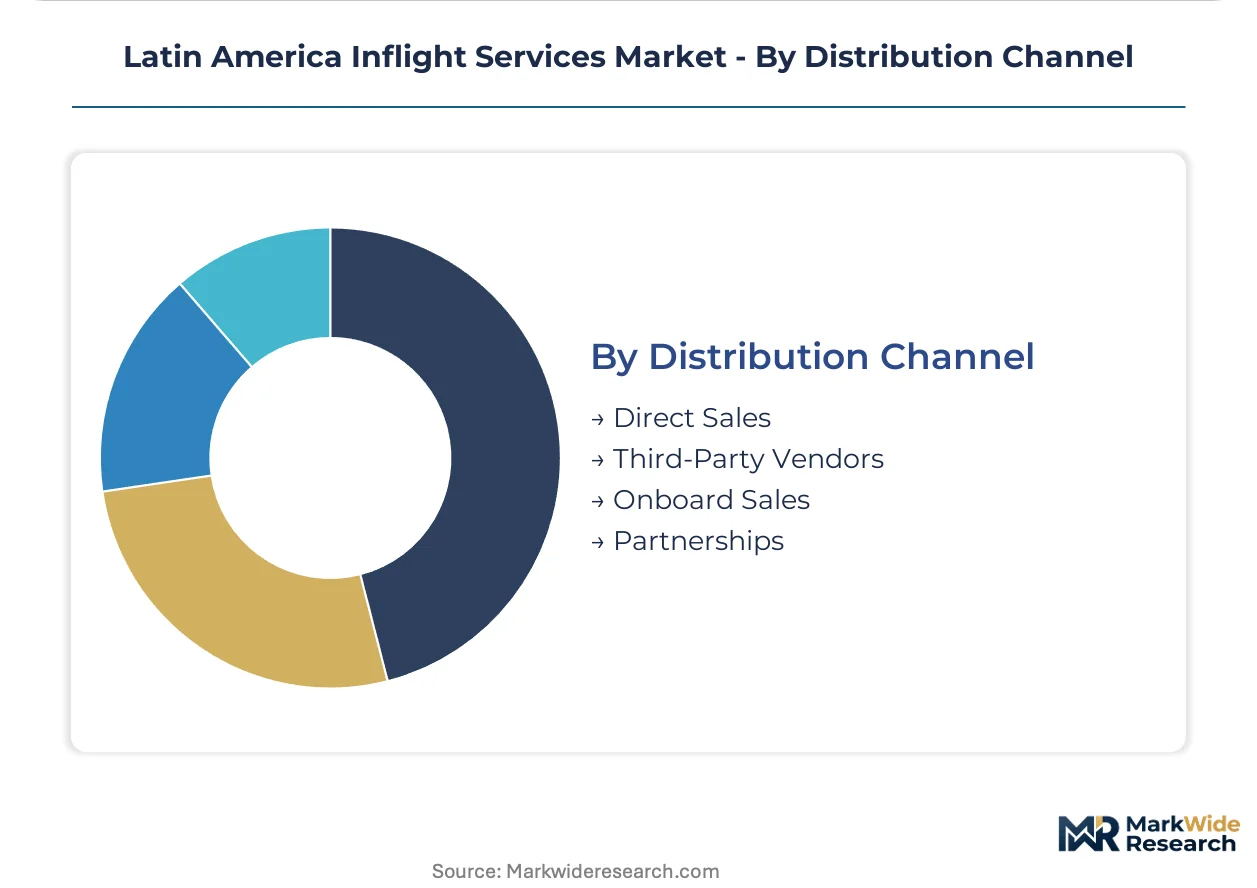
Distribution Channel:
Supply concentration varies by channel control, with direct airline-caterer relationships capturing operational efficiency gains.
- Direct Sales:Flag carriers LATAM and Aeromexico maintain captive kitchen networks or exclusive long-term contracts with LSG Sky Chefs and Gategroup for hub provisioning.
- Third-Party Vendors:Independent caterers serve secondary airports and seasonal capacity surges, competing on flexibility rather than scale.
- Onboard Sales:Buy-on-board and duty-free transactions generate passenger-facing revenue streams with real-time inventory management requirements.
- Partnerships:Frequent flyer program integrations and co-branded lounge access create bundled service offerings for consolidated corporate travel spend.
Direct Sales holds structural advantage at primary hubs, though Partnerships are expanding fastest through loyalty program monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leisure travelers across Central America exhibit acute price sensitivity to buy-on-board meal pricing, while corporate accounts in São Paulo and Mexico City demonstrate inelastic demand for premium cabin catering and integrated entertainment bundles.
Brazil
Domestic trunk routes between São Paulo Guarulhos, Rio de Janeiro Galeão, and Brasília drive standardized narrow-body galley configurations for GOL and LATAM. ANAC facility audit mandates for cold-chain compliance are disqualifying subscale caterers from hub airport contracts. São Paulo's Guarulhos International anchors continental kitchen networks serving long-haul lie-flat cabin provisioning to Miami and Madrid.
Mexico
Aeromexico's Mexico City-Madrid and Cancun-Los Angeles wide-body rotations generate specialized catering demand for altitude-adjusted meal presentation. COFEPRIS digital submission pathways for food facility registrations are accelerating vendor qualification timelines. The Mexico City Benito Juárez hub concentrates satellite broadband retrofit coordination across narrow-body fleets.
Argentina
Aerolineas Argentinas state-owned procurement imposes localized content requirements and extended payment terms on inflight service vendors. ANMAT pharmaceutical controls for onboard medical kits create layered compliance obligations for multi-country operators. Buenos Aires Ezeiza serves as the primary wide-body provisioning point for southern cone long-haul routes.
Chile
LATAM's Santiago hub operations link Pacific and Atlantic long-haul networks, driving demand for integrated entertainment-catering packages on Boeing 787 and Airbus A350 fleets. The country's national aviation regulator enforces HACCP-aligned facility standards for international catering vendors. Santiago Arturo Merino Benítez concentrates cold-chain infrastructure for Antarctic gateway and Patagonia secondary airport services.
Colombia
Avianca's Bogotá hub connects North and South American trunk routes, generating procurement scale for narrow-body galley standardization. The country's food safety authority mandates traceability documentation for international catering suppliers. Bogotá El Dorado serves as the primary distribution point for Andean region business-jet catering to secondary airports lacking captive cold-chain infrastructure.
Latin America Inflight Services Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with continental kitchen networks sustaining cold-chain reliability across multiple climate zones while regional specialists compete on flexible scheduling and rapid menu customization. The market structure consolidates around hub-based provisioning contracts at São Paulo and Mexico City, with secondary airport services fragmenting across independent operators. Three archetypes dominate: integrated global caterers with continental kitchen networks, hub-focused specialists with wide-body provisioning expertise, and business-jet operators controlling last-mile logistics. Competitive moves concentrate on strategic partnerships for satellite-enabled entertainment bundling and geographic expansion into underpenetrated secondary airports.
Among integrated global caterers, LSG Sky Chefs and Gategroup exemplify archetypes anchored by continental kitchen networks and hub-focused wide-body provisioning respectively. Newrest Group occupies a position within the business-jet specialist tier, representing operators with captive last-mile logistics capabilities to secondary airports lacking cold-chain infrastructure.
| Leading Market Players |
|---|
| LSG Sky Chefs |
| Gategroup |
| Newrest Group |
| GCG Catering |
| Air Culinaire Worldwide LLC |
| Gate Gourmet |
| Marcia's Catering |
| Manny Caterin |
| GateGourmet |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at São Paulo Guarulhos and Mexico City Benito Juárez continental kitchens shapes both supply concentration and price floors for wide-body provisioning contracts. Full-service carriers extract volume discounts from LSG Sky Chefs and Gategroup while mid-tier caterers absorb fixed-cost pressure from ANAC facility audit mandates.
Pricing Analysis
After-sales service bundling drives lifetime value as Aeromexico and Avianca frequent flyer programs incorporate pre-ordered meal preferences into annual corporate allowances. Three-tier pricing structure across premium, standard, and economy levels stratifies by cabin class and route length, with altitude-adjusted meal presentation commanding brand premiums on São Paulo-Miami trunk routes. Cost compression in narrow-body galley provisioning intensifies as GOL and Volaris standardize configurations for bulk purchasing leverage. Leisure travelers on domestic Brazilian routes exhibit acute price sensitivity to buy-on-board meal pricing, while corporate accounts in São Paulo financial services demonstrate inelastic demand for lie-flat cabin catering.
Supply Chain Analysis
Just-in-time cold-chain coordination dominates inventory strategy as satellite-enabled galley loading systems synchronize with real-time passenger manifest updates from Sabre and Amadeus platforms. Supply concentrates in Brazil, Mexico, and Argentina, where ANAC, COFEPRIS, and ANMAT facility audits create regulatory moats for certified operators. Raw material dependencies span temperature-controlled protein sourcing, specialized packaging for altitude-adjusted palatability, and pharmaceutical-grade medical kit components. Single-source vulnerability runs through São Paulo and Mexico City hub airport concentration, where 60% of regional wide-body turns create provisioning chokepoints. Distribution runs through direct airline-caterer relationships at primary hubs, with third-party vendors serving secondary airport seasonal surges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of robotics maintenance and IoT cold-chain monitoring expertise in São Paulo and Mexico City inflates wage premiums and constrains galley automation deployment timelines for mid-tier caterers.
For Market Incumbents: Compound defensive positions by deepening captive kitchen networks at São Paulo Guarulhos and Mexico City Benito Juárez to preempt emerging entrant access to wide-body contracts. Invest in ANAC and COFEPRIS certification portability across Mercosur to collapse multi-jurisdiction audit costs and accelerate vendor qualification timelines for regional expansion. For New Entrants and Emerging Players: Anchor in underpenetrated secondary airport business-jet catering to Florianopolis, Merida, and Bariloche, where cold-chain infrastructure gaps reward operators with captive last-mile logistics. Target plant-based menu convergence as LATAM and Avianca pilot sustainable catering tiers, leveraging HACCP-compliant vegan protein preparation as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hub-focused specialists with wide-body provisioning expertise and integrated entertainment-catering bundling capabilities as satellite broadband retrofits compress service differentiation windows. Long-term viability hinges on consolidation plays for operators with continental kitchen networks spanning multiple climate zones. Watch for IATA regional harmonization initiative progress as inflection indicator for multi-jurisdiction audit cost collapse and accelerated vendor certification portability.| Strategic Initiative | Industry Significance |
|---|---|
| Galley Automation Investment | ANAC facility audit mandates disqualify subscale vendors lacking robotics maintenance capabilities. |
| Satellite Broadband Integration | LATAM and Aeromexico fleet retrofits create bundled entertainment-catering procurement opportunities. |
| Secondary Airport Expansion | Florianopolis and Merida cold-chain gaps reward operators with captive last-mile logistics control. |
| Plant-Based Menu Development | HACCP-compliant vegan protein preparation opens ancillary revenue streams at sustainable catering tiers. |
| Regulatory Harmonization Alignment | IATA regional safety initiatives could collapse multi-jurisdiction audit costs across Mercosur markets. |
Research Methodology
A spread of perspectives from airline procurement directors, catering facility operations managers, regulatory compliance officers, and ground-handling coordinators converged on the working assumptions underlying market size and growth trajectory estimates. Primary interviews with LATAM, Aeromexico, and GOL supply chain executives supplemented secondary validation through ANAC audit disclosure records, COFEPRIS facility registration databases, IATA safety initiative documentation, and customs data on aviation catering equipment imports. Bottom-up triangulation across service type, aircraft type, and customer segment dimensions anchored value estimates, while top-down cross-checks against regional airline fleet deployment and passenger traffic data ensured consistency.
Segmentation dimensions modeled encompass service type, aircraft type, customer segment, and distribution channel, with additional granularity for regulatory jurisdiction clusters across Brazil, Mexico, Argentina, Chile, and Colombia. CAGRs were derived from trend extrapolation of satellite broadband retrofit penetration, premium cabin rollout schedules, and ANAC facility audit compliance timelines across the projection horizon. Industry-specific forecast inputs include narrow-body fleet standardization patterns, lie-flat cabin provisioning demand on trunk routes, and business-jet catering yield differentials at secondary airports.
Material uncertainties — jet fuel price volatility, regulatory harmonization delays, and galley automation talent scarcity — sit outside the modeled envelope and could compress or extend growth trajectories. Forecasts reflect assumptions about carrier ancillary spending recovery and cold-chain infrastructure investment continuity. Revision becomes warranted when satellite broadband retrofit penetration or ANAC audit disqualification rates cross thresholds that reconfigure competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
India Outbound Tourism Market
Travel and Tourism
Germany Outbound Tourism Market
Travel and Tourism
Pet Travel Services Market
Travel and Tourism
China Online Travel Market
Travel and Tourism
Surfing Tourism Market
Travel and Tourism
Yacht Charter Market
Travel and Tourism
New Zealand Sports Tourism Market
Travel and Tourism
North America Travel Retail Market
Travel and Tourism
Europe Driving Vacation Market
Travel and Tourism
Water Park Market
Travel and Tourism
Sustainable Tourism Market
Travel and Tourism
GCC Outbound Tourism Market
Travel and Tourism
Travel and Tourism User Generated Content Market
Travel and Tourism
UK Outbound Travel Market
Travel and Tourism
Luxury Travel Market
Travel and Tourism
Maldives Hospitality Market