
 Inflight Shopping Market | 2026-2036
Inflight Shopping Market Size, Share, and Industry Trends Forecast 2026-2036
Inflight Shopping Market Outlook
ISO 9001 quality management certification is redrawing competitive boundaries for inflight retail technology providers. Panasonic Avionics Corporation leverages its integrated inflight entertainment and commerce platforms to dominate long-haul routes. Avolta AG anchors global airport and onboard retail operations through extensive concession networks. SITA competes by deploying passenger processing systems that streamline duty-free transactions across multiple carrier clients.
Inflight shopping encompasses the sale of goods to airline passengers during flights or through airline-affiliated channels, typically involving duty-free pricing, limited cabin inventory managed through seatback screens or crew handheld devices, and fulfillment either onboard or via airport collection points. The primary commercial purpose is generating ancillary revenue for airlines while offering passengers tax-exempt pricing on luxury and convenience goods. Electronics and beauty products command premium margin pools due to high perceived value in duty-free contexts, while mobile apps represent the fastest-growing sales channel as carriers integrate retail into passenger smartphone ecosystems. Leisure travelers constitute the largest customer type by volume, though frequent flyers concentrate higher per-trip spending through loyalty point redemption programs.
FAA cabin safety regulations in the United States govern stowage and crew handling of inflight retail inventory, while EU Green Deal packaging requirements are reshaping product sourcing for European carriers. REACH compliance affects beauty product formulations sold on EU-registered aircraft, and IATA operational standards facilitate cross-border payment processing for onboard transactions. Stakeholders must monitor how biometric payment authentication and evolving duty-free allowance thresholds reshape passenger willingness to purchase during flight segments.
Market Dynamics
IATA's One Order standards are dismantling legacy passenger service systems, forcing airlines to rebuild retail infrastructure around unified digital identity and seamless payment flows. This structural overhaul compresses booking-to-fulfillment cycles and redefines competitive advantage around data integration depth.
Growth Catalysts
- Cabin connectivity upgrades:Satellite broadband installations on narrow-body fleets enable real-time inventory synchronization and dynamic pricing adjustments during flight segments.
- REACH compliance frameworks:EU-registered carriers reformulate beauty assortments to meet chemical safety thresholds, expanding eligible product categories for duty-free channels.
- Hub airport throughput:Concentrated passenger flows through Dubai International Airport and Heathrow Terminal 5 generate captive retail audiences with extended dwell times.
Market Restraints
- Inventory carrying costs:Perishable luxury goods require climate-controlled stowage and specialized crew training, elevating operational overhead on long-haul routes.
- Payment processing fragmentation:Cross-border transaction authorization delays persist outside IATA-standardized corridors, throttling conversion rates on certain carrier networks.
- Duty-free allowance compression:Bilateral trade agreements in key corridors are narrowing passenger exemption thresholds, constraining average transaction values.
Strategic Opportunities
- Biometric authentication convergence:Facial recognition payment systems linked to passenger manifest data eliminate friction in onboard transaction workflows.
- Pre-order mobile channels:Airline smartphone applications now capture reservation-tender-fulfillment sequences before passengers reach departure gates.
- EU Green Deal packaging mandates:Sustainable material requirements for single-use retail containers create first-mover advantages for compliant suppliers.
Industry Challenges
- Legacy system integration:Carrier reservation platforms built on EDIFACT messaging protocols resist real-time retail data exchange with modern e-commerce architectures.
- Crew workforce calibration:Flight attendant time allocation between safety duties and sales activities requires precise regulatory boundary navigation under FAA cabin rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inflight Shopping Market |
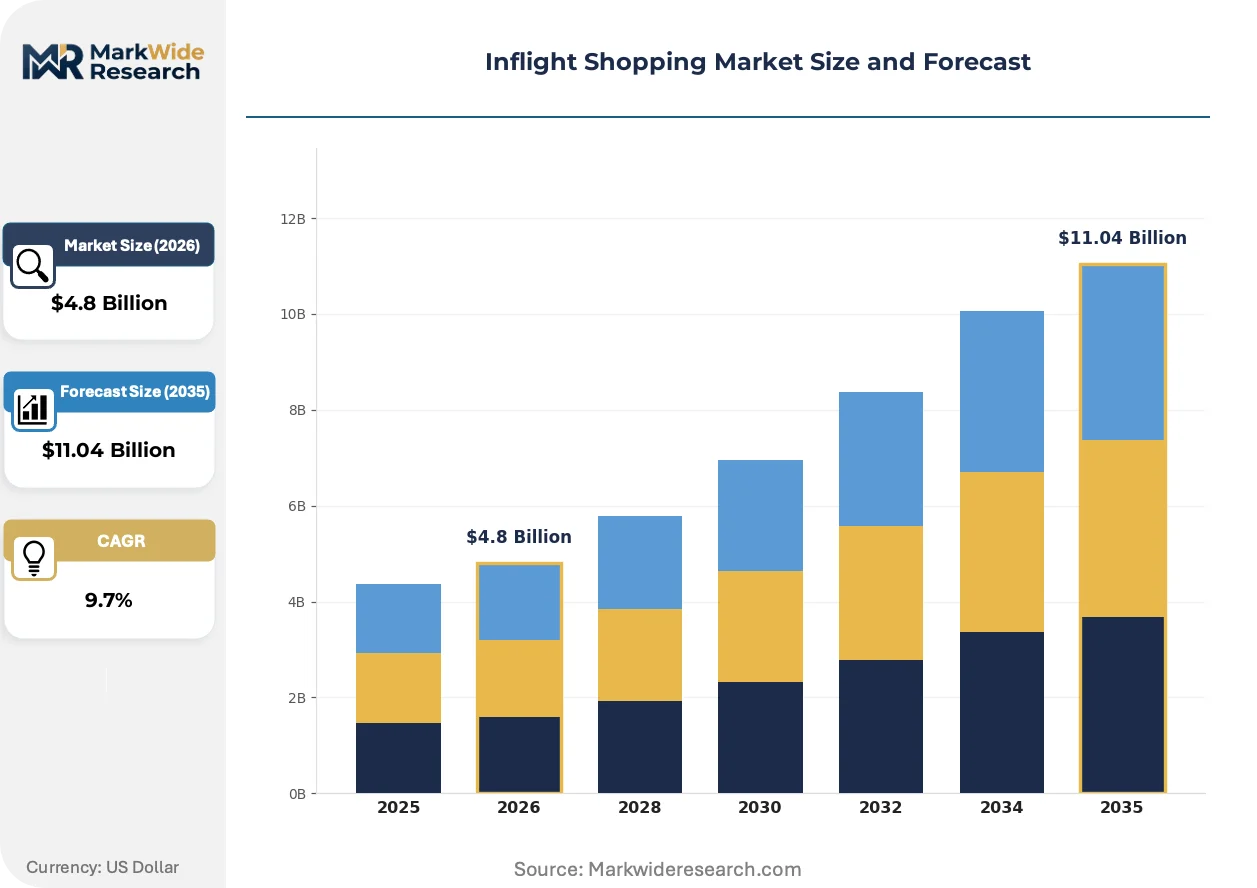
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Apparel, Accessories, Beauty Products Customer Type: Leisure Travelers, Business Travelers, Frequent Flyers, Family Travelers Sales Channel: Onboard Retail, Inflight Catalogs, Mobile Apps, Airline Website Payment Method: Credit Cards, Mobile Payments, Cash, Loyalty Points |
| Companies Covered | Anuvu, Viasat Inc., Lufthansa Systems, Avolta AG, Gategroup, Panasonic Avionics Corporation, The Emirates Group, SITA, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inflight Shopping Market Strategic Shifts
Digital retail infrastructure is overtaking physical cabin inventory as the primary value creation layer, with software-defined shopping experiences now determining passenger engagement depth and ancillary revenue capture efficiency.
Seatback screen commerce interfaces are supplanting traditional crew-trolley distribution on major carrier fleets. Full-service airlines operating Boeing 787 and Airbus A350 platforms are retrofitting embedded entertainment systems with integrated payment rails. This technology compression eliminates manual cash handling and enables post-purchase fulfillment through airport collection points rather than immediate cabin delivery.
EU Green Deal packaging requirements are mandating biodegradable or recyclable materials for all duty-free product containers sold on European-registered aircraft. Beauty and spirits categories face the steepest compliance curves given historical reliance on laminated boxes and plastic shrink-wrap. Carriers with substantial intra-European operations are consolidating supplier bases around vendors with certified sustainable packaging supply chains.
Passenger purchasing behavior is fragmenting across pre-flight, in-flight, and post-flight touchpoints rather than concentrating in the cabin window. Mobile application pre-ordering captures high-intent buyers before boarding, while arrival lounge fulfillment options extend the transaction window beyond landing. This channel proliferation is most pronounced among business travelers on transatlantic routes who prioritize convenience over immediate possession.
Inflight Shopping Market Segmentation
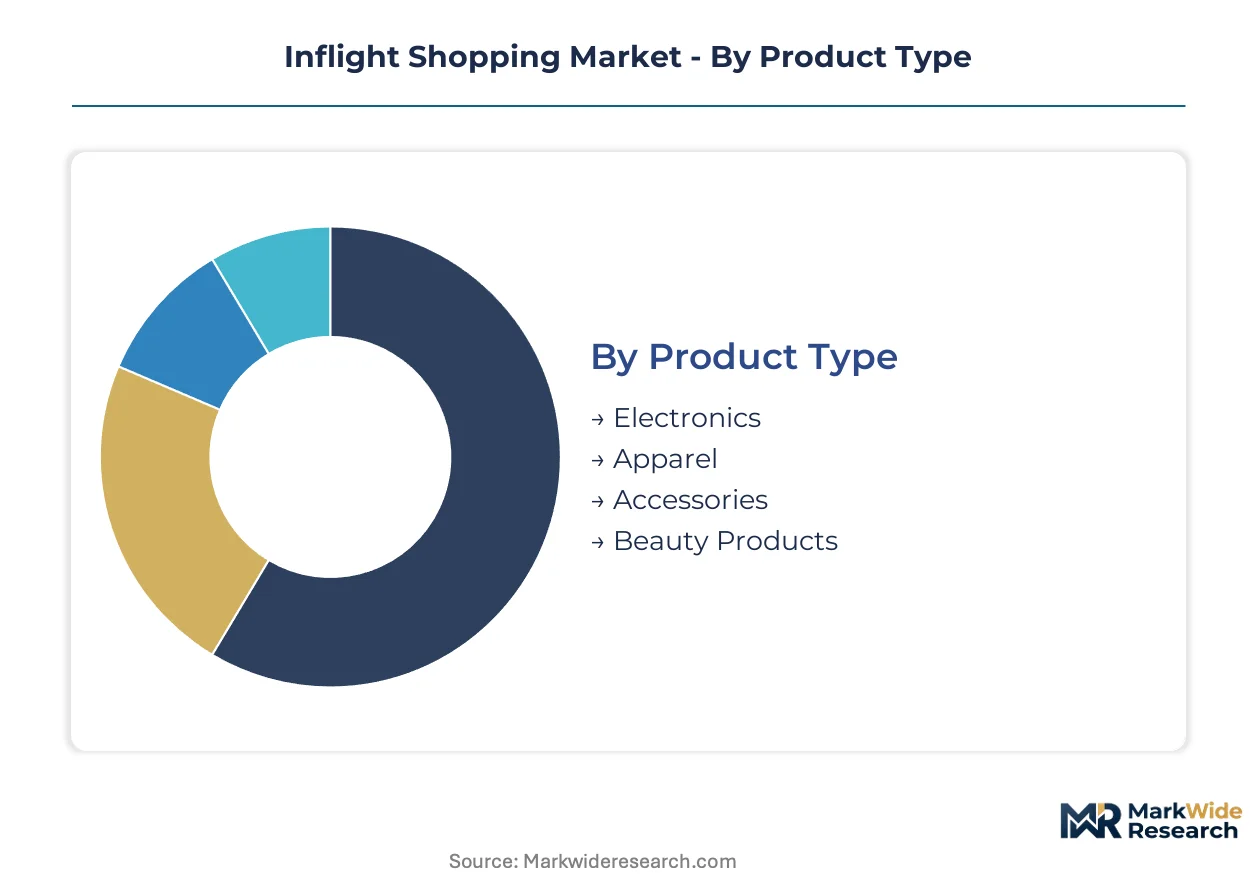
Segmentation in inflight shopping reveals how passenger demographics, product categories, and transaction interfaces fragment revenue capture across carrier networks. Airlines calibrate inventory depth and pricing elasticity differently for each slice, determining which segments warrant dedicated cabin space versus digital-only fulfillment.
Product Type:
Margin pools concentrate in compact, high-perceived-value goods where duty-free exemptions amplify price attractiveness against terrestrial retail benchmarks.
- Electronics:Noise-canceling headphones, portable chargers, and smartwatches dominate transaction values due to functional immediacy during travel. Demand clusters on long-haul routes from Dubai International Airport and Heathrow Terminal 5, where extended flight durations justify premium device purchases.
- Beauty Products:Skincare serums, fragrances, and cosmetics leverage tax-free pricing differentials against downtown department stores. REACH compliance requirements for EU-registered carriers restrict certain chemical formulations, narrowing supplier pools but elevating compliant brand premiums.
- Apparel:Compact accessories like scarves, ties, and travel pillows generate incremental attach rates but carry lower per-unit margins than electronics or beauty.
- Accessories:Sunglasses, jewelry, and leather goods round out cabin inventory with impulse-purchase positioning near galley service points.
The dominant share belongs to Electronics, while Beauty Products is closing the gap fastest as carriers expand skincare assortments for Asian hub routes.
Customer Type:
Volume throughput and spending concentration diverge sharply between occasional vacationers and route-loyal frequent flyers with accumulated loyalty currency.
- Leisure Travelers:Price-sensitive vacationers respond to promotional duty-free pricing on spirits and confectionery. Demand concentrates in seasonal peaks from China and the United Kingdom, where outbound tourism surges drive cabin retail traffic.
- Frequent Flyers:Loyalty program members deploy accumulated points for zero-cash transactions, generating ancillary revenue recognition without immediate payment friction. These passengers concentrate on transatlantic routes operated by full-service carriers with mature redemption platforms.
- Business Travelers:Time-constrained passengers prioritize convenience over browsing, favoring pre-ordered mobile purchases collected at arrival lounges.
- Family Travelers:Multi-passenger groups drive bundled purchases of entertainment devices and snack assortments, though per-capita spending trails individual business travelers.
Leisure Travelers generate the highest transaction counts, though Frequent Flyers deliver superior margin contribution through point-redemption mechanics.
Sales Channel:
Technology deployment costs and passenger interface preferences determine which channels warrant infrastructure investment versus legacy maintenance.
- Mobile Apps:Smartphone-based pre-ordering captures reservation-tender-fulfillment sequences before boarding, eliminating inventory risk and enabling airport collection fulfillment. This channel expands most quickly among business travelers on transatlantic routes who prioritize convenience.
- Onboard Retail:Crew-trolley and seatback screen transactions remain essential for spontaneous purchases during flight segments, particularly on routes with limited pre-flight digital engagement.
- Inflight Catalogs:Printed materials persist on certain long-haul fleets as backup channels where connectivity gaps interrupt digital interfaces.
- Airline Website:Web-based pre-ordering serves passengers who plan purchases during booking or check-in workflows rather than through dedicated mobile applications.
Onboard Retail retains volume leadership on legacy fleets, while Mobile Apps are climbing the fastest as carriers retrofit narrow-body fleets with satellite broadband.
Payment Method:
Authorization speed and cross-border compatibility shape conversion rates across carrier networks with varying banking infrastructure partnerships.
- Credit Cards:Visa and Mastercard networks dominate transaction authorization, though cross-border processing delays persist outside IATA-standardized corridors.
- Loyalty Points:Program currency redemption eliminates cash friction and drives engagement with carrier co-branded credit portfolios.
- Mobile Payments:Apple Pay and Google Wallet integration accelerates on newer seatback entertainment platforms with embedded NFC readers.
- Cash:Physical currency handling declines as carriers eliminate manual transactions, though certain regional operators maintain acceptance for unbanked passenger segments.
Credit Cards process the highest transaction values, while Mobile Payments are gaining share fastest as biometric authentication converges with passenger manifest data.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Business travelers and frequent flyers concentrate purchasing power in hub airport corridors across China, the United Arab Emirates, and the United Kingdom. These passenger archetypes drive premium electronics and beauty transactions during extended dwell times. Hub throughput dynamics reshape inventory deployment strategies for carriers operating from high-volume terminals.
China
Outbound tourism surges from first-tier cities propel seasonal demand spikes for inflight retail. MIIT satellite broadband mandates accelerate cabin connectivity upgrades on domestic narrow-body fleets. Shanghai Pudong International Airport anchors East Asian duty-free volume with concentrated passenger flows through integrated terminal retail zones.
United Arab Emirates
Dubai International Airport generates captive retail audiences through extended connection windows on long-haul routes. MOHAP product registration requirements govern beauty and fragrance formulations sold on UAE-registered aircraft. Abu Dhabi-based carriers deploy biometric payment authentication across A350 and 787 fleets operating European and Asia-Pacific corridors.
United Kingdom
Heathrow Terminal 5 concentrates high-value transactions among transatlantic business travelers with loyalty program currency. REACH compliance frameworks restrict certain chemical formulations in beauty assortments on EU-registered British carriers. London Gatwick and Manchester terminals support pre-order mobile fulfillment through dedicated arrival lounge collection infrastructure.
United States
FAA cabin safety regulations govern stowage protocols and crew time allocation for retail activities during domestic and international segments. Chicago O'Hare and Los Angeles International serve as Pacific corridor hubs where seatback screen commerce interfaces capture spontaneous purchases. Major carriers retrofit legacy fleets with satellite broadband to enable real-time inventory synchronization.
Germany
Lufthansa Systems anchors European inflight retail technology deployment from its Munich operational base. EU Green Deal packaging mandates drive supplier consolidation around biodegradable container vendors for intra-European routes. Frankfurt Airport's Terminal 1 supports integrated pre-order fulfillment through centralized duty-free collection points.
Inflight Shopping Market Competitive Environment
Player mix skews toward integrated technology providers and concession operators with established carrier relationships. The vendor base concentrates around firms combining hardware deployment with software-defined retail platforms. Two strategic archetypes dominate: satellite connectivity specialists enabling real-time transaction processing, and duty-free concession holders managing physical inventory across airport and onboard channels. Competitive moves center on strategic partnerships with full-service carriers and portfolio diversification into pre-order mobile fulfillment systems.
Within the integrated technology tier, Panasonic Avionics Corporation and Thales Group exemplify hardware-software convergence for seatback commerce interfaces. Avolta AG and SITA occupy distinct positions across the concession-operator and passenger-processing vectors respectively. Anuvu and Viasat Inc. represent the connectivity-specialist archetype enabling broadband-dependent retail workflows. These named entities anchor industry-level patterns without specifying individual strategic postures or financial performance.
| Leading Market Players |
|---|
| Anuvu |
| Viasat Inc. |
| Lufthansa Systems |
| Avolta AG |
| Gategroup |
| Panasonic Avionics Corporation |
| The Emirates Group |
| SITA |
| Thales Group |
| Others |
Value Chain & Pricing Dynamics
Long-term concession agreements between airlines and duty-free operators lock in inventory access and margin visibility across multi-year contract windows. These arrangements tether pricing power to passenger throughput guarantees at named hub airports, compressing flexibility when duty-free allowance thresholds shift under bilateral trade negotiations.
Pricing Analysis
Cost-plus contracts with passenger-volume indexation dominate carrier-retailer partnerships, embedding throughput risk into margin calculations. Price differentiation rests on route premiumization and loyalty program integration depth, with transatlantic corridors commanding superior terms against regional feeders. Pricing pressure intensifies as mobile pre-order channels erode captive cabin audiences. Leisure travelers exhibit highest price sensitivity, while frequent flyers redeeming loyalty points show minimal cash-friction responsiveness.
Supply Chain Analysis
Inventory lead times for perishable beauty assortments extend 8-12 weeks given REACH compliance testing and EU Green Deal packaging certification. Supply concentrates in France, Switzerland, and South Korea for fragrance formulations and electronics assembly. Raw material dependencies span lithium-ion cells, biodegradable laminates, and NFC payment hardware. Single-source vulnerability runs through satellite broadband providers enabling real-time inventory sync. Distribution runs through hub airport consolidation centers with bonded warehouse status.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
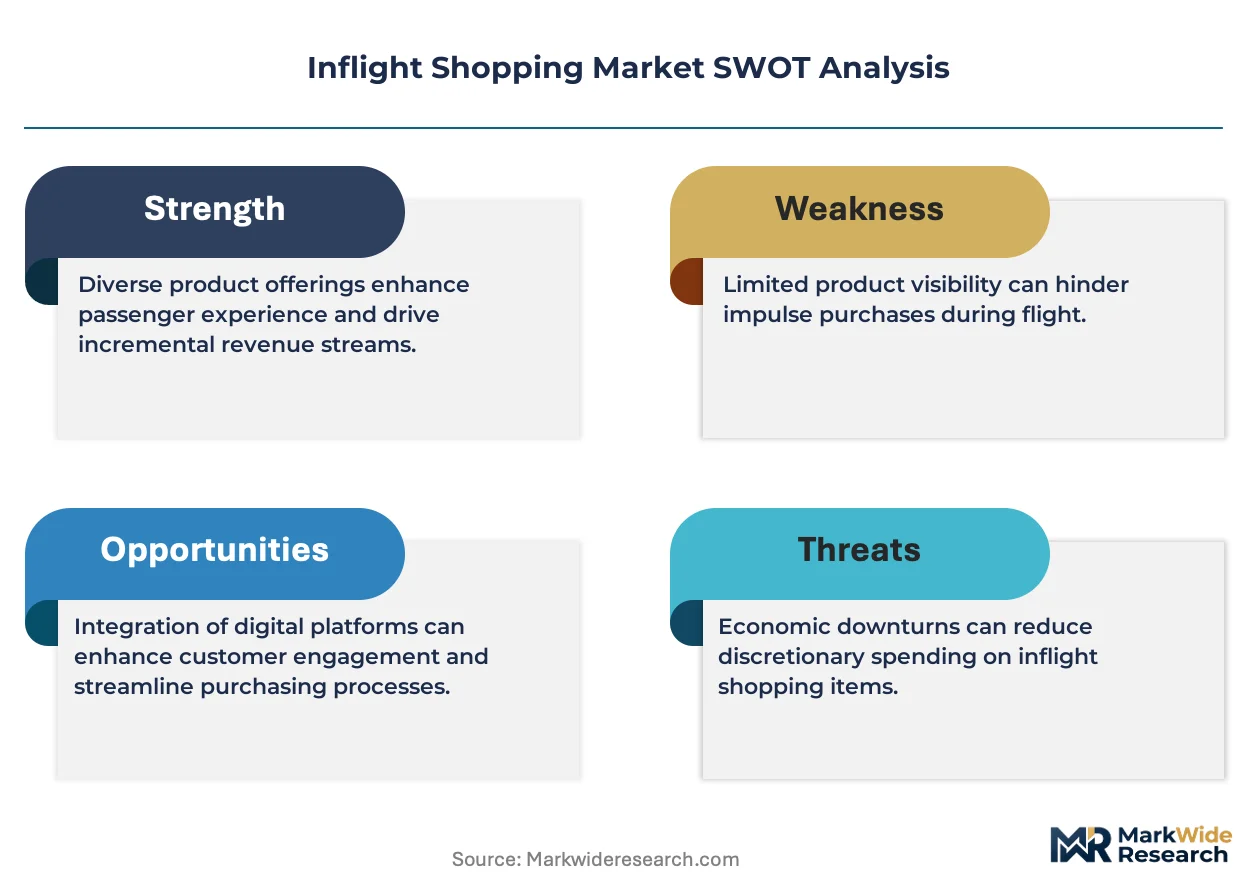
Incumbents face substitution pressure from airport duty-free operators capturing pre-flight spend through mobile pre-order platforms, eroding the captive cabin audience that historically anchored onboard retail economics.
For Market Incumbents: Shield margin pools by deepening vertical integration into pre-order mobile fulfillment systems, bypassing concession fee structures that compress unit economics. Consolidate supplier bases around REACH-compliant and EU Green Deal-certified vendors to preempt regulatory displacement. Channel control through owned-and-operated retail technology stacks, rather than third-party concession dependencies, offers the strongest defensive lever against airport operator encroachment.
For New Entrants and Emerging Players: ISO 9001 certification fast-track positions specialized retail technology vendors for carrier procurement shortlists where incumbent systems face legacy replacement cycles. White-space concentrates in biometric payment authentication for narrow-body fleets and sustainable packaging supply chains for European-registered carriers. Go-to-market traction requires SITA or IATA partnership validation to unlock cross-carrier deployment credibility.
For Investors and Strategic Acquirers: Capital is best deployed toward satellite connectivity specialists with proven narrow-body retrofit track records and established airline procurement relationships. Long-term viability hinges on cabin broadband penetration rates as the enabling infrastructure for software-defined retail. Watch IATA One Order adoption velocity as the inflection signal—carriers migrating to unified digital identity standards will accelerate technology refresh spending.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Payment Integration | Facial recognition authentication eliminates transaction friction on A350 and 787 fleets. |
| Pre-Order Mobile Platform Launch | Airline smartphone apps capture reservation-tender-fulfillment sequences before boarding gates. |
| Sustainable Packaging Certification | EU Green Deal compliance creates first-mover advantages with biodegradable container suppliers. |
| Satellite Broadband Retrofit | Narrow-body fleet connectivity enables real-time inventory synchronization and dynamic pricing. |
| Concession Network Consolidation | Hub airport retail integration captures extended dwell-time purchasing across Dubai and Heathrow. |
Study Parameters
Desk research of IATA operational standards, FAA regulatory filings, and EU REACH compliance databases preceded structured interviews with airline ancillary revenue directors, inflight retail technology vendors, duty-free concession operators, and satellite connectivity providers. Secondary validation drew from carrier annual reports, airport authority throughput statistics, and customs duty-free allowance documentation. Bottom-up passenger spend modeling triangulated against top-down market sizing from aviation industry associations.
Variance decomposition across product type, customer segment, sales channel, and payment method dimensions shaped the analytical framework over the projection horizon. CAGRs derived from logistic adoption curves for cabin connectivity penetration and passenger digital engagement rates. Industry-specific inputs included MIIT satellite broadband mandate implementation timelines and EU Green Deal packaging compliance transition schedules.
Decision-makers should treat outputs as directional under assumptions of sustained hub airport throughput growth and stable duty-free allowance thresholds; material deviation in bilateral trade negotiations or biometric payment adoption velocity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
USA Sustainable Tourism Market
Travel and Tourism
France Culinary Tourism Market
Travel and Tourism
China Outbound Travel Market
Travel and Tourism
Indonesia Sustainable Tourism Market
Travel and Tourism
North America Pet Travel Services Market
Travel and Tourism
Camping and Caravanning Market
Travel and Tourism
Singapore Tourism Market
Travel and Tourism
Luxury Travel Market
Travel and Tourism
Agritourism Market
Travel and Tourism
Yacht Charter Service Market
Travel and Tourism
Japan Travel Retail Market
Travel and Tourism
Solo Ecotourism Market
Travel and Tourism
China Travel Retail Market
Travel and Tourism
Yoga Tourism Market
Travel and Tourism
Greece Tourism Market
Travel and Tourism
Middle East and Africa Travel Retail Market