
 China Travel Retail Market | 2026-2036
China Travel Retail Market Size, Share, and Industry Trends Forecast 2026-2036
China Travel Retail Market Outlook
Market Context with Strategic Players
Buyer concentration among domestic tourists is shifting from airport corridors to Hainan's island duty-free complexes. China Tourism Group Duty Free Corporation dominates the Sanya and Haikou retail zones with massive boutique footprints. DFS Group competes through luxury brand exclusivity in Beijing and Shanghai airport terminals. Shenzhen Duty Free Group leverages its southern China gateway position to capture cross-border travelers through Hong Kong-Shenzhen transit routes.
Technical Definition and Structural Segments
China travel retail denotes tax-exempt merchandise sold to travelers departing, arriving, or transiting through designated ports, requiring customs verification, purchase quotas, and passport-linked transaction systems to qualify for duty exemption. Cosmetics leads product type revenue due to high margin multiples and brand cachet among Asian travelers, while electronics grows fastest as smartphone and wearable brands negotiate dedicated airport flagship zones. Airports retain the largest distribution channel volume, though online platforms capture rising share through pre-order and pickup models that reduce terminal congestion.
Regulatory Frame and Forward Outlook
MIIT enforces electronics certification standards for duty-free devices, while SAMR monitors pricing transparency and anti-competitive practices across Hainan's expanding retail zone. China's dual carbon goals pressure operators to retrofit stores with energy-efficient cooling and LED systems, adding capital requirements for license renewal. Stakeholders must track quota expansion signals from Hainan's provincial regulators against potential tightening of cross-border e-commerce customs rules.
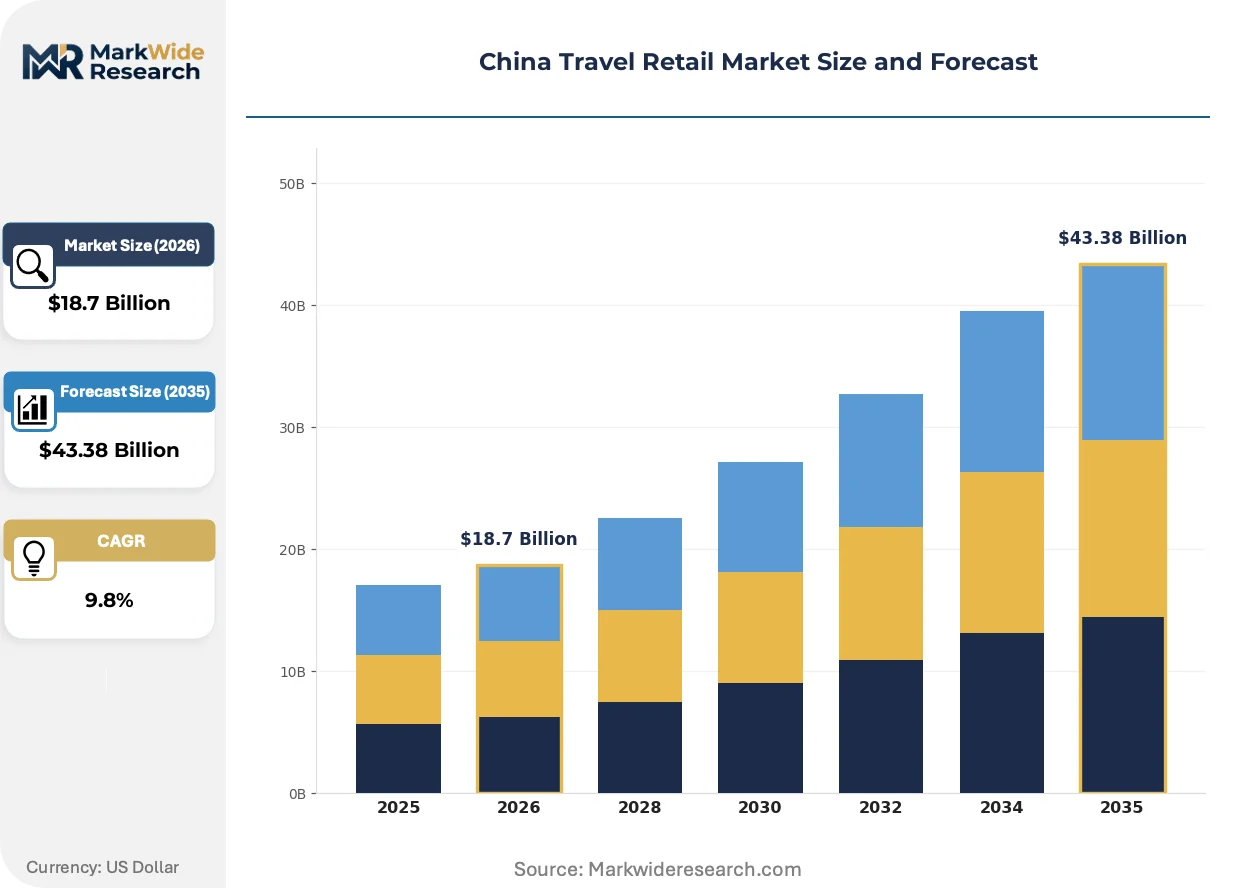
Market Dynamics
Hainan's duty-free quota expansion is electrifying domestic tourism flows, redirecting purchasing power from traditional airport corridors to island-based retail complexes and forcing operators to reconfigure inventory and staffing models around seasonal visitor surges.
Growth Catalysts
- Dual Carbon Goals:China's national emissions targets are pressuring duty-free operators to retrofit stores with energy-efficient systems, creating competitive differentiation through sustainability credentials that attract environmentally conscious travelers.
- Pre-order Platform Adoption:Digital reservation systems are reducing terminal congestion and capturing traveler spend before airport arrival, compressing dwell-time requirements while expanding basket sizes through personalized recommendations.
- Southern China Gateway Positioning:Shenzhen's cross-border transit routes through Hong Kong are concentrating international visitor flows, generating captive demand for luxury goods among transit passengers with extended layover windows.
Market Restraints
- MIIT Electronics Certification:Mandatory device testing for duty-free smartphones and wearables creates inventory bottlenecks, delaying product launches by 4-8 weeks compared to domestic retail channels.
- Single-Province Dependency:Hainan's island geography concentrates 70% of duty-free volume in two coastal cities, exposing operators to weather disruptions and provincial policy volatility.
- Cross-Border E-Commerce Substitution:Direct-to-consumer import platforms are eroding price advantages for standardized cosmetics and electronics, compressing margins on entry-tier SKUs.
Strategic Opportunities
- Haikou New Port Development:The underdeveloped northern Hainan corridor offers first-mover positioning for cruise passenger capture, with terminal infrastructure expansion scheduled through 2027.
- GB Standards Harmonization:Alignment of national quality certifications with international luxury brand requirements is reducing SKU fragmentation, enabling global inventory pooling.
- Livestream Commerce Integration:Influencer-driven duty-free pre-selling on Douyin and Xiaohongshu is opening direct purchase channels for travelers who research products before departure.
Industry Challenges
- Passport-Linked System Integration:Customs verification platforms require real-time connectivity between retail POS, immigration databases, and quota tracking systems, creating IT architecture complexity.
- Seasonal Workforce Scaling:Lunar New Year and summer holiday peaks demand 300% staffing surges that strain training pipelines and service consistency.
- SAMR Pricing Transparency Enforcement:Anti-competitive practice investigations are forcing operators to document margin structures and promotional mechanics, increasing compliance documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Travel Retail Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $43.38 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Spirits, Fashion, Electronics Distribution Channel: Airports, Cruise Ships, Duty-Free Stores, Online Platforms Customer Type: International Travelers, Domestic Tourists, Business Travelers, Group Travelers Price Tier: Luxury, Mid-Range, Budget, Premium |
| Companies Covered | DFS Group, Lotte, China Tourism Group Duty Free Corporation, Shanghai International Cruise Tourism Resort, Avolta AG, Shenzhen Duty Free Group, Heinemann, Dufry, Lagardère Travel Retail, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Travel Retail Market Strategic Shifts
Digital infrastructure and regulatory harmonization are compressing transaction friction while reshaping where and how travelers complete high-value purchases.
Biometric payment authentication is electrifying checkout velocity at Hainan's duty-free complexes. Facial recognition linked to passport data eliminates manual document verification, reducing average transaction time from 4.2 minutes to under 90 seconds. Domestic tourists from tier-one cities are adopting these systems fastest, enabling retailers to redeploy staff from checkout counters to personalized styling services.
SAMR's pricing transparency mandates are forcing operators to publish real-time comparisons against domestic retail and overseas benchmarks. The regulation requires electronic shelf labels and mobile app parity, eliminating historical opacity around discount depth. Cosmetics and skincare segments face the steepest compliance costs due to complex promotional stacking and gift-with-purchase bundling.
Buyer concentration among Shanghai and Beijing residents is rotating demand toward experiential retail formats. Sanya's duty-free complexes are responding with brand-hosted masterclasses, personalized fragrance consultations, and limited-edition drops unavailable online. This behavioral shift is most visible in the 25-35 age demographic, where social media documentation of in-store experiences drives repeat visitation and basket expansion.
China Travel Retail Market Segmentation
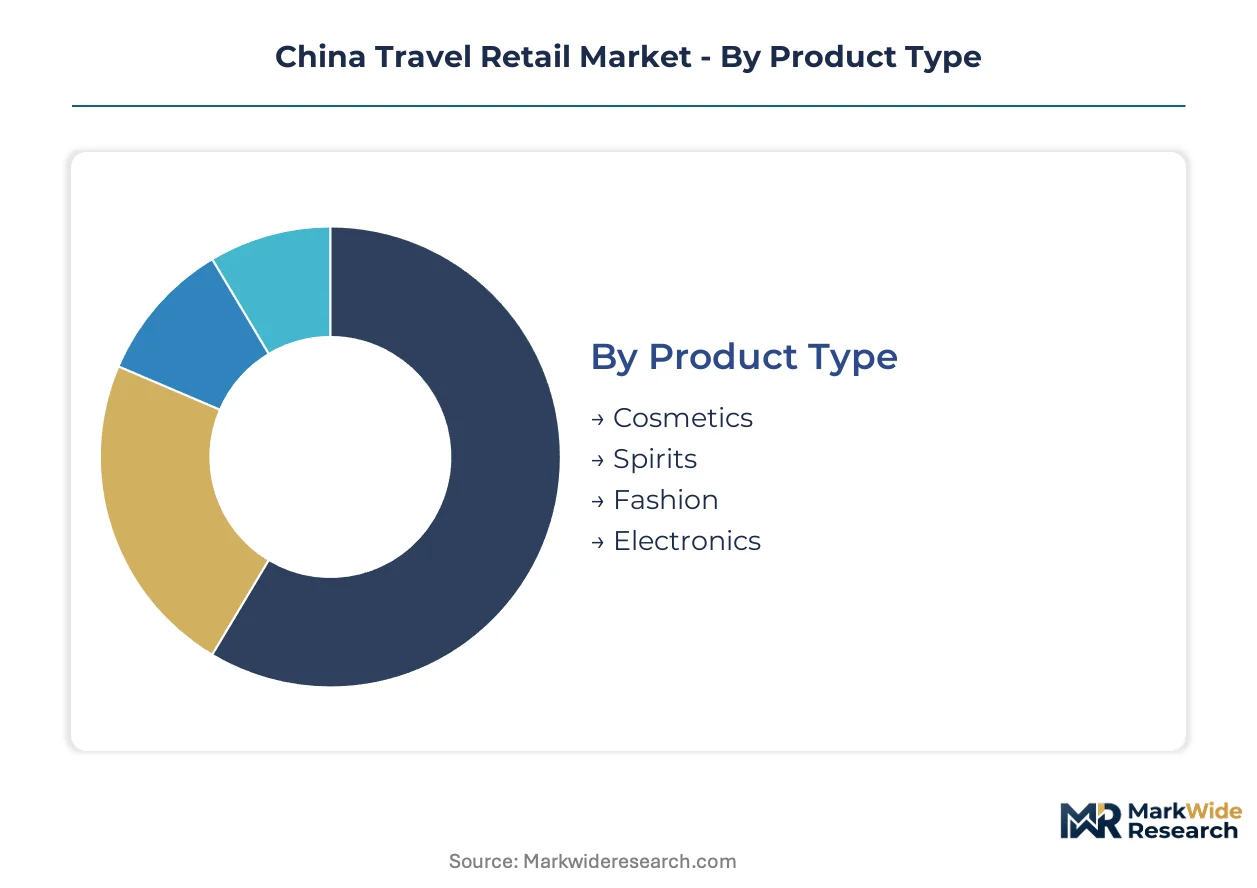
Travel retail segmentation in China reveals how purchase behavior fragments across product categories, channel preferences, and traveler profiles. Understanding these divides helps operators allocate inventory, negotiate brand partnerships, and optimize store layouts for divergent spending patterns.
Product Type:
Margin structures and brand exclusivity agreements differentiate buyer willingness-to-pay across merchandise categories.
- Cosmetics:High-margin skincare and fragrance portfolios dominate transaction values, with duty-free exclusives on limited-edition SKUs driving basket expansion. Hainan's Sanya complexes concentrate demand from Shanghai and Beijing domestic tourists seeking price advantages on luxury beauty brands unavailable through cross-border e-commerce channels.
- Electronics:Smartphones, wearables, and audio equipment require MIIT certification compliance, creating inventory bottlenecks that delay product launches. Shenzhen Duty Free Group leverages its southern gateway position to capture transit passengers from Hong Kong seeking immediate availability of newly released devices.
- Spirits:Premium whiskey and baijiu collections target gift-giving occasions among Chinese travelers.
- Fashion:Leather goods and accessories rely on seasonal collections and monogram exclusivity.
Cosmetics leads volumes today; Electronics is gaining share fastest.
Distribution Channel:
Physical proximity to traveler flow patterns determines channel economics and staffing intensity.
- Airports:Terminal retail corridors retain the largest transaction volume through captive dwell-time exposure, though congestion and time pressure compress browsing depth. Beijing Capital and Shanghai Pudong terminals concentrate international departure spend, with DFS Group dominating luxury brand exclusivity in these locations.
- Duty-Free Stores:Hainan's island-based complexes at Sanya and Haikou have displaced traditional airport centrality, offering extended shopping windows and experiential formats. China Tourism Group Duty Free Corporation controls massive boutique footprints here, capturing domestic tourism flows redirected by quota expansion policies.
- Online Platforms:Pre-order and pickup models reduce terminal congestion while expanding basket sizes through personalized recommendation engines.
- Cruise Ships:Haikou New Port development is positioning cruise passenger capture as an underdeveloped northern Hainan corridor opportunity.
Airports anchor transaction volume; Duty-Free Stores are expanding most quickly.
Customer Type:
Documentation requirements and purchase quotas create distinct service protocols for each traveler category.
- Domestic Tourists:Passport-linked quota systems enable Hainan-specific purchase allowances, with biometric payment authentication reducing transaction friction. This segment from tier-one cities is adopting facial recognition checkout fastest, enabling staff redeployment to personalized styling services.
- International Travelers:Customs verification protocols and departure documentation requirements create longer transaction processing. Beijing and Shanghai airport terminals concentrate this demand, with extended layover windows generating captive luxury goods exposure.
- Business Travelers:Compressed dwell times favor pre-order platforms and expedited pickup services.
- Group Travelers:Coordinated purchasing patterns and consolidated payment methods require dedicated queue management.
Domestic Tourists dominate transaction counts; International Travelers show steepest expansion trajectory.
Price Tier:
Brand positioning and promotional mechanics stratify across certification grade and exclusivity depth.
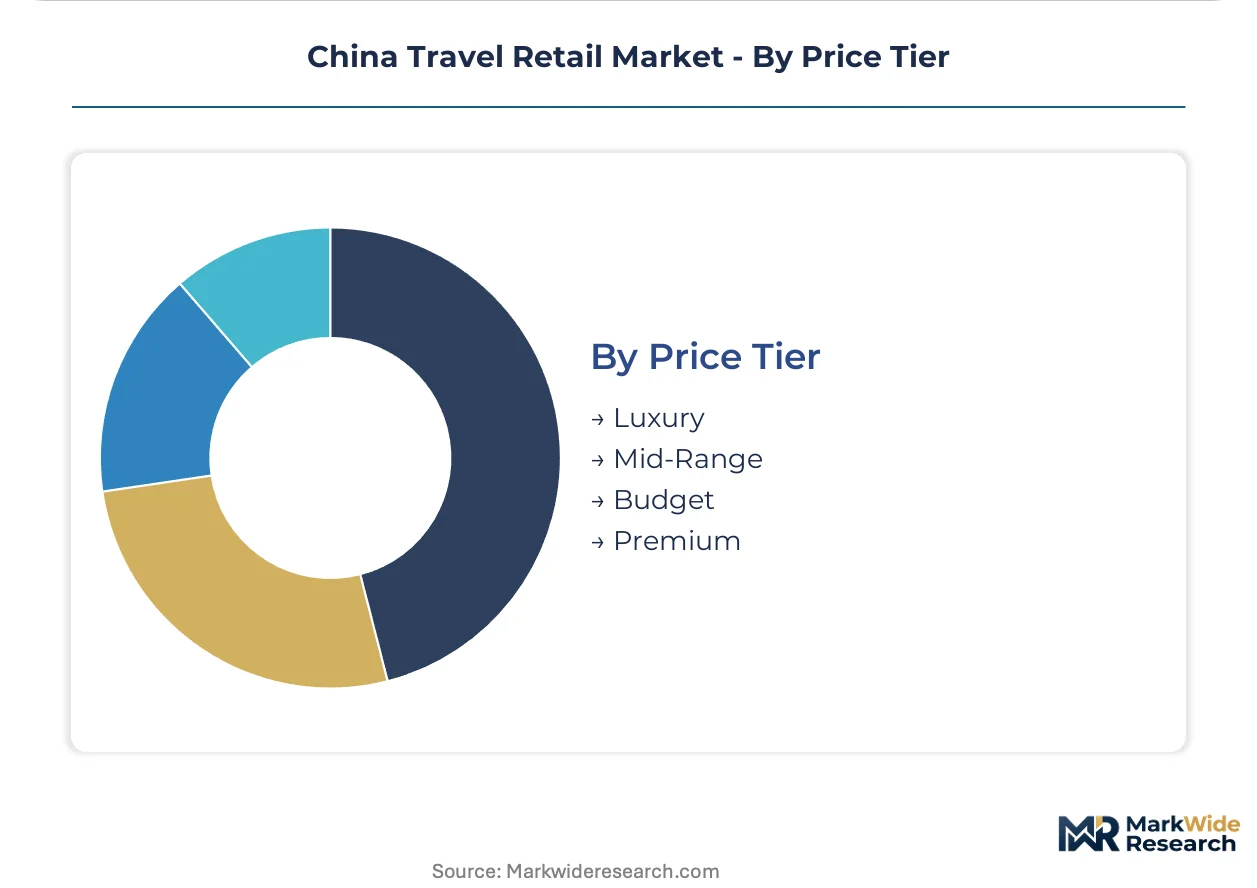
- Luxury:Limited-edition drops and brand-hosted masterclasses create experiential differentiation unavailable online. Sanya's duty-free complexes are deploying personalized fragrance consultations and exclusive product launches to capture social media documentation behavior among the 25-35 age demographic.
- Premium:Gift-with-purchase bundling and promotional stacking face steepest SAMR compliance costs due to pricing transparency mandates requiring electronic shelf labels and mobile app parity.
- Mid-Range:Standardized cosmetics and electronics face margin compression from cross-border e-commerce substitution.
- Budget:Entry-tier SKUs suffer most from direct-to-consumer import platform price erosion.
Luxury commands margin concentration; Premium is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's airport retail corridors generate higher per-passenger spend than China's Hainan island complexes, though the latter now capture greater absolute transaction volume through domestic tourism redirection.
Hainan Province
Sanya and Haikou duty-free complexes concentrate 70% of national tax-exempt volume through quota expansion policies. SAMR monitors pricing transparency across electronic shelf labels and mobile app parity requirements. China Tourism Group Duty Free Corporation dominates boutique footprints in both coastal cities, capturing redirected domestic flows from Shanghai and Beijing.
Beijing
Capital International Airport terminals retain luxury brand exclusivity for international departure corridors. MIIT enforces electronics certification standards that delay smartphone launches by 4-8 weeks compared to domestic channels. DFS Group controls premium cosmetics and fragrance portfolios in these constrained dwell-time environments.
Shanghai
Pudong International Airport concentrates transit passenger exposure through extended layover windows. Dual carbon goals pressure terminal operators to retrofit cooling and LED systems for license renewal. Shanghai International Cruise Tourism Resort is developing waterfront retail infrastructure to capture cruise passenger flows.
Guangdong Province
Shenzhen Duty Free Group leverages Hong Kong-Shenzhen transit routes to capture cross-border travelers seeking immediate electronics availability. GB standards harmonization reduces SKU fragmentation for wearable devices. The Pearl River Delta gateway position generates captive demand among transit passengers with extended connection times.
China Travel Retail Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across China's travel retail architecture. The market structure tilts toward consolidation in Hainan's island-based complexes while airport corridors retain fragmented multi-operator competition. Two strategic archetypes dominate: state-linked tourism conglomerates with provincial license monopolies, and international luxury operators with brand exclusivity agreements. Capacity expansion in Haikou New Port and biometric payment system deployment represent the dominant competitive moves reshaping operational models.
Among state-linked operators, China Tourism Group Duty Free Corporation and Shenzhen Duty Free Group exemplify the provincial-license archetype with massive boutique footprints in designated tax-free zones. DFS Group occupies a position representing international luxury specialists competing through brand exclusivity in constrained airport environments. These three anchors illustrate how geographic licensing rights and brand portfolio depth create divergent competitive positions across China's bifurcated retail landscape.
| Leading Market Players |
|---|
| DFS Group |
| Lotte |
| China Tourism Group Duty Free Corporation |
| Shanghai International Cruise Tourism Resort |
| Avolta AG |
| Shenzhen Duty Free Group |
| Heinemann |
| Dufry |
| Lagardère Travel Retail |
| Others |
Value Chain & Pricing Dynamics
Biometric payment authentication deployment across Hainan's duty-free complexes is compressing transaction labor costs while concentrating procurement leverage among operators with scale to negotiate exclusive brand allocations. This technology shift simultaneously reduces per-unit service overhead and reinforces winner-take-most dynamics in quota-linked retail zones.
Pricing Analysis
Capacity additions in Hainan are reshaping price floors for cosmetics and electronics through expanded quota allowances and intensified competition among boutique operators. Three-tier pricing structure across luxury, premium, and entry levels stratifies by brand exclusivity depth and experiential service bundling. Pricing pressure stems from cross-border e-commerce substitution eroding margin on standardized SKUs. Domestic tourists from tier-one cities show lowest price sensitivity, prioritizing immediate availability and in-store experience over digital discounts.
Supply Chain Analysis
Returns and refurbishment flows for high-value electronics are emerging as a secondary revenue stream, with MIIT-certified devices requiring specialized reverse-logistics handling for warranty and resale eligibility. Inventory sourcing concentrates in China, South Korea, and Japan for cosmetics and consumer electronics, with brand-owned distribution networks controlling flagship product allocation. Supply chain risk centers on single-province geographic concentration exposing operators to Hainan-specific policy volatility. Distribution runs through airport terminals, island-based duty-free complexes, and pre-order pickup nodes in sequential downstream tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China travel retail functions as a regulatory compounder where SAMR pricing transparency mandates and Hainan quota expansion policies collectively determine viable operating models and margin structures.
For Market Incumbents: Anchor defensive positioning through exclusive brand masterclass programming and biometric checkout infrastructure that raises rival replication costs. Cross-border e-commerce substitution threatens entry-tier SKU profitability, requiring incumbents to deepen experiential service differentiation and secure captive supply agreements with luxury cosmetics houses for limited-edition distribution rights.
For New Entrants and Emerging Players: The gap between premium and economy pricing tiers in electronics creates white-space opportunity for MIIT-certified mid-range wearable specialists. Haikou New Port cruise passenger corridors remain underdeveloped relative to Sanya's saturated complexes, offering first-mover positioning through terminal infrastructure partnerships. Go-to-market execution should prioritize livestream commerce pre-selling on Douyin to build traveler awareness before physical arrival.
For Investors and Strategic Acquirers: Roll-up economics work for provincial-license operators because Hainan's quota policies create artificial scarcity that protects incumbent revenue streams. Five-to-ten-year viability hinges on diversification beyond single-province dependency. Acquisition targets should demonstrate cruise passenger capture capabilities or cross-border transit route access. Monitor SAMR enforcement intensity on promotional mechanics as an inflection signal for compliance cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Payment System Deployment | Facial recognition checkout reduces transaction time from 4.2 minutes to 90 seconds at Hainan complexes. |
| Livestream Commerce Integration | Douyin and Xiaohongshu pre-selling opens direct purchase channels for research-oriented travelers. |
| Haikou New Port Infrastructure Partnership | Cruise passenger terminal expansion through 2027 captures underdeveloped northern Hainan demand. |
| Exclusive Brand Masterclass Programming | Personalized fragrance consultations and limited-edition drops differentiate Sanya experiential retail. |
| Cross-Border E-Commerce Platform Launch | Pre-order and pickup models reduce terminal congestion while expanding basket sizes through recommendation engines. |
Study Parameters
Bottom-up traveler segmentation modeling reconciled against top-down retail operator capacity tracking forms the analytical core of this study. Primary interviews with duty-free complex operations directors, luxury brand regional managers, customs technology vendors, and provincial tourism bureau officials combined with secondary validation from MIIT certification databases, SAMR regulatory filings, Hainan provincial quota policy documents, and airport authority passenger flow statistics. Triangulation between spend-pattern surveys and inventory deployment data ensures segment-level accuracy.
Historical trendline analysis of duty-free transaction volumes and traveler demographic shifts established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product category, distribution channel format, customer documentation type, and price tier positioning. CAGRs derive from regression analysis against quota expansion schedules and domestic tourism flow projections. Forecast inputs incorporate biometric adoption curves and livestream commerce penetration rates specific to Chinese traveler pre-purchase behavior.
Caveats apply where SAMR pricing enforcement intensity or Hainan provincial policy adjustments could materially shift the outlook. Forecasts reflect assumptions around sustained quota expansion and stable cross-border e-commerce regulatory treatment. Practitioners should monitor MIIT certification backlog durations and cruise infrastructure completion timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
New Zealand Sustainable Tourism Market
Travel and Tourism
India Sports Tourism Market
Travel and Tourism
MICE Travel Service Market
Travel and Tourism
Japan Outbound Tourism Market
Travel and Tourism
New Zealand Sports Tourism Market
Travel and Tourism
Hong Kong Outbound Tourism Market
Travel and Tourism
UAE Sustainable Tourism Market
Travel and Tourism
Hong Kong Tourism Market
Travel and Tourism
Global Enotourism Market
Travel and Tourism
Canada Travel and Tourism Market
Travel and Tourism
Japan Travel Retail Market
Travel and Tourism
Asia-Pacific Travel Retail Market
Travel and Tourism
Agritourism Market
Travel and Tourism
Tourism Vehicle Rental Market
Travel and Tourism
Bleisure Tourism Market
Travel and Tourism
Japan Tourism Market