
 India Outbound Tourism Market | 2026-2036
India Outbound Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
India Outbound Tourism Market Outlook
Digital booking platforms is restructuring how Indian travelers discover and purchase international itineraries, collapsing traditional agent-mediated workflows into app-based transactions. MakeMyTrip leverages its first-mover advantage in mobile-first bookings to dominate the online channel. Yatra Online competes through corporate travel specialization and loyalty program depth. SOTC Travel anchors its position in group leisure packages, particularly for religious and senior-citizen segments.
India outbound tourism encompasses all resident-initiated international travel for leisure, business, medical treatment, or pilgrimage, requiring valid passports, visas, and foreign currency transactions processed through authorized dealer banks. The sector functions as a foreign exchange outflow channel governed by RBI's Liberalized Remittance Scheme, with air access constrained by bilateral aviation agreements and airport slot allocations. Leisure travel occupies the largest value pool among destination types, while medical tourism records the fastest expansion driven by cost arbitrage in complex procedures. Booking channel dynamics reveal online travel agencies capturing share from traditional travel agents, though high-consideration itineraries still depend on agent-assisted customization for visa-heavy destinations.
RBI's LRS framework, Ministry of Tourism's outbound promotion policies, and DGCA's bilateral capacity negotiations collectively shape market access and consumer spending ceilings. BIS standards for travel insurance products and emigration clearance requirements for certain worker categories add compliance layers to specific outbound flows. Stakeholders must monitor evolving aviation treaty expansions and fintech regulatory clarity around cross-border payment wallets to anticipate channel disruption and destination accessibility shifts.
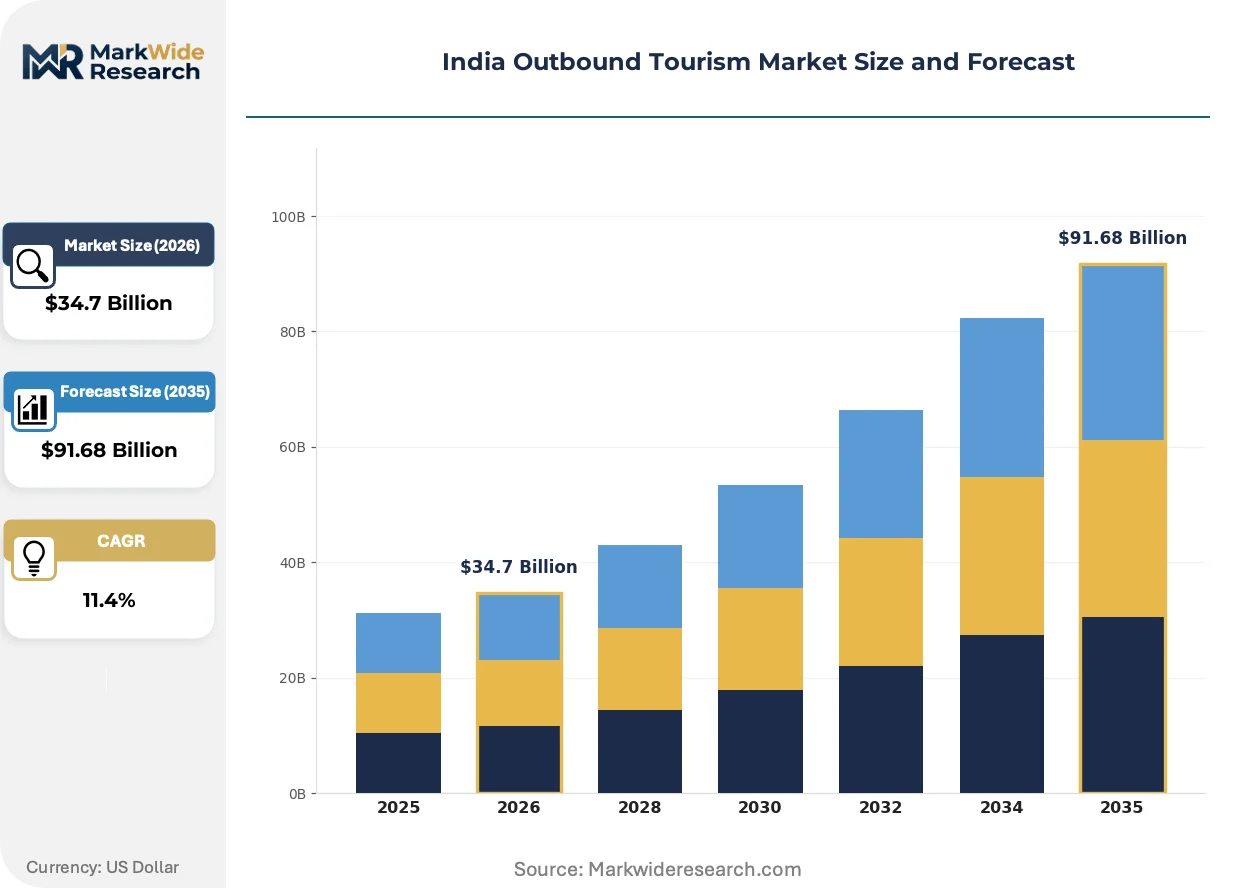
Market Dynamics
RBI's Liberalized Remittance Scheme has dismantled capital controls that historically constrained Indian overseas spending, converting latent travel demand into executable transactions through higher annual foreign exchange allowances.
Growth Catalysts
- Liberalized Remittance Scheme:RBI's annual foreign exchange ceiling expansion permits larger family travel budgets and multi-destination itineraries without prior approval requirements.
- Young professionals:Dual-income millennial households prioritize experiential consumption over asset accumulation, directing discretionary surplus toward international leisure.
- Visa facilitation:Thailand, Malaysia, and Indonesia have implemented e-visa or visa-on-arrival protocols specifically targeting Indian passport holders.
Market Restraints
- Bilateral aviation capacity:DGCA's slot allocations and air service agreements limit seat supply on high-demand routes, inflating fares during peak seasons.
- Documentation friction:Schengen and North American visa processing timelines create booking uncertainty that suppresses long-haul demand.
- Rupee volatility:Exchange rate fluctuations against the dollar and euro compress real purchasing power for destination spending.
Strategic Opportunities
- Tier-2 city penetration:Ahmedabad, Kochi, and Chandigarh exhibit rising outbound propensity with underserved direct air connectivity.
- Medical tourism packaging:Cost arbitrage in cardiac and orthopedic procedures attracts Indian patients to Thailand, Turkey, and UAE facilities.
- Fintech integration:Cross-border payment wallets and travel-specific credit products reduce foreign exchange transaction friction.
Industry Challenges
- Skilled counselor shortage:Complex visa-heavy itineraries require trained agents, but talent attrition to digital platforms erodes service quality.
- Legacy system integration:Traditional travel agencies struggle to synchronize offline customer relationships with online booking engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Outbound Tourism Market |
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $91.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Destination Type: Leisure, Business, Medical, Religious Customer Demographics: Families, Couples, Solo Travelers, Groups Booking Channel: Online Travel Agencies, Direct Bookings, Travel Agents, Mobile Apps Travel Duration: Short Trips, Medium Length Stays, Long Vacations, Weekend Getaways |
| Companies Covered | Kesari Tours, In Orbit Tours, Thomas Cook India, Yatra Online, MakeMyTrip, SOTC Travel, Raj Travels, Goibibo, Orbit Travels, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Outbound Tourism Market Strategic Shifts
Digital infrastructure is collapsing the traditional travel agency model into algorithmic discovery and instant confirmation, reshaping how Indian travelers research, compare, and commit to international itineraries.
Artificial intelligence is integrating dynamic personalization into mobile booking platforms. MakeMyTrip and similar aggregators deploy machine learning to predict traveler preferences from search patterns. Young professionals receive tailored destination recommendations without human consultation. The technology is integrating predictive pricing and inventory optimization that compresses decision cycles from weeks to hours.
RBI's enhanced remittance thresholds under LRS are expanding permissible transaction ceilings for education-linked and medical travel. The central bank's periodic calibration of foreign exchange limits directly determines market-accessible spending capacity. Family travelers and senior citizens benefit most from simplified documentation requirements for authorized dealer bank transactions.
Channel disintermediation is fragmenting booking pathways across Instagram discovery, influencer referral codes, and direct airline apps. Traditional travel agents retain relevance only for visa-complex destinations like the United States and United Kingdom. Urban millennials in Mumbai and Delhi demonstrate the highest comfort with fully digital itinerary construction and payment.
India Outbound Tourism Market Segmentation
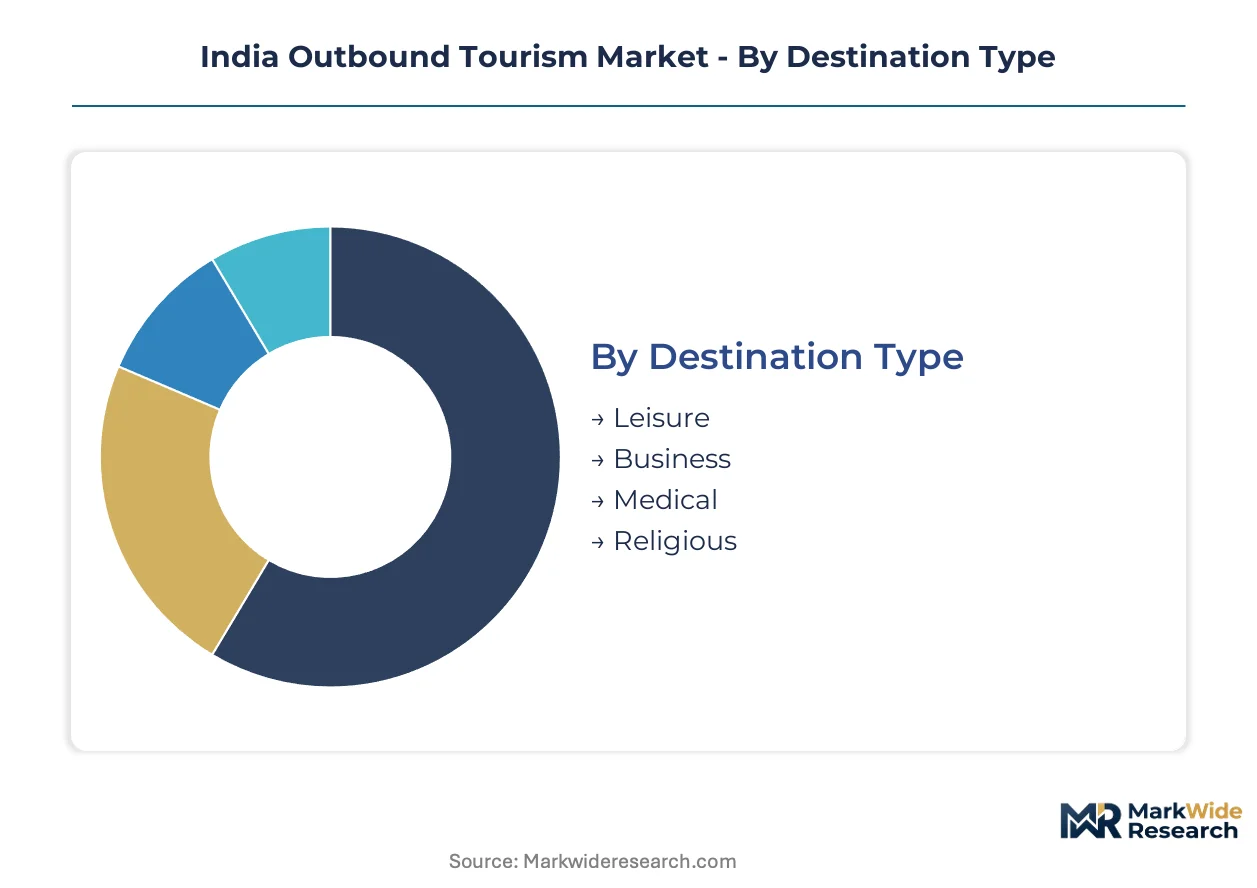
Outbound tourism from India fragments across four distinct category axes, each revealing divergent spending patterns and service requirements. Understanding these divisions enables stakeholders to align inventory, pricing, and distribution investments with actual traveler behavior rather than aggregate demand assumptions.
Destination Type:
Supply concentration in visa facilitation and air access privileges certain destination categories over others, creating tiered market accessibility.
- Leisure:Beach resorts, cultural circuits, and adventure experiences dominate outbound volume from India. Demand concentrates in Thailand, Malaysia, and Indonesia where e-visa protocols eliminate documentation friction for Mumbai and Delhi metro travelers.
- Medical:Cardiac surgery, orthopedics, and fertility treatments drive patient flows to Thailand, Turkey, and UAE hospitals. Cost arbitrage of 60-70% versus domestic private facilities sustains this segment's expansion trajectory.
- Business:Corporate travel for conferences, client meetings, and trade exhibitions follows manufacturing and IT sector expansion patterns. Singapore and Dubai capture disproportionate share due to regional headquarters concentration.
- Religious:Pilgrimage circuits to Mecca, Jerusalem, Buddhist sites in Southeast Asia, and Catholic destinations in Europe serve distinct demographic cohorts with specialized package requirements.
Today's leader: Leisure. Tomorrow's challenger: Medical.
Customer Demographics:
Cost tier differentiation separates mass-market family packages from premium couple and solo traveler offerings.
- Families:Multi-generational travel units prioritize safety, connectivity, and value-conscious accommodation. Demand clusters in summer holiday windows and festival periods when school calendars align.
- Couples:Honeymoon and anniversary travelers command premium pricing for seclusion and experiential add-ons. Maldives, Switzerland, and Greece concentrate this high-yield segment.
- Solo Travelers:Young professionals and retirees pursuing independent exploration favor flexible itineraries with single-occupancy room options. Hostel networks and co-living accommodations serve this emerging cohort.
- Groups:Corporate incentive travel and friend-circle expeditions require block booking coordination. SOTC and specialized operators dominate this channel with negotiated rate structures.
Volume concentration favors families; margin expansion tracks couples and solo travelers.
Booking Channel:
Application-based segmentation separates convenience-driven digital adoption from complexity-necessitated human assistance.
- Online Travel Agencies:Aggregator platforms consolidate flight, hotel, and activity inventory with dynamic pricing algorithms. Mobile-first interfaces capture urban millennial preference for self-service itinerary construction.
- Direct Bookings:Airline and hotel proprietary channels bypass intermediary commissions through loyalty program incentives and exclusive rate guarantees. Full-service carriers leverage this pathway for premium cabin sales.
- Travel Agents:Human counselors retain relevance for Schengen, UK, and US visa-heavy destinations requiring documentation guidance. Traditional agencies face talent attrition to digital platforms.
- Mobile Apps:Smartphone-native booking interfaces integrate payment wallets and real-time itinerary management. Push notification pricing alerts compress decision cycles for impulse-driven travelers.
Digital channels gain share fastest; agent-assisted booking defends position in visa-complex corridors.
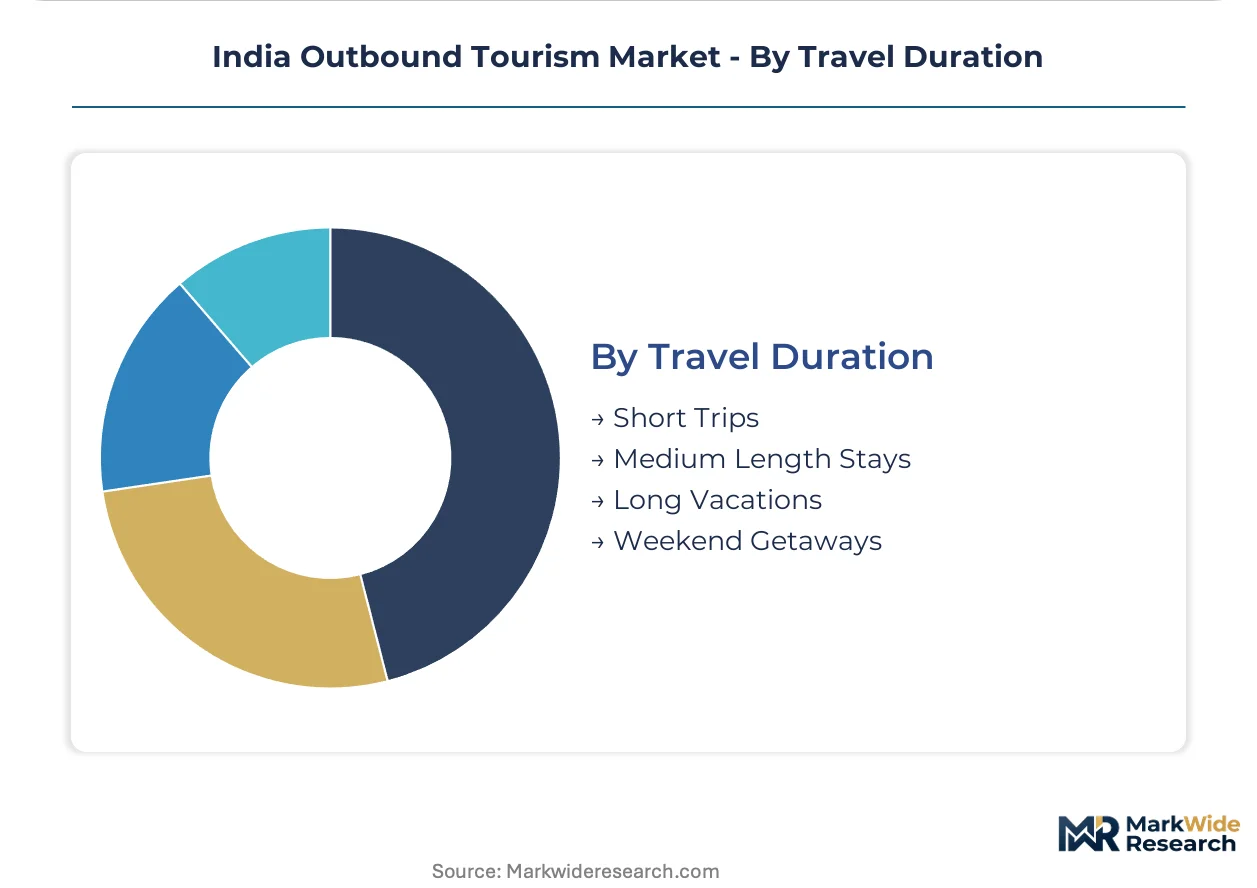
Travel Duration:
Geography within India shapes duration preference, with tier-1 city residents exhibiting distinct patterns from tier-2 emerging markets.
- Short Trips:Three-to-five-day itineraries to Dubai, Singapore, and Bangkok accommodate limited leave allowances. Budget carriers and long-weekend scheduling maximize accessibility for time-constrained professionals.
- Medium Length Stays:Seven-to-fourteen-day vacations enable multi-city European or East Asian circuits. This duration tier requires advance planning and aligns with annual leave entitlements.
- Long Vacations:Extended sabbatical and retirement travel supports immersive cultural exploration. Australia, New Zealand, and extended European itineraries serve this demographic.
- Weekend Getaways:Forty-eight-to-seventy-two-hour escapes to Colombo, Kathmandu, or Muscat exploit proximity and minimal jet lag. Ultra-short-haul demand concentrates in western and southern India with superior Middle East connectivity.
Short trips command volume leadership; medium stays generate highest per-capita expenditure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors outbound tourism demand generation through its concentration of dual-income households and direct air connectivity to Southeast Asian and Middle Eastern destinations. The city's travel ecosystem processes the highest volume of foreign exchange remittances under RBI's Liberalized Remittance Scheme.
Maharashtra
Mumbai and Pune generate premium leisure demand for Maldives and European honeymoon circuits. RBI's LRS documentation simplification benefits family travelers from these metros. Thane's emerging suburbs exhibit rising short-haul booking frequency to Dubai and Singapore.
Delhi-NCR
The capital region drives religious tourism volume to Saudi Arabia and Southeast Asian Buddhist sites. BIS-mandated travel insurance standards protect pilgrims on organized group departures. Gurugram's corporate headquarters sustain business travel corridors to Singapore and Dubai.
Gujarat
Ahmedabad's textile and diamond trading communities generate diaspora-linked travel to Belgium, Israel, and the United Arab Emirates. DGCA's bilateral capacity negotiations with UAE carriers expanded direct seat supply from Sardar Vallabhbhai Patel International Airport. Surat's emerging affluence supports family leisure packages to Thailand.
Karnataka
Bengaluru's technology workforce prioritizes experiential leisure to Vietnam and Indonesia. Visa facilitation agreements with Southeast Asian nations reduced documentation friction for software professionals. The city's Kempegowda International Airport secured additional bilateral slots to Middle Eastern hubs.
Telangana
Hyderabad's pharmaceutical and IT sectors generate corporate travel demand to European regulatory destinations. The state's outbound propensity concentrates in medium-length stays for medical tourism to Turkey and Thailand. Rajiv Gandhi International Airport expanded Middle East carrier partnerships.
India Outbound Tourism Market Competitive Environment
Portfolio diversification dominates the current landscape as operators defend share against algorithmic booking platforms. The market exhibits tiered concentration with national aggregators, regional specialists, and legacy package tour operators coexisting. Three archetypes define competitive positioning: mobile-first aggregators with inventory breadth, corporate travel specialists with loyalty depth, and group package operators with visa-handling expertise. Technology licensing and strategic airline partnerships constitute the dominant competitive moves.
Within the mobile-first aggregator tier, MakeMyTrip and Goibibo exemplify platform-scale positioning through app-based transaction infrastructure. Yatra Online occupies the corporate travel specialist archetype with negotiated rate structures for business accounts. Thomas Cook India and SOTC Travel anchor the traditional package operator segment, retaining relevance for visa-complex destinations and religious pilgrimage circuits where documentation counseling remains essential.
| Leading Market Players |
|---|
| Kesari Tours |
| In Orbit Tours |
| Thomas Cook India |
| Yatra Online |
| MakeMyTrip |
| SOTC Travel |
| Raj Travels |
| Goibibo |
| Orbit Travels |
| Others |
Value Chain & Pricing Dynamics
Visa-processing counselor concentration in Mumbai and Delhi creates labor-cost differentials that widen pricing-tier spreads between premium agent-assisted packages and self-service digital bookings. RBI's LRS documentation requirements for high-value remittances anchor premium pricing in metro-based expertise clusters.
Pricing Analysis
Input-cost pass-through from aviation fuel surcharges and bilateral slot scarcity drives dynamic pricing volatility across booking channels. Three-tier pricing structure across premium, standard, and economy levels segments by after-sales service depth and visa-handling complexity. Pricing pressure stems from aggregator commission compression as MakeMyTrip and Goibibo compete on app-based convenience. Mass-market family packages exhibit highest price sensitivity; bespoke medical tourism and honeymoon itineraries show lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements for international inventory mandate that OTAs qualify multiple airline GDS platforms and hotel aggregators simultaneously. Supply concentrates in Thailand, UAE, and Singapore as primary destination nodes, with secondary sourcing from Vietnam and Indonesia for emerging circuits. Raw material dependencies include bilateral aviation capacity, e-visa processing infrastructure, and foreign exchange liquidity at authorized dealer banks. Single-source vulnerability concentrates in DGCA's slot allocation decisions for peak-season routes. Distribution runs through mobile-first OTAs for urban millennials, agent networks for visa-complex destinations, and direct airline channels for loyalty program members.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India outbound tourism represents a late-cycle quality story as dual-income households shift demand toward premium experiential specifications and personalized itinerary construction over commoditized packages.
For Market Incumbents: Acquire visa-processing talent pools in tier-2 cities before digital platforms automate documentation workflows. Consolidate corporate travel accounts through negotiated rate structures that lock in Gurugram and Bengaluru IT sector demand. Threat substitution from AI-driven itinerary generators demands investment in counselor expertise for Schengen and North American destinations. Channel control through exclusive airline partnerships remains the critical defensive lever. For New Entrants and Emerging Players: Launch via mobile-first interfaces targeting solo travelers and young professionals in Hyderabad and Pune with flexible single-occupancy inventory. White-space concentration sits in medical tourism packaging for cardiac and orthopedic procedures to Turkey and Thailand, where cost arbitrage sustains premium pricing. Underserved tier-2 city penetration in Ahmedabad and Kochi offers lowest competitive density. Go-to-market acceleration hinges on influencer referral codes and Instagram discovery integration. For Investors and Strategic Acquirers: Airline loyalty program operators and fintech cross-border payment platforms are the most active acquirers in this space, seeking captive distribution for premium cabin inventory and foreign exchange transaction flows. Five-to-ten-year viability rests on regulatory stability in RBI's LRS calibration and DGCA's bilateral expansion pace. Acquisition targets cluster around visa-specialist agencies with established counselor training infrastructure. The signal to watch is e-visa protocol expansion to additional Schengen and North American destinations, which would compress agent-assisted booking relevance and shift volume toward fully digital channels.| Strategic Initiative | Industry Significance |
|---|---|
| Visa Processing Automation | AI-driven documentation workflows reduce counselor dependency for Schengen and UK applications. |
| Airline Partnership Expansion | Exclusive inventory agreements with Emirates and Singapore Airlines secure premium cabin allocation. |
| Medical Tourism Packaging | Hospital partnerships in Bangkok and Istanbul capture cardiac surgery cost arbitrage demand. |
| Mobile Wallet Integration | RBI-compliant cross-border payment products reduce foreign exchange friction for LRS remittances. |
| Tier-2 City Penetration | Direct connectivity from Ahmedabad and Kochi unlocks underserved outbound propensity. |
Study Parameters
Direct dialogue with online travel agency platform managers, traditional travel agency proprietors, airline revenue management executives, hotel distribution directors, and RBI-authorized dealer bank officers grounded qualitative insights in operational reality. Secondary validation drew from DGCA bilateral aviation agreements, RBI Liberalized Remittance Scheme circulars, Ministry of Tourism outbound policy frameworks, BIS travel insurance standards, and customs foreign exchange transaction records. Bottom-up passenger volume modeling and top-down market value estimation triangulated segment-level outputs.
Segmentation-level projections across destination type, customer demographics, booking channel, and travel duration dimensions fed into consolidated market sizing over the analysis window. CAGRs derived from historical outbound passenger growth rates, LRS remittance ceiling expansion trajectories, and bilateral capacity addition schedules. Forecast inputs incorporated e-visa protocol adoption curves, rupee-dollar exchange rate assumptions, and tier-2 city airport infrastructure development timelines.
Several conditions sit outside the modeled scope, including geopolitical disruptions to Middle East corridor stability, pandemic-era travel restriction reinstatement, and abrupt RBI capital control tightening. Forecasts reflect documented assumptions regarding visa facilitation momentum and aviation bilateral negotiation pace. Deviation in DGCA's slot allocation generosity or Schengen visa processing timeline extension would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
North America Pet Travel Services Market
Travel and Tourism
Travel Intermediaries Business Market
Travel and Tourism
United Kingdom Casino Tourism Market
Travel and Tourism
Malaysia Tourism Market
Travel and Tourism
Latin America Inflight Services Market
Travel and Tourism
Japan Travel Retail Market
Travel and Tourism
Mexico Sustainable Tourism Market
Travel and Tourism
Educational Tourism Market
Travel and Tourism
Inflight Shopping Market
Travel and Tourism
Travel Retail Market
Travel and Tourism
Asia Pacific Wellness Tourism Market
Travel and Tourism
Yoga Tourism Market
Travel and Tourism
Global Home Exchange Service Market
Travel and Tourism
Russia Outbound Tourism Market
Travel and Tourism
Europe Tourism Vehicle Rental Market
Travel and Tourism
India Travel Retail Market