
 UK Outbound Travel Market | 2026-2036
UK Outbound Travel Market Size, Share, and Industry Trends Forecast 2026-2036
UK Outbound Travel Market Analytics
Package Travel and Linked Travel Arrangements Regulations is decoupling financial protection requirements from traditional tour operator models, forcing digital platforms to absorb compliance costs previously borne by legacy agencies. TUI Group leverages its vertically integrated airline-hotel portfolio to sustain margin control across Mediterranean routes. Booking Holdings Inc. anchors its UK position through Booking.com's inventory depth in short-haul European destinations. On the Beach Group plc differentiates via dynamic packaging technology that navigates regulatory complexity without holding charter inventory.
UK outbound travel encompasses all commercially organized journeys by UK residents to foreign destinations, typically involving pre-arranged transport, accommodation, or experience components booked through direct or intermediary channels. The sector operates on yield management systems that optimize per-seat and per-room pricing against capacity constraints and seasonal demand curves. Leisure travel dominates volume flows, with coastal and urban destination types capturing the largest share of UK consumer spend. Online travel agencies and mobile app booking channels are expanding fastest, while traditional travel agent networks retain concentrated demand among senior customer demographics seeking assisted purchase journeys.
ABTA membership standards and ATOL licensing administered by the UK Civil Aviation Authority shape operator credibility and consumer trust mechanisms in this market. The Competition and Markets Authority monitors price transparency and cancellation terms across digital platforms. Financial Conduct Authority oversight of travel money and insurance products adds a secondary compliance layer for bundled offerings. Stakeholders must monitor how post-Brexit passport validity rules and emerging EU entry-exit system requirements reshape booking lead times and destination preferences.
Market Dynamics
Package Travel and Linked Travel Arrangements Regulations is decoupling financial protection from traditional tour operator models, compelling digital platforms to absorb compliance costs previously managed by legacy agencies while reshaping competitive economics across booking channels.
Growth Catalysts
- ATOL licensing expansion:The UK Civil Aviation Authority's broadened coverage requirements for dynamic packaging platforms is extending financial protection to previously unregulated online bookings, expanding addressable market scope for compliant intermediaries.
- Mobile-first booking behavior:Smartphone-native consumers in the 25-40 demographic are shifting reservation volumes toward app-based channels, compressing search-to-purchase cycles and reducing customer acquisition costs for platform operators.
- Mediterranean route yield optimization:Spanish and Greek island destination clusters are deploying AI-driven capacity management, improving load factors and enabling sustained margin expansion on high-frequency short-haul services.
Market Restraints
- Jet fuel price volatility:Crude oil derivative exposure in airline cost structures creates margin compression risk during supply disruptions, particularly affecting charter-dependent tour operators with limited hedging coverage.
- Spanish accommodation concentration:Overreliance on Balearic and Canary Islands inventory exposes operators to regional supply shocks, seasonal capacity constraints, and localized pricing power held by dominant hotel groups.
- Passport validity friction:Post-Brexit requirements mandating ten-year validity with no more than ten years elapsed are creating booking abandonment at checkout, particularly among infrequent travelers unfamiliar with rule changes.
Strategic Opportunities
- Scottish outbound corridor development:Edinburgh and Glasgow departure point expansion offers underserved regional access, reducing London-centric capacity dependence and capturing price-sensitive leisure segments.
- Experience-led dynamic packaging:Convergence of activity booking APIs with core transport-accommodation bundles enables real-time customization, shifting value capture from commoditized rooms toward higher-margin experiential add-ons.
- FCA travel insurance bundling:Financial Conduct Authority regulatory clarity on embedded protection products is creating compliant pathways for platforms to monetize cancellation and medical coverage at point of sale.
Industry Challenges
- Revenue recognition system complexity:Package Travel Regulations mandate distinct accounting for transport, accommodation, and experience components, forcing legacy ERP upgrades and interim manual reconciliation processes.
- ATOL certificate integration:Real-time licensing verification against Civil Aviation Authority databases requires API infrastructure investment, creating execution risk for mid-size operators with constrained technology budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Outbound Travel Market |
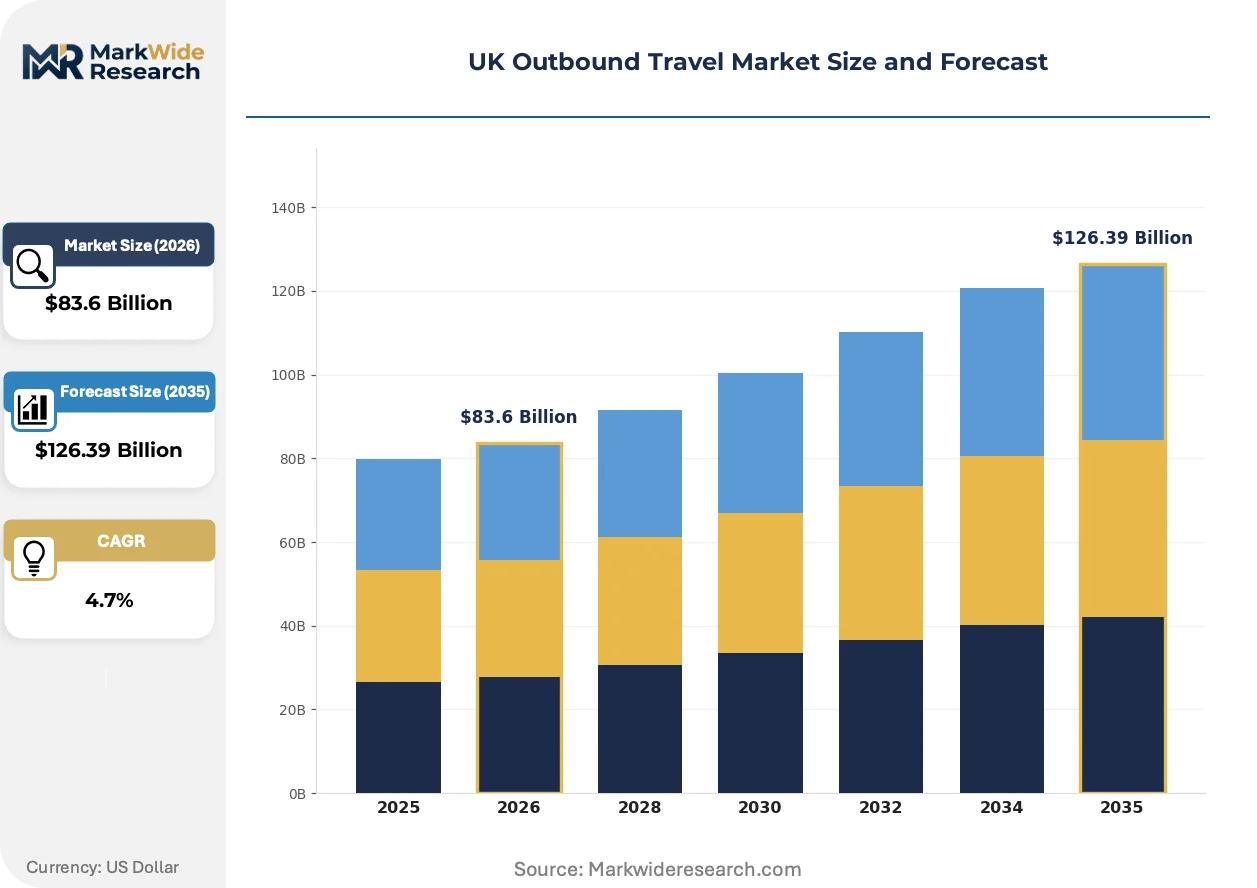
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $126.39 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Travel Type: Leisure, Business, Education, Medical Booking Channel: Online Travel Agency, Direct Booking, Travel Agent, Mobile App Customer Demographic: Families, Solo Travelers, Couples, Seniors Destination Type: Cultural, Coastal, Urban, Adventure |
| Companies Covered | TUI Group, Booking Holdings Inc., Expedia Group Inc., On the Beach Group plc, Airbnb Inc., Opodo, Hotels.com, Booking.com, Thomas Cook, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Outbound Travel Market Evolving Landscape
Digital infrastructure investments are compressing search-to-booking timelines while regulatory digitization and shifting consumer loyalty patterns are redistributing value across the intermediary landscape.
Artificial intelligence-powered recommendation engines are electrifying the discovery phase of travel planning, matching traveler preference data against inventory availability in real time. Mid-market online agencies are deploying these tools fastest, reducing dependency on paid search acquisition. The structural consequence is a shift from destination-led toward experience-led booking initiation, compressing the traditional inspiration-to-reservation funnel.
The Package Travel and Linked Travel Arrangements Regulations 2018, as enforced by the Competition and Markets Authority, is mandating price transparency across all component breakdowns. This regulatory pressure is forcing platforms to redesign checkout flows and refund mechanisms. City break and short-haul segments are responding with simplified product architectures that reduce regulatory surface area while maintaining margin.
Subscription and membership models are displacing transactional loyalty programs among frequent leisure travelers. Premium tier offerings bundling priority support, flexible cancellation, and exclusive inventory access are capturing high-value repeat booking segments. This pattern is most visible in London and Southeast England departure markets, where platform switching costs remain low and brand differentiation depends on service architecture rather than price alone.
UK Outbound Travel Market Segmentation
Segmentation in the UK outbound travel market reveals distinct operational economics across booking channels and traveler profiles. Each dimension carries specific regulatory obligations, technology requirements, and margin structures that shape competitive positioning.
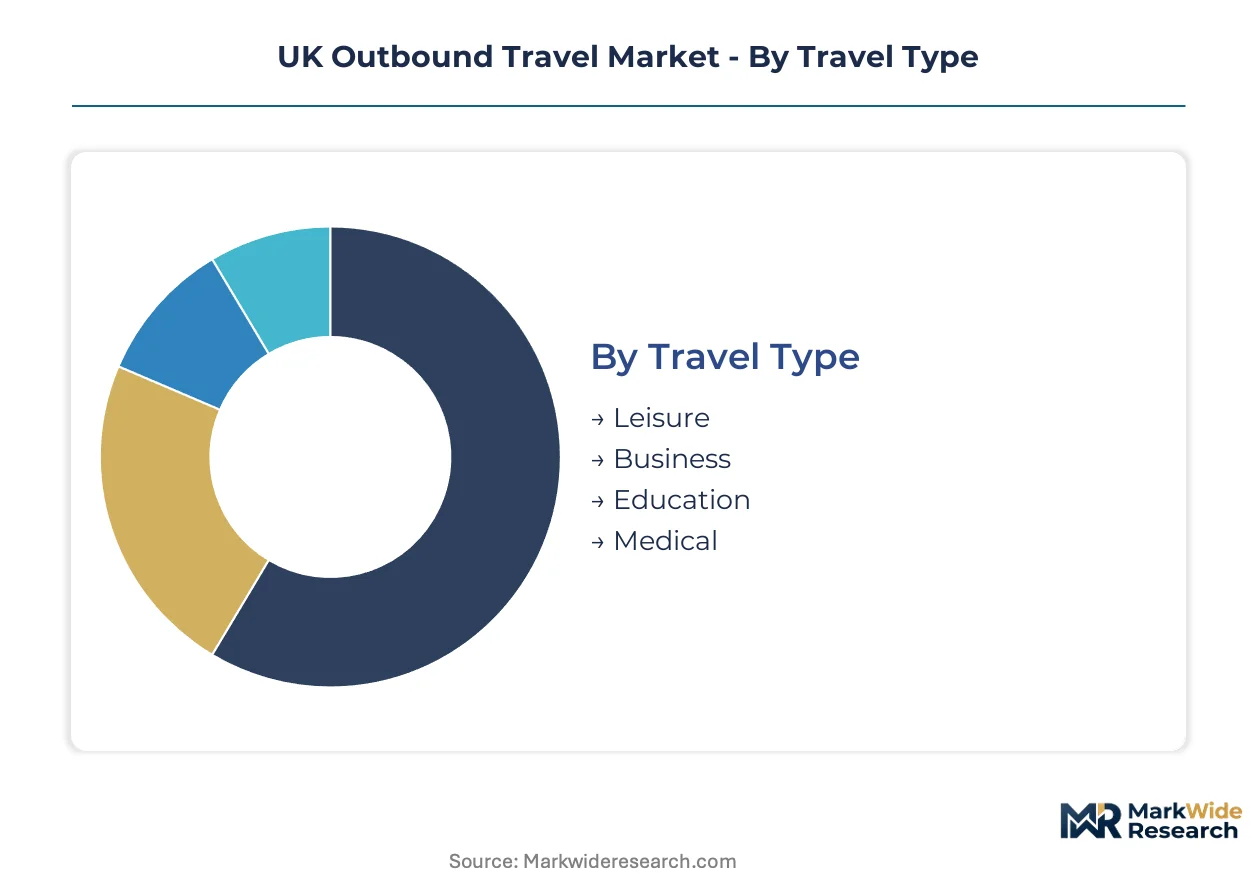
Travel Type:
Integration depth varies sharply across travel purpose segments, with standalone leisure packages operating on fundamentally different protection frameworks than embedded business travel procurement systems.
- Leisure:Pre-arranged packages combining transport, accommodation, and experiences dominate UK outbound volume. Mediterranean coastal and city break destinations concentrate demand, with Package Travel Regulations mandating component-level financial protection that adds compliance overhead but builds consumer trust.
- Business:Corporate travel management platforms embed booking within enterprise expense systems, reducing per-trip transaction friction. London and Southeast England headquarters drive procurement concentration, though post-pandemic hybrid work patterns have compressed absolute trip frequency.
- Education:School and university exchange programs operate on extended lead cycles with group coordination requirements. ATOL licensing covers most organized educational travel, creating barrier to entry for non-compliant providers.
- Medical:Elective treatment and wellness travel segments source specialized accommodation and transport arrangements. Private healthcare referral networks in Spain, Turkey, and Eastern Europe anchor destination selection.
Leisure leads volumes today; medical travel is gaining share fastest.
Booking Channel:
Cost tier separation across channels reflects customer acquisition economics and technology infrastructure investment levels.
- Online Travel Agency:Platform aggregators consolidate inventory from multiple suppliers, enabling real-time price comparison. Dynamic packaging technology allows component bundling without charter inventory ownership, reducing capital intensity.
- Direct Booking:Airline and hotel proprietary channels capture margin otherwise paid to intermediaries. British Airways and easyJet leverage loyalty program data to reduce dependency on third-party acquisition.
- Travel Agent:High-touch assisted purchase retains concentrated demand among senior demographics and complex multi-destination itineraries. Physical branch networks concentrate in suburban and regional England locations.
- Mobile App:Smartphone-native booking compresses search-to-purchase cycles through stored payment credentials and push notification retargeting. The 25-40 demographic drives disproportionate volume through this channel.
Online travel agency channels lead volumes today; mobile app is expanding most quickly.
Customer Demographic:
Application context shapes product architecture, with family travel requiring coordination complexity that solo and couple segments avoid.
- Families:Multi-generational group coordination demands flexible cancellation terms and adjacent room inventory guarantees. School holiday timing constraints create predictable demand spikes that operators price dynamically.
- Solo Travelers:Individual booking behavior favors short-haul European destinations with single supplement avoidance. Experience-led and adventure-oriented subsegments show highest growth trajectory.
- Couples:Romantic and anniversary travel concentrates in premium accommodation tiers. City break and coastal resort combinations capture significant share of this segment.
- Seniors:Assisted purchase preference and insurance inclusion requirements distinguish this demographic. Longer average trip duration and shoulder season flexibility offset lower per-night spend rates.
Families lead volumes today; solo travelers are climbing the fastest.
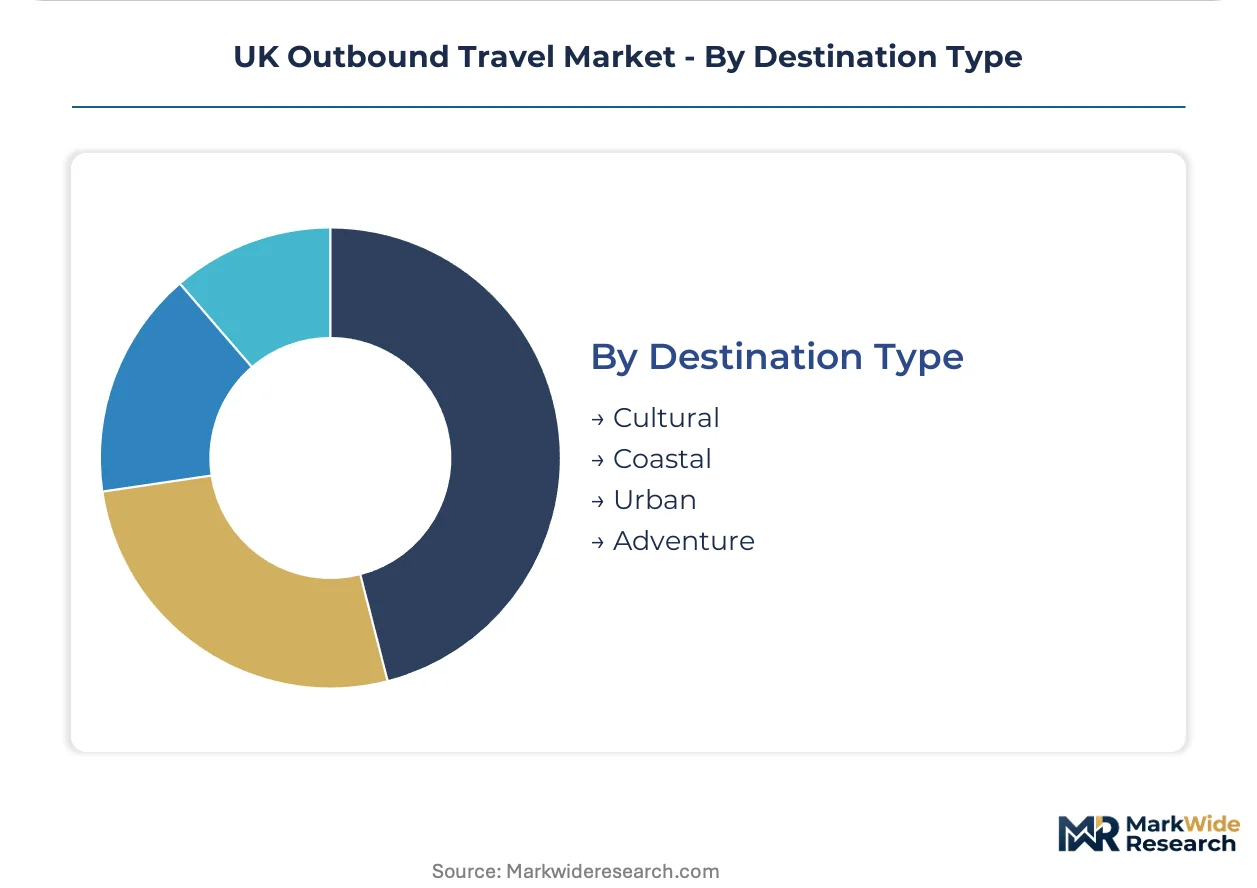
Destination Type:
Supply concentration patterns across destination categories determine operator margin sustainability and inventory risk exposure.
- Cultural:Heritage site and museum-focused itineraries concentrate in Italian and French urban clusters. Extended dwell times and experience add-on potential improve per-trip revenue capture.
- Coastal:Beach and resort travel dominates Spanish and Greek island demand. Seasonal capacity constraints and hotel group pricing power create margin pressure during peak periods.
- Urban:Short-break city destinations prioritize transport connectivity and central accommodation location. Barcelona, Paris, and Amsterdam anchor UK outbound urban travel.
- Adventure:Activity-led travel segments source specialized equipment and guide services. Alpine skiing and Nordic outdoor experiences command premium pricing tiers.
Coastal leads volumes today; adventure is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Travel agent talent clusters in London and Edinburgh anchor UK outbound travel expertise, with regional departure point expansion reshaping distribution economics across British metropolitan areas.
London and Southeast England
Corporate headquarters concentration and Heathrow/Gatwick capacity dominance drive premium leisure and business travel procurement. The UK Civil Aviation Authority's ATOL licensing requirements shape operator compliance investments. The M25 corridor hosts dense online travel agency and tour operator clusters competing on dynamic packaging technology.
Scotland
Edinburgh and Glasgow departure growth targets underserved north British leisure segments with competitive pricing against London-centric alternatives. Scottish Government tourism agency funding supports route development negotiations. Aberdeen's energy sector workforce generates distinctive long-haul business travel demand patterns.
North England
Manchester Airport expansion captures price-sensitive family leisure segments seeking Mediterranean and Canary Islands packages. The Competition and Markets Authority monitors price transparency compliance across regional booking platforms. Leeds and Newcastle travel agent networks retain concentrated senior demographic demand for assisted purchase journeys.
Wales
Cardiff Airport's limited route network funnels outbound demand toward Bristol and London alternatives, creating distinctive booking channel preferences. Welsh Government aviation policy supports seasonal charter capacity to Spanish coastal destinations. The M4 corridor links Welsh consumers to Bristol's consolidated tour operator retail presence.
Midlands
Birmingham Airport's long-haul expansion targets Caribbean and Middle Eastern leisure segments beyond traditional European short-haul. East Midlands Airport cargo infrastructure supports tour operator charter operations. Nottingham and Leicester travel agent branches serve family holiday coordination demand with flexible payment plan offerings.
UK Outbound Travel Market Competitive Landscape
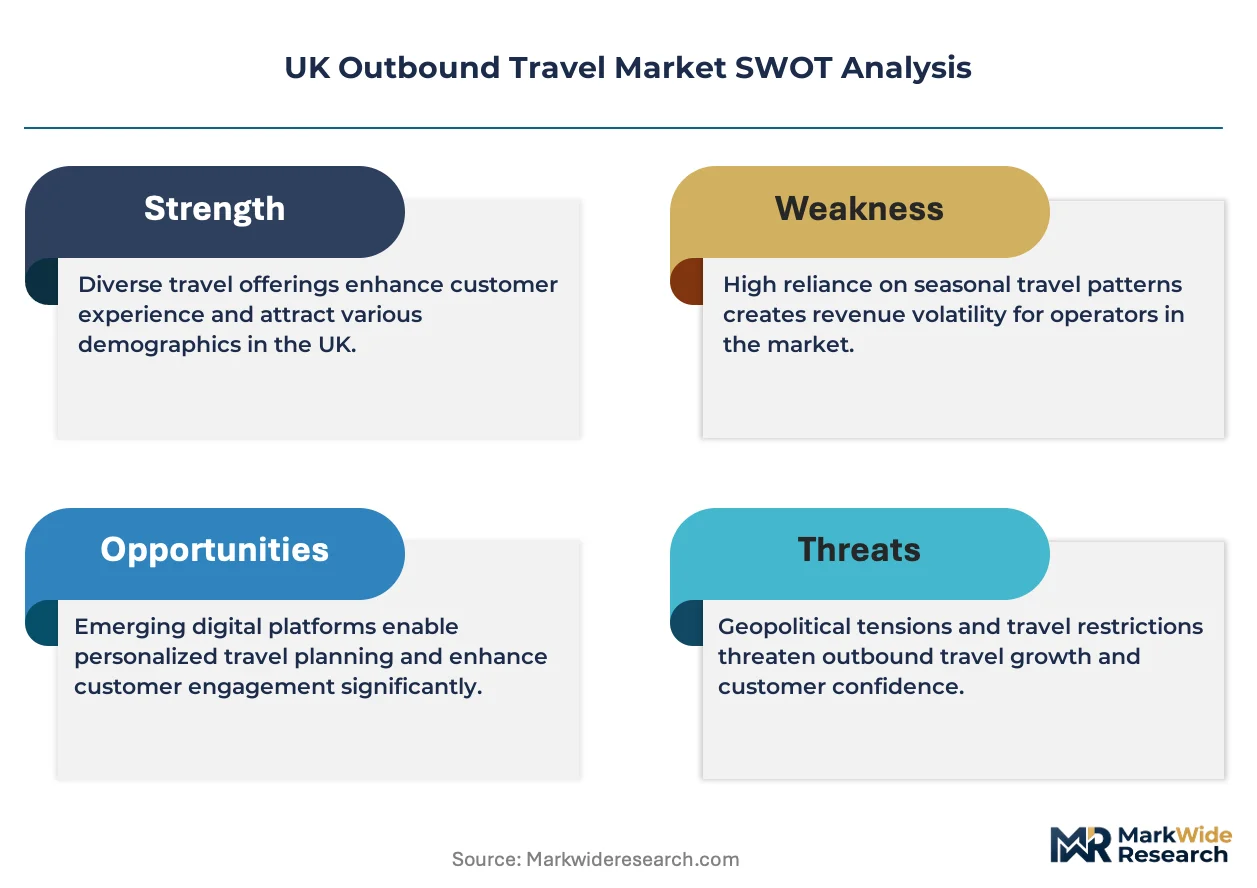
Diversified conglomerates compete with focused pure-play specialists across the UK outbound travel market, creating tiered competitive pressure on margin structures and customer acquisition economics. The market exhibits moderate consolidation with distinct strategic archetypes occupying differentiated positions. Three player types dominate: vertically integrated tour operators owning charter capacity, asset-light online platforms aggregating third-party inventory, and hybrid specialists blending proprietary technology with selective inventory commitments. Competitive moves center on dynamic packaging technology investment and regional departure point expansion.
Within the integrated tour operator tier, TUI Group anchors German-origin multinational presence with UK market penetration. Among online travel agency platforms, Booking Holdings Inc. and Expedia Group Inc. occupy positions representing US-based global aggregation scale. The specialist segment includes On the Beach Group plc exemplifying British dynamic packaging technology without charter inventory ownership.
| Leading Market Players |
|---|
| TUI Group |
| Booking Holdings Inc. |
| Expedia Group Inc. |
| On the Beach Group plc |
| Airbnb Inc. |
| Opodo |
| Hotels.com |
| Booking.com |
| Thomas Cook |
| Others |
Value Network & Pricing Analysis
Dynamic packaging technology is compressing operator cost structures while fragmenting supplier power across Mediterranean destination clusters. ATOL licensing expansion forces digital platforms to absorb compliance overhead previously externalized, reshaping margin allocation between inventory owners and aggregators.
Pricing Analysis
Bundled package holidays versus unbundled component bookings split the UK outbound market into divergent pricing architectures. Three-tier pricing structure across premium, standard, and economy levels captures family leisure segments, while dynamic packaging enables real-time price customization. Price differentiation rests on departure point proximity and cancellation flexibility tiers. Pricing pressure stems from airline yield management algorithms compressing intermediary markups. Price-sensitive families booking school holiday departures face the steepest premiums, while flexible solo travelers accessing shoulder-season inventory capture lowest net rates.
Supply Chain Analysis
Jet fuel cost volatility and short-haul aircraft positioning expenses dominate supply chain economics for UK-originating services. Inventory concentration in Spain, Greece, and Portugal creates seasonal bottlenecks at peak demand windows. Accommodation contracting draws from Balearic Islands, Canary Islands, and mainland Spanish hotel groups with consolidated pricing power. Single-source vulnerability runs through concentrated Mediterranean resort capacity controlled by dominant hotel chains. Distribution runs through online travel agency platforms, direct airline channels, and residual travel agent networks serving assisted-purchase demographics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK outbound travel market compounds steadily as mobile-first booking behavior permanently shifts reservation volumes toward lower-acquisition-cost digital channels.
For Market Incumbents: Cement platform loyalty through subscription membership tiers bundling flexible cancellation and priority customer support. Defend against specialized experience-booking entrants by deepening proprietary inventory commitments in Spanish and Greek island clusters. ATOL licensing complexity creates barrier advantages against undercapitalized challengers lacking compliance infrastructure. For New Entrants and Emerging Players: Package Travel and Linked Travel Arrangements Regulations in the UK opens a window for technology-native platforms to capture market share through superior refund automation and component-level price transparency. Target Scottish outbound corridor development with Edinburgh and Glasgow departure point specialization. Pursue white-label dynamic packaging partnerships with regional airlines lacking in-house bundling capability. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-size dynamic packaging specialists with proven technology stacks but limited brand recognition. Long-term viability favors operators controlling proprietary customer data across repeat booking cycles. Monitor mobile app booking share trajectories as inflection indicator for platform switching momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Dynamic Packaging Technology Investment | Enables real-time component bundling without charter inventory capital commitment. |
| Regional Departure Point Expansion | Captures price-sensitive north British leisure segments outside London-centric capacity. |
| Subscription Membership Launch | Shifts customer economics from transactional acquisition toward recurring revenue retention. |
| ATOL Compliance Infrastructure Buildout | Creates regulatory moat against unlicensed competitors in financial protection landscape. |
| Experience API Integration | Monetizes activity bookings at higher margins than commoditized accommodation slots. |
Research Methodology
Direct dialogue with tour operator revenue managers, online travel agency platform directors, airline network planners, and travel agent branch owners grounded qualitative findings in operational reality. Secondary validation drew from UK Civil Aviation Authority ATOL licensing databases, Competition and Markets Authority enforcement notices, Office for National Statistics travel expenditure surveys, and airline route profitability disclosures. Bottom-up passenger volume modeling and top-down market value triangulation cross-checked segment-level estimates.
Bottom-up analysis built passenger trip estimates from departure point capacity data and load factor assumptions, while top-down approaches validated totals against consumer expenditure surveys. Segmentation dimensions modeled include travel purpose, booking channel, customer demographic, and destination type clusters. CAGRs derived from trend extrapolation adjusted for regulatory intervention effects and technology adoption curves. Forecast inputs incorporated mobile booking penetration trajectories and Mediterranean hotel supply expansion pipelines.
Revisions become necessary when jet fuel price shocks, EU entry-exit system implementation delays, or abrupt regulatory reinterpretations of package travel scope materialize. Forecasts reflect documented assumptions about consumer preference stability and airline capacity discipline. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Asia-Pacific Travel Retail Market
Travel and Tourism
USA Sports Tourism Market
Travel and Tourism
Water Park Market
Travel and Tourism
Domestic Tourism Market
Travel and Tourism
Incentive Travel Market
Travel and Tourism
Sports Tourism Market
Travel and Tourism
Airline Retailing Market
Travel and Tourism
Surfing Tourism Market
Travel and Tourism
North America Pet Travel Services Market
Travel and Tourism
South Korea Tourism Market
Travel and Tourism
Greece Tourism Market
Travel and Tourism
Ecotel Tourism Market
Travel and Tourism
United Kingdom Casino Tourism Market
Travel and Tourism
Africa Wellness Tourism Market
Travel and Tourism
Europe Tourism Vehicle Rental Market
Travel and Tourism
France Outbound Tourism Market