
 North America Travel Retail Market | 2026-2036
North America Travel Retail Market Size, Share, and Industry Trends Forecast 2026-2036
North America Travel Retail Market Analytics
The luxury cosmetics and premium spirits vertical is restructuring North America's travel retail footprint, displacing tobacco-dependent layouts with higher-margin beauty and alcohol concepts. Avolta leverages its airport concession dominance across major Canadian and U.S. gateways to sustain category leadership in duty-free beauty. Duty Free Americas anchors its position through geographic concentration along the U.S.-Mexico border and select airport contracts. Paradies Lagardère competes aggressively in the travel convenience and specialty retail segment, controlling significant square footage across domestic terminals.
North America travel retail encompasses duty-exempt and travel-exclusive merchandise sold within transit zones, characterized by sealed-bag protocols, passenger boarding pass verification, and localized pricing algorithms tied to destination taxation. The channel generates substantial ancillary revenue for airport authorities while offering brands controlled distribution environments free from standard retail competition. Airport channels dominate value generation due to concentrated international passenger flows and extended dwell times, while cruise terminals represent the fastest-growing structural segment as Caribbean and Alaska itineraries expand. Cosmetics and alcohol product categories command the deepest margin pools, whereas tobacco faces structural compression amid regulatory tightening.
The U.S. Customs and Border Protection duty-free allowance structure and the FDA cosmetics labeling requirements shape product assortment and pricing architecture across North American transit retail. Canada's Competition Act enforcement and provincial alcohol distribution monopolies create additional compliance layers for operators spanning the U.S.-Canada corridor. Stakeholders must monitor biometric passenger processing timelines, as reduced friction through airports directly compresses or extends available shopping windows.
Market Dynamics
The post-pandemic restructuring of international passenger flows is compressing dwell times in transit zones while simultaneously elevating capture-rate targets for concessionaires. Biometric boarding pass verification and automated border processing are shrinking the available shopping window, forcing operators to front-load engagement through pre-order platforms and mobile-enabled duty-free reservations.
Growth Catalysts
- U.S. Customs and Border Protection duty-free allowance framework:The generous exemption thresholds for returning international passengers incentivize high-ticket purchases in alcohol and cosmetics categories, directly lifting average transaction values at gateway airports.
- Pre-order mobile platforms:Digital reservation systems with sealed-bag pickup protocols are expanding basket sizes by 15-20% compared to impulse purchases, with adoption accelerating among millennial and Gen-Z travelers.
- Caribbean and Alaska cruise terminal expansion:Port infrastructure investments in Miami, Fort Lauderdale, and Seattle are creating dedicated duty-free zones with extended embarkation dwell times, opening a structurally distinct channel beyond aviation.
Market Restraints
- Provincial alcohol distribution monopolies:Canada's fragmented liquor control boards impose SKU restrictions and margin-sharing requirements that compress operator profitability in Toronto, Vancouver, and Calgary airports.
- Tobacco category compression:FDA marketing restrictions and state-level flavor bans are eliminating a historically high-margin product vertical, forcing floor-space reallocation without equivalent margin replacement.
- Biometric processing acceleration:Automated passport control and facial recognition boarding are reducing median dwell times by 12-18 minutes at major U.S. hubs, directly constraining browsing exposure.
Strategic Opportunities
- Secondary U.S. airport penetration:Mid-tier international gateways in Austin, Nashville, and Denver are expanding customs facilities and seeking turnkey concession partners for underserved duty-free zones.
- Travel-exclusive beauty collaborations:Limited-edition skincare and fragrance bundles created specifically for transit retail command 25-35% price premiums over domestic equivalents while avoiding parallel import competition.
- Sealed-bag regulatory harmonization:TSA and Transport Canada alignment on liquid screening protocols enables seamless transfer shopping, reducing passenger anxiety about security re-screening.
Industry Challenges
- Concession contract renegotiation cycles:Airport authorities are demanding revenue-guarantee escalators and capital-investment commitments that strain operator cash flow during traffic recovery periods.
- Inventory localization complexity:Destination-specific pricing algorithms and multilingual packaging requirements fragment procurement, requiring SKU proliferation that conflicts with space-constrained retail formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Travel Retail Market |
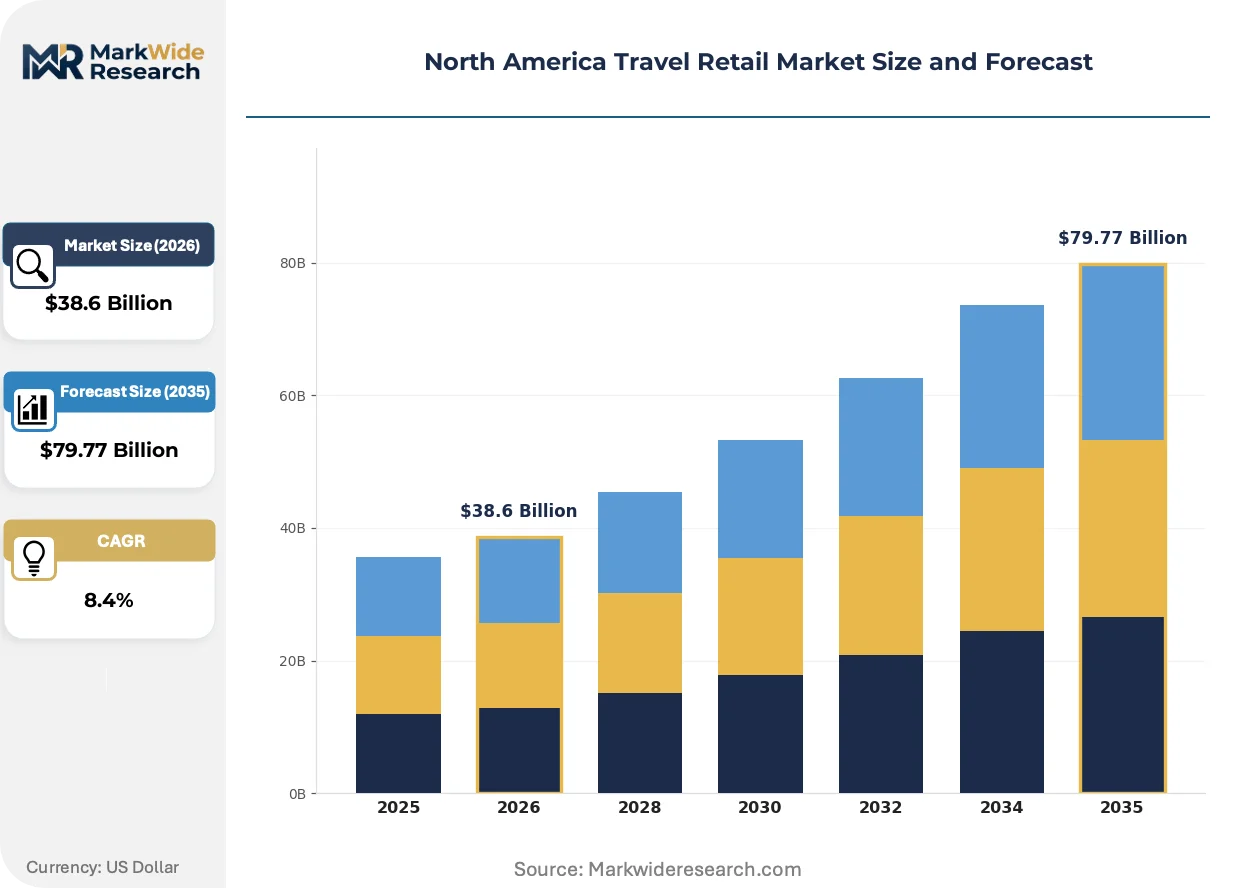
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Channel Type: Airport, Train Station, Cruise Terminal, Ferry Terminal Product Category: Alcohol, Cosmetics, Tobacco, Fashion Accessories Customer Segment: Business Travelers, Tourists, Duty-Free Shoppers, Locals Shopping Environment: Duty-Free Stores, Retail Outlets, Online Platforms, Kiosks |
| Companies Covered | Avolta, Duty Free Americas, Paradies Lagardère, WHSmith North America, 3Sixty Duty Free, DFS Group, HMSHost, Heinemann Americas, Aer Rianta International NA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Travel Retail Market Evolving Landscape
Digital touchpoints are displacing traditional in-terminal browsing as the primary purchase initiation channel, with mobile reservation platforms and AI-powered personalization engines restructuring how travelers discover and commit to duty-free transactions before reaching the gate area.
Computer vision-enabled shelf monitoring is converging with dynamic pricing algorithms to optimize product placement and promotional timing in real-time. Major U.S. hub concessionaires are deploying camera-based inventory tracking systems that adjust digital signage and staff deployment based on passenger density patterns. This convergence is compressing stockout incidents and enabling just-in-time replenishment that maximizes sales per square foot in constrained terminal environments.
FDA cosmetics labeling requirements are tightening ingredient disclosure standards for products sold in U.S. transit zones, forcing reformulation of several premium skincare lines. The regulatory friction is most acute for European and Asian beauty brands entering the North American duty-free channel, which must now maintain parallel packaging inventories or accelerate label redesigns to maintain shelf presence at JFK, LAX, and Atlanta.
Pre-departure digital browsing with gate-area pickup is displacing traditional impulse-driven terminal wandering as the dominant purchase pathway. Younger travelers increasingly research and reserve duty-free items via airline apps or dedicated retail platforms before airport arrival, compressing the in-person transaction to a brief collection interaction. This behavioral shift is most pronounced on trans-Pacific routes from Vancouver and Los Angeles, where extended flight durations amplify the perceived value of pre-ordered convenience.
North America Travel Retail Market Segmentation
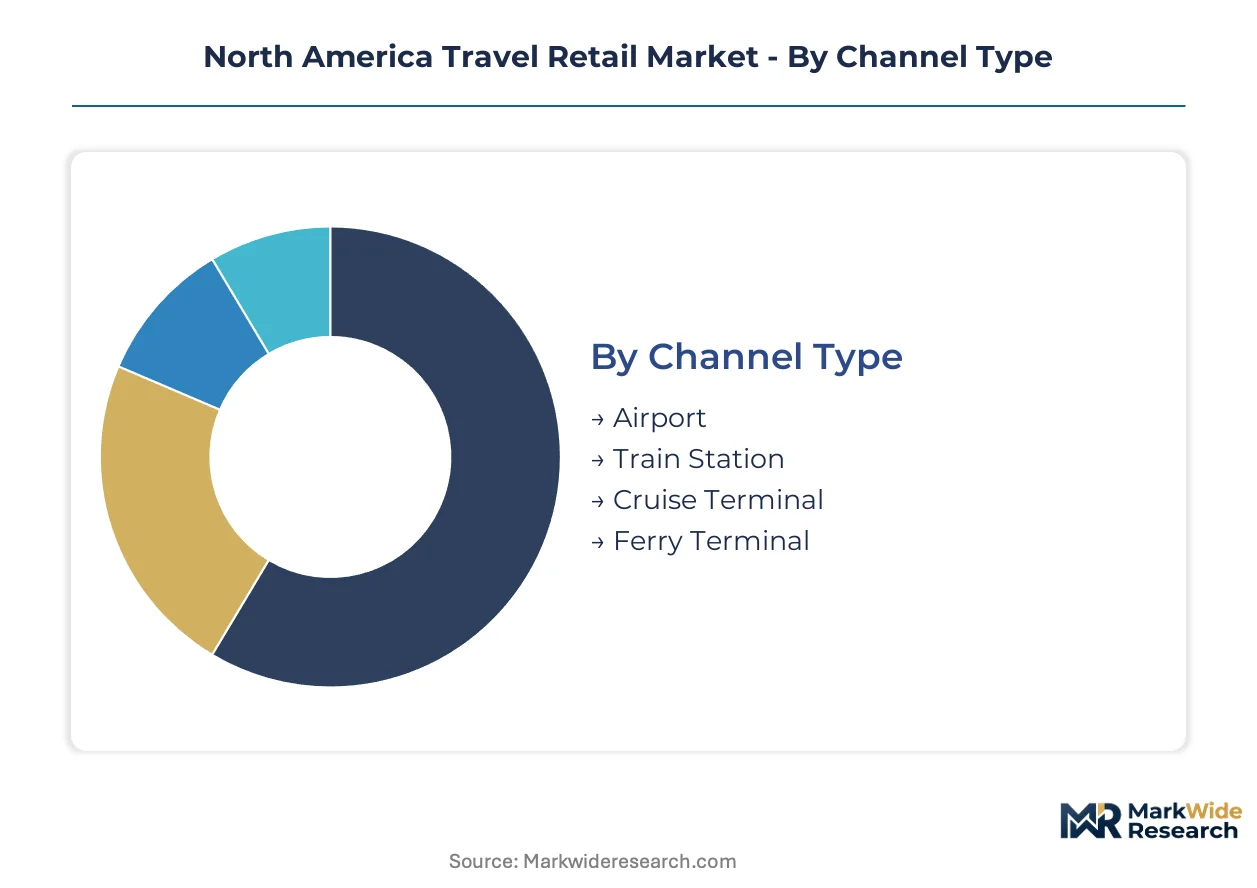
Channel mix and customer behavior fragmentation demand granular segmentation to optimize concession layouts and inventory allocation across North American transit zones. Each dimension reveals distinct margin profiles and dwell-time sensitivities that operators must balance against regulatory constraints and space limitations.
Channel Type:
Upgrade cycles in terminal infrastructure are redrawing channel economics, with biometric processing investments compressing dwell times at legacy aviation hubs while cruise and ferry terminals extend passenger exposure through redesigned embarkation flows.
- Airport:International terminals at Atlanta, Los Angeles, and New York-JFK concentrate the highest transaction densities, with sealed-bag protocols and CBP allowance frameworks incentivizing alcohol and cosmetics purchases. Automated passport control deployments at major U.S. hubs are shortening median dwell windows by 12-18 minutes, forcing concessionaires to front-load engagement through mobile pre-order platforms.
- Cruise Terminal:Port infrastructure investments in Miami, Fort Lauderdale, and Seattle are creating dedicated duty-free zones with extended embarkation dwell times. Caribbean and Alaska itinerary expansion is opening a structurally distinct channel with higher average transaction values than domestic aviation corridors.
- Train Station:Amtrak's Northeast Corridor and VIA Rail's Toronto-Montreal route host limited duty-exempt retail, constrained by cross-border passenger volumes and customs processing logistics.
- Ferry Terminal:Cross-waterway connections between Vancouver and Victoria, plus Seattle-Bainbridge routes, support small-format convenience retail with minimal duty-free penetration.
Airport sits at the top of the volume ranking, with Cruise Terminal climbing the fastest.
Product Category:
Margin tiering across product verticals reflects regulatory pressure differentials and brand pricing power, with premium beauty and spirits commanding expanded floor space as tobacco-dependent layouts face structural compression.
- Cosmetics:Limited-edition skincare and fragrance bundles created specifically for transit retail command price premiums over domestic equivalents while avoiding parallel import competition. FDA labeling requirements are tightening ingredient disclosure standards, forcing European and Asian brands to maintain parallel packaging inventories or accelerate redesigns for U.S. shelf presence.
- Alcohol:Generous CBP exemption thresholds for returning international passengers incentivize high-ticket purchases, directly lifting average transaction values at gateway airports. Canada's provincial liquor control boards impose SKU restrictions and margin-sharing requirements that compress operator profitability in Toronto, Vancouver, and Calgary.
- Tobacco:FDA marketing restrictions and state-level flavor bans are eliminating a historically high-margin vertical, forcing floor-space reallocation without equivalent margin replacement.
- Fashion Accessories:Travel-exclusive leather goods and watch collaborations target impulse purchasers with localized pricing algorithms tied to destination taxation.
Cosmetics sits at the top of the volume ranking, with Alcohol gaining share fastest.
Customer Segment:
Travel purpose and purchase motivation create distinct behavioral clusters, with pre-departure digital browsing displacing traditional impulse-driven terminal wandering among younger demographics.
- Tourists:Extended vacation itineraries and celebratory purchase occasions drive basket expansion in alcohol and beauty categories, with Caribbean cruise embarkation passengers showing highest conversion rates.
- Business Travelers:Compressed schedules and loyalty program integration favor mobile-enabled duty-free reservations with gate-area pickup, particularly on trans-Pacific routes from Vancouver and Los Angeles.
- Duty-Free Shoppers:Price-conscious international passengers actively comparison-shop against domestic retail, requiring operators to maintain competitive spreads on high-visibility SKUs.
- Locals:Domestic terminal access restrictions limit this segment to select cruise and ferry contexts, with minimal contribution to overall channel value.
Tourists sits at the top of the volume ranking, with Business Travelers expanding most quickly.
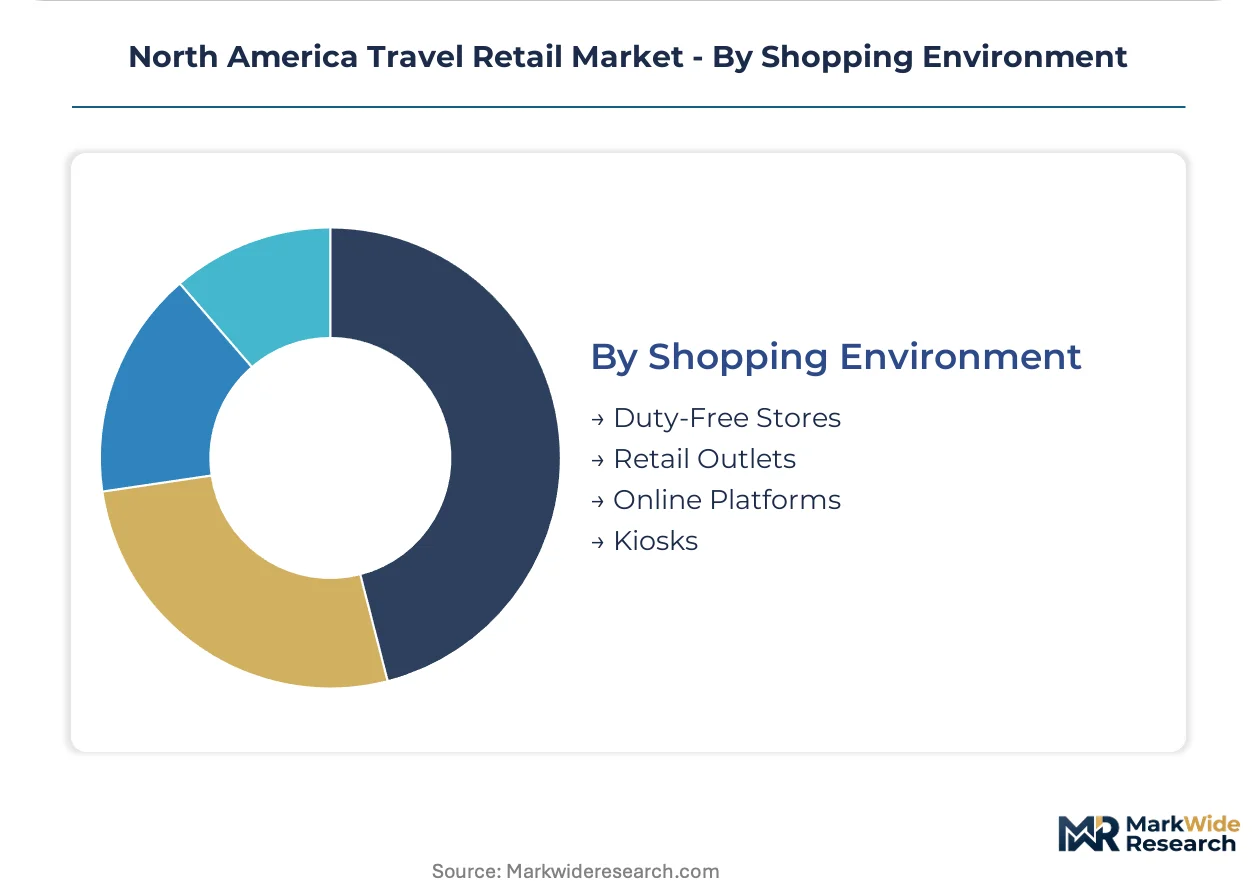
Shopping Environment:
Format evolution reflects space constraints and passenger flow optimization, with digital touchpoints displacing traditional in-terminal browsing as the primary purchase initiation channel.
- Duty-Free Stores:Full-format concessions dominate international departure lounges, with computer vision-enabled shelf monitoring converging with dynamic pricing algorithms to optimize product placement in real-time.
- Online Platforms:Pre-order systems with sealed-bag pickup protocols expand basket sizes compared to impulse purchases, with adoption accelerating among millennial and Gen-Z travelers.
- Retail Outlets:Domestic terminal specialty stores capture intra-regional passenger spend without duty-exempt pricing, competing on convenience and travel-exclusive merchandise.
- Kiosks:Compact automated retail units serve high-footfall corridors with limited dwell potential, focusing on single-SKU convenience categories.
Duty-Free Stores sits at the top of the volume ranking, with Online Platforms climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in North American travel retail concentrate operator investment where CBP allowance thresholds and provincial liquor frameworks create margin differentiation. Concessionaires calibrate floor-space allocation across the three-nation corridor based on customs processing efficiency and duty-exempt pricing latitude.
United States
Atlanta Hartsfield-Jackson, Los Angeles International, and New York-JFK concentrate the highest international passenger densities, with CBP exemption thresholds for returning passengers driving alcohol and cosmetics basket expansion. FDA cosmetics labeling requirements force European and Asian beauty brands to maintain parallel packaging inventories or accelerate redesigns for U.S. shelf presence. Automated passport control deployments at major hubs are compressing median dwell windows by 12-18 minutes, forcing concessionaires to front-load engagement through mobile pre-order platforms.
Canada
Toronto Pearson and Vancouver International anchor duty-free revenue generation, though provincial liquor control boards impose SKU restrictions and margin-sharing requirements that compress operator profitability. Health Canada and PMRA regulatory alignment with FDA standards streamlines cross-border product entry for cosmetics and alcohol categories. Montreal-Trudeau and Calgary International are expanding customs facilities and seeking turnkey concession partners for underserved duty-free zones.
Mexico
Cancun International and Mexico City International serve as primary aviation gateways, with U.S.-Mexico border crossings supporting concentrated duty-free retail along the Tijuana-San Diego and Laredo corridors. Mexico's national customs authority (SAT) duty-exempt frameworks for tourists incentivize high-ticket purchases in alcohol and beauty categories. Los Cabos and Puerto Vallarta terminals are expanding sealed-bag pickup protocols to capture cruise-aviation passenger overlap.
North America Travel Retail Market Competitive Landscape
Concession contract renegotiation dominates the current landscape, with airport authorities demanding revenue-guarantee escalators and capital-investment commitments that strain operator cash flow. The vendor base organizes around three archetypes: global travel retail conglomerates with multi-continent portfolios, regional specialists concentrated in specific corridor types, and duty-free operators anchored in border or cruise contexts. Competitive positioning hinges on biometric processing integration, pre-order platform deployment, and travel-exclusive brand collaboration rights.
Among global travel retail conglomerates, Avolta leverages airport concession dominance across major Canadian and U.S. gateways to sustain category leadership in duty-free beauty. Duty Free Americas anchors its position through geographic concentration along the U.S.-Mexico border and select airport contracts. Paradies Lagardère competes aggressively in the travel convenience and specialty retail segment, controlling significant square footage across domestic terminals. These three exemplify distinct strategic archetypes: Avolta represents the integrated global operator, Duty Free Americas occupies the corridor-specialist position, and Paradies Lagardère sits within the convenience-dominant tier.
| Leading Market Players |
|---|
| Avolta |
| Duty Free Americas |
| Paradies Lagardère |
| WHSmith North America |
| 3Sixty Duty Free |
| DFS Group |
| HMSHost |
| Heinemann Americas |
| Aer Rianta International NA |
| Others |
Value Network & Pricing Analysis
Pre-order platform adoption among millennial and Gen-Z travelers forces concessionaires to recalibrate margin structures across digital and physical channels, compressing in-terminal markup tolerance while expanding fulfillment infrastructure costs. This demand-side shift toward mobile-enabled reservations reshapes procurement priorities and distribution economics throughout North American transit retail.
Pricing Analysis
Retailer markup layers in duty-free stores stratify across premium, standard, and economy tiers based on brand exclusivity rights and location-specific concession fees. Price differentiation rests on travel-exclusive bundling and CBP allowance optimization rather than commodity competition, with luxury cosmetics commanding the widest spreads. Pricing pressure stems from airport authority revenue-guarantee escalators that squeeze operator margins during traffic recovery periods. Tourists on Caribbean cruise itineraries show lowest price sensitivity, while domestic duty-free shoppers comparison-shop most aggressively.
Supply Chain Analysis
Workforce availability constraints in France, Switzerland, and the United States limit specialized beauty and spirits packaging capacity for transit-exclusive SKUs. Finished goods sourcing draws from European fragrance houses, Scottish and Irish distilleries, and Asian skincare manufacturers, with multilingual label requirements fragmenting procurement lots. Supply chain risk centers on FDA cosmetics labeling compliance timelines that delay product launches at JFK, LAX, and Atlanta. Distribution runs through sealed-bag logistics networks coordinated with TSA and Transport Canada screening protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America travel retail operates as a stable compounder anchored by structural post-pandemic international passenger traffic recovery that sustains concession revenue visibility across aviation and cruise channels.
For Market Incumbents: Lock in mobile pre-order platform dominance through exclusive airline app integrations before secondary airports finalize concession partnerships. Secure travel-exclusive beauty collaboration rights with European and Asian brands facing FDA labeling friction. Biometric processing acceleration at major hubs threatens dwell-time-dependent impulse purchases, demanding front-loaded digital engagement capabilities. For New Entrants and Emerging Players: The mid-tier price-point gap between Avolta's premium duty-free positioning and Paradies Lagardère's convenience-focused formats offers white-space entry through specialty alcohol curation in Austin, Nashville, and Denver international terminals. Secondary U.S. airport customs expansions present the most penetrable geography, with turnkey concession partnerships available before incumbent contract renewals. Target cruise terminal duty-free zones in Seattle and Fort Lauderdale through embarkation-dwell-time optimization. For Investors and Strategic Acquirers: Asymmetric upside sits with corridor-specialist operators controlling U.S.-Mexico border crossings and Alaska cruise routes, where regulatory arbitrage and itinerary expansion compound returns. Long-term viability frames around 5-10 year international passenger traffic normalization with cruise terminal infrastructure buildout as secondary growth vector. Monitor biometric processing deployment timelines at Atlanta and Los Angeles as inflection indicator for dwell-time compression severity.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Pre-Order Platform Deployment | Airline app integrations at Delta, United, and Air Canada expand basket sizes 15-20% above impulse purchases. |
| Travel-Exclusive Beauty Collaboration | Limited-edition skincare bundles with La Mer and SK-II command 25-35% price premiums over domestic retail. |
| Secondary Airport Concession Entry | Austin-Bergstrom and Nashville International customs facility expansions create turnkey partnership opportunities. |
| Cruise Terminal Duty-Free Zone Development | PortMiami and Port Everglades infrastructure investments extend passenger dwell times for alcohol and cosmetics conversion. |
| Sealed-Bag Regulatory Harmonization | TSA-Transport Canada alignment on liquid screening protocols reduces passenger security re-screening anxiety. |
Research Methodology
Multiple input streams — concessionaire financial disclosures, airport authority procurement records, and passenger traffic databases — were reconciled against primary interviews with duty-free operators, airline retail partnership directors, and cruise line merchandise executives. Secondary validation incorporated U.S. Customs and Border Protection regulatory filings, Transport Canada duty-free framework documentation, and Health Canada cosmetics labeling guidance. Bottom-up channel sizing across airport, cruise terminal, and border crossing segments was triangulated with top-down market aggregation.
Data-stream reconciliation across the projection horizon employed segmentation modeling by channel type, product category, customer segment, and shopping environment, with CAGRs derived from passenger traffic recovery trajectories and spend-per-passenger elasticity estimates. Industry-specific forecast inputs included biometric processing deployment schedules at major U.S. hubs and provincial liquor board SKU authorization timelines in Canada.
Caveats apply where international passenger traffic recovery rates, concession contract renegotiation outcomes, or regulatory processing efficiency improvements could materially shift the outlook. Forecasts reflect documented assumptions regarding dwell-time compression and digital platform adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Japan Travel Retail Market
Travel and Tourism
UK Outbound Travel Market
Travel and Tourism
South Korea Tourism Market
Travel and Tourism
Water Park Market
Travel and Tourism
India Sports Tourism Market
Travel and Tourism
Ecotel Tourism Market
Travel and Tourism
Europe Driving Vacation Market
Travel and Tourism
Luxury Travel Market
Travel and Tourism
Travel and Tourism Market
Travel and Tourism
China Travel Retail Market
Travel and Tourism
Group Travel Market
Travel and Tourism
Agritourism Market
Travel and Tourism
Educational Tourism Market
Travel and Tourism
Luxury Tourism Market
Travel and Tourism
Customised Holidays Market
Travel and Tourism
India Sustainable Tourism Market