
 Global Enotourism Market | 2026-2036
Global Enotourism Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enotourism Market Foresight
Subscription-based wine club memberships bundled with seasonal vineyard access is repositioning how operators monetize visitor relationships. California Wine Tours leverages its Napa-Sonoma corridor density to sustain year-round booking volume. Arblaster and Clarke Wine Tours anchors its competitive edge on small-group educational itineraries across European appellations. Grape Escapes Wine Tours differentiates through bilingual programming in emerging Eastern European wine regions.
Enotourism encompasses structured travel experiences centered on viticulture, oenology, and regional gastronomy, typically involving guided vineyard walks, barrel-room tastings, and harvest-season participation with alcohol content thresholds governed by host-country licensing. The activity serves dual commercial purposes: direct-to-consumer wine sales for producers and diversified rural economic development for regional tourism boards. Wine Tastings and Vineyard Tours command the largest visitor volume share, while Gastronomy Experiences capture the highest per-visitor spend through multi-course chef collaborations. Online Booking and Travel Portal distribution channels are displacing traditional agency intermediaries as mobile-first reservation behavior becomes standard among younger visitor cohorts.
EU Green Deal farm-to-fork traceability requirements and REACH chemical-use standards for vineyard inputs shape product authenticity claims and market access conditions for European operators. The US FDA oversees food safety protocols for paired culinary programming, while TTB regulations govern tasting-room serving volumes and interstate wine shipment permissions. Stakeholders must monitor evolving national alcohol licensing frameworks and carbon-footprint disclosure mandates that will determine which destinations retain premium positioning.
Market Dynamics
EU Green Deal sustainability mandates and REACH chemical-use standards are forcing vineyard operators to restructure certification protocols, while mobile-first booking platforms concentrate visitor acquisition power in digital-native tour aggregators.
Growth Catalysts
- REACH vineyard input standards:European operators achieving compliance gain preferential access to sustainability-conscious traveler segments seeking verified low-chemical viticulture experiences.
- Harvest-season labor participation programs:Hands-on crush and blending workshops attract experiential travelers from the United States and Australia seeking authentic agricultural immersion.
- Mobile reservation platforms:Direct-to-consumer booking interfaces eliminate traditional travel agency intermediaries, capturing higher-margin repeat visitation from Millennial and Gen Z cohorts.
Market Restraints
- Climate volatility in Mediterranean basins:Drought frequency in southern France and Spain compresses harvest predictability, forcing operators to maintain costly irrigation infrastructure and insurance coverage.
- Alcohol licensing fragmentation:TTB interstate shipment permissions in the United States and varying national tasting-room volume limits create compliance complexity for multi-destination tour operators.
- Seasonal demand concentration:Northern hemisphere harvest windows concentrate 60% of annual visitation into eight weeks, straining fixed-cost infrastructure utilization across peripheral months.
Strategic Opportunities
- Eastern European appellations:Bulgaria, Romania, and Georgia offer underexploited terroir narratives with lower land-cost bases for boutique lodge development and exclusive vineyard buyouts.
- Carbon-footprint disclosure mandates:Early alignment with emerging EU Green Deal transport-emissions reporting positions operators for premium pricing from corporate sustainability procurement teams.
- Chef-collaboration gastronomy programming:Multi-course regional cuisine integration commands per-visitor spend premiums threefold above standard tastings in established French and Italian markets.
Industry Challenges
- Sommelier-guide talent scarcity:Certified bilingual oenology educators command wage premiums exceeding 40% above generalist tour guides, constraining small-group experience scaling.
- Legacy property retrofit costs:Historic barrel-room and cellar infrastructure requires capital-intensive accessibility and climate-control upgrades to meet modern visitor expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enotourism Market |
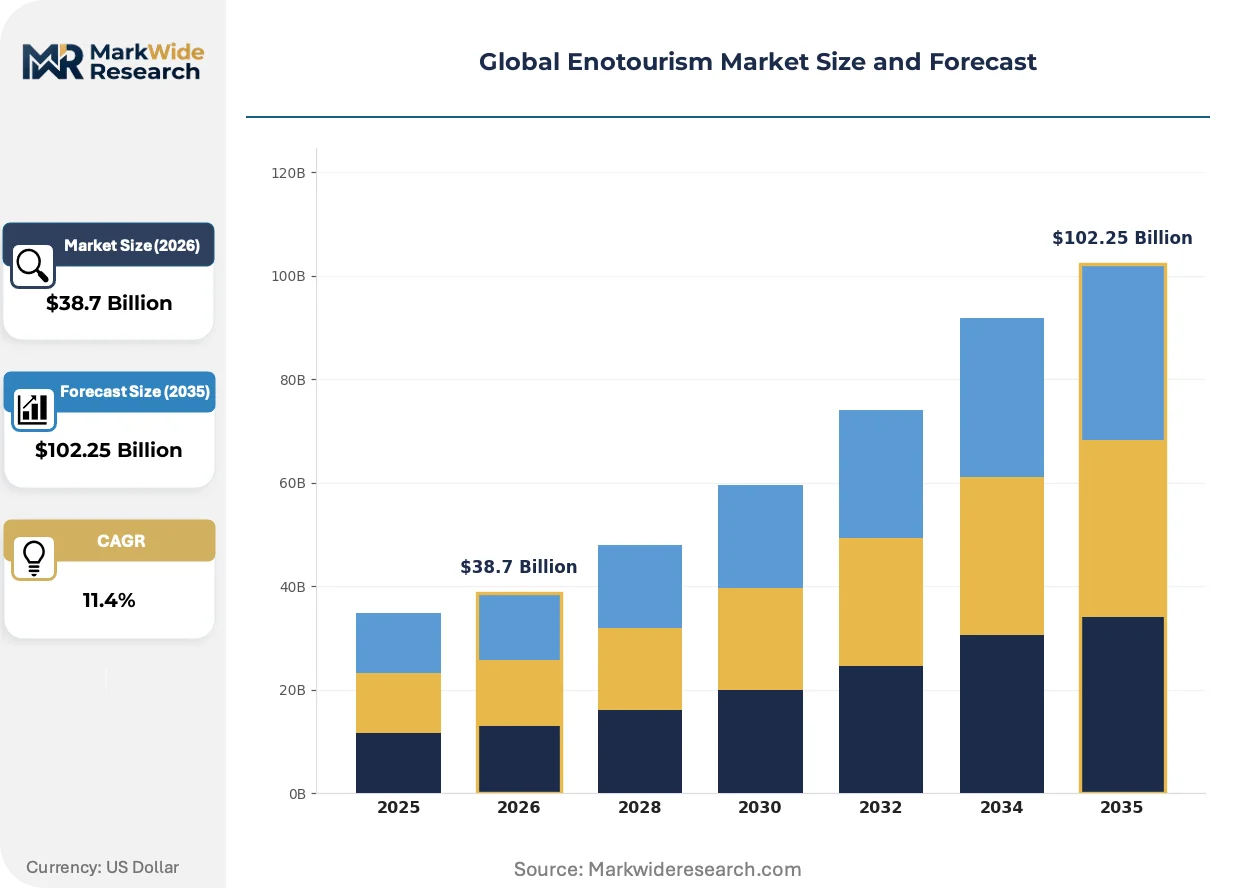
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tour Type: Wine Tastings, Vineyard Tours, Grape Harvesting, Wine Production Workshops, Cultural Events, Gastronomy Experiences Visitor Profile: Leisure Travelers, Wine Enthusiasts, Culinary Tourists, Eco-Friendly Tourists, Educational Groups, Luxury Travelers Service Offering: Guided Tours, Wine Pairing Sessions, Accommodation Packages, Shuttle Services, Event Hosting, Online Booking Distribution Channel: Travel Agencies, Online Travel Portals, Local Tourism Boards, Direct Booking, Corporate Partnerships, Social Media Marketing |
| Companies Covered | A Great Oregon Wine Tour, California Wine Tours, Arblaster and Clarke Wine Tours, Bulgaria Wine Tours, Grape Escapes Wine Tours, Iowa Wine Tours Inc, 290 Wine Shuttle, Cloud Climbers Jeep and Wine Tours, Discover Texas Wine Tours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enotourism Market Shifts & Advancements
Digital-native travelers are compressing the discovery-to-booking cycle while demanding granular customization, forcing operators to rearchitect reservation systems around real-time inventory transparency and modular experience bundling.
Virtual reality pre-visit vineyard walkthroughs is modularizing how travelers evaluate terroir and accommodation quality before committing to multi-day itineraries. High-net-worth prospects from the United States and United Kingdom now expect immersive digital reconnaissance as standard in their consideration phase. This compression of physical site visits into virtual previews is reducing cancellation rates while elevating upfront content production costs for operators.
EU Green Deal farm-to-fork traceability requirements are mandating blockchain-verified provenance documentation for vineyard inputs and wine production batches. French and Italian cooperatives must now maintain granular chemical-application records accessible to visitor-facing QR codes. Compliance investments are favoring larger estate operations with dedicated sustainability officers over fragmented smallholder associations.
Subscription-based wine club memberships bundled with seasonal vineyard access are displacing transactional single-visit ticketing as the dominant monetization model. California and Australian operators pioneered annual membership tiers with priority harvest participation rights. This recurring-revenue structure is visible most acutely in Napa-Sonoma corridor properties where repeat visitation rates now exceed 35% for enrolled members.
Global Enotourism Market Segmentation
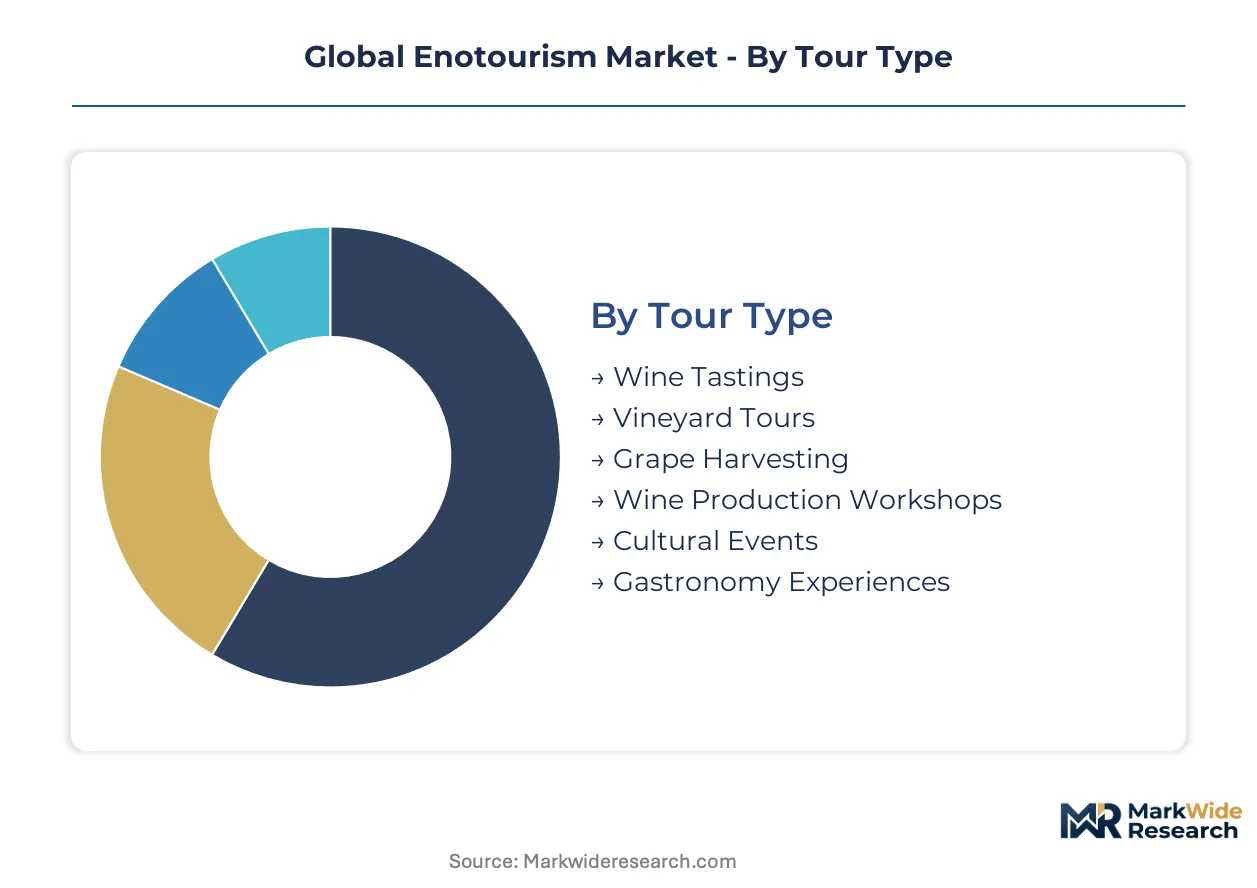
Enotourism operators structure their offerings around distinct visitor motivations and booking behaviors. Segment boundaries increasingly blur as subscription models bundle multiple service categories into recurring-revenue relationships.
Tour Type:
Supply concentrates in experiential formats that extend dwell time and per-visitor spend.
- Wine Tastings and Vineyard Tours:Structured barrel-room and cellar experiences with licensed serving protocols. France, Italy, and Spain absorb the bulk of installed capacity due to established route infrastructure and appellation density.
- Gastronomy Experiences:Multi-course chef collaborations integrating regional cuisine with paired wine sequences. Culinary tourists from the United States and United Kingdom drive demand concentration, with per-visitor spend premiums above standard tastings.
- Grape Harvesting:Seasonal crush and blending participation programs. Hands-on agricultural immersion attracts experiential travelers seeking authentic viticulture engagement.
- Wine Production Workshops:Educational sessions covering fermentation science and blending techniques. Small-group formats constrain scaling due to certified educator requirements.
- Cultural Events:Festival and concert programming at vineyard estates. Extends visitation into shoulder seasons with lower infrastructure utilization.
- Cultural Events:Heritage site integration and historical narrative programming. Regional tourism boards leverage UNESCO designations to differentiate destination positioning.
Wine Tastings and Vineyard Tours absorb the bulk of installed capacity; Gastronomy Experiences are expanding most quickly.
Visitor Profile:
Cost tier stratification separates mass-market day-trippers from high-net-worth annual membership subscribers.
- Leisure Travelers:Casual visitors seeking weekend excursion experiences. Millennial and Gen Z cohorts concentrate demand through mobile-first booking platforms.
- Luxury Travelers:High-net-worth individuals purchasing exclusive vineyard buyouts and private chef services. Napa-Sonoma corridor operators capture premium pricing through membership tier structures.
- Wine Enthusiasts:Collectors and connoisseurs pursuing educational depth and rare vintage access. Sommelier-guided small-group formats command wage premiums exceeding generalist tour guides.
- Culinary Tourists:Gastronomy-focused visitors prioritizing chef collaboration and regional cuisine integration. Per-visitor spend concentrates in French and Italian markets.
- Eco-Friendly Tourists:Sustainability-conscious travelers seeking EU Green Deal certified low-chemical viticulture. REACH compliance documentation via QR-accessible provenance records shapes destination selection.
- Educational Groups:University and professional cohorts studying oenology and regional agricultural systems. Seasonal concentration aligns with harvest windows.
Leisure Travelers represent the largest addressable base; Luxury Travelers deliver the steepest expansion trajectory through recurring-revenue membership models.
Service Offering:
Margin structure favors direct-to-consumer channels eliminating intermediary commissions.
- Guided Tours:Certified educator-led vineyard walks and production facility access. Bilingual oenology specialists constrain scaling due to talent scarcity.
- Online Booking:Direct-to-consumer reservation platforms with real-time inventory transparency. Mobile-first interfaces displace traditional travel agency intermediaries.
- Accommodation Packages:Multi-day lodge and boutique hotel bundling with vineyard access. California and Australian operators sustain year-round volume through property density.
- Wine Pairing Sessions:Curated tasting sequences with technical education components. TTB and national alcohol licensing frameworks govern serving volumes.
- Shuttle Services:Transport coordination between urban centers and rural vineyard clusters. Carbon-footprint disclosure mandates reshape fleet procurement decisions.
- Event Hosting:Corporate and private function facilities at estate properties. Straddles peak and shoulder season demand curves.
Guided Tours absorb the bulk of labor deployment; Online Booking is gaining share fastest through margin capture and repeat visitation enablement.
Distribution Channel:
Volume flows increasingly through digital-native aggregators with mobile-optimized interfaces.
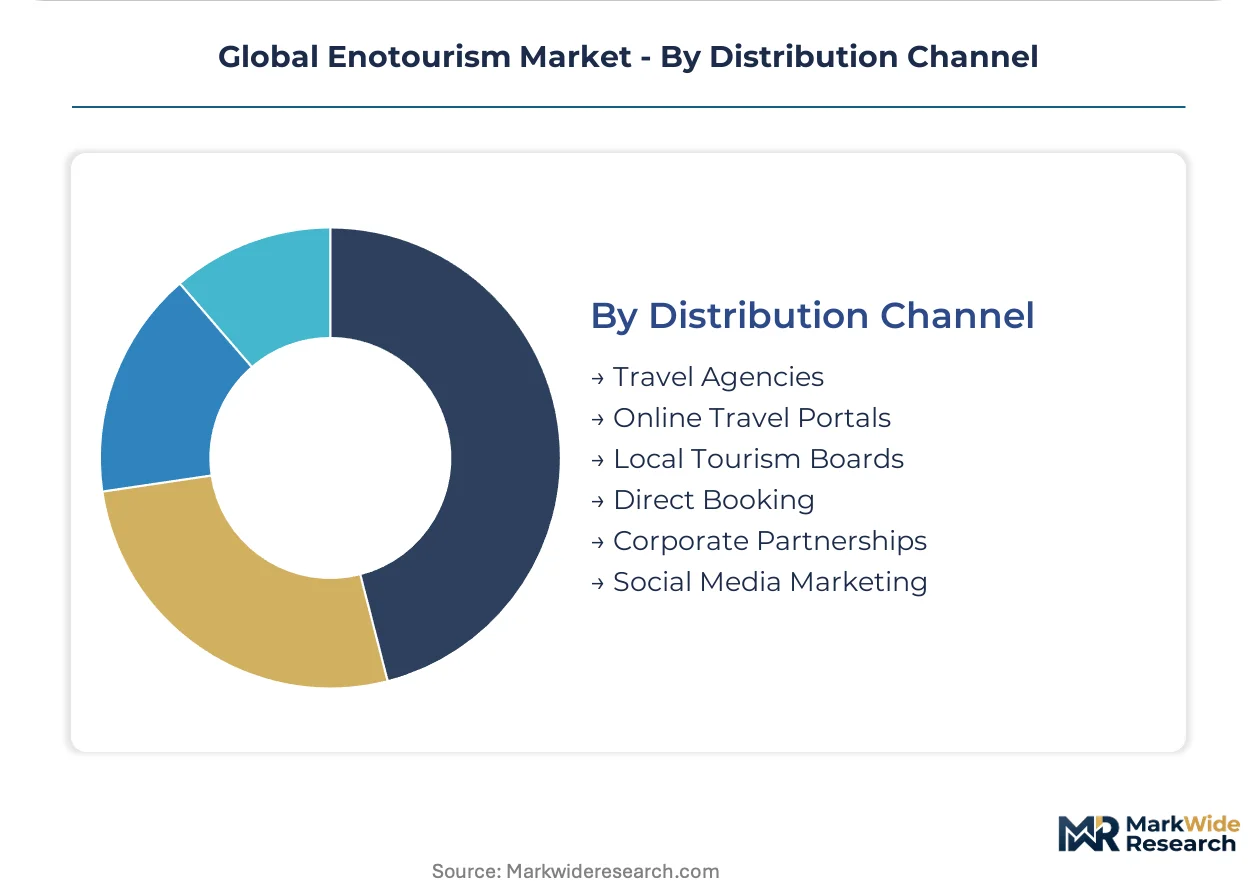
- Online Travel Portals:Aggregator platforms with modular experience bundling and transparent pricing. Millennial and Gen Z procurement patterns concentrate here.
- Direct Booking:Proprietary reservation systems capturing full margin and customer data. Subscription wine club integration enables recurring-revenue relationships.
- Travel Agencies:Traditional intermediaries serving older demographic cohorts and complex multi-destination itineraries. Share erosion accelerates as mobile adoption broadens.
- Local Tourism Boards:Regional destination marketing organizations promoting route infrastructure. EU Green Deal sustainability certification requirements reshape partnership criteria.
- Corporate Partnerships:Enterprise procurement of team-building and incentive travel programming. Sustainability reporting alignment drives vendor selection.
- Social Media Marketing:Influencer-driven discovery and direct conversion through platform-embedded booking. Virtual reality pre-visit content reduces cancellation rates.
Online Travel Portals capture the bulk of new visitor acquisition; Direct Booking is climbing the fastest as operators invest in proprietary platform development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France produces the bulk of established wine route infrastructure while the United States captures premium pricing through membership-based monetization. Italy and Spain concentrate harvest-season visitor volume through gastronomy integration. Australia and emerging Eastern European destinations compete for experiential traveler segments seeking lower-cost viticulture immersion.
France
Bordeaux and Burgundy châteaux drive luxury traveler demand through exclusive vineyard buyout programs. EU Green Deal farm-to-fork traceability requirements mandate blockchain-verified provenance documentation accessible via QR codes. Champagne region cooperatives invest in certified low-chemical viticulture credentials to capture sustainability-conscious visitor segments.
United States
Napa-Sonoma corridor operators sustain year-round booking volume through subscription wine club memberships bundled with seasonal access. TTB interstate shipment permissions and tasting-room volume limits create compliance complexity for multi-destination tour packaging. California properties pioneer recurring-revenue structures with repeat visitation rates exceeding 35% for enrolled members.
Italy
Tuscany and Piedmont absorb the bulk of gastronomy experience demand through multi-course chef collaborations commanding per-visitor spend premiums. REACH chemical-use standards reshape certification protocols for vineyard input documentation. UNESCO-designated heritage sites in rural appellations differentiate positioning through historical narrative programming.
Spain
Rioja and Priorat concentrate experiential traveler demand through harvest-season labor participation programs. Drought frequency in southern growing regions compresses harvest predictability and strains irrigation infrastructure utilization. Andalusian operators extend shoulder-season visitation through festival and concert programming at estate properties.
Australia
Barossa Valley and Margaret River anchor English-language enotourism demand from North American and British visitor cohorts. National alcohol licensing frameworks govern tasting-room serving protocols and direct-to-consumer shipment permissions. Boutique lodge development in cooler-climate sub-regions targets high-net-worth prospects seeking exclusive vineyard access.
Global Enotourism Market Competitive Landscape
Top-tier vendors anchor established wine corridor density, while regional specialists compete on terroir narrative differentiation and emerging destination access. The vendor base stratifies across three tiers: multinational tour aggregators with proprietary booking platforms, corridor-focused operators leveraging route infrastructure concentration, and boutique specialists emphasizing small-group educational formats. Two strategic archetypes dominate competitive positioning: membership-based recurring-revenue models and experiential programming specialists. Geographic expansion into underexploited appellations and technology-enabled reservation transparency represent the dominant competitive moves.
Within the corridor-focused tier, California Wine Tours exemplifies route-density monetization through year-round Napa-Sonoma booking volume. Arblaster and Clarke Wine Tours occupies a position among European educational itinerary specialists emphasizing small-group formats across established appellations. Grape Escapes Wine Tours represents the emerging-market access archetype through bilingual programming in Eastern European regions. These three operators collectively illustrate how competitive positioning stratifies across geographic concentration, educational depth, and destination novelty vectors.
| Leading Market Players |
|---|
| A Great Oregon Wine Tour |
| California Wine Tours |
| Arblaster and Clarke Wine Tours |
| Bulgaria Wine Tours |
| Grape Escapes Wine Tours |
| Iowa Wine Tours Inc |
| 290 Wine Shuttle |
| Cloud Climbers Jeep and Wine Tours |
| Discover Texas Wine Tours |
| Others |
Supply & Pricing Matrix
Millennial and Gen Z procurement through mobile-first booking platforms is forcing vineyard operators toward direct-to-consumer reservation infrastructure, compressing intermediary margins and elevating upfront technology investment requirements that reshape cost recovery timelines across tiered service offerings.
Pricing Analysis
Cost-down pressure on standard tasting packages accelerates as digital-native aggregators displace traditional travel agency intermediaries and capture repeat visitation through subscription wine club bundling. Three-tier pricing structure across premium, standard, and economy levels separates exclusive vineyard buyout programs from small-group educational formats and mass-market day-trip excursions. REACH compliance certification and EU Green Deal traceability documentation command price premiums from sustainability-conscious traveler segments. Luxury travelers demonstrate lowest price sensitivity through membership-based recurring-revenue relationships, while leisure day-trippers concentrate demand in economy tiers.
Supply Chain Analysis
Reverse logistics for wine club fulfillment and interstate shipment returns flow through centralized Napa-Sonoma corridor distribution hubs serving North American subscriber bases. Supply concentrates in France, Italy, and Spain for established route infrastructure and appellation density, with emerging capacity in Bulgaria, Romania, and Georgia for lower-cost boutique development. Vineyard input dependencies rest on oak barrel cooperage from French and American forests, glass bottle manufacturing from Italy and Germany, and certified low-chemical fertilizer sourcing compliant with REACH standards. Single-source vulnerability in sommelier-guide talent pools constrains experience scaling. Distribution runs through proprietary direct-booking platforms and online travel portal aggregators with mobile-optimized interfaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Virtual reality pre-visit vineyard walkthroughs are displacing physical site reconnaissance as the standard consideration-phase technology, compressing cancellation rates while elevating content production costs that separate digital-capable operators from legacy-dependent competitors.
For Market Incumbents: Deepen vertical integration into proprietary booking platform development to defend margin capture against digital-native aggregator encroachment. Invest in certified bilingual oenology educator pipelines to address talent scarcity constraining small-group experience scaling. Prioritize EU Green Deal compliance documentation through blockchain-verified provenance systems to maintain premium positioning under emerging carbon-footprint disclosure mandates. For New Entrants and Emerging Players: Enter via Eastern European appellations in Bulgaria, Romania, and Georgia where land-cost bases support boutique lodge development and exclusive vineyard buyout programs with limited incumbent saturation. Target eco-friendly tourist segments through REACH-certified low-chemical viticulture credentials and QR-accessible traceability records. Deploy bilingual programming as the primary go-to-market angle for experiential travelers seeking authentic agricultural immersion outside saturated Western European corridors. For Investors and Strategic Acquirers: The window for entry favors corridor-focused operators with established route density and recurring-revenue membership structures over transactional single-visit ticketing models. Long-term viability hinges on technology-enabled reservation transparency and carbon-footprint compliance positioning. Monitor EU Green Deal transport-emissions reporting implementation as the signal to watch for premium pricing power inflection among early-aligning operators.| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Reality Content Development | Pre-visit vineyard walkthroughs reduce cancellation rates among high-net-worth prospects from the United States and United Kingdom. |
| Blockchain Provenance Implementation | EU Green Deal farm-to-fork traceability requirements mandate QR-accessible chemical-application records for French and Italian cooperatives. |
| Subscription Membership Tiering | California Wine Tours sustains repeat visitation rates exceeding 35% through priority harvest participation rights bundling. |
| Eastern European Appellation Expansion | Grape Escapes Wine Tours captures experiential travelers through bilingual programming in underexploited Bulgarian and Romanian terroirs. |
| Certified Educator Pipeline Investment | Sommelier-guide wage premiums exceeding 40% above generalist tour guides constrain small-group experience scaling across European appellations. |
Research Methodology
Independent corroboration across vineyard operator interviews, regional tourism board consultations, and digital platform developer engagements underwrites the qualitative findings in this study. Primary fieldwork captured perspectives from estate sustainability officers, certified oenology educators, mobile booking platform engineers, and corporate procurement managers for team-building programming. Secondary validation drew from EU Green Deal regulatory filings, TTB interstate shipment permission records, national alcohol licensing framework documentation, and hospitality sector trade association reports. Bottom-up segmentation modeling triangulated against top-down corridor capacity assessments.
Comparable-period anchoring to historical visitation patterns across harvest and shoulder seasons structured the projection horizon for experience-type demand evolution. The analytical framework modeled segmentation across tour type, visitor profile, service offering, and distribution channel dimensions, with regional regulatory cluster as an additional enotourism-specific layer. CAGRs were derived from trend extrapolation calibrated to mobile-first booking adoption curves and subscription membership penetration trajectories. Forecast inputs incorporated climate volatility impact on Mediterranean harvest predictability and sommelier-guide labor market tightness.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Green Deal enforcement timelines or prolonged drought frequency in southern French and Spanish growing regions. Material deviation in carbon-footprint disclosure mandate implementation schedules or TTB interstate shipment permission liberalization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
France Luxury Travel Market
Travel and Tourism
Dark Tourism Market
Travel and Tourism
MICE Travel Service Market
Travel and Tourism
France Outbound Tourism Market
Travel and Tourism
Japan Sports Tourism Market
Travel and Tourism
UAE Sustainable Tourism Market
Travel and Tourism
Vietnam Online Travel Market
Travel and Tourism
Japan Outbound Tourism Market
Travel and Tourism
Tourism Market
Travel and Tourism
Middle East and Africa Travel Retail Market
Travel and Tourism
Japan Tourism Market
Travel and Tourism
Europe Wellness Tourism Market
Travel and Tourism
Luxury Tourism Market
Travel and Tourism
Sports Tourism Market
Travel and Tourism
GCC Outbound Tourism Market
Travel and Tourism
Japan Travel Retail Market