
 Hot Pot Seasoning Market | 2026-2036
Hot Pot Seasoning Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Pot Seasoning Market Insights
E-commerce platforms and quick-commerce delivery networks is rewriting how hot pot seasoning reaches consumers in China's tier-two cities. Yihai International Holding Ltd. leverages its captive supply chain to control costs across chili sourcing and blending operations. Teway Food Group anchors its position through deep distribution into Sichuan's restaurant wholesale channel. Little Sheep Group differentiates via brand recognition built from its restaurant heritage.
Hot pot seasoning comprises concentrated flavor bases—typically oil-based chili suspensions, fermented bean pastes, or dried herb blends—formulated to dissolve into boiling broth and deliver consistent mala, savory, or herbal profiles across meal occasions. Manufacturers employ low-temperature grinding and controlled oxidation steps to preserve volatile capsaicinoids and aromatic compounds. Spicy formulations occupy the largest margin pool due to premium Sichuan peppercorn and chili sourcing costs, while pouches gain traction among younger urban consumers seeking single-use convenience. Packets still dominate food service procurement where volume and shelf stability matter most.
China's SAMR enforces GB standards for additive limits and labeling accuracy in compounded seasonings, pushing smaller blenders toward certified co-manufacturers. The EU's EFSA and REACH frameworks govern imported seasoning shipments entering European retail through Asian grocery networks. Stakeholders must monitor how dual carbon goals from China's MEE reshape energy-intensive chili drying and oil extraction operations, and whether compliance investments consolidate the supplier base faster than brand expansion can offset.
Market Dynamics
Chili oil extraction and Sichuan peppercorn sourcing concentrate in Sichuan basin and Chongqing municipality, creating geographic chokepoints that amplify input cost volatility and favor blenders with captive agricultural networks.
Growth Catalysts
- Quick-commerce infrastructure:Meituan and Ele.me delivery networks compress last-mile timelines for fresh seasoning pouches in Chengdu and Wuhan, expanding addressable occasions beyond restaurant procurement.
- GB standards compliance:China's SAMR enforcement of additive limits and labeling accuracy pushes unlicensed blenders toward certified co-manufacturers, consolidating volume with compliant producers.
- Fermentation biotechnology:Controlled microbial inoculation of broad bean pastes shortens maturation cycles from months to weeks, stabilizing supply for mala base formulations.
Market Restraints
- Input cost volatility:Sichuan peppercorn harvests fluctuate with summer rainfall patterns in Yunnan and Guizhou provinces, squeezing margins on premium mala profiles.
- Supply concentration risk:Chili drying operations cluster in Xinjiang and Shandong, exposing blenders to regional drought and transportation bottlenecks.
- Regulatory friction:EU EFSA novel food assessments delay entry of fermented chili pastes into European retail through Asian grocery channels.
Strategic Opportunities
- Underpenetrated tier-three cities:Hefei, Nanchang, and Guiyang exhibit rising hot pot restaurant density without matching seasoning brand penetration, creating first-mover whitespace.
- Plant-based broth convergence:Kombu and mushroom extract technologies merge with traditional mala bases to capture flexitarian diners in Shanghai and Shenzhen.
- Dual carbon incentives:China's MEE subsidies for solar-powered chili drying equipment reward early adopters with operational cost advantages.
Industry Challenges
- Flavor chemist scarcity:Formulation expertise in capsaicinoid stabilization and Maillard reaction control concentrates among senior technicians in Chongqing, constraining R&D expansion.
- Traceability system integration:NMPA-mandated blockchain ingredient tracking requires legacy blenders to rebuild procurement databases, extending compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Pot Seasoning Market |
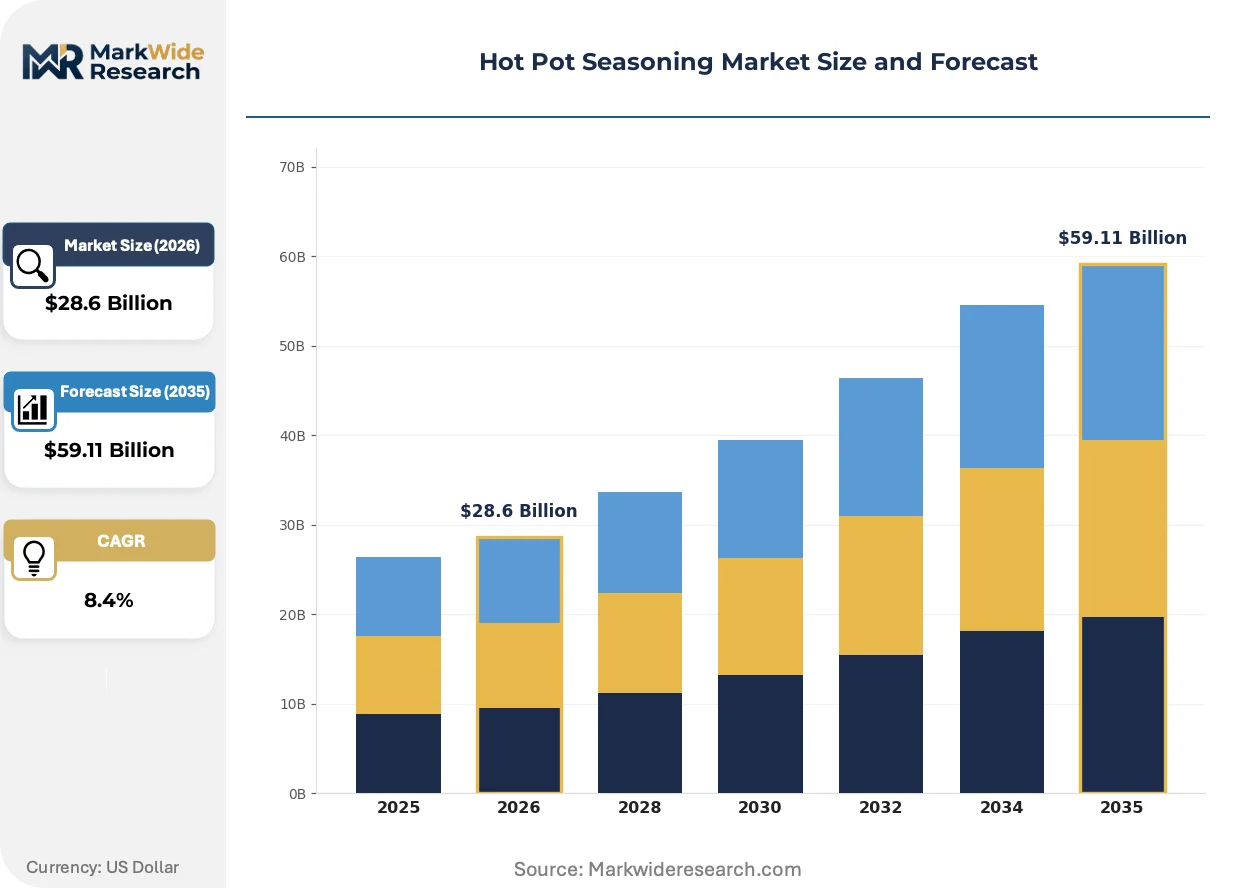
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spicy, Savory, Herbal, Seafood Ingredient Type: Chili, Garlic, Ginger, Sesame Packaging Type: Packets, Jars, Pouches, Bottles Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service |
| Companies Covered | Teway Food Group, Little Sheep Group, Yihai International Holding Ltd., Sichuan Haidilao Food Co., Ltd., Chongqing Zhoujunji Hot-pot Food Co Ltd, Chongqing Hongjiujiu Food Co., Ltd., Dezhuang, Lee Kum Kee, Inner Mongolia Red Sun Food Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Pot Seasoning Market Trends and Innovations
Low-temperature grinding and nitrogen-flush packaging are compressing the gap between artisanal flavor fidelity and industrial scale, reshaping how premium positioning is manufactured rather than merely marketed.
Supercritical CO2 extraction of chili oleoresins preserves heat compounds without thermal degradation, enabling precise Scoville standardization. Mid-tier blenders in Chengdu adopt this equipment to enter restaurant private-label contracts previously reserved for heritage brands. Batch consistency is rendering obsolete the artisan credential that once justified premium pricing.
China's dual carbon targets from the MEE impose energy intensity audits on chili drying and oil extraction facilities, accelerating consolidation toward producers with captive solar arrays. Smaller blenders face capital requirements for heat-pump retrofits or risk losing SAMR operating licenses. Sichuan-based manufacturers with existing agricultural land rights are converting drying yards to photovoltaic canopies fastest.
Single-serve pouch formats displace bulk canisters among urban renters in Beijing and Hangzhou who lack storage space and cook hot pot irregularly. Convenience-store chains now stock rotating mala, tomato, and mushroom base SKUs near checkout, replacing traditional wholesale restaurant dependency. Chongqing-born brands with heritage restaurant DNA struggle to adapt packaging formats without diluting perceived authenticity.
Hot Pot Seasoning Market Segmentation
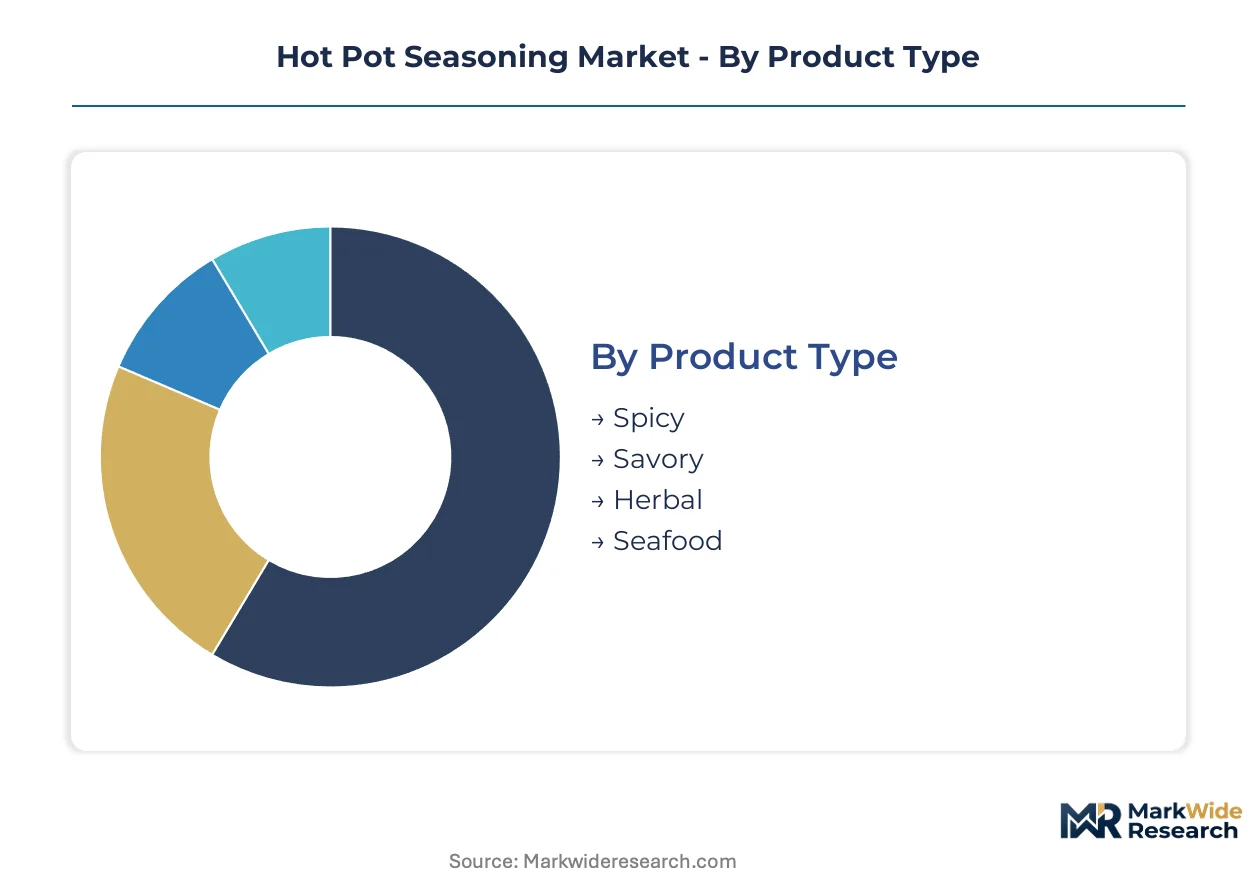
Hot pot seasoning manufacturers engineer product architectures around flavor intensity, ingredient provenance, and occasion-based packaging. Segmentation discipline separates commodity blenders from premium positioning in China's fragmented condiment landscape.
Product Type:
Mature spicy formulations anchor revenue while emerging profiles target dietary diversification and regional taste migration.
- Spicy:Oil-based chili suspensions incorporating Sichuan peppercorn deliver the signature mala numbing-heat profile. Restaurant chains in Chongqing and Chengdu specify Scoville-calibrated batches for broth consistency. Premium Sichuan peppercorn sourcing costs compress margins during poor harvests in Yunnan.
- Savory:Fermented bean paste bases with controlled Maillard reaction depth provide umami foundations without capsaicin heat. Home cooking enthusiasts in Shanghai and Beijing favor these for family meals with children. Tomato and mushroom variants are displacing traditional chicken stock concentrates in supermarket aisles.
- Herbal:Medicinal botanical infusions target wellness-positioned dining occasions.
- Seafood:Dried shrimp and kelp extracts serve coastal Fujian and Guangdong preferences.
Spicy handles the majority of throughput; savory is the fastest mover on share.
Ingredient Type:
Cost tier stratification runs from commodity bulb crops to geographically restricted rhizomes and oilseeds.
- Chili:Xinjiang and Shandong drying yards supply capsaicinoid-rich varieties for mala formulations. Xinjiang's arid climate produces higher oleoresin concentration than humid southern alternatives. Drought risk in the Tarim Basin amplifies price volatility for premium extract-grade fruit.
- Garlic:Shandong province dominates global bulb production with mechanized harvesting. Industrial dehydrators in Jinxiang county supply standardized flake and powder specifications. Cold storage capacity constraints create seasonal price troughs post-harvest.
- Ginger:Yunnan highland rhizomes command premium positioning for medicinal hot pot variants.
- Sesame:Henan and Hubei crushing mills provide roasted oil and paste inputs for dipping sauces.
Chili commands the highest input cost share; ginger is climbing the fastest on per-kilogram value.
Packaging Type:
Volume scale separates food service procurement from convenience-driven retail formats.
- Packets:Laminated film sachets dominate restaurant and institutional procurement for portion control and extended shelf stability. Chongqing blenders supply 500g multi-serve packs to hot pot chain central kitchens. Unit economics favor high-throughput rotary filling lines with nitrogen flush.
- Pouches:Stand-up flexible packaging with resealable zippers targets urban renters in Beijing and Hangzhou lacking pantry space. Single-serve 50g formats rotate through convenience store checkout displays. Meituan quick-commerce networks compress delivery windows for impulse replenishment.
- Jars:Glass containers preserve fermented paste integrity for premium positioning.
- Bottles:PET and glass formats serve liquid chili oil and sesame dressing segments.
Packets handle the majority of throughput; pouches are expanding most quickly on unit volume.
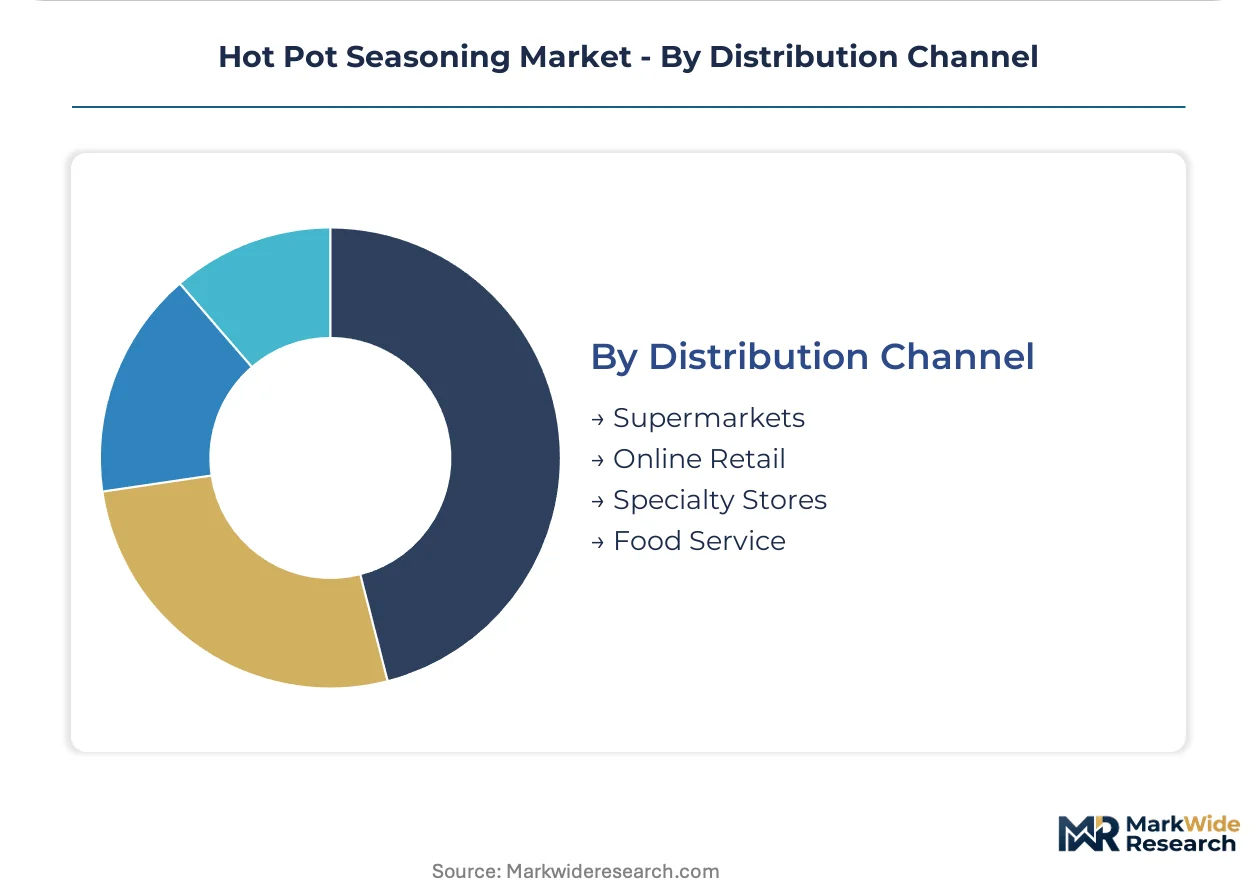
Distribution Channel:
Customer type bifurcates between procurement professionals and end-consumers with divergent quality signals.
- Food Service:Restaurant chains and independent hot pot operators purchase bulk specifications through Sichuan wholesale markets. Teway Food Group maintains dedicated sales teams for Chengdu restaurant row accounts. Chefs evaluate samples for broth clarity and residual sediment after boiling.
- Online Retail:Tmall and JD.com flagship stores transmit brand storytelling through origin videos and chef endorsements. Live-streaming hosts in Chongqing demonstrate mala base preparation to tier-three city audiences. Return logistics complexity limits glass jar penetration.
- Supermarkets:Yonghui and Carrefour shelf placement requires slotting fees and promotional calendar coordination.
- Specialty Stores:Asian grocery networks in North America and Europe curate heritage brands for diaspora consumers.
Food service handles the majority of throughput; online retail is gaining share fastest on customer acquisition efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Chongqing and Sichuan province exceeds that of coastal manufacturing hubs by a significant margin, reflecting the cultural authenticity premium attached to mala origin terroir. This asymmetry shapes procurement patterns across Asia-Pacific and diaspora markets. Regulatory divergence between China's SAMR enforcement and EU EFSA novel food assessments creates divergent compliance cost structures.
China
Restaurant chains in Chengdu and Chongqing drive bulk procurement of Scoville-calibrated mala bases through dedicated wholesale channels. SAMR enforcement of GB additive limits and labeling accuracy pushes smaller blenders toward certified co-manufacturers, consolidating volume with compliant producers. Sichuan basin agricultural networks supply Sichuan peppercorn and chili inputs with captive drying operations concentrated in Xinjiang and Shandong.
Japan
Specialty Asian grocery channels in Tokyo and Osaka curate heritage Chongqing brands for expatriate and adventurous domestic consumers. METI food import standards govern additive thresholds and irradiation restrictions on dried chili shipments. Kansai region distributors maintain refrigerated warehousing for fermented paste formats requiring temperature-controlled logistics.
South Korea
Seoul-based hot pot restaurant operators source mala bases through Busan-Ulsan port logistics corridors serving Chinese manufacturing clusters. MFDS import inspection protocols mandate heavy metal testing and capsaicinoid content disclosure for compounded seasonings. Daegu-Gyeongbuk food processing hubs increasingly blend Korean chili varieties with imported Sichuan formulations for localized heat profiles.
United States
Asian-American communities in Los Angeles County and Queens, New York sustain retail demand for authentic Chongqing-origin pouches and jars. FDA facility registration and FSVP importer verification requirements govern seasoning shipments entering through Los Angeles and Long Beach ports. California-based distributors negotiate slotting fees with regional supermarket chains for rotating mala and tomato base SKUs.
Germany
Turkish and Vietnamese diaspora communities in Berlin-Brandenburg and North Rhine-Westphalia expand addressable occasions for hot pot seasoning beyond traditional Chinese consumer bases. EFSA novel food assessments and REACH chemical safety frameworks delay entry of fermented chili pastes into mainstream retail. Frankfurt logistics hubs serve as consolidation points for redistribution into Netherlands and French Asian grocery networks.
Hot Pot Seasoning Market Competitive Landscape
Heritage restaurant-origin blenders and captive supply chain operators split the market between authenticity-positioned and cost-controlled volume plays. The vendor base concentrates among Sichuan-Chongqing rooted entities with agricultural land rights and solar-equipped drying infrastructure, alongside Hong Kong-listed food conglomerates with multi-category condiment portfolios. Three archetypes dominate: restaurant-heritage brands leveraging provenance storytelling, agricultural-integrated manufacturers controlling chili and peppercorn sourcing, and diversified sauce specialists cross-leveraging fermentation capabilities. Competitive moves center on quick-commerce distribution partnerships and solar-powered drying yard retrofits to capture MEE dual carbon subsidies.
Within the heritage-restaurant tier, Little Sheep Group and Dezhuang exemplify positioning built from dining establishment origins rather than manufacturing-first entry. Yihai International Holding Ltd. anchors the agricultural-integrated archetype through upstream control over chili sourcing and blending operations. Among diversified condiment houses, Lee Kum Kee occupies a position spanning multiple Asian sauce categories with manufacturing infrastructure adaptable to hot pot base production.
| Leading Market Players |
|---|
| Teway Food Group |
| Little Sheep Group |
| Yihai International Holding Ltd. |
| Sichuan Haidilao Food Co., Ltd. |
| Chongqing Zhoujunji Hot-pot Food Co Ltd |
| Chongqing Hongjiujiu Food Co., Ltd. |
| Dezhuang |
| Lee Kum Kee |
| Inner Mongolia Red Sun Food Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Xinjiang's arid chili drying yards and Shandong's mechanized processing clusters anchor upstream capacity, concentrating bargaining power among blenders with captive agricultural networks and amplifying price volatility when regional drought disrupts harvests. This geographic chokepoint configuration rewards producers who control land rights and solar-equipped infrastructure with downstream pricing leverage against fragmented restaurant procurement.
Pricing Analysis
Configured-to-order Scoville calibration for restaurant chains commands premium spreads over standard retail pouches, with price differentiation driven by Sichuan peppercorn provenance certification and volume scale commitments. Three-tier pricing structure across heritage-restaurant, agricultural-integrated, and diversified-condiment archetypes stratifies the market. Pricing pressure stems from input cost volatility in Yunnan peppercorn harvests, squeezing margins on premium mala formulations. Independent restaurant operators in tier-three cities exhibit highest price sensitivity, while Chongqing-based chain central kitchens prioritize batch consistency over unit cost.
Supply Chain Analysis
Tariff exposure between China and EU member states dominates supply chain risk for fermented paste exports awaiting EFSA novel food assessments. Geographic supply concentrates in Sichuan basin agricultural networks, Xinjiang drying yards, and Shandong processing clusters. Raw material dependencies center on Sichuan peppercorn, Xinjiang chili varieties, and Shandong garlic bulb crops. Single-source vulnerability in Yunnan highland ginger rhizomes creates bottleneck exposure for medicinal formulations. Distribution runs through Sichuan wholesale markets for food service, quick-commerce networks for urban retail, and Asian grocery channels for diaspora markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hot pot seasoning sits at the intersection of quick-commerce infrastructure buildout and NMPA-mandated blockchain traceability, creating a high-growth disruption where compliance investments consolidate volume faster than brand expansion can offset.
For Market Incumbents: Pre-empt unlicensed blender consolidation by securing SAMR-certified co-manufacturing capacity before compliance deadlines eliminate competitors. Lock in solar-powered drying yard retrofits to capture MEE dual carbon subsidies and anchor cost position against agricultural-integrated challengers. Defensive priority centers on quick-commerce distribution partnerships with Meituan and Ele.me networks. For New Entrants and Emerging Players: Tier-three city whitespace in Hefei, Nanchang, and Guiyang offers first-mover positioning before heritage brands adapt packaging formats. Target plant-based broth convergence with kombu and mushroom extract technologies to capture flexitarian diners in Shanghai and Shenzhen. Go-to-market angle should leverage single-serve pouch convenience for urban renters lacking pantry space. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors agricultural-integrated manufacturers with captive chili sourcing and solar-equipped infrastructure over brand-dependent heritage plays. Long-term viability hinges on traceability system integration capabilities and quick-commerce network access. Acquisition target archetype: Sichuan-based blenders with existing land rights and photovoltaic canopy conversions. Signal to watch: MEE enforcement timelines accelerating SAMR license consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Solar-Powered Drying Yard Retrofit | Captures MEE dual carbon subsidies while insulating against Xinjiang drought-driven input volatility. |
| Blockchain Traceability Integration | Meets NMPA ingredient tracking mandates and consolidates volume from non-compliant legacy blenders. |
| Quick-Commerce Distribution Partnership | Compresses last-mile delivery windows for single-serve pouches through Meituan and Ele.me networks. |
| Fermentation Biotechnology Scale-Up | Shortens broad bean paste maturation cycles from months to weeks for mala base supply stability. |
| Plant-Based Broth Line Extension | Merges kombu and mushroom extracts with traditional mala bases for flexitarian capture in coastal cities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SAMR regulatory filings, customs trade records, and NMPA food safety bulletins through structured interviews with hot pot restaurant procurement managers, Sichuan wholesale channel distributors, condiment R&D directors, and quick-commerce platform category buyers. Bottom-up volume estimates from individual blender capacity and top-down market sizing from retail audit data triangulate to convergence thresholds.
Forecast inputs span flavor intensity tiers, packaging format migration, and distribution channel evolution across the projection horizon. Segmentation dimensions modeled include product type, ingredient provenance, packaging convenience level, and customer procurement archetype. CAGRs derive from elasticity-adjusted demand curves incorporating quick-commerce penetration rates and regulatory compliance cost trajectories. Industry-specific inputs include Sichuan peppercorn harvest yield variance and solar drying equipment adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by agricultural-integrated manufacturers with captive land rights would shift outcomes through accelerated volume consolidation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Moringa Leaves Powder Market
Spices and Seasonings
Middle East and Africa Botanical Extract Market
Spices and Seasonings
Garlic Salt Market
Spices and Seasonings
Middle East and Africa Ashwagandha Market
Spices and Seasonings
Boswellia Extract Market
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
Green Pepper Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
Global Clove Market
Spices and Seasonings
Chipotle Salt Market
Spices and Seasonings
Ginger Oil Market
Spices and Seasonings
Paprika Powder Market
Spices and Seasonings
Pumpkin Pie Spices Market
Spices and Seasonings
Europe and Asia Juniper Berries Market
Spices and Seasonings
Gourmet Seaweed Seasoning Market
Spices and Seasonings
Asia-Pacific Spice and Herb Extracts Market