
 Global Used Smartphones Market | 2026-2036
Global Used Smartphones Market Size, Share, and Industry Trends Forecast 2026-2036
Global Used Smartphones Market Foresight
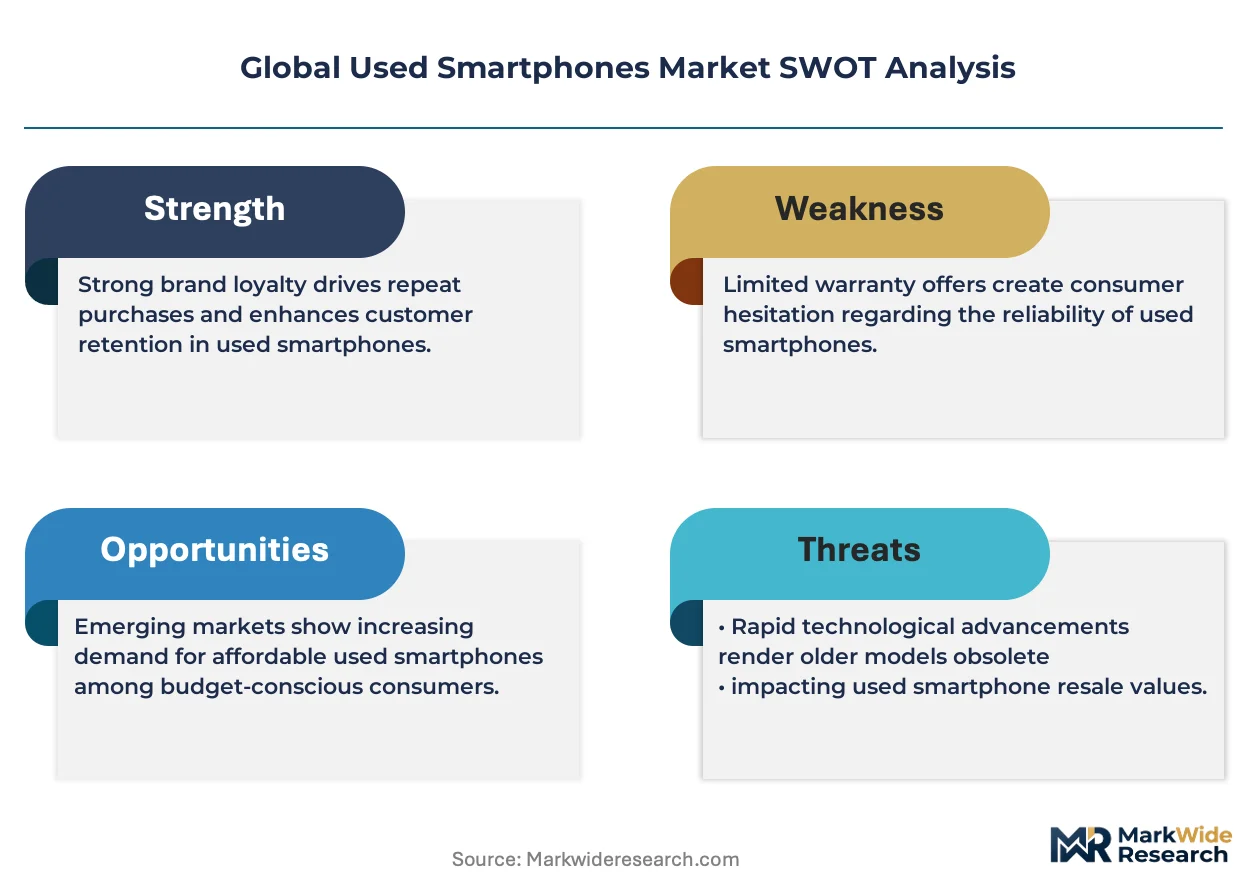
Aluminum chassis construction is hardening as the dominant housing material in refurbished devices, replacing fragile polycarbonate shells and improving drop-test resilience for secondary-market buyers. Back Market leverages direct partnerships with certified refurbishment facilities across France and Germany to control quality consistency. Samsung Electronics anchors its resale pipeline through in-house trade-in programs that feed certified pre-owned inventory. Gazelle specializes in streamlined device buyback workflows that reduce inspection friction for North American consumers.
A used smartphone denotes a previously activated mobile handset that has undergone functional verification, cosmetic grading, and data sanitization before re-entering commercial circulation; these devices typically retain minimum 80% battery health capacity and receive firmware support for secure enterprise deployment. The product condition segment stratifies into refurbished units commanding premium pricing, while Grade B inventory moves through bulk reseller channels at compressed margins. Online marketplaces capture the dominant transaction volume, though specialty retailers sustain higher per-unit profitability through add-on warranty attachment and in-person technical support.
The US Federal Communications Commission enforces equipment authorization standards that prevent blacklisted IMEI devices from accessing domestic carrier networks, while the EU REACH regulation restricts hazardous substance thresholds in refurbished electronics sold across member states. India's BIS certification mandate for imported pre-owned devices creates a compliance gate that filters low-quality cross-border supply. Stakeholders must monitor evolving right-to-repair legislation and IMEI registry harmonization as these frameworks determine which device cohorts qualify for legal resale in major consumption corridors.
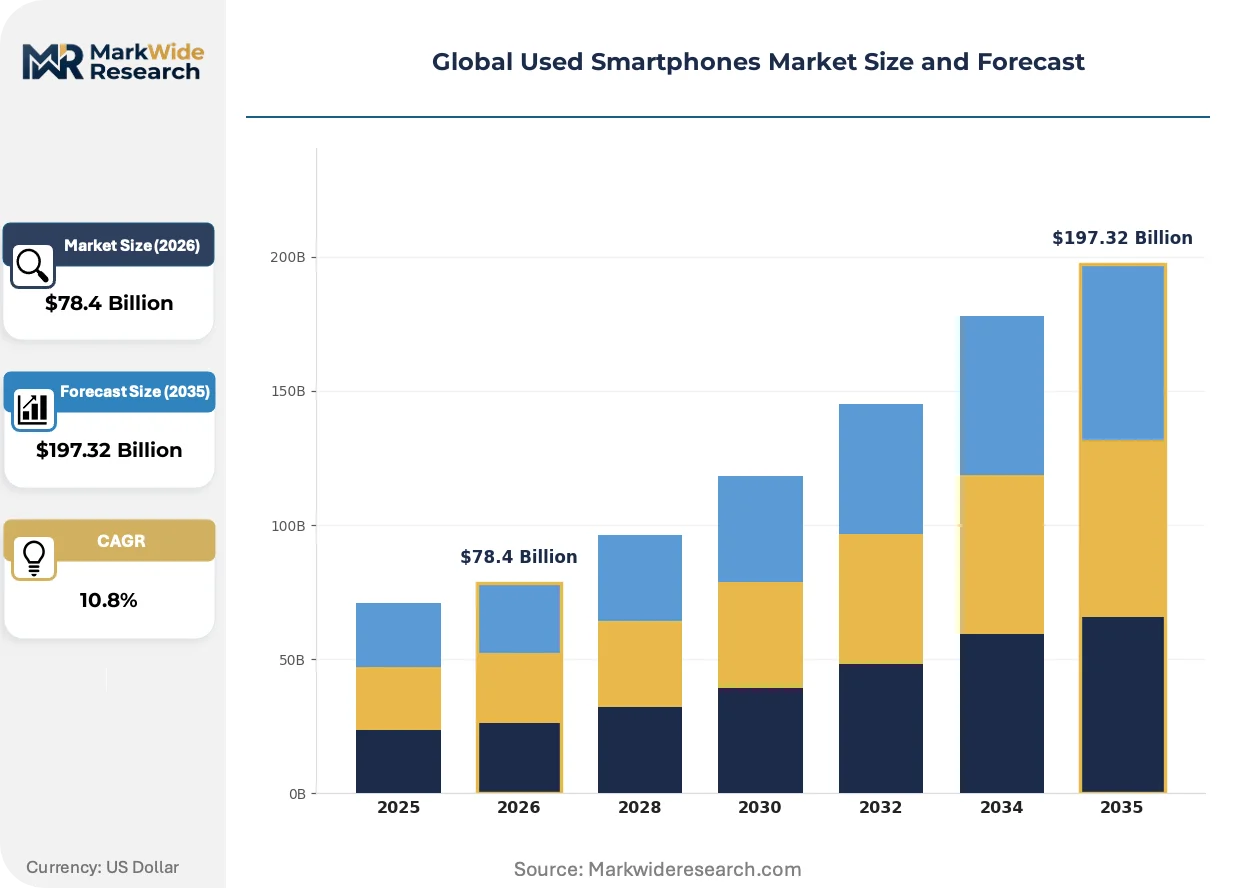
Market Dynamics
Right-to-repair mandates are compressing replacement cycles across major consumption corridors, forcing OEMs to release spare parts and diagnostic tools that extend device lifecycles and expand refurbisher access to repair-grade components.
Growth Catalysts
- EU Right-to-Repair Framework:Mandated parts availability and repair documentation access enable independent refurbishers to restore devices previously classified as uneconomical, expanding addressable supply pools across member states.
- India Digital Infrastructure Expansion:Price-sensitive first-time smartphone adopters in tier-2 and tier-3 cities are driving dense secondary-market corridors as 4G penetration deepens and e-commerce logistics reach smaller urban centers.
- Aluminum Chassis Adoption:Structural housing upgrades in refurbished devices reduce return rates from drop-damage claims, improving margin stability for warranty-backed resellers serving enterprise procurement segments.
Market Restraints
- IMEI Blacklist Fragmentation:Non-harmonized stolen-device registries across carrier networks create arbitrage risks where blacklisted devices migrate to jurisdictions with weaker cross-border verification, eroding buyer trust.
- Battery Cell Supply Concentration:Replacement battery sourcing depends on concentrated Asian manufacturing hubs, exposing refurbishers to input cost volatility and extended lead times for high-capacity cells.
- Biometric Component Interoperability:Proprietary fingerprint and face-recognition modules resist third-party replacement, rendering damaged security hardware a functional total-loss event despite intact core processors.
Strategic Opportunities
- Brazil Secondary-Market Formalization:Regulatory momentum toward device traceability and tax compliance creates first-mover advantages for certified refurbishers establishing localized grading and distribution infrastructure.
- Enterprise Fleet Refresh Cycles:Corporate mobility-as-a-service providers are sourcing certified pre-owned devices for field-worker deployments, opening B2B volume contracts with standardized security configurations.
- Modular Repair-Platform Convergence:Cloud-based diagnostic tools paired with augmented-reality guided disassembly are reducing technician training barriers and enabling distributed micro-refurbishment networks.
Industry Challenges
- Data Sanitization Certification Complexity:Multi-jurisdictional standards for secure erasure create compliance overhead, with NIST 800-88, GDPR data-deletion mandates, and enterprise audit requirements demanding redundant verification workflows.
- Display Panel Grading Subjectivity:Inconsistent cosmetic classification standards across resale platforms generate dispute volumes and return logistics costs that compress net transaction yields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Used Smartphones Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $197.32 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Condition: Refurbished, Grade A, Grade B, Unlocked Distribution Channel: Online Marketplaces, Specialty Retailers, Reseller Networks, Trade Shows End User Type: Individual Buyers, Small Enterprises, E-commerce Sellers, Mobile Network Operators Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Apple Inc., Samsung Electronics, Back Market, Amazon Renewed, Gazelle, ecoATM, Swappa, Decluttr, Best Buy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Used Smartphones Market Shifts & Advancements
Component-level traceability and automated condition assessment are reconfiguring how secondary-market inventory flows from collection through final sale, compressing inspection timelines and reducing information asymmetry between buyers and sellers.
Automated optical inspection systems are electrifying quality verification in high-volume refurbishment facilities. These machine-vision platforms detect sub-pixel display defects and chassis micro-fractures at throughput rates exceeding manual technician capacity by an order of magnitude. European and North American refurbishers are deploying these systems to reduce grading disputes and warranty claim rates.
REACH substance restrictions are tightening material compliance burdens for cross-border device resale. The EU regulation's hazardous substance thresholds now cover flame retardants and plasticizers in housing materials, requiring component-level testing documentation. Refurbishers serving EU member states are consolidating supply relationships with certified parts distributors to maintain compliance traceability.
Direct-to-consumer marketplace models are displacing traditional wholesale-to-retail distribution for Grade A inventory. Individual sellers and small refurbishers are leveraging platform authentication services to reach end-buyers without intermediary margin extraction. This channel compression is most pronounced in India and Southeast Asia, where mobile-first marketplace penetration enables seller-to-buyer transactions at scale.
Global Used Smartphones Market Segmentation
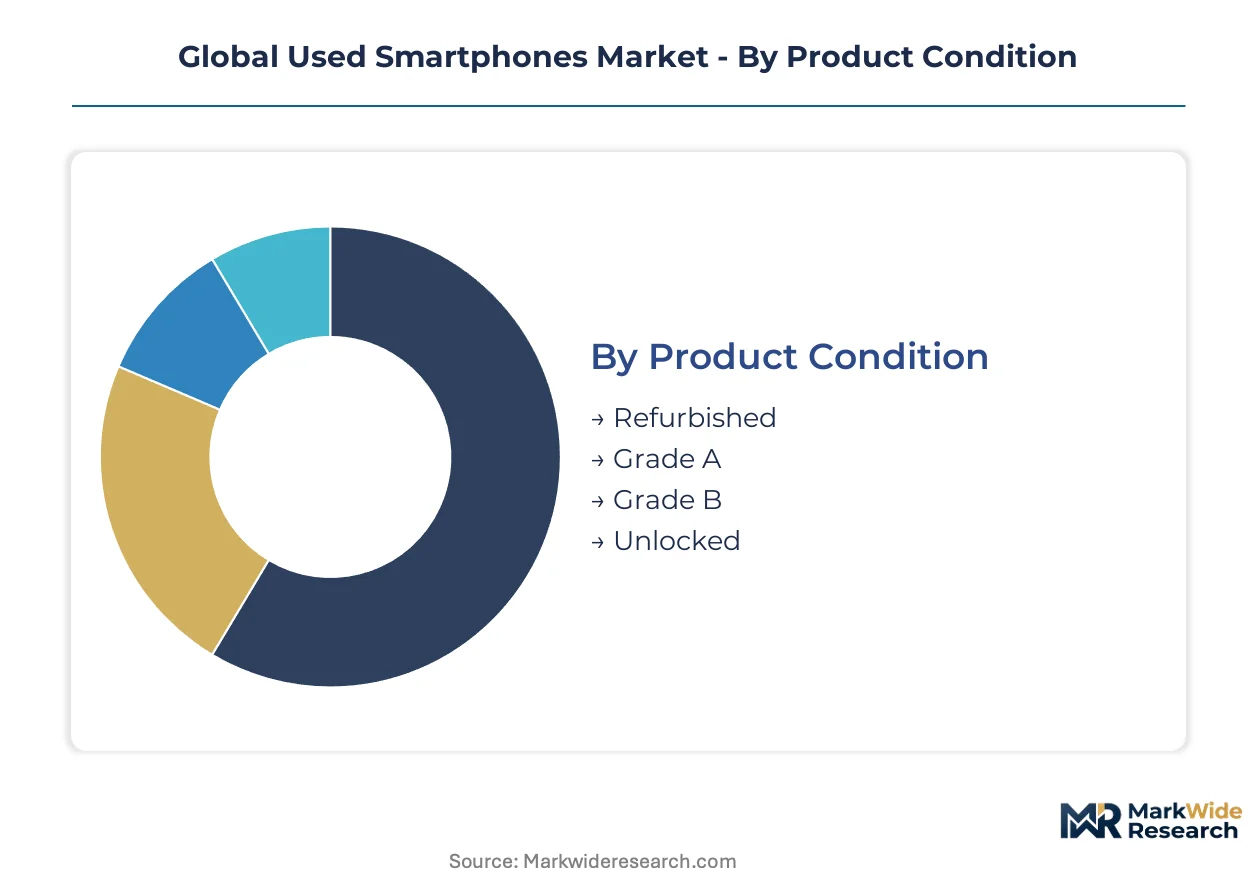
Condition grading and channel configuration determine margin capture in used smartphone resale. Price tier stratification aligns procurement sourcing with buyer willingness-to-pay across emerging and mature economies.
Product Condition:
Standalone resale dominates refurbished and Grade A inventory, while Grade B and unlocked units increasingly embed into bulk reseller workflows and carrier subsidy programs.
- Refurbished:Devices undergo component replacement, battery renewal, and cosmetic restoration to near-original specifications. Demand concentrates among enterprise fleet managers in Germany and France seeking standardized security configurations with warranty backing.
- Grade A:Minimal cosmetic wear with full functional integrity and battery health above 85%. Small enterprises in India's tier-2 cities prioritize these units for field-worker deployments where device appearance affects customer-facing interactions.
- Grade B:Visible cosmetic imperfections with intact core functionality. E-commerce sellers in Southeast Asia source these through bulk channels for price-sensitive consumer segments.
- Unlocked:Carrier-agnostic devices compatible with multiple network standards. Mobile network operators in Brazil bundle these with prepaid plans to reduce subsidy burdens.
Refurbished leads volumes today; Grade A is gaining share fastest.
Distribution Channel:
Channel selection reflects cost tier and buyer trust requirements, with high-touch formats serving premium segments and automated platforms capturing budget transactions.
- Online Marketplaces:Platform-mediated transactions with authentication services and buyer protection. Individual buyers in India and Indonesia drive volume through mobile-first interfaces with integrated logistics.
- Specialty Retailers:Physical inspection, technical support, and warranty attachment at point of sale. Small enterprises in France and Germany pay premium pricing for in-person service and immediate replacement guarantees.
- Reseller Networks:B2B bulk transactions between wholesalers and downstream distributors. E-commerce sellers in Southeast Asia rely on these channels for Grade B inventory at compressed margins.
- Trade Shows:Periodic congregation of regional wholesalers for large-lot negotiation. Mobile network operators in Brazil source enterprise fleet volumes through these events.
Online Marketplaces dominates transaction volume; Specialty Retailers delivers highest per-unit profitability.
End User Type:
Procurement patterns diverge between price-optimized individual acquisition and volume-negotiated enterprise deployment with standardized security requirements.
- Individual Buyers:Single-unit purchasers prioritizing price-to-performance ratios and cosmetic condition. India's tier-3 cities generate dense demand as first-time smartphone adopters enter digital commerce.
- Small Enterprises:Fleet purchasers requiring uniform device configurations and bulk warranty terms. Field-service companies in Germany source certified pre-owned units through trade-in programs.
- E-commerce Sellers:Intermediary actors arbitraging price differentials across regional markets. Reseller networks in Southeast Asia feed their inventory through platform-based retail channels.
- Mobile Network Operators:Carrier-integrated procurement for subsidy and prepaid plan bundling. Brazilian operators leverage unlocked inventory to reduce device financing exposure.
Individual Buyers anchor volume; Small Enterprises show steepest expansion trajectory.
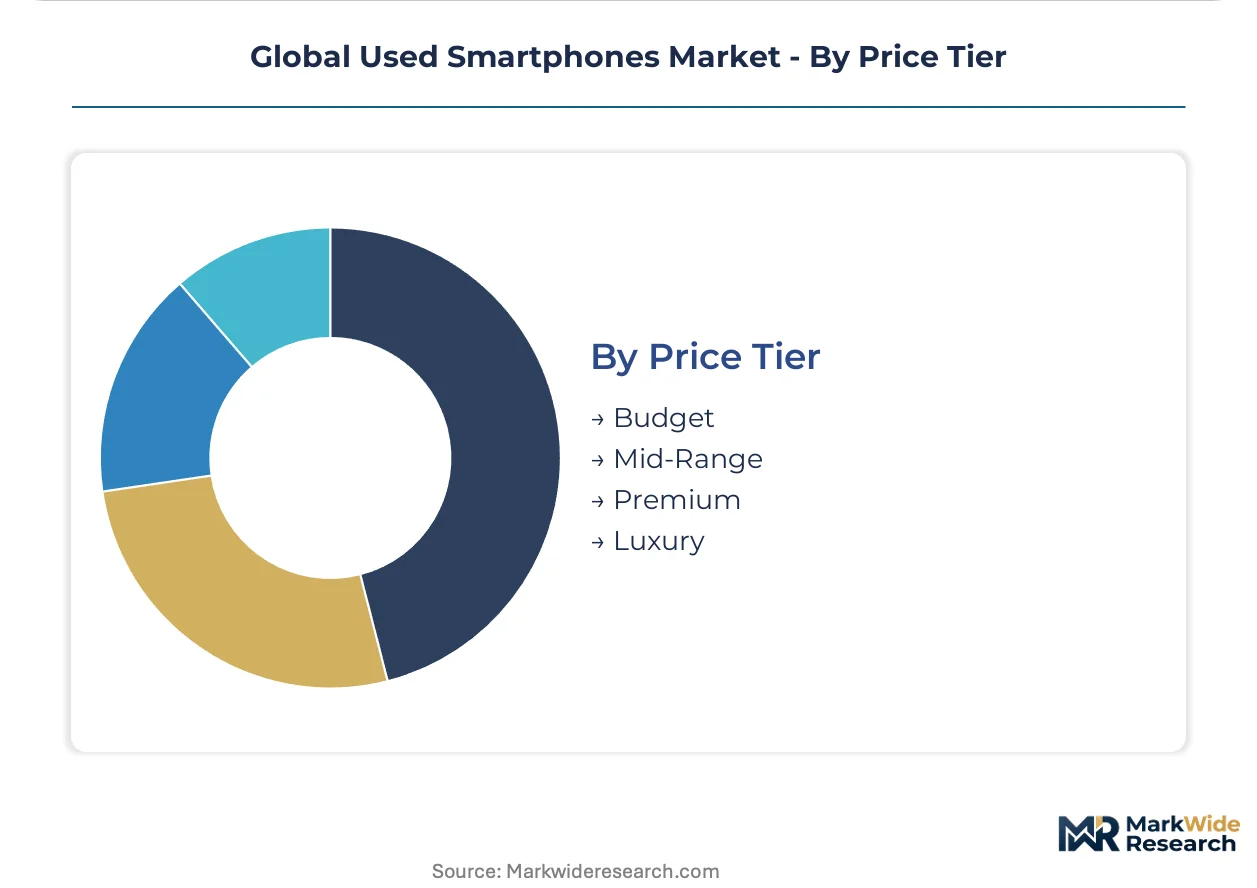
Price Tier:
Tier positioning aligns with condition grade and channel markup structure, with premium and luxury segments commanding certification overhead that budget tiers bypass.
- Budget:Sub-$150 devices targeting price-sensitive first-time adopters. Grade B inventory through online marketplaces serves India's rural digital infrastructure expansion.
- Mid-Range:$150-$400 segment balancing performance and affordability. Refurbished units through specialty retailers attract small enterprises in France seeking warranty-backed fleet standardization.
- Premium:$400-$800 former flagships with residual performance headroom. Enterprise procurement in Germany concentrates here for field-worker devices with adequate processing capacity.
- Luxury:$800-plus devices with brand cachet and collector value. Constrained supply limits this tier to specialty retailers in mature European markets.
Budget leads unit volumes; Premium climbs fastest on enterprise fleet conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor anchors secondary-market supply chains, with refurbishment clusters feeding both domestic Chinese demand and cross-border export channels into Southeast Asia and Africa.
United States
Enterprise fleet refresh cycles and carrier trade-in programs drive certified pre-owned volumes. The FCC's equipment authorization standards block blacklisted IMEI devices from domestic networks, tightening supply quality. Dallas-Fort Worth hosts major reverse-logistics hubs where devices undergo data sanitization and cosmetic grading before redistribution.
India
Price-sensitive first-time adopters in tier-2 and tier-3 cities generate dense resale demand as 4G penetration deepens. BIS certification mandates for imported pre-owned devices filter low-quality cross-border supply. Mumbai and Delhi-NCR concentrate refurbishment operations serving both domestic consumption and re-export to African markets.
Germany
Enterprise procurement of warranty-backed refurbished units dominates volume, with small businesses standardizing field-worker device fleets. REACH substance restrictions and right-to-repair mandates extend hardware lifecycles and expand refurbisher access to repair-grade components. Berlin and Hamburg host certified refurbishment facilities serving EU-wide distribution.
Brazil
Mobile network operators bundle unlocked pre-owned devices with prepaid plans to reduce subsidy burdens. Regulatory momentum toward device traceability and tax compliance creates formalization opportunities for certified refurbishers. São Paulo anchors grading and distribution infrastructure serving Latin American resale corridors.
France
Direct-to-consumer marketplace models capture premium refurbished inventory, with quality authentication services reducing buyer-seller information asymmetry. EU right-to-repair frameworks mandate parts availability for independent refurbishers. Paris and Lyon concentrate certified refurbishment partnerships that control quality consistency across member states.
Global Used Smartphones Market Competitive Landscape
Platform authentication investments dominate the current landscape, with marketplace operators and carrier-integrated programs racing to reduce inspection friction and warranty claim rates. The vendor base splits between manufacturer-led trade-in ecosystems, independent refurbishment specialists, and peer-to-peer exchange platforms. Three archetypes define positioning: OEM-captive programs leveraging in-house supply chains, pure-play refurbishers optimizing component-level restoration, and marketplace aggregators arbitraging price differentials across regional markets. Vertical integration into diagnostic tooling and strategic partnerships with logistics providers represent the dominant competitive vectors.
Among manufacturer-captive operators, Apple Inc. and Samsung Electronics exemplify the trade-in-to-refurbishment archetype, using in-house programs to control certified pre-owned inventory quality and capture secondary-market margins that would otherwise leak to independent channels. Back Market occupies a distinct position within the independent marketplace tier, anchoring European quality standardization through direct partnerships with certified refurbishment facilities. These three entities collectively represent the spectrum from closed-loop OEM control to open-platform aggregation that characterizes current competitive dynamics.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Back Market |
| Amazon Renewed |
| Gazelle |
| ecoATM |
| Swappa |
| Decluttr |
| Best Buy |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up refurbishment specialists have consolidated regional grading operations across France and Germany, tightening quality control while compressing procurement spreads between collection and resale. This ownership concentration feeds pricing discipline through standardized cost-to-serve metrics and captive warranty underwriting capacity.
Pricing Analysis
Input-cost pass-through from battery cell procurement runs directly into refurbished unit markups, with replacement lithium-polymer cells sourced from concentrated Asian manufacturing hubs commanding premium placement in warranty-backed inventory. Pricing stratifies across premium, standard, and economy tiers based on certification grade from EU-authorized facilities and cosmetic classification precision. Cost compression in Grade B channels is intensifying because e-commerce sellers arbitrage thin margins through volume velocity. Individual buyers in India's tier-3 cities exhibit highest price sensitivity, while German small enterprises absorb premium pricing for standardized security configurations and immediate replacement guarantees.
Supply Chain Analysis
Battery cell supply rests on South Korean and Chinese specialty chemical producers, with replacement component sourcing further concentrated in Shenzhen's electronics manufacturing corridor. Aluminum chassis feedstock draws from Chinese smelters and German precision metalworkers, while display panel procurement hinges on South Korean and Taiwanese OEM surplus channels. Single-source vulnerability in fingerprint and face-recognition modules creates functional total-loss exposure when proprietary biometric hardware sustains damage. Distribution runs through online marketplaces for Grade A inventory, with specialty retailers capturing premium refurbished flows through warranty attachment and technical support bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in used smartphones rests on automated optical inspection deployment compressing grading labor costs and enterprise fleet contracts shifting procurement toward certified pre-owned tiers with attached service revenue.
For Market Incumbents: Lock in quality differentiation through direct partnerships with EU-authorized refurbishment facilities controlling diagnostic tooling and spare parts access. Backward integration into data sanitization certification reduces compliance overhead from multi-jurisdictional standards including NIST 800-88 and GDPR deletion mandates. Defensive positioning against marketplace aggregators requires proprietary grading algorithms and reduced warranty claim rates through machine-vision defect detection. For New Entrants and Emerging Players: Launch via cloud-based diagnostic platforms paired with augmented-reality guided disassembly to enable distributed micro-refurbishment networks without capital-intensive facility buildout. Brazil's regulatory momentum toward device traceability and tax compliance presents the most penetrable formalization corridor for certified refurbishers establishing localized infrastructure. Target enterprise mobility-as-a-service providers through standardized security configurations and bulk warranty terms rather than competing for saturated individual buyer segments. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play refurbishers lacking OEM-captive supply chains but possessing established EU certification and quality authentication infrastructure. Long-term viability over the five-to-ten year horizon depends on right-to-repair mandate expansion forcing parts availability and repair documentation access across major consumption corridors. Watch IMEI registry harmonization progress as the critical inflection signal determining cross-border arbitrage risk and buyer trust restoration potential.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Optical Inspection Deployment | Machine-vision platforms at European facilities reduce grading disputes and warranty claim rates below manual technician benchmarks. |
| EU Right-to-Repair Compliance Investment | Mandated parts availability from Samsung and Apple expands addressable supply pools for independent restoration operations. |
| Enterprise Fleet Certification Program | Corporate mobility providers in Germany standardize on warranty-backed refurbished units for field-worker deployments. |
| Cross-Border IMEI Verification Infrastructure | Harmonized stolen-device registries reduce arbitrage migration of blacklisted units to weaker verification jurisdictions. |
| Direct-to-Consumer Marketplace Authentication | Platform-mediated quality verification in India compresses intermediary margin extraction for Grade A inventory flows. |
Research Methodology
Direct dialogue with refurbishment facility operators, enterprise fleet procurement managers, marketplace platform engineers, and regulatory compliance officers grounded qualitative assessment of quality standardization and warranty underwriting practices. Secondary validation drew from FCC equipment authorization filings, EU REACH substance restriction documentation, BIS certification records for Indian imports, and trade data through customs declarations. Bottom-up device flow modeling triangulated against top-down market size estimates from carrier trade-in disclosures and platform transaction volumes.
Bottom-up segmentation analysis modeled condition grade, distribution channel configuration, end-user procurement pattern, and price tier positioning across the projection horizon. Analytical framework derived CAGRs from installed base turnover rates, replacement cycle extension from right-to-repair mandates, and digital infrastructure penetration curves in emerging consumption corridors. Forecast inputs incorporated battery health degradation curves, firmware support lifecycle data from OEM disclosure patterns, and enterprise fleet refresh cycle surveys.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt right-to-repair enforcement delays or IMEI registry fragmentation acceleration. Analysis reflects documented assumptions regarding certification standard harmonization and cross-border logistics cost stability. Regulatory momentum in Brazil, battery cell supply concentration exposure, and biometric component interoperability barriers warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
DVD Remote Controls Market
Consumer Electronics
GCC Soundbar Market
Consumer Electronics
Sports Electronics Market
Consumer Electronics
Middle East and Africa Mobile Phone Accessories Market
Consumer Electronics
Laptop Accessories Market
Consumer Electronics
Ereader Market
Consumer Electronics
Pool Speakers Market
Consumer Electronics
Closed Back Studio Headphone Market
Consumer Electronics
Global White Noise Machines Market
Consumer Electronics
Gaming Mouse Market
Consumer Electronics
Ergonomic Mouse Market
Consumer Electronics
Vibrating Alarm Clock Market
Consumer Electronics
Portable Smart Speaker Market
Consumer Electronics
Notebook Market
Consumer Electronics
Portable Stick Market
Consumer Electronics
Asia-Pacific Gaming Keyboard Market