
 IoT in Consumer Electronics Market | 2026-2036
IoT in Consumer Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
IoT in Consumer Electronics Market Outlook
East Asian semiconductor foundry capacity is consolidating around advanced node production for IoT chipsets. Samsung Electronics Co., Ltd. leverages its captive fabrication to secure component supply for wearable devices. Apple Inc. sustains premium positioning through proprietary silicon and closed-loop ecosystem control. Huawei Technologies Co., Ltd. anchors its domestic market position with integrated baseband-to-cloud architectures despite export restrictions.
IoT in consumer electronics encompasses networked physical devices embedded with sensors, actuators, and connectivity modules operating on protocols such as IEEE 802.11ax (Wi-Fi 6) with sub-1W standby power budgets, enabling real-time data exchange between endpoints and cloud platforms for automated user environments. Wearable Devices and Home Automation Devices command the highest margin pools due to recurring service attach rates and sensor fusion complexity. Smart Speakers face commoditization pressure as LPWAN-enabled distributed audio nodes displace centralized hub architectures in multi-room deployments.
FCC Part 15 rules in the United States govern unlicensed radio emissions for Wi-Fi and Bluetooth consumer endpoints, while the EU AI Act imposes conformity assessments on autonomous decision-making in smart home systems. China's MIIT enforces GB/T national standards for wireless coexistence and cybersecurity labeling of networked consumer products. Stakeholders must monitor divergence between regional certification regimes when architecting single-SKU global product strategies.
Market Dynamics
The EU AI Act and China's GB/T cybersecurity labeling requirements are forcing manufacturers to redesign hardware architectures before single-SKU global strategies become economically viable. This regulatory divergence is compressing product development timelines while fragmenting certification pathways.
Growth Catalysts
- Smart Home Security Adoption:Residential buyers in China are scaling ecosystem-integrated installations. MIIT's GB/T wireless coexistence standards accelerate domestic certification cycles.
- LPWAN Audio Distribution:Distributed audio nodes operating on unlicensed sub-GHz bands are displacing centralized smart speaker hubs in multi-room deployments. IEEE 802.11ax power budgets enable sub-1W standby operation.
- Sensor Fusion Complexity:Wearable devices command recurring service attach rates through biometric algorithm stacks. Advanced node foundry capacity concentrates in East Asian semiconductor corridors.
Market Restraints
- Advanced Node Supply Concentration:Foundry capacity for IoT chipsets clusters in Taiwan and South Korea. Single-source wafer exposure creates vulnerability to geopolitical disruption.
- Regulatory Certification Fragmentation:FCC Part 15 rules diverge from EU AI Act conformity assessments. Parallel testing regimes inflate pre-market compliance costs.
- Wi-Fi 6 Module Cost Structure:RF front-end component prices fluctuate with gallium arsenide substrate availability. Cost volatility compresses margin pools in economy-tier home automation devices.
Strategic Opportunities
- India PLI Scheme Incentives:The country's production-linked incentive scheme for electronics manufacturing attracts assembly migration from coastal China. Component localization mandates create captive supplier development opportunities.
- Matter Protocol Convergence:Thread and Zigbee interoperability standards unify previously siloed smart home ecosystems. Multi-protocol silicon enables single-hardware SKUs across regional variants.
- Energy Harvesting Integration:Photovoltaic and thermoelectric generators eliminate battery replacement cycles in distributed sensors. Residential retrofit markets in Germany and Japan show early adoption velocity.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for sub-1W power budgets requires specialized RF and low-level driver expertise. Recruitment pipelines in Eastern Europe and Vietnam remain underdeveloped.
- Legacy Hub Integration Friction:Proprietary cloud architectures from incumbent smart speaker vendors resist open API standardization. Migration tooling for consumer data portability lacks mature implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT in Consumer Electronics Market |
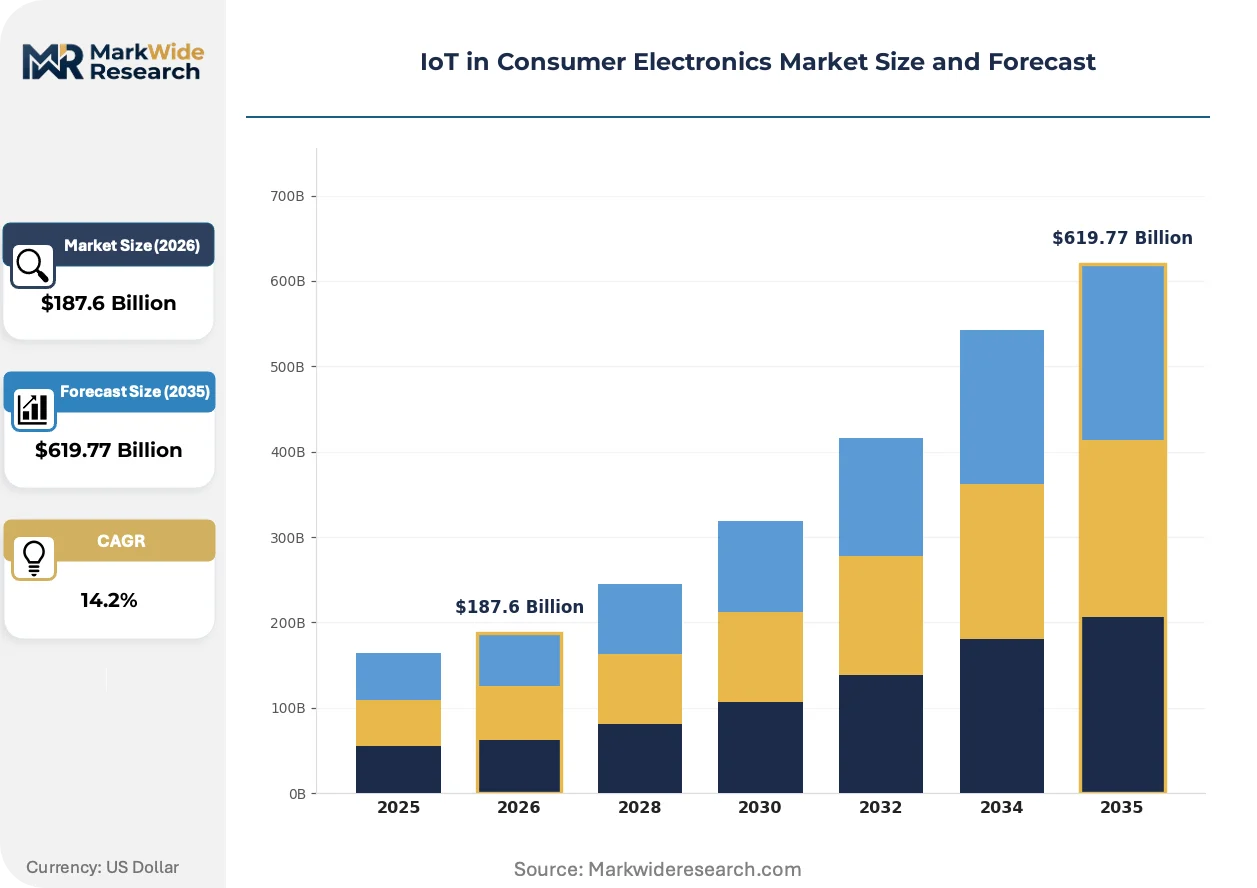
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $619.77 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Speakers, Wearable Devices, Smart TVs, Home Automation Devices Technology: Wi-Fi, Bluetooth, Zigbee, LPWAN Use Case: Home Security, Health Monitoring, Smart Lighting, Energy Management End User: Consumers, Retailers, Enterprises, Service Providers |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Amazon.com, Inc., Google (Alphabet Inc.), Sony Corporation, LG Electronics, Huawei Technologies Co., Ltd., Microsoft Corporation, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT in Consumer Electronics Market Strategic Shifts
Protocol convergence and energy autonomy are restructuring how connected devices communicate and power themselves. These shifts compress hardware refresh cycles while elevating software-defined feature differentiation.
Matter-over-Thread is electrifying residential smart home deployments by unifying previously incompatible device ecosystems under a single application layer. Home automation installers in Germany and the Netherlands are standardizing on multi-protocol silicon to reduce truck-roll complexity. The technology is compressing consumer switching costs between ecosystem brands.
China's MIIT cybersecurity labeling mandate for networked consumer products is forcing hardware redesigns to isolate biometric processing from cloud transmission. Manufacturers must implement edge-based inference engines to achieve GB/T compliance. Smart doorbell and camera segments face the steepest certification timeline extensions.
Subscription unbundling from hardware purchases is fragmenting traditional retail margin structures. Direct-to-consumer channels in the United States and United Kingdom are displacing big-box electronics distribution for premium wearable lines. Fitness and health monitoring verticals show the fastest channel-shift velocity as users prioritize continuous algorithm updates over point-of-sale feature completeness.
IoT in Consumer Electronics Market Segmentation
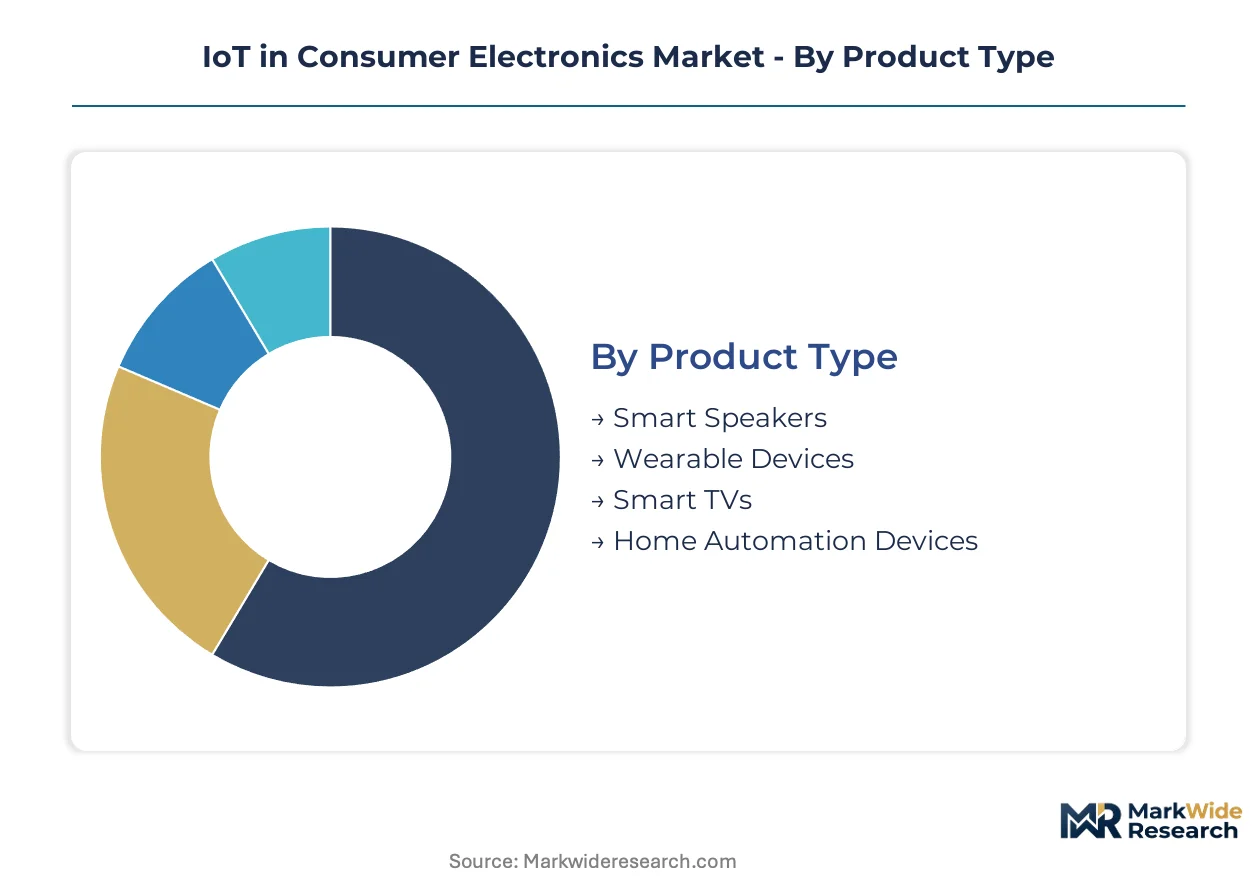
Segmentation in IoT consumer electronics reveals how capital allocation, protocol choices, and end-use requirements fragment manufacturing strategies. Each dimension carries distinct margin profiles and certification burdens that shape vendor positioning.
Product Type:
Capital intensity varies sharply across hardware categories, with semiconductor content and sensor fusion complexity driving upfront investment requirements.
- Wearable Devices:Biometric sensor arrays and edge inference engines demand advanced node foundry access. Demand concentrates in China where domestic manufacturers bundle health algorithm subscriptions with hardware sales.
- Home Automation Devices:Multi-protocol silicon and RF front-end integration raise BOM costs. Installers in Germany and the Netherlands standardize on Thread-compatible modules to reduce truck-roll complexity.
- Smart Speakers:Centralized hub architectures face displacement from distributed audio nodes. LPWAN-enabled endpoints compress margins through commoditized codec licensing.
- Smart TVs:Panel procurement and streaming SoC integration dominate capital structure. Retail channel concentration in the United States and United Kingdom pressures margin capture.
Home Automation Devices absorb the bulk of installed capacity; Wearable Devices are expanding most quickly.
Technology:
Protocol selection determines RF engineering talent requirements and regional certification pathway costs.
- Wi-Fi:IEEE 802.11ax implementations with sub-1W standby budgets require specialized low-level driver expertise. FCC Part 15 and MIIT GB/T testing regimes impose parallel compliance costs.
- LPWAN:Unlicensed sub-GHz bands enable multi-room audio distribution without centralized hubs. Residential deployments in Germany show early adoption velocity for energy-autonomous sensor networks.
- Bluetooth:Legacy audio pairing and beacon applications face protocol convergence pressure. Matter-over-Thread unification threatens standalone silicon demand.
- Zigbee:Mesh networking for lighting controls migrates toward multi-protocol silicon integration. Thread interoperability reduces standalone chipset shipments.
Wi-Fi commands the largest installed base; LPWAN is climbing the fastest as distributed architectures displace hub-centric designs.
Use Case:
Application-level segmentation exposes divergent regulatory exposure and service attach rate potential.
- Home Security:Camera and doorbell systems face EU AI Act conformity assessments for autonomous decision-making. China's MIIT cybersecurity labeling mandates edge-based biometric processing isolation.
- Health Monitoring:Continuous algorithm updates drive subscription unbundling from hardware. Direct-to-consumer channels in the United States and United Kingdom displace big-box distribution.
- Smart Lighting:Matter protocol convergence compresses ecosystem switching costs. Installers prioritize multi-protocol silicon to reduce inventory complexity.
- Energy Management:Photovoltaic and thermoelectric harvesting eliminates battery replacement cycles. Residential retrofit demand in Germany and Japan accelerates sensor deployment.
Home Security carries the heaviest compliance burden; Health Monitoring shows the steepest channel-shift velocity toward recurring revenue models.
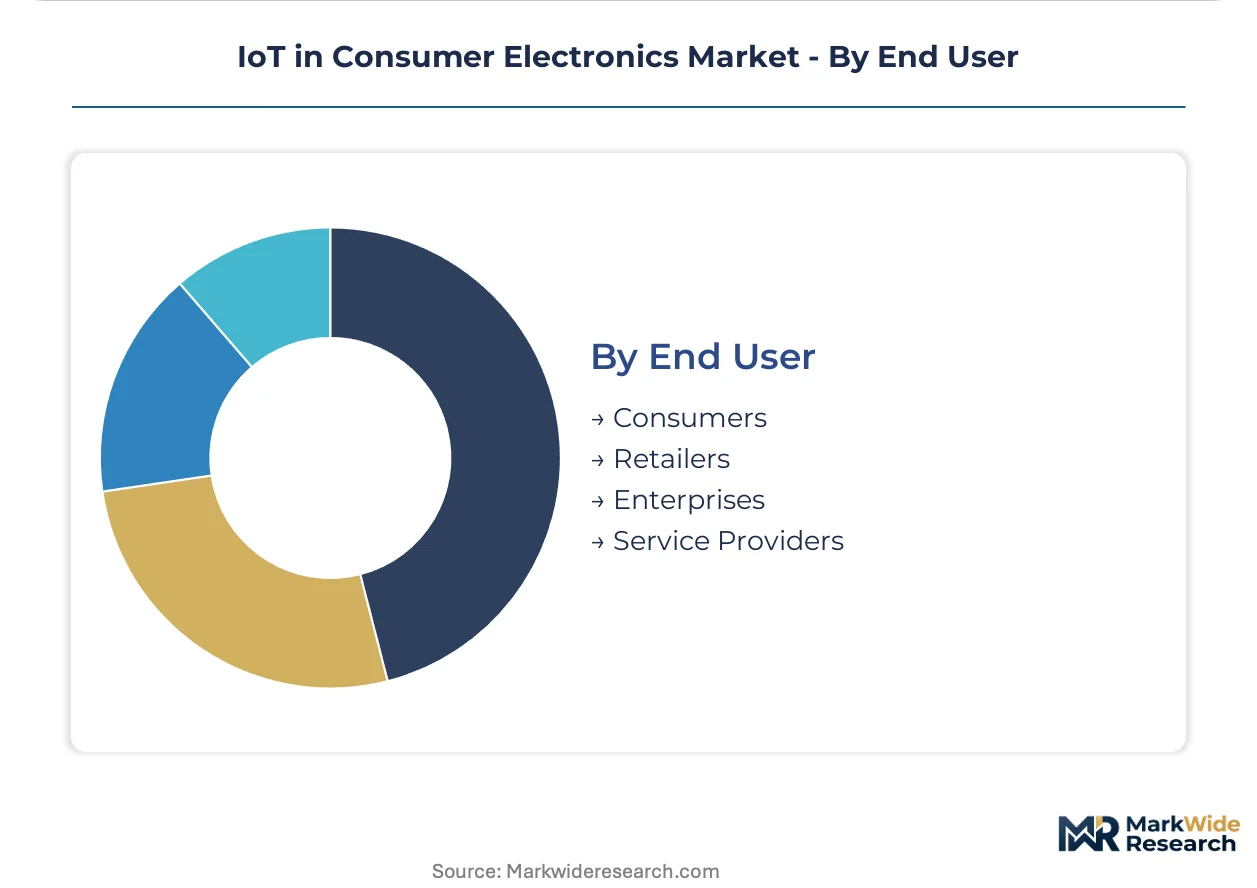
End User:
Customer-type segmentation reveals procurement pattern divergence between volume aggregation and direct relationship economics.
- Consumers:Subscription unbundling prioritizes continuous algorithm updates over point-of-sale feature completeness. Fitness verticals demonstrate fastest channel migration.
- Service Providers:Bundled installation and monitoring contracts capture recurring revenue. Smart home security adoption in China scales through ecosystem-integrated offerings.
- Retailers:Big-box electronics distribution faces margin compression from direct-to-consumer displacement. Premium wearable lines bypass traditional channels.
- Enterprises:Fleet deployment and centralized management tools drive procurement decisions. Workplace wellness programs expand biometric monitoring deployments.
Consumers represent the largest addressable base; Service Providers are gaining share fastest through bundled ecosystem offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium arsenide substrate availability from Australian mining operations constrains RF front-end component pricing across major manufacturing corridors. Semiconductor packaging demand concentrates in East Asian foundry clusters. Regulatory divergence between Washington, Brussels, and Beijing fragments certification pathways for connected device vendors.
United States
Residential smart home security installations scale through service provider bundling. FCC Part 15 rules govern unlicensed radio emissions for Wi-Fi and Bluetooth endpoints. Austin and Seattle tech corridors host firmware engineering talent pools for sub-1W power budget optimization.
China
Domestic manufacturers integrate health algorithm subscriptions with wearable hardware sales. MIIT enforces GB/T national standards for wireless coexistence and cybersecurity labeling. Shenzhen and Dongguan electronics clusters drive ecosystem-integrated smart home security deployment velocity.
Germany
Home automation installers standardize on Thread-compatible modules to reduce truck-roll complexity. EU AI Act conformity assessments apply to autonomous decision-making in camera systems. Munich and Stuttgart industrial regions accelerate photovoltaic sensor network adoption for residential retrofit markets.
South Korea
Captive fabrication secures component supply for advanced node IoT chipsets. National semiconductor strategy prioritizes domestic foundry capacity expansion. Seoul Capital Area and Busan-Ulsan corridors concentrate wearable device OEM manufacturing and RF engineering expertise.
India
Production-linked incentive schemes attract electronics assembly migration from coastal China. Component localization mandates create captive supplier development opportunities. Karnataka and Tamil Nadu manufacturing zones scale multi-protocol silicon integration for export-oriented smart home devices.
IoT in Consumer Electronics Market Competitive Environment
Global majors compete with regional champions across protocol standardization and ecosystem integration dimensions. The vendor base stratifies into three tiers: captive silicon owners, multi-protocol platform licensors, and contract assembly specialists. Strategic archetypes include vertically integrated hardware-stack controllers, cloud-architecture gatekeepers, and foundry-dependent module vendors. M&A activity concentrates on sensor fusion algorithm stacks and energy harvesting IP portfolios.
Within the captive silicon tier, Apple Inc. and Samsung Electronics Co., Ltd. occupy positions defined by proprietary chip design and closed-loop ecosystem control. Huawei Technologies Co., Ltd. anchors the regional champion archetype through integrated baseband-to-cloud architectures. These three entities exemplify divergent responses to regulatory fragmentation: Washington-aligned IP restrictions, Brussels-mandated interoperability standards, and Beijing-directed domestic market prioritization.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Amazon.com, Inc. |
| Google (Alphabet Inc.) |
| Sony Corporation |
| LG Electronics |
| Huawei Technologies Co., Ltd. |
| Microsoft Corporation |
| Intel Corporation |
| Others |
Value Chain & Pricing Dynamics
EU AI Act conformity assessments and China's GB/T cybersecurity labeling mandates are forcing hardware redesigns that fragment certification pathways and compress supplier margins across tiered product portfolios.
Pricing Analysis
Warranty and algorithm-subscription bundling separates premium wearable vendors from economy-tier home automation suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and sensor fusion complexity. Cost compression in economy-tier Wi-Fi 6 modules intensifies because gallium arsenide substrate availability fluctuates with Australian mining output. Service providers show lowest price sensitivity through bundled installation contracts; direct-to-consumer channels face highest switching elasticity.
Supply Chain Analysis
India's PLI scheme localization mandates and China's component-sourcing rules are reshaping sourcing patterns for multi-protocol silicon and RF front-end assemblies. Advanced node foundry capacity clusters in Taiwan and South Korea; assembly migration accelerates toward Karnataka and Tamil Nadu corridors. Gallium arsenide substrates, MEMS sensors, and multi-protocol chipsets anchor BOM structures. Single-source wafer exposure in Taiwan Strait corridors creates geopolitical vulnerability. Distribution runs through Shenzhen and Dongguan electronics clusters for ecosystem-integrated offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT consumer electronics market reads as a cost-of-compliance story where EU AI Act conformity assessments erect barrier-to-entry moats favoring incumbents with captive certification resources.
For Market Incumbents: To counter LPWAN-enabled distributed audio nodes displacing centralized smart speaker hubs, deepen backward integration into multi-protocol silicon design and expand edge-inference engine capacity in South Korea captive foundries. Secure MIIT GB/T pre-certification for biometric isolation architectures ahead of hardware refresh cycles.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription channels targeting health monitoring verticals in the United States and United Kingdom where algorithm-update loyalty exceeds point-of-sale feature sensitivity. Exploit installer frustration with proprietary cloud lock-in by offering Matter-over-Thread migration tooling for residential retrofit markets in Germany.
For Investors and Strategic Acquirers: The window for entry favors sensor fusion algorithm stacks and energy harvesting IP portfolios with near-term regulatory clearance pathways. Long-term viability hinges on edge-AI architectures decoupled from cloud dependency. Watch MIIT cybersecurity labeling timeline extensions as inflection signal for compliance-capable hardware vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Inference Engine Development | Isolates biometric processing from cloud transmission to achieve GB/T compliance for doorbell and camera segments. |
| Matter Protocol Certification | Enables single-hardware SKUs across EU, US, and Chinese regional variants through Thread interoperability. |
| Energy Harvesting Integration | Eliminates battery replacement cycles in photovoltaic sensor networks for German and Japanese residential retrofits. |
| Captive Foundry Capacity Expansion | Secures advanced node wafer supply for wearable biometric arrays amid Taiwan Strait concentration risk. |
| Direct-to-Consumer Channel Buildout | Captures subscription attach rates in fitness verticals displacing big-box electronics distribution. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with connected device OEM procurement managers, smart home installation contractors, semiconductor foundry planning officers, and MIIT certification consultants combined with FCC Part 15 docket reviews and EU AI Act implementation guidance. SEC 10-K disclosures from captive silicon owners and hyperscaler IoT capex statements provided demand-side validation. Bottom-up SKU-level buildups and top-down category spend estimates triangulated market sizing.
Granularity-level modeling disaggregated volume and value across product type, protocol technology, use case application, and end-user archetype dimensions throughout the forecast period. CAGRs derived from segment-specific adoption curves weighted by regulatory implementation timelines and foundry capacity expansion schedules. LPWAN infrastructure deployment velocity and Matter protocol certification throughput served as IoT-specific demand inputs.
The model assumes a particular technology adoption path; alternative pathways for energy harvesting integration would alter the outlook if photovoltaic efficiency breakthroughs accelerate cost parity. Forecasts reflect assumptions around regulatory divergence persistence and semiconductor supply concentration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
United States Smart TV Market
Consumer Electronics
Russia Gaming Gadgets Market
Consumer Electronics
Mannequin Head Market
Consumer Electronics
Smartphone Screen Protector Market
Consumer Electronics
Gaming Computer Market
Consumer Electronics
Wet Wipes Market
Consumer Electronics
Global Bluetooth Mono Earpieces Market
Consumer Electronics
Ultra HD Action Camera Market
Consumer Electronics
PC Accessories Market
Consumer Electronics
Stress Ball Market
Consumer Electronics
Tablet Market
Consumer Electronics
Gaming Keyboard Market
Consumer Electronics
Asia-Pacific Professional Audio-Visual Systems Market
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
Digital Accessories Market
Consumer Electronics
Dual Screen Laptops Market