
 Fruit and Vegetable Processing Equipment Market | 2026-2036
Fruit and Vegetable Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit and Vegetable Processing Equipment Market Foresight
Aftermarket service revenue is narrowing as original equipment manufacturers shift toward bundled lifecycle contracts. GEA Group AG leverages its global service footprint to capture recurring maintenance streams from installed sorting and washing lines. Alfa Laval AB sustains competitive position through stainless steel heat exchanger specialization in blanching applications. JBT Corporation anchors North American juice extraction with high-capacity citrus processing systems.
Fruit and vegetable processing equipment encompasses mechanical and thermal systems engineered to clean, sort, cut, blanch, and package raw produce at throughputs exceeding 20 metric tons per hour, with wash water recirculation rates and temperature profiles calibrated to microbial reduction standards. The equipment serves industrial food manufacturers seeking to extend shelf life while preserving nutritional and sensory properties. Sorting machines and washing equipment represent the largest equipment type segments, with optical sorters commanding premium positioning due to AI-driven defect detection capabilities. Frozen produce manufacturing and juice extraction lead application demand, though ready-to-eat meal processors are expanding cutting and packaging unit purchases fastest as retail deli sections broaden fresh offerings.
The FDA's Food Safety Modernization Act and USDA's Hazard Analysis Critical Control Point framework mandate validated kill steps and sanitary design, forcing equipment upgrades across U.S. canning and frozen food facilities. EU REACH chemical safety standards and CE machinery directives constrain material selection and electrical design for European export-bound suppliers. Stakeholders must monitor evolving pathogen detection thresholds and water reuse regulations, as compliance timelines will dictate capital deployment priorities more sharply than throughput economics alone.
Market Dynamics
The FDA's updated Food Safety Modernization Act requirements for preventive controls are accelerating capital deployment across U.S. processing facilities, forcing equipment upgrades faster than natural replacement cycles would dictate.
Growth Catalysts
- Regulatory compliance mandates:The FDA's FSMA preventive controls rules require validated kill steps and sanitary design, compelling U.S. canning and frozen food facilities to replace legacy washing and blanching systems.
- Fresh-cut convenience demand:North American retail chains are expanding deli sections with ready-to-eat produce, driving automated washing and peeling line purchases from processors in California's Central Valley.
- Optical sorting AI advancement:Machine vision systems with defect detection capabilities now command premium positioning as tomato and leafy green processors modernize legacy operations.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 stainless steel price swings compress margins for heat exchanger and vessel manufacturers serving blanching applications.
- European export compliance friction:EU REACH chemical safety standards and CE machinery directives constrain material selection and electrical design, adding certification costs for suppliers targeting European markets.
- Water treatment technical ceiling:Wash water recirculation rates face microbial reduction thresholds that current membrane and UV systems struggle to meet cost-effectively at 20+ metric ton per hour throughputs.
Strategic Opportunities
- India food processing modernization:FSSAI enforcement of food safety standards and PLI scheme incentives for food processing equipment create entry points for sorting and packaging system suppliers.
- Juice extraction byproduct valorization:Citrus and pomace waste stream processing into pectin and dietary fiber supplements opens secondary revenue lines for extraction equipment operators.
- Modular equipment architectures:Skid-mounted washing and cutting units allow mid-scale processors to scale capacity incrementally without full line shutdowns during expansion.
Industry Challenges
- Sanitary welding certification scarcity:Qualified orbital welders for stainless steel dairy-grade joints command premium wages, constraining OEM capacity expansion and service response times.
- Legacy control system integration:New optical sorters and automated packaging lines must interface with 1990s-era SCADA architectures common in established canning facilities, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit and Vegetable Processing Equipment Market |
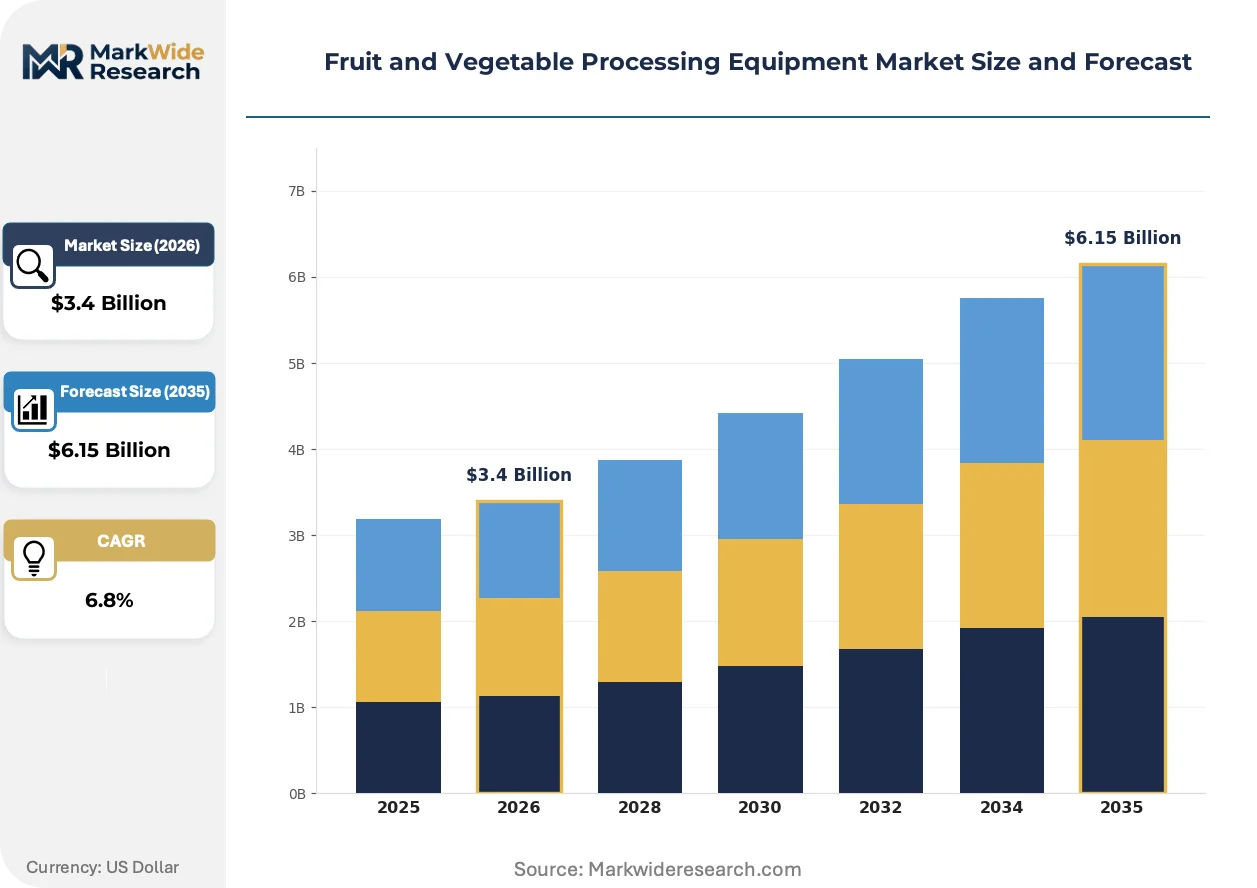
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Sorting Machines, Washing Equipment, Peeling Machines, Cutting Devices, Blanchers, Packaging Units Technology: Optical Sorters, Vacuum Systems, Steam Blanching, Cold Water Washing, Automatic Feeders, Conveyor Belts Application: Frozen Produce Manufacturing, Juice Extraction, Canning Processes, Dehydrated Snacks, Puree Production, Ready-to-Eat Meals End User: Food Processing Plants, Beverage Manufacturers, Canning Facilities, Frozen Food Companies, Juice Factories, Catering Services |
| Companies Covered | GEA Group AG, Alfa Laval AB, Bühler AG, JBT Corporation, Krones AG, Marel, Heat and Control Inc., Syntegon Technology GmbH, Tomra Systems ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit and Vegetable Processing Equipment Market Shifts & Advancements
Equipment architecture is pivoting from standalone machines toward integrated lines with closed-loop water and energy recovery, reshaping how processors evaluate total cost of ownership.
Hyperspectral imaging systems paired with pneumatic ejection mechanisms now detect subsurface bruising and internal defects in stone fruit and potatoes. Large fresh-cut salad processors in the United States are adopting these units at replacement cycles compressed from seven years to four. Conventional color-camera sorters are rendering obsolete for high-value produce categories where defect tolerance approaches zero.
The EU's CSRD sustainability reporting requirements now mandate supply chain emissions disclosure for food manufacturers above defined revenue thresholds. European processors must document energy and water intensity per unit output, driving demand for heat recovery heat exchangers and vacuum cooling systems with verified efficiency metrics. Frozen vegetable manufacturers in Germany and the Netherlands are retrofitting existing blanching lines with integrated energy monitoring to meet 2025 disclosure deadlines.
Service contract unbundling is fragmenting how processors procure maintenance. OEMs now face competition from independent service providers offering remote diagnostics and predictive parts replacement for washing and sorting lines. This shift is most visible among mid-scale tomato and pepper processors in California, where third-party technicians with proprietary AI-driven vibration analysis tools are capturing recurring revenue streams previously held by original equipment manufacturers.
Fruit and Vegetable Processing Equipment Market Segmentation
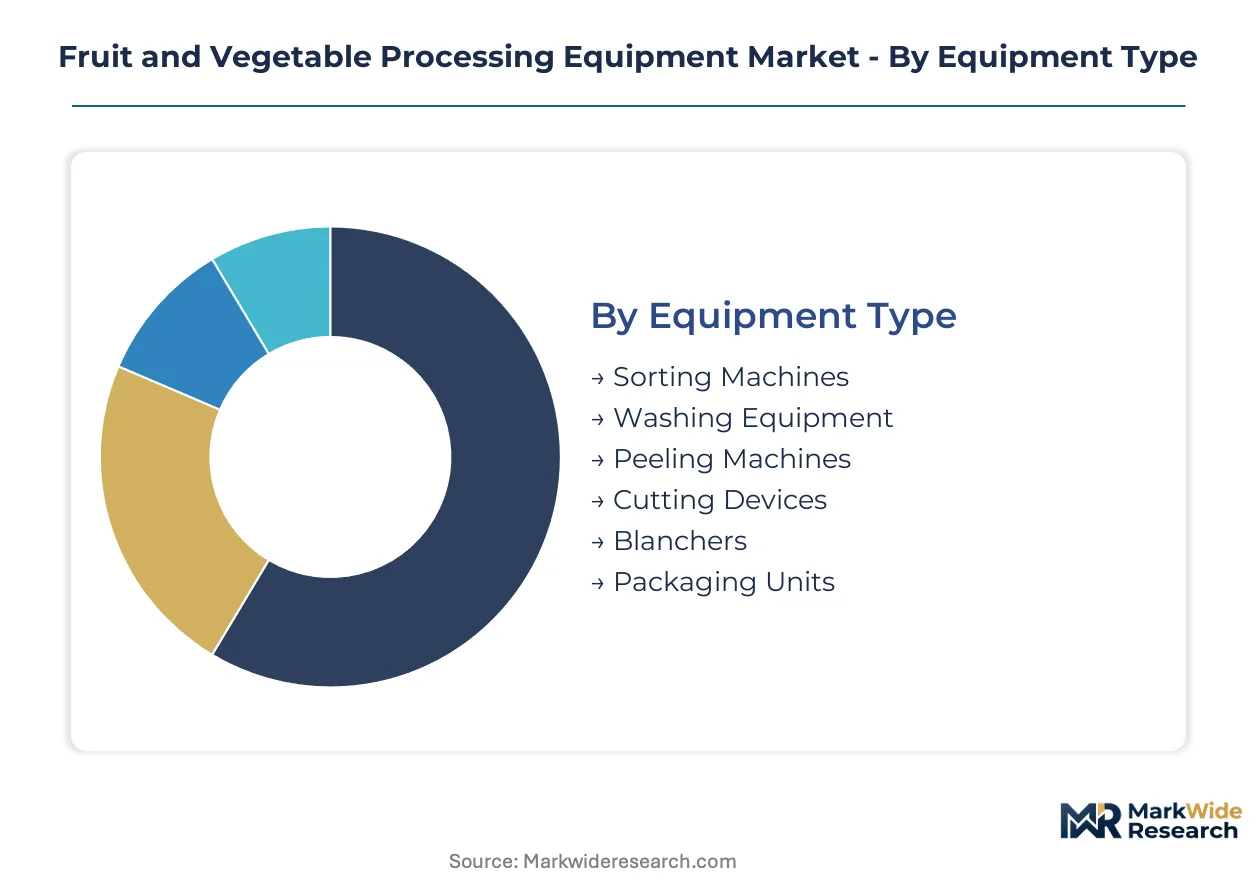
Equipment segmentation in fruit and vegetable processing reveals distinct replacement rhythms and capital allocation priorities. Cycle times vary dramatically—from four-year refresh rates for AI-enabled optical sorters to decade-long depreciation schedules for steam blanching vessels. Understanding these temporal patterns helps suppliers align service contracts and inventory planning with actual procurement behavior.
Equipment Type:
Replacement cycles diverge sharply across equipment categories, with AI-driven systems turning over fastest and thermal vessels slowest.
- Sorting Machines:Hyperspectral imaging units with pneumatic ejection mechanisms now detect subsurface defects in stone fruit and potatoes. California's Central Valley tomato processors are compressing replacement cycles from seven years to four as defect tolerance approaches zero.
- Washing Equipment:Closed-loop wash water systems with recirculation rates calibrated to FDA microbial reduction standards dominate new line installations. Fresh-cut salad processors in North America are expanding automated washing lines to meet retail demand for convenience produce.
- Peeling Machines:Vacuum-based and abrasive peeling systems serve root vegetable and citrus processors with throughput demands exceeding 20 metric tons per hour.
- Cutting Devices:Automated slicing and dicing units are gaining share fastest among ready-to-eat meal processors broadening fresh deli offerings.
- Blanchers:Stainless steel heat exchanger systems for thermal processing face extended depreciation schedules due to capital intensity and sanitary welding certification requirements.
- Packaging Units:Vacuum-based packaging systems with modified atmosphere capabilities serve frozen vegetable and puree manufacturers modernizing legacy operations.
Sorting machines dominate installed base. Washing equipment is where expansion concentrates.
Technology:
Technology selection tracks the tension between precision demands and water-energy recovery imperatives reshaping total cost of ownership calculations.
- Optical Sorters:Machine vision systems with AI-driven defect detection capabilities command premium positioning. Large fresh-cut salad processors in the United States are rendering conventional color-camera sorters obsolete for high-value produce categories.
- Vacuum Systems:Vacuum cooling and packaging technologies reduce thermal damage while extending shelf life for leafy greens and delicate fruits.
- Steam Blanching:Thermal processing systems with integrated energy monitoring help European frozen vegetable manufacturers meet CSRD sustainability disclosure requirements.
- Cold Water Washing:Low-temperature wash systems with membrane and UV treatment face technical ceilings at high throughputs.
- Automatic Feeders:Precision metering equipment ensures consistent product flow to downstream cutting and sorting operations.
- Conveyor Belts:Sanitary design conveying systems with clean-in-place capabilities serve as backbone infrastructure across processing lines.
Optical sorters command the steepest price premiums. Vacuum systems are climbing fastest as energy recovery priorities intensify.
Application:
Application demand clusters around shelf-life extension requirements and retail format evolution driving capital deployment.
- Frozen Produce Manufacturing:Blanching and freezing lines with validated kill steps serve industrial-scale vegetable processors. Germany and Netherlands manufacturers are retrofitting existing lines with integrated energy monitoring.
- Juice Extraction:High-capacity citrus processing systems anchor North American demand, with byproduct valorization into pectin and dietary fiber opening secondary revenue streams.
- Canning Processes:Legacy thermal processing facilities face accelerated upgrade timelines under FDA preventive controls mandates.
- Dehydrated Snacks:Low-moisture fruit and vegetable processing equipment serves snack manufacturers expanding healthy convenience offerings.
- Puree Production:Homogenization and thermal processing systems for infant food and ingredient applications.
- Ready-to-Eat Meals:Automated cutting and packaging unit purchases are expanding fastest as retail deli sections broaden fresh produce offerings.
Frozen produce manufacturing holds the largest equipment installed base. Ready-to-eat meals are gaining share fastest as retail formats evolve.
End User:
End-user procurement patterns reflect divergent scale economies and regulatory exposure across the processing value chain.
- Food Processing Plants:Integrated operations with multi-product capabilities drive demand for modular, skid-mounted washing and cutting units enabling incremental capacity scaling.
- Beverage Manufacturers:Juice and smoothie processors require extraction and pasteurization systems with validated pathogen control.
- Canning Facilities:Established operations with 1990s-era SCADA architectures face legacy control system integration challenges when upgrading to optical sorters and automated packaging lines.
- Frozen Food Companies:Large-scale operators with energy intensity disclosure obligations under EU CSRD are prioritizing heat recovery heat exchangers.
- Juice Factories:Citrus and pomace waste stream processing capabilities are creating differentiation in extraction equipment specifications.
- Catering Services:Mid-scale prepared food operations with variable batch requirements drive demand for flexible, quick-changeover equipment configurations.
Food processing plants anchor equipment demand volume. Frozen food companies are where specification intensity is concentrating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. U.S. buyers prioritize regulatory compliance over capital cost, while Indian processors weigh equipment financing against PLI scheme incentives. European purchasers face sustainability disclosure mandates that reshape total cost calculations.
United States
Fresh-cut salad processors in California's Central Valley are expanding automated washing and peeling lines to capture retail convenience demand. The FDA's updated Food Safety Modernization Act preventive controls rules compel faster equipment replacement than natural cycles would allow. Tomato and leafy green processors in the Central Valley are modernizing legacy canning operations with optical sorting and vacuum-based packaging systems.
Germany
Frozen vegetable manufacturers are retrofitting blanching lines with integrated energy monitoring to meet CSRD sustainability disclosure deadlines. The EU's Corporate Sustainability Reporting Directive mandates supply chain emissions documentation for food manufacturers above defined revenue thresholds. Processors in Lower Saxony and Bavaria are prioritizing heat recovery heat exchangers and vacuum cooling systems with verified efficiency metrics.
India
FSSAI enforcement of food safety standards and PLI scheme incentives for food processing equipment create entry points for sorting and packaging system suppliers. The Production Linked Incentive scheme subsidizes capital equipment purchases for food processing modernization. Maharashtra and Gujarat food processing clusters are attracting equipment vendors targeting mid-scale processors seeking modular capacity expansion.
China
Domestic fruit and vegetable processors are upgrading washing and thermal treatment systems to meet dual carbon goals and GB food safety standards. The Ministry of Ecology and Environment enforces wastewater discharge limits that accelerate closed-loop water system adoption. Shandong Peninsula and Yangtze River Delta processing hubs are retrofitting legacy lines with membrane and UV treatment technologies.
Brazil
Citrus and tropical fruit processors are expanding juice extraction capacity to serve export markets and domestic beverage demand. ANVISA sanitary regulations for fruit juice production mandate validated pathogen control steps and sanitary equipment design. São Paulo state processors are modernizing extraction lines while exploring pomace waste valorization into pectin and dietary fiber supplements.
Fruit and Vegetable Processing Equipment Market Competitive Landscape
Specialized thermal equipment fabricators and integrated line suppliers split the market along capital intensity lines. The vendor base clusters around stainless steel vessel manufacturing expertise and control system integration capabilities. Three archetypes dominate: European engineering conglomerates with full-line portfolios, Nordic precision specialists in optical sorting, and mid-scale regional fabricators serving price-sensitive emerging markets. Competitive positioning hinges on service contract bundling and lifecycle cost optimization rather than equipment pricing alone.
Among European engineering conglomerates, GEA Group AG and Alfa Laval AB occupy positions reflecting distinct specialization vectors. GEA exemplifies the full-line service-integrated archetype, while Alfa Laval represents thermal equipment precision engineering. JBT Corporation anchors North American market presence as a regional scale specialist. These three sit within a competitive structure where aftermarket revenue streams and regulatory compliance capabilities determine contract outcomes more than initial equipment specifications.
| Leading Market Players |
|---|
| GEA Group AG |
| Alfa Laval AB |
| Bühler AG |
| JBT Corporation |
| Krones AG |
| Marel |
| Heat and Control Inc. |
| Syntegon Technology GmbH |
| Tomra Systems ASA |
| Others |
Supply & Pricing Matrix
Trans-Pacific container freight corridors linking East Asian stainless steel mills to California's Central Valley processing hubs transmit cost volatility directly into equipment pricing power, concentrating margin pressure on heat exchanger fabricators while enabling premium capture by optical sorter vendors with captive service networks.
Pricing Analysis
Lifecycle service contracts now drive lifetime value more than initial equipment sales, with OEMs bundling predictive maintenance and spare parts subscription into multi-year agreements. Three-tier pricing structure across premium AI-enabled sorters, standard mechanical washers, and economy-grade conveyors reflects certification tier and throughput scale differentiation. Cost compression in mid-range blanching equipment is intensifying because Grade 304 stainless steel price swings compress fabricator margins. Small-scale canning facilities in Brazil exhibit highest price sensitivity, while multinational frozen food companies in Germany prioritize compliance capabilities over capital cost.
Supply Chain Analysis
Supplier-financing facilities with 180-day extended payment terms have become standard for Indian and Brazilian processor purchases, easing capital constraints for mid-scale operators. Stainless steel feedstock concentrates in China, Indonesia, and South Korea; precision optical components draw from German and Japanese sensor manufacturers. Single-source vulnerability runs through AI vision chip suppliers serving defect detection systems. Distribution runs through regional equipment distributors with certified installation capabilities, particularly for sanitary welding-intensive thermal systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent equipment suppliers face substitution pressure from modular skid-mounted architectures that displace full-line capital commitments, forcing defensive repositioning around integrated lifecycle service platforms.
For Market Incumbents: Pre-empt modular competitor encroachment by acquiring regional service networks in California's Central Valley and India's Maharashtra cluster. Lock in tomato and leafy green processors with bundled optical sorter upgrades and validated FSMA compliance documentation. Backward integration into stainless steel vessel fabrication secures margin control against raw material volatility.
For New Entrants and Emerging Players: Establish a beachhead in India's mid-scale food processing segment where PLI scheme subsidies reduce customer acquisition friction. Target modular washing and cutting skid sales to Maharashtra and Gujarat processors seeking incremental capacity without line shutdowns. Lead with remote diagnostics capabilities that match OEM service response times at lower contract pricing.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized food processing equipment divisions lacking AI-enabled sorting capabilities. Long-term viability hinges on regulatory compliance automation and water-energy recovery integration rather than throughput scale alone. Monitor FSSAI enforcement intensity in India and CSRD disclosure deadlines in Germany as capital deployment inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Lifecycle Service Contract Bundling | Captures recurring revenue streams from installed optical sorting and washing lines at California tomato processors. |
| AI-Enabled Defect Detection Integration | Hyperspectral imaging upgrades command premium positioning as fresh-cut salad processors compress replacement cycles. |
| Modular Skid-Mounted Architecture Development | Enables mid-scale Indian processors to scale capacity incrementally without full line shutdowns during expansion. |
| Sanitary Welding Certification Investment | Addresses qualified orbital welder scarcity constraining OEM capacity expansion and service response times. |
| Byproduct Valorization Capability Addition | Opens secondary revenue lines from citrus pomace processing into pectin and dietary fiber supplements. |
Research Methodology
Operator-level perspectives from plant engineers at California Central Valley processors, maintenance directors at German frozen vegetable manufacturers, procurement leads at Indian food processing clusters, and aftermarket service heads at European OEMs anchored the qualitative base. These interviews combined with secondary validation from FDA FSMA guidance documents, EU CSRD regulatory texts, FSSAI enforcement circulars, and SEC filings of listed equipment suppliers. Bottom-up equipment unit economics and top-down market sizing triangulated across the analysis window.
Scenario-bracketing around regulatory compliance timelines, stainless steel price volatility bands, and water reuse technology adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include equipment type, technology tier, application process, and end-user scale category. CAGRs derived from installed base replacement cycle compression rates and greenfield capacity addition patterns in emerging processing clusters. Industry-specific inputs encompassed orbital welder labor availability and optical sensor cost decline trajectories.
Stress conditions across Grade 304/316 stainless steel price spikes, FDA enforcement intensity variations, and membrane-UV treatment technical ceiling breakthroughs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables Processing Equipment
Global Fruit and Vegetable Processing Market
Fruits and Vegetables Processing Equipment
Grape Crusher Market
Fruits and Vegetables Processing Equipment
Global Fruit Processing Equipment Market
Fruits and Vegetables Processing Equipment
Juice Extractors Market
Fruits and Vegetables Processing Equipment
Fruit Tree Shaker Market
Fruits and Vegetables Processing Equipment
Juicer Market
Fruits and Vegetables Processing Equipment
Tomato Processing Market
Fruits and Vegetables Processing Equipment
Juice Extraction Equipment Market
Fruits and Vegetables Processing Equipment
Smart Juicer Market
Fruits and Vegetables Processing Equipment
Smart Juicer Machine Market
Fruits and Vegetables Processing Equipment
North America Avocado Processing Market
Fruits and Vegetables Processing Equipment
Portable Juicer Market
Fruits and Vegetables Processing Equipment
Avocado Processing Market