
 Fruit Tree Shaker Market | 2026-2036
Fruit Tree Shaker Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Tree Shaker Market Insights
High-strength aluminum alloys is repositioning chassis and boom construction across the fruit tree shaker category, trimming unit weight without sacrificing structural tolerance for dense orchard canopies. John Deere leverages its precision agriculture ecosystem to bundle shaker hardware with telemetry and fleet management software. AGCO Corporation sustains a broad dealer network across European fruit-growing belts, ensuring aftermarket parts availability during compressed harvest windows. Orchard Machinery Corporation specializes in trunk-shake configurations for nut crops, dominating the California almond corridor.
A fruit tree shaker is a mechanized harvesting implement that transmits controlled vibrational energy through a tree trunk or limb to dislodge mature fruit, typically operating at frequencies between 10 and 25 Hz and clamp forces calibrated to avoid bark damage or structural injury. The equipment serves commercial orchards where manual picking costs and labor availability constraints make mechanical intervention economically necessary. Pneumatic shakers lead installed base volumes due to their power-to-weight efficiency in mature olive and citrus operations, though electric shakers are gaining traction where grid-connected charging infrastructure supports emission-targeting farm protocols. Among end users, agricultural contractors represent the fastest-expanding category as orchard owners outsource capital-intensive harvesting to specialized service fleets that amortize equipment across multiple growing seasons.
EU machinery safety standards and CE marking requirements govern shaker design, operator protection, and electromagnetic compatibility for equipment sold across member states, while EPA and OSHA frameworks in the United States set noise exposure limits and operator-safety guard specifications that influence domestic product configurations. California's Air Resources Board imposes additional emission thresholds on combustion-driven units that push manufacturers toward electrified powertrains in that state. Stakeholders must monitor regulatory divergence between jurisdictions and assess whether platform standardization or regional product variants offer the more defensible manufacturing strategy.
Market Dynamics
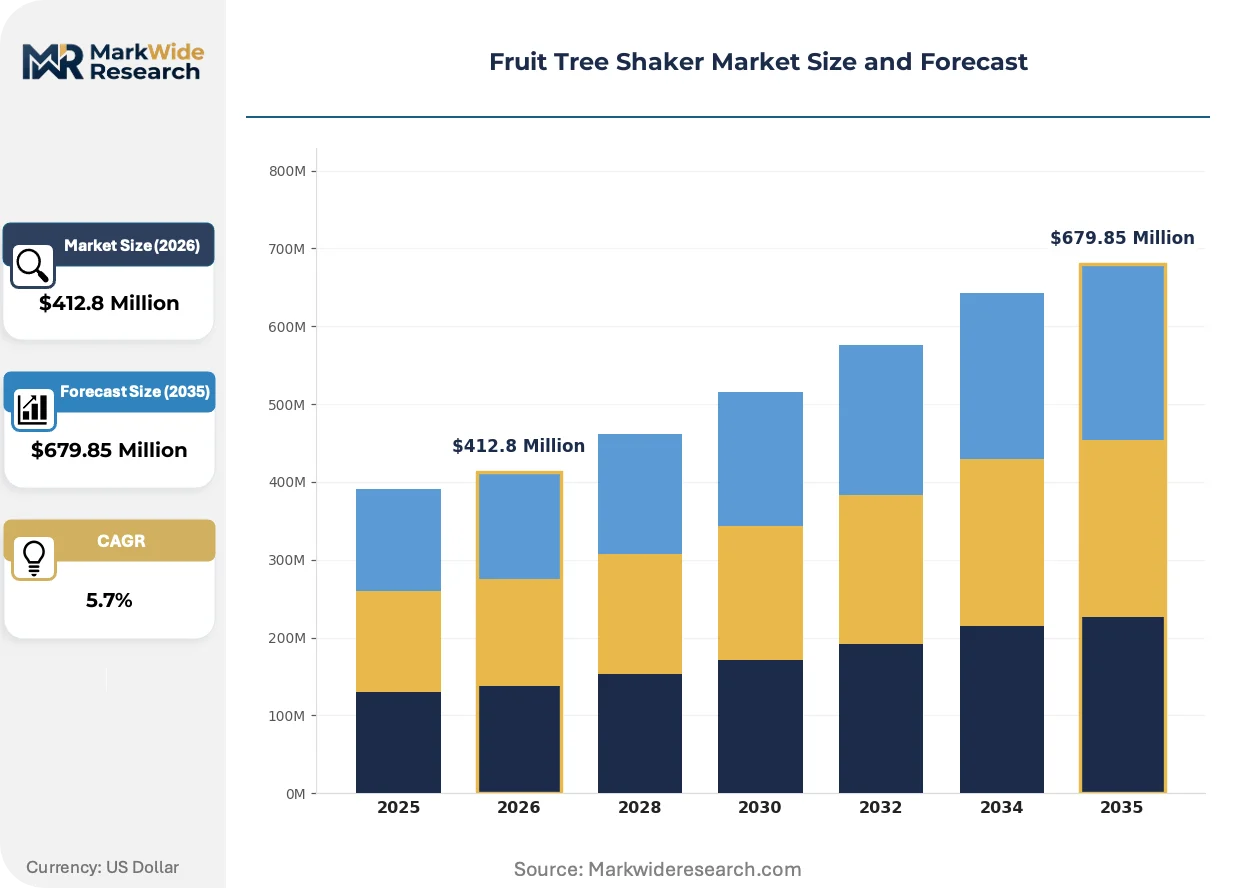
The fruit tree shaker market is experiencing structural pressure from Mediterranean orchard owners accelerating fleet mechanization to counter seasonal labor scarcity, while EU machinery safety directives force redesign cycles that compress product lifecycles and elevate compliance costs for manufacturers serving member states.
Growth Catalysts
- EU Machinery Safety Directives:CE marking requirements for electromagnetic compatibility and operator protection are filtering out low-cost competitors, consolidating demand around certified suppliers with documented conformity assessment procedures.
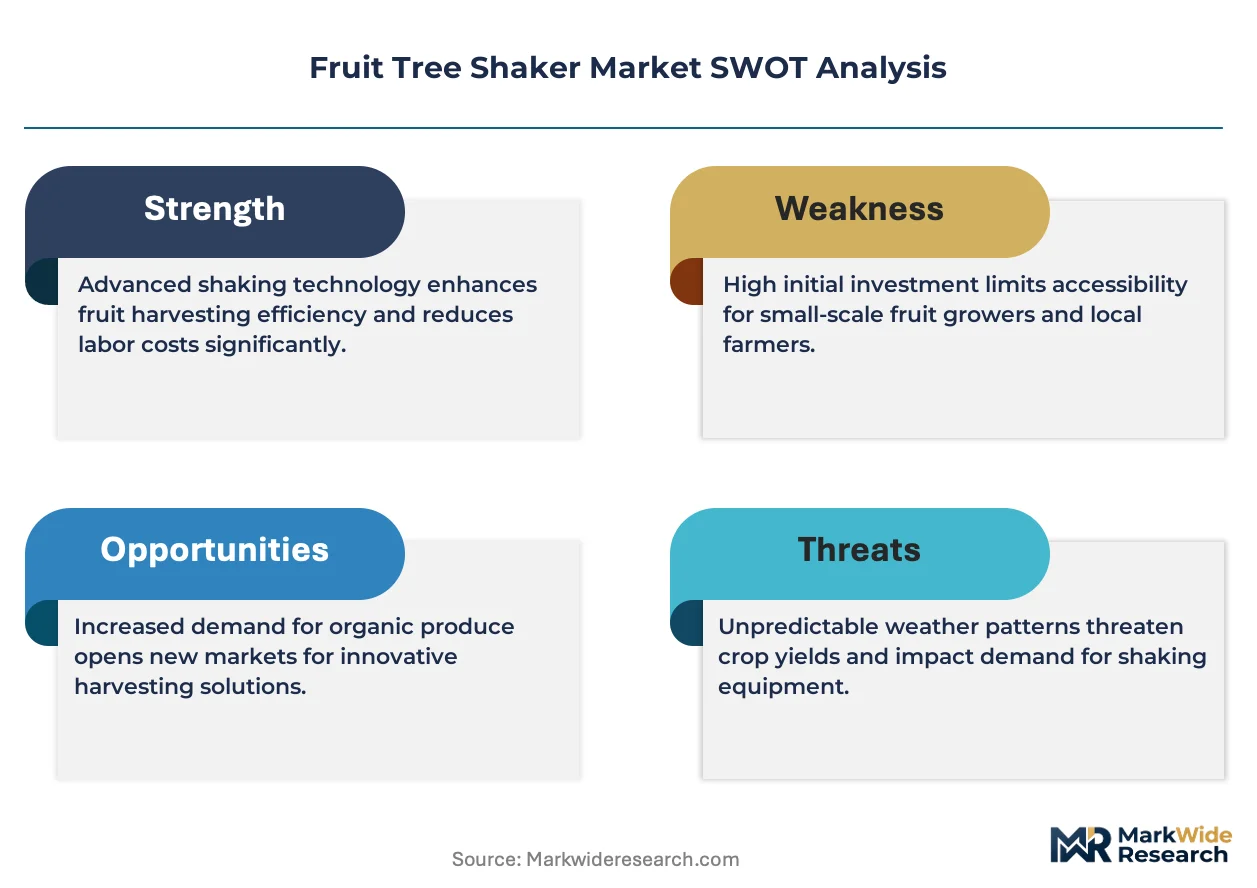
- High-strength aluminum alloys:Chassis and boom construction utilizing advanced metallurgy trims unit weight by substantial margins without sacrificing structural tolerance, enabling denser orchard penetration and reducing soil compaction.
- Agricultural contractor fleets:Specialized harvesting service providers amortize capital-intensive shaker investments across multiple growing seasons and orchard clients, expanding addressable equipment demand beyond owner-operators.
Market Restraints
- Input cost volatility:Aluminum and hydraulic component prices fluctuate with energy market swings, compressing manufacturer margins and complicating long-term contract pricing with orchard capital planners.
- Technical limitation:Trunk-shake configurations struggle with irregular canopy architectures and multi-stem cultivars, restricting applicability in heritage olive groves and certain almond varietals.
- Regulatory friction:California Air Resources Board emission thresholds on combustion-driven units force parallel powertrain development, fragmenting engineering resources and delaying platform standardization.
Strategic Opportunities
- Grid-connected charging infrastructure:Electric shaker architectures gain traction in Spanish and Italian cooperative networks where emission-targeting farm protocols align with available electrical distribution, creating first-mover positioning for electrified product lines.
- Telemetry convergence:Precision agriculture data layers from soil moisture sensors and weather stations are integrating with shaker operation parameters, enabling predictive harvest timing and equipment dispatch optimization.
- Aftermarket parts unbundling:Compressed harvest windows in Greece and Portugal generate demand for rapid component replacement services, opening channel innovation through regional parts depots and mobile technician networks.
Industry Challenges
- Vibration engineering specialization:Calibrating clamp forces and frequency ranges to avoid bark damage requires scarce mechanical engineering talent with orchard biomechanics expertise, constraining manufacturer R&D throughput.
- OSHA noise exposure compliance:Operator-safety guard specifications and hearing conservation programs add certification complexity and training overhead for contractor fleets managing seasonal workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Tree Shaker Market |
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $679.85 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic Shakers, Electric Shakers, Hydraulic Shakers, Manual Shakers End User: Orchard Owners, Agricultural Contractors, Fruit Processors, Retailers Application: Fruit Harvesting, Pollination Aid, Pruning, Orchard Maintenance Technology: Vibration Technology, Mechanical Technology, Lifting Technology, Automation Systems |
| Companies Covered | John Deere, AGCO Corporation, Fendt, Orchard Machinery Corporation, Lopez Garrido, SICMA, AMB Rousset, Greefa, Hansen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Tree Shaker Market Trends and Innovations
Electrification trajectories and precision agriculture integration are restructuring competitive requirements, forcing manufacturers to embed connectivity and emission compliance into core platform architectures rather than treating them as peripheral features.
Variable-frequency electric drive systems are replacing fixed-output pneumatic architectures in new equipment deployments. Spanish and Italian cooperative purchasing consortia specify these configurations for grid-connected orchard blocks. The technology is converging with telematics platforms to enable remote diagnostics and fleet-wide harvest coordination.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant management protocols in ancillary cooling systems for operator cabins and hydraulic circuits. Equipment suppliers must document alternative cooling architectures or face market exclusion in member states. Mediterranean contractor fleets prioritize compliant configurations to maintain cross-border operational flexibility.
Harvest service contracting is displacing direct equipment ownership among mid-scale orchard operators. Greek and Portuguese nut growers increasingly outsource capital-intensive shaking operations to specialized regional fleets. This model concentrates purchasing authority with fewer, larger buyers who negotiate multi-year equipment supply agreements and demand performance guarantees.
Fruit Tree Shaker Market Segmentation
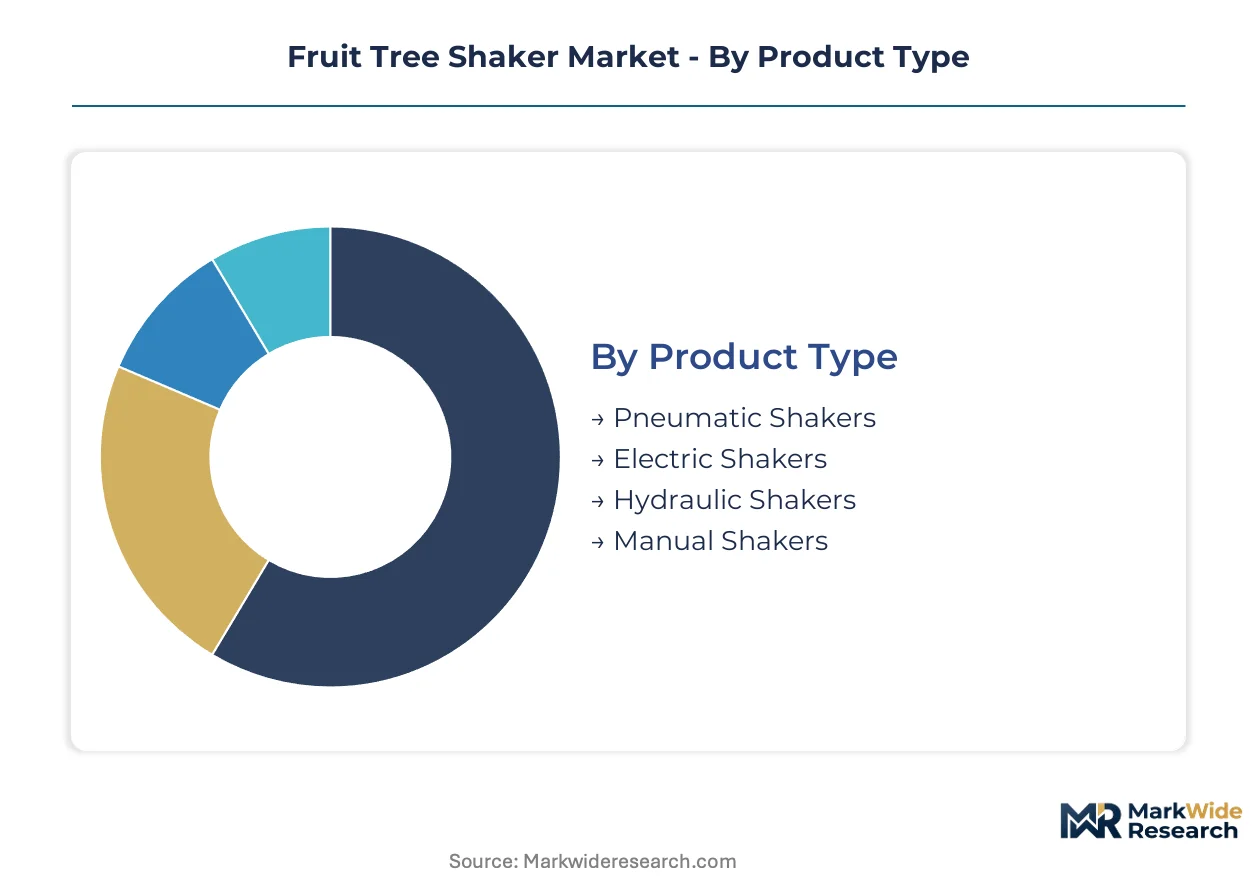
Segmentation in the fruit tree shaker market reveals how certification burdens, powertrain architectures, and operational models reshape procurement patterns across Mediterranean orchard systems. Understanding these divides exposes where compliance costs concentrate and where electrification premiums command buyer attention.
Product Type:
Pneumatic shakers carry lighter CE marking documentation for electromagnetic compatibility than electric variants, though EPA emission thresholds in California force parallel certification tracks for combustion-driven units.
- Pneumatic Shakers:Compressed-air systems deliver power-to-weight efficiency through reciprocating piston mechanisms, dominating mature olive and citrus operations in Spain and Italy where grid infrastructure remains uneven. CE marking requirements for pressure vessel safety and noise emissions filter out uncertified suppliers, consolidating procurement around documented conformity assessments.
- Electric Shakers:Variable-frequency drive architectures eliminate combustion emissions and reduce operator noise exposure, gaining traction in Portuguese and Greek cooperative networks with available charging infrastructure. Ecodesign regulations and EU F-Gas compliance for ancillary cooling systems add certification layers that elevate upfront costs against lifetime operating savings.
- Hydraulic Shakers:Fluid-power systems deliver calibrated clamp forces for dense-canopy nut varieties, requiring ISO 4413 machinery safety documentation for European market access.
- Manual Shakers:Hand-portable units serve heritage grove maintenance and varietal trials, bypassing machinery directive thresholds but limiting throughput to smallholder scale.
Leading the category by volume: Pneumatic Shakers. Growing fastest: Electric Shakers.
End User:
Capital deployment patterns diverge sharply between asset owners and service providers, with contractor fleets amortizing equipment across multiple harvest windows and demanding performance guarantees.
- Agricultural Contractors:Specialized harvesting service providers concentrate purchasing authority through multi-year equipment agreements, prioritizing telemetry-enabled fleet coordination and rapid parts availability during compressed Mediterranean harvest seasons. OSHA noise exposure programs and seasonal workforce training add operational overhead that favors standardized platform configurations.
- Orchard Owners:Direct equipment purchasers in Spain and Italy justify capital intensity through decades-long grove lifecycles, selecting trunk-shake or limb-shake architectures based on cultivar-specific canopy structures and soil compaction tolerance.
- Fruit Processors:Downstream handlers occasionally maintain captive shaking capacity for quality-control integration, though most outsource harvesting to preserve balance-sheet flexibility.
- Retailers:Supermarket chains and cooperative buying groups exert indirect influence through sustainability procurement standards that favor electrified or low-emission harvesting protocols in supplier orchards.
Dominating capital deployment: Orchard Owners. Expanding most quickly: Agricultural Contractors.
Application:
Functional requirements determine frequency calibration and clamp force specifications, with harvest timing applications demanding precision biomechanics that pruning or maintenance tasks do not.
- Fruit Harvesting:Mature-fruit dislodgement at 10-25 Hz frequencies with bark-damage avoidance protocols commands the largest equipment footprint, driving R&D investment in vibration engineering specialization across Spanish and Italian manufacturing clusters.
- Orchard Maintenance:Canopy management and debris clearance applications tolerate broader frequency ranges, opening market space for lighter-duty pneumatic configurations with reduced certification burdens.
- Pollination Aid:Controlled vibration improves pollen distribution in self-incompatible cultivars, requiring precise amplitude control distinct from harvest-force calibration.
- Pruning:Limb access and cut positioning applications leverage shaker boom geometry without engaging vibration mechanisms, repurposing chassis investments across seasonal task cycles.
Commanding equipment investment: Fruit Harvesting. Gaining functional share: Orchard Maintenance.
Technology:
Patent concentration and engineering talent scarcity favor vibration technology incumbents, while automation systems attract venture investment for telemetry and predictive harvest coordination.
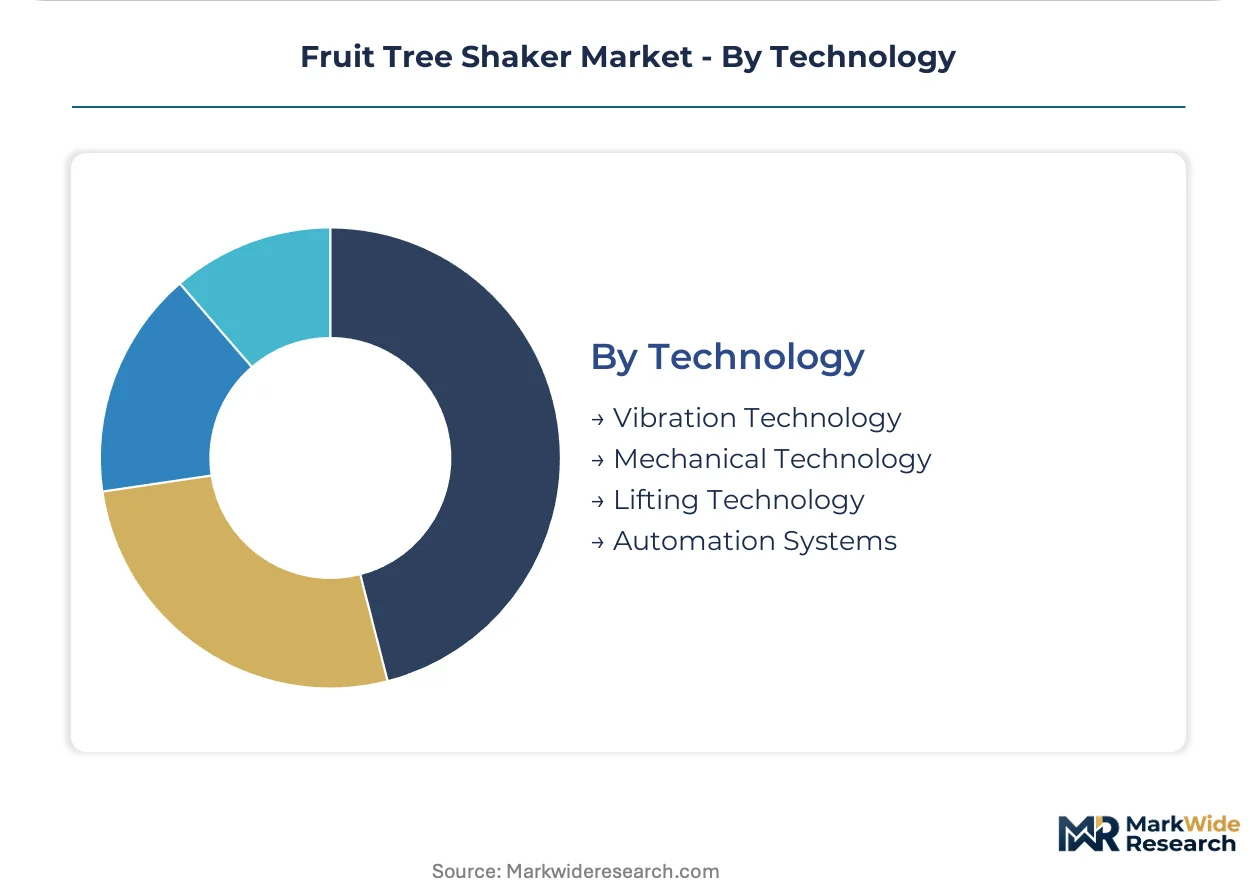
- Vibration Technology:Electromechanical oscillation systems with frequency-variable drives and force-calibrated clamping heads remain the core competitive battleground, with Spanish and Italian suppliers defending decades of orchard biomechanics expertise against Asian manufacturing cost pressure.
- Automation Systems:GPS-guided positioning, remote diagnostics, and fleet-wide harvest coordination software are climbing the fastest as precision agriculture convergence reshapes buyer requirements, particularly among contractor fleets managing dispersed orchard portfolios.
- Mechanical Technology:Purely mechanical linkages and fixed-output drives persist in price-sensitive segments and heritage equipment replacement cycles.
- Lifting Technology:Articulated boom and telescoping mast architectures enable canopy penetration in dense olive groves, requiring structural engineering compliance with EU machinery stability standards.
Holding technology leadership: Vibration Technology. Steepest expansion trajectory: Automation Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain concentrates the largest installed base of trunk-shake equipment, with Andalusian olive cooperatives driving replacement cycles for aging pneumatic fleets. Mechanization rates in Mediterranean orchard systems diverge sharply from Northern European fruit-growing patterns.
Spain
Andalusian olive cooperatives account for the densest concentration of shaker deployments outside California, with Jaén province alone hosting over four hundred contractor fleets. CE marking requirements under EU machinery safety directives filter out uncertified imports, consolidating procurement around documented conformity assessments. Seville-based equipment yards coordinate seasonal redistribution across Extremadura and Castilla-La Mancha growing belts.
Italy
Puglia and Sicily maintain competing standards for harvest timing protocols, with Apulian olive growers favoring earlier mechanical intervention than Sicilian almond operators. Ecodesign regulations and F-Gas compliance schedules for ancillary cooling systems elevate upfront equipment costs against lifetime operating savings. Bologna manufacturing clusters supply vibration-engineered clamp heads calibrated for heritage grove architectures.
Greece
Peloponnese nut growers accelerate outsourcing to specialized contractor fleets as seasonal labor migration patterns shift toward urban construction. National noise-emission standards align with EU machinery directive thresholds, though enforcement capacity varies across prefectural boundaries. Thessaly equipment depots stock rapid-replacement components for compressed September harvest windows.
United States
California's Central Valley dominates North American demand, with CARB emission thresholds forcing parallel powertrain development for combustion-driven units. OSHA noise exposure limits and operator-safety guard specifications influence domestic product configurations distinct from European CE-marked variants. Modesto-based service networks support high-utilization contractor fleets across the almond corridor.
Australia
Riverina and Sunraysia irrigation districts deploy shakers for almond and citrus operations, with biosecurity protocols restricting second-hand equipment imports from Mediterranean sources. State-level machinery safety frameworks reference ISO standards without full EU directive harmonization. Griffith equipment dealerships coordinate cross-border service coverage into Victoria's Murray Valley.
Fruit Tree Shaker Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-line agricultural equipment suppliers defending position through precision agriculture bundling while regional fabricators compete on customization velocity for heritage grove requirements. Market structure tilts toward consolidated procurement authority among contractor fleets, compressing vendor counts in mature olive and citrus territories. Three archetypes dominate: diversified machinery conglomerates with telemetry integration capabilities, regional specialists in trunk-shake biomechanics, and cooperative-affiliated fabricators serving captive purchasing consortia. Competitive moves concentrate on M&A for vibration engineering talent and capacity expansion into aluminum alloy component machining.
Within the diversified machinery tier, John Deere and AGCO Corporation exemplify platform-scale positioning, with the former leveraging precision agriculture ecosystems and the latter sustaining broad dealer networks across European fruit-growing belts. Orchard Machinery Corporation anchors the specialist archetype, occupying a position concentrated in California almond corridor deployments. Lopez Garrido and SICMA represent cooperative-adjacent fabricators, sitting within Mediterranean purchasing consortia structures where emission-targeting farm protocols influence specification authority.
| Leading Market Players |
|---|
| John Deere |
| AGCO Corporation |
| Fendt |
| Orchard Machinery Corporation |
| Lopez Garrido |
| SICMA |
| AMB Rousset |
| Greefa |
| Hansen |
| Others |
Pricing and Supply Chain Analysis
Variable-frequency electric drive systems are displacing fixed-output pneumatic architectures across Mediterranean manufacturing clusters, simultaneously elevating R&D amortization burdens and concentrating component sourcing around Bologna and Seville equipment yards. This technological transition compresses margins for legacy pneumatic suppliers while rewarding aluminum alloy machining capabilities that trim unit weight without sacrificing structural tolerance.
Pricing Analysis
Volume concentration in pneumatic shakers trades against margin capture in electric variants, with three-tier pricing structure across premium, standard, and economy levels separating CE-marked certified units from uncertified imports. Price differentiation hinges on electromagnetic compliance documentation and after-sales service bundling. Pricing pressure stems from aluminum and hydraulic input cost volatility. Agricultural contractors exhibit highest price sensitivity due to fleet amortization pressures, while orchard owners prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Workforce scarcity in vibration engineering specialization constrains throughput at Bologna and Seville manufacturing clusters, forcing lead time extension during compressed Mediterranean harvest windows. Component sourcing draws from Italian aluminum alloy suppliers, German hydraulic system manufacturers, and Spanish pneumatic component fabricators. Single-source vulnerability concentrates in force-calibrated clamp head production. Distribution runs through cooperative-affiliated equipment yards and AGCO Corporation dealer networks across European fruit-growing belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where scarce mechanical engineering talent with orchard biomechanics expertise props equipment pricing and extends delivery timelines for certified configurations.
For Market Incumbents: Anchor market position through captive aluminum alloy machining capacity in Seville and Bologna manufacturing clusters to defend against Asian cost pressure. Deepen backward integration into force-calibrated clamp head production to reduce single-source vulnerability. Prioritize CE marking documentation investment to filter low-cost competitors under EU machinery safety directives. For New Entrants and Emerging Players: EU F-Gas Regulation phase-down schedules in member states open a window for alternative cooling system architectures in electric shaker configurations. Target Portuguese and Greek cooperative networks with grid-connected charging infrastructure as the most penetrable geography. Pursue telemetry-enabled fleet coordination software as the primary go-to-market angle to bypass capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified agricultural machinery conglomerates seeking vibration engineering specialization. Long-term viability favors platforms with demonstrated CE marking compliance and aluminum alloy chassis manufacturing capabilities. Monitor CARB emission threshold enforcement in California as the critical inflection signal for electrification investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Alloy Chassis Integration | High-strength metallurgy trims unit weight for dense orchard penetration without soil compaction trade-offs. |
| CE Marking Certification Investment | EU machinery safety directive compliance filters uncertified competitors from Mediterranean procurement channels. |
| Telemetry Platform Development | Precision agriculture data convergence enables predictive harvest timing for contractor fleet optimization. |
| Regional Parts Depot Expansion | Thessaly and Jaén component stocking addresses compressed September harvest window downtime risks. |
| Electric Powertrain Transition | Variable-frequency drive architectures align with Portuguese cooperative emission-targeting farm protocols. |
Research Methodology
Independent corroboration across orchard equipment procurement managers, agricultural contractor fleet operators, vibration engineering specialists, and cooperative purchasing consortia underwrites the qualitative findings presented in this study. Primary fieldwork combined structured interviews with secondary validation through EU machinery directive documentation, CE marking conformity assessment records, and aluminum alloy trade flow data. Bottom-up equipment deployment estimates triangulated against top-down Mediterranean orchard mechanization rate projections.
Comparable-period anchoring to historical pneumatic shaker replacement cycles and electric adoption trajectories structured the forecast window across the projection horizon. Segmentation dimensions modeled include powertrain architecture, end-user operational model, canopy penetration application, and regional regulatory cluster. CAGRs derived from equipment procurement pipeline analysis and cooperative purchasing consortia capital expenditure intentions. Forecast inputs incorporated CARB emission threshold enforcement patterns and F-Gas Regulation phase-down compliance timelines.
Caveats apply where aluminum price volatility, workforce migration patterns in Mediterranean agriculture, or regulatory divergence between EU and California jurisdictions could materially shift the outlook. Forecasts reflect documented assumptions regarding cooperative network electrification readiness and contractor fleet consolidation trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables Processing Equipment
Tomato Processing Market
Fruits and Vegetables Processing Equipment
North America Avocado Processing Market
Fruits and Vegetables Processing Equipment
Smart Juicer Market
Fruits and Vegetables Processing Equipment
Smart Juicer Machine Market
Fruits and Vegetables Processing Equipment
Fruit and Vegetable Processing Equipment Market
Fruits and Vegetables Processing Equipment
Juice Extractors Market
Fruits and Vegetables Processing Equipment
Juicer Market
Fruits and Vegetables Processing Equipment
Avocado Processing Market
Fruits and Vegetables Processing Equipment
Grape Crusher Market
Fruits and Vegetables Processing Equipment
Portable Juicer Market
Fruits and Vegetables Processing Equipment
Juice Extraction Equipment Market
Fruits and Vegetables Processing Equipment
Global Fruit and Vegetable Processing Market
Fruits and Vegetables Processing Equipment
Global Fruit Processing Equipment Market