
 Grape Crusher Market | 2026-2036
Grape Crusher Market Size, Share, and Industry Trends Forecast 2026-2036
Grape Crusher Market Foresight
Stainless-steel grade upgrades in commercial-grade crushing equipment is bifurcating the competitive landscape between premium fabricators and commodity assemblers. Bucher Vaslin leverages its French manufacturing heritage to sustain dominance in pneumatic destemmer-crushers for large Bordeaux châteaux. Pellenc Group anchors its position through proprietary optical sorting integration that extends beyond crushing into whole-cluster processing workflows. Grifo Marchetti competes aggressively on manual and electric entry-level units, occupying the home brewer and small estate segments across Italy's Veneto and Piedmont regions.
A grape crusher is a mechanical device designed to break grape skins and release juice prior to fermentation, typically employing stainless steel rollers or perforated drums with adjustable gap settings measured in millimeters to control maceration intensity and seed integrity. The equipment serves wineries, beverage producers, and home brewers by converting whole grape clusters into must while optionally separating stems through integrated destemming mechanisms. Electric crushers lead the Type dimension due to labor cost pressures in mid-scale wineries across France and Spain, while pneumatic variants represent the fastest-growing category as Champagne houses and premium sparkling wine producers adopt gentler pressing philosophies. Stainless Steel dominates the Material segment because regulatory hygiene mandates and CIP (clean-in-place) compatibility requirements eliminate wood and most aluminum alternatives in certified commercial operations.
The EU's Machinery Directive and CE marking requirements shape product safety and electromagnetic compatibility standards for all crushers sold within member states, while the FDA's Good Manufacturing Practices and OSHA's lockout/tagout rules govern equipment deployed in US wineries and beverage production facilities. California's Cal/OSHA and South Australia's WorkSafe SA impose additional state-level mechanical guarding standards that influence regional product configurations. Stakeholders must monitor evolving energy efficiency benchmarks under the EU Ecodesign framework and assess whether battery-powered or solar-integrated electric crushers warrant development investment as distributed renewable generation spreads across rural winegrowing regions.
Market Dynamics
The EU's F-Gas Regulation is compressing demand timelines for energy-efficient crushing systems across European wine regions, forcing producers to accelerate capital replacement cycles ahead of enforcement deadlines.
Growth Catalysts
- Climate-controlled fermentation mandates:The EU F-Gas Regulation drives French and Italian producers toward pneumatic destemmer-crushers with lower refrigerant dependency.
- Estate modernization clusters:Australia's Barossa Valley wine producers are retrofitting processing infrastructure with stainless-steel electric units to reduce labor intensity.
- Optical sorting convergence:Integration of machine-vision stem detection is expanding crusher utility into whole-cluster processing workflows for premium sparkling houses.
Market Restraints
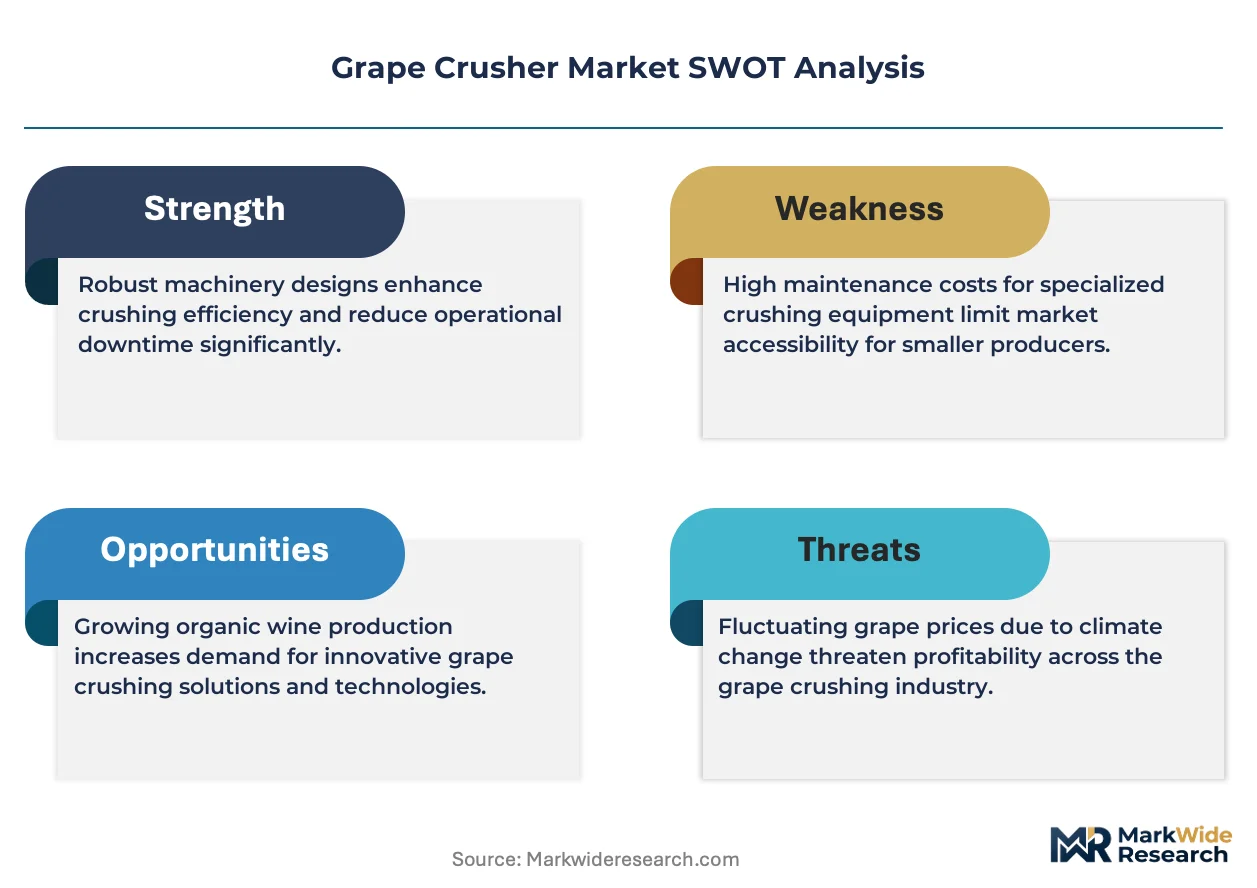
- Stainless-steel input volatility:Grade 304 and 316 sheet metal price swings compress margins for fabricators serving mid-scale winery segments.
- Supply concentration in Italian componentry:Gearbox and motor subassembly production clusters in Emilia-Romagna, creating single-source vulnerability for European OEMs.
- CE marking procedural friction:Machinery Directive compliance timelines extend product launch windows by four to eight months for non-EU manufacturers.
Strategic Opportunities
- Battery-powered electric mobility:Solar-integrated crushing units align with distributed renewable generation spreading across rural California and South Australian winegrowing zones.
- Home brewer channel expansion:Manual and entry-level electric crushers face underpenetrated demand among amateur winemakers in Germany and Austria.
- Ecodesign energy benchmarking:The EU Ecodesign framework creates first-mover advantage for OEMs certifying ultra-efficient drive systems ahead of mandatory thresholds.
Industry Challenges
- Mechatronics skill scarcity:Servo-controlled gap adjustment and PLC programming expertise shortages constrain service network expansion in secondary wine regions.
- Legacy CIP integration complexity:Retrofitting automated clean-in-place protocols into existing winery infrastructure demands custom engineering that extends deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grape Crusher Market |
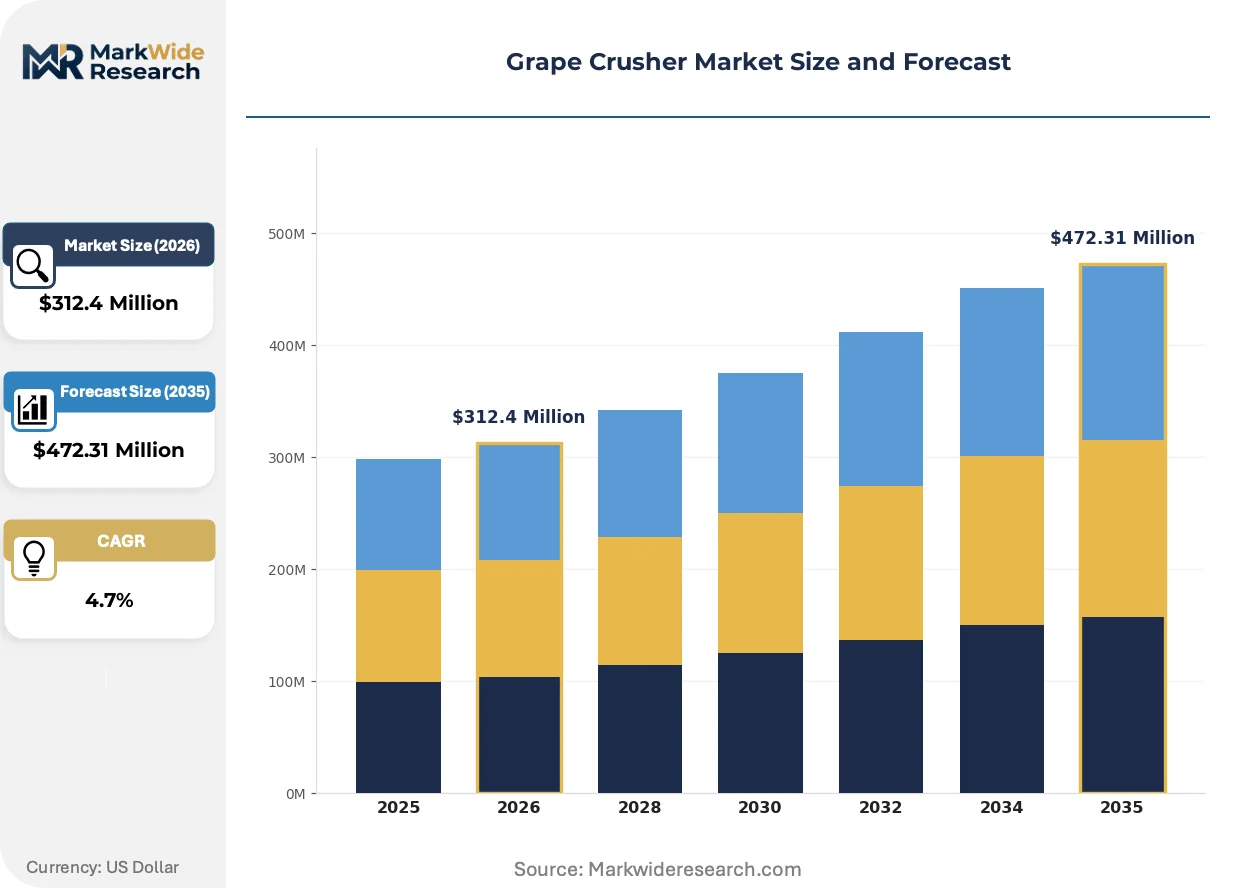
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Manual, Electric, Pneumatic, Hydraulic Material: Stainless Steel, Plastic, Wood, Aluminum End User: Winery, Home Brewer, Commercial Kitchen, Beverage Producer Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Zambelli Enotech, Bucher Vaslin, Pellenc Group, Enoitalia Srl, Marchisio S.p.A., Gino Pinto Inc., Grifo Marchetti, Winequip, Speidel Tank- und Kellereitechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grape Crusher Market Shifts & Advancements
Pneumatic pressing philosophy is displacing mechanical intensity across premium segments, while regulatory energy mandates and distributed renewable infrastructure reshape equipment specification priorities.
Perforated drum destemming with adjustable membrane pressure is decomposing the traditional roller-crusher paradigm for seed-sensitive maceration. Champagne houses and premium sparkling producers in France's Côte des Blancs are adopting these systems at accelerated replacement cycles. The technology is decomposing equipment lifecycle expectations from fifteen-year horizons toward seven-to-ten-year refresh rates.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is redirecting capital toward climate-independent crushing architectures. Wineries in Bordeaux and Tuscany are prioritizing ambient-cooling-compatible pneumatic systems to preempt compliance exposure. Large châteaux with existing glycol infrastructure face the steepest retrofit cost pressure and are negotiating extended transition timelines with national environmental agencies.
Boutique estate buyers are consolidating vendor relationships around full-process integration rather than standalone crushing procurement. Napa Valley and Sonoma producers now specify destemmer-crushers as part of broader optical-sorting and press-system packages, compressing the addressable market for component specialists. This consolidation pattern is most visible among California wineries with annual production between five thousand and fifty thousand cases, where technical staff scarcity favors single-source accountability.
Grape Crusher Market Segmentation
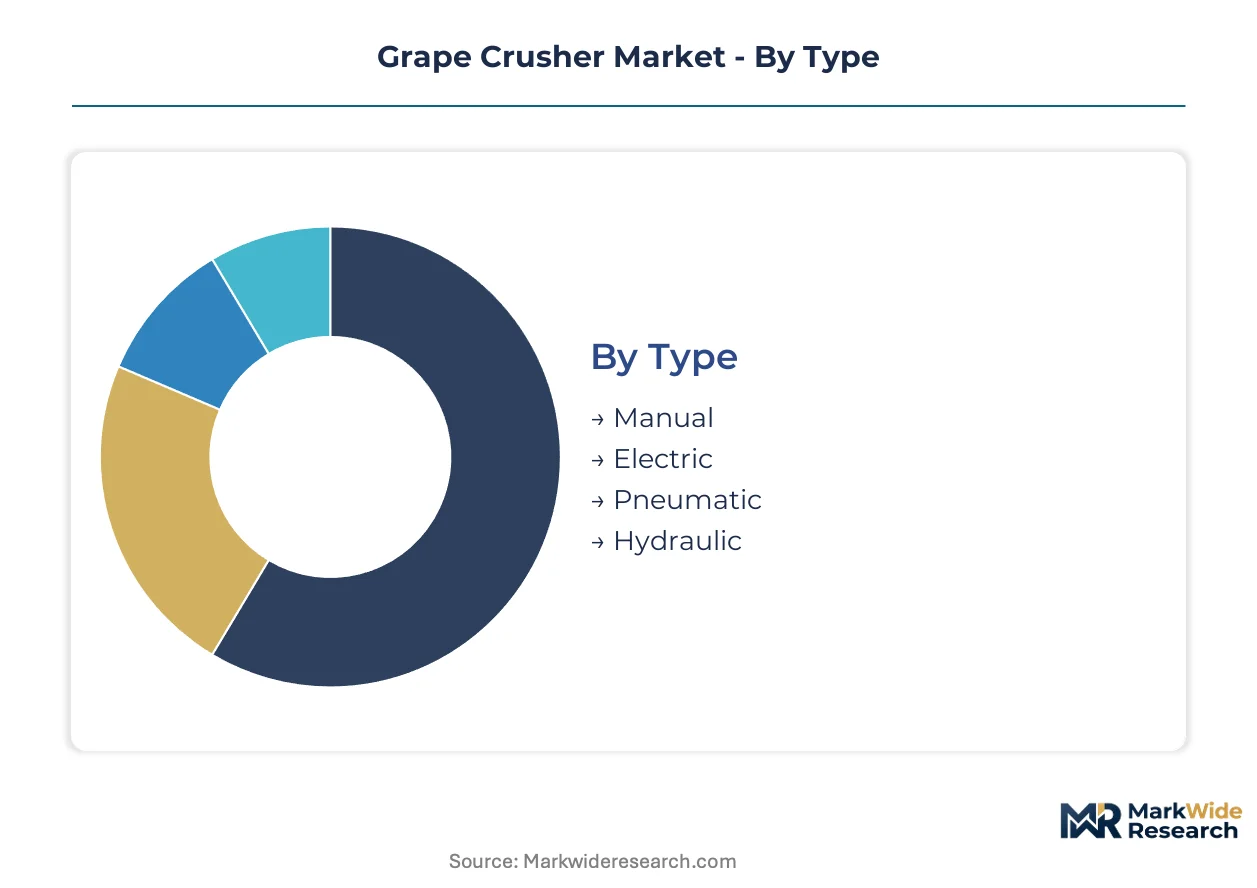
Grape crusher procurement patterns diverge sharply across equipment types, construction materials, and operational scales. Understanding these fault lines reveals where substitution threats and margin pressure concentrate for fabricators and distributors.
Type:
Pneumatic systems face the most acute substitution pressure from next-generation electric drives with servo-controlled gap adjustment, while manual units confront displacement from entry-level electric alternatives in labor-cost-sensitive regions.
- Manual:Hand-cranked cast-iron or steel mechanisms requiring physical operator effort. Demand persists among heritage estates in Italy's Piedmont and hobbyist segments in Germany where traditional winemaking rituals sustain preference despite ergonomic limitations.
- Electric:Motor-driven roller assemblies with fixed or variable speed control, typically drawing single-phase or three-phase power. French and Spanish mid-scale wineries specify these units most heavily as labor cost pressures intensify seasonal staffing challenges.
- Pneumatic:Air-pressure-actuated membrane or bladder systems enabling gentle berry processing with minimal seed fracture. Champagne houses in France's Côte des Blancs and premium sparkling producers across Australia's Yarra Valley deploy these for whole-cluster workflows demanding maceration precision.
- Hydraulic:High-pressure fluid-driven crushing systems delivering maximum throughput for large-scale juice extraction. Industrial beverage operations in California's Central Valley and bulk wine processors in Spain's La Mancha region specify these for volume-centric harvest windows.
Electric crushers retain volume leadership across commercial installations; pneumatic configurations hold the steepest expansion curve among premium estate replacements.
Material:
Cost tier stratification separates food-grade certified fabrications from commodity alternatives, with regulatory hygiene mandates eliminating lower-tier options from certified commercial channels.
- Stainless Steel:Grade 304 or 316 construction delivering corrosion resistance, CIP compatibility, and regulatory compliance for commercial operations. EU hygiene mandates and FDA Good Manufacturing Practices render this the default specification for wineries in Bordeaux, Napa Valley, and South Australia's Barossa Valley.
- Plastic:Polymer or composite housings and components reducing unit weight and capital outlay. Home brewer segments in Austria and Switzerland accept these for small-batch fermentation experiments where equipment longevity matters less than acquisition cost.
- Wood:Traditional barrel-stave or hardwood construction preserving historical aesthetic and perceived terroir alignment. Boutique estates in Portugal's Douro Valley and heritage producers in Georgia's Kakheti region specify these for tourism-facing installations and traditional qvevri winemaking.
- Aluminum:Lightweight alloy frames and perforated drums offering intermediate durability between plastic and stainless grades. Limited penetration reflects corrosion vulnerability in acidic must environments and restricted CIP chemical compatibility.
Stainless steel commands the revenue base across certified commercial channels; plastic alternatives gain share fastest in amateur and experimental user segments.
End User:
Application intensity varies dramatically across user categories, with professional wineries demanding integrated destemming-sorting-pressing workflows that amateur segments neither require nor finance.
- Winery:Licensed wine production facilities with bonded storage and regulatory compliance obligations. Estate producers across France, Italy, and California specify destemmer-crushers as components of broader optical-sorting and press-system packages.
- Home Brewer:Non-commercial amateur winemakers operating below regulatory licensing thresholds. Demand concentrates in Germany and Austria where hobbyist culture supports entry-level electric and manual unit sales through specialty retailers.
- Commercial Kitchen:Restaurant, hotel, and catering operations producing house wines or ingredient musts. Urban hospitality clusters in Melbourne and San Francisco deploy compact electric units for limited-batch programs.
- Beverage Producer:Multi-product juice, cider, and fermented beverage manufacturers requiring cross-functional crushing equipment. Operations in Washington State's Yakima Valley and New Zealand's Hawke's Bay specify adaptable systems for grape and alternative fruit processing.
Winery end users dominate equipment value; home brewer channels are climbing fastest as amateur winemaking proliferates through online communities.
Capacity:
Customer type and harvest scale dictate capacity selection, with estate modernization cycles in established wine regions driving replacement demand in medium and large classifications.
- Small:Units processing under 500 kilograms hourly, suited to micro-wineries and experimental batches. Proliferating urban winery projects in Portland and Austin specify these for tasting-room-adjacent production.
- Medium:Equipment handling 500-2000 kilograms hourly, aligning with family estate and cooperative scale. Australia's Barossa Valley retrofitting wave concentrates replacement demand in this bracket.
- Large:Systems processing 2000-5000 kilograms hourly for substantial commercial operations. Bordeaux châteaux and Napa Valley mid-tier producers deploy these as central crush pad infrastructure.
- Extra Large:Industrial-scale installations exceeding 5000 kilograms hourly for bulk wine and concentrate production. Central Valley California processors and La Mancha cooperatives operate these within integrated harvest-receiving complexes.
Medium capacity equipment sustains the broadest installed base; extra large configurations are expanding most quickly through consolidation in high-volume winegrowing zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian componentry clusters in Emilia-Romagna anchor gearbox and motor subassembly supply for European OEMs, while fabrication demand concentrates in established winegrowing economies with estate modernization cycles underway.
United States
California's Napa Valley and Sonoma County estates are consolidating vendor relationships around full-process integration rather than standalone crushing procurement. Cal/OSHA mechanical guarding standards shape regional product configurations for equipment deployed in bonded wineries. Mid-tier producers between five thousand and fifty thousand cases favor single-source accountability for destemmer-crusher, optical-sorting, and press-system packages.
France
Champagne houses in the Côte des Blancs are accelerating replacement cycles toward seven-to-ten-year horizons as pneumatic pressing philosophy displaces mechanical intensity. The EU F-Gas Regulation's hydrofluorocarbon phasedown redirects capital toward ambient-cooling-compatible systems. Large Bordeaux châteaux negotiate extended transition timelines with national environmental agencies while prioritizing climate-independent crushing architectures.
Italy
Heritage estates in Piedmont sustain manual crusher preference for traditional winemaking rituals despite ergonomic limitations, while Veneto and Emilia-Romagna fabricators supply gearbox and motor subassemblies across European OEM networks. CE marking requirements under the EU Machinery Directive extend product launch windows for non-EU manufacturers seeking Italian market entry.
Australia
Barossa Valley wine producers are retrofitting processing infrastructure with stainless-steel electric units to reduce labor intensity during compressed harvest windows. WorkSafe SA mechanical guarding standards influence regional equipment specifications. Estate modernization demand concentrates in the medium-capacity bracket as family-scale operations replace aging crush pad infrastructure.
Germany
Hobbyist culture in rural winegrowing regions supports entry-level electric and manual unit sales through specialty retailers serving amateur winemakers. The EU Ecodesign framework creates first-mover advantage for OEMs certifying ultra-efficient drive systems ahead of mandatory energy benchmarking thresholds. Southern wine regions face underpenetrated demand for home brewer channel expansion.
Grape Crusher Market Competitive Landscape
Concentration sits with heritage European fabricators possessing French and Italian manufacturing lineage, while mid-scale commodity assemblers compete on stainless-steel grade differentiation. The competitive landscape bifurcates between premium pneumatic destemmer-crusher specialists and entry-level manual-electric providers. Strategic moves center on optical sorting convergence for whole-cluster workflow integration and battery-powered electric mobility aligned with distributed renewable generation.
Within the heritage fabrication tier, Bucher Vaslin and Pellenc Group represent French manufacturing archetypes with established presence in large châteaux and premium sparkling houses. Grifo Marchetti occupies the Italian entry-level segment for home brewer and small estate markets. Zambelli Enotech and Enoitalia Srl exemplify Veneto-based fabricators serving regional demand clusters across Piedmont and Emilia-Romagna.
| Leading Market Players |
|---|
| Zambelli Enotech |
| Bucher Vaslin |
| Pellenc Group |
| Enoitalia Srl |
| Marchisio S.p.A. |
| Gino Pinto Inc. |
| Grifo Marchetti |
| Winequip |
| Speidel Tank- und Kellereitechnik |
| Others |
Supply & Pricing Matrix
CE marking requirements under the EU Machinery Directive gate both supplier qualification and price tier stratification simultaneously, forcing fabricators to absorb compliance costs or exit certified commercial channels entirely. Stainless-steel grade certification and CIP protocol validation separate premium French and Italian OEMs from commodity assemblers serving uncertified home brewer segments.
Pricing Analysis
The EU Machinery Directive dictates the pricing tier structure across European commercial channels, with CE-certified pneumatic systems commanding substantial premiums over non-certified alternatives. Three-tier pricing structure across premium, standard, and economy levels separates optical-sorting-integrated packages from standalone crushers and entry-level manual units. Pricing pressure stems from Grade 304 and 316 sheet metal volatility compressing fabricator margins. Mid-scale wineries exhibit highest price sensitivity due to capital constraint cycles, while Champagne houses demonstrate lowest sensitivity given replacement urgency from F-Gas compliance deadlines.
Supply Chain Analysis
Inventory lead times for gearbox and motor subassemblies from Emilia-Romagna suppliers currently stretch deployment schedules for European OEMs. Component sourcing draws from Italy for precision mechanical parts, China for electrical assemblies, and France for pneumatic membrane technologies. Raw material dependencies rest on nickel-alloy stainless grades, food-grade lubricants, and servo-drive electronics. Single-source vulnerability concentrates in Italian gearbox production clusters. Distribution runs through bonded winery equipment distributors in Bordeaux, Napa Valley, and Barossa Valley with direct technical service obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The grape crusher market faces high-growth disruption from EU F-Gas Regulation enforcement compressing replacement cycles toward energy-efficient pneumatic architectures. This regulatory inflection creates asymmetric opportunity for OEMs with climate-independent crushing portfolios.
For Market Incumbents: Secure backward integration into Italian gearbox supply chains to mitigate Emilia-Romagna concentration risk threatening production continuity. Lock in long-term stainless-steel offtake agreements with mills serving Grade 304 and 316 specifications before commodity volatility intensifies. Prioritize optical-sorting convergence R&D to defend against displacement from whole-cluster workflow specialists entering destemmer-crusher adjacencies. For New Entrants and Emerging Players: CE marking fast-track certification creates viable entry path into mid-scale French and Spanish winery segments underserved by heritage fabricator lead times. Target Australia's Barossa Valley estate modernization wave with battery-powered electric units aligned to distributed solar generation spreading across South Australian winegrowing zones. Pursue home brewer channel expansion in Germany and Austria through specialty retailer partnerships bypassing incumbent distributor control. For Investors and Strategic Acquirers: The EU Ecodesign framework's mandatory energy benchmarking reshapes the acquisition landscape toward OEMs with ultra-efficient drive system certifications already secured. Five-to-ten year viability favors vertically integrated fabricators controlling in-house pneumatic membrane production and Italian component sourcing. Watch for F-Gas enforcement acceleration signals from French and Italian environmental agencies as inflection indicator for premium pneumatic demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sorting Integration | Pellenc Group's machine-vision convergence extends crusher utility into whole-cluster Champagne workflows. |
| Battery-Powered Electric Development | Solar-integrated crushing units align with California and South Australia distributed renewable generation. |
| CE Marking Fast-Track Investment | Compressed compliance timelines create first-mover advantage for non-EU manufacturers entering European markets. |
| Italian Componentry Backward Integration | Upstream control over Emilia-Romagna gearbox supply mitigates single-source vulnerability for European OEMs. |
| Home Brewer Channel Expansion | Underpenetrated German and Austrian amateur segments offer volume offset to commercial winery cyclicality. |
Research Methodology
A spread of perspectives from crush pad engineers, winery procurement directors, OEM technical sales leads, and aftermarket service managers converged on the working assumptions shaping demand projections. Primary fieldwork combined structured interviews with equipment operators across Bordeaux, Napa Valley, and Barossa Valley with secondary validation from EU Machinery Directive compliance databases, FDA Good Manufacturing Practice guidance documents, and stainless-steel commodity trade flows. Bottom-up winery census data and top-down equipment shipment aggregates were triangulated to anchor volume estimates.
Segmentation dimensions modeled include equipment type, material grade, end-user category, and processing capacity tier across the projection horizon. CAGRs were derived from replacement cycle compression analysis, regulatory deadline mapping, and estate modernization spend patterns. Forecast inputs incorporated F-Gas Regulation enforcement phasing, Ecodesign energy benchmark adoption curves, and distributed renewable generation penetration in rural winegrowing zones.
Decision-makers should treat outputs as directional under assumptions of stable stainless-steel pricing, sustained EU regulatory enforcement timelines, and continued labor cost pressures in mid-scale winery operations; material deviation in commodity markets or policy acceleration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables Processing Equipment
Portable Juicer Market
Fruits and Vegetables Processing Equipment
Smart Juicer Machine Market
Fruits and Vegetables Processing Equipment
Smart Juicer Market
Fruits and Vegetables Processing Equipment
Juicer Market
Fruits and Vegetables Processing Equipment
Global Fruit Processing Equipment Market
Fruits and Vegetables Processing Equipment
Avocado Processing Market
Fruits and Vegetables Processing Equipment
Fruit Tree Shaker Market
Fruits and Vegetables Processing Equipment
North America Avocado Processing Market
Fruits and Vegetables Processing Equipment
Fruit and Vegetable Processing Equipment Market
Fruits and Vegetables Processing Equipment
Global Fruit and Vegetable Processing Market
Fruits and Vegetables Processing Equipment
Juice Extractors Market
Fruits and Vegetables Processing Equipment
Tomato Processing Market
Fruits and Vegetables Processing Equipment
Juice Extraction Equipment Market