
 North America Avocado Processing Market | 2026-2036
North America Avocado Processing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Avocado Processing Market Intelligence
High-pressure processing technology is narrowing the shelf-life gap between fresh-cut and pasteurized avocado products. West Pak Avocado leverages vertical integration from orchard to retail-ready packs across California and Mexico. Calavo Growers sustains R&D intensity in varietal development and ripening protocols. Mission Produce anchors North American supply through its network of ripening centers and direct retail partnerships.
North America avocado processing encompasses the mechanical transformation of Hass and alternate cultivars into guacamole, oil, puree, and diced formats through washing, destoning, peeling, and either high-pressure or thermal pasteurization, yielding products with controlled enzymatic browning and specified pulp dry-matter content for food manufacturing and food service use. Guacamole commands the largest product-type volume pool though avocado oil extracts premium margins in retail and cosmetic-adjacent channels. Food service application leads absolute consumption while snack-food manufacturing represents the fastest-growing demand vector as extruded and coated products proliferate. Direct sales distribution dominates institutional volumes even as online retail channels gain traction in household and small-restaurant procurement.
The U.S. FDA enforces Hazard Analysis Critical Control Point protocols and traceability mandates under FSMA that elevate compliance costs for cross-border processors. Mexico's national agricultural health authority, SENASICA, coordinates phytosanitary certification for fresh avocado exports while USDA grading standards shape U.S. domestic product classification and price discovery. Canada requires bilingual labeling and CFIA import inspection for processed avocado goods entering through British Columbia and Ontario ports. Stakeholders must monitor evolving U.S.-Mexico-Canada Agreement rules-of-origin interpretations and California water-allocation rulings that could reshape supply geography and processing location decisions.
Market Dynamics
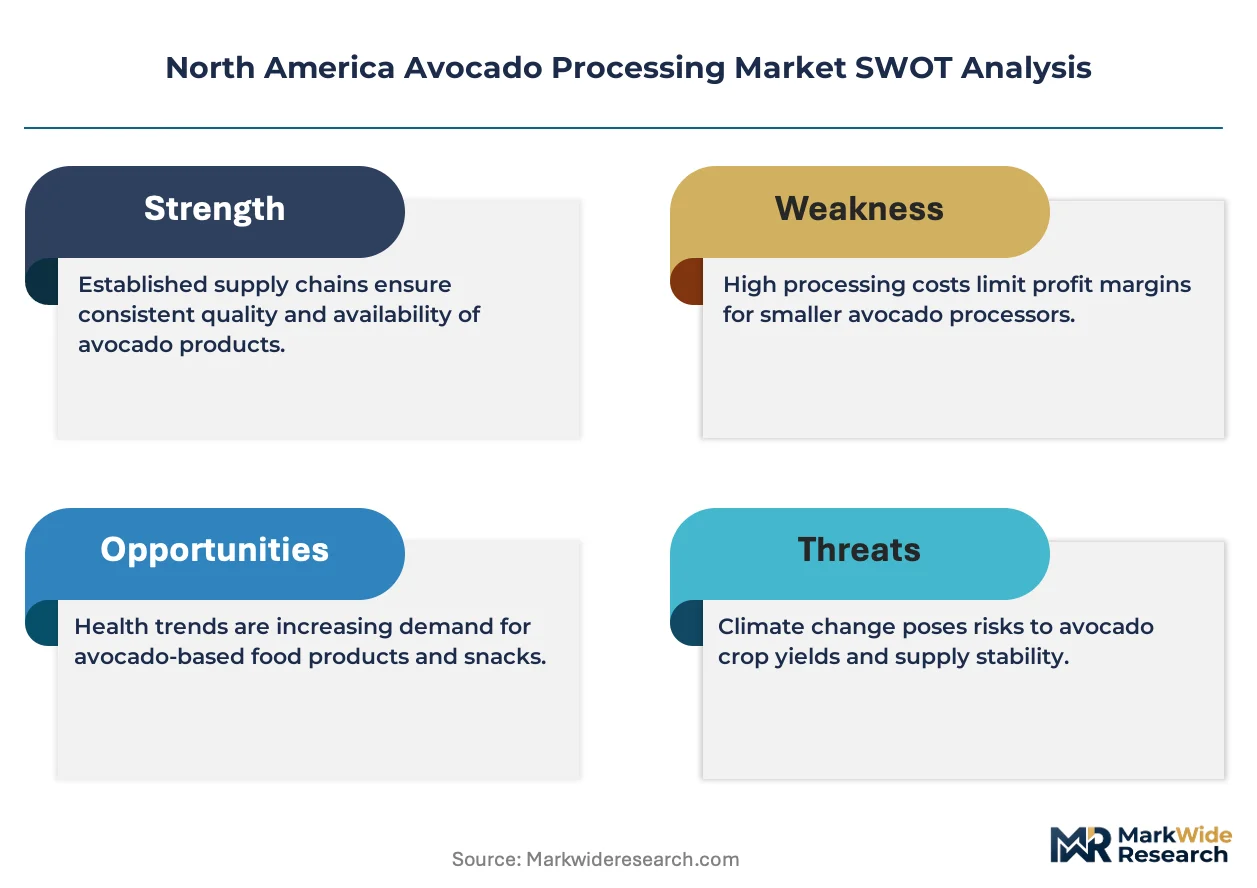
High-pressure pasteurization (HPP) is compressing the shelf-life differential between fresh-cut and thermally processed avocado formats, forcing processors to recalibrate capital allocation between cold-chain infrastructure and thermal retort lines. This technology inflection is reshaping competitive positioning across California and Mexico processing corridors.
Growth Catalysts
- FSMA traceability mandates:The FDA's Food Safety Modernization Act lot-tracking requirements are accelerating cold-chain and data-system investments among cross-border processors serving US food service accounts.
- Snack-food manufacturing pull:Extruded and coated avocado applications are expanding demand for specified pulp dry-matter content from processors with controlled enzymatic browning capabilities.
- Michoacán corridor concentration:Integrated packer-shippers with captive ripening infrastructure are capturing margin pools previously held by fragmented regional handlers.
Market Restraints
- Input cost volatility:California water-allocation rulings and irrigation restrictions are elevating orchard operating costs and compressing processor feedstock margins.
- Supply concentration risk:Michoacán's dominance in Hass avocado production creates phytosanitary vulnerability, with SENASICA certification disruptions rippling through North American supply.
- Technical limitation:Enzymatic browning control in minimally processed formats remains imperfect, constraining fresh-cut expansion into extended distribution channels.
Strategic Opportunities
- Canadian retail penetration:CFIA bilingual labeling requirements and import inspection protocols at British Columbia and Ontario ports represent underdeveloped channels for compliant processors.
- Cosmetic-adjacent oil extraction:Avocado oil's premium positioning in personal care applications offers margin expansion beyond food-service and retail grocery channels.
- USMCA rules-of-origin clarity:Evolving interpretation of regional content thresholds creates incentive for processors to relocate finishing operations within treaty boundaries.
Industry Challenges
- HACCP implementation timelines:Small and mid-scale processors face extended compliance certification periods under FDA Hazard Analysis Critical Control Point protocols.
- Skill scarcity in HPP operations:Qualified technicians for high-pressure pasteurization system maintenance and calibration are concentrated among equipment OEM service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Avocado Processing Market |
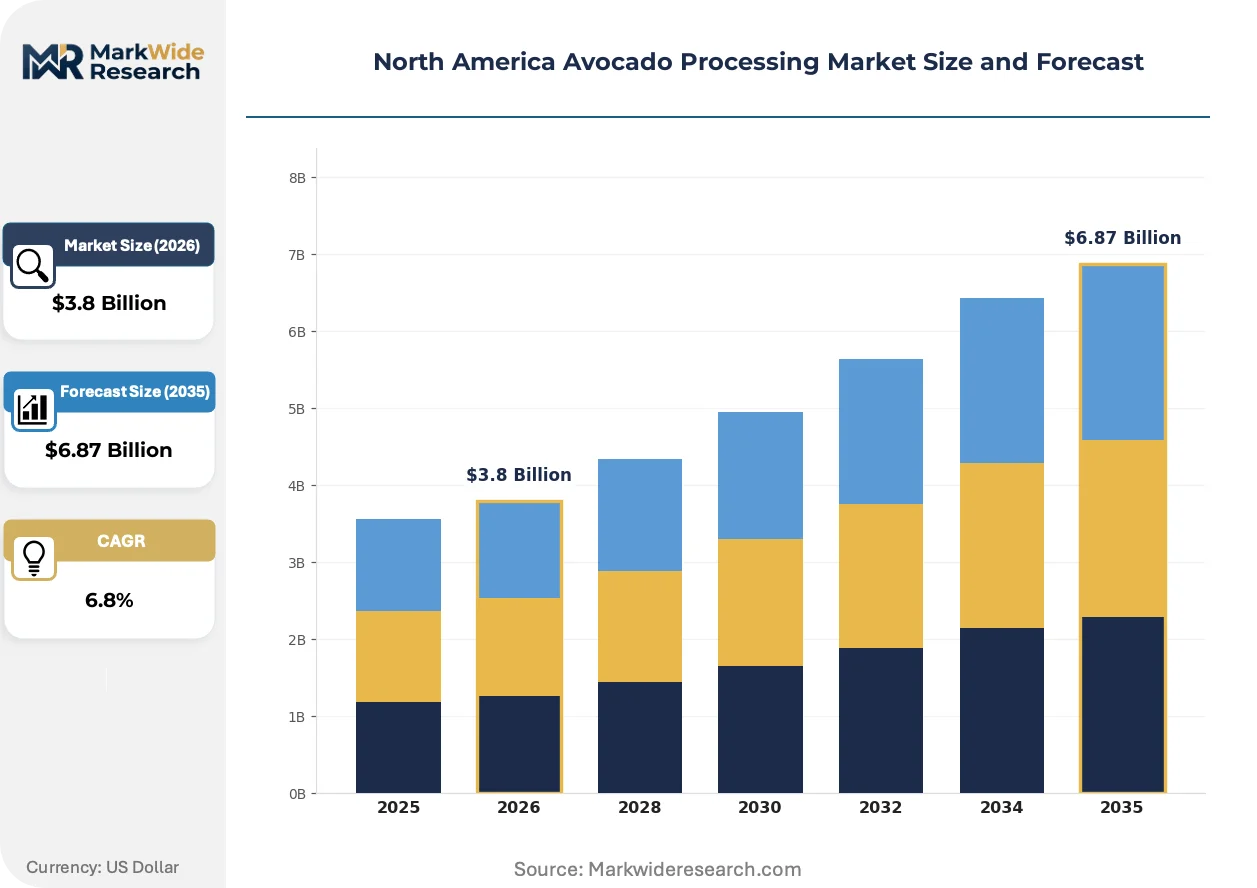
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Guacamole, Avocado Oil, Avocado Puree, Diced Avocado Application: Food Service, Retail, Food Manufacturing, Snack Foods End User: Households, Restaurants, Food Processors, Catering Services Distribution Channel: Direct Sales, Online Retail, Supermarkets, Wholesalers |
| Companies Covered | West Pak Avocado, Del Rey Avocado Co., Calavo Growers, F&S Fresh Foods, Simplot Food Group, Mission Produce, Henry Avocado Corporation, Flagship Food Group, Index Fresh, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Avocado Processing Market Strategic Shifts & Innovations
Processing technology, regulatory compliance architecture, and procurement pattern evolution are converging to redefine competitive advantage in North American avocado transformation. These three forces are compressing legacy operational models while opening new margin pools.
High-pressure processing technology is migrating from niche premium guacamole lines to mainstream food-service pasteurized formats. Mid-scale processors in California are retrofitting existing thermal facilities with HPP units to capture extended shelf-life specifications demanded by institutional distributors. This equipment transition is enabling direct-to-retail ready packs that bypass traditional ripening-center intermediation.
USMCA origin-certification requirements are forcing processors to document cross-border supply chain provenance with granular lot-level traceability. The treaty's evolving rules-of-origin interpretations are elevating compliance system investments among integrated packer-shippers operating dual-country footprints. Mexican processors with California finishing operations are most exposed to audit intensity and documentation burden.
Food service operators are consolidating procurement through direct ripening-center partnerships, displacing traditional distributor intermediaries. Large restaurant chains and institutional feeders are negotiating volume commitments with Mission Produce and West Pak Avocado for specified ripeness-stage delivery. This channel compression is most visible in Texas and Southwest US markets where just-in-time ripening infrastructure anchors supply reliability.
North America Avocado Processing Market Segmentation
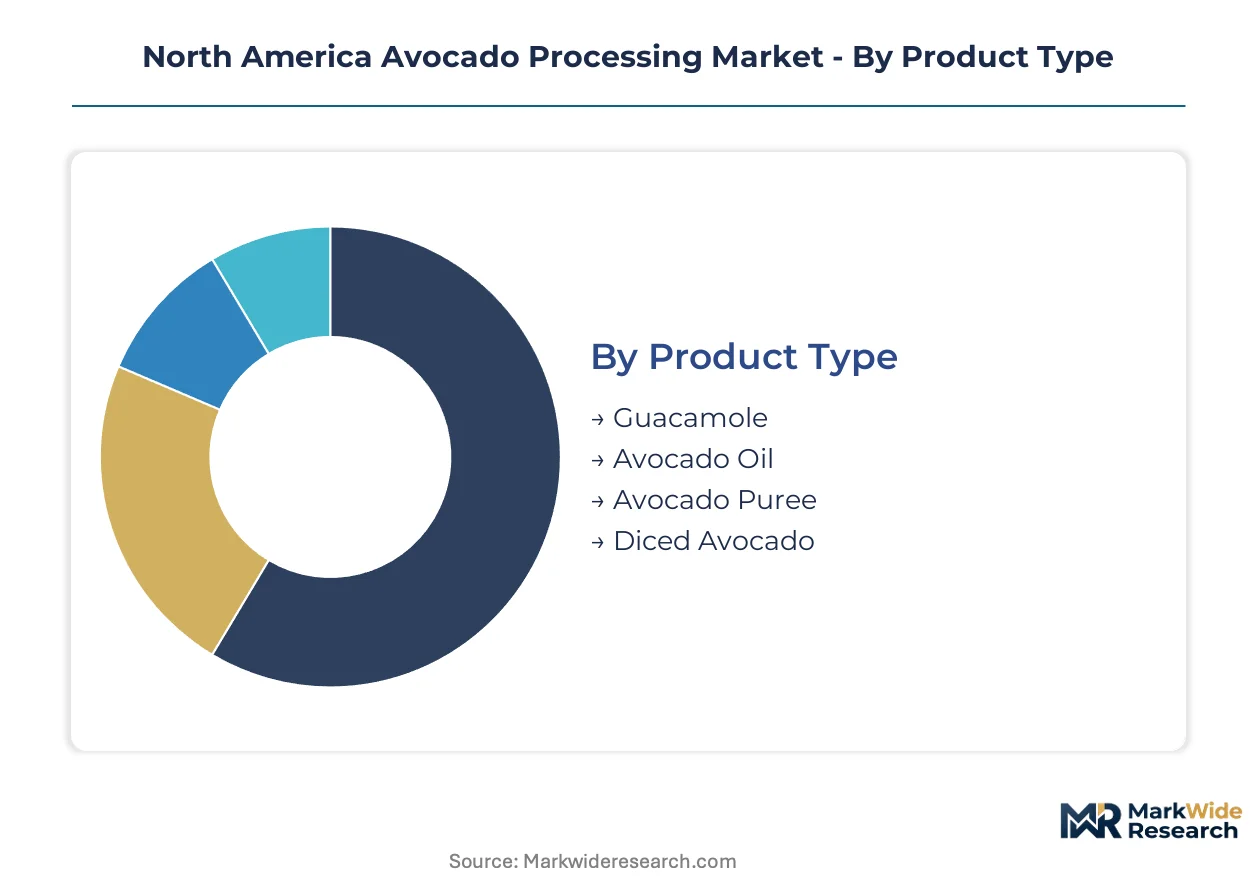
Avocado processing segmentation reveals how mechanical transformation, distribution logistics, and end-use specifications create distinct margin pools across North American supply chains. Category boundaries matter because HPP equipment investments and cold-chain requirements vary dramatically by product format and customer type.
Product Type:
Mature pasteurized formats dominate current throughput while emerging minimal-processing technologies are capturing premium positioning.
- Guacamole:Pasteurized or HPP-treated avocado pulp blended with acidulants and preservatives achieves 30-45 day refrigerated shelf life. California and Michoacán processors supply food service chains with specified Scoville heat units and pulp dry-matter content. Guacamole handles the majority of throughput; Avocado Oil is the fastest mover on share.
- Avocado Oil:Cold-pressed or centrifugally extracted oil with smoke points above 270°C commands cosmetic and culinary premium channels. Personal care manufacturers in California source unrefined grades for emollient applications. Demand concentrates in retail and cosmetic-adjacent channels where organic certification drives price premiums.
- Avocado Puree:Smooth, pumpable pulp with controlled enzymatic browning serves infant food and smoothie manufacturing.
- Diced Avocado:IQF or acidulated fresh-cut cubes target food service salad and bowl assembly operations.
Guacamole handles the majority of throughput; Avocado Oil is the fastest mover on share.
Application:
Volume concentration sits with institutional channels while margin expansion follows snack-food manufacturing specifications.
- Food Service:Restaurants, cafeterias, and institutional feeders procure ripeness-specified packs for just-in-time guacamole preparation. Texas and Southwest US markets anchor direct ripening-center partnerships with Mission Produce and West Pak Avocado. Food Service handles the majority of throughput; Snack Foods is the fastest mover on share.
- Food Manufacturing:Extruded and coated avocado applications require specified pulp dry-matter content from processors with controlled enzymatic browning capabilities. Snack-food manufacturers represent the steepest expansion trajectory as coated products proliferate.
- Retail:Grocery and club-store channels demand bilingual labeling under CFIA requirements for Canadian penetration.
- Snack Foods:Extruded, puffed, and coated avocado ingredients are expanding demand for specified pulp formulations.
Food Service handles the majority of throughput; Snack Foods is the fastest mover on share.
End User:
Procurement scale separates large institutional accounts from fragmented household demand.
- Restaurants:National chains negotiate volume commitments for specified ripeness-stage delivery, bypassing traditional distributor intermediaries. Direct ripening-center partnerships are displacing legacy procurement channels in Texas and Southwest markets. Restaurants handles the majority of throughput; Food Processors is the fastest mover on share.
- Food Processors:Secondary manufacturers require controlled enzymatic browning and specified pulp dry-matter content for extruded and coated product lines.
- Households:Small-volume purchasers increasingly source through online retail channels for home delivery.
- Catering Services:Event and contract feeders demand flexible ripeness specifications for batch preparation.
Restaurants handles the majority of throughput; Food Processors is the fastest mover on share.
Distribution Channel:
Direct relationships concentrate margin capture while digital channels fragment traditional wholesale structures.
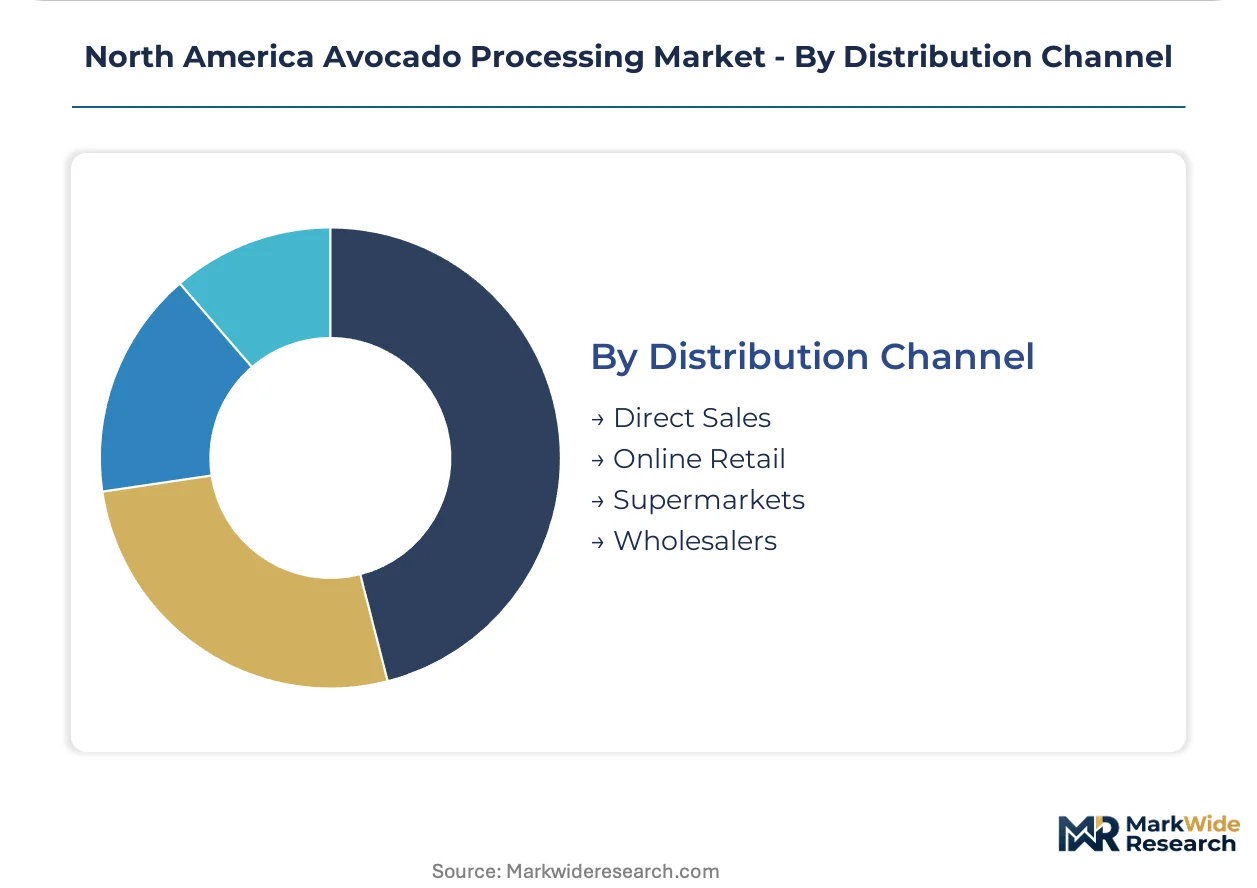
- Direct Sales:Integrated packer-shippers with captive ripening infrastructure capture margin pools previously held by fragmented regional handlers. Institutional volumes flow through direct ripening-center partnerships with specified delivery windows. Direct Sales handles the majority of throughput; Online Retail is the fastest mover on share.
- Supermarkets:California and Texas retail chains source retail-ready packs that bypass traditional ripening-center intermediation.
- Wholesalers:Traditional distributors face compression as food service operators consolidate procurement through direct partnerships.
- Online Retail:Household and small-restaurant procurement is gaining traction through e-commerce platforms.
Direct Sales handles the majority of throughput; Online Retail is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico-to-United States avocado flows dominate North American trade corridors, with Michoacán orchards supplying California and Texas processing hubs. Cross-border cold-chain infrastructure anchors volume throughput. Regulatory harmonization under USMCA shapes investment location decisions across the three-country bloc.
United States
California food service chains and snack-food manufacturers drive demand for HPP-treated guacamole and specified pulp formulations. FDA FSMA traceability mandates require lot-level tracking systems for processors serving institutional accounts. San Diego and Los Angeles processing corridors concentrate ripening-center infrastructure near border entry points.
Mexico
Michoacán-based packer-shippers control feedstock supply through integrated orchard-to-port operations. SENASICA phytosanitary certification requirements govern export eligibility to US and Canadian markets. Uruapan and Peribán processing clusters anchor high-volume pasteurized format production for cross-border shipment.
Canada
CFIA bilingual labeling requirements and import inspection protocols at Vancouver and Toronto ports filter compliant processors from non-compliant suppliers. Health Canada food safety regulations align with FDA frameworks while adding domestic inspection layers. British Columbia and Ontario retail channels represent underdeveloped penetration for US and Mexican suppliers meeting documentation standards.
North America Avocado Processing Market Key Industry Players
Channel-controlling players compete with product-specialist players across ripening infrastructure, processing technology, and retail-ready pack formats. The vendor base concentrates among integrated packer-shippers with captive orchard supply and regional processors dependent on spot feedstock markets. Two archetypes dominate: vertically integrated California-Mexico operators with ripening-center networks, and specialist guacamole manufacturers with HPP equipment access. Competitive moves center on cold-chain capacity expansion and direct food service procurement partnerships displacing traditional distributor intermediaries.
Within the integrated operator tier, Mission Produce and West Pak Avocado exemplify channel-controlling archetypes with cross-border infrastructure footprints. Calavo Growers occupies a specialist position focused on varietal development and ripening protocol R&D. These three entities anchor competitive dynamics through differentiated control points—Mission Produce through ripening-center density, West Pak Avocado through orchard-to-retail integration, and Calavo Growers through technical specification leadership.
| Leading Market Players |
|---|
| West Pak Avocado |
| Del Rey Avocado Co. |
| Calavo Growers |
| F&S Fresh Foods |
| Simplot Food Group |
| Mission Produce |
| Henry Avocado Corporation |
| Flagship Food Group |
| Index Fresh |
| Others |
Cost & Logistics Intelligence
Undercapacity in California HPP retrofit facilities is compressing lead times for food-service pasteurized formats and elevating spot pricing for processors without captive ripening infrastructure. Michoacán packer-shippers exploit this bottleneck through forward-contract premiums tied to SENASICA certification status.
Pricing Analysis
Thermal pasteurization versus HPP technology generations command divergent price bands, with legacy retort-processed guacamole occupying standard tiers and high-pressure treated formats capturing premium positioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by shelf-life specification and pulp dry-matter certification. Price differentiation hinges on FSMA traceability documentation and organic certification grade. Pricing pressure stems from California water-allocation rulings elevating orchard feedstock costs. Quick-service restaurant chains exhibit highest price sensitivity due to volume procurement scale, while cosmetic-adjacent oil extractors show lowest sensitivity given emollient-grade premiums.
Supply Chain Analysis
USMCA rules-of-origin documentation requirements function as de facto export controls limiting cross-border flow flexibility for processors with dual-country footprints. Geographic supply concentration centers on Mexico, the United States, and Canada. Raw material dependencies encompass Hass avocado feedstock, acidulant preservatives, and HPP equipment consumables. Supply chain risk manifests as SENASICA certification disruption creating single-source vulnerability. Distribution runs through direct ripening-center partnerships displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated food-service chains negotiating direct ripening-center partnerships, fragmenting traditional distributor influence across Texas and Southwest procurement corridors.
For Market Incumbents: Insulate margin pools by deepening captive ripening infrastructure in California and Michoacán processing corridors. Secure SENASICA certification redundancy across multiple orchard zones to mitigate phytosanitary disruption threats. Prioritize HPP technician training partnerships with equipment OEM service networks to address skill scarcity constraining capacity expansion. For New Entrants and Emerging Players: Canadian retail channels through British Columbia and Ontario ports represent the most penetrable entry point given CFIA bilingual labeling barriers filtering incumbent competition. Cosmetic-adjacent oil extraction for personal care manufacturers offers white-space margin expansion beyond food-service saturation. Pursue private-label partnerships with club-store buyers seeking compliant import documentation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated packer-shippers with forward-contract food-service volume commitments. Long-term viability over the medium-term projection horizon favors processors with dual-country USMCA qualification and HPP equipment access. Acquisition targets should demonstrate ripening-center density in border-adjacent geographies. Watch SENASICA audit intensity as inflection signal for supply concentration risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| HPP Capacity Expansion | Retrofit investments enable direct-to-retail packs bypassing ripening intermediaries. |
| Backward Integration into Ripening Infrastructure | Captive ripening centers anchor just-in-time delivery commitments with Mission Produce scale. |
| FSMA Traceability System Deployment | Lot-level tracking satisfies FDA mandates for institutional food-service accounts. |
| Cosmetic-Grade Oil Certification | Organic emollient positioning unlocks personal care manufacturer premiums beyond food channels. |
| USMCA Origin Documentation Investment | Granular provenance systems defend cross-border qualification under evolving treaty interpretation. |
Research Approach
A standing panel of ripening-center operations directors, food-service procurement managers, SENASICA compliance officers, and HPP equipment technicians provided ongoing calibration across the study period. Primary interview data combined with secondary validation from USDA grading standards, FDA FSMA guidance documents, CFIA import inspection protocols, and USMCA rules-of-origin advisory circulars. Bottom-up volume modeling triangulated against top-down trade flow analysis.
Scenario bracketing anchored the analytical framework across the projection horizon, with demand elasticity tested against water-allocation ruling severity and phytosanitary disruption frequency. Segmentation dimensions encompassed product format, application channel, end-user scale, and distribution structure. CAGRs derived from trend extrapolation moderated by capacity constraint assumptions and technology adoption S-curves. Forecast inputs included California orchard yield variance and HPP equipment depreciation schedules.
Macroeconomic conditions sit as an overlay; deviation in food-service employment levels and cross-border logistics costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology cost curves. Material shifts in USMCA interpretation or SENASICA certification protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables Processing Equipment
Global Fruit and Vegetable Processing Market
Fruits and Vegetables Processing Equipment
Juice Extraction Equipment Market
Fruits and Vegetables Processing Equipment
Portable Juicer Market
Fruits and Vegetables Processing Equipment
Fruit Tree Shaker Market
Fruits and Vegetables Processing Equipment
Global Fruit Processing Equipment Market
Fruits and Vegetables Processing Equipment
Smart Juicer Machine Market
Fruits and Vegetables Processing Equipment
Avocado Processing Market
Fruits and Vegetables Processing Equipment
Juicer Market
Fruits and Vegetables Processing Equipment
Tomato Processing Market
Fruits and Vegetables Processing Equipment
Fruit and Vegetable Processing Equipment Market
Fruits and Vegetables Processing Equipment
Juice Extractors Market
Fruits and Vegetables Processing Equipment
Grape Crusher Market
Fruits and Vegetables Processing Equipment
Smart Juicer Market