
 Juicer Market | 2026-2036
Juicer Market Size, Share, and Industry Trends Forecast 2026-2036
Juicer Market Analysis
Stainless steel is decoupling juicer construction from petroleum-based plastic dependence as manufacturers respond to durability expectations and thermal stability requirements. Breville Group Ltd leverages its Australian engineering heritage to sustain premium positioning in high-wattage centrifugal systems across English-speaking markets. Koninklijke Philips N.V. anchors European distribution through broad retail partnerships and connected-kitchen ecosystem integration. Omega Juicers specializes in slow-juice extraction technology that competes on nutrient-retention claims in North American wellness channels.
A juicer is an electromechanical appliance designed to extract liquid from fruits, vegetables, and leafy greens through mechanical compression or high-speed centrifugal force, typically operating at rotational speeds ranging from 80 RPM for masticating units to 15,000 RPM for centrifugal designs. Its primary commercial purpose spans residential meal preparation, hospitality beverage programs, and health-club refreshment operations where fresh extraction replaces pre-packaged alternatives. Masticating and triturating types capture the strongest margin pools as consumers trade up from entry-level centrifugal models toward cold-press systems with longer shelf-life output. Stainless steel housings lead material preference in commercial and premium residential tiers, while plastic dominates volume shipments in emerging Asian markets where first-time appliance penetration drives affordability requirements.
The US Food and Drug Administration governs food-contact surface safety for juicer components, while the EU REACH regulation restricts hazardous substances in polymer housings and rubber gaskets, effectively filtering lower-cost imports from European retail shelves. China's SAMR enforces GB standards for small-appliance electrical safety and electromagnetic compatibility, creating a compliance threshold that shapes export manufacturing footprints. Japan's METI administers appliance efficiency labeling that influences power-rating segmentation and consumer purchasing decisions in that market. Stakeholders must monitor evolving food-contact chemical restrictions and energy-efficiency mandates as these regulatory vectors increasingly determine which product architectures achieve market access in priority geographies.
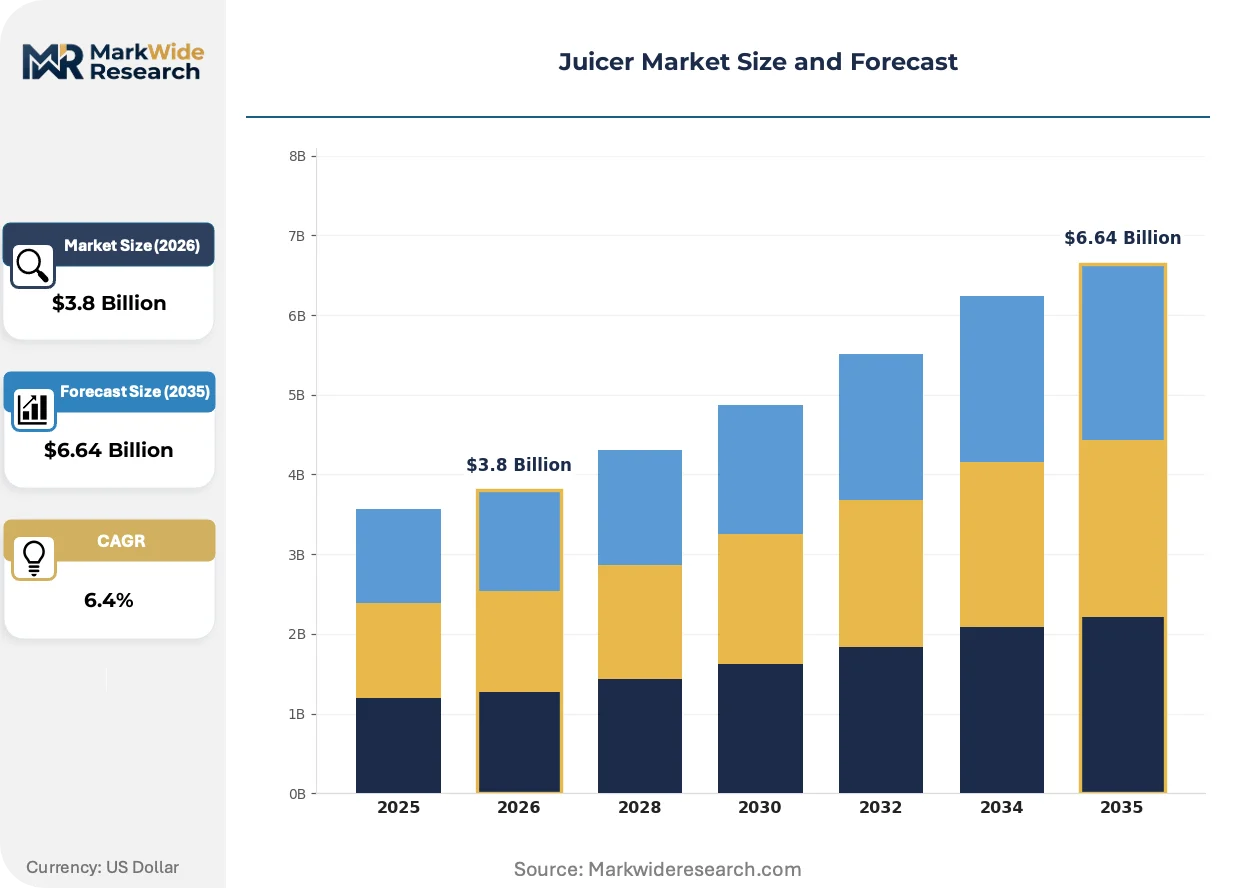
Market Dynamics
Stainless steel housings are decoupling premium juicer construction from petroleum-based plastics as REACH chemical restrictions and thermal stability requirements tighten across European retail channels. This material pivot compresses margin structures for low-cost manufacturers while elevating compliance costs as a competitive filter.
Growth Catalysts
- Cold-press nutrient retention claims:Wellness studios and health clubs in the United States are expanding fresh-pressed juice programs to replace pre-packaged alternatives, driving masticating unit adoption.
- EU REACH polymer restrictions:Hazardous substance limits on rubber gaskets and plastic housings are filtering lower-cost imports from European shelves, creating shelf-space openings for compliant stainless steel models.
- Japan METI efficiency labeling:Mandatory appliance energy ratings are segmenting power-rated offerings and steering consumer purchases toward premium efficient designs.
Market Restraints
- Stainless steel input volatility:Nickel and chromium price swings compress tooling amortization schedules for manufacturers transitioning from plastic-dominant architectures.
- Centrifugal technology ceiling:High-speed oxidation limits shelf-life of extracted juice to minutes, constraining commercial batch preparation and food-service adoption.
- China SAMR electromagnetic compliance:GB standard certification timelines extend export manufacturing footprints by 8-14 weeks for non-domestic producers.
Strategic Opportunities
- India first-time appliance penetration:Plastic-dominated volume shipments target affordability requirements in emerging urban households with limited existing small-appliance ownership.
- Connected-kitchen ecosystem integration:Smart home platform compatibility enables subscription-based consumable replenishment and usage analytics for premium residential tiers.
- German boutique wellness studio expansion:Cold-press program adoption in Berlin, Munich, and Hamburg commercial fitness chains creates B2B equipment refresh cycles.
Industry Challenges
- Multi-jurisdictional food-contact certification:FDA, EFSA, and Japan's Food Sanitation Act create divergent testing protocols that fragment R&D resource allocation.
- Legacy motor supplier concentration:Dependence on specialized high-torque brushless motor producers in East Asia creates vulnerability during semiconductor allocation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Juicer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Centrifugal, Masticating, Triturating, Juicing Machine End User: Residential, Commercial, Health Clubs, Hotels Material: Plastic, Stainless Steel, Glass, Aluminum Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Breville Group Ltd, Koninklijke Philips N.V., Panasonic Corporation, Hamilton Beach Brands Holding Co., Electrolux AB, Omega Juicers, Cuisinart Inc., Hurom America Inc., Kuvings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Juicer Market Emerging Trajectories
Juicer engineering is pivoting from extraction speed toward output quality preservation, with thermal management and oxidation control becoming the primary axes of product differentiation. Three converging developments are compressing traditional centrifugal dominance.
Cold-press auger systems operating at 80 RPM are rewriting the performance benchmark for nutrient retention in leafy green extraction. Boutique wellness studios across California and New York are replacing centrifugal fleets with masticating units that extend juice shelf-life from minutes to 72 hours. This compression of oxidation timelines is enabling centralized commissary production models that reduce labor costs per location.
EU REACH Annex XVII restrictions on phthalates and heavy metals in food-contact polymers are accelerating stainless steel adoption across German and French retail channels. Manufacturers with existing metal-stamping capabilities are capturing shelf space vacated by non-compliant imports. The regulation is most acute for entry-level plastic housings targeting price-sensitive Southern European markets.
Direct-to-consumer subscription models for produce boxes paired with juicer financing are displacing traditional big-box retail in United States urban markets. Millennial households in Austin, Denver, and Seattle are accepting 24-month equipment leases bundled with organic vegetable delivery. This channel shift concentrates customer acquisition spend toward digital platforms and away from in-store demonstration investments.
Juicer Market Segmentation
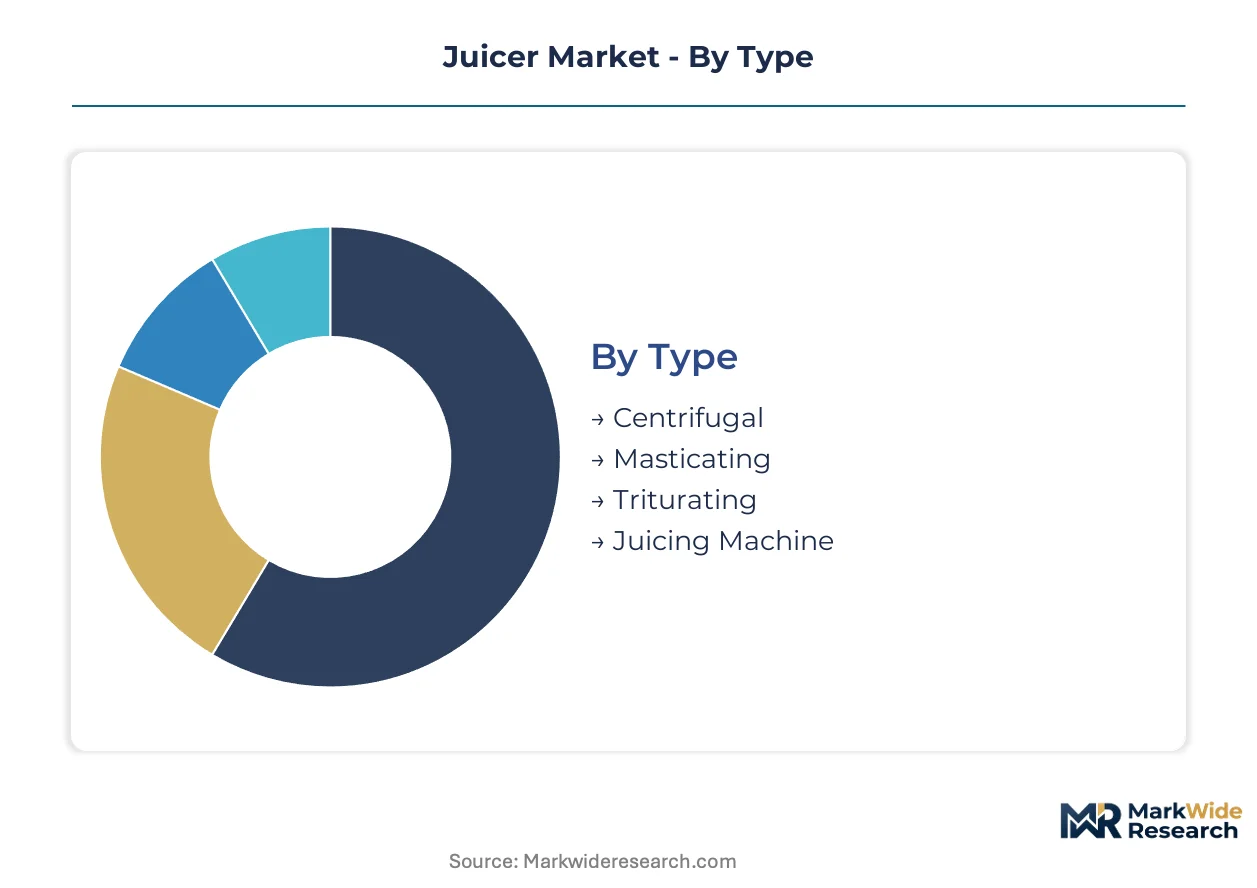
Juicer segmentation tracks the divergence between entry-level convenience and premium extraction performance. Manufacturers configure product architectures around motor torque, housing durability, and oxidation control to match distinct usage intensities and replacement cycles across consumer and commercial tiers.
Type:
Standalone countertop units dominate residential placement, while embedded systems integrate into commercial kitchen suites and health-club refreshment stations.
- Centrifugal:High-speed blade systems operating at 15,000 RPM extract juice through rapid centrifugal force. Demand concentrates in United States big-box retail channels where price-sensitive first-time buyers prioritize speed over nutrient retention.
- Masticating:Single-auger cold-press designs rotating at 80 RPM minimize heat and oxidation. Wellness studios in California and New York are replacing centrifugal fleets with these units to extend juice shelf-life from minutes to 72 hours, enabling centralized commissary production.
- Triturating:Twin-gear crushing systems apply simultaneous grinding and pressing action for maximum yield from leafy greens.
- Juicing Machine:Automated self-contained systems with integrated pulp ejection and continuous feed capabilities.
Volume placements concentrate in Centrifugal; the faster expansion belongs to Masticating.
End User:
Cost tier separation shapes distribution architecture, with direct-to-consumer platforms capturing premium residential tiers and institutional procurement governing commercial segments.
- Residential:Individual household acquisition through retail and e-commerce channels. German consumers are trading up from entry centrifugal models toward cold-press systems with longer shelf-life output, compressing replacement cycles.
- Commercial:Food-service operations and institutional kitchens requiring batch production capacity. Japan's METI efficiency labeling steers procurement toward premium power-rated designs that reduce operational energy costs.
- Health Clubs:Boutique fitness studios and wellness centers operating fresh-pressed juice programs. United States health clubs are expanding these programs to replace pre-packaged alternatives, driving masticating unit adoption.
- Hotels:Hospitality beverage programs in full-service and luxury properties.
Residential accounts for the largest unit base; Health Clubs are climbing the fastest as wellness programming expands.
Material:
Supply concentration in metalworking regions versus petrochemical basins determines regional manufacturing footprints and export competitiveness.
- Plastic:Polymer housings dominate volume shipments in emerging Asian markets where first-time appliance penetration drives affordability requirements. India's urban households with limited existing small-appliance ownership prioritize these entry-level units.
- Stainless Steel:Nickel-chromium alloy construction meets EU REACH chemical restrictions on food-contact surfaces. German and French retail channels are accelerating adoption as non-compliant imports vacate shelf space.
- Glass:Borosilicate collection vessels and viewing chambers for premium aesthetic positioning.
- Aluminum:Lightweight die-cast housings for portable and travel-oriented product lines.
Plastic retains the highest shipment volumes; Stainless Steel is gaining share fastest on regulatory compliance advantages.
Power Rating:
Customer type segmentation separates occasional home users from high-throughput commercial operators with divergent torque and thermal management requirements.
- Low Power:Compact motors under 200 watts for intermittent residential use. These units suit Japanese apartment dwellers where METI efficiency labels influence purchasing decisions toward minimal energy draw.
- Medium Power:Mid-range motors balancing extraction speed with noise control for daily household operation.
- High Power:Robust induction motors sustaining continuous batch cycles. United States health clubs deploy these units for morning rush production of green juice blends.
- Ultra High Power:Industrial-grade systems exceeding 1000 watts for commercial commissary and hotel central kitchen installations.
Medium Power holds the broadest placement; High Power is expanding most quickly on commercial wellness program adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan, where premium masticating models command sustained retail placement and cold-press nutrient retention claims drive commercial wellness program adoption.
United States
Health clubs and boutique wellness studios across California and New York are expanding fresh-pressed juice programs to replace pre-packaged alternatives. FDA food-contact surface safety standards govern juicer component compliance. Austin, Denver, and Seattle millennial households are accepting equipment leases bundled with organic vegetable delivery through direct-to-consumer subscription models.
Germany
Consumers are trading up from entry centrifugal models toward cold-press systems with longer shelf-life output, compressing replacement cycles. EU REACH Annex XVII restrictions on phthalates and heavy metals in food-contact polymers are filtering lower-cost imports from retail shelves. Berlin, Munich, and Hamburg commercial fitness chains are driving B2B equipment refresh cycles through boutique wellness studio expansion.
Japan
METI appliance efficiency labeling is segmenting power-rated offerings and steering consumer purchases toward premium efficient designs. Japanese apartment dwellers prioritize low-power compact motors under 200 watts where minimal energy draw influences purchasing decisions. Tokyo and Osaka metropolitan areas concentrate demand for mid-range motors balancing extraction speed with noise control.
India
First-time appliance penetration in emerging urban households with limited existing small-appliance ownership is driving plastic-dominated volume shipments prioritizing affordability. BIS electrical safety standards and electromagnetic compatibility requirements shape import compliance thresholds. Maharashtra and Gujarat manufacturing clusters are scaling export production footprints to serve price-sensitive South Asian markets.
China
SAMR GB standards for small-appliance electrical safety and electromagnetic compatibility create compliance thresholds that extend export manufacturing footprints by 8-14 weeks for non-domestic producers. Dual carbon goals are pressuring energy efficiency improvements across domestic appliance manufacturing. Yangtze River Delta and Pearl River Delta industrial basins concentrate motor supplier networks for high-torque brushless systems.
Juicer Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers pivot from petroleum-based plastics toward stainless steel architectures under tightening chemical restrictions. The vendor base spans consolidated multinational appliance conglomerates with broad retail partnerships and specialized cold-press engineering houses with narrow wellness channel focus. Three archetypes define competitive positioning: Australian-engineered high-wattage centrifugal specialists, European connected-kitchen ecosystem integrators, and North American nutrient-retention technology pure-plays. M&A activity and vertical integration into motor supply chains represent the dominant competitive moves as semiconductor allocation cycles expose supplier concentration risks.
Within the premium-tier vector, Breville Group Ltd leverages its Australian engineering heritage to sustain positioning in high-wattage centrifugal systems across English-speaking markets. Koninklijke Philips N.V. anchors European distribution through broad retail partnerships and exemplifies the connected-kitchen ecosystem integrator archetype. Omega Juicers occupies a position as a North American nutrient-retention technology specialist competing on cold-press extraction claims in wellness channels.
| Leading Market Players |
|---|
| Breville Group Ltd |
| Koninklijke Philips N.V. |
| Panasonic Corporation |
| Hamilton Beach Brands Holding Co. |
| Electrolux AB |
| Omega Juicers |
| Cuisinart Inc. |
| Hurom America Inc. |
| Kuvings |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in German and Italian metalworking regions are consolidating stainless steel stamping capacity to defend margin structures against nickel price volatility, while their pricing discipline filters through to premium-tier placement in EU retail channels. This ownership concentration tightens supply response times and elevates compliance investment as a competitive barrier against plastic-dependent imports.
Pricing Analysis
Volume placements concentrate in plastic-dominated centrifugal units where affordability requirements in emerging Asian markets compress absolute margins, while premium masticating systems capture superior returns through nutrient-retention claims and extended shelf-life performance. Three-tier pricing structure across premium, standard, and economy levels separates stainless steel cold-press models from mid-range hybrid designs and entry-level plastic centrifugal units. Pricing pressure stems from nickel and chromium input volatility that compresses tooling amortization schedules for manufacturers transitioning from petroleum-based architectures. Health clubs and boutique wellness studios exhibit the lowest price sensitivity as operational uptime and juice quality consistency override capital expenditure considerations, while first-time appliance buyers in India and Southeast Asia prioritize unit acquisition cost above performance specifications.
Supply Chain Analysis
Brushless motor supply rests on specialized producers concentrated in China's Yangtze River Delta and Pearl River Delta industrial basins, creating semiconductor allocation vulnerability during cyclical shortages. Nickel-chromium alloy feedstock draws from Indonesian and Philippine mining operations processed through Chinese and South Korean smelting facilities, while precision metal stamping capacity clusters in Germany, Italy, and Japan. Single-source vulnerability in high-torque motor controllers exposes non-integrated manufacturers to 8-14 week procurement delays. Distribution runs through big-box retail partnerships in the United States, specialized kitchen equipment distributors in Germany and France, and direct-to-consumer digital platforms capturing subscription-financed residential placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Juicer manufacturing is becoming a vertical-integration race as players pursue captive supply of high-torque brushless motors to insulate against semiconductor allocation cycles and supplier concentration risks.
For Market Incumbents: Anchor cold-press technology leadership through backward integration into auger machining and motor winding capabilities, while defending shelf position against stainless steel-compliant imports by accelerating EU REACH certification across full product portfolios. Consolidate procurement relationships with Indonesian nickel processors to hedge input cost volatility. For New Entrants and Emerging Players: Direct-to-consumer wellness platforms represent the most penetrable channel vector for masticating unit introduction, bypassing established retail gatekeepers through subscription-based equipment financing bundled with organic produce delivery. Target United States millennial households in secondary metropolitan areas where health-club juice program adoption is accelerating but local equipment supply remains fragmented. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized cold-press engineering houses with narrow wellness channel focus and proprietary auger geometries, particularly those with manufacturing footprints in Vietnam or Mexico that mitigate tariff exposure. Long-term viability hinges on ecosystem integration capabilities and motor supply chain control. Watch for FDA food-contact surface rulemaking expansion as an inflection signal for compliance-cost driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Manufacturing | Captive high-torque brushless production insulates against semiconductor allocation cycles affecting Yangtze River Delta suppliers. |
| EU REACH Compliance Certification | Stainless steel housing validation unlocks shelf space in German and French retail channels filtering non-compliant imports. |
| Direct-to-Consumer Subscription Launch | Equipment leasing bundled with organic produce delivery captures Austin, Denver, and Seattle millennial households. |
| Cold-Press Technology Licensing | Auger system IP monetization enables wellness studio chains to deploy centralized commissary production models. |
| Indonesian Nickel Supply Partnership | Upstream feedstock control hedges chromium and nickel price volatility compressing premium-tier margin structures. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, while primary interviews with appliance product managers, wellness studio operators, retail category buyers, and metal stamping facility directors provided operational validation. FDA 510(k) food-contact surface submissions, EU ECHA REACH registration databases, and Japan METI efficiency labeling disclosures supplied compliance benchmarking. SAMR GB standard certification timelines and BIS electrical safety registrations informed export manufacturing footprint analysis. Bottom-up unit shipment tallies triangulated against top-down consumer expenditure estimates.
Data-stream reconciliation across manufacturer production schedules, retail inventory turns, and end-user procurement cycles informed the analytical framework. Segmentation dimensions modeled include juicer type, end-user category, housing material specification, and power rating tier across the projection horizon. CAGRs derived from curve-fitting historical shipment trajectories against penetration saturation assumptions. Forecast inputs incorporated health-club wellness program expansion rates, EU chemical restriction phase-in timelines, and nickel price volatility indices.
Caveats apply where FDA food-contact surface rulemaking expansion, EU REACH Annex XVII amendment, or nickel supply disruption could materially shift the outlook. Forecasts reflect assumptions regarding wellness channel adoption velocity and stainless steel cost normalization. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables Processing Equipment
Avocado Processing Market
Fruits and Vegetables Processing Equipment
Juice Extractors Market
Fruits and Vegetables Processing Equipment
Smart Juicer Market
Fruits and Vegetables Processing Equipment
Global Fruit Processing Equipment Market
Fruits and Vegetables Processing Equipment
Juice Extraction Equipment Market
Fruits and Vegetables Processing Equipment
Fruit and Vegetable Processing Equipment Market
Fruits and Vegetables Processing Equipment
Grape Crusher Market
Fruits and Vegetables Processing Equipment
Tomato Processing Market
Fruits and Vegetables Processing Equipment
North America Avocado Processing Market
Fruits and Vegetables Processing Equipment
Portable Juicer Market
Fruits and Vegetables Processing Equipment
Global Fruit and Vegetable Processing Market
Fruits and Vegetables Processing Equipment
Smart Juicer Machine Market
Fruits and Vegetables Processing Equipment
Fruit Tree Shaker Market