
 Juice Extraction Equipment Market | 2026-2036
Juice Extraction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Juice Extraction Equipment Market Foresight
OEM-direct and distributor channels for juice extraction equipment is fragmenting as regional food processors seek localized service and faster spare parts turnaround. GEA Group AG leverages its global service network to anchor premium contracts with multinational beverage brands. Bucher Unipektin AG specializes in apple and pear processing lines, dominating Central European orchard cooperatives. Alfa Laval AB competes on thermal integration, bundling extraction with pasteurization systems to extend plant-level energy efficiency.
Juice extraction equipment encompasses mechanical systems designed to rupture cell walls of fruits and vegetables while separating liquid from pulp, operating at pressures ranging from 100 bar in hydraulic presses to 3,000 RPM in centrifugal configurations, primarily serving commercial juice production and ingredient supply chains. Cold press juicers command margin pools due to enzyme preservation and extended shelf-life claims, while centrifugal units retain volume leadership in high-throughput processing facilities. Electric technology leads installed base across industrial settings, though pneumatic systems occupy niche positions where explosion-proof ratings govern winery and distillery applications.
FDA food safety modernization rules shape equipment hygiene standards, mandating clean-in-place protocols and stainless-steel contact surfaces that elevate capital costs for U.S.-bound suppliers. EFSA and CE marking requirements across Europe enforce motor efficiency tiers and noise emission limits, filtering non-compliant Asian manufacturers from premium tender processes. Stakeholders must weigh regulatory compliance investments against channel expansion timelines, as diverging national standards complicate platform standardization strategies.
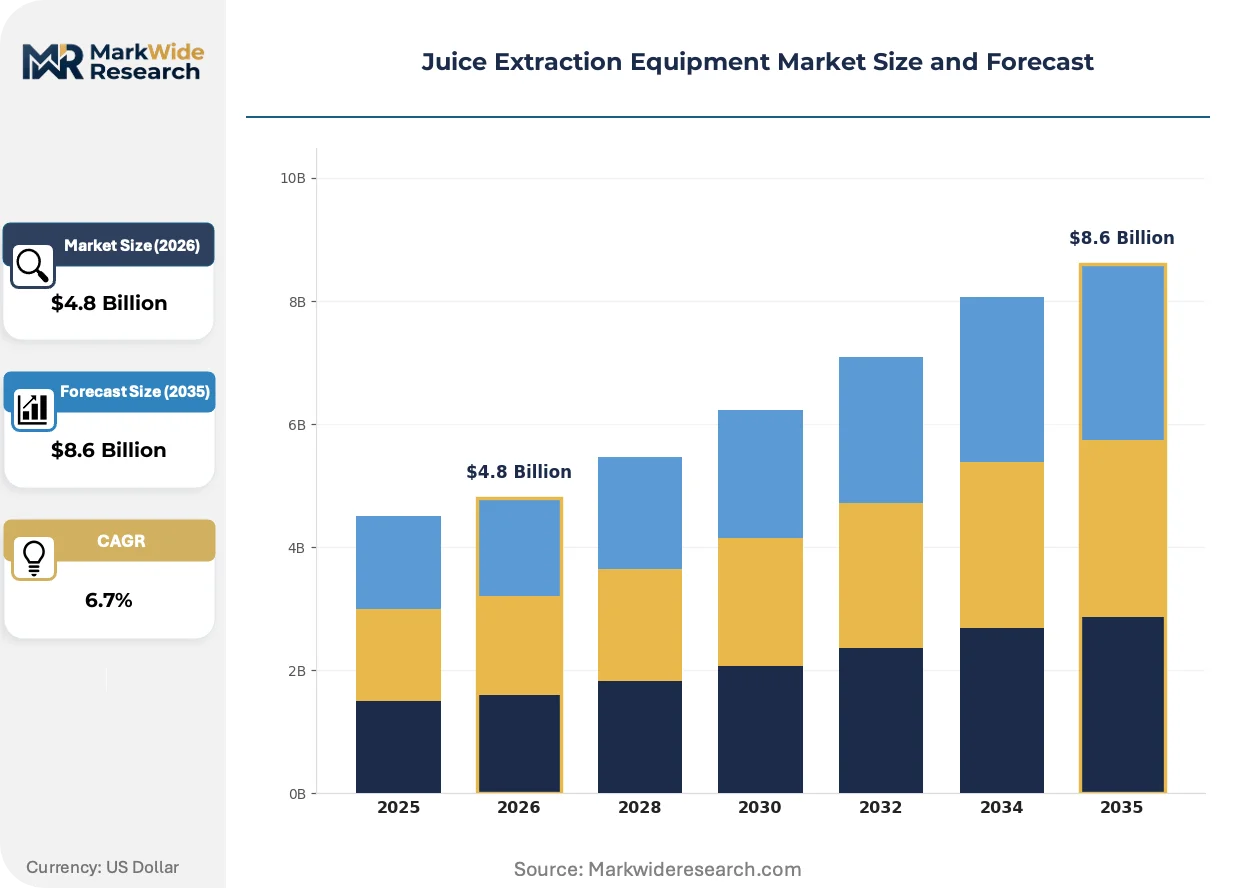
Market Dynamics
Cold press technology adoption is compressing centrifugal equipment margins while FDA nutritional labeling requirements force processors to upgrade extraction systems for enzyme retention claims. Equipment vendors now compete on total cost of ownership rather than throughput metrics alone.
Growth Catalysts
- FDA Food Safety Modernization Act:Mandates for clean-in-place protocols drive replacement cycles in U.S. citrus processing facilities. Stainless-steel contact surface requirements elevate capital expenditure thresholds for new market entrants.
- São Paulo citrus cluster concentration:Brazil's orange juice processing corridor generates sustained equipment procurement from multinational concentrate suppliers. Regional cooperatives expand capacity to meet export contract specifications.
- Enzyme preservation technology:Cold press systems extend shelf-life claims for premium juice brands. Retailers command HPP-compatible extraction lines as condition of shelf placement.
Market Restraints
- Stainless steel input volatility:Grade 316L price swings compress fabrication margins for European equipment builders. Foundry capacity constraints in Germany extend lead times for pressure vessel components.
- CE marking compliance costs:EFSA motor efficiency tiers and noise emission limits filter non-compliant Asian manufacturers from premium tender processes. Certification timelines stretch 14-18 months for new platform introductions.
- High-pressure processing substitution:HPP tolling services reduce capital requirements for mid-tier juice brands. Third-party processing networks displace in-house extraction investments in North American metropolitan markets.
Strategic Opportunities
- India FSSAI enforcement expansion:Packaged juice safety standards tighten across Maharashtra and Karnataka processing zones. Domestic equipment fabricators lack cold press capability, creating import substitution windows.
- Smart factory convergence:IoT-enabled extraction systems integrate yield optimization algorithms with predictive maintenance modules. Early deployments in Dutch tomato processing demonstrate 12% throughput gains.
- Direct-to-procurement platforms:Equipment-as-a-service models bypass traditional distributor networks for orchard cooperatives. Subscription pricing lowers barrier to precision extraction technology for small-batch producers.
Industry Challenges
- Clean-in-place engineering scarcity:Specialized sanitation system designers command premium compensation. Equipment builders compete with pharmaceutical and dairy sectors for identical talent pools.
- Legacy analog control integration:Digital retrofit kits face compatibility failures with 1990s-era hydraulic press architectures. Plant engineers resist full line replacement due to footprint constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Juice Extraction Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Juicers, Cold Press Juicers, Masticating Juicers, Hydraulic Presses End User: Food Processing Industry, Restaurants, Cafés, Home Users Technology: Hydraulic Technology, Pneumatic Technology, Electric Technology, Manual Technology Application: Fruit Juicing, Vegetable Juicing, Smoothies, Others |
| Companies Covered | Bucher Unipektin AG, GEA Group AG, JBT Corporation, Zumex Group S.A., Alfa Laval AB, Tetra Pak International S.A., Krones AG, FENCO Food Machinery S.r.l., Bertuzzi Food Processing S.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Juice Extraction Equipment Market Shifts & Advancements
Extraction technology is converging with adjacent processing stages as energy efficiency mandates compress equipment footprints. Vendors bundle thermal integration and digital monitoring to differentiate beyond mechanical performance.
Pneumatic-hydraulic hybrid press systems is hybridizing juice extraction architectures for winery and distillery applications requiring explosion-proof ratings. California and Bordeaux vintners adopt these configurations to process pomace while satisfying OSHA and French labor safety inspectorate requirements. The technology compresses capital expenditure gaps between premium cold press and standard centrifugal alternatives.
EU F-Gas Regulation phase-down schedules accelerate refrigerant-dependent extraction system obsolescence. Thermal integration bundling—combining extraction with pasteurization heat recovery—becomes mandatory for CE marking compliance in German and Italian processing facilities. Equipment tenders now specify coefficient of performance thresholds that disqualify standalone extraction units.
Service unbundling disrupts traditional OEM maintenance contracts as regional food processors seek localized spare parts turnaround. Third-party technical service networks in São Paulo and Valencia challenge GEA Group AG and Bucher Unipektin AG captive service organizations. Procurement teams negotiate component-level agreements rather than comprehensive maintenance packages, compressing vendor margin pools.
Juice Extraction Equipment Market Segmentation
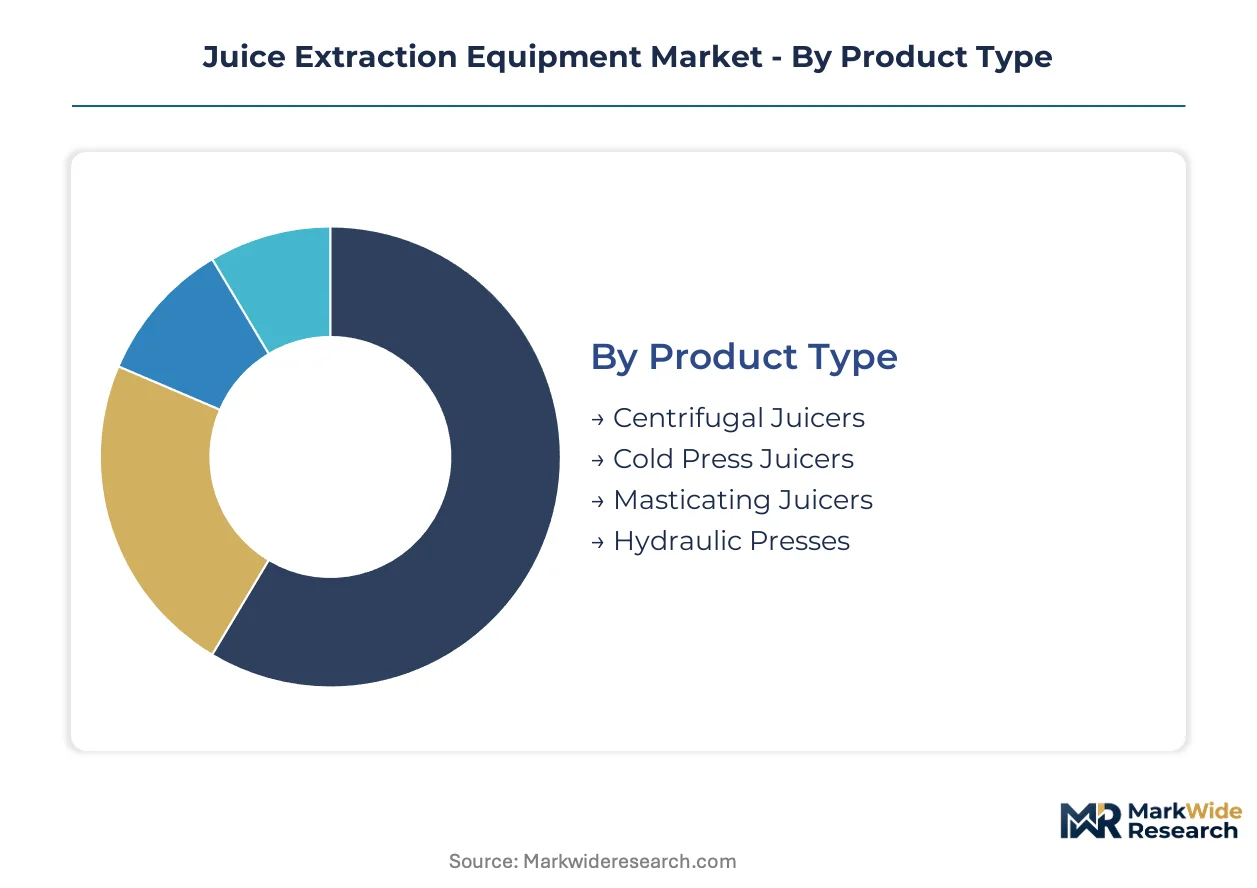
Segmentation in juice extraction equipment reveals how procurement priorities diverge across operational scales and regulatory environments. Equipment specifications, power systems, and end-use applications each create distinct margin pools and compliance obligations that shape vendor positioning strategies.
Product Type:
Cost tier stratification in extraction equipment reflects capital intensity trade-offs between throughput volume and nutritional retention specifications.
- Cold Press Juicers:Hydraulic and slow-rotating auger systems operate at 80-100 RPM to minimize heat generation and preserve enzyme activity. São Paulo citrus processors deploy these for not-from-concentrate export grades where FDA nutritional labeling substantiates premium shelf positioning.
- Centrifugal Juicers:High-speed blade assemblies at 3,000-14,000 RPM deliver rapid liquid separation through centrifugal force. High-throughput facilities in Brazil's processing corridors specify these for concentrate production where thermal degradation is acceptable.
- Masticating Juicers:Single-gear auger designs crush produce against static screens for small-batch commercial operations.
- Hydraulic Presses:Batch-mode rack-and-cloth systems apply 100-400 bar pressure for winery pomace and premium juice applications.
Centrifugal equipment holds installed capacity. Cold press configurations are rotating up the share rankings.
End User:
Customer type determines service intensity requirements and equipment durability specifications across deployment environments.
- Food Processing Industry:Industrial-scale installations require clean-in-place protocols and stainless-steel contact surfaces mandated by FDA Food Safety Modernization Act compliance. São Paulo concentrate suppliers and Dutch tomato processors anchor procurement volume for continuous-feed systems with predictive maintenance modules.
- Restaurants:Front-of-house visibility demands compact footprints with noise emission controls below 70 decibels for CE marking compliance in European Union food service deployments.
- Cafés:Mid-volume throughput specifications balance speed claims against ingredient waste metrics for specialty beverage menus.
- Home Users:Consumer-grade electrical safety certifications and dishwasher-compatible components dominate purchasing criteria.
Food processing industry holds installed capacity. Restaurants are rotating up the share rankings.
Technology:
Power system selection governs operational safety ratings and energy efficiency compliance across regulatory jurisdictions.
- Electric Technology:Three-phase motor configurations dominate industrial installed base with integrated variable frequency drives for yield optimization. EFSA motor efficiency tiers and EU F-Gas Regulation thermal integration requirements filter non-compliant equipment from German and Italian tender processes.
- Hydraulic Technology:Fluid power systems deliver consistent pressure profiles for cold press applications where mechanical precision controls extraction yield variance.
- Pneumatic Technology:Compressed air actuation satisfies explosion-proof ratings required by OSHA for California and Bordeaux winery pomace processing in volatile organic compound environments.
- Manual Technology:Hand-cranked lever systems occupy artisanal and demonstration niche positions with minimal regulatory compliance burden.
Electric technology holds installed capacity. Pneumatic-hydraulic hybrid configurations are rotating up the share rankings.
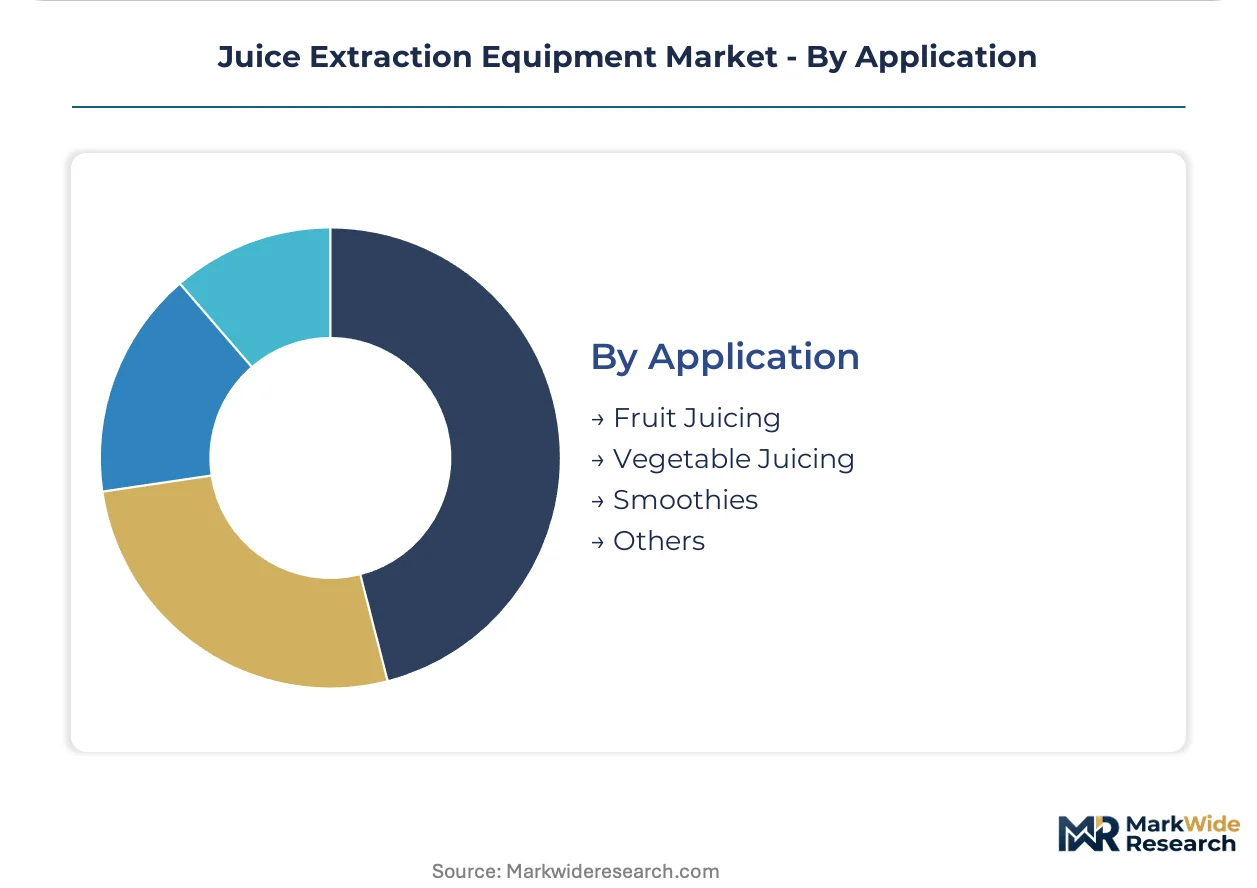
Application:
Volume concentration varies by raw material characteristics and downstream shelf-life requirements.
- Fruit Juicing:Citrus, pome, and stone fruit processing drives equipment specification for acid-resistant contact surfaces and oil recovery integration. Brazil's orange juice export infrastructure generates sustained procurement for multi-stage extraction lines.
- Vegetable Juicing:Fibrous root vegetables and leafy greens demand auger torque ratings and screen aperture optimization distinct from fruit parameters.
- Smoothies:Whole-food blending requirements extend equipment scope to homogenization and particle size distribution control.
- Others:Nut milk, botanical extraction, and functional ingredient applications create specialized attachment and sanitation protocol demands.
Fruit juicing holds installed capacity. Vegetable juicing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos container terminal underwrites Brazil's dominance in orange juice concentrate exports, connecting São Paulo state processing corridors to European and Asian markets. This maritime infrastructure anchors procurement cycles for industrial-scale extraction systems serving multinational beverage suppliers.
United States
California's Central Valley vegetable processing and Florida's citrus belt drive equipment demand for high-throughput facilities. FDA Food Safety Modernization Act mandates for clean-in-place protocols accelerate replacement cycles in concentrate plants. The Port of Tampa Bay corridor hosts retrofit activity as processors upgrade stainless-steel contact surfaces for export compliance.
Germany
Baden-Württemberg orchard cooperatives and Bavarian beverage conglomerates sustain premium equipment procurement. EFSA motor efficiency tiers and EU F-Gas Regulation thermal integration requirements filter non-compliant Asian vendors from tender processes. The Stuttgart industrial zone concentrates service unbundling activity as regional processors negotiate component-level maintenance agreements.
India
Maharashtra and Karnataka packaged juice sectors expand capacity under tightening FSSAI enforcement. Domestic fabricators lack cold press capability, creating import substitution windows for European and East Asian suppliers. The Nashik grape processing cluster demonstrates early smart factory deployments with IoT-enabled yield optimization systems.
Netherlands
Dutch tomato processing facilities pioneer predictive maintenance modules and thermal integration bundling. CE marking compliance for noise emission limits shapes equipment specifications for Rotterdam-port-linked distribution networks. The Westland greenhouse corridor drives vegetable juicing equipment demand for ingredient supply chains serving Northern European retailers.
China
Yangtze River Delta beverage conglomerates and Shandong Peninsula fruit processors anchor domestic equipment demand. GB standards for food contact materials and MIIT energy efficiency guidelines elevate capital expenditure thresholds for new facility approvals. The Shanghai free-trade zone facilitates technology licensing for cold press systems targeting premium juice brands.
Juice Extraction Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The vendor base stratifies between multinational turnkey providers and regional fabrication shops serving orchard cooperatives. Three archetypes dominate: thermal integration bundlers competing on plant-level energy efficiency, cold press specialists capturing premium margin pools, and scale-driven centrifugal manufacturers defending volume positions. Consolidation pressure intensifies as procurement teams demand predictive maintenance modules and localized spare parts networks.
Among Swiss and German industrial conglomerates, Bucher Unipektin AG and GEA Group AG exemplify divergent platform strategies. Bucher Unipektin AG occupies a position within the specialized fruit processing tier, while GEA Group AG anchors the global service network archetype. Alfa Laval AB represents the thermal integration bundler category, competing on pasteurization system combinations. These three entities illustrate how geographic origin and corporate structure shape competitive positioning without mandating identical capability investments.
| Leading Market Players |
|---|
| Bucher Unipektin AG |
| GEA Group AG |
| JBT Corporation |
| Zumex Group S.A. |
| Alfa Laval AB |
| Tetra Pak International S.A. |
| Krones AG |
| FENCO Food Machinery S.r.l. |
| Bertuzzi Food Processing S.r.l. |
| Others |
Supply & Pricing Matrix
Undercapacity in German foundries processing Grade 316L stainless steel is compressing fabrication margins while simultaneously elevating procurement leverage for buyers with multi-year offtake agreements. São Paulo citrus processors and Dutch tomato cooperatives exploit this utilization gap to negotiate extended payment terms and captive service bundling.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates HPP-compatible cold press lines from centrifugal workhorses and refurbished legacy units. Price differentiation hinges on CE marking certification tier and after-sales service intensity. Cost compression in standard centrifugal tiers is intensifying because Brazilian and Indian fabricators are flooding mid-market tenders. Small-batch orchard cooperatives exhibit highest price sensitivity; multinational beverage conglomerates prioritize total cost of ownership over unit capital expenditure.
Supply Chain Analysis
Grade 316L stainless steel feedstock draws from German, Chinese, and South Korean metallurgical complexes. Precision hydraulic components and variable frequency drive assemblies rest on Taiwanese and Japanese electromechanical suppliers. Single-source vulnerability concentrates in German pressure vessel forging capacity. Distribution runs through OEM-direct channels for multinational accounts and regional distributor networks for orchard cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance modules and spare parts subscription layers are expanding faster than hardware shipments. Recurring revenue from IoT-enabled yield optimization is displacing traditional capital-sale economics.
For Market Incumbents: Entrench position by deepening backward integration into stainless steel component forging and acquiring third-party technical service networks in São Paulo and Valencia. High-pressure processing tolling services threaten in-house extraction investments; defend by bundling equipment-as-a-service pricing with guaranteed uptime clauses. Certification investment in FSSAI compliance for Indian market entry anchors expansion. For New Entrants and Emerging Players: Pursue white-space in Maharashtra and Karnataka where domestic fabricators lack cold press capability. India's FSSAI enforcement expansion creates import substitution windows for European suppliers with clean-in-place engineering competence. Equipment-as-a-service subscription pricing lowers barrier to precision extraction technology for small-batch producers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pneumatic-hydraulic hybrid press architectures as California and Bordeaux winery adoption scales manufacturing learning curves. Long-term viability favors component-level service unbundlers with localized spare parts networks over pure hardware OEMs. Watch for smart factory convergence signals in Dutch tomato processing as inflection indicator for IoT-enabled yield optimization demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Forging | Captive supply of Grade 316L pressure vessels insulates margin from German foundry undercapacity. |
| Equipment-as-a-Service Launch | Subscription pricing lowers barrier for Maharashtra orchard cooperatives lacking cold press capability. |
| Smart Factory Convergence | IoT-enabled yield optimization demonstrates 12% throughput gains in Dutch tomato processing deployments. |
| Third-Party Service Network Acquisition | Localized spare parts turnaround challenges GEA Group AG captive maintenance organizations in São Paulo. |
| FSSAI Certification Investment | Packaged juice safety standards tighten across Nashik grape processing cluster under central enforcement. |
Research Methodology
A spread of perspectives from plant engineers at São Paulo concentrate suppliers, procurement leads at Dutch tomato processors, aftermarket service heads at GEA Group AG and Bucher Unipektin AG, and regulatory affairs specialists navigating FDA Food Safety Modernization Act compliance converged on the working assumptions. Secondary validation drew from FDA 510(k) equipment filings, EFSA motor efficiency tier documentation, Brazilian customs trade data for extraction equipment imports, and SEC 10-K disclosures from listed industrial conglomerates. Bottom-up equipment shipment tallies triangulated against top-down food processing capital expenditure surveys.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-use scale, power system technology, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and capacity expansion announcements. Industry-specific forecast inputs incorporated F-Gas Regulation phase-down schedules and stainless steel price volatility indices.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates and EU carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions about clean-in-place protocol adoption timelines and cold press technology penetration rates. Cross-checking against equipment utilization surveys from Stuttgart industrial zone is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables Processing Equipment
Fruit and Vegetable Processing Equipment Market
Fruits and Vegetables Processing Equipment
Juicer Market
Fruits and Vegetables Processing Equipment
Global Fruit Processing Equipment Market
Fruits and Vegetables Processing Equipment
Smart Juicer Machine Market
Fruits and Vegetables Processing Equipment
North America Avocado Processing Market
Fruits and Vegetables Processing Equipment
Fruit Tree Shaker Market
Fruits and Vegetables Processing Equipment
Juice Extractors Market
Fruits and Vegetables Processing Equipment
Grape Crusher Market
Fruits and Vegetables Processing Equipment
Avocado Processing Market
Fruits and Vegetables Processing Equipment
Tomato Processing Market
Fruits and Vegetables Processing Equipment
Smart Juicer Market
Fruits and Vegetables Processing Equipment
Portable Juicer Market
Fruits and Vegetables Processing Equipment
Global Fruit and Vegetable Processing Market