
 Smart Juicer Machine Market | 2026-2036
Smart Juicer Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Juicer Machine Market Insights
A shift from single-source component procurement to multi-source supplier strategies is repositioning how smart juicer manufacturers manage motor and sensor supply chains. Hurom Co., Ltd. leverages in-house slow-juice screw production to sustain margin control against commodity competitors. Breville Group Limited anchors its premium positioning through direct-to-consumer channel dominance in English-speaking markets. Panasonic competes on manufacturing scale, operating vertically integrated appliance plants that reduce lead times for Wi-Fi module integration.
A smart juicer machine constitutes an electromechanical food-preparation appliance incorporating brushless DC motors, stainless-steel augers or centrifugal baskets, and IoT-enabled control boards that communicate via Wi-Fi or Bluetooth protocols to mobile applications for recipe programming and usage tracking. Its primary commercial purpose is automated extraction of fruit and vegetable juices with programmable consistency settings, self-monitoring capabilities, and remote operational control. Masticating juicer configurations command the deepest margin pools due to slower oxidation rates and higher juice yield per input weight. Smart connectivity technology is expanding fastest among technology dimensions, with automated cleaning functionality emerging as a decisive purchase criterion for time-constrained household end users.
FCC certification governs wireless radio emissions for all Wi-Fi-enabled units sold in the United States, while CE marking and the EU Ecodesign Directive regulate energy consumption and electromagnetic compatibility across European markets. China's GB standards and MIIT network-access licensing impose additional testing burdens for app-integrated appliances, effectively filtering smaller brands from official distribution channels. Stakeholders must monitor evolving cybersecurity labeling requirements for connected kitchen appliances, as regulatory scope expands from hardware safety to data privacy and firmware integrity verification.
Market Dynamics
Energy-efficiency mandates under the EU Ecodesign Directive and comparable U.S. DOE standards are compelling manufacturers to redesign motor systems and standby power profiles, fundamentally restructuring component sourcing and product development cycles across the smart juicer value chain.
Growth Catalysts
- Residential kitchen connectivity:Connected appliance adoption is broadening among urban middle-class households, creating pull-through demand for Wi-Fi-enabled juicing systems with recipe programming capabilities.
- EU Ecodesign Directive:Stricter energy-efficiency mandates are accelerating brushless DC motor adoption and forcing standby power reductions that differentiate compliant products in premium retail channels.
- China urban clusters:Shanghai, Beijing, and Shenzhen households are driving premium smart appliance penetration, concentrating demand for masticating configurations with automated cleaning functionality.
Market Restraints
- Neodymium magnet cost volatility:Brushless DC motor production depends on rare-earth supply concentration, exposing manufacturers to price swings from Chinese export quota policies.
- MIIT network-access licensing:China's GB standards and app-integration testing requirements impose burdens that filter smaller brands from official distribution channels, consolidating shelf access for incumbents.
- Centrifugal juicer substitution:Lower-cost non-connected centrifugal units retain share among price-sensitive segments, limiting premium smart product addressable market expansion.
Strategic Opportunities
- Automated cleaning functionality:Time-constrained household end users are elevating self-monitoring and remote operational control as decisive purchase criteria, creating margin expansion for feature-differentiated SKUs.
- Cybersecurity labeling expansion:Evolving firmware integrity verification requirements for connected kitchen appliances present first-mover advantage to brands with established data privacy architectures.
- Masticating configuration premiumization:Slower oxidation rates and higher juice yield per input weight command the deepest margin pools, rewarding upstream control over auger and screw production.
Industry Challenges
- FCC certification timelines:Wi-Fi-enabled units sold in the United States face wireless radio emissions testing bottlenecks that compress product launch windows and strain R&D coordination.
- Multi-source supplier qualification:Shifts from single-source component procurement to diversified motor and sensor supply chains introduce quality consistency risks and vendor management complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Juicer Machine Market |
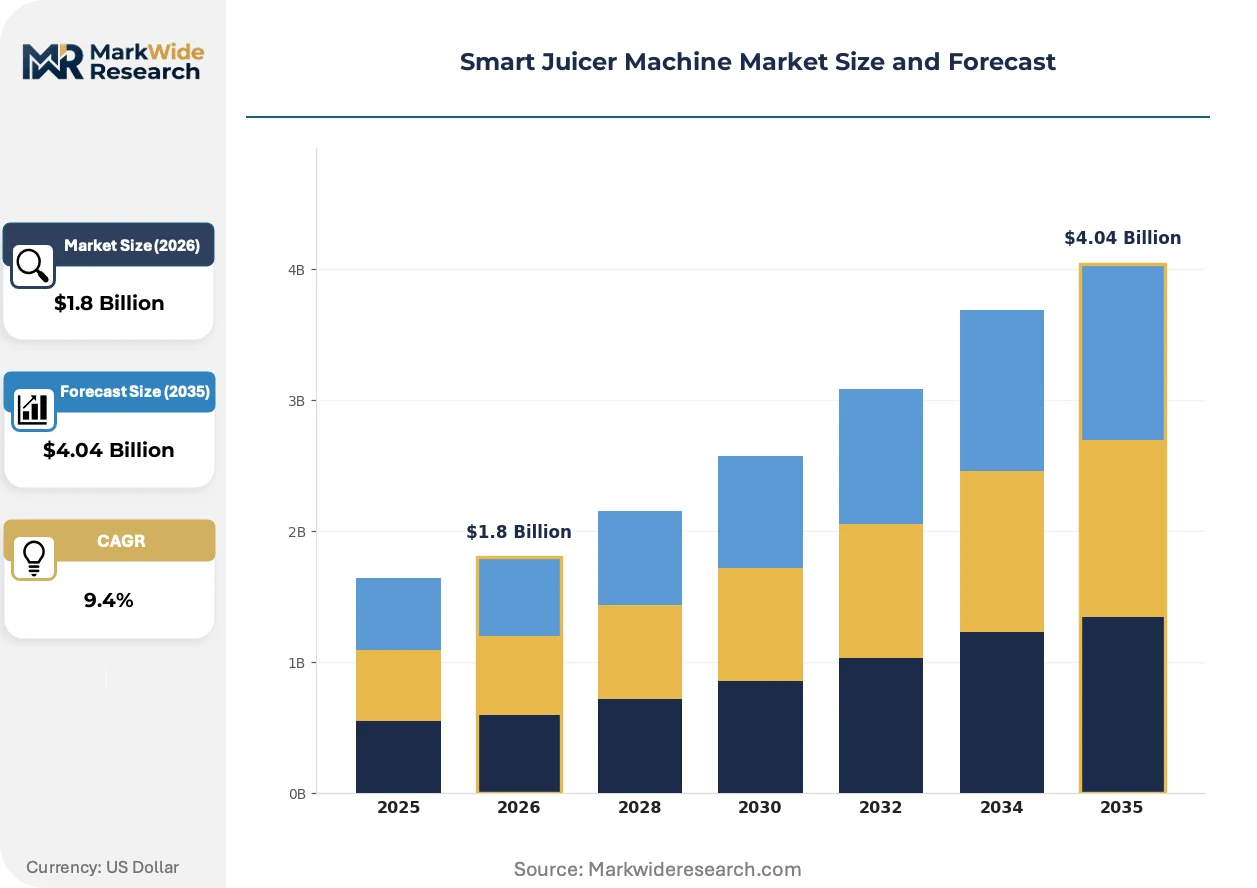
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Juicer, Masticating Juicer, Citrus Juicer, Cold Press Juicer Technology: Smart Connectivity, Automated Cleaning, Dual Blade Technology, Nutrient Extraction End User: Households, Restaurants, Juice Bars, Health Clubs Distribution Channel: Online Stores, Retail Outlets, Wholesale Distributors, Specialty Stores |
| Companies Covered | Breville Group Limited, Hurom Co., Ltd., Kuvings, Hamilton Beach Brands Holding Company, Philips, Omega Products Inc., Cuisinart, Tribest Corporation, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Juicer Machine Market Trends and Innovations
IoT-enabled control boards communicating via Wi-Fi and Bluetooth protocols are redefining user interaction models, while regulatory pressure on energy consumption and electromagnetic compatibility is accelerating hardware redesign cycles.
Brushless DC motor systems paired with precision sensor arrays are automating torque adjustment and pulp ejection timing in real-time. Residential buyers in connected-home ecosystems are adopting these configurations faster than commercial food-service operators. This automation is compressing the performance gap between entry-tier and mid-market products, forcing premium brands to deepen software differentiation.
The EU Ecodesign Directive's expanding scope now captures standby power draw and motor efficiency metrics previously exempt from kitchen appliances. Manufacturers serving European markets must retool production lines to meet tiered compliance deadlines. Masticating juicer SKUs with integrated power management chips are capturing shelf preference in German and French retail channels ahead of enforcement dates.
Direct-to-consumer channel strategies are displacing traditional appliance retail distribution in English-speaking markets. Breville Group Limited's online dominance demonstrates how bypassing big-box intermediaries captures margin and usage data simultaneously. This channel rotation is most visible in Australia and the United Kingdom, where subscription-based consumable bundling now accompanies hardware purchases.
Smart Juicer Machine Market Segmentation
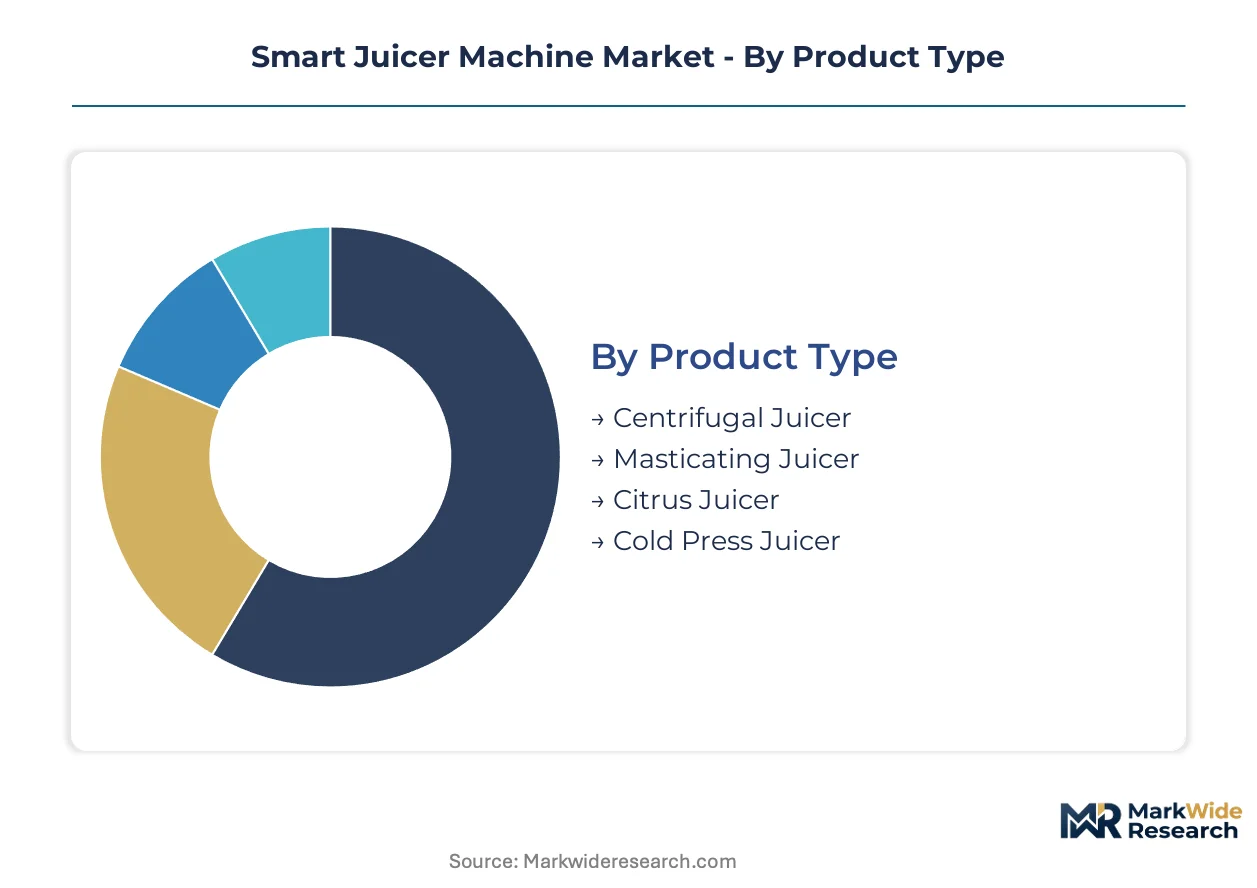
Smart juicer manufacturers engineer product portfolios around divergent capital requirements, with motor technology and connectivity infrastructure driving fixed-cost disparities across segments. Understanding these structural differences clarifies where margin pools concentrate and which configurations justify premium positioning.
Product Type:
Capital intensity varies sharply across juicer architectures, with auger-based systems demanding precision machining investments that centrifugal designs avoid entirely.
- Masticating Juicer:Horizontal or vertical auger configurations crush produce at 40-100 RPM, minimizing heat and oxidation. Shanghai, Beijing, and Shenzhen households drive demand for these units as premium smart appliance penetration accelerates among urban middle-class buyers seeking higher juice yield per input weight.
- Centrifugal Juicer:High-speed spinning baskets shred produce through mesh filters at 3,000-16,000 RPM. Price-sensitive segments retain strong preference for these lower-cost non-connected units, constraining premium smart product addressable market expansion in mass retail channels.
- Citrus Juicer:Dedicated reamer mechanisms target orange, lemon, and grapefruit extraction with minimal component complexity.
- Cold Press Juicer:Hydraulic or pneumatic pressing systems operate without blades, appealing to raw food enthusiasts seeking minimal oxidation.
Most installed capacity flows through Centrifugal Juicer. Expansion is steepest in Masticating Juicer.
Technology:
Software-enabled features command higher engineering overhead than mechanical innovations, reshaping R&D allocation toward firmware and app ecosystems.
- Smart Connectivity:Wi-Fi and Bluetooth control boards enable recipe programming, usage tracking, and remote operation through mobile applications. Residential kitchens in connected-home ecosystems adopt these configurations faster than commercial operators, with FCC certification timelines creating launch bottlenecks for US-bound units.
- Automated Cleaning:Integrated water circulation and brush systems reduce manual maintenance. Time-constrained household end users elevate this functionality as decisive purchase criteria, creating margin expansion for feature-differentiated SKUs in German and French retail channels ahead of EU Ecodesign enforcement dates.
- Dual Blade Technology:Counter-rotating blade pairs improve extraction efficiency through enhanced cellular disruption.
- Nutrient Extraction:High-shear blending combined with juicing functions targets fiber-inclusive beverage preparation.
Component sourcing concentrates around Smart Connectivity. Adoption velocity peaks with Automated Cleaning.
End User:
Volume procurement patterns separate commercial operators from residential buyers, with durability specifications and connectivity requirements diverging accordingly.
- Households:Individual consumers prioritize countertop footprint reduction, noise dampening, and app integration. Urban middle-class households in China concentrate demand for Wi-Fi-enabled juicing systems with recipe programming capabilities as connected appliance adoption broadens.
- Restaurants:Food-service operators demand NSF-certified stainless construction and continuous-run motors. These commercial accounts favor brushless DC motor configurations with automated torque adjustment, though centrifugal substitution limits premium smart product penetration among price-sensitive independent operators.
- Juice Bars:Dedicated beverage retailers require high-throughput configurations with rapid pulp ejection cycles.
- Health Clubs:Wellness facilities integrate juicing stations into amenity portfolios with usage tracking for member engagement.
Unit economics favor Households for average selling price. Throughput requirements dominate Juice Bars.
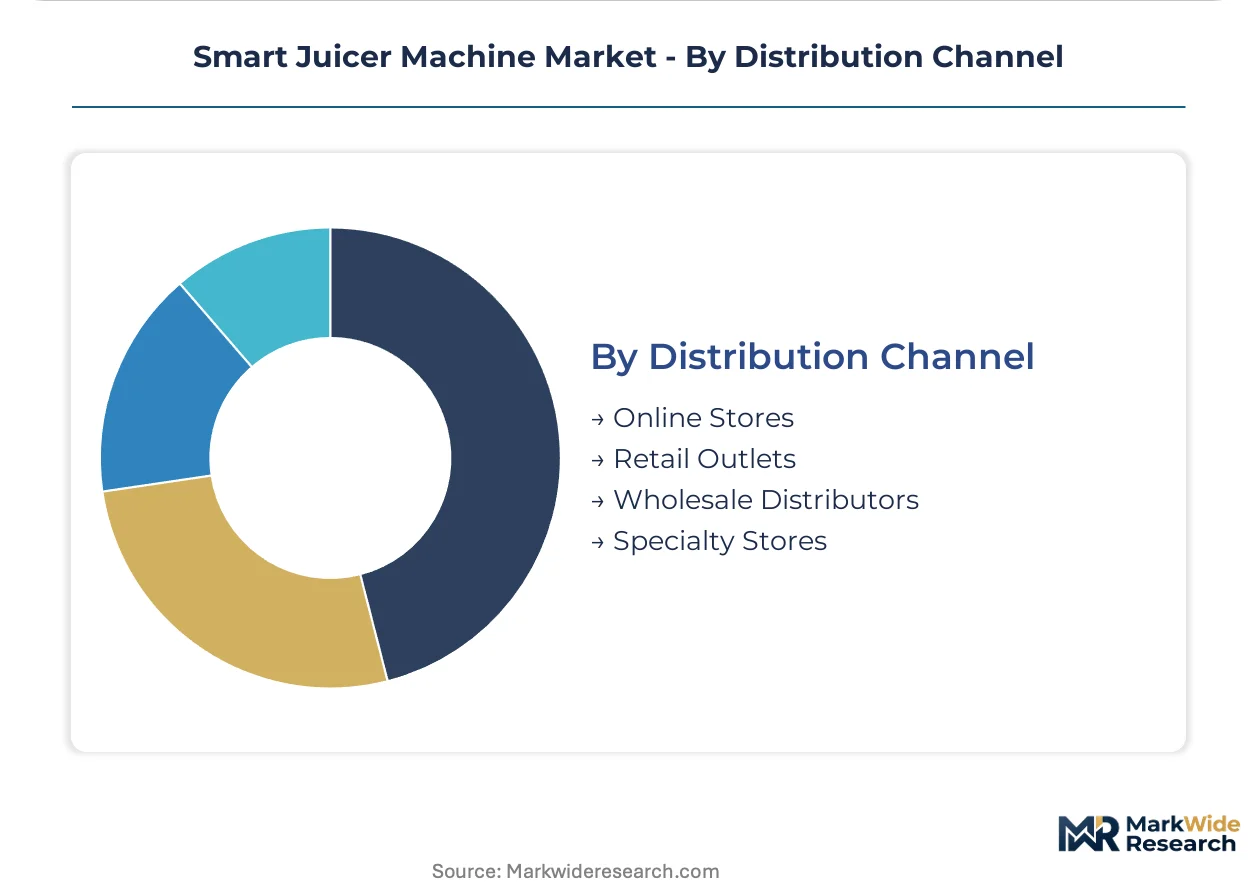
Distribution Channel:
Channel selection determines margin retention and data capture capabilities, with direct models displacing traditional retail intermediaries in mature markets.
- Online Stores:Direct-to-consumer platforms bypass big-box intermediaries to capture margin and usage data simultaneously. Australia and United Kingdom markets demonstrate this channel rotation most visibly, where subscription-based consumable bundling now accompanies hardware purchases.
- Retail Outlets:Big-box and appliance specialty retailers provide tactile evaluation and immediate fulfillment. These brick-and-mortar channels retain importance for masticating juicer SKUs where in-store demonstration clarifies operational differences from centrifugal alternatives.
- Wholesale Distributors:B2B intermediaries serve commercial accounts with volume pricing and service contracting.
- Specialty Stores:Kitchenware boutiques and wellness retailers curate premium assortments with educated sales support.
Revenue mix tilts toward Online Stores. Shelf access tightens through Wholesale Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai, Beijing, and Shenzhen anchor smart juicer demand concentration as urban middle-class households drive premium appliance penetration across connected-home ecosystems.
United States
Residential kitchen connectivity pulls Wi-Fi-enabled juicing systems into suburban and urban households seeking recipe programming capabilities. FCC certification governs wireless radio emissions testing for all connected units, compressing product launch windows for manufacturers. California and Texas metro areas concentrate early-adopter demand for automated cleaning functionality among time-constrained professionals.
China
Urban middle-class expansion in tier-one cities creates sustained demand for masticating configurations with app integration and remote operational control. MIIT network-access licensing and GB standards impose testing burdens that filter smaller brands from official distribution channels. The Yangtze River Delta and Pearl River Delta manufacturing clusters supply precision-machined augers and brushless DC motor assemblies for domestic and export markets.
Germany
Energy-conscious households prioritize standby power efficiency and motor performance metrics ahead of EU Ecodesign Directive enforcement deadlines. CE marking and electromagnetic compatibility regulations accelerate hardware redesign cycles for Wi-Fi module integration. Bavaria and North Rhine-Westphalia retail channels show shelf preference for masticating SKUs with integrated power management chips.
Japan
Compact countertop footprints and noise dampening specifications dominate household procurement criteria in dense urban residential environments. METI efficiency standards and JIS certification requirements shape product development priorities for domestic manufacturers. The Kanto region around Tokyo concentrates premium smart appliance adoption within connected-home ecosystem deployments.
United Kingdom
Direct-to-consumer channel rotation displaces traditional big-box retail intermediaries, capturing margin and usage data simultaneously through online platforms. Subscription-based consumable bundling now accompanies hardware purchases in English-speaking markets. London and Southeast England urban households lead adoption of app-integrated juicing systems with automated cleaning features.
Smart Juicer Machine Market Competitive Landscape
Global majors compete with regional champions across distribution channel architecture and motor technology sourcing. The vendor base separates into scale-driven appliance conglomerates, precision-manufacturing specialists, and direct-to-consumer platform operators. Strategic moves concentrate on multi-source supplier qualification for brushless DC motors and Wi-Fi control boards, plus channel rotation toward online-first distribution models that bypass retail intermediaries.
Among Asia-Pacific specialists, Hurom Co., Ltd. and Kuvings occupy positions within the precision-manufacturing tier, exemplifying upstream control over slow-juice screw and auger production. Breville Group Limited anchors the direct-to-consumer archetype in English-speaking markets. Panasonic sits within the scale-driven conglomerate category, representing vertically integrated appliance manufacturing with captive motor and electronics assembly capabilities.
| Leading Market Players |
|---|
| Breville Group Limited |
| Hurom Co., Ltd. |
| Kuvings |
| Hamilton Beach Brands Holding Company |
| Philips |
| Omega Products Inc. |
| Cuisinart |
| Tribest Corporation |
| Panasonic |
| Others |
Pricing and Supply Chain Analysis
Urban middle-class households in Shanghai, Beijing, and Shenzhen anchor premium smart juicer procurement, concentrating pricing power among manufacturers serving connected-home ecosystems with app-integrated masticating configurations.
Pricing Analysis
Neodymium magnet cost volatility in brushless DC motor production feeds directly into tiered pricing across premium, standard, and economy levels. FCC certification timelines and MIIT network-access licensing create quality-grade differentiation that separates Wi-Fi-enabled units from non-connected alternatives. Cost compression in centrifugal configurations is intensifying because price-sensitive segments retain preference for lower-speed alternatives. Households seeking automated cleaning functionality show least price sensitivity, while mass-market centrifugal buyers exhibit highest elasticity.
Supply Chain Analysis
Container freight rates from Yangtze River Delta and Pearl River Delta manufacturing clusters to North American and European distribution centers shape landed cost structures for finished units. Precision-machined auger production concentrates in China, South Korea, and Japan, with brushless DC motor assemblies drawing from Taiwanese and Chinese electronics suppliers. Single-source vulnerability in rare-earth magnet procurement exposes manufacturers to Chinese export quota volatility. Distribution runs through direct-to-consumer platforms in English-speaking markets and big-box retail intermediaries elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Residential kitchen connectivity creates a stable compounder profile, with urban middle-class appliance replacement cycles generating predictable demand for Wi-Fi-enabled configurations.
For Market Incumbents: Anticipate centrifugal juicer substitution pressure from low-cost non-connected competitors by deepening software differentiation through recipe programming ecosystems. Defend margin position through backward integration into slow-juice screw production and captive Wi-Fi module sourcing that compresses lead times against multi-source supplier qualification risks.
For New Entrants and Emerging Players: Specialty kitchenware boutiques offer shelf access with educated sales support for masticating configurations where in-store demonstration clarifies operational advantages. Target automated cleaning functionality gaps in German and French retail channels ahead of EU Ecodesign enforcement, leveraging white-label partnerships with precision-manufacturing specialists in South Korea or Taiwan.
For Investors and Strategic Acquirers: Appliance conglomerates with vertically integrated manufacturing capabilities are the most active acquirers in this space, seeking captive motor and electronics assembly to reduce Wi-Fi integration lead times. Five-to-ten-year viability favors targets with established FCC and CE marking pathways plus direct-to-consumer data infrastructure. Monitor cybersecurity labeling expansion for connected kitchen appliances as the inflection signal for regulatory-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slow-Juice Screw Production | Hurom's in-house auger manufacturing sustains margin control against commodity competitors. |
| Direct-to-Consumer Channel Expansion | Breville's online dominance captures usage data alongside hardware margin in English-speaking markets. |
| Automated Cleaning Feature Development | Time-constrained households elevate self-monitoring as decisive purchase criterion ahead of EU enforcement. |
| Cybersecurity Labeling Pre-Compliance | First-mover brands with data privacy architectures capture shelf preference as firmware integrity requirements expand. |
| Multi-Source Supplier Qualification | Diversified motor and sensor sourcing reduces single-source vulnerability to rare-earth export quotas. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with appliance product managers, procurement leads at retail chains, motor system engineers, and channel distribution heads with secondary validation against FCC certification databases, EU Ecodesign Directive compliance filings, MIIT network-access licensing records, and customs trade data. Bottom-up SKU-level volume aggregation and top-down macroeconomic calibration ensured triangulation across estimation approaches.
Historical reference periods anchored the projection horizon through regression analysis of connected appliance adoption curves and premium product penetration rates. Segmentation dimensions modeled include juicer architecture type, connectivity technology tier, end-user category, and distribution channel structure. CAGRs derived from weighted average of demand elasticity estimates and replacement cycle assumptions, with neodymium price indices and regulatory compliance cost trajectories serving as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare-earth supply disruptions, cybersecurity labeling acceleration, and channel rotation velocity toward direct-to-consumer platforms. Forecasts reflect documented assumptions about urban middle-class expansion rates and connected-home ecosystem penetration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables Processing Equipment
Avocado Processing Market
Fruits and Vegetables Processing Equipment
Fruit Tree Shaker Market
Fruits and Vegetables Processing Equipment
Global Fruit Processing Equipment Market
Fruits and Vegetables Processing Equipment
Juice Extraction Equipment Market
Fruits and Vegetables Processing Equipment
North America Avocado Processing Market
Fruits and Vegetables Processing Equipment
Grape Crusher Market
Fruits and Vegetables Processing Equipment
Juice Extractors Market
Fruits and Vegetables Processing Equipment
Global Fruit and Vegetable Processing Market
Fruits and Vegetables Processing Equipment
Fruit and Vegetable Processing Equipment Market
Fruits and Vegetables Processing Equipment
Portable Juicer Market
Fruits and Vegetables Processing Equipment
Juicer Market
Fruits and Vegetables Processing Equipment
Smart Juicer Market
Fruits and Vegetables Processing Equipment
Tomato Processing Market