
 Portable Juicer Market | 2026-2036
Portable Juicer Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Juicer Market Analytics
Engineering talent specialized in compact motor design and lithium-ion power management is rotating toward consumer appliance divisions, unlocking faster iteration cycles for portable formats. Panasonic leverages vertical integration in battery cell production to sustain margin control across cordless SKUs. Midea anchors high-volume manufacturing in Guangdong, while Philips differentiates through European design standards and health-certification protocols. SKG competes aggressively on price in Southeast Asian e-commerce channels.
A portable juicer is a battery-powered or manually operated compact extraction device, typically housing a DC motor between 50W and 200W, stainless steel or titanium-plated auger assemblies, and food-grade Tritan or borosilicate containment vessels engineered for mobility. The primary commercial purpose is single-serve fresh juice preparation outside fixed kitchen infrastructure, serving commuters, gym users, and travel segments. USB rechargeable juicers now lead volume shipments due to universal power compatibility and declining lithium-polymer costs. Fitness enthusiasts represent the fastest-growing end-user pool as protein-vegetable blend routines expand beyond bodybuilding into mainstream wellness. Single-serve capacity dominates unit economics, while 500ml formats capture premium positioning among busy professionals seeking meal-replacement portability.
FDA food-contact notifications govern plastic and BPA-free material claims in the United States, directly influencing supplier qualification and labeling investments. China's SAMR enforces GB standards for small appliance electrical safety and electromagnetic compatibility, creating compliance thresholds for export-bound manufacturers. The EU RoHS directive and REACH chemical restrictions constrain material choices for brands accessing European retail channels. Stakeholders must monitor evolving battery transportation regulations and emerging right-to-repair mandates that could reshape modular design requirements and aftermarket service obligations.
Market Dynamics
USB rechargeable lithium-polymer systems have compressed development cycles and democratized entry, pulling engineering talent from power tools into compact motor design while FDA and SAMR compliance costs filter out sub-scale competitors.
Growth Catalysts
- Fitness-Enthusiast Meal Routines:Protein-vegetable blend protocols have migrated from bodybuilding into mainstream wellness, creating sustained replacement demand for single-serve extraction devices among gym users and commuters.
- EU RoHS Material Standards:REACH chemical restrictions and RoHS directives on hazardous substances have legitimized premium positioning for Tritan and borosilicate vessel suppliers, accelerating BPA-free certification investments.
- Guangdong Electronics Cluster:Cost-efficient lithium-ion cell and DC motor supply chains concentrated in China's Pearl River Delta enable rapid SKU proliferation at entry price points.
Market Restraints
- Lithium-Polymer Price Volatility:Raw material swings for cobalt and lithium carbonate compress margins on cordless SKUs, forcing trade-offs between battery capacity and unit economics.
- 50-200W Motor Thermal Limits:Compact DC motor architectures face hard physics constraints on sustained operation, limiting extraction efficiency for dense root vegetables and frozen ingredients.
- Battery Transportation Regulations:IATA and UN38.3 testing requirements for lithium cells create freight cost premiums and channel restrictions for direct-to-consumer cross-border shipments.
Strategic Opportunities
- India Tier-2 Urban Expansion:Underpenetrated demand in cities like Pune and Ahmedabad offers first-mover positioning as FSSAI appliance safety norms formalize.
- Right-to-Repair Mandates:Emerging EU and US state-level repairability requirements create modular design premiums for brands offering swappable battery packs and auger assemblies.
- USB-C Power Delivery Convergence:Universal 65W-100W charging standards enable cross-device compatibility with laptop and phone ecosystems, reducing consumer accessory burden.
Industry Challenges
- Compact Motor Thermal Engineering Talent:Scarcity of specialists integrating heat dissipation into sub-100W form factors extends R&D timelines and inflates compensation costs.
- Multi-Jurisdiction Certification Overlap:Simultaneous FDA food-contact, SAMR electrical safety, and CE marking requirements create testing bottlenecks and label complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Juicer Market |
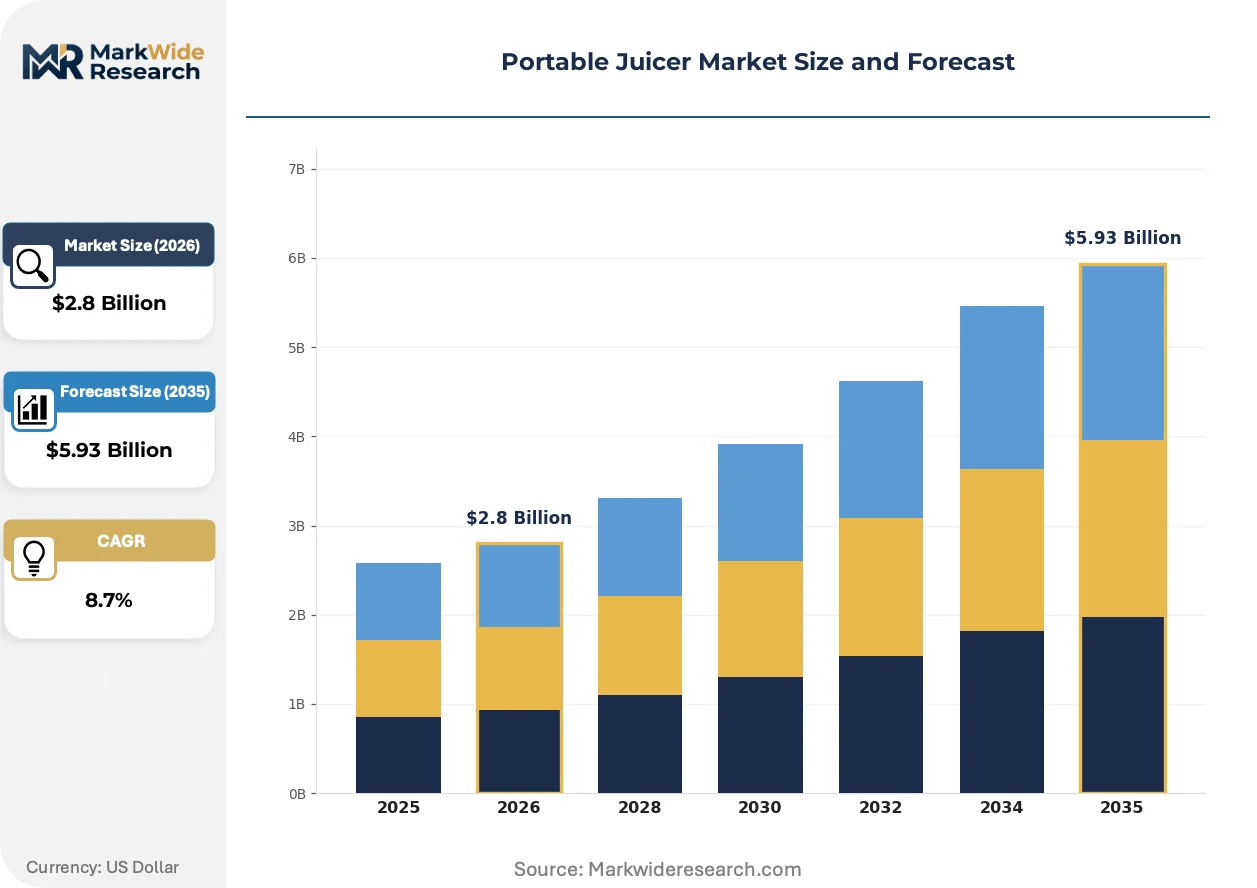
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cordless Juicers, USB Rechargeable Juicers, Mini Juicers, Travel Juicers End User: Fitness Enthusiasts, Busy Professionals, Students, Health-Conscious Consumers Capacity: Single Serve, 500ml, 750ml, 1 Liter Material: Plastic, Stainless Steel, Glass, BPA-Free |
| Companies Covered | Panasonic, Midea, SKG, SUPOR, Philips, Black+Decker, Heshan Zilong Home Appliance, Cuisinart, Ninja, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Juicer Market Evolving Landscape
Power management silicon and vessel materials are diverging into parallel development tracks, with motor efficiency and charging protocols now advancing faster than extraction mechanism design.
Magnetic-drive auger systems are fragmenting the traditional direct-drive architecture by eliminating shaft seals and enabling fully submersible cleaning. Fitness-oriented buyers in Seoul and Sydney are adopting these formats for gym-bag portability despite 15-20% extraction speed trade-offs. The technology is fragmenting supplier tiers, as magnetic coupling expertise migrates from pump manufacturers into appliance OEMs.
China's SAMR enforcement of updated GB 4706 small-appliance electrical safety standards is forcing redesigns of legacy charging circuits and thermal cutoffs. Export-bound manufacturers in Foshan and Ningbo face six-month retooling windows to maintain European retail access. The compliance burden falls heaviest on 50-80W entry SKUs where margin absorption is thinnest.
Subscription-based consumable bundles are displacing transactional hardware-only sales in direct channels. Busy professionals in London and New York receive pre-portioned frozen ingredient packs paired to specific juicer torque profiles, locking in recurring revenue. The model concentrates customer lifetime value capture among brands with captive supply chain integration.
Portable Juicer Market Segmentation
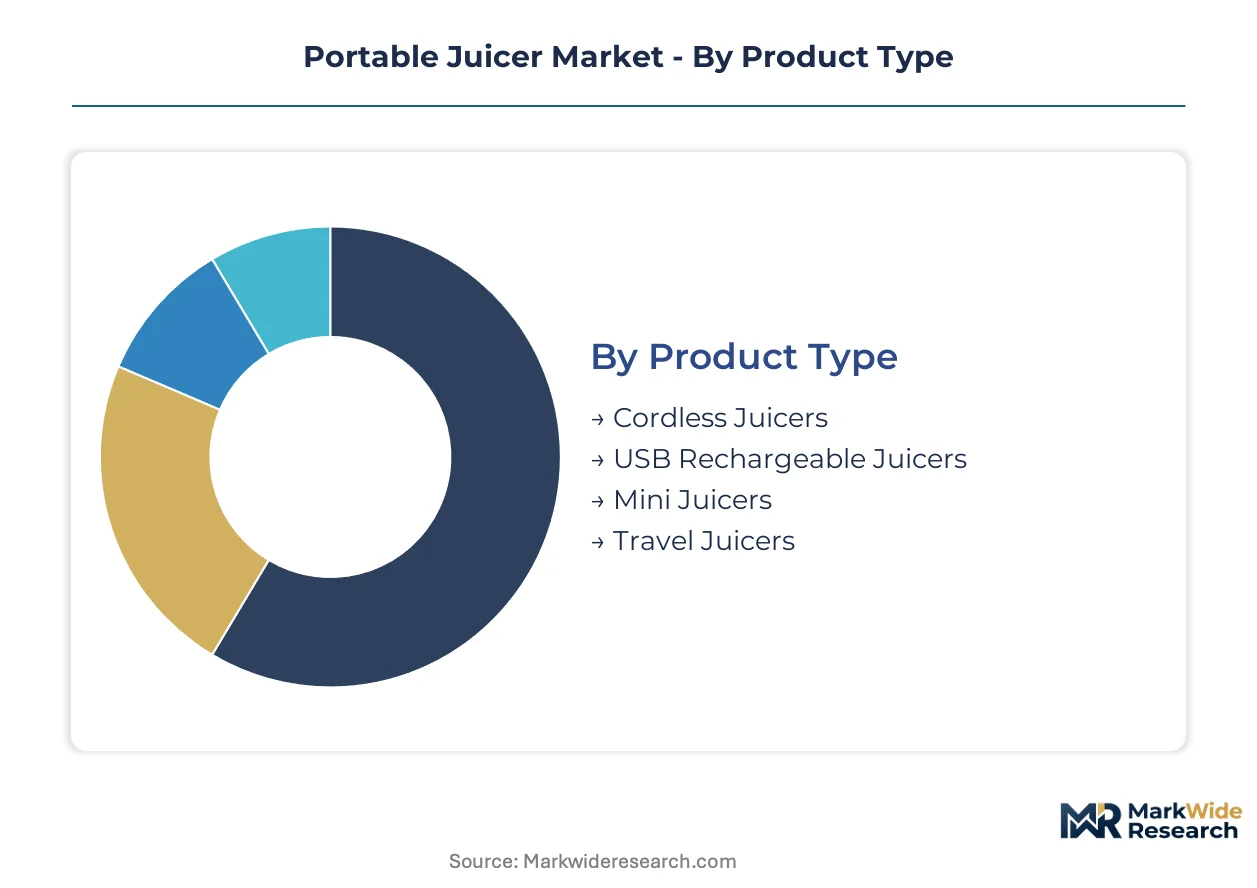
Portable juicer segmentation reveals how power source, user lifestyle, vessel size, and material safety claims partition demand across price tiers and regulatory exposure zones. Substitution pressures from food processors, ready-to-drink beverages, and commercial juice bars vary sharply by segment, reshaping R&D allocation and channel strategy.
Product Type:
Cordless formats face the strongest substitution threat from USB-rechargeable alternatives as lithium-polymer costs fall and universal charging protocols standardize.
- USB Rechargeable Juicers:These units integrate 2000mAh-4000mAh lithium-polymer cells with USB-C or Micro-USB inputs, enabling charging from vehicle ports, laptops, and power banks. Demand concentrates among commuters in Seoul and Sydney who prioritize gym-bag portability over kitchen-bound alternatives. The segment benefits from declining battery cell costs and cross-device charging ecosystem compatibility.
- Cordless Juicers:Battery-powered units with proprietary charging docks or removable cell packs, typically housing 50W-150W DC motors in 300ml-500ml form factors. Fitness enthusiasts in London and New York drive replacement cycles as protein-vegetable blend routines expand beyond bodybuilding. Thermal management constraints on sustained operation limit extraction efficiency for dense root vegetables.
- Mini Juicers:Ultra-compact 200ml-350ml formats prioritizing minimal weight over juice yield, often employing manual crank or low-wattage motor assist. Students in dormitory settings favor these for countertop footprint and price accessibility.
- Travel Juicers:Ruggedized designs with leak-proof sealing and TSA-compliant battery capacities for air travel, featuring collapsible or modular vessel assemblies. Health-conscious consumers in extended-stay corporate travel segments sustain niche demand despite premium pricing.
USB Rechargeable Juicers retain volume leadership; Cordless Juicers hold the steepest expansion curve.
End User:
Cost tier stratification separates premium wellness spenders from price-sensitive entry buyers, with professional segments commanding 40-60% price premiums over student equivalents.
- Fitness Enthusiasts:Users following protein-vegetable blend protocols that migrated from bodybuilding into mainstream wellness, requiring 150W-200W motors for frozen ingredient processing. Demand concentrates in gym-adjacent retail and direct-to-consumer subscription bundles in London and New York. Magnetic-drive auger adoption is highest here despite extraction speed trade-offs.
- Busy Professionals:Time-constrained buyers seeking single-serve meal replacement portability, prioritizing 500ml capacity and sub-60-second cleaning cycles. Pre-portioned frozen ingredient subscriptions paired to specific torque profiles lock in recurring revenue for integrated brands.
- Students:Price-sensitive users in dormitory and shared-kitchen environments favoring mini formats under $30 with minimal countertop footprint. USB rechargeable models dominate as universal charging reduces accessory burden.
- Health-Conscious Consumers:Broad wellness-oriented buyers spanning age demographics, responsive to BPA-free labeling and borosilicate vessel claims. FDA food-contact notification compliance and EU REACH restrictions directly influence purchase decisions.
Fitness Enthusiasts retain volume leadership; Busy Professionals hold the steepest expansion curve.
Capacity:
Application use case determines volume selection, with meal replacement scenarios driving larger formats and on-the-go consumption favoring minimal vessel sizes.
- Single Serve:250ml-350ml formats optimized for immediate consumption without storage, dominating commuter and gym-use scenarios. These units capture the highest shipment volumes due to entry price points and universal portability.
- 500ml:Mid-size vessels targeting meal-replacement positioning among busy professionals, enabling vegetable-protein blends with caloric density sufficient for breakfast substitution. Premium pricing reflects Tritan and borosilicate material upgrades.
- 750ml:Larger formats for shared consumption or extended travel, requiring more powerful motors and heavier battery configurations that compromise portability metrics.
- 1 Liter:Maximum capacity tier approaching countertop appliance territory, niche-positioned for family outdoor activities and RV travel where power access is limited.
Single Serve retains volume leadership; 500ml holds the steepest expansion curve.
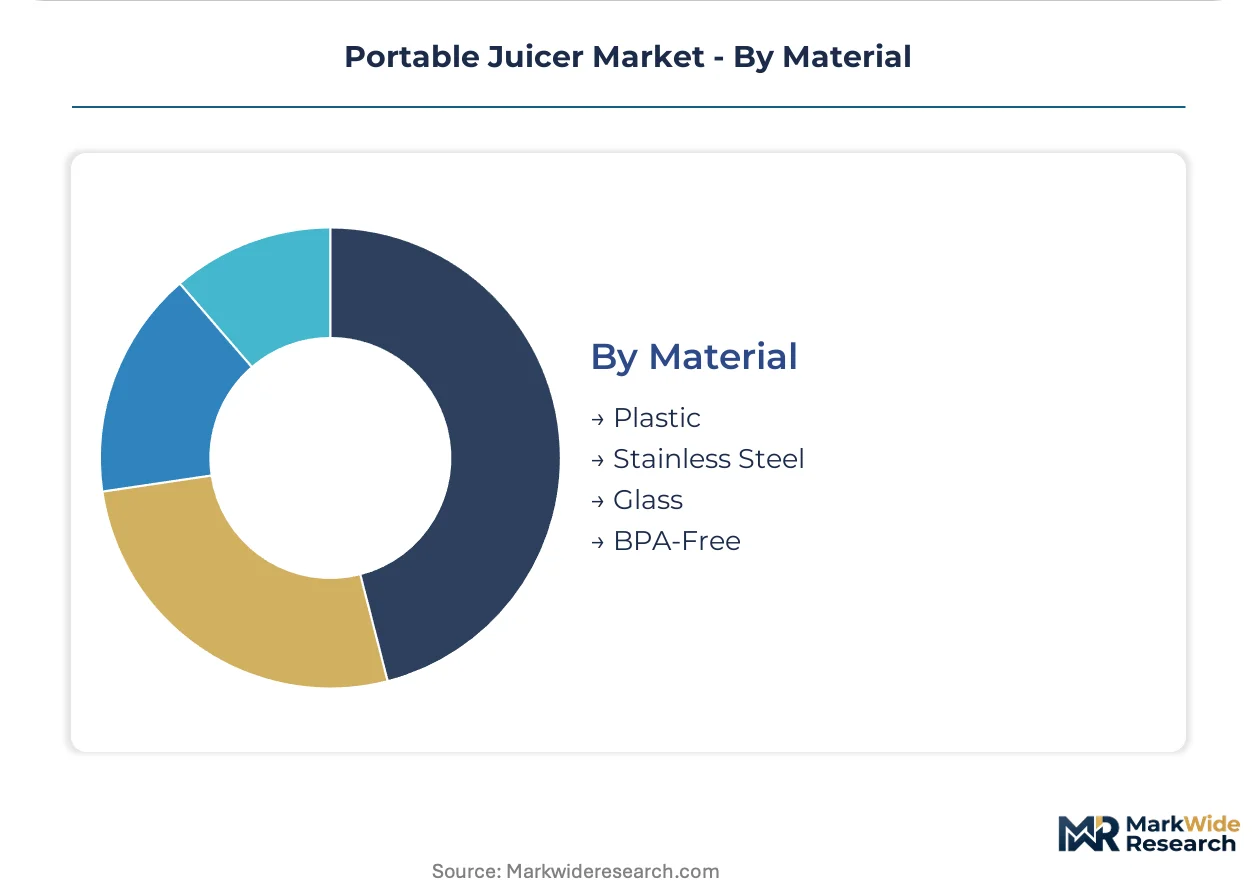
Material:
Margin structure diverges sharply by certification tier, with BPA-free and glass vessels commanding 25-35% price premiums over standard plastic equivalents.
- BPA-Free:Tritan copolyester and verified BPA-free plastics carrying FDA food-contact notification compliance and EU REACH alignment. Health-conscious consumers in the United States and European Union treat these claims as table stakes, filtering non-compliant alternatives from consideration sets.
- Glass:Borosilicate vessels offering thermal shock resistance and chemical inertness, premium-positioned for professionals seeking meal-replacement durability. Weight penalties limit adoption in travel-focused segments.
- Stainless Steel:Metal containment with auger assemblies, favored for durability and aesthetic differentiation in gift and corporate channels. Higher unit costs constrain volume penetration.
- Plastic:Standard food-grade polymers without BPA-free certification, concentrated in entry-tier mini and student-targeted SKUs. SAMR GB standards and FDA compliance costs filter sub-scale suppliers from this segment.
Plastic retains volume leadership; BPA-Free holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Fitness enthusiasts in Seoul and Sydney prioritize gym-bag portability and USB-C compatibility, while busy professionals in London and New York gravitate toward subscription-linked meal-replacement formats. Health-conscious consumers in Chinese urban centers drive volume through cost-efficient domestic supply chains.
United States
FDA food-contact notifications and BPA-free labeling requirements shape supplier qualification and retail channel access. The agency's enforcement of plastic safety standards directly influences material selection for vessel components. California's wellness-oriented consumer base sustains premium positioning for borosilicate and Tritan formats in Los Angeles and San Francisco metro areas.
China
SAMR enforcement of updated GB 4706 electrical safety standards is forcing six-month retooling windows for export-bound manufacturers in Foshan and Ningbo. The Pearl River Delta's concentrated lithium-ion cell and DC motor supply chains enable rapid SKU proliferation at entry price points. Domestic health-conscious consumers in Shenzhen and Shanghai drive USB rechargeable adoption through universal charging compatibility.
Germany
EU RoHS directives and REACH chemical restrictions constrain material choices for brands accessing European retail channels. The country's engineering heritage elevates expectations for motor efficiency and thermal management in compact formats. Berlin and Munich serve as test markets for magnetic-drive auger systems despite extraction speed trade-offs.
Japan
METI efficiency standards and compact living constraints favor mini and single-serve formats in Tokyo and Osaka metropolitan areas. The country's aging demographic sustains demand for simplified cleaning protocols and lightweight vessel designs. Domestic retailers emphasize BPA-free certification as a baseline expectation rather than premium differentiator.
India
FSSAI appliance safety norms are formalizing compliance thresholds as Tier-2 cities like Pune and Ahmedabad emerge as expansion targets. Price-sensitive demand concentrates in mini formats under $30 with USB rechargeable configurations. Mumbai and Bangalore fitness communities represent early adoption pockets for protein-vegetable blend routines.
Portable Juicer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding margin control through captive battery cell production and vertical manufacturing scope. The middle tier fragments across regional specialists competing on design differentiation and certification compliance. Three archetypes dominate: scale-driven electronics conglomerates with home appliance divisions, design-forward European brands leveraging health-certification protocols, and cost-optimized Chinese manufacturers anchored in Guangdong production clusters. Competitive moves concentrate on strategic partnerships for subscription-based consumable bundles and modular design investments anticipating right-to-repair mandates.
Within the integrated-leader tier, Panasonic and Midea exemplify contrasting geographic anchors—Panasonic leveraging Japanese battery cell production for cordless SKU margin control, Midea anchoring high-volume manufacturing in Guangdong for cost-efficient electronics integration. Philips occupies a position emphasizing European design standards and health-certification protocols. SKG sits within the aggressive-price-competition archetype, targeting Southeast Asian e-commerce channels.
| Leading Market Players |
|---|
| Panasonic |
| Midea |
| SKG |
| SUPOR |
| Philips |
| Black+Decker |
| Heshan Zilong Home Appliance |
| Cuisinart |
| Ninja |
| Others |
Value Network & Pricing Analysis
Sixty-day lithium-polymer cell lead times from Guangdong suppliers concentrate pricing power among vertically integrated battery producers, while FDA and SAMR compliance investments filter sub-scale competitors from premium tiers. This inventory compression forces trade-offs between motor capacity and margin preservation across cordless SKUs.
Pricing Analysis
Long-term offtake agreements between Guangdong manufacturers and lithium-ion cell suppliers anchor entry-tier pricing, while spot-market cobalt volatility creates premium tier differentiation. Three-tier pricing structure across premium, standard, and economy levels separates BPA-free certified vessels from standard plastic alternatives. Pricing pressure stems from raw material swings in lithium carbonate, compressing margins on 50-80W entry SKUs. Students represent the most price-sensitive buyer archetype, while busy professionals accept 40-60% premiums for meal-replacement formats.
Supply Chain Analysis
Pearl River Delta port congestion acts as a chokepoint for DC motor and battery cell shipments destined for European and North American assembly facilities. Manufacturing concentrates in China, South Korea, and Japan, with lithium-polymer cells, Tritan copolyester, and compact DC motors as critical inputs. Single-source vulnerability in rare-earth magnet supply for motor assemblies creates exposure to export restriction shocks. Distribution runs through direct-to-consumer e-commerce channels and gym-adjacent retail partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
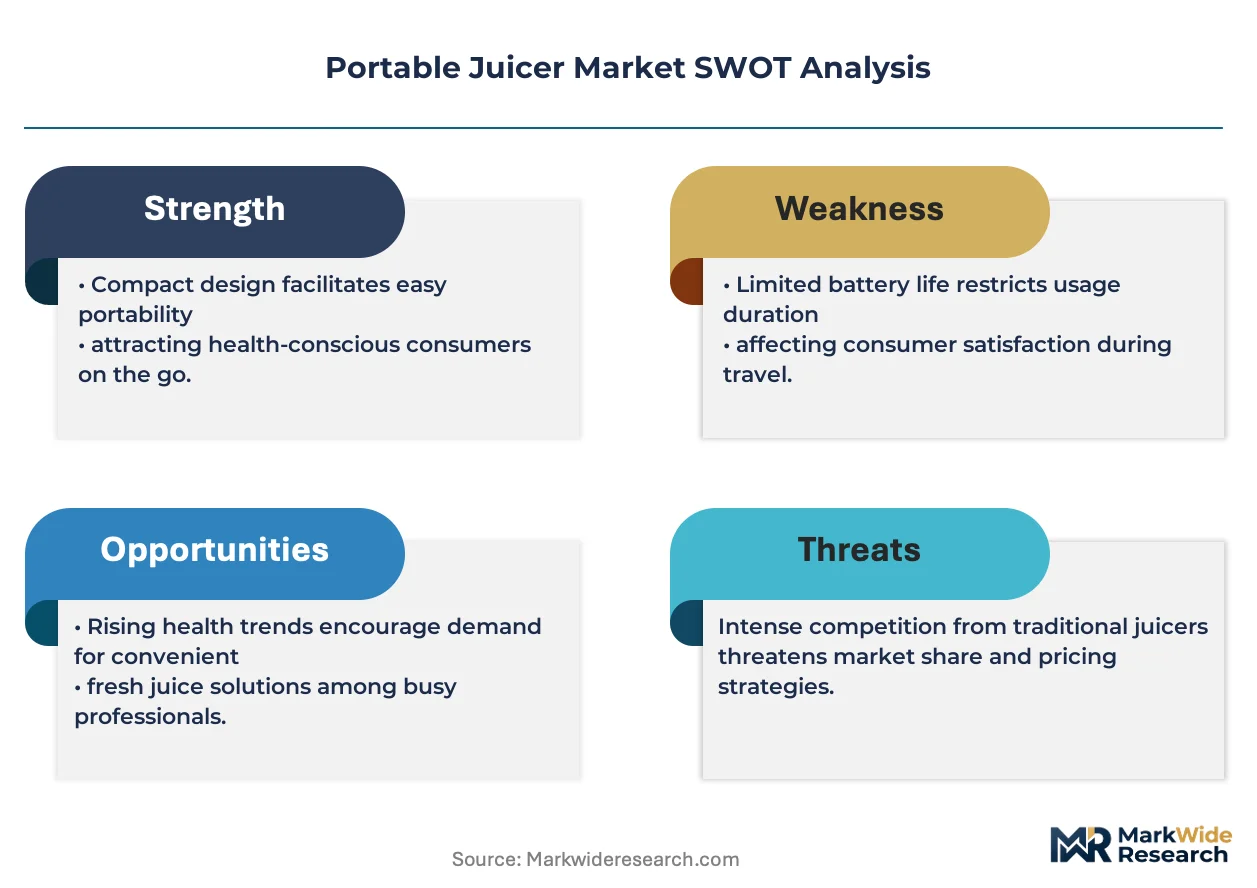
Ready-to-drink beverage subscription services and commercial juice bar chains threaten hardware incumbents by capturing recurring wellness spend without countertop appliance ownership.
For Market Incumbents: Fortify captive battery cell supply through upstream partnerships with Panasonic or Samsung SDI production networks, while accelerating FDA food-contact notification investments to filter price-aggressive challengers from premium positioning. Magnetic-drive auger patent portfolios offer defensive moats against extraction mechanism commoditization. For New Entrants and Emerging Players: FDA 510(k) fast-track equivalence pathways for food-contact materials enable rapid qualification for BPA-free Tritan vessels, opening white-space in Indian Tier-2 cities where FSSAI norms are formalizing. Target Pune and Ahmedabad fitness communities with USB-C compatible mini formats under $25, leveraging universal charging ecosystems to reduce consumer accessory burden. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across magnetic-drive auger specialists as pump manufacturer expertise migrates into appliance OEMs, compressing R&D timelines for sub-100W thermal engineering. Acquisition candidates with modular battery pack designs and swappable auger assemblies align with emerging right-to-repair mandates. Monitor EU battery transportation regulation enforcement as an inflection signal for cross-border direct-to-consumer channel viability.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription-Based Consumable Bundles | Pre-portioned frozen ingredient packs paired to torque profiles lock in recurring revenue for integrated brands in London and New York. |
| Magnetic-Drive Auger Patent Development | Eliminating shaft seals enables fully submersible cleaning, differentiating gym-bag portability despite extraction speed trade-offs in Seoul. |
| USB-C Power Delivery Integration | Universal 65W-100W charging standards reduce consumer accessory burden and enable cross-device compatibility with laptop ecosystems. |
| Modular Battery Pack Design | Swappable cell configurations anticipate EU and US state-level right-to-repair mandates, creating aftermarket service revenue streams. |
| FSSAI Compliance Pre-Investment | Early appliance safety certification in India captures first-mover positioning as Tier-2 urban demand formalizes in Pune and Ahmedabad. |
Research Methodology
Initial hypotheses were tested against primary input from product development executives at consumer appliance divisions, procurement leads at lithium-ion cell suppliers, regulatory affairs specialists navigating FDA food-contact notifications, and category buyers at gym-adjacent retail channels, then refined against secondary validation from SAMR GB standard filings, EU RoHS directive updates, customs records for DC motor trade flows, and SEC 10-K disclosures from integrated electronics conglomerates. Bottom-up shipment estimates triangulated with top-down wellness spend allocation models.
Variance-decomposition across power source, end-user lifestyle, vessel capacity, and material certification tiers structured the analytical framework throughout the projection horizon. CAGRs derived from segment-level adoption curves weighted by urban commuter density and fitness facility penetration. Lithium-polymer cost decline trajectories and magnetic-drive auger yield improvements served as technology-specific forecast inputs.
Underlying assumptions cover sustained USB-C ecosystem convergence and stable cobalt supply chain conditions, with deviation risk concentrated in IATA battery transportation regulation enforcement and EU right-to-repair mandate timing. Practitioners should keep alternative scenarios live as SAMR electrical safety standard updates and FSSAI appliance norm formalization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables Processing Equipment
Tomato Processing Market
Fruits and Vegetables Processing Equipment
Global Fruit Processing Equipment Market
Fruits and Vegetables Processing Equipment
Juice Extraction Equipment Market
Fruits and Vegetables Processing Equipment
Fruit Tree Shaker Market
Fruits and Vegetables Processing Equipment
Juicer Market
Fruits and Vegetables Processing Equipment
Avocado Processing Market
Fruits and Vegetables Processing Equipment
Grape Crusher Market
Fruits and Vegetables Processing Equipment
Fruit and Vegetable Processing Equipment Market
Fruits and Vegetables Processing Equipment
Global Fruit and Vegetable Processing Market
Fruits and Vegetables Processing Equipment
North America Avocado Processing Market
Fruits and Vegetables Processing Equipment
Juice Extractors Market
Fruits and Vegetables Processing Equipment
Smart Juicer Market
Fruits and Vegetables Processing Equipment
Smart Juicer Machine Market