
 Juice Extractors Market | 2026-2036
Juice Extractors Market Size, Share, and Industry Trends Forecast 2026-2036
Juice Extractors Market Outlook
The capital-intensity divergence between in-house motor manufacturing and outsourced assembly is redrawing competitive boundaries in the juice extractor industry. Breville Group Limited leverages vertical integration across its Australian and Chinese production bases to control blade and motor supply chains. Philips sustains technology leadership through proprietary slow-juicing systems that command premium positioning in European and Asian retail channels.
Juice extractors are electromechanical appliances designed to separate liquid from fruit and vegetable pulp through mechanical crushing, grinding, or pressing action, typically operating at speeds ranging from 40 RPM for cold-press units to 15,000 RPM for centrifugal models. The primary commercial purpose centers on delivering nutrient-dense beverages for household consumption, foodservice operations, and wellness institutions. Masticating and cold-press configurations capture expanding margin pools as consumers prioritize enzyme retention and lower oxidation rates over extraction speed. The commercial end-user segment, spanning restaurants and health clubs, outpaces household growth in absolute unit terms across developed Asian markets. Stainless steel and BPA-free material categories are displacing conventional plastic housings as durability and food-safety concerns reshape procurement criteria at the institutional level.
Regulatory oversight from the FDA in the United States, EFSA in Europe, and BIS in India governs electrical safety, food-contact material compliance, and energy efficiency labeling for juice extraction equipment. REACH restrictions on phthalates and FDA food-contact notifications directly constrain material selection for components exposed to acidic juices, elevating compliance costs for plastic-dependent manufacturers. Stakeholders must monitor evolving energy-efficiency standards and material disclosure requirements as procurement departments at health clubs and restaurant chains embed regulatory compliance into vendor qualification protocols.
Market Dynamics
Material compliance costs under REACH and FDA food-contact notifications are compressing margins for plastic-dependent manufacturers while rewarding stainless steel and BPA-free suppliers with institutional procurement access.
Growth Catalysts
- REACH Phthalate Restrictions:ECHA's tightening limits on plasticizers in food-contact applications are accelerating stainless steel housing adoption across European health club procurement chains.
- Health Club Channel Expansion:Wellness institutions in India and Southeast Asia are installing commercial-grade cold-press units to capture post-workout beverage demand from protein-oriented consumers.
- Slow-Juicing Technology:Masticating configurations operating below 100 RPM are capturing margin pools as enzyme retention becomes a decisive purchase criterion over extraction speed.
Market Restraints
- Copper and Rare Earth Volatility:Motor winding materials face price instability from concentrated Chilean and Chinese supply, compressing assembler margins on centrifugal models.
- Technical Oxidation Limits:Centrifugal units operating at 15,000 RPM cannot match cold-press nutrient retention, creating a permanent performance ceiling in wellness-focused segments.
- Substitution by Pre-Packaged Cold-Pressed Juices:HPP-treated retail beverages are capturing convenience-oriented consumers who reject appliance ownership entirely.
Strategic Opportunities
- India Appliance Retail Networks:Tier-2 and Tier-3 cities remain underpenetrated for premium slow-juicing systems as organized retail expands beyond Mumbai and Delhi.
- Restaurant Chain Central Kitchen Integration:Large-format masticating units with continuous feed mechanisms are displacing batch processing in high-volume foodservice operations.
- BIS Energy Efficiency Labeling:India's mandatory star-rating program for small appliances creates first-mover advantage for compliant manufacturers in government procurement.
Industry Challenges
- Food-Contact Certification Timelines:FDA notification reviews and EFSA material approvals extend product launch cycles by 8-14 months for novel polymer formulations.
- Electromechanical Integration Complexity:Combining precision gearboxes with brushless DC motors requires rare mechatronics expertise that assemblers struggle to source.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Juice Extractors Market |
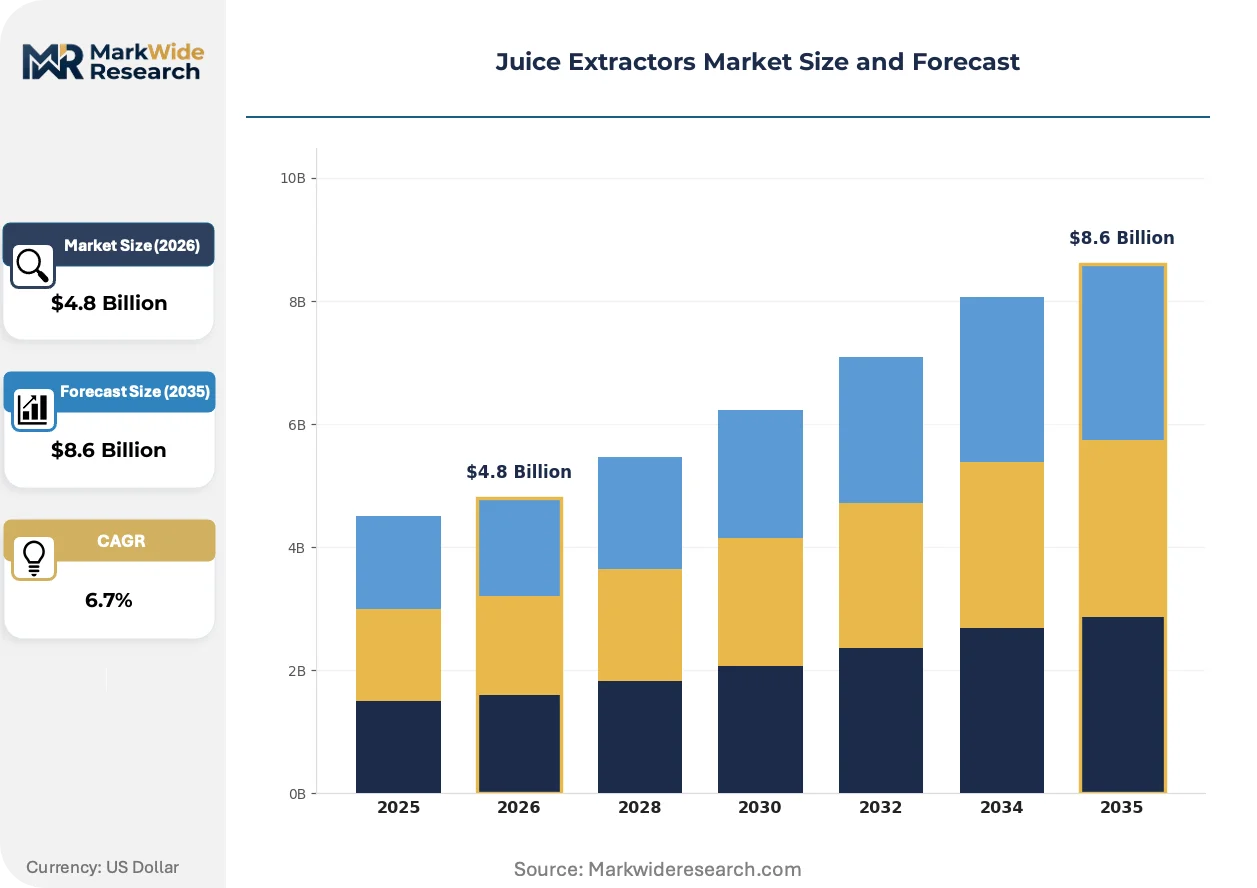
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal, Masticating, Twin Gear, Cold Press End User: Household, Commercial, Health Clubs, Restaurants Material: Plastic, Stainless Steel, Glass, BPA-Free Price Range: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Breville Group Limited, Conair LLC, Hamilton Beach Brands Inc., Hurom India, Joyoung Co. Ltd., Kenwood Limited, Philips, Cuisinart, Omega Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Juice Extractors Market Strategic Shifts
Active material substitution and regulatory disclosure mandates are reconfiguring supply chain priorities across extraction equipment manufacturing. Three distinct vectors are compressing legacy operating models.
Ceramic and stainless steel auger assemblies are displacing acetal and nylon components in masticating juicer construction. Health clubs and institutional buyers in Germany and Japan specify these materials to eliminate microplastic shedding concerns. The shift is compressing margins for molders dependent on commodity thermoplastics while rewarding metal-forming specialists with multi-year service contracts.
EFSA's updated guidance on food-contact material migration limits is forcing reformulation of gaskets and seals exposed to acidic citrus juices. Manufacturers serving European health club chains must now document compliance with specific migration thresholds for 28-day extraction tests. The burden falls heaviest on mid-tier assemblers lacking in-house polymer chemistry capabilities.
Wellness institutions are consolidating vendor relationships around outcome-based equipment leasing rather than capital purchase. Health clubs in South Korea and Australia now contract for guaranteed juice yield per kilogram of input produce, transferring operational risk to equipment suppliers. This compresses traditional distributor margins while elevating service-integrated manufacturers with predictive maintenance platforms.
Juice Extractors Market Segmentation
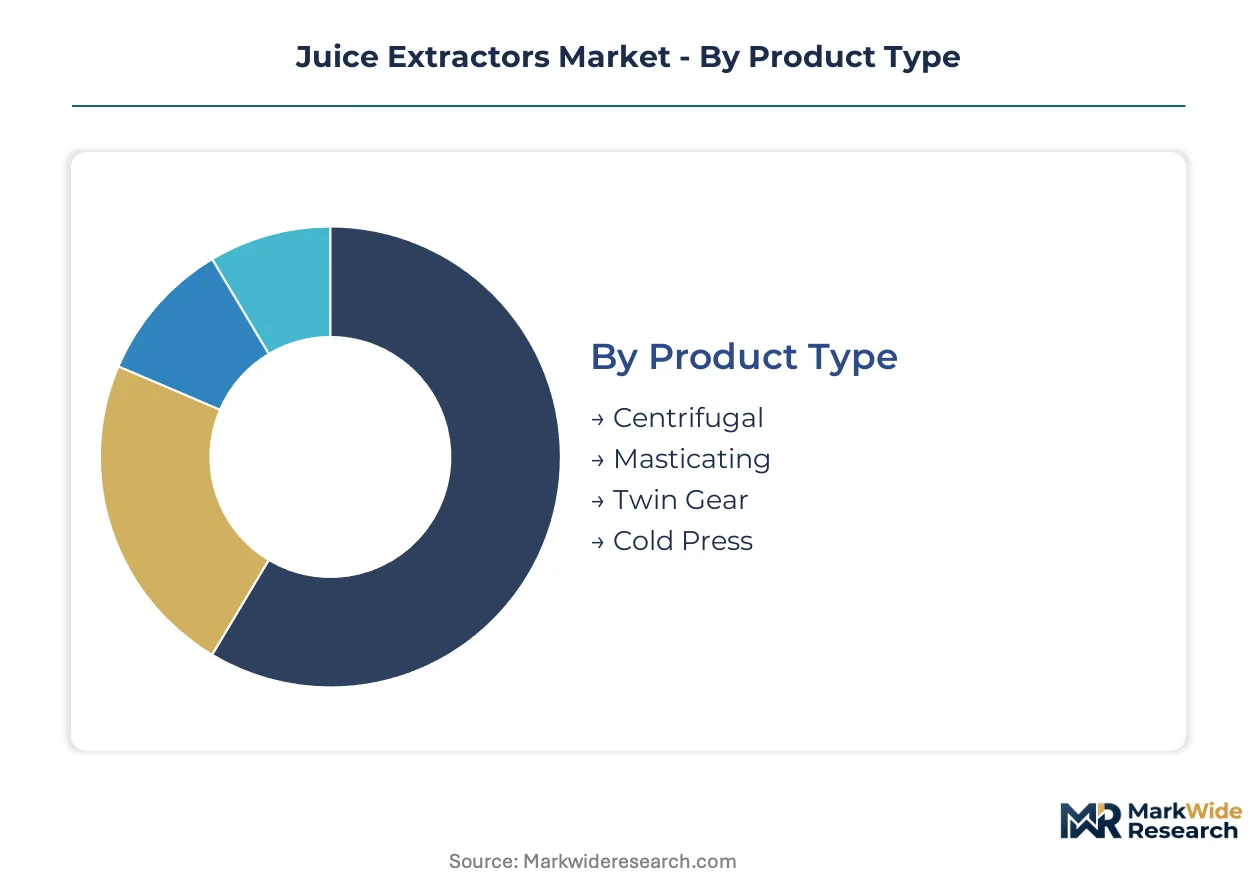
Segmentation in juice extractors reveals divergent supply chain configurations and regulatory exposure profiles. Manufacturers configure production lines differently for centrifugal versus cold-press architectures, while material choices determine institutional market access under REACH and FDA frameworks.
Product Type:
Domestic demand concentrates on centrifugal and masticating units across North American and European retail channels, while cold-press and twin-gear systems serve export-led institutional procurement in Asia-Pacific wellness markets.
- Centrifugal:High-speed extraction at 6,000-15,000 RPM separates pulp through centrifugal force. Household demand in the United States concentrates here due to lower price points, though oxidation limits constrain penetration in enzyme-conscious segments. Ease of use and rapid processing dominate purchase criteria.
- Masticating:Single-auger systems operating at 40-100 RPM crush produce against static screens. South Korean health clubs specify these units for post-workout juice bars, prioritizing nutrient retention over speed. The auger mechanism demands more durable materials, elevating stainless steel content.
- Twin Gear:Interlocking triturating gears press produce between stainless steel augers. German and Japanese institutional buyers favor this configuration for maximum yield efficiency in commercial kitchens.
- Cold Press:Hydraulic or pneumatic pressing without heat generation. Australian wellness retreats and California juice bars specify these systems for premium positioning, accepting 5-10 minute processing cycles.
Centrifugal units hold the largest share; momentum sits with masticating configurations as enzyme retention becomes decisive.
End User:
Cost tier stratification separates household price sensitivity from commercial durability requirements and health club outcome-based procurement models.
- Household:Individual consumers purchasing through appliance retail and e-commerce channels. Indian Tier-2 cities show expanding demand for compact masticating units as organized retail penetrates beyond metropolitan centers.
- Commercial:Foodservice operations including hotels, cafeterias, and catering services. High-volume continuous-feed requirements favor robust motor specifications and dishwasher-safe components.
- Health Clubs:Wellness institutions installing juice bars for member retention. South Korean chains now contract for guaranteed yield-per-kilogram metrics, transferring operational risk to equipment suppliers.
- Restaurants:Fine-dining and fast-casual establishments integrating fresh juice into menus. Central kitchen consolidation in US and European chains favors large-format units with automated feed systems.
Household volume dominates unit shipments; health clubs are climbing the fastest as wellness-oriented consumers shift from home-based to institutional juicing.
Material:
Supply concentration in Asian metal-forming and polymer processing centers shapes procurement geography, with European REACH compliance requirements filtering material selection for export-bound production.
- Plastic:ABS and polycarbonate housings for budget-tier household units. EFSA migration limits on phthalates and bisphenol compounds are accelerating displacement in food-contact applications.
- Stainless Steel:304 and 316 grade alloys for augers, screens, and housings. German health club procurement chains now specify full stainless construction to eliminate microplastic shedding concerns entirely.
- Glass:Borosilicate collection containers and feed chutes. Premium household positioning in Japan and Nordic markets favors glass for aesthetic and chemical-inertness properties.
- BPA-Free:Tritan copolyester and alternative thermoplastics meeting FDA food-contact notifications. Mid-range positioning bridges cost and compliance requirements for European and North American retail channels.
Plastic retains volume leadership; stainless steel is gaining share fastest as institutional procurement embeds durability and food-safety criteria.
Price Range:
Margin structure varies dramatically across tiers, with premium and luxury segments capturing disproportionate profit pools through technology differentiation and material specification.
- Budget:Entry-level centrifugal units under $100 retail. Chinese manufacturing concentration serves mass-market distribution through hypermarkets and online marketplaces.
- Mid-Range:$100-$300 positioning with masticating and basic cold-press options. European and North American retail channels concentrate volume here, balancing performance and accessibility.
- Premium:$300-$600 slow-juicing systems with proprietary auger geometries. South Korean and Australian health clubs specify these units for yield optimization and brand positioning.
- Luxury:$600+ commercial-grade and designer collaborations. Japanese and German institutional buyers and high-net-worth households drive limited but high-margin demand.
Mid-Range captures the largest unit volume; Premium is expanding most quickly as wellness institutions upgrade from capital purchase to outcome-based leasing models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German and Japanese procurement chains while cost-competitive manufacturing gravitates toward Chinese and Indian production bases. This asymmetry shapes regional investment flows and technology transfer patterns across the juice extractor value chain.
United States
Household centrifugal demand dominates mass-market retail channels, though California wellness retreats and New York health clubs are specifying cold-press systems for premium juice bar positioning. FDA food-contact notifications govern BPA-free material claims on product labeling. Austin and Los Angeles clusters host emerging direct-to-consumer brands targeting enzyme-conscious millennials.
Germany
Industrial procurement from commercial kitchens and institutional foodservice drives demand for twin-gear and large-format masticating configurations. EFSA migration limits on phthalates and bisphenol compounds filter material selection for export-bound production. The Stuttgart and Munich engineering corridors concentrate precision gearbox and stainless steel forming capabilities serving domestic and EU-wide distribution.
India
Tier-2 and Tier-3 city expansion through organized appliance retail is unlocking first-time household penetration for compact masticating units. BIS mandatory star-rating for small appliances creates compliance differentiation in government procurement channels. Hurom India and domestic competitors are building distribution networks through Bangalore and Hyderabad retail infrastructure.
Japan
Health club chains and corporate wellness programs specify slow-juicing systems with guaranteed yield-per-kilogram contracting. METI energy efficiency guidelines influence motor specification requirements for domestic market access. Osaka and Nagoya manufacturing bases supply precision auger assemblies and ceramic components for premium-tier regional export.
Australia
Outcome-based equipment leasing models are displacing capital purchase in health club procurement, transferring operational risk to suppliers with predictive maintenance platforms. TGA therapeutic claims oversight applies to enzyme retention marketing on wellness-oriented products. Melbourne and Sydney serve as test markets for service-integrated manufacturer business models before Asia-Pacific rollout.
Juice Extractors Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with proprietary slow-juicing systems commanding premium positioning while outsourced assembly operations capture volume in budget-tier retail. The vendor base stratifies across three tiers: integrated manufacturers controlling motor and blade supply chains, brand licensors relying on contract manufacturing, and regional assemblers serving price-sensitive emerging markets. Dominant competitive moves include backward integration into precision metal forming and outcome-based leasing partnerships with institutional wellness chains.
Among Asia-Pacific-based manufacturers, Joyoung Co. Ltd. and Hurom India exemplify the technology-specialist archetype with regional production depth, while Breville Group Limited anchors the integrated multinational tier with captive supply chain control across Australian and Chinese manufacturing bases. These three companies occupy distinct competitive positions without direct segment overlap, reflecting the market's structural segmentation between premium technology licensing and cost-engineered volume production.
| Leading Market Players |
|---|
| Breville Group Limited |
| Conair LLC |
| Hamilton Beach Brands Inc. |
| Hurom India |
| Joyoung Co. Ltd. |
| Kenwood Limited |
| Philips |
| Cuisinart |
| Omega Products |
| Others |
Value Chain & Pricing Dynamics
Ceramic and stainless steel auger assemblies replacing acetal and nylon components simultaneously redraw procurement geography toward German and Japanese metal-forming corridors while compressing margin pools for commodity thermoplastic molders. This material transition elevates landed costs for European health club chains by fifteen to twenty-five percent against legacy plastic-dependent configurations.
Pricing Analysis
The customization-premium spread separates standard centrifugal units from configured-to-order masticating systems with proprietary auger geometries and yield guarantees. Three-tier pricing structure across premium, standard, and economy levels stratifies by motor specification, material grade, and after-sales service bundling. Cost compression in budget tiers intensifies because Chinese assemblers compete on motor wattage and plastic housing costs. Household consumers in Indian Tier-2 cities exhibit highest price sensitivity; German institutional buyers accept premium positioning for full stainless construction and documented EFSA compliance.
Supply Chain Analysis
Port congestion on Shenzhen-Hamburg lanes and container availability constraints on trans-Pacific routes elevate inbound logistics costs for motor windings and precision gearbox components. Manufacturing concentrates in China, South Korea, and Vietnam for motor assembly and plastic injection molding, while Germany and Japan anchor auger fabrication and ceramic component finishing. Copper winding supply draws from Chilean concentrate and Chinese rare earth processing, creating single-source vulnerability for brushless DC motor specifications. Distribution runs through appliance retail networks in emerging markets and direct service contracts with health club chains in developed economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechatronics expertise scarcity constrains product development timelines, as precision gearbox integration with brushless DC motors demands specialized engineering talent concentrated in Stuttgart and Osaka corridors.
For Market Incumbents: Compound technology leadership through backward integration into ceramic auger fabrication and predictive maintenance platform deployment. Lock in multi-year service contracts with Australian health club chains before outcome-based leasing becomes standard procurement protocol. Defensive priority centers on denying emerging assemblers institutional market access through pre-emptive FDA and EFSA certification breadth. For New Entrants and Emerging Players: BIS energy efficiency fast-track certification unlocks government procurement channels in Indian Tier-2 and Tier-3 cities where organized retail penetration accelerates first-time household adoption. White-space concentration sits with compact masticating units priced between budget centrifugal and premium slow-juicing tiers. Channel strategy emphasizes appliance retail partnerships in Bangalore and Hyderabad over e-commerce price warfare. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier assemblers lacking in-house polymer chemistry capabilities to navigate EFSA migration limit compliance. Long-term viability favors manufacturers with captive stainless steel forming and health club service integration rather than pure-play brand licensors. Inflection signal to monitor: consolidation of vendor relationships around guaranteed yield-per-kilogram contracting in South Korean wellness chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Auger Production | Captures margin pools migrating from plastic molders while satisfying German health club microplastic elimination requirements. |
| Outcome-Based Equipment Leasing Programs | Transfers operational risk from health clubs to manufacturers with predictive maintenance platforms in Australian test markets. |
| BIS Star-Rating Compliance Investment | Creates first-mover advantage in Indian government procurement as mandatory labeling expands beyond metropolitan centers. |
| EFSA Migration Limit Pre-Certification | Accelerates European health club market access before mid-tier competitors complete 8-14 month notification review cycles. |
| Health Club Central Kitchen Partnerships | Displaces batch processing in high-volume foodservice operations through continuous-feed masticating unit specification. |
Study Parameters
Cross-validation between primary interviews with health club procurement directors, appliance retail category managers, and polymer chemistry specialists anchors the qualitative findings against customs records for motor component trade flows and BIS energy efficiency registration databases. Bottom-up triangulation aggregates unit shipment data across centrifugal, masticating, and cold-press configurations, while top-down verification reconciles aggregate value estimates against SEC filings from listed appliance manufacturers.
Sensitivity analysis around copper price volatility and REACH compliance cost trajectories shapes the forecast framework across the analysis window. Segmentation dimensions modeled include product architecture, end-user procurement model, material specification tier, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to historical penetration patterns in wellness institution channels and appliance retail expansion metrics.
Underlying assumptions cover sustained health club channel expansion, stable rare earth supply concentration, and incremental REACH restriction tightening, with deviation risk concentrated in substitution acceleration by HPP-treated retail beverages and electromechanical integration complexity bottlenecks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables Processing Equipment
Fruit Tree Shaker Market
Fruits and Vegetables Processing Equipment
Tomato Processing Market
Fruits and Vegetables Processing Equipment
Juicer Market
Fruits and Vegetables Processing Equipment
Global Fruit and Vegetable Processing Market
Fruits and Vegetables Processing Equipment
North America Avocado Processing Market
Fruits and Vegetables Processing Equipment
Avocado Processing Market
Fruits and Vegetables Processing Equipment
Fruit and Vegetable Processing Equipment Market
Fruits and Vegetables Processing Equipment
Juice Extraction Equipment Market
Fruits and Vegetables Processing Equipment
Grape Crusher Market
Fruits and Vegetables Processing Equipment
Global Fruit Processing Equipment Market
Fruits and Vegetables Processing Equipment
Smart Juicer Market
Fruits and Vegetables Processing Equipment
Smart Juicer Machine Market
Fruits and Vegetables Processing Equipment
Portable Juicer Market