
 Smart Juicer Market | 2026-2036
Smart Juicer Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Juicer Market Analytics
IoT-enabled recipe optimization and automated pulp-ejection algorithms is reconfiguring how smart juicers integrate with broader connected-kitchen architectures. Breville leverages app-based nutrient-tracking to differentiate its premium line. Hurom sustains leadership in slow-juicing mechanics through proprietary auger designs. Philips competes across price tiers with modular connectivity platforms that reduce hardware obsolescence.
A smart juicer combines precision motors, food-grade stainless-steel or Tritan housings, and Bluetooth or Wi-Fi modules to enable remote operation, usage analytics, and automated maintenance scheduling, serving residential and commercial operators seeking consistent yield with minimal manual intervention. Cold press and masticating systems command margin pools due to superior nutrient retention and longer operational lifespans. Smart connectivity technology anchors premium positioning as consumers prioritize app ecosystems over standalone appliances. Online retail channels capture volume growth through direct-to-consumer subscription models for consumable pairings.
The FDA governs food-contact material safety for juicer components sold in the United States, while the FCC certifies wireless transmission protocols in connected units. The EU Ecodesign Directive and REACH framework constrain motor-efficiency thresholds and chemical composition of plastics across European markets. Stakeholders must monitor evolving interoperability standards between appliance brands and dominant voice-assistant platforms to preserve addressable market scope.
Market Dynamics
Connected kitchen ecosystems are compressing replacement cycles as consumers prioritize interoperable appliances over standalone functionality, forcing manufacturers to embed modular connectivity architectures that preserve hardware relevance across software generations.
Growth Catalysts
- EU Ecodesign Directive:Motor-efficiency mandates from the European Commission are accelerating R&D investment in brushless DC motor platforms that reduce standby power consumption below 0.5 watts.
- Cold-press nutrient retention:Health-conscious households in Germany and the United States are driving premium tier demand for masticating systems that minimize oxidation and preserve enzyme activity.
- Direct-to-consumer subscription models:Online retail channels are capturing volume growth through consumable pairings that lock in recurring revenue and reduce customer acquisition costs.
Market Restraints
- Stainless-steel and Tritan input volatility:Food-grade housing materials face price pressure from energy-intensive smelting and petrochemical feedstock fluctuations.
- Voice-assistant platform fragmentation:Dominant smart home ecosystems operate walled gardens that threaten addressable market scope for appliance brands lacking certification partnerships.
- Manual juicer substitution:Low-cost hand-crank alternatives retain share among price-sensitive segments in emerging markets where electricity reliability varies.
Strategic Opportunities
- Commercial foodservice integration:High-throughput juice bars and wellness cafés in the United States represent an underpenetrated vertical for automated pulp-ejection and predictive maintenance systems.
- REACH-compliant bioplastics:The EU chemical framework is creating first-mover advantage for manufacturers developing housings from bio-based polymers that satisfy food-contact safety standards.
- Recipe algorithm monetization:App ecosystems are virtualizing content delivery, enabling subscription revenue from personalized nutrition plans and ingredient auto-replenishment.
Industry Challenges
- Interoperability certification timelines:FCC wireless protocol approval and voice-assistant platform integration create 6-12 month delays between hardware completion and market entry.
- Embedded systems talent scarcity:Firmware engineering for Bluetooth and Wi-Fi modules competes with broader IoT device sectors for limited semiconductor design capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Juicer Market |
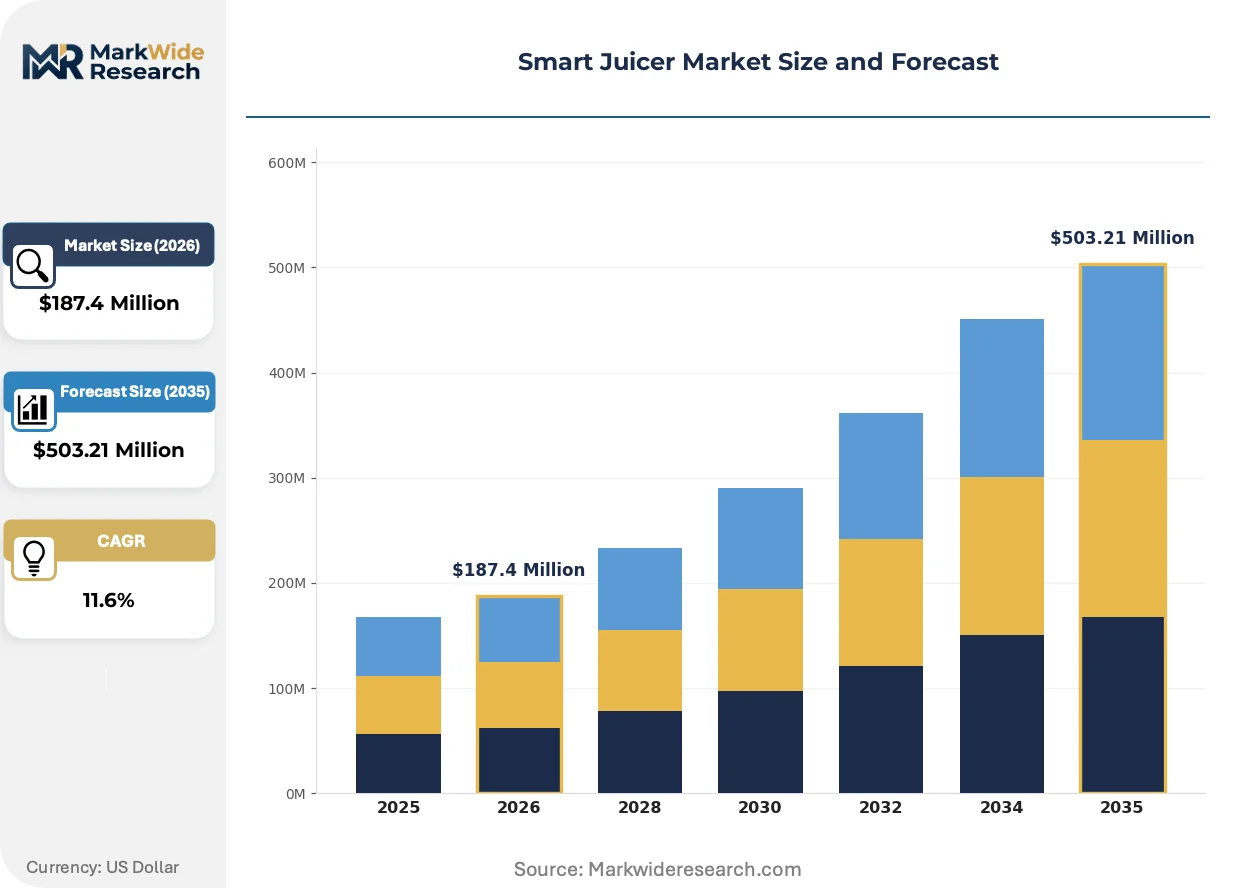
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal, Cold Press, Masticating, Manual Technology: Smart Connectivity, Voice Control, Touchscreen, Automated Cleaning End User: Household, Commercial, Health Clubs, Juice Bars Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Breville, Hurom, Philips, Panasonic, Kuvings, Braun, Cuisinart, Electrolux, Oster, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Juicer Market Evolving Landscape
Algorithmic personalization and predictive maintenance capabilities are redefining value capture models, shifting revenue from hardware margins to recurring software and consumable relationships.
Augmented reality troubleshooting interfaces are virtualizing technical support, reducing warranty service costs for manufacturers while accelerating resolution times for residential users. Early adopters in premium segments now expect visual guided repair rather than phone-based diagnostics. This compression of after-sales infrastructure is forcing traditional service networks to pivot toward installation and premium consulting.
The EU Ecodesign Directive's 2027 standby power thresholds are mandating capacitor and transformer redesigns that eliminate vampire draw. Motor suppliers are consolidating around unified platforms that satisfy both European efficiency mandates and North American voltage standards. German manufacturers are responding fastest, integrating power management ICs that dynamically scale motor output based on produce load detection.
Subscription bundling of organic produce with appliance financing is displacing transactional retail relationships in the United States. Wellness-focused direct-to-consumer brands are capturing household pantry share through vertically integrated supply chains that lock in juicing ingredient sourcing. This channel consolidation concentrates procurement power among platforms that control both hardware and consumable fulfillment.
Smart Juicer Market Segmentation
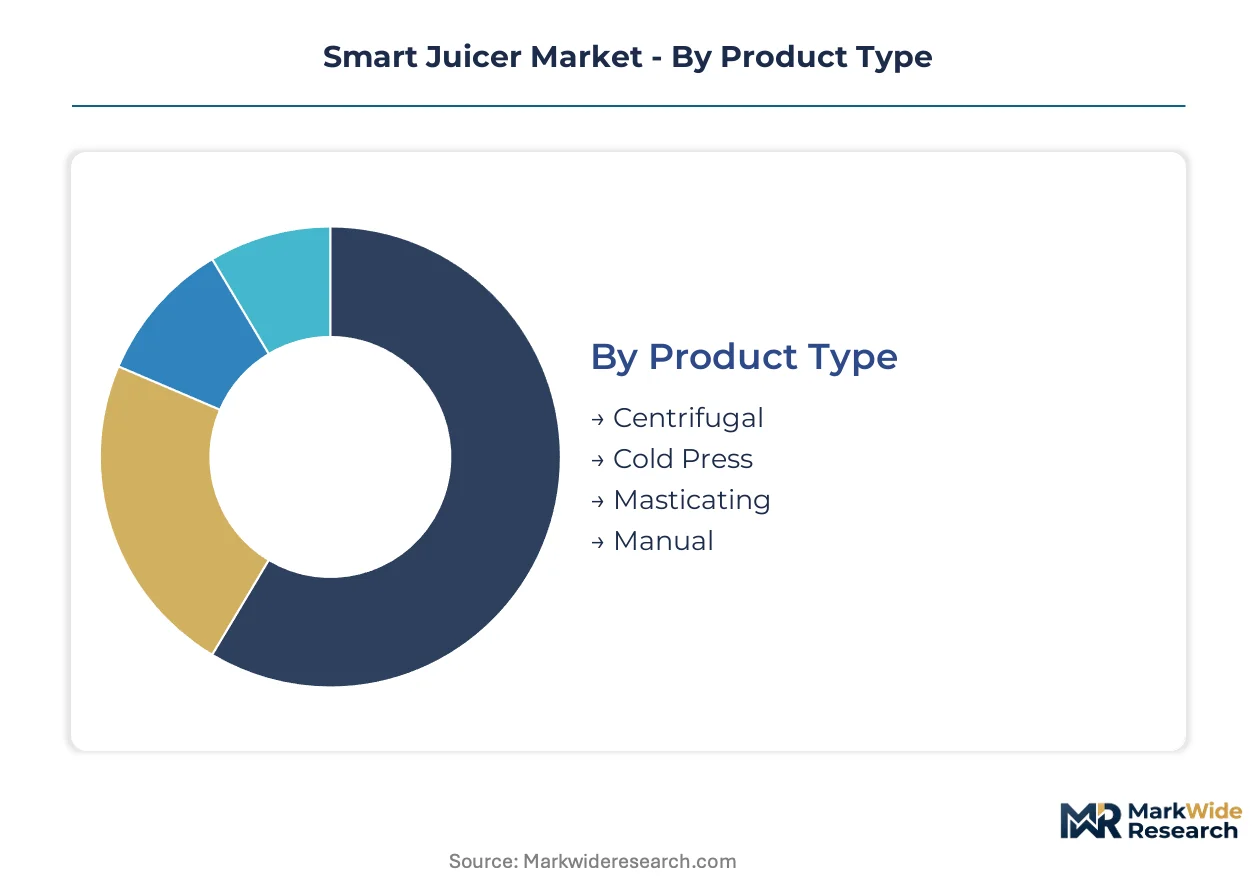
Smart juicer segmentation reveals divergent replacement dynamics across mechanical architectures and connectivity tiers. Cycle time varies dramatically between centrifugal units with shorter functional lifespans and masticating systems engineered for decade-long service intervals.
Product Type:
Cold press systems turn over slowest due to premium positioning and durability engineering, while centrifugal models cycle fastest through price-driven replacement.
- Cold Press:Auger-driven slow-rotation mechanics operating below 100 RPM minimize heat generation and oxidation. Health-conscious households in Germany drive demand for enzyme-preserving extraction, constrained by higher capital outlay and longer payback periods.
- Centrifugal:High-speed blade systems process produce through rapid filtration screens. United States residential kitchens favor speed and convenience despite nutrient degradation trade-offs and louder operational profiles.
- Masticating:Twin-gear or single-auger designs crush fibrous vegetables efficiently. Commercial operators seeking maximum yield per kilogram of input material specify these units for high-volume environments.
- Manual:Hand-crank mechanisms require no electrical infrastructure. Emerging markets with unreliable grid access retain this category for cost accessibility and portability.
Cold press dominates installed base in premium European households. Centrifugal is where expansion concentrates among first-time buyers seeking entry-level price points.
Technology:
Connectivity modules add cost tiers that stratify customer acquisition economics and recurring revenue potential.
- Smart Connectivity:Bluetooth and Wi-Fi modules enable remote operation, usage logging, and firmware updates. United States consumers prioritize app ecosystems that integrate with broader connected-kitchen platforms, though FCC wireless certification extends development timelines.
- Voice Control:Integration with dominant voice-assistant ecosystems permits hands-free operation. Kitchen environments with messy hands drive adoption where interoperability certifications are secured.
- Touchscreen:Embedded displays deliver recipe guidance and maintenance alerts. Premium positioning targets tech-forward households willing to pay interface premiums.
- Automated Cleaning:Self-rinsing cycles with dedicated filtration reduce manual maintenance burden. Commercial juice bars value labor savings that justify higher equipment expenditure.
Smart connectivity commands margin premiums. Automated cleaning is climbing fastest as commercial operators quantify labor cost reductions.
End User:
Volume concentration and margin structure diverge sharply between residential convenience seekers and commercial throughput maximizers.
- Household:Individual and family units purchasing for daily nutritional supplementation. United States health trends drive replacement of conventional blenders with dedicated juicing appliances.
- Commercial:Foodservice establishments requiring certified food-safe materials and warranty coverage for high-duty cycles. Juice bars and wellness cafés represent underpenetrated verticals for predictive maintenance systems.
- Health Clubs:Fitness centers offering post-workout recovery beverages. Equipment durability under constant use demands commercial-grade motor specifications.
- Juice Bars:Dedicated retail concepts with ingredient sourcing integration. Vertical supply chain control over organic produce procurement locks in recurring consumable revenue.
Household segment holds largest unit volumes. Juice bars are gaining share fastest through subscription bundling models that merge hardware financing with ingredient fulfillment.
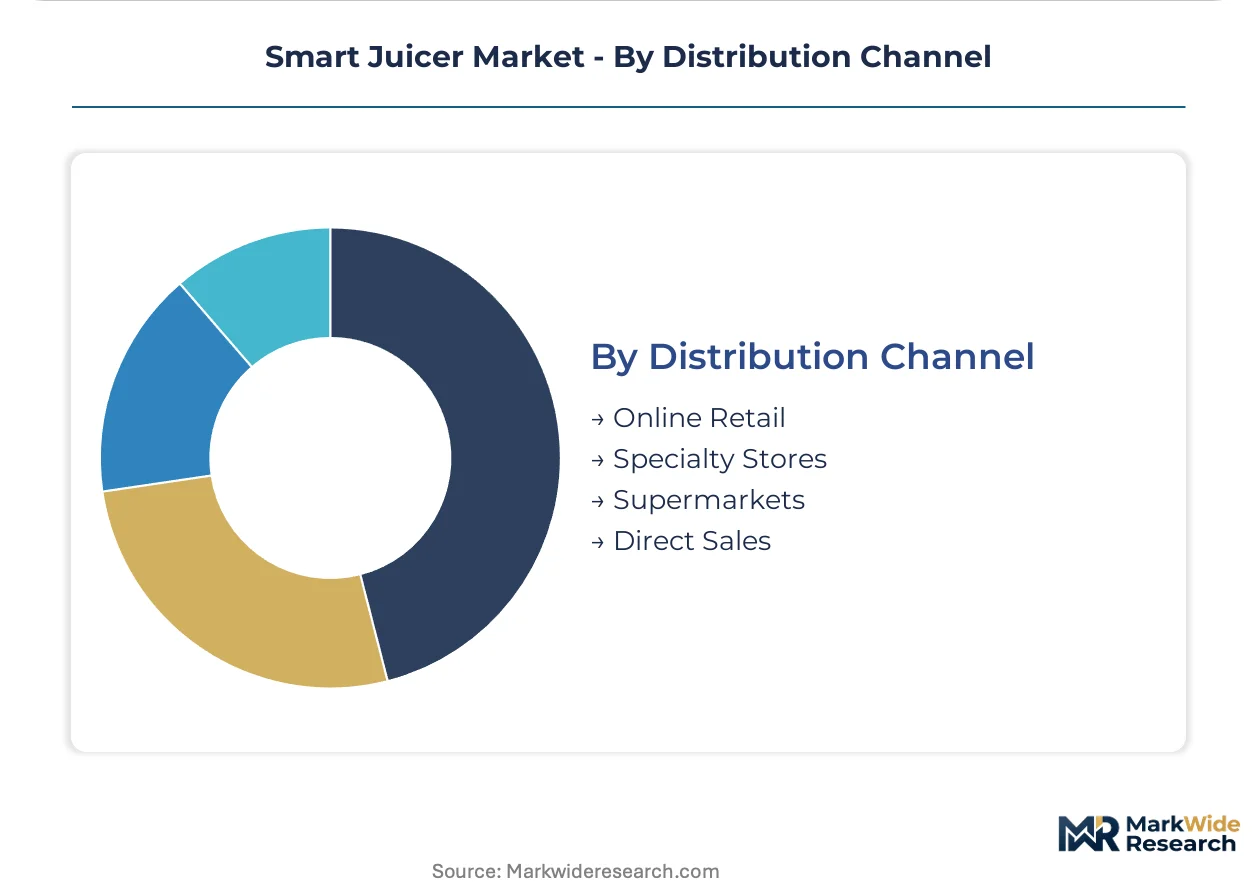
Distribution Channel:
Channel economics determine customer lifetime value capture and brand control over post-purchase relationships.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators. Subscription pairing with organic produce delivery concentrates procurement power among vertically integrated wellness brands.
- Specialty Stores:Kitchen appliance boutiques with demonstration capabilities. Hands-on product experience justifies premium positioning for masticating and cold press systems.
- Supermarkets:Mass retail placement for centrifugal entry-level models. Impulse purchase dynamics favor lower price points with limited connectivity features.
- Direct Sales:Manufacturer-owned channels including branded websites and showrooms. Maximum margin retention and customer data ownership support recurring revenue algorithm development.
Online retail captures volume growth through consumable bundling. Direct sales is expanding most quickly as manufacturers prioritize customer relationship ownership over third-party margin sharing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in smart juicer equipment tilt toward net importing in premium connectivity segments, while component sourcing concentrates in East Asian electronics clusters. Trade balances reflect divergent manufacturing capabilities across motor engineering, wireless module assembly, and food-grade metal fabrication.
United States
Connected-kitchen ecosystem integration and health-conscious household penetration anchor demand for app-enabled juicing appliances. The FCC certifies wireless transmission protocols under Part 15 rules, extending development timelines for Bluetooth and Wi-Fi module integration. California's Bay Area wellness technology cluster incubates direct-to-consumer brands merging hardware financing with organic produce subscription fulfillment.
Germany
Premium cold-press adoption and masticating system preference concentrate among enzyme-retention-focused consumers. The EU Ecodesign Directive mandates motor-efficiency thresholds and sub-0.5-watt standby power consumption, compressing design cycles for brushless DC platforms. Bavaria's appliance engineering corridor hosts manufacturers integrating power management ICs with load-detection algorithms for dynamic output scaling.
China
Domestic manufacturing scale and component ecosystem depth supply global demand for precision motors and connectivity modules. The country's national quality regulator enforces GB standards for food-contact material safety in electrical appliances. Shenzhen's electronics manufacturing cluster dominates Bluetooth and Wi-Fi module assembly, compressing procurement lead times for international brands.
Japan
Longevity-focused consumer electronics purchasing and compact kitchen form-factor requirements sustain demand for space-efficient juicing systems. METI's energy-efficiency labeling program creates procurement preference for low-standby-power designs among institutional buyers. Osaka's precision motor engineering district specializes in auger-drive mechanics for slow-rotation extraction systems.
United Kingdom
Wellness café proliferation and juice bar format expansion commercialize demand for automated cleaning and predictive maintenance capabilities. The UK's product safety regulator enforces electrical equipment standards aligned with EU CE marking requirements post-Brexit. London's foodservice equipment distribution network concentrates procurement authority for high-throughput commercial installations.
Smart Juicer Market Competitive Landscape
On the supply side, the industry is tiered across premium connectivity specialists, mass-market diversified appliance manufacturers, and component-integrated systems engineers. Strategic archetypes include ecosystem-anchored brands leveraging app platforms for recurring revenue, engineering-focused specialists preserving proprietary mechanical designs, and diversified conglomerates competing on procurement scale and distribution breadth. Dominant competitive moves center on voice-assistant interoperability certification partnerships and direct-to-consumer channel construction bypassing traditional retail margin structures.
Within the premium connectivity tier, Breville exemplifies ecosystem-anchored positioning through app-based nutrient-tracking integration, while Hurom occupies a specialist archetype preserving proprietary auger engineering for slow-juicing mechanics. Philips represents diversified conglomerate strategy, competing across price tiers with modular platform architectures that reduce hardware obsolescence risk.
| Leading Market Players |
|---|
| Breville |
| Hurom |
| Philips |
| Panasonic |
| Kuvings |
| Braun |
| Cuisinart |
| Electrolux |
| Oster |
| Others |
Value Network & Pricing Analysis
Tariff exposure on Chinese electronics modules compresses margin pools across all connectivity tiers while simultaneously forcing procurement diversification into Vietnam and Mexico assembly operations. This dual pressure reshapes both the spread between premium and entry-level juicer price points and the geographic footprint of supplier networks.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Certification grade for FCC wireless modules and FDA food-contact compliance separate tiers, with brand premium capturing additional markup. Cost compression in economy segments intensifies because of stainless-steel input volatility. Price-sensitive first-time centrifugal purchasers drive volume, while enzyme-retention-focused households show least sensitivity.
Supply Chain Analysis
Food-grade stainless-steel feedstock draws from German and Japanese metallurgical suppliers, while Tritan polymer hinges on petrochemical complexes in Texas and Rotterdam. Bluetooth module assembly centers on Shenzhen, with brushless DC motor engineering anchored in Bavaria and Osaka. Single-source vulnerability concentrates in power management IC fabrication. Distribution runs through vertically integrated wellness platforms and traditional appliance retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineering capacity for embedded connectivity systems constrains product launch velocity across all manufacturer tiers, creating acquisition premiums for teams with proven voice-assistant integration track records.
For Market Incumbents: Pre-empt voice-assistant platform fragmentation by securing interoperability certifications with dominant ecosystems before hardware lock-in. Acquire auger-drive engineering specialists to defend proprietary slow-juicing mechanics against modular connectivity entrants. Channel control through direct-to-consumer subscription bundling preserves margin against retail margin erosion. For New Entrants and Emerging Players: Establish a beachhead in commercial juice bar installations where predictive maintenance capabilities remain underdeveloped. Target wellness café operators seeking automated pulp-ejection systems with ingredient sourcing integration. Go-to-market through equipment financing bundled with organic produce procurement contracts bypasses incumbent retail shelf dominance. For Investors and Strategic Acquirers: EU Ecodesign Directive's standby power thresholds reshape the acquisition landscape toward brushless DC motor platforms and power management IC capabilities. Five-to-ten year viability favors manufacturers with backward integration into auger fabrication and captive app ecosystem development. Watch FCC certification backlog duration as inflection indicator for hardware launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Voice-Assistant Interoperability Certification | FCC-partnered ecosystem integration preserves addressable market scope against platform fragmentation. |
| Backward Integration into Auger Fabrication | Proprietary slow-juicing mechanics defend margin pools in enzyme-retention-focused premium tiers. |
| Direct-to-Consumer Subscription Launch | Organic produce bundling captures recurring revenue and reduces customer acquisition costs. |
| REACH-Compliant Bioplastic Development | Bio-based polymer housings create first-mover advantage under EU chemical framework constraints. |
| Predictive Maintenance Platform Deployment | Algorithmic service virtualization reduces warranty costs for commercial high-duty-cycle operators. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with appliance engineering directors, connected-kitchen platform managers, wellness brand procurement leads, and commercial foodservice equipment buyers; and secondary validation against FCC equipment authorization databases, EU Ecodesign Directive implementation reports, customs trade flow records, and SEC filings from diversified appliance manufacturers. Bottom-up unit economics triangulated against top-down market sizing across connectivity tiers and mechanical architectures.
Forecast inputs considered cold-press versus centrifugal replacement cycle divergence, voice-assistant certification timeline compression, and subscription bundling penetration rates across the analysis window. Segmentation modeling captured product type, connectivity technology, end-user vertical, and distribution channel dynamics. CAGRs derived from installed base turnover rates and premium tier mix shift assumptions.
Sensitivities concentrate around FCC wireless protocol approval delays, REACH bioplastic compliance timeline acceleration, and voice-assistant platform exclusivity shifts. Forecasts reflect documented assumptions on interoperability standard evolution and motor-efficiency mandate implementation pacing. Cross-checking against Ecodesign Directive enforcement intensity metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables Processing Equipment
Grape Crusher Market
Fruits and Vegetables Processing Equipment
Juicer Market
Fruits and Vegetables Processing Equipment
Fruit and Vegetable Processing Equipment Market
Fruits and Vegetables Processing Equipment
Global Fruit Processing Equipment Market
Fruits and Vegetables Processing Equipment
North America Avocado Processing Market
Fruits and Vegetables Processing Equipment
Fruit Tree Shaker Market
Fruits and Vegetables Processing Equipment
Juice Extractors Market
Fruits and Vegetables Processing Equipment
Portable Juicer Market
Fruits and Vegetables Processing Equipment
Smart Juicer Machine Market
Fruits and Vegetables Processing Equipment
Avocado Processing Market
Fruits and Vegetables Processing Equipment
Global Fruit and Vegetable Processing Market
Fruits and Vegetables Processing Equipment
Tomato Processing Market
Fruits and Vegetables Processing Equipment
Juice Extraction Equipment Market