
 Avocado Processing Market | 2026-2036
Avocado Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Avocado Processing Market Intelligence
Mexican Hass avocado packers is hardening capacity discipline after successive climate-pressured harvests. Calavo Growers leverages its vertical integration from orchard networks in California and Mexico through to retail-ready guacamole production. Mission Produce anchors global distribution through its ripening center network spanning the Netherlands and the United States. Westfalia Fruit differentiates through year-round supply security powered by its multi-hemisphere orchard footprint in South Africa, Peru, and Colombia.
Avocado processing transforms raw fruit into shelf-stable or value-added formats through mechanical pulping, enzymatic stabilization, cold-pressing for oil extraction, or individual quick freezing for diced products, with primary commercial purpose extending perishability from days to months while preserving lipid profiles and organoleptic properties. Oil extraction commands the deepest margin pools due to supercritical CO2 and expeller-press technology barriers, whereas puree volume leads in absolute tonnage driven by foodservice guacamole and infant nutrition demand. Frozen diced segments compete on harvest timing and varietal specificity, with Peruvian Hass gaining share against traditional Mexican supply during Northern Hemisphere off-seasons.
FDA enforcement of Food Safety Modernization Act preventive controls and EPA wastewater discharge limits for oil extraction facilities shape capital deployment and site selection across the United States, while Mexico's SENASICA phytosanitary protocols govern export eligibility to protected markets. The EU's deforestation regulation and EFSA novel food assessments for emerging avocado-derived ingredients will filter market access for non-compliant suppliers. Stakeholders must monitor water stress indices across Michoacán and Jalisco growing belts as the critical variable for supply continuity and processing margin stability.
Market Dynamics
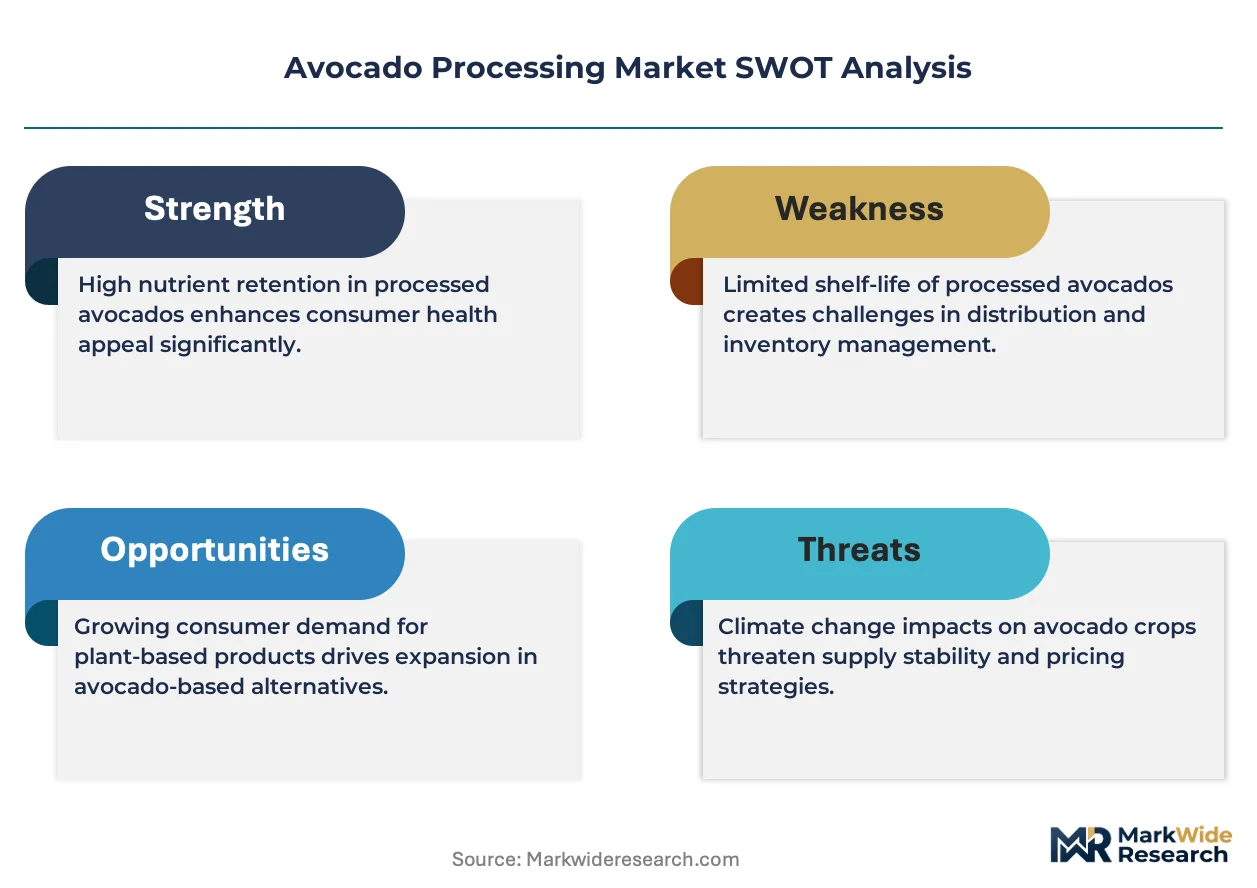
Water stress indices across Michoacán and Jalisco growing belts are tightening raw material availability, forcing processors to harden supply contracts and relocate capacity toward Peruvian and Colombian orchard networks with more stable precipitation profiles.
Growth Catalysts
- Clean-label formulation mandates:North American food and beverage manufacturers are expanding avocado-based ingredient portfolios to meet retailer clean-label requirements, pulling additional puree and oil volume through processing facilities.
- HACCP traceability protocols:FDA preventive controls under the Food Safety Modernization Act are mandating lot-level tracking for imported processed avocado, advantaging vertically integrated packers with captive orchard-to-retail documentation systems.
- Supercritical CO2 extraction:Oil processors deploying this technology command premium positioning in functional food and cosmetic applications where lipid profile preservation determines contract renewals.
Market Restraints
- Input cost volatility:Mexican Hass raw material pricing swings with alternate-bearing cycles and climate-pressured harvests, compressing margin predictability for non-integrated processors.
- Supply concentration risk:Michoacán state dominates global Hass exports, creating single-point vulnerability when SENASICA phytosanitary suspensions interrupt shipments to protected markets.
- Substitution threat:Sunflower and olive oil blenders are reformulating with algae-derived omega alternatives in infant nutrition segments where avocado oil previously held formulation preference.
Strategic Opportunities
- EU deforestation regulation compliance:Early alignment with EUDR geolocation requirements opens preferential access to European retail and foodservice channels as the regulation filters non-compliant suppliers from 2025 onward.
- Infant nutrition application expansion:EFSA novel food assessments for avocado-derived phospholipid ingredients could unlock pediatric formula contracts currently served by dairy and marine lipid suppliers.
- Multi-hemisphere sourcing networks:Processors establishing year-round supply security through South African and Peruvian orchard partnerships can displace seasonal Mexican-dependent competitors in Northern Hemisphere off-seasons.
Industry Challenges
- Cold chain integrity gaps:Frozen diced avocado processors face spoilage losses where last-mile refrigerated transport infrastructure remains underdeveloped in emerging market distribution corridors.
- Enzymatic browning control:Maintaining organoleptic stability in high-pressure processed guacamole requires precise ascorbic acid and citric acid dosing protocols that strain quality control staffing at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Avocado Processing Market |
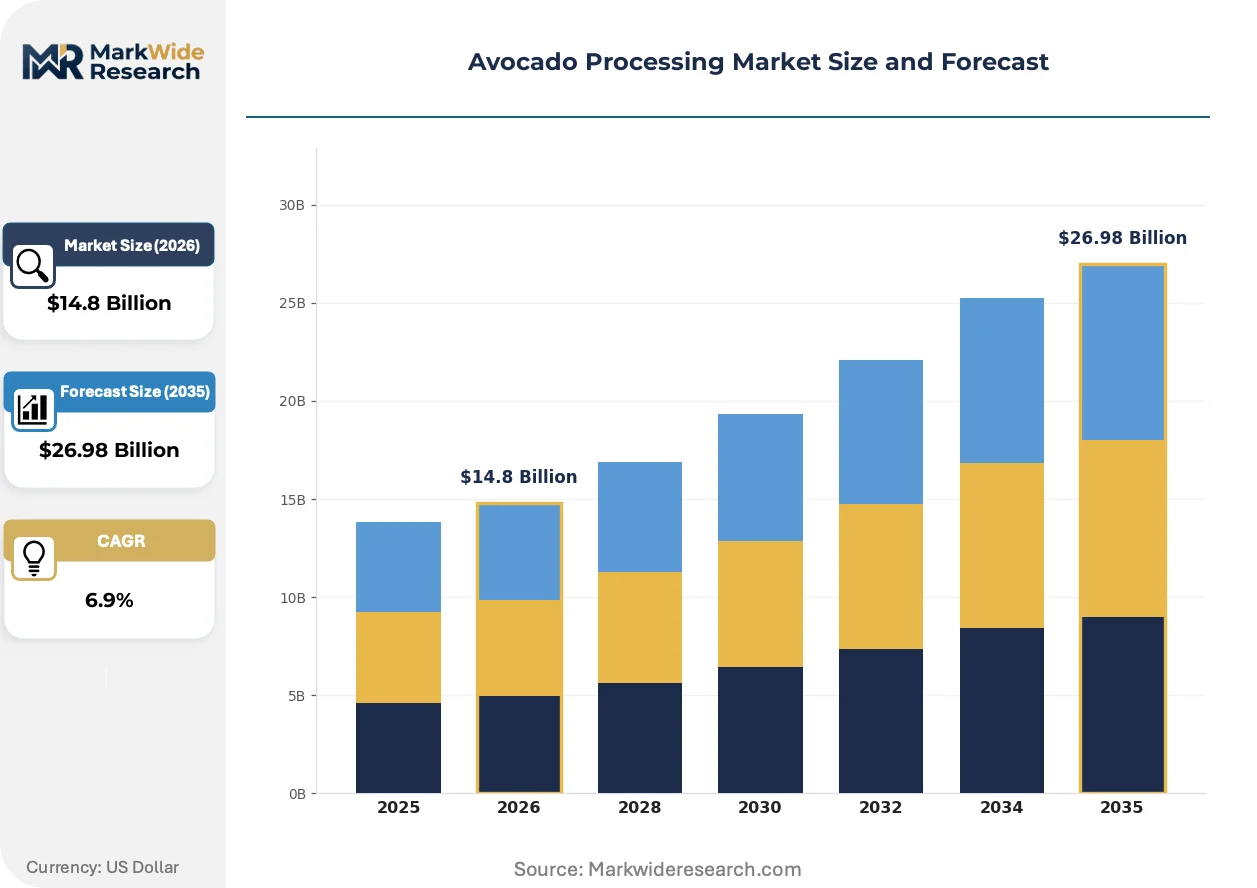
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Puree, Oil, Diced, Frozen End Use Industry: Food & Beverage, Cosmetic, Dietary Supplements, Spreads Packaging Type: Glass Bottles, Tetra Packs, Pouches, Jars Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Calavo Growers, Mission Produce, Westfalia Fruit, MegaMex Foods, Olivado Group, Avocados From Mexico, Yucatan Foods, Spectrum Organic Products, Grupo Industrial Batellero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Avocado Processing Market Strategic Shifts & Innovations
Processing technology and regulatory compliance frameworks are converging to reshape competitive positioning, with automation investments and sustainability verification becoming inseparable from market access rather than optional differentiation.
High-pressure processing (HPP) for guacamole and avocado puree is consolidating shelf-life extension capabilities previously fragmented across thermal pasteurization and chemical preservative approaches. Foodservice distributors and retail private-label programs in the United States are adopting HPP lines at accelerating cadence. This technology compression is enabling clean-label claims that command placement in premium chilled deli sections while displacing traditional frozen formats.
The EU Deforestation Regulation (EUDR) is mandating geolocation traceability for all avocado-derived products entering European Union markets, requiring processors to deploy satellite-verified farm polygon documentation. Compliance infrastructure investments are diverting capital from expansion budgets among mid-tier packers. Smallholder-dependent supply chains in Mexico face the steepest adaptation curve as aggregation systems lack the technical capacity to meet EUDR data requirements.
Ingredient buyers in infant nutrition and functional food segments are consolidating supplier relationships around processors with dual certifications for organic handling and infant-grade production. Long-tail distributors serving independent natural products retailers are losing volume to direct-procurement arrangements between multinational formula manufacturers and vertically integrated avocado oil refiners. This channel compression is most visible in Germany and the Netherlands where DSM and FrieslandCampina have tightened approved supplier lists.
Avocado Processing Market Segmentation
Segmentation in avocado processing reveals how capital deployment, regulatory exposure, and margin architecture vary across product formats and customer channels. Processors must match equipment specialization to segment-specific shelf-life and organoleptic requirements.
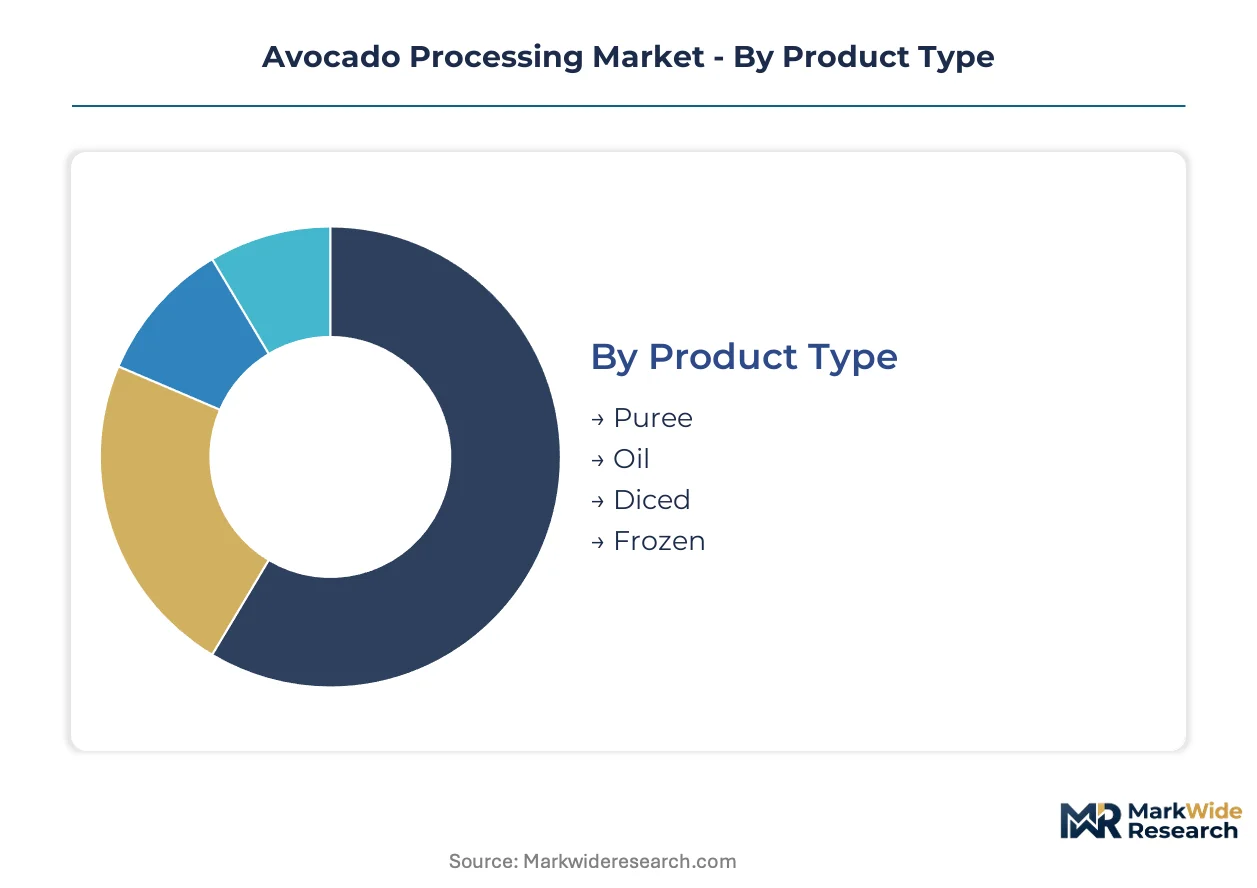
Product Type:
Capital intensity peaks with oil extraction infrastructure, where supercritical CO2 and cold-press systems demand the heaviest upfront investment, while puree lines achieve scale through more modular high-pressure processing configurations.
- Puree:Mechanical pulping followed by enzymatic stabilization yields pumpable pulp for foodservice guacamole and infant nutrition bases. Demand concentrates in North American retail and foodservice channels where clean-label positioning drives HPP adoption over thermal pasteurization.
- Oil:Cold-pressing and supercritical CO2 extraction preserve lipid profiles for cosmetic and functional food applications. European cosmetic formulators and infant nutrition manufacturers in Germany and the Netherlands command premium positioning for certified organic and extra-virgin grades.
- Diced:Individual quick freezing of hand-cut or machine-diced fruit extends perishability for foodservice salad and bowl applications. Peruvian Hass supply gains share during Northern Hemisphere off-seasons when Mexican harvest volumes contract.
- Frozen:Blast-frozen halves and chunks serve industrial ingredient buyers with lower organoleptic requirements. Cold chain infrastructure gaps in emerging market distribution corridors constrain penetration beyond established retail networks.
Most installed capacity flows through Puree. Expansion is steepest in Oil.
End Use Industry:
Application-driven formulation standards split the market between food-grade mass volume and pharmaceutical-grade margin pools, with cosmetic and dietary supplement channels imposing the most stringent certification burdens.
- Food & Beverage:Guacamole retail packs, prepared salad kits, and smoothie bases absorb the majority of processed avocado volume. Clean-label mandates from US and European retailers are pulling HPP-treated products into premium chilled deli sections.
- Cosmetic:Emollient and anti-aging formulations leverage avocado oil's fatty acid profile for skincare and haircare applications. French and German cosmetic manufacturers dominate procurement, with EUDR traceability requirements filtering supplier eligibility.
- Dietary Supplements:Softgel encapsulation of avocado-derived unsaponifiables targets joint health positioning. EFSA novel food assessments govern European market access, while FDA dietary supplement regulations shape US formulation claims.
- Spreads:Shelf-stable avocado butters and compound spreads compete with nut-based alternatives in natural products retail. Price positioning sits below premium nut butters but above conventional vegetable oil spreads.
Food & Beverage commands absolute volume. Cosmetic applications are climbing the fastest.
Packaging Type:
Packaging selection tracks shelf-life requirements and retail channel placement, with aseptic and barrier technologies commanding equipment premiums that separate integrated processors from tolling operations.
- Glass Bottles:Premium oil presentation for specialty retail and gift channels. Weight and fragility constrain e-commerce penetration despite superior oxygen barrier properties.
- Tetra Packs:Aseptic carton systems enable ambient distribution of purees in European and Latin American retail. Capital requirements for filling line installation favor large-scale processors.
- Pouches:Flexible retort and HPP-compatible formats reduce shipping cube for foodservice and club store channels. Stand-up pouch adoption is accelerating in US retail guacamole.
- Jars:Traditional guacamole and spread packaging with modified atmosphere sealing. Refrigerated distribution requirements limit reach compared to shelf-stable alternatives.
Most throughput moves through Jars. Pouch formats are gaining share fastest.
Distribution Channel:
Channel selection determines margin capture and traceability documentation intensity, with direct procurement arrangements between processors and multinational buyers displacing traditional distributor intermediaries in high-volume segments.
- Online:Direct-to-consumer oil and premium puree sales through brand-owned storefronts and Amazon. Cold chain fulfillment costs constrain frozen product penetration.
- Supermarkets:Private-label guacamole and retail oil packs drive volume in Kroger, Albertsons, and Tesco networks. Slotting fees and promotional spending requirements favor scaled suppliers.
- Specialty Stores:Natural products retailers and gourmet food shops command organic and fair-trade certified positioning. Whole Foods Market's supplier approval process shapes formulation and packaging decisions.
- Wholesale:Foodservice distributors including Sysco and US Foods handle bulk puree and diced product for restaurant chains. Contract specifications mandate HACCP documentation and lot-level traceability.
Wholesale channels handle the largest tonnage. Online distribution is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting processing investments toward jurisdictions with lower compliance costs and more stable water availability. Producers are relocating capacity from drought-stressed Mexican growing belts to South American and African orchard networks with favorable precipitation profiles and emerging regulatory frameworks.
United States
Foodservice distributors in California and Texas are driving HPP guacamole adoption through direct procurement contracts with retail chains. FDA preventive controls under FSMA mandate lot-level traceability for imported processed avocado, advantaging vertically integrated operators with captive documentation systems. The Central Valley processing corridor anchors domestic oil extraction capacity, though EPA wastewater discharge limits constrain expansion at existing facilities.
Mexico
Michoacán state packers face tightening raw material availability as water stress indices compress successive harvest cycles. SENASICA phytosanitary protocols govern export eligibility to protected markets, with suspension events creating shipment volatility. Jalisco's emerging orchard belt is attracting processing capacity relocation from drought-impacted Michoacán growing zones.
Peru
Hass avocado exports to Northern Hemisphere markets are climbing during Mexican off-season windows, with Ica and La Libertad valleys expanding IQF diced capacity. The national agricultural health service enforces phytosanitary certification aligned with EU and US import requirements. Lima-based processors are investing in cold-chain infrastructure to reduce post-harvest losses in coastal export corridors.
Netherlands
Rotterdam and Venlo distribution hubs anchor European ripening and repackaging operations for retail chains across Germany, France, and the UK. EUDR geolocation traceability requirements are filtering supplier eligibility, with early-compliant processors capturing preferential shelf placement. Dutch traders are consolidating procurement relationships with EUDR-certified Latin American packers ahead of full enforcement.
South Africa
Western Cape and Limpopo orchard networks are supplying year-round avocado oil to European cosmetic formulators seeking multi-hemisphere supply security. The country's phytosanitary authority maintains export certification protocols recognized by EU and UK regulators. Cape Town-area processors are expanding cold-press capacity to serve German and French skincare manufacturers.
Avocado Processing Market Key Industry Players
Mexican producers anchor one tier; Californian and South African specialists hold differentiated positions in premium oil and year-round supply segments. Market structure concentrates around vertically integrated packers with captive orchard networks and tolling operators serving seasonal demand surges. Three archetypes dominate: multi-hemisphere orchard owners, regional puree specialists with HPP capabilities, and commodity oil refiners competing on extraction efficiency. Capacity expansion and EUDR compliance infrastructure represent the dominant competitive moves.
Among North American integrated operators, Calavo Growers exemplifies the orchard-to-retail archetype through its cross-border California-Mexico production network. Mission Produce occupies a position defined by global distribution infrastructure spanning ripening centers in multiple continents. Westfalia Fruit represents the multi-hemisphere supply security model with orchard assets distributed across southern hemisphere growing regions. These three entities illustrate how geographic diversification strategies are reshaping competitive positioning in processed avocado supply chains.
| Leading Market Players |
|---|
| Calavo Growers |
| Mission Produce |
| Westfalia Fruit |
| MegaMex Foods |
| Olivado Group |
| Avocados From Mexico |
| Yucatan Foods |
| Spectrum Organic Products |
| Grupo Industrial Batellero |
| Others |
Cost & Logistics Intelligence
High-pressure processing technology adoption is compressing cost structures for guacamole manufacturers while simultaneously concentrating pricing power among capital-equipped processors with HPP line investments. Mexican Hass raw material volatility feeds directly into puree contract pricing, forcing buyers to choose between long-term offtake commitments at fixed premiums or spot-market exposure during alternate-bearing harvest cycles.
Pricing Analysis
Retailer markup layers in North American supermarkets separate premium HPP guacamole from conventional thermal-pasteurized alternatives, with price differentiation driven by organic certification grade and clean-label positioning. Cost compression in frozen diced segments is intensifying because Peruvian suppliers are gaining volume share during Mexican off-seasons. Foodservice distributors exhibit the highest price sensitivity due to thin menu-margin constraints, while cosmetic formulators in Germany and France show the least sensitivity for certified organic oil grades.
Supply Chain Analysis
Hass avocado supply rests on orchard networks concentrated across Mexico, Peru, and Colombia, with Michoacán state anchoring raw material flows for North American processors. Cold-press oil extraction equipment and IQF freezing infrastructure represent critical capital dependencies. Single-source vulnerability around SENASICA phytosanitary certification suspension events creates shipment volatility. Distribution runs through Rotterdam and Venlo ripening hubs for European retail placement, with direct procurement displacing traditional trader intermediaries in high-volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Avocado processing offers margin expansion through premium-tier clean-label positioning and cost-down automation in HPP lines. The shift from thermal pasteurization to high-pressure methods enables price capture in chilled deli sections previously unreachable.
For Market Incumbents: To counter water stress compression in Michoacán and Jalisco growing belts, harden supply contracts with Peruvian and Colombian orchard partners for year-round volume security. Invest in EUDR geolocation traceability infrastructure ahead of full enforcement to capture preferential European retail placement.
For New Entrants and Emerging Players: The gap between premium organic oil pricing and economy-grade conventional puree creates white-space opportunity in mid-tier certified conventional segments. Target South African and Colombian processing capacity for European cosmetic formulator contracts. Enter through tolling arrangements with established packers to bypass capital-intensive HPP equipment requirements.
For Investors and Strategic Acquirers: Valuations sit cheapest among non-integrated tolling operators lacking captive orchard assets. Long-term viability favors processors with multi-hemisphere supply networks spanning three or more growing regions. Watch water stress indices across Michoacán as the inflection signal for supply disruption and margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| EUDR Compliance Infrastructure | Geolocation traceability systems secure European retail access as SENASICA-aligned packers face filtering. |
| Multi-Hemisphere Orchard Partnerships | South African and Peruvian supply networks displace seasonal Mexican dependence in Northern Hemisphere off-seasons. |
| HPP Line Expansion | High-pressure processing capacity captures clean-label premium placement in US chilled deli sections. |
| Backward Integration into Orchards | Captive Hass supply insulates margin predictability from alternate-bearing cycle volatility. |
| Infant Nutrition Certification | EFSA novel food assessments unlock pediatric formula contracts from dairy and marine lipid incumbents. |
Research Approach
Direct dialogue with Hass avocado packers, foodservice procurement directors, cosmetic formulator sourcing leads, and infant nutrition ingredient buyers grounded qualitative findings in operational reality. Secondary validation drew from FDA FSMA guidance documents, SENASICA phytosanitary bulletins, EFSA novel food assessment registers, and EU customs trade flow data. Bottom-up volume modeling triangulated against top-down category spend estimates across puree, oil, and diced product formats.
Bottom-up segment analysis modeled product type, end-use industry, packaging format, and distribution channel dimensions across the projection horizon. CAGRs were derived from historical volume trajectories adjusted for technology adoption curves and regulatory enforcement timelines. Forecast inputs incorporated water stress indices for Michoacán and Jalisco growing belts alongside HPP equipment installation rates in North American processing facilities.
Caveats apply where SENASICA suspension events, EUDR enforcement delays, or substitution by algae-derived omega alternatives could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables Processing Equipment
Global Fruit and Vegetable Processing Market
Fruits and Vegetables Processing Equipment
Fruit Tree Shaker Market
Fruits and Vegetables Processing Equipment
Juice Extractors Market
Fruits and Vegetables Processing Equipment
North America Avocado Processing Market
Fruits and Vegetables Processing Equipment
Fruit and Vegetable Processing Equipment Market
Fruits and Vegetables Processing Equipment
Tomato Processing Market
Fruits and Vegetables Processing Equipment
Smart Juicer Machine Market
Fruits and Vegetables Processing Equipment
Juice Extraction Equipment Market
Fruits and Vegetables Processing Equipment
Grape Crusher Market
Fruits and Vegetables Processing Equipment
Juicer Market
Fruits and Vegetables Processing Equipment
Global Fruit Processing Equipment Market
Fruits and Vegetables Processing Equipment
Portable Juicer Market
Fruits and Vegetables Processing Equipment
Smart Juicer Market