
 Japan Pet Food Market | 2026-2036
Japan Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Pet Food Market Outlook
Specialty pet shops and veterinary clinics is rewriting how premium nutrition reaches Japanese households. DoggyMan H.A. Co., Ltd. leverages its deep veterinary channel relationships to sustain recurring revenue from prescription diet lines. Unicharm Corp dominates the cat food segment through shelf-stable wet formats tailored to aging feline populations. Nippon Pet Food Co. anchors the mid-market with grain-inclusive dry formulations distributed through mass retail.
Japan pet food encompasses commercially manufactured nutritional products formulated to AAFCO or Japanese Pet Food Association nutrient profiles, typically comprising protein meals, fats, vitamins, and moisture-controlled matrices processed through extrusion, retorting, or freeze-drying to deliver complete diets for companion animals. Dry food occupies the largest volume share due to storage convenience and lower per-feeding cost, though wet food captures disproportionate margin pools as owners prioritize hydration and palatability for senior pets. Treats represent the fastest-growing product type, fueled by functional positioning around dental health and joint support that commands price premiums over standard rewards.
METI enforces pet food manufacturing standards under the Food Sanitation Act, while the Japanese Pet Food Association administers voluntary ingredient certification and labeling guidelines that shape consumer trust and retail access. PMDA oversight of veterinary prescription diets creates a regulated pathway for therapeutic nutrition that limits competition to clinically validated suppliers. Stakeholders must monitor how evolving sustainability disclosure requirements and alternative protein acceptance reshape ingredient sourcing strategies and brand positioning.
Market Dynamics
Pet humanization in Greater Tokyo and Osaka Prefecture is compressing purchase cycles and elevating ingredient transparency expectations beyond METI's baseline disclosure mandates.
Growth Catalysts
- Urban Cat Ownership Concentration:Tokyo apartment dwellers favor compact wet food formats that address hydration needs without refrigeration burden.
- METI Ingredient Disclosure Rules:Mandatory sourcing transparency under the Food Sanitation Act rewards early compliance with veterinary channel access.
- Aging Feline Demographics:Renal-support formulations capture recurring purchases from households with cats exceeding twelve years of age.
Market Restraints
- Animal Protein Input Volatility:Domestic poultry and fishmeal supply fluctuations force reformulation cycles that strain R&D budgets.
- Mass Retail Channel Concentration:Four national supermarket chains control shelf access, extracting slotting fees that erode mid-market margins.
- PMDA Prescription Diet Barriers:Clinical validation requirements limit therapeutic nutrition entrants to established veterinary suppliers.
Strategic Opportunities
- Freeze-Dried Raw Formats:Premium positioning in Sapporo and Fukuoka metros bypasses refrigeration constraints through moisture removal technology.
- Subscription Direct-to-Consumer Models:Recurring delivery platforms capture data on consumption patterns for predictive formulation.
- Alternative Protein Acceptance:Insect and cultivated protein ingredients align with sustainability disclosure requirements under evolving METI guidelines.
Industry Challenges
- Veterinary Nutritionist Talent Scarcity:Formulation science expertise concentrates among legacy manufacturers, constraining new entrant product development velocity.
- Retort Processing Capacity Bottlenecks:Wet food sterilization equipment requires capital deployment that smaller regional producers cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Pet Food Market |
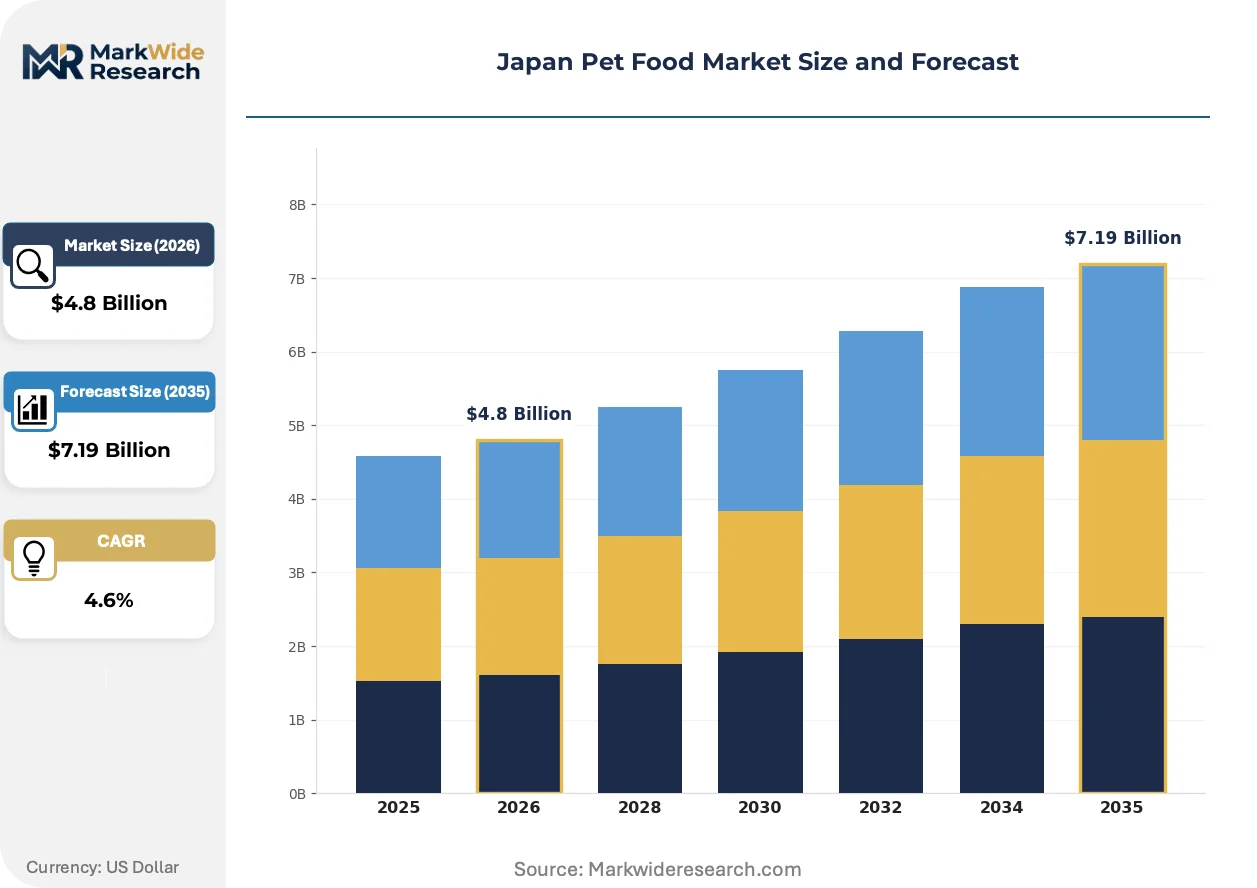
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Animal Type: Dogs, Cats, Small Mammals, Birds Distribution Channel: Supermarkets, Pet Shops, Online Retailers, Veterinary Clinics Ingredients: Meat, Fish, Grains, Vegetables |
| Companies Covered | DoggyMan H.A. Co., Ltd., Petline Ltd., Unicharm Corp, MG Group, Maruha Nichiro Corporation, Nestlé Purina PetCare KK, Nippon Pet Food Co., Nisshin Pet Food Inc., Inaba Petfood, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Pet Food Market Strategic Shifts
Formulation transparency and processing technology are compressing traditional category boundaries between therapeutic and wellness nutrition.
High-pressure processing (HPP) is collapsing the shelf-life gap between raw and retorted products. Premium urban retailers in Tokyo's Shibuya and Minato wards now stock HPP-treated fresh meals alongside conventional wet formats. This technology is collapsing the historical trade-off between nutritional bioavailability and distribution reach that constrained raw food expansion.
METI's evolving sustainability disclosure framework mandates supply chain carbon accounting for pet food manufacturers above specified revenue thresholds. Formulators must now document ingredient provenance from farm to finished product. Wet food producers with integrated seafood sourcing in Hokkaido and Kyushu demonstrate compliance advantages over importers.
Single-serve pouch formats are displacing multi-can purchases among cat-owning households. Convenience stores in Osaka Prefecture report accelerated turns for portion-controlled servings that reduce waste. This pattern concentrates in dual-income households where feeding schedules lack predictability.
Japan Pet Food Market Segmentation
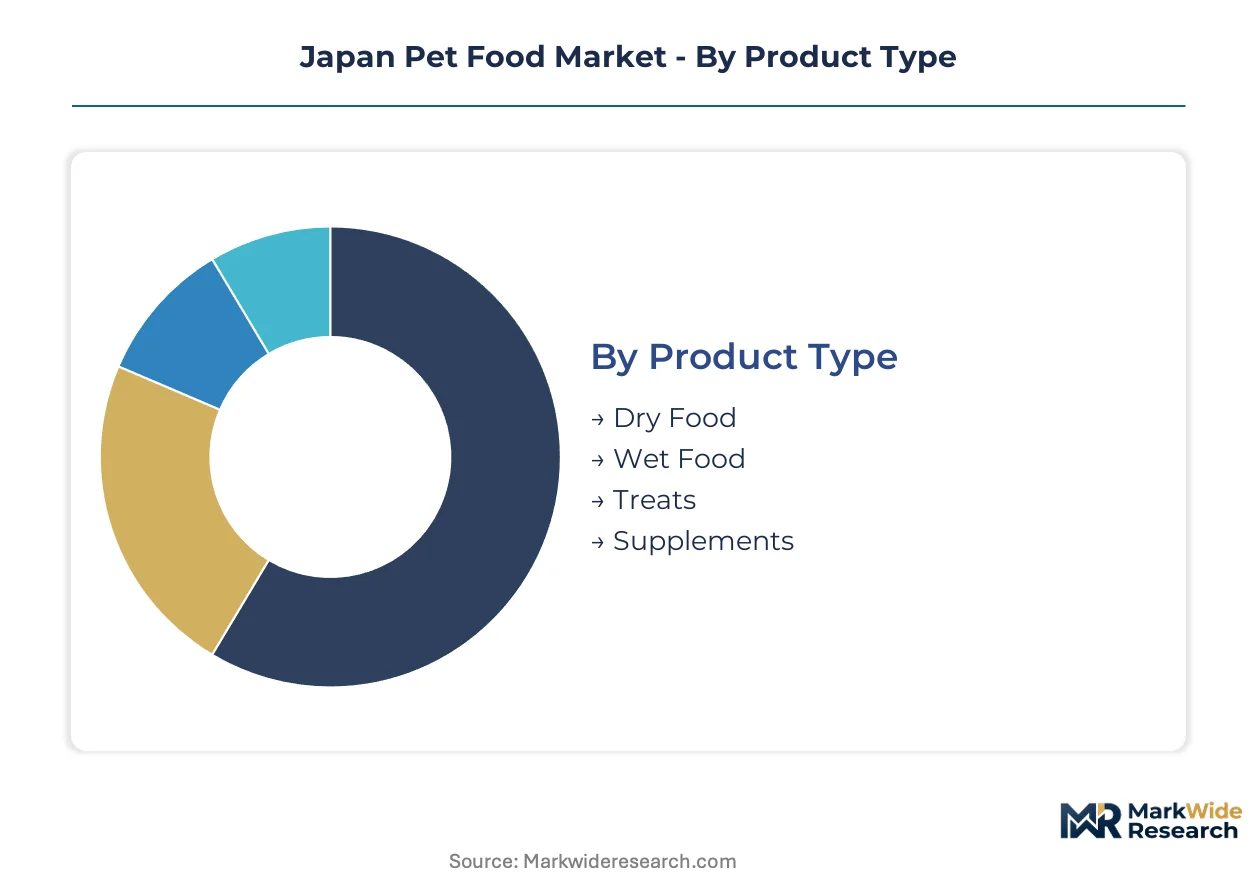
Segmentation discipline separates volume-driven commodity plays from margin-rich premium positions in Japan's pet food landscape. Formulation complexity and channel access requirements vary sharply across product types and animal categories, reshaping where manufacturers deploy R&D and veterinary relationship investments.
Product Type:
After-sales intensity concentrates in wet food and prescription formats, where veterinary follow-up and feeding guidance sustain recurring revenue streams.
- Dry Food:Extruded kibble formulations deliver complete nutrition through moisture-controlled matrices with 6-12 month ambient stability. Volume demand clusters in Greater Tokyo's suburban municipalities, where multi-pet households prioritize storage economy and automated feeder compatibility. METI's Food Sanitation Act compliance costs per unit run lowest here, supporting mid-market positioning.
- Wet Food:Retorted or HPP-treated meals with 75-85% moisture content address hydration deficits in aging cats. Osaka Prefecture's dense apartment housing drives preference for single-serve pouches that eliminate refrigeration burden. PMDA oversight of therapeutic variants creates veterinarian-dependent purchase cycles that sustain premium pricing.
- Treats:Functional positioning around dental abrasion and joint support commands price multiples over standard rewards in Sapporo's aging household demographics.
- Supplements:Powder and liquid additives targeting coat condition and digestive health gain traction through specialty pet shop consultation channels in Fukuoka.
By volume, dry food leads. By growth pace, treats are expanding most quickly.
Animal Type:
Cost tier stratification runs deepest in feline nutrition, where therapeutic formulation requirements exceed canine standards.
- Cats:Renal-support and urinary-tract-specific diets dominate premium R&D pipelines, with twelve-plus-year-old feline populations in Tokyo and Osaka driving recurring prescription purchases.
- Dogs:Breed-size segmentation shapes kibble geometry and caloric density, with large-format packaging preferred in rural Hokkaido municipalities.
- Small Mammals:Hay-pellet and extruded fiber formulations for rabbits and guinea pigs concentrate in specialty pet shops with veterinary-trained staff.
- Birds:Seed blends and pelleted complete diets serve a contracting but high-loyalty owner base in Greater Tokyo's established residential districts.
By volume, cats lead. By margin expansion, cats are ahead.
Distribution Channel:
Geographic reach and regulatory burden fragment access, with veterinary clinics carrying the highest certification requirements.
- Supermarkets:Four national chains control shelf access in Greater Tokyo and Osaka, extracting slotting fees that compress mid-market margins.
- Pet Shops:Specialty retailers with veterinary-trained staff drive premium wet food and supplement attachment rates in Fukuoka and Sapporo metros.
- Online Retailers:Subscription platforms capture consumption data for predictive formulation, with Tokyo apartment dwellers driving recurring delivery adoption.
- Veterinary Clinics:PMDA-regulated prescription diet distribution limits therapeutic nutrition to clinically validated suppliers with established channel relationships.
By transaction volume, supermarkets lead. By customer lifetime value, veterinary clinics are climbing the fastest.
Ingredients:
Supply concentration and METI disclosure mandates reshape sourcing strategies across protein categories.
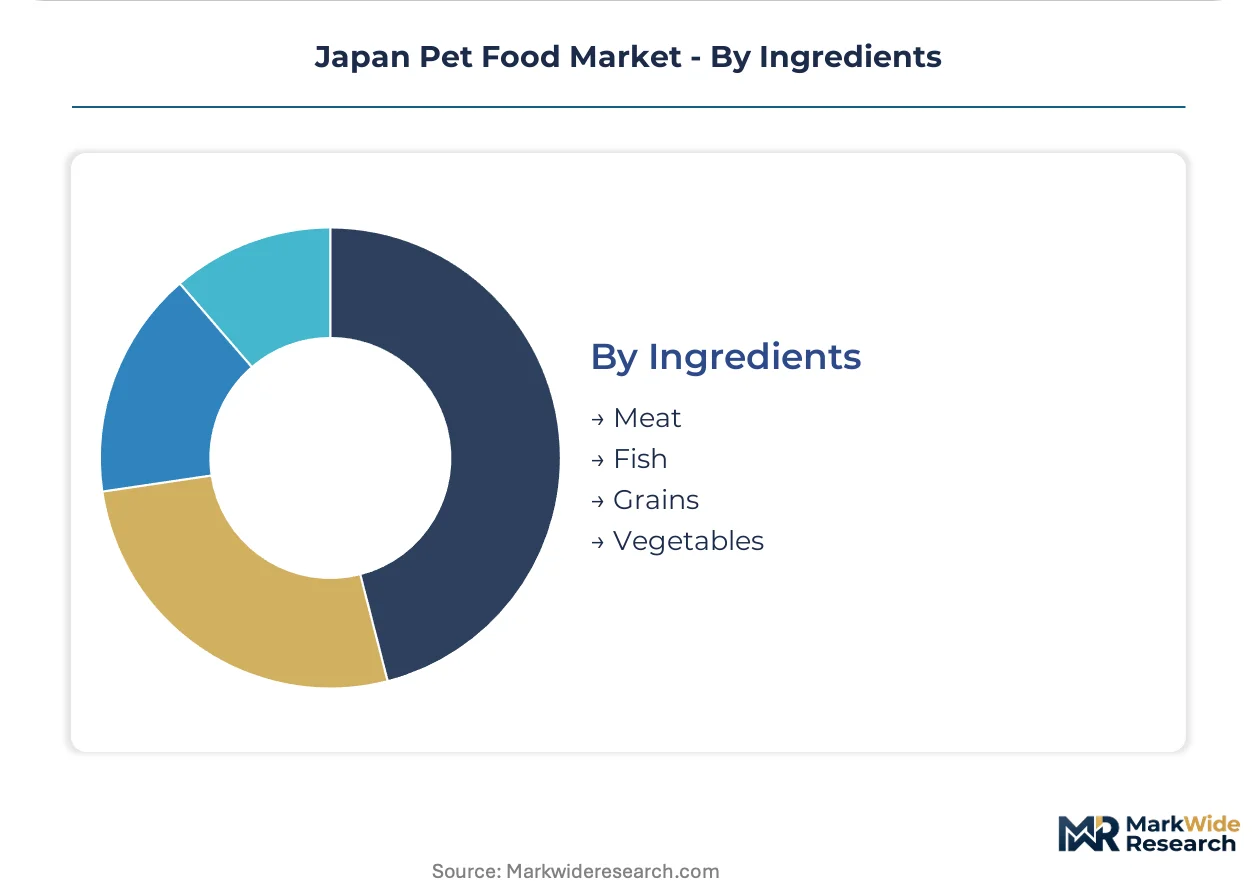
- Meat:Domestic poultry meal supply fluctuations force reformulation cycles, with Hokkaido-integrated producers demonstrating traceability advantages.
- Fish:Kyushu-based seafood processors supply bonito and tuna derivatives for palatability enhancement in premium wet formats.
- Grains:Rice and wheat formulations anchor mid-market dry food positioning through mass retail channels.
- Vegetables:Sweet potato and pumpkin inclusions address fiber and antioxidant positioning in functional treat lines.
By formulation share, meat leads. By sustainability disclosure readiness, fish is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's regulatory framework anchors the Kanto region's dominance in Japanese pet food formulation and distribution. The market's geographic concentration reflects urban pet humanization patterns and veterinary infrastructure density.
Kanto/Tokyo
Tokyo apartment dwellers drive premium wet food demand through single-serve pouch formats. METI's Food Sanitation Act compliance costs concentrate formulation expertise in this corridor. Shibuya and Minato specialty retailers stock HPP-treated fresh meals alongside conventional formats.
Kansai/Osaka
Dual-income households in Osaka Prefecture accelerate convenience-store turns for portion-controlled cat food servings. PMDA oversight of therapeutic diets sustains veterinarian-dependent purchase cycles in this dense urban housing market. The region's supermarket chains extract significant slotting fees from mid-market brands.
Chubu/Nagoya
Industrial pet food manufacturing clusters around Nagoya's processing equipment suppliers and packaging material providers. The Japanese Pet Food Association's voluntary certification programs shape regional quality standards. Formulation R&D facilities serve as technical support hubs for national distribution networks.
Kyushu
Seafood processors in Kyushu supply bonito and tuna derivatives for palatability enhancement in premium wet formats. Integrated sourcing from regional fisheries demonstrates METI sustainability disclosure compliance advantages. Fukuoka metro specialty pet shops drive supplement attachment rates through veterinary-trained staff consultation.
Hokkaido
Domestic poultry meal supply chains in Hokkaido provide traceability advantages for METI ingredient disclosure mandates. Rural municipalities prefer large-format dry food packaging for multi-pet household storage economy. Sapporo's aging household demographics support functional treat positioning around dental and joint health.
Japan Pet Food Market Competitive Environment
Established domestic manufacturers and multinational nutrition specialists split the market through divergent channel strategies. The competitive structure tiers around veterinary access, mass retail scale, and specialty formulation capabilities. Three archetypes dominate: legacy Japanese houses with deep veterinary relationships, global CPG players with retail scale, and regional specialists with integrated ingredient sourcing. Capacity expansion in retort processing and strategic partnerships for alternative protein supply dominate competitive moves.
Among domestic incumbents, DoggyMan H.A. Co., Ltd. and Nippon Pet Food Co. exemplify the veterinary-channel and mass-retail archetypes respectively. Unicharm Corp occupies a position bridging specialty retail penetration with scaled manufacturing. These three anchors demonstrate how formulation complexity and distribution access requirements shape sustainable competitive positioning in METI-regulated markets.
| Leading Market Players |
|---|
| DoggyMan H.A. Co., Ltd. |
| Petline Ltd. |
| Unicharm Corp |
| MG Group |
| Maruha Nichiro Corporation |
| Nestlé Purina PetCare KK |
| Nippon Pet Food Co. |
| Nisshin Pet Food Inc. |
| Inaba Petfood |
| Others |
Value Chain & Pricing Dynamics
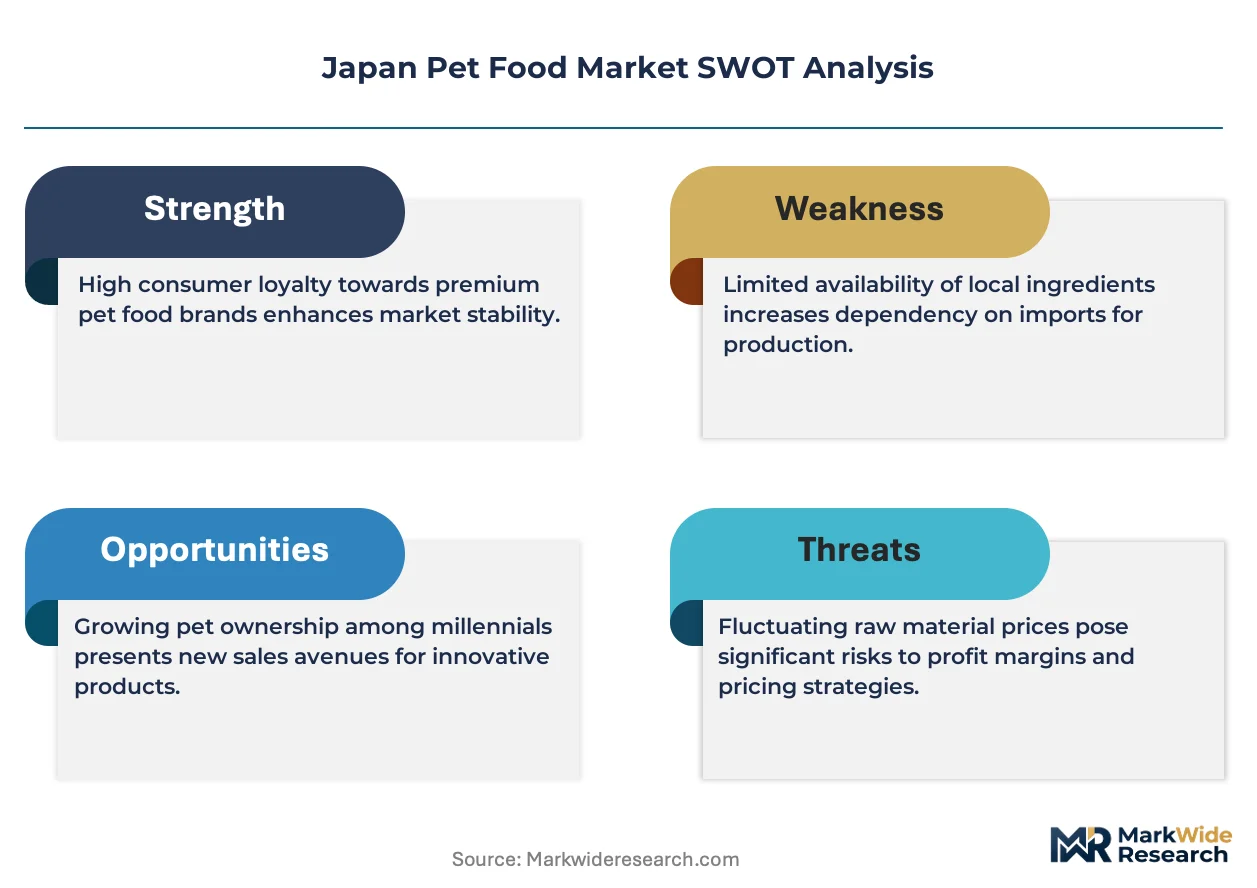
Animal protein input volatility in domestic poultry and fishmeal supply chains determines both tiered pricing spreads and supply chain configuration in Japan's pet food sector. METI's ingredient disclosure mandates reward integrated producers with traceability advantages while forcing reformulation cycles that compress mid-market margins.
Pricing Analysis
The customization-premium spread separates PMDA-validated prescription diets from standard wet and dry formats. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity, veterinary channel certification, and volume scale. Cost compression in mid-market dry food intensifies because supermarket chains extract escalating slotting fees. Mass retail shoppers demonstrate highest price sensitivity, while veterinary clinic purchasers accept premium positioning for therapeutic nutrition.
Supply Chain Analysis
Supplier-financing facilities from Kyushu seafood processors and Hokkaido poultry integrators sustain working capital for ingredient procurement cycles. Domestic production draws from Kyushu fisheries, Hokkaido poultry operations, and Chubu packaging material providers. Raw material dependencies center on bonito derivatives, domestic poultry meal, and rice-based carbohydrate matrices. Single-source vulnerability concentrates in Hokkaido poultry supply for METI traceability compliance. Distribution runs through four national supermarket chains, veterinary clinic networks, and specialty pet shop channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's pet food market is recovering from input cost cyclicality as domestic protein supply stabilizes and METI disclosure investments mature. Urban pet humanization patterns sustain demand elasticity that favors premium positioning.
For Market Incumbents: Pre-empt alternative protein entrants by accelerating Hokkaido and Kyushu backward integration into cultivated and insect protein supply. Secure retort processing capacity additions in Chubu before regional bottlenecks worsen. METI's evolving sustainability disclosure timeline compresses the window for traceability infrastructure deployment.
For New Entrants and Emerging Players: Single-serve pouch formats for Tokyo apartment dwellers represent the most penetrable entry point given refrigeration constraints and convenience-store channel expansion. Fukuoro and Sapporo specialty pet shops with veterinary-trained staff offer consultative go-to-market positioning that bypasses mass retail slotting fee barriers.
For Investors and Strategic Acquirers: PMDA's prescription diet validation pathway reshapes the acquisition landscape toward clinically validated suppliers with established veterinary relationships. Five-to-ten-year viability favors integrated producers with captive seafood or poultry sourcing. The signal to watch is METI's carbon accounting threshold expansion, which would accelerate consolidation among sub-scale wet food manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Retort Processing Capacity Expansion | Chubu equipment suppliers enable wet food sterilization scale that regional competitors cannot replicate. |
| Alternative Protein Supply Partnership | Insect and cultivated protein sourcing aligns with METI sustainability disclosure mandates before threshold expansion. |
| Veterinary Channel Certification Investment | PMDA validation creates recurring revenue moats through prescription diet exclusivity. |
| Direct-to-Consumer Subscription Launch | Tokyo apartment dwellers drive recurring delivery adoption with consumption data for predictive formulation. |
| Integrated Seafood Sourcing Control | Kyushu fishery integration demonstrates METI ingredient provenance compliance for premium wet formats. |
Study Parameters
Cross-validation between veterinary nutritionist interviews and Japanese Pet Food Association certification records anchors the qualitative findings. Primary fieldwork engaged pet food formulation scientists, specialty pet shop category managers, supermarket procurement leads, and veterinary clinic distribution coordinators. Secondary sources incorporated METI Food Sanitation Act filings, PMDA prescription diet registrations, customs import data for alternative proteins, and Nielsen retail audit metrics. Bottom-up segmentation modeling and top-down macroeconomic calibration ensured triangulation integrity.
Calibration against historical volume trajectories and input cost elasticity patterns shaped the analytical framework. Segmentation dimensions spanned product type, animal category, distribution channel, and ingredient sourcing origin across the analysis window. CAGRs derived from regression analysis of price-volume relationships and demographic pet ownership projections. Industry-specific inputs included aging feline population estimates and METI regulatory implementation schedules.
Practitioners should monitor domestic poultry supply fluctuations, PMDA validation queue lengths, and METI carbon accounting threshold announcements for early signals. Forecasts reflect assumptions about urban pet humanization continuity and alternative protein acceptance curves. Macroeconomic contraction, regulatory acceleration, or technological disruption in processing equipment would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Hypoallergenic Dog Food Market
Pet Care Products
Pet Water Dispenser Market
Pet Care Products
Cat Window Perches and Wall Shelves Market
Pet Care Products
Dog Float Market
Pet Care Products
Asia-Pacific Pet Clothing Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Canada Pet Boarding Market
Pet Care Products
Mobile Pet Care Market
Pet Care Products
Dog Bathing Systems Market
Pet Care Products
India Pet Clothing Market
Pet Care Products
Dog Hats Market
Pet Care Products
Pet Care Market
Pet Care Products
Dog Vest Market
Pet Care Products
Frozen and Freeze-Dried Pet Food Market
Pet Care Products
Germany Pet Training Services Market
Pet Care Products
Organic Dog Food Market