
 China Pet Boarding Market | 2026-2036
China Pet Boarding Market Size, Share, and Industry Trends Forecast 2026-2036
China Pet Boarding Market Insights
Subscription-based wellness packages is recalibrating what pet boarding operators sell, bundling daycare with grooming and veterinary check-ins rather than transactional nightly stays. PetBacker leverages its digital platform to aggregate home boarding supply across tier-one cities. DoggyMan anchors its position through specialized kennel infrastructure designed for large-breed dogs. MeowStar Pet Hotel differentiates via cat-exclusive catteries with climate-controlled environments and live-streaming access for owners.
China pet boarding encompasses temporary housing and care services for companion animals during owner absence, typically involving climate-regulated enclosures, scheduled feeding protocols, exercise rotations, and health monitoring systems with digital check-in reporting. Its primary commercial purpose is to substitute domestic caregiving for time-constrained urban households while ensuring animal welfare compliance. Overnight boarding and pet hotels capture the dominant share of value as owners prioritize premium amenities and extended-stay packages. Daycare services represent the fastest-expanding segment among young professionals seeking weekday drop-off solutions. Home boarding maintains niche traction through lower price points and personalized attention, though margin pools remain thinner due to scale constraints.
SAMR enforces business licensing and consumer protection standards for pet service providers, while NMPA regulates veterinary pharmaceutical use within boarding facilities, and GB standards specify animal housing dimensions and sanitation protocols. These frameworks elevate capital requirements for new entrants and push existing operators toward facility upgrades and staff certification programs. Stakeholders must monitor enforcement intensity in lower-tier cities where compliance gaps still permit informal competition, and assess whether regulatory harmonization will consolidate market share toward licensed chains or sustain fragmented local operators.
Market Dynamics
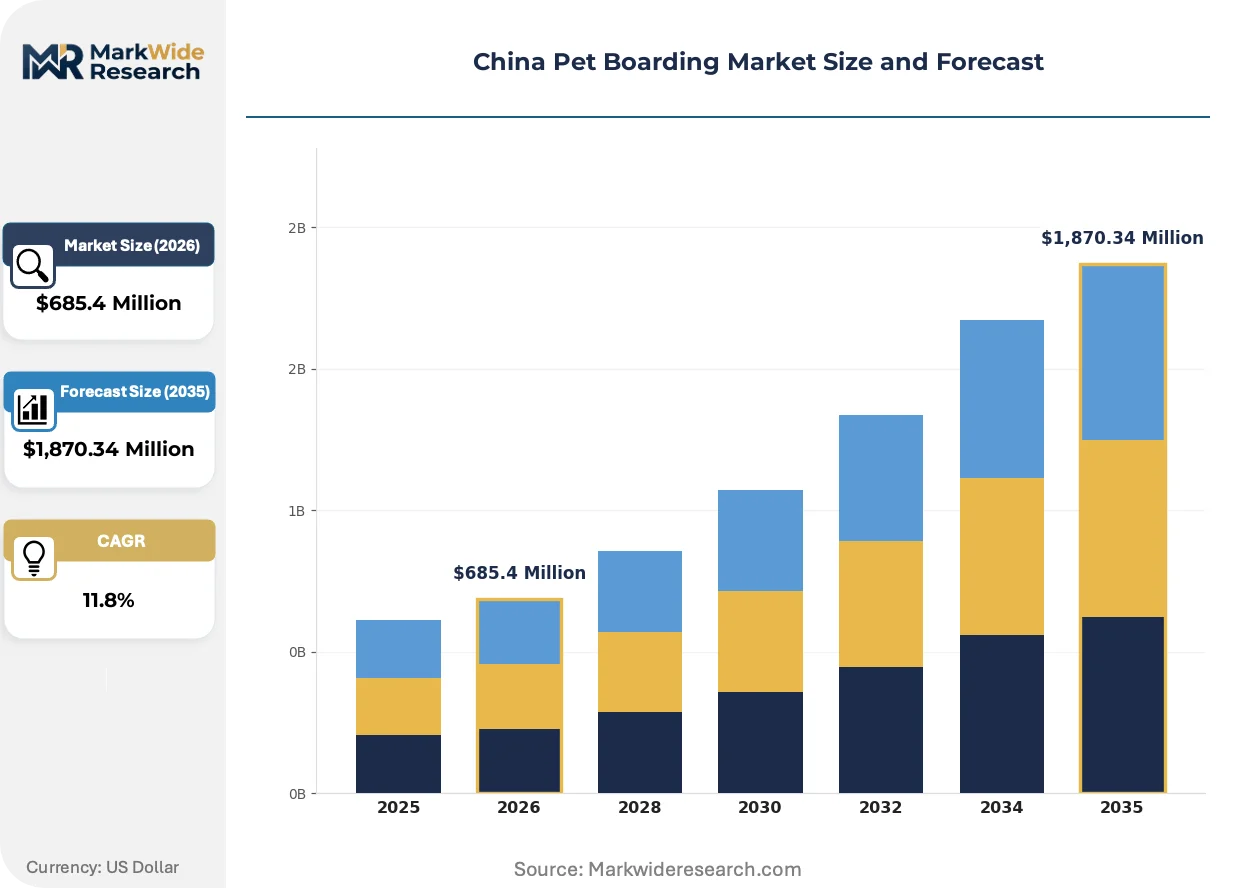
China's pet boarding sector is experiencing structural recalibration as SAMR licensing mandates and GB sanitation standards force facility upgrades while subscription bundling replaces transactional overnight stays. Dual-income households in tier-one cities now demand integrated wellness packages that merge housing with veterinary oversight and grooming protocols.
Growth Catalysts
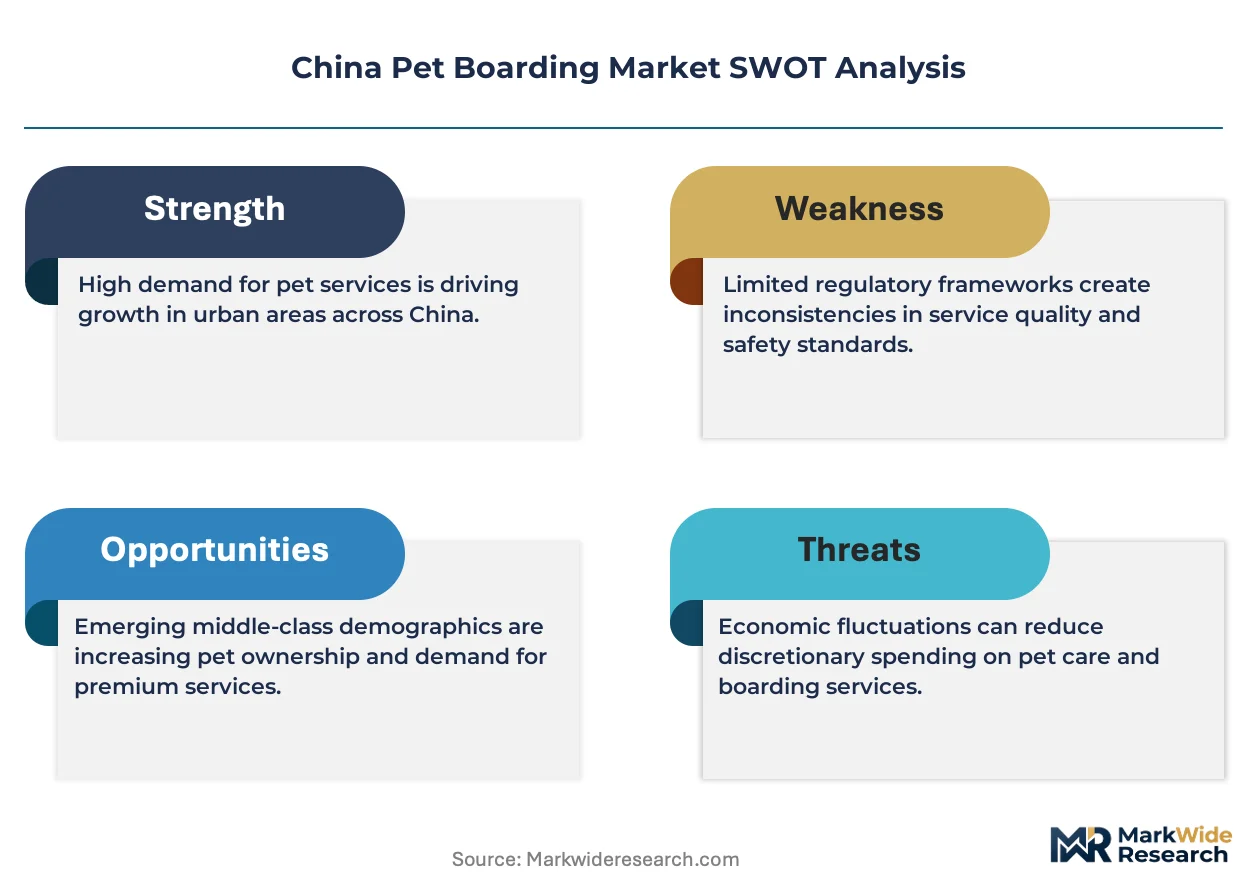
- Regulatory standardization:SAMR business licensing and NMPA pharmaceutical oversight now require documented vaccination records and certified staff, eliminating informal competitors and consolidating demand toward compliant operators.
- Urban household formation:Young professionals in Shanghai and Beijing maintain pet ownership rates substantially above national averages while lacking extended family caregiving networks available in lower-tier regions.
- Digital platform aggregation:Home boarding supply is expanding into centralized booking systems that match verified hosts with demand clusters, reducing customer acquisition friction.
Market Restraints
- Capital intensity for compliance:GB-mandated climate control systems and enclosure specifications require facility investments that strain independent operators in tier-two and tier-three cities.
- Input cost volatility:Veterinary pharmaceutical pricing fluctuates under NMPA procurement frameworks, compressing margins on bundled wellness packages.
- Geographic demand concentration:Revenue pools concentrate in Shanghai, Beijing, and Shenzhen, leaving operators in interior provinces with underutilized capacity and thinner returns.
Strategic Opportunities
- Tier-two city penetration:Chengdu, Hangzhou, and Wuhan exhibit rising pet humanization indicators with limited premium boarding supply, creating first-mover positioning for licensed chains.
- Technology convergence:Live-streaming infrastructure paired with IoT environmental sensors enables remote owner monitoring, differentiating mid-market offerings from basic kennel competitors.
- Dual carbon alignment:MEE efficiency guidelines incentivize solar-powered facilities and waste-to-energy systems, qualifying operators for municipal green business certifications.
Industry Challenges
- Veterinary technician scarcity:NMPA-mandated pharmaceutical administration requires certified staff that boarding facilities must compete for against clinical practices offering superior compensation.
- Legacy system integration:Established operators face friction migrating paper-based health records to SAMR-compliant digital audit trails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Pet Boarding Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,870.34 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Daycare, Overnight Boarding, Grooming, Training, Veterinary Care Pet Type: Dogs, Cats, Small Mammals, Exotic Pets, Birds Facility Type: Specialized Kennels, Catteries, Home Boarding, Pet Hotels, Veterinary Clinics Customer Type: Individual Owners, Pet Sitters, Breeders, Rescue Organizations, Corporates |
| Companies Covered | PetBacker, DoggyMan, PetHotel China, MeowStar Pet Hotel, PawPals Boarding, China Pet Resort, Urban Paws China, Furry Friends Lodge, Beijing PetStay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Pet Boarding Market Trends and Innovations
Subscription economics and live-streaming transparency are displacing transactional overnight models. Operators now compete on continuity of care rather than per-night pricing, while regulatory digitization mandates accelerate technology adoption across facility tiers.
IoT-enabled environmental monitoring is expanding into standard facility infrastructure. Sensors track temperature, humidity, and air quality in real-time, transmitting data to owner applications. Premium operators in Beijing and Shanghai deploy these systems as baseline amenities, compressing differentiation timelines for mid-market competitors.
GB standards revision for animal housing dimensions and sanitation protocols now mandates quarterly third-party audits. Facilities must document enclosure measurements, cleaning schedules, and waste disposal chain-of-custody. Tier-one city operators absorb compliance costs through scale, while smaller competitors face exit pressure or acquisition.
Young professionals now favor weekday daycare subscriptions over episodic boarding. This behavioral pivot favors operators with urban micro-locations near commercial districts, displacing suburban kennel models dependent on vehicle access. Shanghai's central business district operators report strongest uptake of morning drop-off, evening retrieval arrangements.
China Pet Boarding Market Segmentation
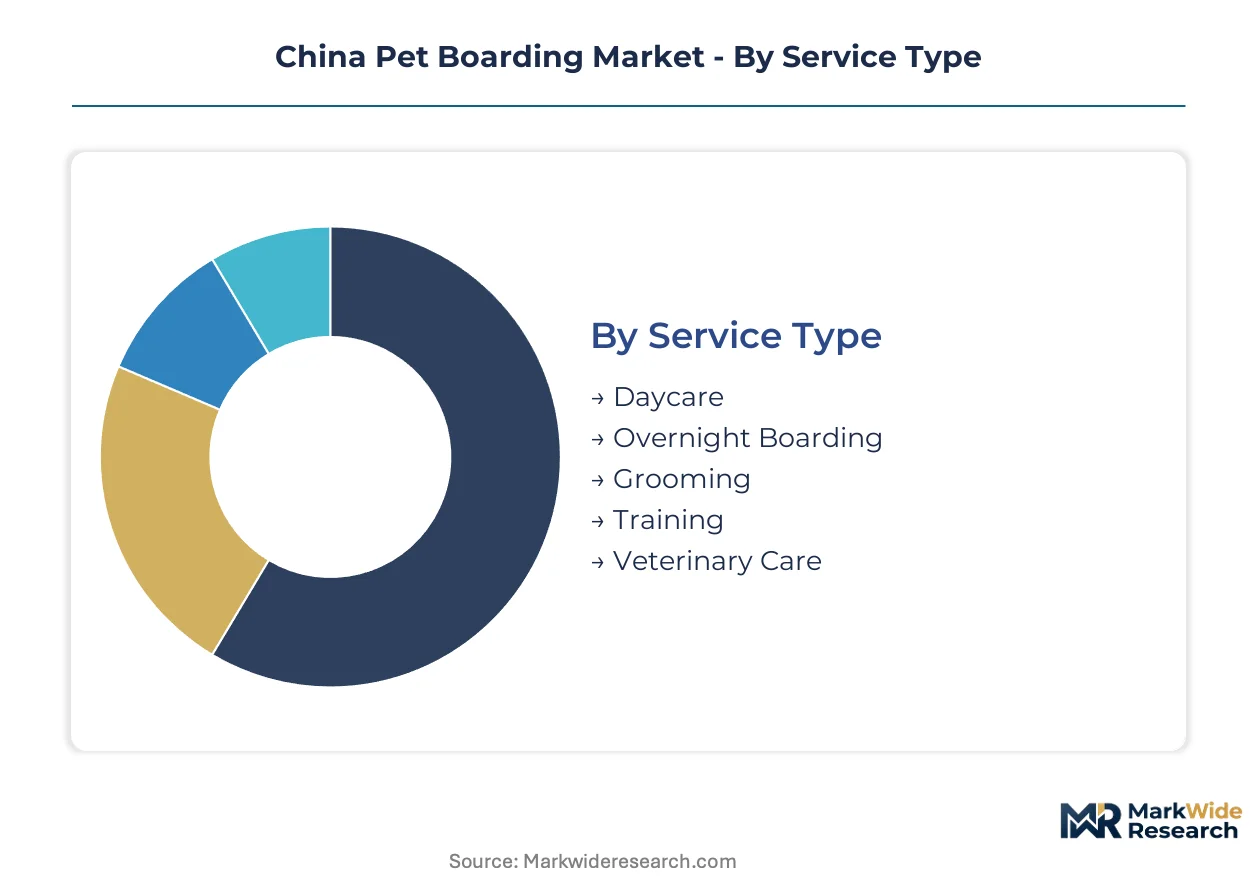
Segmentation reveals how regulatory pressure and urban geography concentrate revenue across distinct operational models. Operators must align service architecture with specific compliance burdens and customer willingness-to-pay gradients.
Service Type:
Supply concentrates in overnight accommodation where capital requirements filter out informal competitors and SAMR licensing creates enforceable quality tiers.
- Overnight Boarding:Climate-regulated enclosures with documented feeding protocols and health monitoring systems constitute the core revenue engine. Shanghai and Beijing dual-income households absorb premium extended-stay packages as substitutes for unavailable extended-family care networks.
- Daycare:Weekday drop-off solutions with morning retrieval scheduling now dominate urban micro-locations near commercial districts. Young professionals in central business districts favor subscription arrangements over episodic booking, compressing suburban kennel relevance.
- Grooming:Hygiene maintenance bundled into wellness packages rather than standalone transactions.
- Training:Behavioral conditioning protocols delivered during extended stays or dedicated sessions.
- Veterinary Care:NMPA-supervised pharmaceutical administration and health check-ins integrated into housing contracts.
Overnight boarding absorbs the bulk of installed capacity; daycare is expanding most quickly.
Pet Type:
Cost tier stratification separates species-specific infrastructure investments from generic housing alternatives.
- Dogs:Large-breed kennel specifications under GB standards demand reinforced enclosures and exercise rotation areas. Beijing operators report strongest demand for specialized infrastructure accommodating restricted breeds in permitted districts.
- Cats:Catteries with vertical climbing structures, separate air handling, and stress-minimization protocols command premium positioning. Shanghai cat ownership rates among young professionals outpace national averages, concentrating demand in tier-one corridors.
- Small Mammals:Rodent and lagomorph housing with species-specific temperature requirements.
- Exotic Pets:Reptile and amphibian enclosures with precise humidity and lighting controls.
- Birds:Aviary specifications with noise isolation and flight space minimums.
Dogs absorb the bulk of installed capacity; cats are climbing the fastest.
Facility Type:
Application context determines whether operators pursue scale economies through centralized infrastructure or flexibility through distributed networks.
- Pet Hotels:Multi-service campuses combining housing, grooming, and veterinary oversight under single management. Tier-one city landlords absorb MEE efficiency upgrade costs through municipal green certification incentives.
- Specialized Kennels:Breed-specific or size-segmented infrastructure optimized for behavioral and physical requirements. Large-breed concentration in northern provinces drives regional specialization patterns.
- Catteries:Feline-exclusive environments with climate control and owner live-streaming access as baseline amenities.
- Home Boarding:Distributed host networks aggregated through digital platforms with verified vaccination documentation.
- Veterinary Clinics:Medical boarding for post-surgical recovery and pharmaceutical administration under NMPA protocols.
Pet hotels absorb the bulk of installed capacity; home boarding is gaining share fastest.
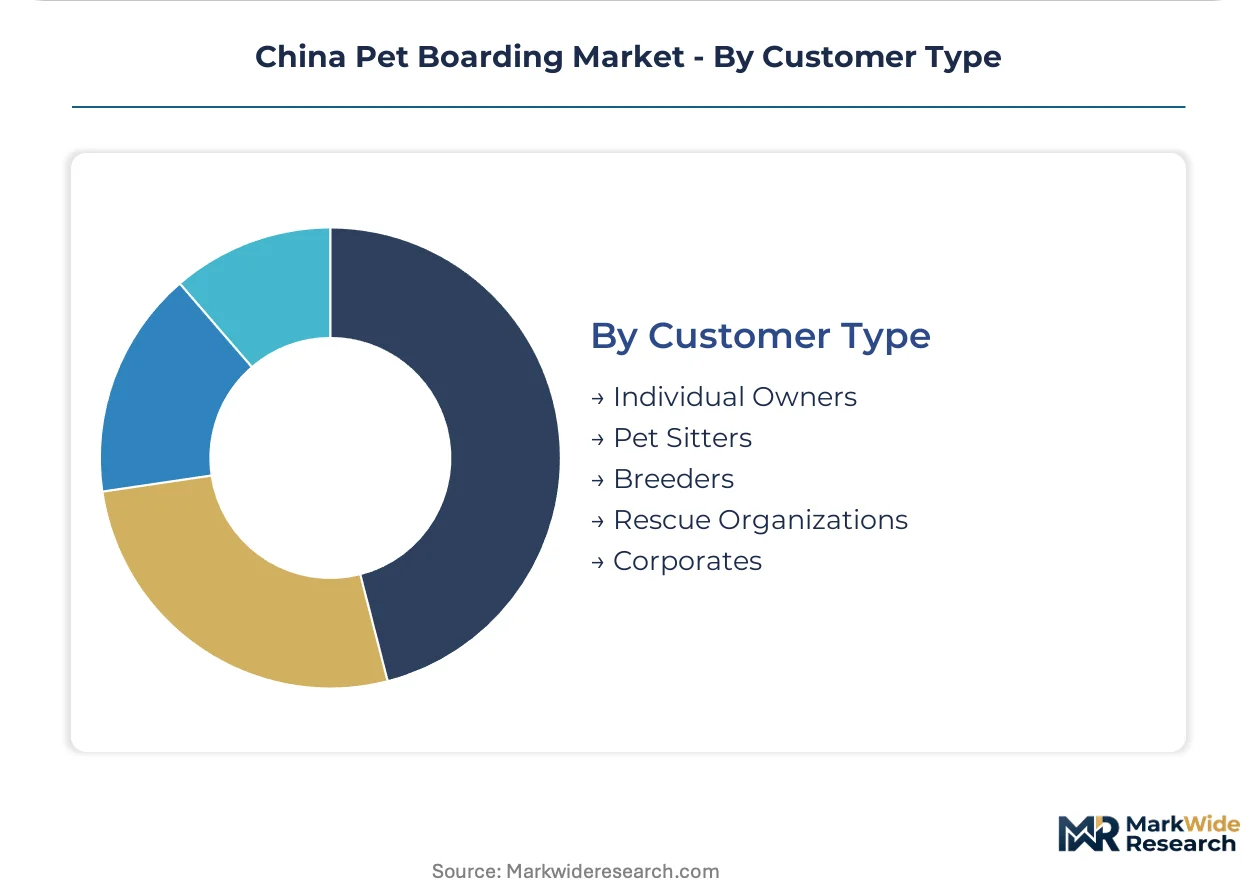
Customer Type:
Volume concentration among individual owners shapes pricing architecture and service bundling decisions.
- Individual Owners:Time-constrained urban households purchasing subscription wellness packages as substitutes for unavailable domestic caregiving. Beijing and Shanghai exhibit highest per-household spending on premium extended-stay arrangements.
- Pet Sitters:Intermediary agents booking capacity blocks for redistribution to end clients.
- Breeders:Commercial operators requiring quarantine-compliant housing for litters and breeding stock.
- Rescue Organizations:Non-profit entities seeking volume discounts for temporary housing of surrendered animals.
- Corporates:Employer-sponsored pet care benefits and relocation service contracts.
Individual owners absorb the bulk of installed capacity; corporate contracts are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's pet boarding capacity clusters in consumption centers rather than production hubs, with demand generation and service delivery co-located in urban corridors where dual-income households concentrate. Facility investment flows toward tier-one cities with stringent SAMR enforcement, leaving interior provinces supply-constrained.
Yangtze River Delta
Shanghai anchors premium boarding demand through young professional households lacking extended-family care networks. SAMR licensing mandates filter out informal operators, consolidating revenue toward compliant pet hotel chains. Suzhou and Hangzhou satellite cities absorb overflow demand with lower facility costs and MEE green certification incentives.
Pearl River Delta
Shenzhen and Guangzhou exhibit fastest daycare segment expansion among tech-sector employees seeking weekday drop-off solutions. GB standards enforcement intensified in 2024, requiring climate-control upgrades that strain independent operators. Dongguan emerges as cost-optimized capacity for price-sensitive segments.
Beijing-Tianjin-Hebei
Capital region maintains highest per-household spending on extended-stay packages among government and finance professionals. NMPA pharmaceutical oversight elevates veterinary boarding requirements, compressing margins on wellness bundles. Tianjin absorbs large-breed kennel specialization due to land availability and GB enclosure specifications.
Sichuan-Chongqing
Chengdu represents the strongest tier-two expansion opportunity with pet humanization rates approaching tier-one levels. Local SAMR enforcement remains less intensive than coastal cities, permitting informal competition that pressures licensed operator pricing. Chongqing's mountainous geography favors centralized pet hotel campuses over distributed home boarding.
Shandong Peninsula
Qingdao and Yantai demonstrate emerging demand from affluent retiree households migrating from Beijing. Facility investment lags demand growth, creating capacity gaps during peak travel periods. Provincial regulators lag national GB implementation timelines, sustaining operational heterogeneity.
China Pet Boarding Market Competitive Landscape
Capital-heavy facility operators compete with asset-light digital aggregators across distinct value capture models. SAMR licensing requirements and GB-mandated infrastructure investments filter out micro-operators, consolidating share toward chains with municipal green certifications and NMPA-compliant veterinary protocols. Three archetypes dominate: integrated pet hotel campuses bundling housing with grooming and medical oversight; specialized kennel operators optimizing for breed-specific requirements; and platform-based aggregators matching verified home hosts with demand clusters. Competitive dynamics center on geographic expansion into tier-two cities and technology convergence through IoT monitoring systems.
Among platform-based aggregators, PetBacker anchors the asset-light archetype through digital supply aggregation. DoggyMan occupies the specialized infrastructure tier with kennel configurations targeting large-breed requirements. MeowStar Pet Hotel exemplifies species-specific differentiation through climate-controlled catteries and live-streaming amenities. These three represent divergent strategic postures within a market recalibrating toward subscription wellness packages and regulatory compliance as primary competitive dimensions.
| Leading Market Players |
|---|
| PetBacker |
| DoggyMan |
| PetHotel China |
| MeowStar Pet Hotel |
| PawPals Boarding |
| China Pet Resort |
| Urban Paws China |
| Furry Friends Lodge |
| Beijing PetStay |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between SAMR-licensed pet hotels and unregulated home boarding operators manifests in both pricing power and procurement configurations across China's tier-one cities. Premium operators absorb GB-mandated climate control and veterinary pharmaceutical costs through subscription bundling, while informal competitors compete on transactional nightly rates with thinner input sourcing.
Pricing Analysis
Margin tightening in mid-market kennel tiers reflects NMPA pharmaceutical procurement volatility and MEE efficiency upgrade mandates. Three-tier pricing structure across premium, standard, and economy levels differentiates by SAMR compliance depth and live-streaming amenity inclusion. Corporate wellness contracts exhibit lowest price sensitivity; individual owners in tier-two cities demonstrate highest elasticity to per-night rates. Cost compression accelerates as GB standards enforcement eliminates informal supply.
Supply Chain Analysis
Return flows of veterinary equipment and climate-control components from decommissioned suburban kennels feed refurbishment networks serving tier-two expansion. Domestic manufacturing in Jiangsu and Zhejiang provinces dominates enclosure fabrication; South Korean and Japanese suppliers anchor IoT sensor procurement. Single-source vulnerability concentrates in pharmaceutical cold-chain logistics. Distribution runs through municipal veterinary supply cooperatives and direct OEM relationships with facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's pet boarding sector functions as a vertical-integration race where control over veterinary pharmaceutical sourcing and certified technician pipelines determines margin capture. Players pursuing backward integration into NMPA-compliant drug distribution or forward integration into corporate wellness contracting secure structural advantage.
For Market Incumbents:Acquire certified veterinary technician training pipelines to lock in scarce NMPA-mandated staffing capacity. Consolidate tier-two city facilities facing GB compliance exit pressure before SAMR enforcement harmonization accelerates. Digital platform entrants threaten margin pools through home boarding aggregation; defend through proprietary IoT infrastructure deployment.
For New Entrants and Emerging Players:Capture Chengdu and Hangzhou white-space before licensed chains establish density. Corporate wellness contracts offer fastest penetration path with lowest customer acquisition friction relative to individual owner markets. Position through MEE green certification eligibility to access municipal incentive programs unavailable to informal competitors.
For Investors and Strategic Acquirers:Re-rating potential sits with tier-two city licensed chains given SAMR enforcement harmonization catalyst. Long-term viability favors operators with captive veterinary pharmaceutical sourcing and integrated daycare-to-boarding subscription platforms. Monitor GB standards audit failure rates as early signal of consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| SAMR Licensing Acquisition | Regulatory compliance eliminates informal competition and enables premium pricing tiers. |
| Veterinary Pharmaceutical Integration | NMPA-supervised sourcing secures margin on bundled wellness packages. |
| Tier-Two City Facility Buildout | Chengdu and Hangzhou penetration captures demand before chain consolidation. |
| IoT Monitoring Infrastructure Deployment | Live-streaming and sensor systems differentiate mid-market from basic kennel offerings. |
| Corporate Wellness Contracting | Employer-sponsored pet benefits reduce customer acquisition costs versus individual markets. |
Research Methodology
Regulatory filings, veterinary pharmaceutical procurement databases, and municipal SAMR enforcement records formed the secondary backbone. Primary interviews with pet hotel operators, NMPA compliance officers, and corporate benefits administrators validated demand patterns. Bottom-up facility capacity counts across Shanghai, Beijing, Shenzhen, Chengdu, and Hangzhou triangulated against top-down household pet ownership surveys.
Bottom-up modeling segmented revenue by service type, pet species, facility tier, and customer archetype across the projection horizon. CAGRs derived from facility investment pipelines, regulatory implementation timelines, and urban household formation projections. Forecast inputs incorporated MEE green certification adoption curves and NMPA pharmaceutical pricing frameworks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAMR enforcement intensity in interior provinces and veterinary technician supply constraints. Practitioners should monitor GB standards audit pass rates and tier-two city licensing application volumes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Bowl Market
Pet Care Products
United States Pet Market
Pet Care Products
Global Cat Trees and Towers Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
North America Pet Diet Market
Pet Care Products
South America Cat Food Market
Pet Care Products
Pet Food Bowl Market
Pet Care Products
Flea, Tick, and Heartworm Products Market
Pet Care Products
Dog Bathing Systems Market
Pet Care Products
Outdoor Cat Houses and Furniture Market
Pet Care Products
Global Pet Carriers Market
Pet Care Products
Spain Pet Boarding Market
Pet Care Products
Dog Sunglasses Market
Pet Care Products
Japan Pet Boarding Market
Pet Care Products
Pet Clean-Up and Odor-Control Products Market
Pet Care Products
Pet Gadgets Market