
 Pet Cups Market | 2026-2036
Pet Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Cups Market Analytics
Polylactic acid is expanding its footprint in pet cup formulations as brand owners seek alternatives to conventional petroleum-based plastics. Dart Container Corporation leverages its thermoforming expertise to sustain cost leadership in high-volume disposable lines. Huhtamaki Oyj anchors its position through integrated fiber-based packaging technology across European and North American operations. WinCup competes aggressively in the biodegradable segment with expanded polylactic acid capacity at its domestic facilities.
Pet cups are purpose-built feeding vessels manufactured from food-grade substrates including polypropylene, coated paperboard, silicone elastomers, or borosilicate glass, designed to deliver measured nutrition and hydration to companion animals in clinical, retail, and residential settings. Structural dynamics favor disposable cups in veterinary clinics where single-use hygiene protocols dominate procurement budgets, while biodegradable cups command premium positioning as municipal composting infrastructure matures in metropolitan clusters. Reusable silicone cups are gaining traction among premium pet retailers targeting sustainability-conscious consumers, though margin pools remain thinner due to extended replacement cycles.
FDA food-contact notifications and EPA resin identification standards govern material safety and recyclability claims in the United States, while the EU Green Deal and REACH chemical restrictions shape export compliance burdens for Asian manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate-specific labeling mandates as regulatory divergence between North American and European jurisdictions intensifies supply chain complexity.
Market Dynamics
Single-use hygiene protocols in veterinary clinics are compressing replacement cycles and redirecting procurement budgets toward disposable formats, while municipal composting maturation in metropolitan clusters creates parallel demand for biodegradable alternatives.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility frameworks in Germany and France are accelerating fiber-based and compostable substrate adoption among brand owners seeking compliance certainty.
- Veterinary clinic expansion:Clinical procurement of measured-dose feeding vessels is intensifying as companion animal medicalization deepens across the United States and United Kingdom.
- Polylactic acid thermoforming advances:Domestic manufacturing scale-up in China is reducing unit economics for biodegradable cups, enabling price parity with conventional polypropylene in bulk orders.
Market Restraints
- Resin price volatility:Polypropylene and polylactic acid feedstock costs fluctuate with crude oil and corn futures, squeezing margin pools for converters without backward integration into raw material supply.
- Composting infrastructure gaps:Biodegradable cups require industrial composting facilities that remain concentrated in coastal metropolitan clusters, limiting addressable market for premium formats.
- REACH chemical restrictions:EU regulatory tightening on food-contact substances creates compliance friction for Asian exporters using legacy coating chemistries.
Strategic Opportunities
- India pet product retail expansion:Organized pet care retail is penetrating Tier-2 and Tier-3 cities, creating first-mover advantage for branded feeding vessel suppliers establishing local distribution.
- Smart dispensing integration:Convergence of RFID-enabled portion control with disposable cup formats opens premium positioning in clinical and boarding facility segments.
- Subscription direct-to-consumer channels:Recurring delivery models bypass traditional veterinary distributor markups, capturing lifetime value from multi-pet households.
Industry Challenges
- Food-contact certification timelines:FDA notification and EU no-objection letter processes extend 12-18 months, delaying new material launches and freezing R&D amortization schedules.
- Thermoforming tooling capex:Precision mold fabrication for complex geometries requires six-figure capital commitments, favoring incumbents with depreciated equipment bases.
- Cross-border labeling harmonization:Divergent resin identification codes between US EPA and EU systems force SKU proliferation and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Cups Market |
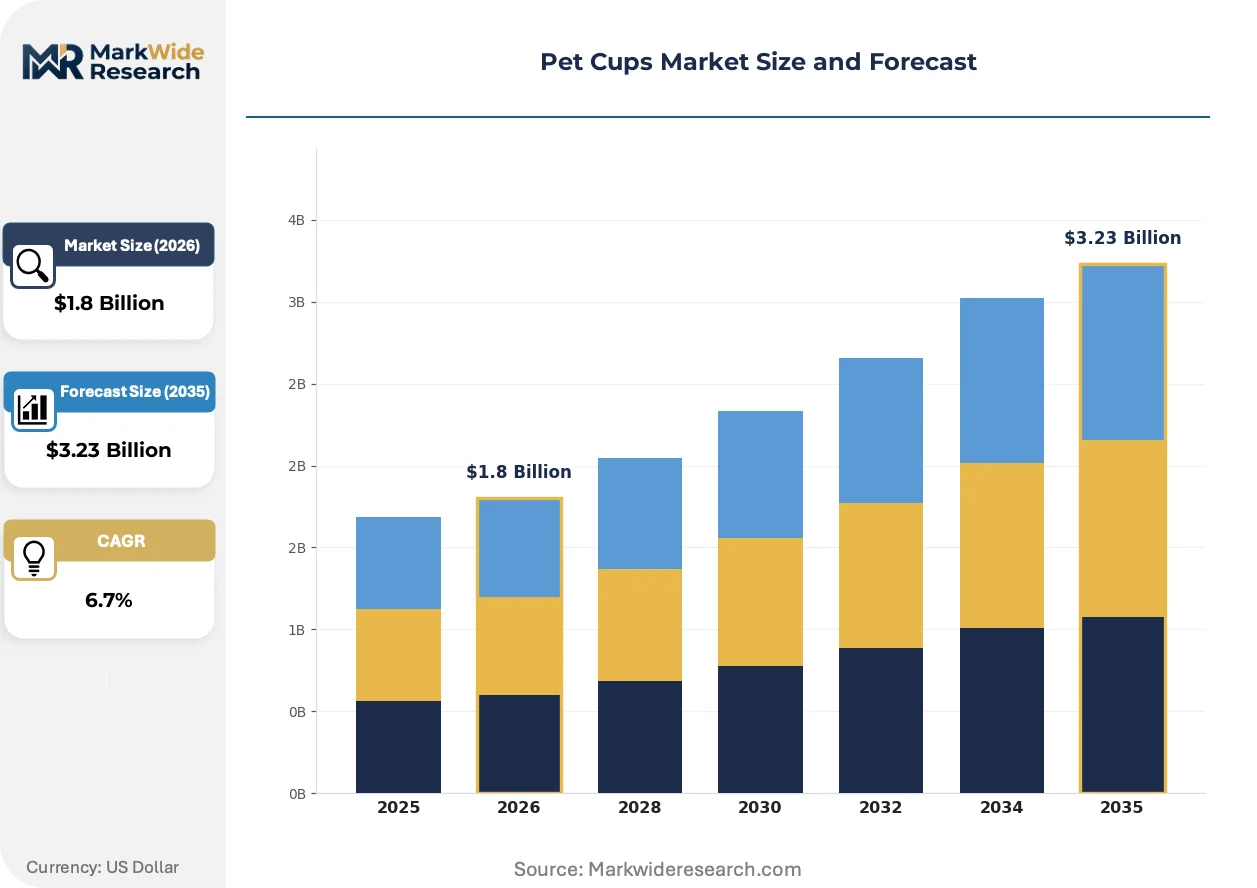
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Cups, Reusable Cups, Biodegradable Cups, Insulated Cups Material: Plastic, Paper, Silicone, Glass End User: Veterinary Clinics, Pet Stores, Animal Shelters, Pet Groomers Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Dart Container Corporation, WinCup, CKF Inc, Anchor Packaging, Ningbo Yi Sheng Plastic Co., Ltd., Huhtamaki Oyj, NNZ Group, Macpac S.A., Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Cups Market Evolving Landscape
Material science convergence and regulatory stringency are compressing innovation cycles, forcing substrate diversification and supply chain reconfiguration across converter networks.
Barrier-coated molded fiber technology is unifying structural rigidity with grease resistance in single-use pet cups, eliminating the polyethylene lining that blocks conventional paperboard from composting streams. Veterinary clinic buyers in the Pacific Northwest and New England are specifying these formats for their municipal composting compatibility. The technology is unifying previously separate supply chains for foodservice and pet specialty applications, enabling volume aggregation that improves converter utilization rates.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are accelerating fluorochemical phaseout in grease-resistant coatings, forcing reformulation investments across European-serving manufacturing bases. The industrial consequence is a 24-36 month window where compliant alternatives command scarcity premiums before supply normalization. Coated paperboard converters with early PFAS-free certifications are capturing shelf space at premium pet retailers in Germany and the Netherlands.
Veterinary group purchasing organizations are consolidating procurement decisions across clinic networks, compressing vendor counts and demanding volume-tiered pricing structures that favor national-scale suppliers. Independent distributors that previously served fragmented clinic bases are losing share to direct manufacturer relationships or specialized veterinary supply aggregators. This concentration is most visible in the United States, where corporate veterinary roll-ups now control substantial outpatient feeding vessel demand.
Pet Cups Market Segmentation
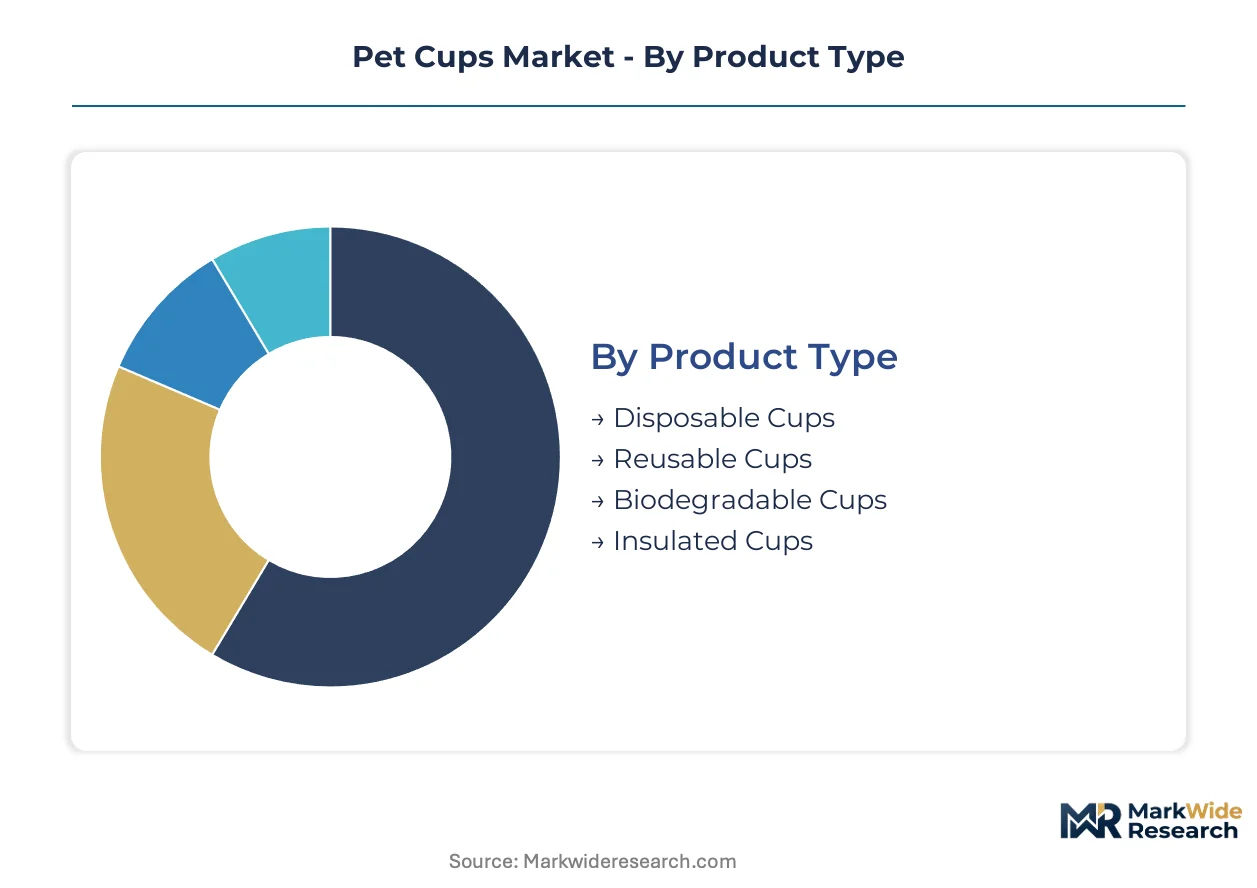
Pet cup procurement splits sharply between high-volume disposable formats for clinical hygiene protocols and premium-positioned reusable alternatives targeting sustainability-conscious residential buyers. Material compliance requirements and end-use sterilization standards create divergent specification pathways that reshape converter production priorities.
Product Type:
Volume concentration favors single-use formats where procurement budgets prioritize infection control, while premium tiers extract value from extended lifecycle positioning.
- Disposable Cups:Polypropylene and coated paperboard substrates dominate veterinary clinic procurement where single-use protocols eliminate cross-contamination risk. Demand concentrates in United States corporate veterinary networks that specify measured-dose formats for inpatient feeding. Dart Container thermoforming operations supply this tier through high-volume domestic contracts.
- Biodegradable Cups:Polylactic acid thermoforming advances are compressing unit economics toward parity with conventional plastics in bulk municipal orders. Deployment concentrates in Pacific Northwest and New England metropolitan clusters where industrial composting infrastructure meets corporate sustainability procurement mandates.
- Reusable Cups:Silicone elastomer and borosilicate glass variants target premium pet retailers with dishwasher-safe durability claims.
- Insulated Cups:Double-wall construction maintains hydration temperature for extended clinical boarding or travel applications.
Mature deployment sits with Disposable Cups. Newer deployment is concentrated in Biodegradable Cups.
Material:
Feedstock selection hinges on regulatory jurisdiction, with FDA food-contact notifications governing United States formulations and REACH chemical restrictions shaping European-serving supply chains.
- Plastic:Polypropylene homopolymer delivers chemical resistance and microwave compatibility at lowest unit cost. Huhtamaki Oyj integrated fiber operations compete aggressively in this tier through backward integration into resin compounding.
- Paper:Barrier-coated molded fiber technology eliminates polyethylene lining to achieve municipal composting compatibility. WinCup expanded polylactic acid capacity captures premium positioning in biodegradable-adjacent fiber formats.
- Silicone:Platinum-cured elastomers offer veterinary-grade sterilization tolerance for reusable clinical applications.
- Glass:Borosilicate construction targets residential premium segments with aesthetic and durability positioning.
Plastic maintains volume leadership. Paper formats are gaining share fastest in composting-enabled metropolitan clusters.
End User:
Procurement sophistication varies dramatically across buyer types, with consolidated veterinary group purchasing organizations extracting volume-tiered pricing unavailable to fragmented shelter networks.
- Veterinary Clinics:Corporate roll-ups in the United States and United Kingdom now control substantial outpatient feeding vessel demand through centralized procurement decisions. Group purchasing organizations compress vendor counts and demand national-scale supply guarantees.
- Pet Stores:Organized retail expansion in India Tier-2 and Tier-3 cities creates first-mover advantage for branded feeding vessel suppliers establishing local distribution partnerships.
- Animal Shelters:Municipal and nonprofit funding constraints prioritize lowest-unit-cost disposable procurement.
- Pet Groomers:Ancillary retail positioning drives impulse purchase of premium reusable formats alongside core service revenue.
Veterinary Clinics anchor volume concentration. Pet Stores represent the steepest expansion trajectory in emerging market organized retail.
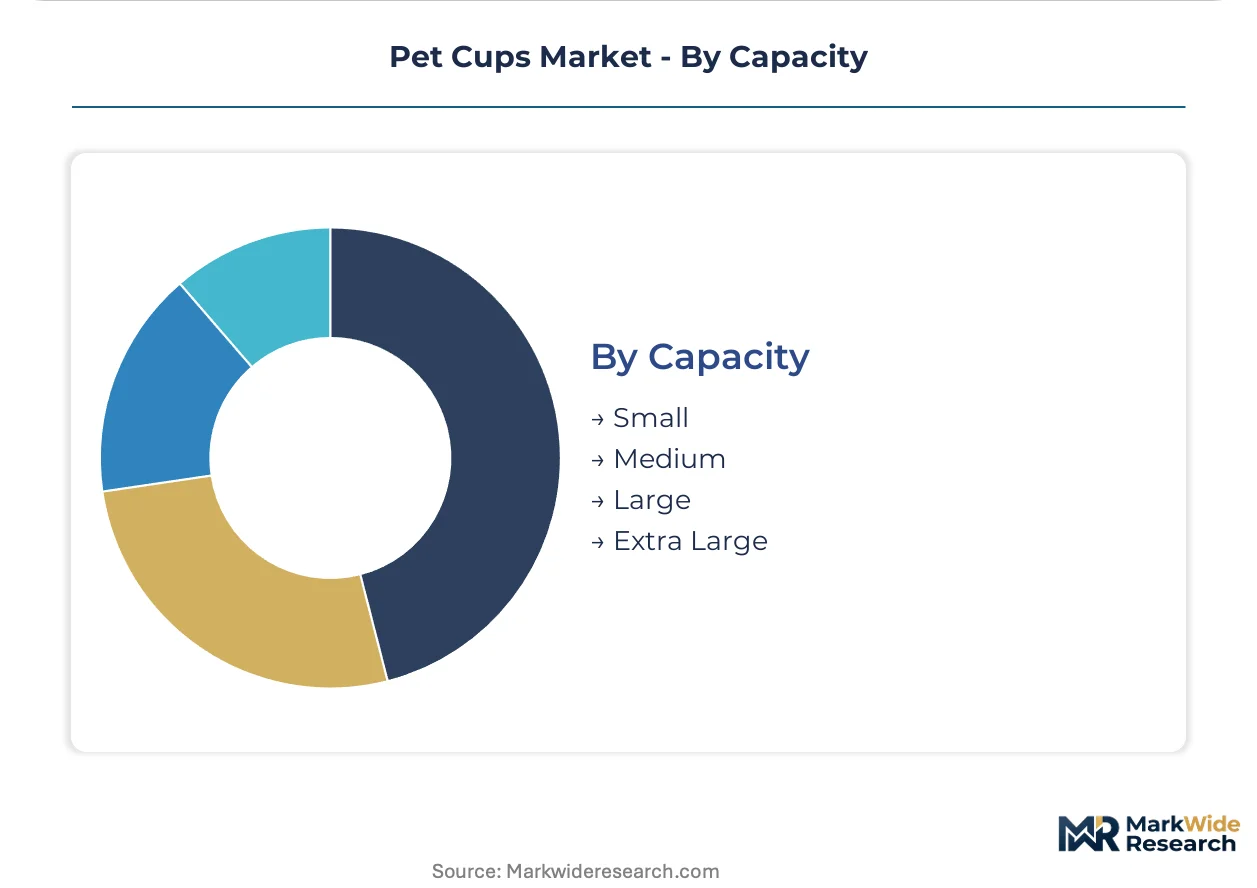
Capacity:
Specification correlates directly with animal size distribution and clinical application, with measured-dose protocols driving precision requirements in therapeutic feeding scenarios.
- Small:Feline and small breed canine formats specify 4-8 ounce capacities for controlled portion delivery in weight management protocols.
- Medium:Standard canine feeding applications dominate residential replacement demand.
- Large:Multi-pet household and commercial boarding specifications drive bulk hydration vessel procurement.
- Extra Large:Giant breed and livestock-adjacent companion animal formats serve niche veterinary specialty practices.
Medium capacity commands procurement volume. Small capacity segments are expanding most quickly alongside feline medicalization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States veterinary clinic networks concentrate substantial procurement volume for measured-dose feeding vessels, while municipal composting infrastructure maturation in specific metropolitan clusters creates parallel demand for biodegradable formats.
United States
Corporate veterinary roll-ups now control substantial outpatient feeding vessel demand through centralized procurement decisions. FDA food-contact notifications and EPA resin identification standards govern material safety and recyclability claims. Pacific Northwest metropolitan clusters specify barrier-coated molded fiber formats for municipal composting compatibility.
China
Domestic pet product manufacturing scales rapidly as companion animal ownership expands in Tier-1 and Tier-2 cities. SAMR food-contact material regulations and GB standards shape substrate compliance requirements. Yangtze River Delta manufacturing bases concentrate polylactic acid thermoforming capacity for export markets.
Germany
Extended producer responsibility frameworks accelerate fiber-based and compostable substrate adoption among brand owners seeking compliance certainty. EU Green Deal packaging mandates and REACH Annex XVII restrictions on per- and polyfluoroalkyl substances drive fluorochemical phaseout. Rhine-Ruhr industrial corridor converters capture shelf space with early PFAS-free certifications.
India
Organized pet care retail penetrates Tier-2 and Tier-3 cities, creating first-mover advantage for branded feeding vessel suppliers establishing local distribution. FSSAI food safety standards and BIS certification requirements shape import compliance. Maharashtra and Gujarat manufacturing clusters scale disposable format production for domestic veterinary networks.
United Kingdom
Clinical procurement of measured-dose feeding vessels intensifies as companion animal medicalization deepens across corporate veterinary networks. REACH chemical restrictions and evolving extended producer responsibility frameworks create compliance complexity. Greater London and Southeast England metropolitan areas specify biodegradable formats aligned with municipal composting infrastructure.
Pet Cups Market Competitive Landscape
Capacity expansion dominates the current landscape as converters scale polylactic acid thermoforming operations to capture biodegradable segment growth. The vendor base stratifies across three tiers: multinational integrated packaging conglomerates with backward resin integration, mid-scale regional specialists serving veterinary distributor networks, and emerging domestic fabricators in Asian manufacturing clusters. Strategic archetypes include cost-leaders leveraging high-volume thermoforming expertise, sustainability-positioned players with certified compostable portfolios, and premium-tier suppliers of reusable silicone and glass formats. M&A activity concentrates in veterinary supply chain consolidation, while technology licensing agreements accelerate PFAS-free coating adoption across European-serving manufacturing bases.
Among North American-based converters, Dart Container Corporation exemplifies cost-leadership archetypes through thermoforming scale, while WinCup occupies a sustainability-positioned tier with expanded polylactic acid capacity. Finnish limited liability company Huhtamaki Oyj anchors integrated fiber-based packaging technology across European and North American operations, representing multinational conglomerate structure with captive substrate supply chains.
| Leading Market Players |
|---|
| Dart Container Corporation |
| WinCup |
| CKF Inc |
| Anchor Packaging |
| Ningbo Yi Sheng Plastic Co., Ltd. |
| Huhtamaki Oyj |
| NNZ Group |
| Macpac S.A. |
| Sonoco Products Company |
| Others |
Value Network & Pricing Analysis
Backward integration into polylactic acid resin compounding anchors both supply security and pricing power for converters serving biodegradable cup demand in Germany and the Pacific Northwest. Captive substrate production insulates margin pools from corn futures volatility while enabling volume-tiered contracting with corporate veterinary networks.
Pricing Analysis
Volume concentration in polypropylene disposable cups compresses margins through commodity spot exposure, while biodegradable formats command premium-mid-economy pricing differentiation based on composting certification tier and municipal procurement scale. FDA food-contact notification costs amortize across high-volume contracts, squeezing smaller converters without depreciated tooling bases. Corporate veterinary group purchasing organizations extract steepest discounts, whereas premium pet retailers show lowest price sensitivity for PFAS-free coated fiber formats.
Supply Chain Analysis
Regional distribution centers in the Yangtze River Delta, Rhine-Ruhr corridor, and Ohio River Valley anchor hub-and-spoke patterns reaching veterinary clinic networks. Thermoforming operations draw from polypropylene resin, polylactic acid pellets, and barrier-coated paperboard rollstock. Single-source vulnerability concentrates in Chinese polylactic acid capacity. Distribution runs through specialized veterinary supply aggregators and direct manufacturer relationships with corporate clinic roll-ups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corporate veterinary procurement consolidation functions as a consolidation play, forcing independent distributors and small-scale converters without national supply guarantees toward exit or acquisition.
For Market Incumbents: Extend thermoforming capacity in Yangtze River Delta manufacturing bases to capture polylactic acid cost parity as Chinese domestic scale matures. Secure early PFAS-free coating certifications ahead of REACH Annex XVII enforcement windows, converting compliance scarcity into shelf space capture at German and Dutch premium retailers.
For New Entrants and Emerging Players: Tier-2 and Tier-3 Indian pet stores represent the most penetrable buyer archetype, with organized retail penetration creating first-mover advantage for branded feeding vessel suppliers establishing Maharashtra-based distribution partnerships. Bypass traditional veterinary distributor markups through subscription direct-to-consumer channels targeting multi-pet households.
For Investors and Strategic Acquirers: Exit pathways concentrate in veterinary supply chain consolidation, with corporate roll-ups seeking captive feeding vessel supply. Long-term viability favors converters with backward integration into resin compounding or certified compostable portfolios. Watch municipal composting infrastructure buildout in Midwestern United States metropolitan clusters as inflection indicator for biodegradable format demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Certification | Early REACH Annex XVII compliance captures scarcity premiums at German premium retailers. |
| Polylactic Acid Capacity Expansion | Yangtze River Delta scale-up enables price parity with polypropylene in bulk municipal orders. |
| Veterinary GPO Direct Contracting | Bypassing distributor markups secures volume-tiered pricing with corporate clinic networks. |
| Smart Dispensing Integration | RFID-enabled portion control opens premium positioning in clinical and boarding segments. |
| India Distribution Partnership | Tier-2 and Tier-3 organized retail penetration creates first-mover advantage in emerging markets. |
Research Methodology
Document review covered FDA food-contact notifications, EU REACH Annex XVII amendments, and veterinary supply chain procurement databases, complemented by interviews with converters, veterinary group purchasing organization procurement directors, and pet specialty retail category managers. Secondary validation drew from customs trade data, SAMR food-contact material filings, and corporate veterinary roll-up SEC disclosures. Bottom-up unit economics modeling triangulated against top-down market sizing across substrate and end-use segments.
Segmentation outputs reflect product type, material substrate, end-user procurement sophistication, and geographic regulatory cluster across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating veterinary clinic expansion rates, municipal composting infrastructure maturation, and polylactic acid thermoforming cost curves. Industry-specific inputs include corporate veterinary network procurement concentration indices and REACH chemical restriction implementation timelines.
Revisions become necessary when FDA notification timelines extend beyond standard windows, when polylactic acid feedstock costs decouple from corn futures, or when municipal composting infrastructure deployment stalls in targeted metropolitan clusters. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
US Pet Treats Market
Pet Care Products
Raw Meat Pet Food Market
Pet Care Products
Canned Wet Cat Food Market
Pet Care Products
Fish Based Pet Food Market
Pet Care Products
Hair Dryer for Pets Market
Pet Care Products
Bird Cages and Accessories Market
Pet Care Products
North America Pet Diet Market
Pet Care Products
Asia-Pacific Pet Food Market
Pet Care Products
Dog Treats Market
Pet Care Products
China Pet Training Services Market
Pet Care Products
Dry Dog Food Market
Pet Care Products
Europe Dog Food Market
Pet Care Products
United States Pet Care and Services Market
Pet Care Products
Cat Shampoo Market
Pet Care Products
UAE Pet Boarding Market
Pet Care Products
Organic and Natural Dog Foods Market