
 Japan Travel Retail Market | 2026-2036
Japan Travel Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Travel Retail Market Foresight
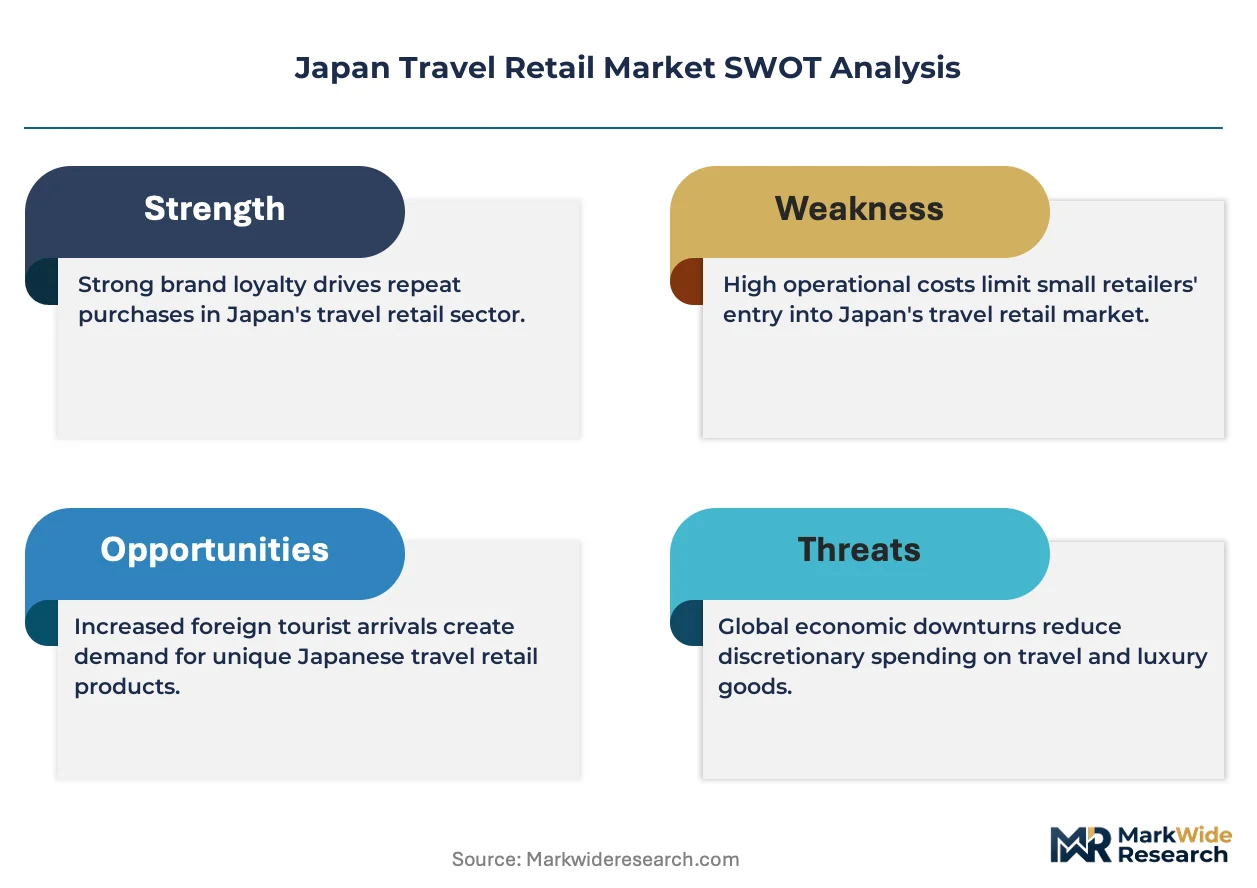
Premium beauty and skincare tier upgrades is reorganizing the Japan travel retail landscape as international visitors prioritize high-margin Japanese cosmetics over conventional souvenir purchases. ANA Trading Duty Free leverages its airline parent network to secure exclusive distribution rights for domestic luxury brands across Tokyo airports. Lagardère Travel Retail sustains competitive pressure through dedicated beauty flagship formats that dominate floor space at Narita Terminal 1. Fa-So-La anchors regional penetration with localized merchandise mixes at secondary hubs like Sendai and Hiroshima.
Japan travel retail encompasses duty-free and tax-exempt commercial transactions conducted within airport terminals, cruise vessels, and designated border zones, typically involving the sale of cosmetics, electronics, fashion goods, and regional souvenirs to non-resident visitors upon presentation of valid travel documentation and passport-based eligibility verification. The channel's primary commercial purpose centers on capturing discretionary spending from time-constrained international travelers through curated assortments, exclusive pricing, and localized brand storytelling unavailable in standard domestic retail. Cosmetics and skincare categories lead product-level margin generation due to Japanese beauty brand equity and traveler gifting behavior, while airport retail channels concentrate the majority of transaction volume through extended dwell-time environments at immigration-adjacent concourses. Online retail represents the fastest-growing distribution vector as pre-order platforms and mobile-enabled duty-free reservation systems reduce physical browsing friction for organized tour groups.
Japan's consumption tax exemption framework, administered by the National Tax Agency in coordination with Japan Customs, mandates strict documentation and product-handoff protocols that shape operator compliance costs and checkout infrastructure investments. METI guidelines on inbound tourism infrastructure and airport commercial development influence concession allocation timelines and retail space expansion approvals at major international gateways. PMDA cosmetics labeling requirements and quarantine inspection protocols for food-containing souvenirs further constrain product assortment decisions and supplier onboarding procedures. Stakeholders must monitor evolving customs automation standards and biometric passenger processing deployments to anticipate how reduced immigration wait times will reshape dwell-time economics and impulse purchase windows.
Market Dynamics
Japan's consumption tax exemption system is compressing checkout friction and rewiring airport concession economics, forcing operators to reconfigure floor space around passport-verified transaction flows rather than traditional browsing patterns.
Growth Catalysts
- Tax-Free Shopping Framework:Japan's streamlined consumption tax exemption protocols reduce documentation burden for foreign visitors at Narita and Haneda terminals. METI guidelines on inbound tourism infrastructure accelerate concession allocation timelines.
- Biometric Passenger Processing:Facial recognition boarding systems at Tokyo airports extend dwell-time windows for impulse purchases. Immigration automation investments by Japan Customs create adjacent retail engagement opportunities.
- Chinese Leisure Travel Recovery:Inbound visitor flows from Greater China concentrate discretionary spending on premium cosmetics and skincare categories. Airport operators capture this demand through dedicated luxury beauty flagships.
Market Restraints
- Labor Cost Escalation:Multilingual staffing requirements at major gateways drive personnel expenditure upward. Tokyo's minimum wage adjustments compound operator margin pressure during peak seasonal volumes.
- Concession Fee Structures:Percentage-rent models tied to passenger traffic create revenue volatility during demand shocks. Fixed-cost obligations persist regardless of flight schedule disruptions.
- Quarantine Inspection Protocols:PMDA food-containing souvenir regulations constrain regional product assortment breadth. Compliance documentation delays supplier onboarding for traditional confectionery and beverage categories.
Strategic Opportunities
- Pre-Order Platform Expansion:Mobile-enabled duty-free reservation systems capture organized tour group spending before airport arrival. Digital checkout integration reduces physical queuing friction.
- Secondary Hub Development:Fukuoka and Osaka Kansai airports offer underexploited capacity for regional duty-free concentration. Sendai and Hiroshima terminals present localized merchandise mix potential.
- Cruise Vessel Retail:International cruise terminal commercial zones at Yokohama and Kobe remain structurally underdeveloped. Maritime passenger volumes create captive audience segments distinct from air travelers.
Industry Challenges
- Legacy System Integration:Tax exemption documentation platforms require synchronization with Japan Customs automation standards. Operator IT infrastructure investments strain mid-tier concessionaires.
- Inventory Localization Complexity:Regional souvenir procurement demands coordination with fragmented domestic supplier bases. Quality consistency across multiple prefectural sourcing relationships challenges category managers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Travel Retail Market |
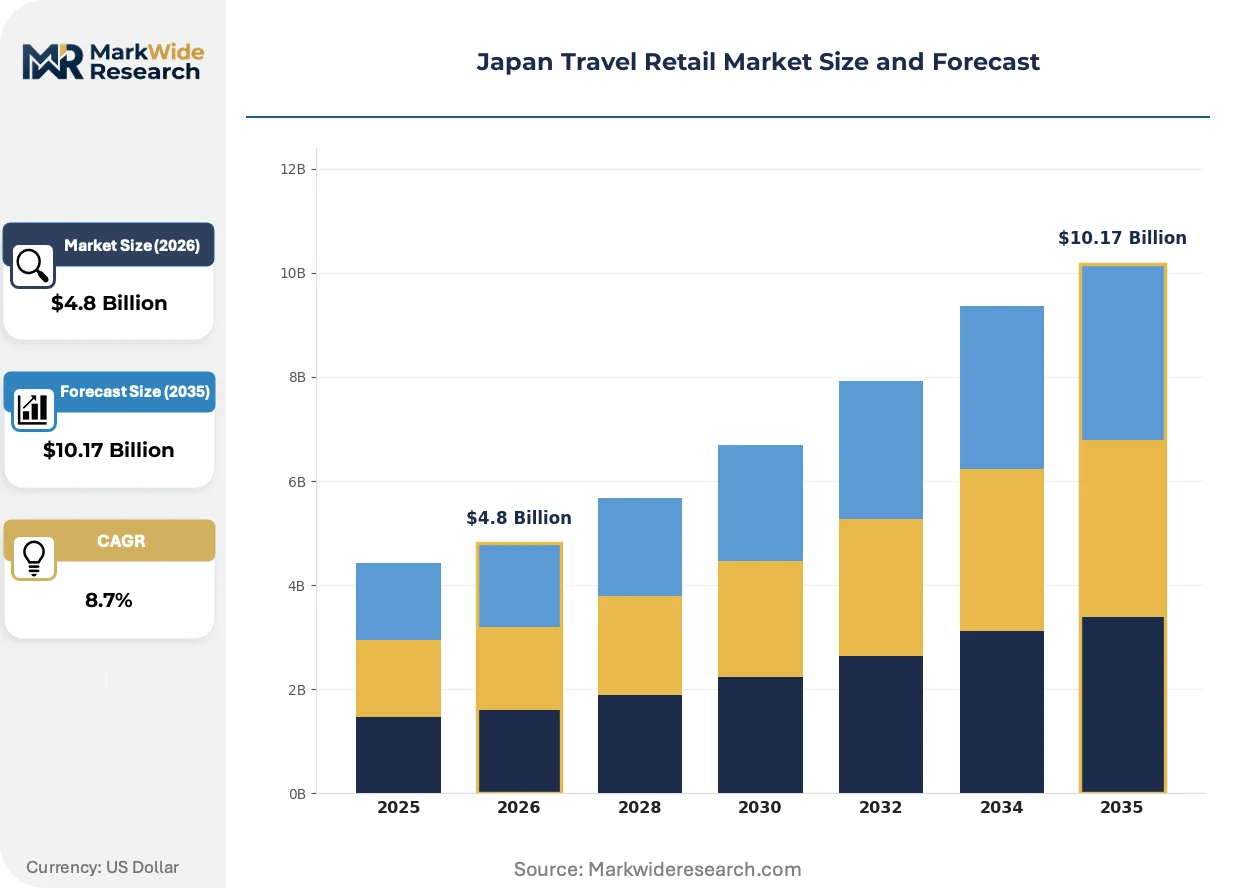
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Cosmetics, Fashion, Electronics, Souvenirs Distribution Channel: Airport Retail, Cruise Shops, Duty-Free Stores, Online Retail Customer Type: Leisure Travelers, Business Travelers, Tour Groups, Independent Tourists Pricing Model: Luxury, Mid-Range, Budget, Discounted |
| Companies Covered | ANA Trading Duty Free, Lagardère Travel Retail, Japan Airport Terminal Co. Ltd., LOTTE Duty Free, Avolta, NAA Retailing (Fa-So-La), DFS Group, TIAT Duty Free, JALUX Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Travel Retail Market Shifts & Advancements
Digital transaction infrastructure and biometric verification systems are compressing traditional duty-free operating models, while regulatory automation and shifting visitor demographics reconfigure product-mix priorities across Japan's airport network.
Contactless payment aggregation is displacing cash-dominant transaction patterns at Tokyo airport terminals. ANA Trading Duty Free and Lagardère Travel Retail deploy unified QR-code systems spanning Alipay, WeChat Pay, and domestic e-money platforms. This infrastructure consolidation compresses checkout duration and reduces foreign exchange handling costs.
METI's inbound tourism infrastructure guidelines mandate biometric passenger processing deployments at Narita, Haneda, and Kansai terminals by 2027. Automated immigration gates reduce passenger wait times and reshape dwell-time economics for adjacent retail concourses. Beauty and skincare concessionaires respond by repositioning high-margin inventory toward immigration-adjacent zones.
Chinese and Southeast Asian visitor preferences are compressing traditional souvenir category allocation. Premium cosmetics and skincare SKUs displace generic regional gifts in floor-space planning. Osaka Kansai operators report category-mix rotation toward J-beauty exclusives unavailable in domestic urban retail.
Japan Travel Retail Market Segmentation
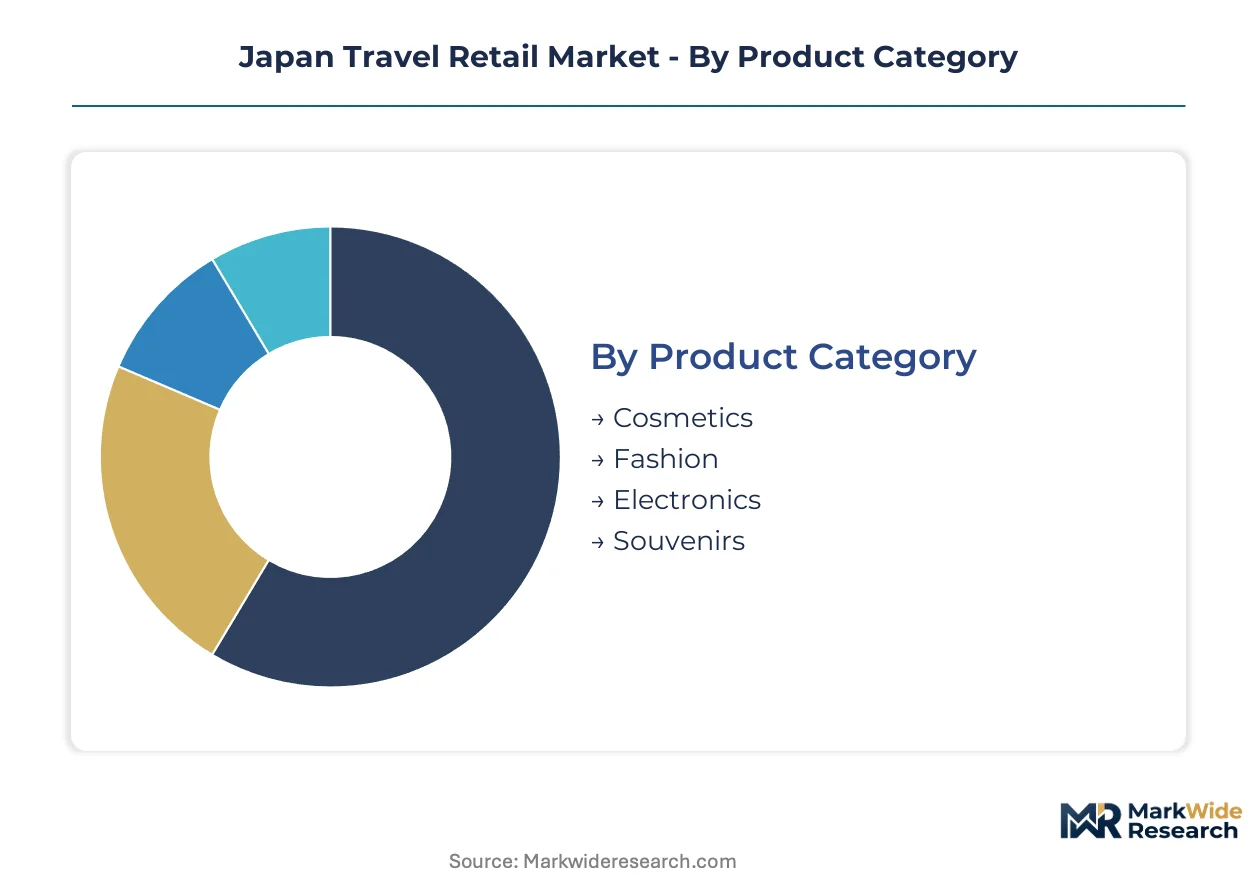
Segmentation in Japan travel retail reveals how passenger demographics, channel economics, and product margins interact within METI-regulated airport environments. Understanding these divisions clarifies where tax exemption protocols and biometric processing investments concentrate commercial returns.
Product Category:
Domestic Japanese brands dominate cosmetics and skincare exports through airport channels, while electronics and regional souvenirs serve primarily inbound leisure demand concentrated at Narita and Haneda.
- Cosmetics:Premium skincare and color cosmetics from Japanese beauty houses generate the highest per-transaction values. Demand clusters at Greater Tokyo airports where Chinese and Southeast Asian visitors purchase J-beauty exclusives unavailable in their home markets. METI tourism infrastructure guidelines support dedicated beauty flagship formats in immigration-adjacent zones.
- Fashion:Apparel and accessories span luxury houses to contemporary Japanese designers. Spending concentrates among independent tourists with extended dwell time at Haneda's international terminal. PMDA labeling requirements do not constrain this category, enabling faster supplier onboarding than cosmetics.
- Electronics:Consumer electronics and personal devices appeal to regional Asian visitors seeking voltage-compatible goods. Osaka Kansai operators report stronger traction than Tokyo gateways for this segment.
- Souvenirs:Regional confectionery, traditional crafts, and prefectural specialty foods face quarantine inspection protocols that constrain assortment breadth. Compliance documentation delays procurement from fragmented domestic supplier bases.
Cosmetics holds the largest share; momentum sits with Fashion as biometric processing extends dwell-time windows.
Distribution Channel:
Channel economics diverge sharply between fixed-concession airport retail and emerging digital platforms, with labor cost structures and passenger traffic volatility determining operator viability.
- Airport Retail:Fixed concession spaces at immigration-adjacent concourses capture the majority of transaction volume. Percentage-rent models tied to passenger traffic create revenue volatility during demand shocks.
- Cruise Shops:Maritime retail at Yokohama and Kobe terminals serves captive passenger segments with distinct purchasing patterns. This channel remains structurally underdeveloped relative to airport infrastructure.
- Duty-Free Stores:Dedicated tax-exempt outlets in downtown Tokyo and Osaka supplement airport capture. Japan Customs documentation requirements apply uniformly across physical locations.
- Online Retail:Mobile-enabled reservation platforms and pre-order systems reduce physical queuing friction for organized tour groups. This channel is expanding most quickly as operators digitize checkout integration.
Airport Retail commands current volume leadership; Online Retail shows the steepest expansion trajectory as biometric passenger processing reshapes dwell-time economics.
Customer Type:
Leisure travelers from Greater China drive premium cosmetics demand, while business travelers and tour groups exhibit divergent channel preferences and price sensitivities.
- Leisure Travelers:Individual vacationers from China and Southeast Asia concentrate discretionary spending on high-margin beauty and skincare. Narita Terminal 1 operators configure floor space around this segment's gifting behavior.
- Business Travelers:Time-constrained corporate passengers favor expedited checkout and compact electronics. Their compressed dwell times limit browsing depth.
- Tour Groups:Organized cohorts move through terminals on fixed schedules, responding to pre-order platforms that secure spending before airport arrival.
- Independent Tourists:Self-directed visitors from Europe and North America explore secondary hubs like Fukuoka and regional terminals at Sendai and Hiroshima.
Leisure Travelers generate the highest revenue per passenger; Independent Tourists are gaining share fastest as visa facilitation expands source market diversity.
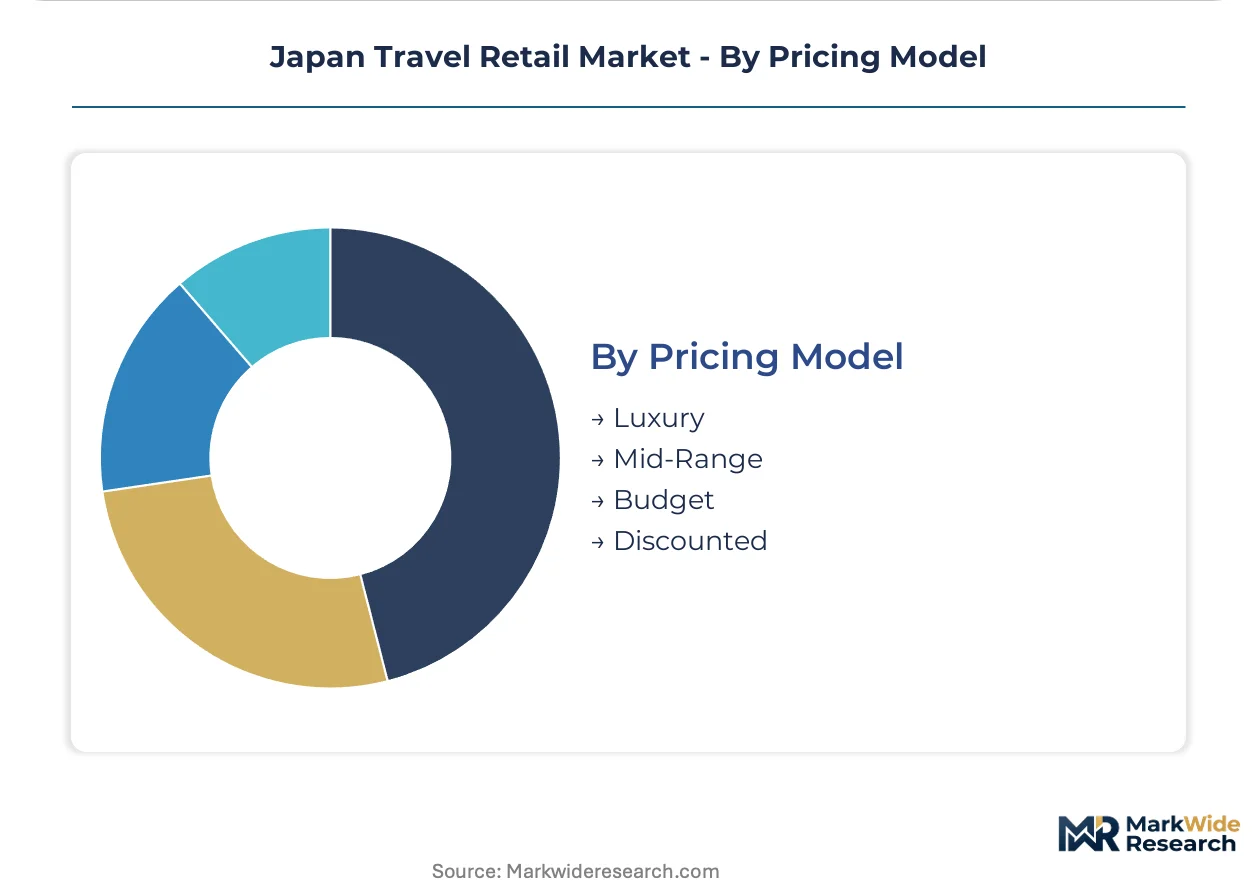
Pricing Model:
Price tiering aligns with passenger origin economics and product category margins, with luxury beauty commanding premium positioning against budget souvenir alternatives.
- Luxury:High-end cosmetics, designer fashion, and premium electronics target Chinese visitors with strong currency purchasing power. ANA Trading Duty Free secures exclusive distribution rights for domestic luxury brands.
- Mid-Range:Contemporary Japanese brands and accessible skincare lines balance margin and volume. This tier dominates floor space at Osaka Kansai.
- Budget:Entry-point cosmetics and functional electronics serve price-sensitive Southeast Asian segments.
- Discounted:Promotional pricing on seasonal inventory and near-expiry confectionery clears stock without damaging brand equity.
Luxury pricing captures the highest absolute margins; Mid-Range is climbing the fastest as operators broaden accessibility to emerging source markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's travel retail infrastructure concentrates passenger flow and commercial investment across five distinct regional clusters, each shaped by distinct regulatory frameworks and visitor demographics.
Kanto/Tokyo
Greater Tokyo's airport cluster commands the dominant share of inbound duty-free spending, with Narita and Haneda terminals processing the bulk of Chinese and Southeast Asian leisure traffic. METI's inbound tourism infrastructure guidelines prioritize concession allocation and biometric processing deployments at these gateways. ANA Trading Duty Free leverages its airline parent network to secure exclusive J-beauty distribution rights across Tokyo terminals.
Kansai/Osaka
Osaka Kansai International Airport functions as the western hub for regional Asian visitor flows, with stronger traction in electronics categories than Tokyo gateways. Japan Customs documentation requirements apply uniformly, though local operators report faster supplier onboarding for non-PMDA-constrained fashion goods. The terminal's floor space increasingly rotates toward mid-range contemporary Japanese brands.
Kyushu/Fukuoka
Fukuoka Airport captures rising independent tourist volumes from visa-facilitated source markets, presenting underexploited capacity for regional duty-free concentration. The prefecture's fragmented domestic supplier base complicates localized souvenir procurement. Operators here configure merchandise mixes around shorter-haul Southeast Asian segments.
Chubu/Nagoya
Chubu Centrair International Airport serves manufacturing corridor business travelers with compressed dwell times favoring expedited checkout formats. PMDA cosmetics labeling requirements still constrain premium beauty assortment breadth. The terminal's retail concourses remain secondary to Osaka and Tokyo in absolute transaction volume.
Tohoku/Sendai
Sendai Airport anchors regional penetration for Fa-So-La with localized merchandise mixes targeting domestic tourism and limited international service. Quarantine inspection protocols for food-containing souvenirs particularly constrain this sub-region's traditional confectionery sourcing. Infrastructure investment lags METI's prioritization of primary international gateways.
Japan Travel Retail Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Japan's travel retail sector. Airline-affiliated concessionaires exploit parent network synergies for exclusive brand access, while independent duty-free operators compete through flagship format investments and localized assortment depth. Three strategic archetypes dominate: carrier-integrated trading houses, global travel retail specialists, and regional airport terminal operators. Competitive moves concentrate on biometric checkout integration and pre-order platform deployment.
Within the carrier-integrated tier, ANA Trading Duty Free and JALUX Inc. exemplify airline-parent leverage for exclusive domestic luxury brand distribution. Lagardère Travel Retail occupies a position among global specialists deploying dedicated beauty flagship formats. NAA Retailing, operating the Fa-So-La brand, anchors regional penetration across secondary hubs. These three represent distinct strategic postures: network-integrated exclusivity, format-led global scale, and sub-regional localization.
| Leading Market Players |
|---|
| ANA Trading Duty Free |
| Lagardère Travel Retail |
| Japan Airport Terminal Co. Ltd. |
| LOTTE Duty Free |
| Avolta |
| NAA Retailing (Fa-So-La) |
| DFS Group |
| TIAT Duty Free |
| JALUX Inc. |
| Others |
Supply & Pricing Matrix
Concession scale economies at Narita and Haneda terminals concentrate procurement leverage among a handful of duty-free operators, compressing supplier margins while establishing price floors that smaller regional players cannot match. METI's infrastructure guidelines accelerate this consolidation by favoring incumbent bidders with proven biometric checkout integration and tax-exemption compliance systems.
Pricing Analysis
METI's consumption tax exemption protocols dictate the pricing tier structure across Japan's airport retail network. Three-tier pricing stratifies across premium J-beauty exclusives, mid-range contemporary Japanese brands, and budget functional electronics. Price differentiation hinges on brand exclusivity secured through airline-parent networks and PMDA certification tiers for cosmetics. Cost compression in the budget tier intensifies as Southeast Asian visitor volumes strain multilingual staffing ratios. Tour group buyers exhibit highest price sensitivity; independent Chinese leisure travelers show lowest sensitivity to premium positioning.
Supply Chain Analysis
Just-in-time inventory strategies dominate cosmetics and skincare procurement, while strategic stockpiling persists for electronics with volatile semiconductor component availability. Manufacturing concentrates in Japan for premium beauty goods, South Korea for display panels and memory components, and China for budget electronics and packaging materials. Raw material dependencies span botanical extracts for skincare formulations, rare earth elements for consumer electronics, and specialized glass for cosmetic packaging. Single-source vulnerability runs through exclusive distribution agreements held by ANA Trading Duty Free and Lagardère Travel Retail. Distribution runs through centralized bonded warehouses at Narita and Haneda before last-mile deployment to concourse retail zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan travel retail operates within a cyclical recovery phase anchored to Chinese leisure travel normalization and METI's biometric processing infrastructure rollout. Passenger volume volatility and concession fee structures amplify cyclical exposure for undercapitalized operators.
For Market Incumbents: Secure exclusive renewal terms at Tokyo terminals before METI's 2027 biometric deployment deadlines compress concession allocation timelines. Lock in backward integration with domestic J-beauty manufacturers to defend margin position against LOTTE Duty Free's aggressive expansion. Biometric checkout standardization threatens to commoditize service differentiation; incumbents must embed proprietary pre-order platform integration to maintain captive customer relationships.
For New Entrants and Emerging Players: Lead with cruise vessel retail at Yokohama and Kobe terminals, where maritime passenger volumes create captive audiences absent entrenched duty-free competition. Secondary hubs Fukuoka and Sendai present underexploited capacity for regional souvenir localization. A digital-first go-to-market angle—mobile-enabled duty-free reservation systems—sidesteps the fixed-cost burden of percentage-rent concession models.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among carrier-integrated trading houses with exclusive brand distribution rights and pre-order platform subscription flows. Long-term viability over a multi-year horizon favors operators with demonstrated METI compliance infrastructure and biometric processing deployment capabilities. The signal to watch is Japan Customs automation standard adoption rates, which will reshape dwell-time economics and concession profitability thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Checkout Integration | METI-mandated facial recognition boarding systems at Narita and Haneda extend impulse purchase windows. |
| Pre-Order Platform Deployment | Mobile-enabled reservation systems capture organized tour group spending before physical airport arrival. |
| Exclusive Brand Distribution | ANA Trading Duty Free leverages airline-parent networks for J-beauty exclusives unavailable in domestic retail. |
| Secondary Hub Expansion | Fukuoka and Sendai terminals offer localized merchandise mix potential with limited incumbent saturation. |
| Cruise Vessel Retail Development | Yokohama and Kobe maritime terminals remain structurally underdeveloped relative to airport infrastructure. |
Research Methodology
A spread of perspectives from duty-free concession managers, airport retail procurement directors, METI infrastructure planners, Japan Customs automation specialists, and J-beauty brand distribution heads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through Japan National Tourism Organization visitor statistics, METI inbound tourism policy documents, PMDA cosmetics registration databases, and airport concession bidding records. Bottom-up passenger flow modeling and top-down revenue triangulation anchored volume and value estimates.
Segmentation dimensions modeled span product category, distribution channel, customer type, pricing tier, and regional airport cluster across the projection horizon. CAGRs were derived from passenger traffic elasticity analysis, tax exemption transaction velocity trends, and biometric processing deployment timelines. Industry-specific forecast inputs include Chinese leisure travel recovery patterns and METI concession allocation priority rankings.
Forecasts assume regulatory continuity in METI tourism infrastructure guidelines and Japan Customs automation standards; material policy shifts would require re-modeling. PMDA labeling requirement changes, quarantine inspection protocol revisions, or bilateral visa facilitation agreements represent specific risk factors that could alter trajectory. Practitioners should keep alternative scenarios live as Chinese visitor volume patterns and biometric deployment schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
MICE Travel Service Market
Travel and Tourism
Wedding Tourism Market
Travel and Tourism
Travel and Tourism Market
Travel and Tourism
Domestic Tourism Market
Travel and Tourism
Agritourism Market
Travel and Tourism
Customised Holidays Market
Travel and Tourism
Global Duty-Free and Travel Retail Market
Travel and Tourism
Russia Outbound Tourism Market
Travel and Tourism
Tourism Vehicle Rental Market
Travel and Tourism
Global Golf Travel Market
Travel and Tourism
Global Enotourism Market
Travel and Tourism
North America Pet Travel Services Market
Travel and Tourism
Global Ecotourism Market
Travel and Tourism
South Korea Tourism Market
Travel and Tourism
Digital Travel Market
Travel and Tourism
South Korea Sports Tourism Market