
 Europe Wellness Tourism Market | 2026-2036
Europe Wellness Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wellness Tourism Market Foresight
The premium medical wellness tier is consolidating around physician-supervised programs and thermal mineral treatments, while commodity spa packages fragment into undifferentiated day-trip offerings. Six Senses Hotels Resorts Spas leverages its science-backed sleep and nutrition programming to sustain rate premiums across Mediterranean and Alpine properties. Lanserhof Group anchors the clinical segment with its fasting and metabolic therapy protocols in Austria and Germany. Accor S.A. competes through scale, integrating spa concepts across mid-tier and luxury portfolios to capture volume.
Europe wellness tourism encompasses travel undertaken for the primary purpose of maintaining or enhancing personal health through structured physical, psychological, nutritional, or spiritual activities, typically involving minimum stays of one night at facilities offering certified therapeutic protocols, licensed practitioner oversight, and purpose-built environments combining mineral water infrastructure, controlled climate systems, and organic sourcing standards. Spa services command the largest revenue share within service type segmentation, though nutritional therapy is gaining share as metabolic health programs attract repeat clientele. Facility type segmentation shows retreat centers generating the highest per-visitor margins due to extended average lengths of stay and bundled pricing models, while day spas face compression from urban wellness studio competition.
EMA guidelines on wellness claims substantiation, EU Green Deal building efficiency mandates for hospitality, and country-level thermal spring classification standards in Germany and Austria collectively raise compliance costs while filtering out uncredentialed operators. CSRD reporting requirements now compel major hotel groups to disclose wellness facility environmental footprints, directing capital toward retrofitting existing thermal infrastructure rather than greenfield development. Stakeholders must weigh whether to pursue medical licensing partnerships that command premium positioning or operate below the regulatory threshold in saturated day-spa segments.
Market Dynamics
The EU Green Deal is compressing capital deployment timelines for thermal spa operators across Germany, Austria, and Switzerland, forcing facility retrofits ahead of building efficiency mandates while redirecting investment from greenfield Alpine developments toward existing mineral water infrastructure upgrades.
Growth Catalysts
- CSRD disclosure mandates:The Corporate Sustainability Reporting Directive compels major hotel groups to document wellness facility environmental footprints, accelerating capital flows toward certified thermal infrastructure and filtering uncredentialed day-spa competitors from premium positioning.
- Alpine thermal corridor concentration:Medical-grade wellness protocols intersect with established hospitality infrastructure across Bavaria, Tyrol, and Styria, creating density economies that reduce patient acquisition costs for physician-supervised metabolic therapy programs.
- Corporate retreat procurement:Human resources departments at financial services and technology firms now structure multi-year wellness contracts with dedicated retreat centers, shifting buyer power from individual consumers toward institutional procurement with guaranteed occupancy floors.
Market Restraints
- EMA wellness claims substantiation:The European Medicines Agency's evidentiary requirements for therapeutic outcome assertions raise legal compliance costs for operators marketing metabolic health benefits, compressing margins for mid-tier facilities lacking clinical research partnerships.
- Thermal spring classification bottlenecks:Germany and Austria maintain divergent mineral water grading protocols that fragment certification pathways, forcing multi-country operators to duplicate testing regimens and delaying cross-border facility standardization.
- Licensed practitioner scarcity:Physician supervision requirements for medical-grade tier positioning outpace specialist training pipeline output in Austria and Switzerland, constraining program expansion regardless of capital availability.
Strategic Opportunities
- Corporate wellness procurement integration:Human resources platforms and employee benefit administrators represent underdeveloped distribution channels for extended-stay metabolic therapy packages, offering direct access to pre-qualified high-intent buyers outside traditional hospitality booking engines.
- Nutritional therapy protocol extension:Metabolic health programming is absorbing demand from diabetes prevention and longevity medicine verticals, enabling Alpine facilities to capture repeat clientele through subscription-based nutritional counseling rather than single-visit spa packages.
- EU Green Deal retrofit incentives:National implementation frameworks in Germany and Austria provide partial capital cost coverage for thermal infrastructure energy efficiency upgrades, improving returns on existing asset repositioning relative to new construction.
Industry Challenges
- Medical licensing partnership negotiations:Facility operators face protracted contracting timelines with physician groups and hospital networks to secure supervisory coverage, delaying premium-tier program launches and compressing first-mover windows.
- Legacy booking system integration:Thermal spa operators with decades-old reservation infrastructure struggle to interface with modern corporate procurement platforms and wellness benefit administrators, creating friction in institutional sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wellness Tourism Market |
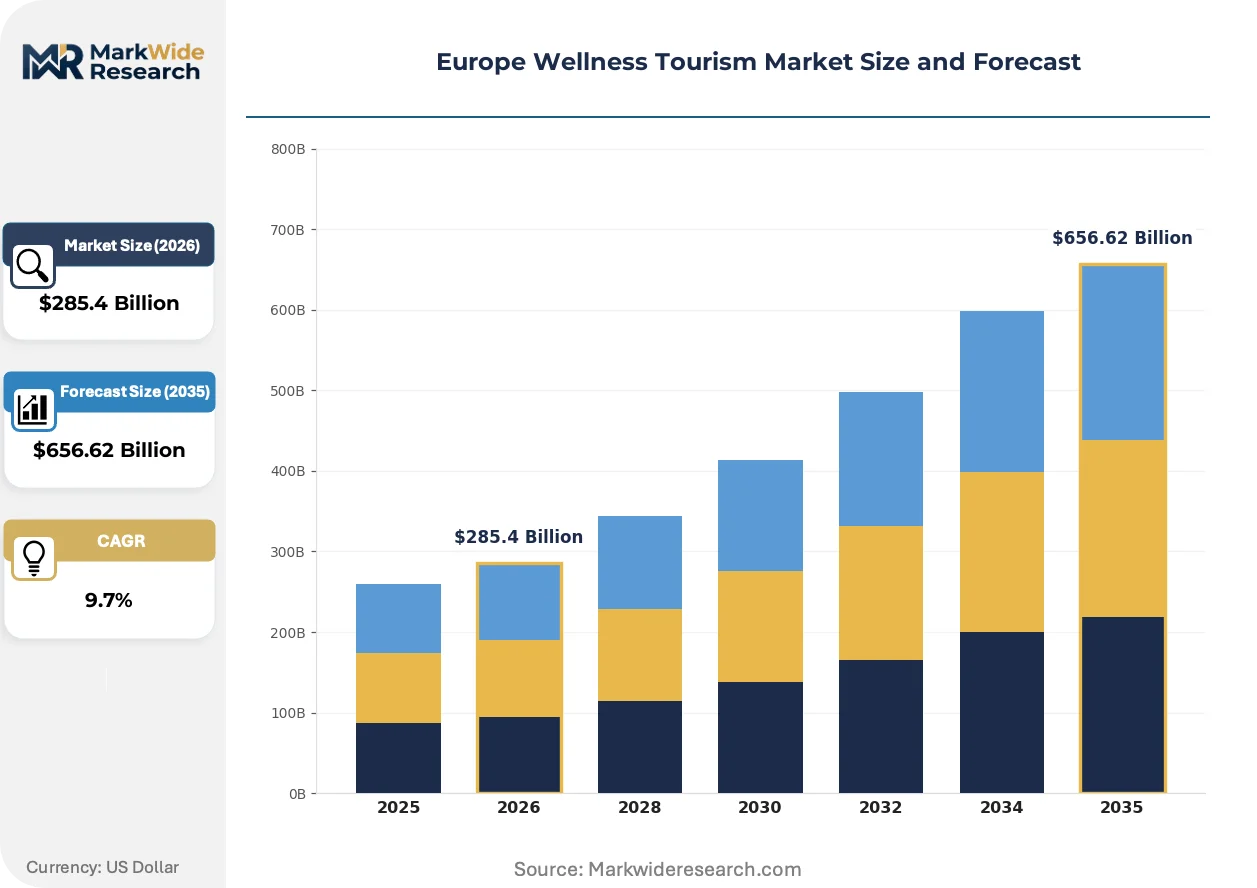
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $656.62 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Spa, Fitness, Alternative Medicine, Nutritional Therapy Customer Type: Leisure Travelers, Corporate Retreats, Wellness Groups, Solo Travelers Facility Type: Resorts, Hotels, Retreat Centers, Day Spas Activity Type: Meditation, Yoga, Nature Therapy, Massage Therapy |
| Companies Covered | InterContinental Hotels Group, Six Senses Hotels Resorts Spas, Accor S.A., Therme Group, Lanserhof Group, Marriott International, Hyatt Hotels, Banyan Tree Holdings, Hilton Worldwide, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wellness Tourism Market Shifts & Advancements
Digital biomonitoring and controlled-environment sleep architecture are reshaping how Alpine wellness facilities differentiate premium medical-tier offerings from commodity spa experiences, compressing the operational gap between hospitality and clinical service delivery.
Continuous glucose monitoring and circadian rhythm optimization systems are absorbing capital allocation from traditional massage and hydrotherapy equipment purchases. Corporate retreat planners now specify biometric tracking integration in procurement requirements. This technology convergence is absorbing rate premiums previously captured through amenity expansion alone, forcing facility operators to prioritize physiological data infrastructure over square footage growth.
The EU Green Deal's building efficiency mandates for hospitality properties are accelerating thermal infrastructure retrofit cycles across Germany and Austria. Operators must achieve specified energy performance thresholds to maintain thermal spring operating licenses. Alpine corridor facilities face the steepest compliance timelines due to older building stock and stricter regional implementation schedules in Bavaria and Tyrol.
Buyer concentration among corporate human resources departments is displacing individual leisure travel as the dominant demand formation mechanism for extended-stay wellness programs. Facility sales teams now maintain dedicated enterprise account functions previously unnecessary in consumer-direct markets. This procurement pattern shift is most visible in Switzerland, where pharmaceutical and banking headquarters clusters generate predictable group booking volumes with longer advance planning horizons than individual wellness tourism.
Europe Wellness Tourism Market Segmentation
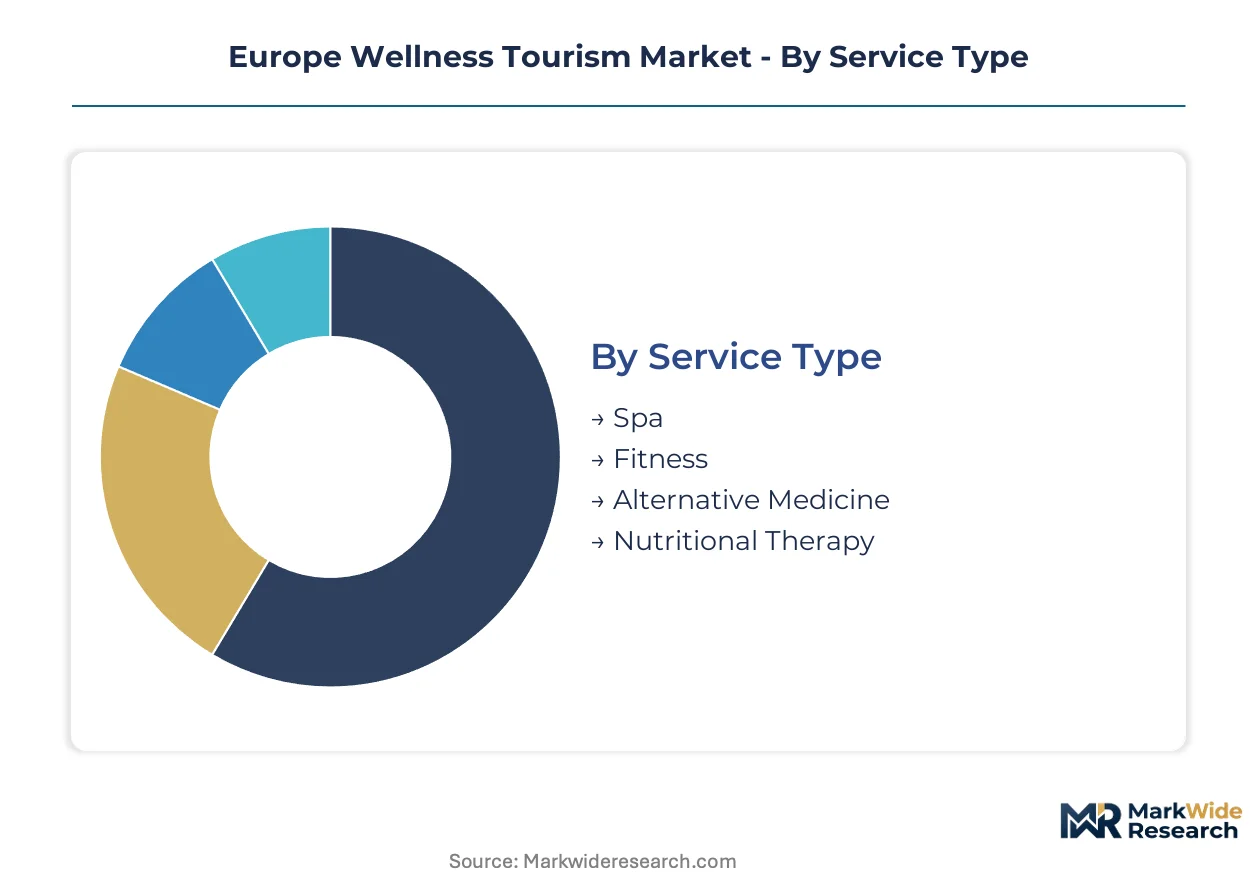
Europe wellness tourism operators must align facility investments with distinct buyer procurement patterns and service delivery requirements. Segmentation reveals where capital flows concentrate and which customer cohorts command premium pricing power.
Service Type:
Upgrade cycles favor modalities with measurable physiological outcomes over experiential amenities.
- Spa:Thermal mineral treatments and hydrotherapy infrastructure dominate capital allocation in Alpine corridors. Bavarian and Tyrolean facilities leverage medically certified spring classifications to sustain rate premiums above Mediterranean competitors.
- Nutritional Therapy:Metabolic health programs incorporating continuous glucose monitoring and personalized dietary protocols attract repeat corporate clientele. Austrian retreat centers bundle extended-stay packages with physician-supervised fasting regimens.
- Fitness:Structured movement programming with biometric tracking integration now appears in procurement specifications from financial services HR departments.
- Alternative Medicine:Ayurvedic and traditional Chinese medicine offerings concentrate in Portuguese and Spanish coastal properties serving longevity-focused retirees.
Volume placements concentrate in Spa; the faster expansion belongs to Nutritional Therapy.
Customer Type:
Buyer power shifts from individual leisure travelers toward institutional procurement with guaranteed occupancy commitments.
- Corporate Retreats:Multi-year wellness contracts from pharmaceutical and banking headquarters in Switzerland generate predictable group bookings. Swissmedic-aligned facilities capture preference through clinical credibility.
- Wellness Groups:Pre-formed communities seeking shared metabolic therapy experiences drive shoulder-season occupancy at Austrian Lanserhof properties.
- Leisure Travelers:Individual bookings fragment across undifferentiated day-spa offerings in German urban centers.
- Solo Travelers:Digital nomad visa holders in Portugal and Spain extend average lengths of stay through subscription-based wellness memberships.
Revenue concentration tilts toward Corporate Retreats; Solo Travelers are climbing the fastest as remote work normalization extends booking windows.
Facility Type:
Margin structures diverge sharply between extended-stay medical-grade properties and commoditized urban day facilities.
- Retreat Centers:Bundled pricing models covering accommodation, diagnostic assessment, and supervised therapy protocols generate per-visitor margins substantially above hospitality industry averages. Styrian properties lead in metabolic therapy density.
- Resorts:Integrated spa concepts across Mediterranean portfolios compete on amenity breadth rather than clinical depth.
- Hotels:Mid-tier properties in German business districts face compression from dedicated wellness studio competition.
- Day Spas:Urban locations without thermal spring access struggle to differentiate against app-booked mobile practitioner services.
Capital deployment concentrates in Retreat Centers; repositioning activity is gaining share fastest among Hotels seeking medical licensing partnerships.
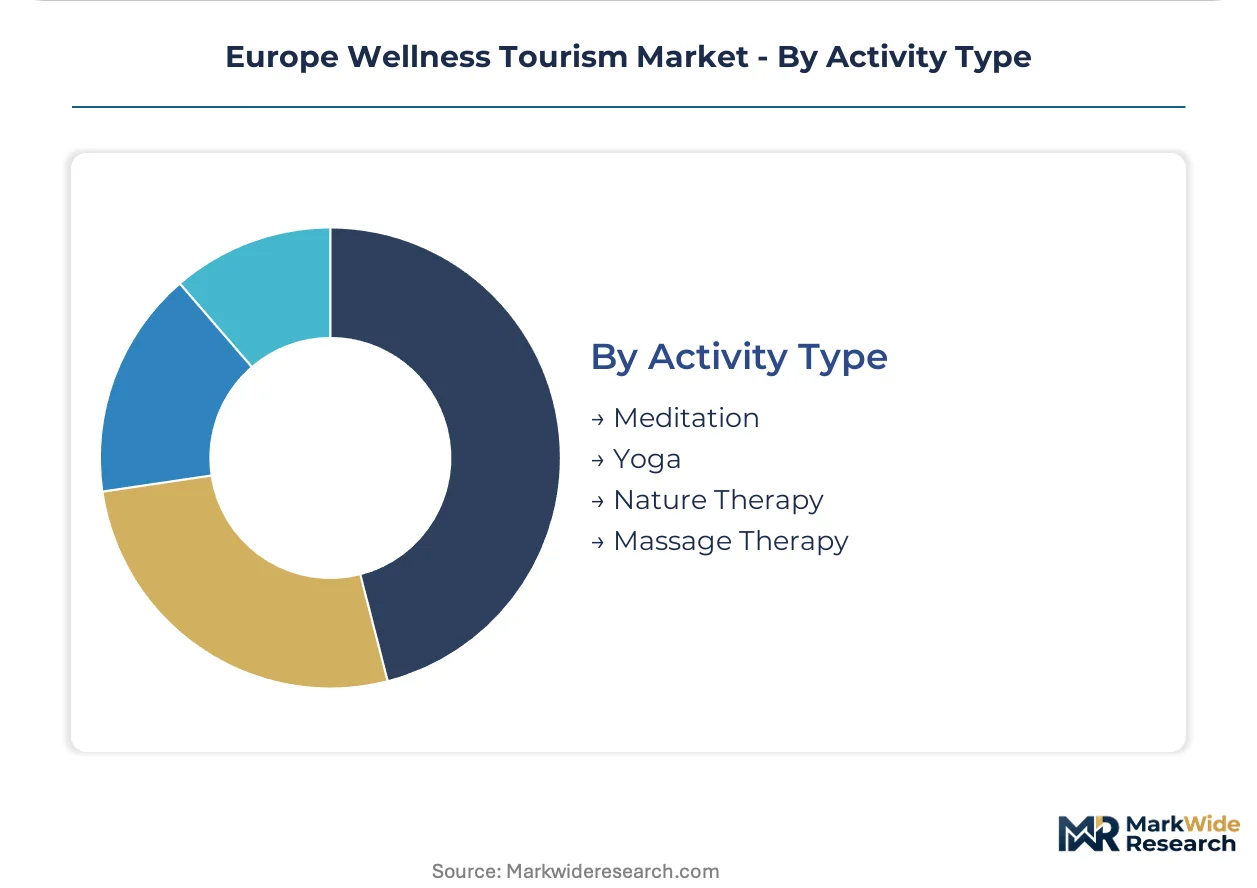
Activity Type:
Procurement specifications increasingly demand biometric validation of claimed therapeutic outcomes.
- Meditation:Neurofeedback-enabled mindfulness training commands premium positioning at Swiss Alpine properties serving executive clientele.
- Yoga:Standardized instructor certification programs from German wellness academies reduce differentiation potential.
- Nature Therapy:Prescribed forest bathing protocols with cortisol level documentation attract German health insurance reimbursement pilot programs.
- Massage Therapy:Manual treatments without diagnostic integration face rate pressure from automated percussion device alternatives.
Program development concentrates in Meditation; Nature Therapy shows the steepest expansion trajectory as CSRD-aligned corporate wellness mandates emphasize measurable stress reduction outcomes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Alpine thermal corridor spanning Bavaria, Tyrol, and Styria anchors European wellness tourism capacity, with Baden-Baden and Merano generating the highest physician-supervised program density on the continent.
Germany
Corporate retreat procurement from Frankfurt and Munich financial services firms drives multi-year thermal spa contracts. The EU Green Deal building efficiency mandates compress retrofit timelines for Bavarian facilities. Baden-Württemberg's mineral spring operators face accelerated compliance deadlines that redirect capital from new construction toward existing infrastructure upgrades.
Austria
Metabolic therapy and fasting protocols attract repeat wellness group clientele seeking extended-stay clinical programs. Thermal spring classification standards under Austrian federal health law fragment certification pathways for cross-border operators. Tyrolean retreat centers in the Stubaital and Zillertal valleys concentrate the highest density of physician-supervised nutritional therapy facilities in Europe.
Switzerland
Pharmaceutical and banking headquarters clusters in Basel and Zurich generate predictable corporate wellness booking volumes with longer advance planning horizons than leisure travel. Swissmedic alignment requirements filter uncredentialed competitors from premium medical-tier positioning. The Engadin and Valais Alpine regions host the continent's most concentrated neurofeedback-enabled executive wellness programming.
France
Thalassotherapy coastal resorts in Brittany and Provence compete on amenity breadth rather than clinical depth. ANSM wellness claims substantiation rules raise evidentiary requirements for therapeutic outcome marketing. The Côte d'Azur corridor between Nice and Monaco captures Mediterranean wellness demand through integrated spa-hotel concepts serving longevity-focused retirees.
United Kingdom
Urban wellness studio competition compresses day-spa margins in London and Manchester. CSRD disclosure mandates for hospitality groups accelerate capital flows toward certified thermal infrastructure investments. The Cotswolds and Scottish Highlands retreat centers develop nature therapy protocols with cortisol documentation to attract corporate wellness procurement.
Europe Wellness Tourism Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification grade and clinical supervision depth. The vendor base organizes into three tiers: physician-supervised medical-grade facilities, integrated resort spa concepts, and undifferentiated urban day operations. Two strategic archetypes dominate competitive positioning—clinical protocol specialists leveraging metabolic therapy credibility, and scale-driven hospitality groups capturing volume through portfolio breadth. M&A activity concentrates on medical licensing partnerships, while capital deployment prioritizes thermal infrastructure retrofitting over greenfield Alpine development.
Within the clinical specialist tier, Lanserhof Group and Six Senses Hotels Resorts Spas exemplify divergent positioning strategies. Lanserhof anchors the Austrian-German medical-grade segment through physician-supervised fasting and metabolic therapy protocols. Six Senses occupies a science-backed lifestyle positioning across Mediterranean and Alpine properties. Accor S.A. represents the scale-driven archetype, integrating spa concepts across mid-tier and luxury portfolios to capture procurement volume from corporate retreat planners.
| Leading Market Players |
|---|
| InterContinental Hotels Group |
| Six Senses Hotels Resorts Spas |
| Accor S.A. |
| Therme Group |
| Lanserhof Group |
| Marriott International |
| Hyatt Hotels |
| Banyan Tree Holdings |
| Hilton Worldwide |
| Others |
Supply & Pricing Matrix
Physician-supervised medical-grade tier divergence from commoditized urban day-spa offerings manifests in divergent pricing power and supply chain configurations across Alpine corridors. Certification depth determines rate premiums while thermal spring access constraints reshape procurement geography and capital deployment priorities.
Pricing Analysis
Outcome-based pricing anchors the medical-grade tier, with bundled metabolic therapy packages commanding premiums tied to measurable physiological markers like glucose regulation and cortisol reduction. Three-tier pricing structure across premium, standard, and economy levels separates Swissmedic-aligned clinical facilities from integrated resort concepts and undifferentiated day operations. Pricing pressure stems from corporate procurement departments demanding biometric validation for rate justification, compressing margins for amenities without diagnostic integration. Leisure travelers at urban German day-spas exhibit highest price sensitivity, while pharmaceutical HR departments in Basel and Zurich demonstrate lowest sensitivity given wellness budget allocation through employee benefit platforms.
Supply Chain Analysis
Dual-sourcing requirements for thermal spring mineral certification force operators to qualify laboratories in both Germany and Austria, fragmenting testing infrastructure despite geographic proximity. Supply concentration centers on Bavaria, Tyrol, and Styria for thermal water infrastructure, with Portugal and Spain providing alternative coastal retreat capacity. Licensed physician partnerships, continuous glucose monitoring hardware, and organic sourcing certifications constitute critical input dependencies. Single-source vulnerability runs through Austrian fasting therapy specialist training pipelines, constraining program expansion regardless of capital availability. Distribution runs through corporate HR benefit administrators and wellness procurement platforms rather than traditional hospitality booking engines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration race dynamics favor operators securing upstream control over thermal spring assets and downstream capture of corporate procurement relationships. Medical licensing partnerships represent the critical lever separating premium-tier positioning from commodity compression.
For Market Incumbents: Deepen thermal infrastructure retrofit investments ahead of EU Green Deal compliance deadlines in Bavaria and Tyrol, securing operating license continuity. Acquire or contract exclusive physician supervision capacity to defend against emerging metabolic therapy entrants from Portugal and Spain. Prioritize legacy booking system modernization to interface with corporate wellness procurement platforms, removing friction in institutional sales cycles threatened by tech-enabled competitors. For New Entrants and Emerging Players: Enter via corporate wellness benefit administrator partnerships, bypassing saturated direct-to-consumer channels dominated by established Alpine brands. Target Portuguese and Spanish coastal corridors for digital nomad visa holders seeking subscription-based wellness memberships, the most penetrable segment given remote work normalization. Pursue nature therapy protocol development with cortisol documentation to qualify for German health insurance reimbursement pilot programs. For Investors and Strategic Acquirers: Re-rating potential sits with clinical protocol specialists given CSRD disclosure mandates filtering uncredentialed competitors from premium positioning. Acquisition focus should center on Austrian and German retreat centers with existing thermal spring licenses and physician network relationships, viable over extended holding periods as regulatory barriers deepen. Watch corporate wellness procurement contract duration and renewal rates as the inflection signal for demand durability.| Strategic Initiative | Industry Significance |
|---|---|
| Medical Licensing Partnership | Swissmedic alignment secures premium-tier rate positioning and corporate procurement preference. |
| Thermal Infrastructure Retrofit | EU Green Deal compliance in Bavaria and Tyrol preserves operating licenses and access to mineral water classification. |
| Biometric Tracking Integration | Continuous glucose monitoring and circadian systems validate therapeutic outcomes for corporate HR specifications. |
| Corporate Procurement Integration | Direct contracting with pharmaceutical and banking HR departments guarantees occupancy floors and reduces acquisition costs. |
| Nutritional Therapy Protocol Extension | Subscription-based metabolic counseling captures repeat clientele from diabetes prevention and longevity medicine verticals. |
Research Methodology
Trade association filings, thermal spring classification registries, and EU regulatory databases formed the secondary backbone for market sizing and competitive mapping. Primary interviews with retreat center operations directors, corporate HR benefit administrators, thermal spa procurement managers, and physician supervision network coordinators validated facility-level capacity and pricing dynamics. Bottom-up thermal spring capacity aggregation and top-down corporate wellness spending allocation were triangulated against hospitality industry disclosure filings.
Bottom-up modeling tracked individual facility investments, certification statuses, and program expansion timelines across the projection horizon. Segmentation dimensions included service type, customer archetype, facility tier, and regional regulatory cluster. CAGRs were derived from facility pipeline analysis and corporate procurement contract growth trajectories. Forecast inputs incorporated EU Green Deal implementation schedules and EMA wellness claims substantiation evolution.
Revisions become necessary when thermal spring licensing timelines accelerate, physician training pipeline output expands materially, or corporate wellness budget allocations shift toward mental health alternatives. Deviation in CSRD enforcement intensity or national sustainability mandate implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Special Interest Tourism Market
Travel and Tourism
Incentive Travel Market
Travel and Tourism
Travel and Tourism User Generated Content Market
Travel and Tourism
Global Enotourism Market
Travel and Tourism
Indonesia Sustainable Tourism Market
Travel and Tourism
Tourism Vehicle Rental Market
Travel and Tourism
Wedding Tourism Market
Travel and Tourism
Leisure Travel Market
Travel and Tourism
Travel Retail Market
Travel and Tourism
Yacht Charter Service Market
Travel and Tourism
Canada Travel and Tourism Market
Travel and Tourism
Tourism Market
Travel and Tourism
Germany Outbound Tourism Market
Travel and Tourism
GCC Outbound Tourism Market
Travel and Tourism
Asia-Pacific MICE Tourism Market
Travel and Tourism
Asia Pacific Wellness Travel Market