
 Asia Pacific Wellness Tourism Market | 2026-2036
Asia Pacific Wellness Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Wellness Tourism Market Outlook
Digital booking platforms and AI-driven personalization is fragmenting how wellness packages are assembled and sold across the Asia Pacific. Banyan Tree Holdings anchors its competitive position through captive spa management and destination resort ownership in Thailand and Vietnam. Minor International leverages its Anantara and AVANI brand portfolio to sustain cross-border guest flows between the Middle East and Southeast Asian wellness hubs.
Asia Pacific wellness tourism encompasses travel undertaken for the purpose of maintaining or enhancing personal health through structured programs combining therapeutic treatments, fitness regimens, nutritional guidance, and stress-reduction protocols. Medical wellness programs integrate diagnostic screenings with minimally invasive interventions, while spa treatments rely on mineral-rich thermal waters and plant-derived formulations. Solo travelers now represent the fastest-expanding customer type as remote work arrangements extend leisure trip durations. Luxury resorts command the deepest margin pools within accommodation type, though eco lodges are gaining share among environmentally conscious segments seeking carbon-neutral stays.
Thailand's Ministry of Public Health regulates medical wellness facilities through licensing standards for traditional Thai massage and herbal therapy practitioners. Japan's PMDA and Ministry of Health, Labour and Welfare coordinate oversight of preventive health programs that qualify for national insurance reimbursement. Stakeholders must monitor how Australia's TGA evaluates wellness claims on therapeutic goods, as stricter evidentiary requirements would reshape product positioning across the region. The intersection of regulatory classification and consumer trust will determine which operators capture premium pricing in medical-adjacent wellness segments.
Market Dynamics
Japan's Ministry of Health, Labour and Welfare reimbursement expansion for preventive wellness programs is compressing booking cycles and forcing operators across Thailand, Vietnam, and Indonesia to recertify offerings for insurance eligibility. This regulatory pivot is reshaping competitive positioning among destination resorts and medical wellness facilities.
Growth Catalysts
- Remote work normalization:Extended leisure trip durations among digital nomads are filling shoulder-season capacity at Thai meditation retreats and Balinese eco-lodges, flattening revenue seasonality.
- PMDA reimbursement pathways:Japan's expanded preventive health coverage accelerates domestic medical wellness participation and creates template incentives for neighboring health ministries.
- Chiang Mai supply clustering:Concentrated integrated spa and meditation infrastructure in northern Thailand generates network effects that reduce customer acquisition costs for new entrants.
Market Restraints
- Traditional practitioner licensing bottlenecks:Thailand's Ministry of Public Health certification requirements for Thai massage and herbal therapy create multi-month onboarding delays for facility expansion.
- Thermal water source concentration:Geologically viable mineral spring locations cluster in specific Japanese prefectures and volcanic zones across Indonesia, constraining authentic spa replication.
- Domestic aviation cost volatility:Jet fuel price swings disproportionately impact archipelago destinations where inter-island connectivity depends on short-haul routes.
Strategic Opportunities
- Vietnam's central coast underdevelopment:Da Nang to Hoi An corridor lacks integrated medical wellness infrastructure despite rising inbound flows from South Korea and China.
- AI-driven personalization convergence:Machine learning recommendation engines hybridizing with biometric monitoring enable dynamic package assembly that captures solo traveler willingness-to-pay premiums.
- Australia's TGA evidentiary pathway:Stricter therapeutic goods evaluation creates first-mover advantage for operators investing in clinical trial documentation for wellness claims.
Industry Challenges
- Cross-border credential recognition:Japanese onsen therapists and Thai traditional medicine practitioners face non-transferable certification when seeking employment across ASEAN markets.
- Legacy property retrofit capex:Converting aging beach resorts into carbon-neutral eco-lodges requires solar microgrid and wastewater system investments that strain mid-tier operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Wellness Tourism Market |
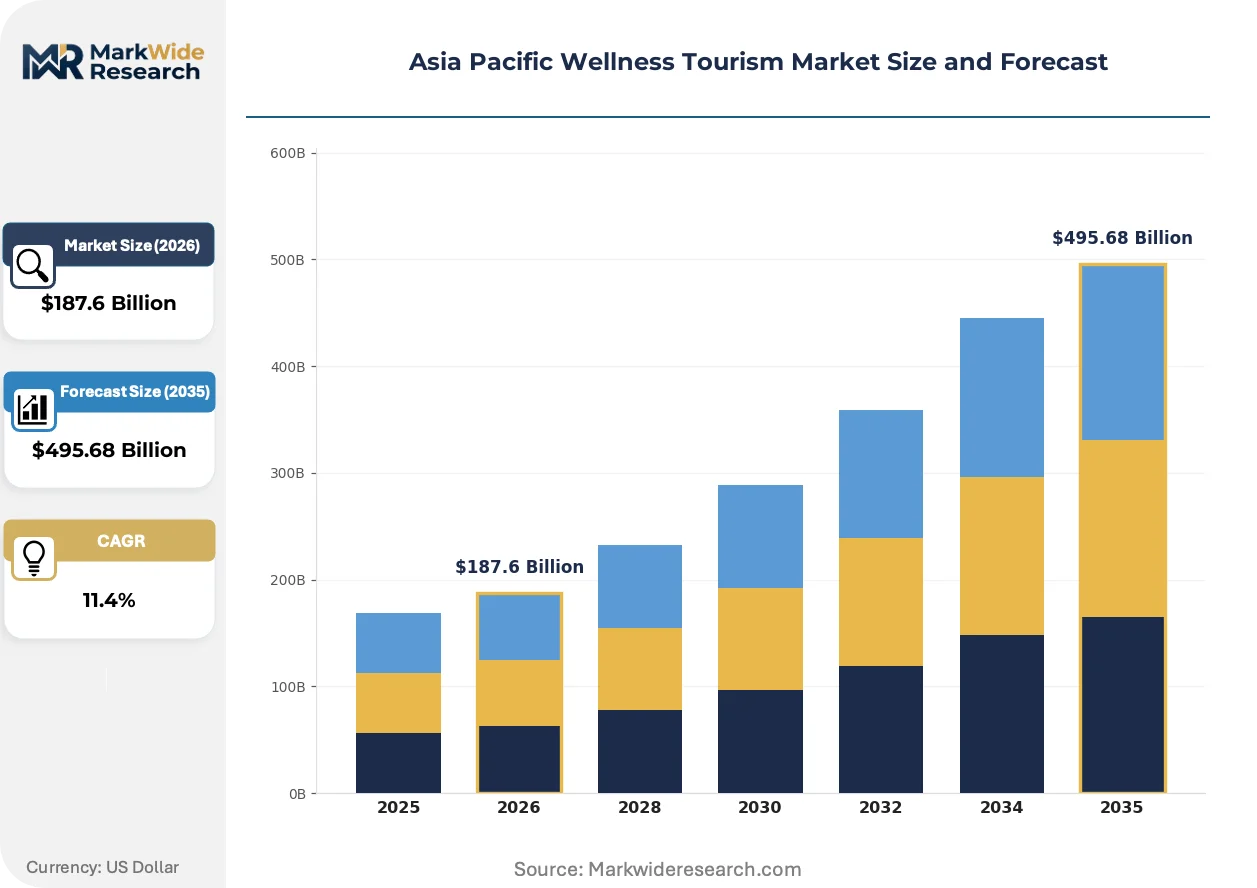
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Spa Treatments, Yoga Retreats, Detox Programs, Medical Wellness Customer Type: Corporate Groups, Families, Couples, Solo Travelers Wellness Focus: Physical Fitness, Mental Health, Nutritional Coaching, Beauty Treatments Accommodation Type: Luxury Resorts, Wellness Hotels, Eco Lodges, Retreat Centers |
| Companies Covered | Four Seasons Hotels, Hyatt Hotels Corporation, Accor, Minor International, Banyan Tree Holdings, Marriott International, InterContinental Hotels Group, Six Senses Hotels Resorts Spas, Hilton Worldwide Holdings Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Wellness Tourism Market Strategic Shifts
Digital infrastructure and regulatory reimbursement frameworks are converging to transform how wellness packages are assembled, priced, and consumed across Southeast Asian and East Asian markets. Three developments are compressing decision cycles and expanding addressable demand.
Biometric monitoring wearables are hybridizing with spa management software to enable real-time program adjustment based on guest stress markers and sleep quality data. Luxury resorts in Phuket and Bali deploy these systems to justify premium pricing tiers. The technology is compressing the gap between diagnostic assessment and therapeutic intervention, enabling same-day protocol shifts that were previously impossible.
Japan's PMDA coordination with the Ministry of Health, Labour and Welfare on preventive health reimbursement is creating template documentation standards that Thailand and Vietnam are adapting for their own insurance integration pilots. Medical wellness facilities must now maintain electronic health record interoperability to qualify for national coverage. This policy convergence most affects mid-tier operators lacking IT infrastructure to meet audit requirements.
Solo travelers now book directly through property-managed channels rather than traditional tour operators, disintermediating package assemblers that historically captured 25-40% margins. This channel shift is most visible in Chiang Mai and Ubud where remote worker communities share accommodation recommendations through private digital networks. Properties capturing these direct relationships gain guest data ownership that enables repeat booking cultivation without intermediary commission burdens.
Asia Pacific Wellness Tourism Market Segmentation
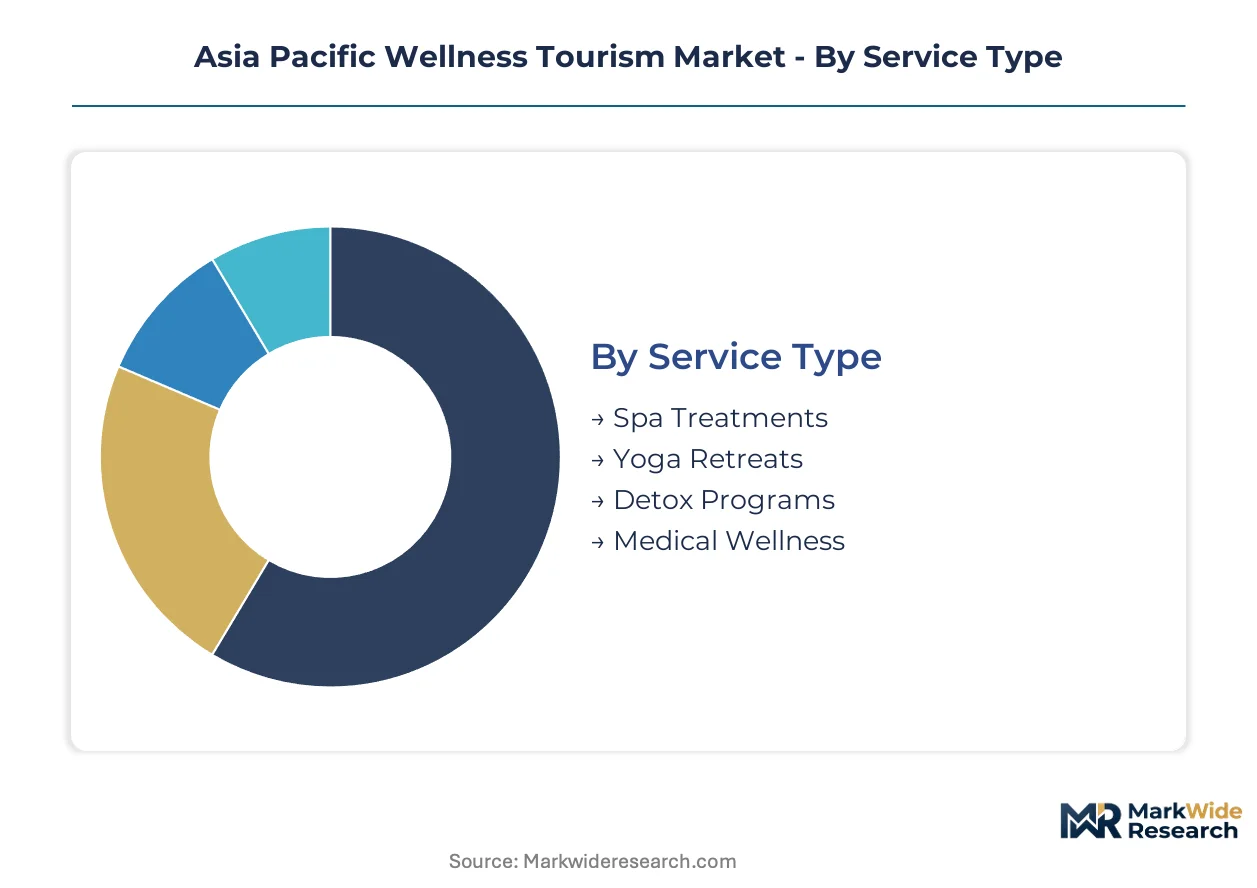
Segmentation in Asia Pacific wellness tourism reveals distinct operational models and margin structures that determine facility investment priorities. Service type and accommodation tier drive capital allocation decisions, while customer composition shapes pricing architecture and booking channel strategy.
Service Type:
Mature therapeutic modalities anchor revenue stability while emerging hybrid formats capture shifting consumer preferences.
- Spa Treatments:Mineral-rich thermal water therapies and plant-derived formulations constitute the core revenue base for Japanese onsen operators and Thai destination resorts. Demand clusters in volcanic zones across Indonesia and specific Japanese prefectures where geological constraints limit authentic replication. Thai Ministry of Public Health licensing requirements for traditional massage practitioners create multi-month onboarding bottlenecks.
- Medical Wellness:Diagnostic screenings combined with minimally invasive interventions integrate with Japan's PMDA-coordinated national insurance reimbursement pathways. Facilities must maintain electronic health record interoperability to qualify for coverage, compressing competitive advantage toward IT-capable operators. Thailand and Vietnam are adapting Japan's template documentation standards for pilot programs.
- Yoga Retreats:Structured programs in Bali and Rishikesh attract extended-stay digital nomads with flat revenue seasonality.
- Detox Programs:Nutritional protocols with medical supervision concentrate in Phuket and Koh Samui facilities.
Spa treatments handle the majority of throughput; medical wellness is expanding most quickly on share.
Customer Type:
Volume concentration varies sharply by booking channel and trip duration economics.
- Solo Travelers:Remote work normalization has produced the steepest expansion trajectory as independent professionals extend leisure trips across shoulder seasons. Direct booking through property-managed channels now dominates in Chiang Mai and Ubud, disintermediating traditional tour operators. Private digital networks within remote worker communities drive accommodation recommendations.
- Corporate Groups:Team-based wellness programming requires dedicated conference infrastructure and standardized protocols that limit customization. Procurement concentrates through incentive travel agencies with annual contract structures.
- Families:Multi-generational programming demands childcare facilities and activity tiering that raise operational complexity.
- Couples:Romantic positioning commands premium pricing in Maldives and Seychelles properties with private villa inventory.
Solo travelers handle the majority of throughput; corporate groups are climbing the fastest on share as HR wellness budgets expand.
Wellness Focus:
Application intensity differs across preventive versus corrective health positioning.
- Physical Fitness:Structured regimens combining personal training with biometric monitoring justify premium pricing tiers at Phuket and Bali luxury resorts. Real-time program adjustment based on guest stress markers compresses the diagnostic-to-intervention cycle.
- Mental Health:Meditation and stress-reduction protocols anchor Chiang Mai's integrated spa infrastructure, generating network effects that reduce customer acquisition costs for new entrants.
- Nutritional Coaching:Personalized meal planning with metabolic assessment concentrates in medical wellness facilities pursuing insurance eligibility.
- Beauty Treatments:Aesthetic services with clinical claims face Australia's TGA evidentiary requirements that reshape product positioning.
Physical fitness handles the majority of throughput; mental health is gaining share fastest among post-pandemic demand patterns.
Accommodation Type:
Margin stratification separates capital-intensive luxury development from operational-light eco-lodge conversion.
- Luxury Resorts:Captive spa management and destination resort ownership command the deepest margin pools through integrated service bundling. Banyan Tree Holdings anchors competitive position in Thailand and Vietnam through vertical control of guest experience.
- Eco Lodges:Carbon-neutral positioning gains share among environmentally conscious segments seeking verified sustainability credentials. Conversion of aging beach properties requires solar microgrid and wastewater system investments that strain mid-tier operator balance sheets.
- Wellness Hotels:Urban-located facilities with day-spa programming target domestic Japanese markets under preventive health reimbursement expansion.
- Retreat Centers:Purpose-built meditation and yoga infrastructure in Ubud and Dharamshala serves extended-stay programming.
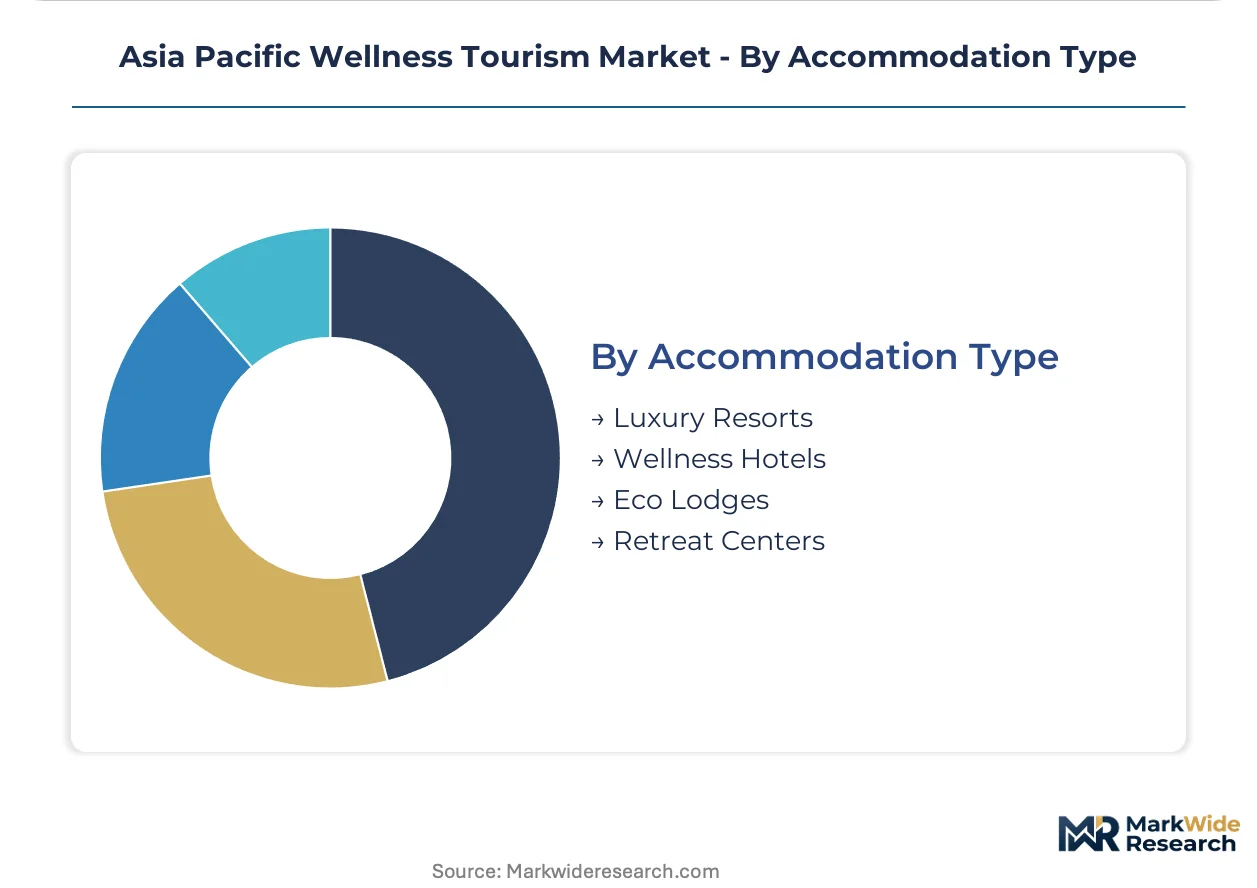
Luxury resorts handle the majority of throughput; eco lodges are climbing the fastest on share as sustainability verification matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's preventive wellness reimbursement flows create outbound demand spillover into Thai and Vietnamese facilities. Cross-border medical wellness traffic concentrates where insurance portability and flight connectivity intersect.
Japan
Domestic medical wellness participation accelerates under PMDA-coordinated national insurance expansion. METI guidelines on preventive health documentation standards create template protocols neighboring ministries adapt. Kanto region wellness hotels capture extended-stay urban professionals seeking day-spa programming under reimbursement eligibility.
Thailand
Chiang Mai's integrated spa and meditation infrastructure generates network effects that reduce customer acquisition costs for new market entrants. Ministry of Public Health licensing requirements for traditional massage and herbal therapy practitioners create multi-month facility expansion delays. Phuket luxury resorts deploy biometric monitoring systems to justify premium pricing tiers through real-time program adjustment.
Vietnam
Inbound flows from South Korea and China rise along the Da Nang to Hoi An corridor lacking integrated medical wellness infrastructure. Provincial tourism boards pilot insurance integration frameworks adapted from Japanese documentation standards. Central coast property developers target conversion opportunities in underserved wellness accommodation segments.
Indonesia
Balinese eco-lodges fill shoulder-season capacity as remote work normalization extends digital nomad trip durations. Geologically viable mineral spring locations cluster in volcanic zones, constraining authentic thermal spa replication beyond established sites. Ubud retreat centers serve extended-stay yoga programming through direct booking channels that disintermediate traditional tour operators.
Australia
TGA evidentiary requirements for therapeutic goods claims reshape wellness product positioning across medical-adjacent segments. Domestic aviation cost volatility impacts inter-regional connectivity to Queensland and Western Australia wellness destinations. New South Wales and Victoria urban wellness hotels target preventive health programming as private insurance coverage expands.
Asia Pacific Wellness Tourism Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented accommodation tiers. Luxury resort operators with captive spa management capabilities capture deepest margin pools through integrated service bundling. Three archetypes dominate: vertically integrated destination resort owners, brand-licensing hospitality groups, and independent eco-lodge operators. Competitive moves concentrate on M&A for property portfolio expansion and strategic partnerships for guest flow coordination between origin and destination markets.
Within the integrated resort tier, Banyan Tree Holdings and Minor International occupy positions that exemplify vertical control over guest experience through destination ownership and captive spa management. Hyatt Hotels Corporation and Marriott International sit within the brand-licensing archetype, leveraging global reservation systems to direct guest flows into Asia Pacific wellness properties. Four Seasons Hotels anchors the ultra-premium positioning through property-managed channels that capture direct relationships with high-value solo travelers.
| Leading Market Players |
|---|
| Four Seasons Hotels |
| Hyatt Hotels Corporation |
| Accor |
| Minor International |
| Banyan Tree Holdings |
| Marriott International |
| InterContinental Hotels Group |
| Six Senses Hotels Resorts Spas |
| Hilton Worldwide Holdings Inc |
| Others |
Value Chain & Pricing Dynamics
Japan's PMDA reimbursement documentation requirements act as a regulatory chokepoint that compresses pricing spreads between insurance-eligible medical wellness facilities and cash-pay spa operators while simultaneously forcing supply chain reconfiguration toward IT-capable vendors with electronic health record interoperability.
Pricing Analysis
Legacy thermal water therapies command premium positioning against emerging biometric-integrated wellness programs that justify dynamic pricing tiers through real-time physiological monitoring. Three-tier pricing structure across premium, standard, and economy levels separates luxury destination resorts with captive spa management from mid-tier wellness hotels and budget retreat centers. Cost compression in mid-tier accommodation is intensifying because legacy property retrofit requirements for carbon-neutral certification strain operator balance sheets. Corporate group procurement through incentive travel agencies exhibits highest price sensitivity, while solo travelers booking direct channels demonstrate lowest sensitivity due to extended-stay economics.
Supply Chain Analysis
Export-control restrictions on biometric monitoring hardware and AI-driven personalization software limit technology flows into Thai and Vietnamese facility upgrade programs. Supply concentrates in Japan for onsen thermal infrastructure, Thailand for traditional massage practitioner training pipelines, and Indonesia for volcanic zone mineral spring access. Raw material dependencies include geothermal drilling equipment, plant-derived formulation ingredients, and wearable sensor components. Single-source vulnerability runs through Japanese electronic health record system vendors that dominate PMDA-compliant documentation standards. Distribution runs through property-managed direct channels that disintermediate traditional tour operators in Chiang Mai and Ubud.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's preventive health reimbursement expansion represents a regulatory inflection that compresses competitive timelines and rewards first-movers with compliant IT infrastructure across the Asia Pacific wellness tourism disruption.
For Market Incumbents: Entrench market position through captive spa management consolidation in Thailand and Vietnam while accelerating electronic health record interoperability investments to capture PMDA-template insurance eligibility spreading across ASEAN health ministries. Defensive priority rests on backward integration into thermal water source control and practitioner training pipeline ownership to limit new entrant replication capacity. For New Entrants and Emerging Players: Vietnam's central coast corridor from Da Nang to Hoi An represents the most penetrable entry point given rising South Korean and Chinese inbound flows against absent integrated medical wellness infrastructure. Underserved mental health programming in secondary Indonesian volcanic zones offers second white-space target. Go-to-market angle should leverage direct booking channel capture through remote worker community digital networks rather than traditional tour operator relationships. For Investors and Strategic Acquirers: The market sits at a policy-convergence phase that favors vertically integrated destination resort owners with existing IT infrastructure over brand-licensing hospitality groups lacking captive spa management capabilities. Acquisition target archetype: mid-tier Thai or Vietnamese wellness hotels with retrofittable properties and unexploited thermal water access rights. Signal to watch is Australia's TGA evidentiary requirement tightening on therapeutic goods claims, which would reshape investable universe toward clinically documented operators.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Documentation Compliance Investment | Electronic health record interoperability unlocks Japan's national insurance reimbursement pathways for preventive wellness programs. |
| Biometric Monitoring Platform Integration | Real-time physiological data enables dynamic package pricing that captures solo traveler willingness-to-pay premiums. |
| Thermal Water Source Acquisition | Geologically constrained volcanic zone access creates defensible supply positions against authentic spa replication. |
| Direct Booking Channel Expansion | Property-managed reservation systems disintermediate tour operators and capture guest data for repeat cultivation. |
| Carbon-Neutral Certification Program | Verified sustainability credentials attract environmentally conscious segments seeking eco-lodge accommodation. |
Study Parameters
Desk research of regulatory filings from Japan's PMDA and Ministry of Health, Labour and Welfare, Thailand's Ministry of Public Health licensing databases, and Australia's TGA therapeutic goods registers preceded structured interviews with destination resort operations directors, traditional medicine practitioner training program administrators, health ministry policy officers, and wellness property development executives. Secondary validation drew from hospitality industry trade publications, tourism board statistics, and electronic health record vendor technical documentation. Bottom-up facility capacity estimates and top-down national tourism expenditure data were triangulated to anchor market sizing.
Assumptions held fixed across the modeling period include Japan's reimbursement expansion trajectory, remote work normalization persistence, and thermal water source geological constraints. Variables stress-tested included domestic aviation cost volatility, cross-border credential recognition harmonization pace, and TGA evidentiary requirement stringency. Segmentation dimensions modeled encompass service type, customer type, wellness focus, and accommodation tier alongside regional regulatory cluster differentiation. CAGRs were derived from facility capacity expansion pipelines and inbound flow projections across the analysis window. Forecast inputs incorporated shoulder-season occupancy flattening from extended digital nomad stays and insurance eligibility penetration rates.
Stress conditions across jet fuel price swings, traditional practitioner licensing backlog durations, and biometric hardware import restriction severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions that macroeconomic volatility or regulatory reversal could revise. Cross-checking against national tourism board arrival statistics and health ministry reimbursement claim volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Ecotel Tourism Market
Travel and Tourism
India Travel Retail Market
Travel and Tourism
Middle East and Africa Travel Retail Market
Travel and Tourism
Hong Kong Tourism Market
Travel and Tourism
Agritourism Market
Travel and Tourism
Incentive Travel Market
Travel and Tourism
Travel and Tourism User Generated Content Market
Travel and Tourism
Cycle Tourism Market
Travel and Tourism
Singapore Tourism Market
Travel and Tourism
China Travel Retail Market
Travel and Tourism
Travel Intermediaries Business Market
Travel and Tourism
Wellness Tourism Market
Travel and Tourism
New Zealand Sports Tourism Market
Travel and Tourism
USA Sports Tourism Market
Travel and Tourism
Global Duty-Free and Travel Retail Market
Travel and Tourism
North America Travel Retail Market