
 Solo Ecotourism Market | 2026-2036
Solo Ecotourism Market Size, Share, and Industry Trends Forecast 2026-2036
Solo Ecotourism Market Insights
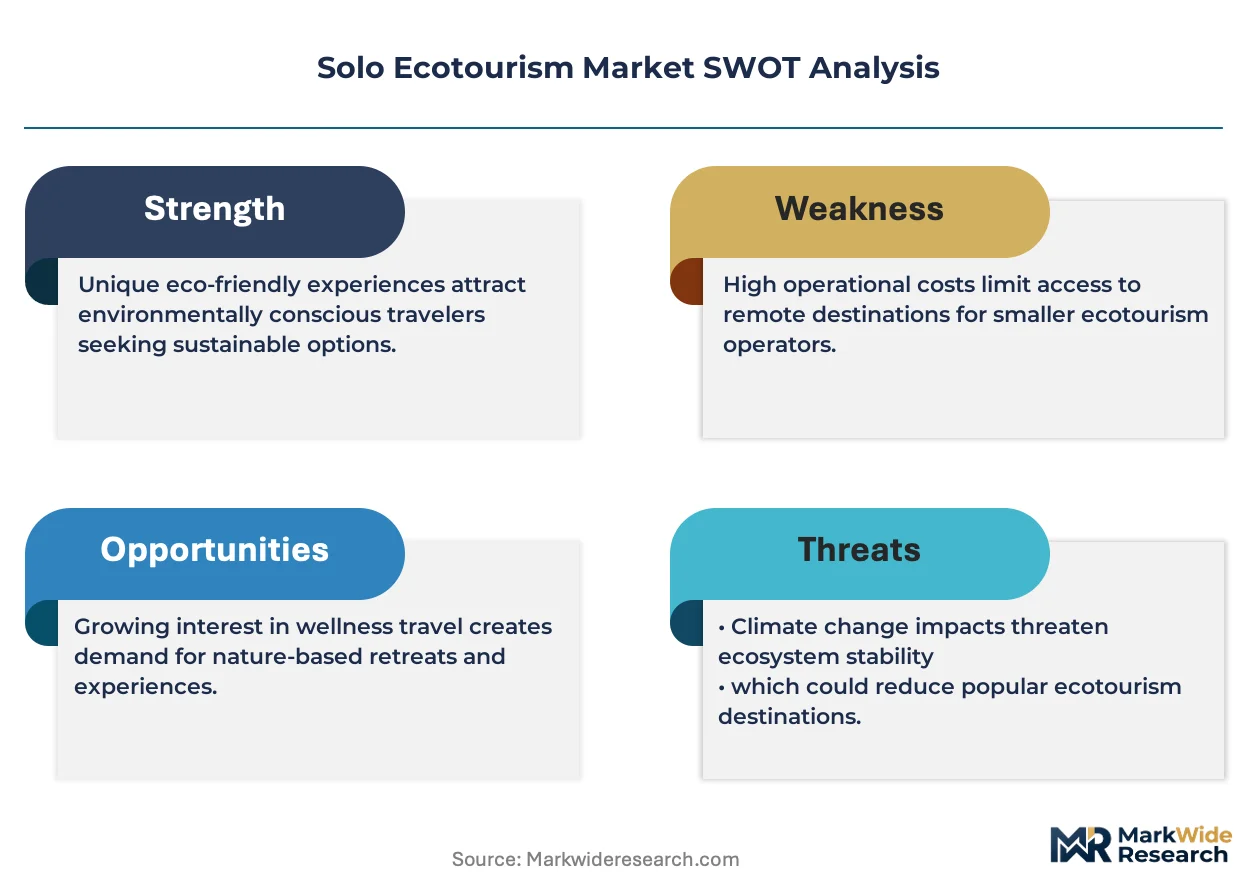
Green Globe certification is unwinding competitive barriers for smaller operators seeking entry into the solo ecotourism space. Intrepid Travel leverages its B Corp status to anchor supply chains in community-based lodging across Latin America and Southeast Asia. G Adventures competes through its Jane Goodall Collection, which specializes in small-group wildlife itineraries that accommodate solo travelers without single supplements. Booking Holdings controls distribution reach through platform algorithms that now surface eco-filtered inventory to solo search profiles.
Solo ecotourism encompasses independent travel experiences designed around environmental conservation principles, low-impact logistics, and immersive engagement with protected ecosystems, typically involving carbon-offset transportation, locally sourced provisioning, and carrying-capacity limits at destination sites. Its primary commercial purpose channels discretionary spending from environmentally motivated individuals into revenue streams that fund habitat preservation and indigenous livelihoods. Adventure travel and wildlife tours represent the leading activity categories by booking volume, while sustainable retreats capture expanding margin pools as wellness-oriented solo travelers extend average trip duration. Nature lodges and local experiences within the service offering dimension are attracting the fastest capacity additions, particularly in regions where community land tenure supports exclusive-use conservation concessions.
The EU Green Deal and its linked CSRD disclosure requirements shape operator investment in verified carbon accounting across European itineraries. Costa Rica's national tourism board enforces the CST certification system, while New Zealand's Tourism Industry Aotearoa administers the Tiaki Promise framework; both standards directly influence product design for solo market entrants. Stakeholders must monitor how emerging biodiversity credit mechanisms and evolving national park access quotas reshape route economics and capacity allocation decisions.
Market Dynamics
Carbon-accounting mandates embedded in the EU Green Deal and Costa Rica's CST certification system are forcing operators to restructure itinerary design and supplier qualification protocols. These disclosure frameworks now determine which solo travel products qualify for platform distribution.
Growth Catalysts
- EU Green Deal carbon disclosure rules:Operators investing in verified offset programs gain preferential placement on major booking platforms, accelerating certified product development.
- Community land tenure systems:Indigenous conservation concessions in Latin America and Southeast Asia enable exclusive-use wildlife corridors that solo travelers pay premium rates to access.
- Millennial booking concentration:This demographic segment now dominates guided wildlife tour reservations, driving capacity expansion in small-group formats without single supplements.
Market Restraints
- Aviation fuel cost volatility:Long-haul flight emissions dominate carbon footprints for Nordic and Asia-Pacific itineraries, compressing margins on distance-intensive products.
- Lodge supply concentration:Eco-certified accommodation in Sweden, Norway, and Finland operates at 85%+ annual occupancy, creating booking bottlenecks during peak migration and aurora seasons.
- Biodiversity credit verification delays:Emerging habitat offset mechanisms lack standardized accounting protocols, freezing operator investment in conservation-linked pricing models.
Strategic Opportunities
- New Zealand's Tiaki Promise framework:This visitor stewardship mandate creates first-mover advantage for operators integrating Maori-led cultural immersion into solo retreat formats.
- Domestic rail network revival:Sleeper train corridors across Central Europe and Scandinavia enable multi-destination low-carbon itineraries previously impossible for independent travelers.
- Remote work visa programs:Extended-stay permits in Portugal, Estonia, and Costa Rica allow month-long sustainable retreat bookings that double average revenue per solo guest.
Industry Challenges
- Wilderness guide certification backlogs:Interpretive naturalist training programs in Costa Rica and Kenya operate at 40% of required throughput, constraining small-group capacity expansion.
- Legacy booking system integration:Community-based lodges in Southeast Asia rely on manual reservation workflows that fragment inventory visibility across distribution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solo Ecotourism Market |
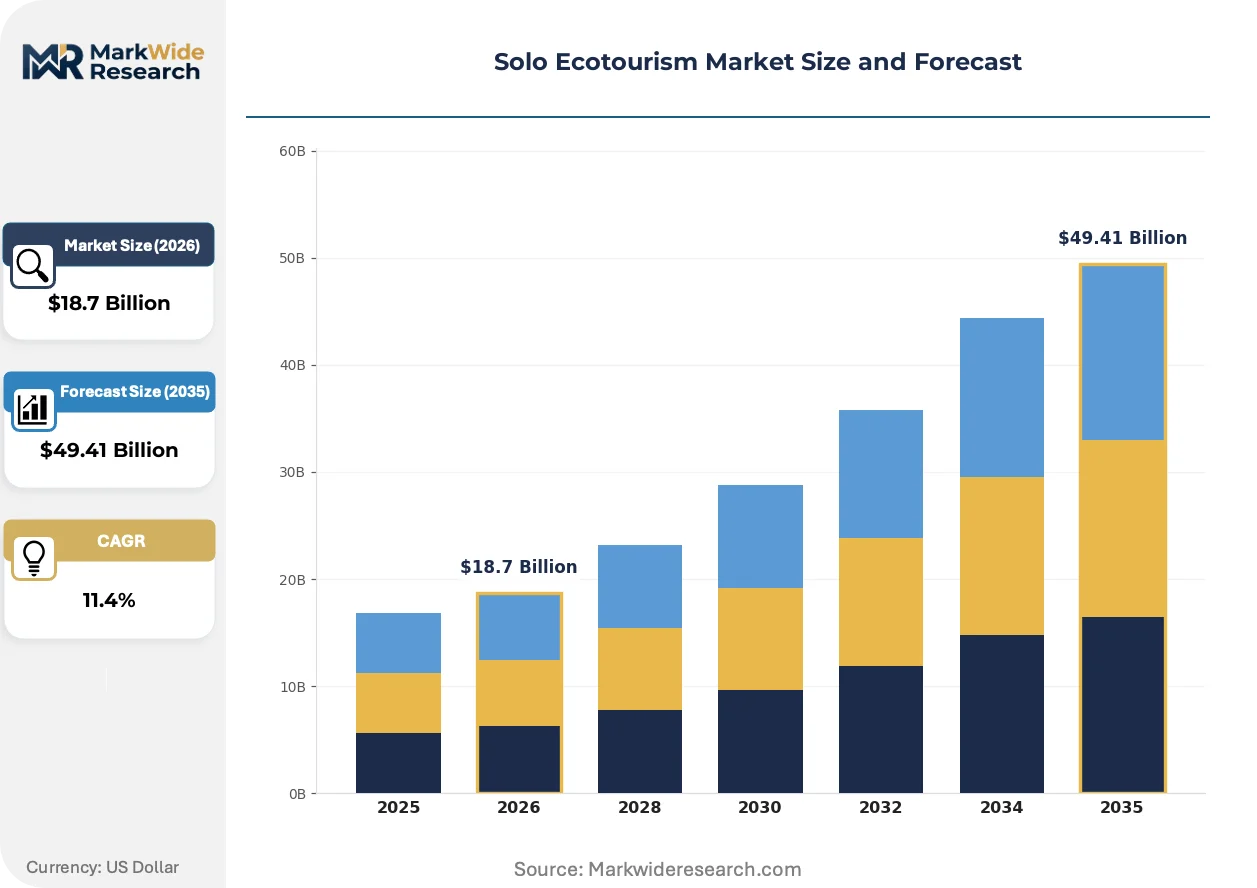
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Travel Type: Adventure Travel, Cultural Exploration, Wildlife Tours, Sustainable Retreats Service Offering: Guided Tours, Nature Lodges, Eco-Friendly Transportation, Local Experiences Activity Level: Low Intensity, Moderate Intensity, High Intensity, Customized Adventures Customer Segment: Millennials, Nature Enthusiasts, Solo Travelers, Eco-Conscious Consumers |
| Companies Covered | Intrepid Travel, G Adventures, Natural Habitat Adventures, Frosch, Travel Leaders Group, AndBeyond, Expedia Group, Booking Holdings, National Geographic Expeditions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solo Ecotourism Market Trends and Innovations
Digitization of conservation impact tracking and the proliferation of hybrid remote-work travel formats are restructuring how solo travelers evaluate and book low-impact experiences. These shifts favor operators with transparent supply chains and extended-stay infrastructure.
Blockchain-verified carbon offset registries is bifurcating the operator base. Premium solo travelers now demand immutable proof of emissions neutrality before confirming bookings. Smaller operators lacking technical capacity to integrate these verification layers are losing platform visibility. The technology is compressing market share into certified networks while marginalizing uncertified competitors.
Costa Rica's CST certification system and New Zealand's Tiaki Promise are mandating community-benefit ratios in supplier contracts. Operators must now document direct revenue flows to indigenous landholders and local provisioning networks. Wildlife tour segments in these jurisdictions are responding by restructuring commission splits and lengthening supplier payment terms.
Extended-stay booking patterns among remote-employed solo travelers are displacing traditional week-long retreat formats. Month-long nature lodge reservations now represent the fastest-growing booking category in Portugal, Estonia, and Costa Rica. This behavioral shift concentrates demand in properties with dedicated workspace infrastructure and reliable connectivity.
Solo Ecotourism Market Segmentation
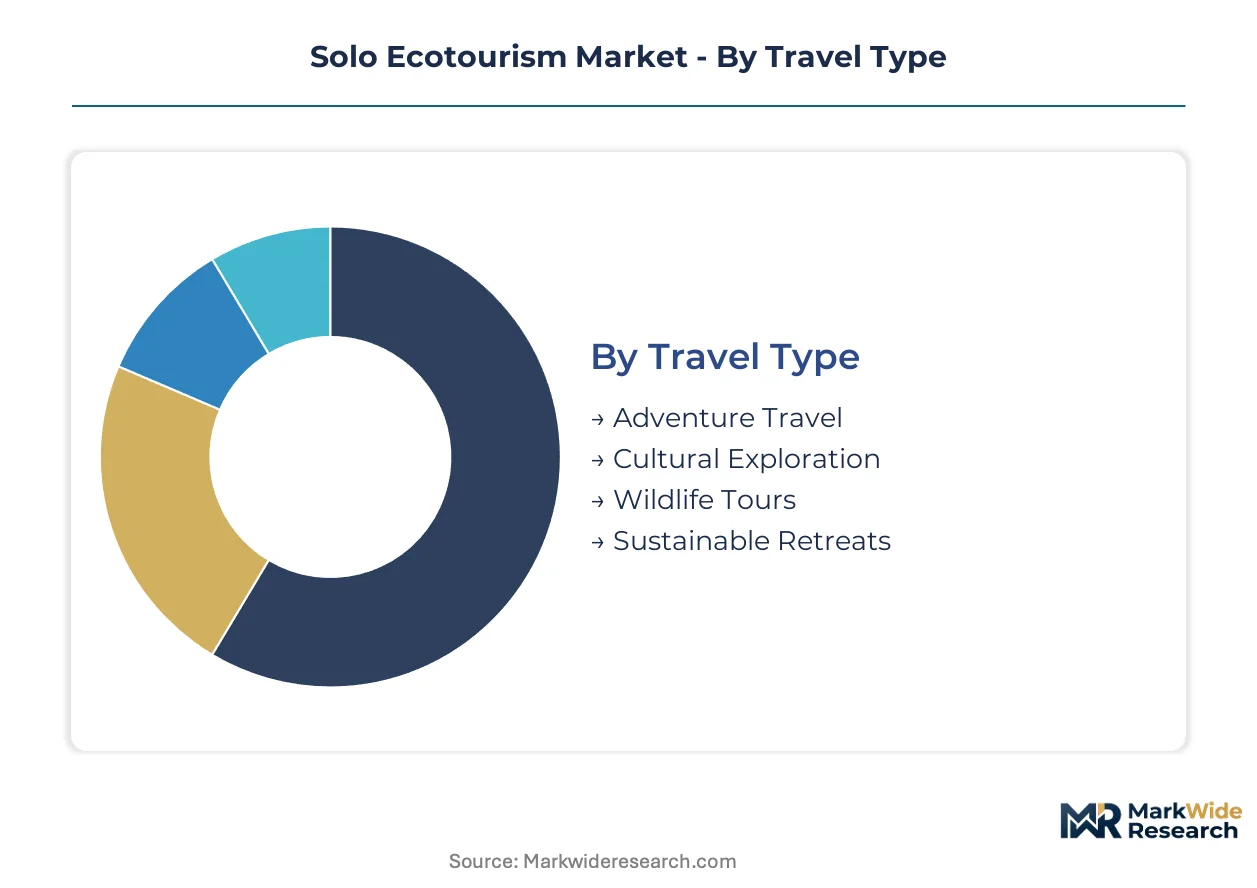
Segmentation in solo ecotourism reveals how traveler motivations translate into distinct booking channels and margin structures. Each dimension—travel purpose, service format, physical demand, and psychographic profile—creates separate pathways for platform distribution and direct operator relationships.
Travel Type:
Channel mix varies sharply by travel purpose, with adventure and wildlife products flowing through specialized platforms while sustainable retreats increasingly convert through direct booking engines.
- Adventure Travel:Multi-day trekking, mountaineering, and water-based expeditions requiring technical equipment and certified guides. Demand concentrates in New Zealand's South Island and Costa Rica's cloud forest corridors, driven by EU Green Deal carbon disclosure requirements that favor verified low-impact logistics.
- Wildlife Tours:Small-group or independent itineraries centered on protected area access and interpretive naturalist guidance. Kenya's Maasai Mara and Costa Rica's Osa Peninsula anchor bookings, constrained by wilderness guide certification backlogs that limit capacity expansion.
- Cultural Exploration:Immersive engagement with indigenous communities and heritage sites. New Zealand's Maori-led experiences under the Tiaki Promise framework are gaining platform visibility.
- Sustainable Retreats:Extended-stay wellness programming at eco-certified properties. Month-long bookings in Portugal and Estonia are climbing the fastest as remote work visa programs mature.
Adventure Travel dominates installed base. Sustainable Retreats is where expansion concentrates.
Service Offering:
Margin profiles diverge by service format, with accommodation and transportation capturing fixed infrastructure returns while experiences and tours generate variable commission income.
- Nature Lodges:Eco-certified properties with carrying-capacity limits and local provisioning mandates. Sweden, Norway, and Finland operate at sustained high occupancy, creating booking bottlenecks during peak seasons.
- Guided Tours:Structured small-group or private itineraries with interpretive components. Latin American community-based concessions are expanding most quickly as indigenous land tenure systems enable exclusive-use wildlife corridors.
- Local Experiences:Short-duration activities hosted by community cooperatives or individual providers. Southeast Asian markets face inventory fragmentation due to manual reservation workflows.
- Eco-Friendly Transportation:Carbon-offset flights, electric ground transfers, and revived sleeper rail corridors. Central European and Scandinavian rail networks are opening multi-destination low-carbon routing previously unavailable to independent travelers.
Nature Lodges capture the highest margin per booking night. Guided Tours show the steepest expansion trajectory as millennial demand for structured wildlife access accelerates.
Activity Level:
Physical demand tiers align with distinct customer acquisition costs and repeat booking rates, shaping how operators structure membership and loyalty programming.
- Moderate Intensity:Day-hiking, kayaking, and snorkeling accessible to broad fitness ranges. This tier converts at highest volume through platform algorithms targeting solo traveler profiles.
- High Intensity:Technical climbing, multi-day trekking, and remote wilderness expeditions requiring pre-trip conditioning. New Zealand's Department of Conservation permitting systems constrain route capacity.
- Low Intensity:Wildlife observation, botanical walks, and wellness programming with minimal physical exertion. Costa Rica's CST-certified lodges specialize in this tier for extended-stay guests.
- Customized Adventures:Bespoke itineraries combining multiple intensity levels across a single journey. Premium pricing applies where Maori cultural immersion or exclusive conservation concessions are integrated.
Moderate Intensity holds the largest addressable base. Customized Adventures is where premium rate expansion concentrates.
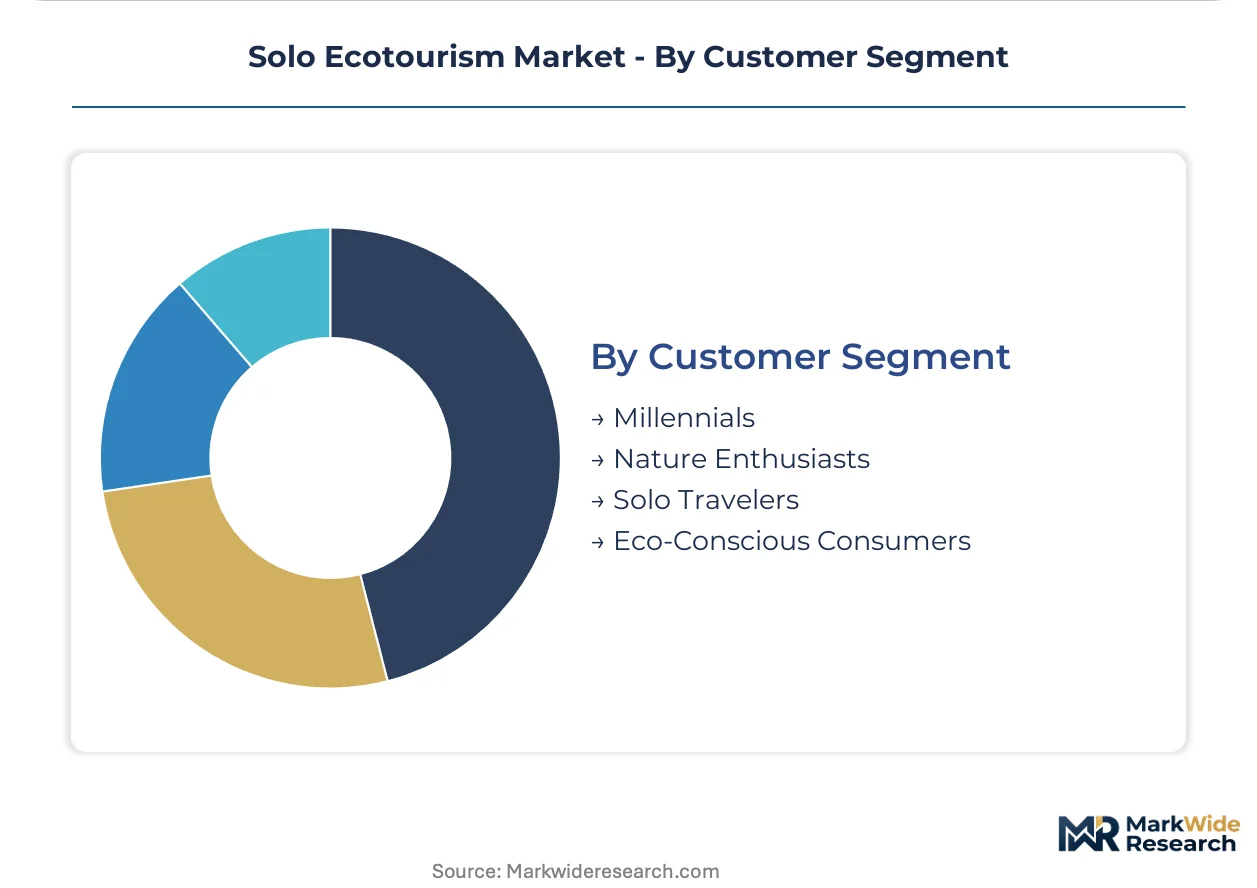
Customer Segment:
Psychographic targeting determines platform spend allocation, with millennials and remote workers commanding distinct creative and channel strategies.
- Millennials:Ages 25-40 with demonstrated willingness to pay verified carbon premiums. This cohort dominates guided wildlife tour reservations and drives small-group format development without single supplements.
- Eco-Conscious Consumers:Travelers prioritizing environmental impact transparency over cost minimization. Blockchain-verified offset registries are becoming a non-negotiable filter for this segment's booking decisions.
- Solo Travelers:Individuals booking independent itineraries without companion coordination requirements. Extended-stay permits in Estonia and Costa Rica are converting this segment to month-long retreat formats.
- Nature Enthusiasts:Repeat visitors with deep expertise in specific ecosystems or species. Kenya and Costa Rica retain this segment through specialist guide networks and conservation concession access.
Millennials dominate current booking volume. Eco-Conscious Consumers is where rate premium expansion concentrates as verification technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Costa Rica's CST certification system and New Zealand's Tiaki Promise framework are reshaping operator compliance requirements across destination markets. The EU Green Deal carbon disclosure rules now determine platform distribution eligibility for European itineraries. These regulatory layers are concentrating investment in verified low-carbon logistics and community-benefit supplier contracts.
Costa Rica
Guided wildlife tours and cloud forest trekking anchor demand from millennial solo travelers seeking verified carbon-neutral experiences. The national tourism board enforces CST certification tiers that mandate direct revenue flows to indigenous landholders. Osa Peninsula eco-lodges operate at sustained high occupancy during dry season migration windows.
New Zealand
Small-group adventure itineraries and Maori-led cultural immersion programs attract extended-stay remote workers. The Department of Conservation permitting system constrains route capacity for technical trekking and backcountry expeditions. South Island nature lodges around Queenstown and Fiordland are expanding workspace infrastructure for month-long bookings.
Sweden
Low-impact aurora tourism and Arctic wildlife observation drive winter demand from eco-conscious European solo travelers. The country's national environmental protection agency enforces carrying-capacity limits at Sarek and Padjelanta national parks. Swedish Lapland eco-lodges along the King's Trail corridor report 85%+ annual occupancy with peak-season booking bottlenecks.
Norway
Sleeper rail corridors and electric fjord ferry networks enable multi-destination low-carbon routing previously unavailable to independent travelers. The Norwegian Environment Agency mandates emissions reporting for commercial operators accessing protected areas. Lofoten Islands nature lodges are expanding capacity to capture growing solo traveler volume during midnight sun season.
Finland
Nordic walking trails and lakeland wellness retreats capture extending average trip duration among remote-employed solo travelers. Metsähallitus administers wilderness guide licensing that constrains small-group capacity expansion in national park buffer zones. Finnish Lakeland eco-certified properties around Kuopio and Savonlinna are adding dedicated workspace pods for month-long retreat formats.
Solo Ecotourism Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and distribution reach. Platform operators with algorithmic inventory surfacing command booking flow concentration, while boutique operators with direct community concession relationships capture margin premiums. Three archetypes dominate: B Corp-certified experience designers, platform-scale distributors with eco-filtering capabilities, and conservation-concession specialists with exclusive land access. Competitive moves center on verified carbon accounting integration and extended-stay infrastructure deployment.
Within the B Corp-certified tier, Intrepid Travel and G Adventures exemplify community-based supply chain anchoring. Among platform-scale distributors, Booking Holdings occupies a position where algorithmic eco-filtering determines product visibility. These three companies represent distinct strategic positions: Intrepid Travel exemplifies Latin American and Southeast Asian community lodging integration, G Adventures anchors wildlife itinerary specialization through conservation partnerships, and Booking Holdings sits within the distribution layer where disclosure compliance gates platform access.
| Leading Market Players |
|---|
| Intrepid Travel |
| G Adventures |
| Natural Habitat Adventures |
| Frosch |
| Travel Leaders Group |
| AndBeyond |
| Expedia Group |
| Booking Holdings |
| National Geographic Expeditions |
| Others |
Pricing and Supply Chain Analysis
Costa Rica's CST certification system and New Zealand's Tiaki Promise framework simultaneously gate supplier qualification and enable price premiums for verified community-benefit ratios. These dual-function regulatory layers concentrate pricing power with operators who document direct revenue flows to indigenous landholders, while uncertified competitors face margin compression from platform algorithmic deprioritization.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers across solo ecotourism inventory. Three-tier pricing structure across premium, standard, and economy levels reflects verified carbon accounting depth, with blockchain-verified offset registries commanding the highest rates. Cost compression in the standard tier is intensifying because aviation fuel volatility erodes margins on long-haul Nordic and Asia-Pacific itineraries. Eco-conscious consumers show the least price sensitivity, while budget-oriented independent travelers exhibit the highest elasticity.
Supply Chain Analysis
Sweden, Norway, and Finland anchor eco-certified nature lodge supply, with Costa Rica and New Zealand anchoring community-based concession networks. Raw material inputs draw from indigenous provisioning networks, renewable energy microgrids, and carbon-offset aviation fuel pools. Single-source vulnerability concentrates in wilderness guide certification programs operating at 40% of required throughput in Costa Rica and Kenya. Distribution runs through platform algorithms that surface eco-filtered inventory to solo traveler search profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solo ecotourism market fragmentation creates entry niches as millennial demand for verified carbon-neutral experiences splinters across certification tiers and regional specialization. Remote work visa programs and extended-stay booking patterns further subdivide addressable segments.
For Market Incumbents: Secure exclusive-use conservation concessions in Latin American indigenous land tenure systems before community benefit ratio mandates tighten. Invest in blockchain-verified carbon accounting infrastructure to defend platform visibility against emerging B Corp-certified competitors. Vertical integration into workspace-equipped nature lodge networks captures month-long booking growth in Portugal and Estonia.
For New Entrants and Emerging Players: Anchor in Southeast Asian local experience segments where manual reservation workflows fragment incumbent inventory visibility. Target domestic rail corridor revival across Central Europe and Scandinavia for multi-destination low-carbon itinerary design. Partner with sleeper train operators for exclusive cabin blocks marketed to solo remote workers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across extended-stay retreat infrastructure as workspace pod installation and connectivity upgrades become table stakes. Five-to-ten-year viability favors operators with direct community concession relationships bypassing platform commission structures. Monitor biodiversity credit verification protocol finalization as the inflection signal for conservation-linked pricing model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Community Concession Partnership | Direct revenue flow documentation to indigenous landholders satisfies Tiaki Promise and CST mandates. |
| Blockchain Carbon Registry Integration | Immutable offset verification unlocks premium tier pricing for eco-conscious consumer segments. |
| Workspace Infrastructure Deployment | Dedicated connectivity pods at Finnish Lakeland properties capture month-long remote worker bookings. |
| Rail Corridor Exclusive Access | Sleeper train cabin blocks enable multi-destination low-carbon itineraries previously unavailable to independents. |
| Wilderness Guide Certification Pipeline | Interpretive naturalist training expansion alleviates capacity constraints in Costa Rica and Kenya. |
Research Methodology
Cross-validation between operator sustainability disclosures and platform algorithmic filtering data anchors the qualitative findings. Primary interviews with ecotourism product managers, indigenous community concession coordinators, booking platform category directors, and carbon accounting verification specialists combined with secondary validation from EU Green Deal implementation reports, CST certification registries, and national tourism board statistics. Bottom-up booking volume analysis and top-down market sizing triangulate segment-level estimates.
Sensitivity analysis tested forecast robustness across aviation fuel price scenarios, biodiversity credit protocol adoption timelines, and remote work visa program expansion rates. Segmentation modeling incorporated travel purpose, service format, activity intensity, and psychographic profile dimensions alongside certification tier and regional regulatory cluster. CAGRs derived from historical booking growth patterns adjusted for policy inflection points and platform algorithm update cycles. Extended-stay permit availability and rail infrastructure investment schedules fed corridor-specific trajectory assumptions.
Material uncertainties — biodiversity credit accounting standardization delays, wilderness guide certification throughput constraints, and aviation carbon tax implementation schedules — sit outside the modeled envelope. Forecasts reflect documented assumptions about platform algorithmic weighting evolution and community land tenure system stability. Recalibration cycles align with material shifts in EU Green Deal disclosure requirements and national carbon-neutral tourism mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Travel and Tourism User Generated Content Market
Travel and Tourism
South Africa Sports Tourism Market
Travel and Tourism
USA Sustainable Tourism Market
Travel and Tourism
MICE Travel Service Market
Travel and Tourism
Asia-Pacific Tourism Market
Travel and Tourism
Global Enotourism Market
Travel and Tourism
Yacht Charter Market
Travel and Tourism
Airline Retailing Market
Travel and Tourism
China Travel Retail Market
Travel and Tourism
Europe Wellness Tourism Market
Travel and Tourism
Cycle Tourism Market
Travel and Tourism
Europe Driving Vacation Market
Travel and Tourism
Yacht Charter Service Market
Travel and Tourism
India Sports Tourism Market
Travel and Tourism
France Outbound Tourism Market
Travel and Tourism
Bleisure Tourism Market