
 Canada Travel and Tourism Market | 2026-2036
Canada Travel and Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Travel and Tourism Market Insights
The Canadian government's National Tourism Strategy is recalibrating the cost-of-entry calculus for new operators by tying federal infrastructure grants to sustainability certifications and Indigenous partnership requirements. Air Canada leverages its dominant slot portfolio at Toronto Pearson, Vancouver International, and Montreal-Trudeau to sustain transcontinental and transborder route density that few rivals can replicate. WestJet Airlines Ltd anchors its competitive stance through Calgary International hub operations and a leisure-focused fare structure that competes aggressively on sun-destination pricing. Marriott International differentiates through its Bonvoy loyalty ecosystem, which controls repeat booking flows across its Canadian property footprint spanning full-service urban towers to select-service airport properties.
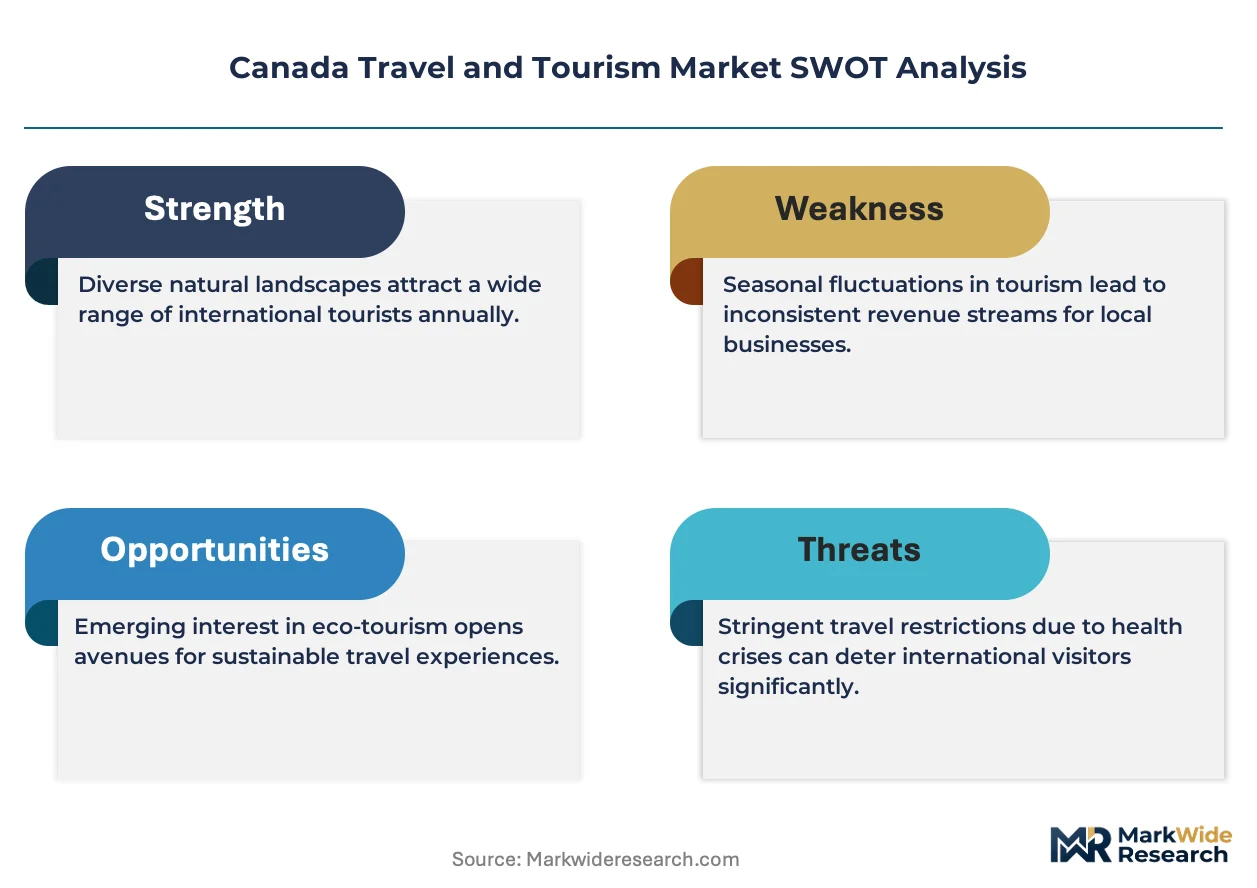
Canada travel and tourism encompasses the organized provision of passenger transportation, temporary accommodation, food and beverage services, recreation, and destination management activities designed to facilitate leisure, business, and cultural visitation across Canadian territory. The sector operates through seasonally variable infrastructure including alpine ski lifts operating at elevations exceeding 2,000 meters, marine ferry networks crossing the Salish Sea and Gulf of St. Lawrence, and remote lodge facilities dependent on bush plane or seasonal ice road access. Domestic travelers constitute the structural backbone of revenue stability, insulating operators from currency-driven international demand volatility, while eco-tourism services capture expanding margin pools as travelers pay premiums for carbon-neutral itineraries and wildlife-certified guiding operations. Winter sports seasonality concentrates capital returns in compressed three-month windows, forcing operators toward dual-season programming to improve asset utilization across summer hiking and mountain biking activations.
Health Canada and the Public Health Agency of Canada shape operator protocols through infectious disease preparedness mandates that affect cruise terminal operations and large-event venue capacities, while Transport Canada governs aviation safety standards and marine passenger vessel certifications that determine fleet eligibility and route licensing. Parks Canada regulates backcountry access permits, visitor carrying capacities, and ecological integrity requirements across the national park estate, directly constraining supply expansion in signature destinations like Banff, Jasper, and Pacific Rim. Stakeholders must monitor how federal carbon pricing trajectories and emerging clean fuel regulations will restructure operating costs for aviation-dependent remote lodges and interprovincial motorcoach networks.
Market Dynamics
Canada's National Tourism Strategy is restructuring operator economics by mandating sustainability certifications and Indigenous partnership frameworks as preconditions for federal infrastructure grants, forcing capital reallocation across accommodation, transport, and destination management segments.
Growth Catalysts
- Indigenous Tourism Partnership Framework:Federal funding tied to Indigenous co-management agreements is unlocking new protected-area access permits in British Columbia and Alberta, expanding supply-constrained backcountry inventory.
- Business Travel Recovery:Cross-border corporate booking volumes from US metropolitan corridors are rebounding, filling mid-week capacity gaps in Toronto and Vancouver urban hotel portfolios.
- Dual-Season Asset Programming:Ski resort operators are repurposing winter lift infrastructure for summer mountain biking and alpine hiking, compressing fixed-cost recovery windows and improving return on capital employed.
Market Restraints
- Aviation Carbon Cost Trajectory:Federal clean fuel regulations and carbon pricing mechanisms are elevating operating costs for remote lodge operators dependent on bush plane access and interprovincial motorcoach networks.
- Parks Canada Carrying Capacity Limits:Visitor permit caps and ecological integrity requirements in Banff, Jasper, and Pacific Rim national parks constrain supply expansion in signature destination corridors.
- Seasonal Labor Volatility:Three-month winter sports concentration creates recruitment and retention friction for specialized alpine operations and backcountry guiding services.
Strategic Opportunities
- Atlantic Canada Marine Tourism:Ferry network modernization and coastal trail development in Nova Scotia and Newfoundland present underpenetrated inventory expansion outside western mountain corridors.
- Carbon-Neutral Itinerary Certification:Eco-tourism operators can capture margin premiums through wildlife-certified guiding operations and carbon-offset packaging that differentiates against conventional mass-market offerings.
- Digital Distribution Platform Convergence:Integration of dynamic packaging engines with loyalty ecosystem APIs is enabling direct-to-consumer booking bypass of traditional wholesale intermediaries.
Industry Challenges
- Wilderness First Responder Certification Bottlenecks:Backcountry operators face extended recruitment timelines and elevated wage pressure due to scarce certified guiding talent pools.
- Legacy Reservation System Migration:Independent lodge properties struggle with integration complexity when replacing on-premise property management systems with cloud-native distribution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Travel and Tourism Market |
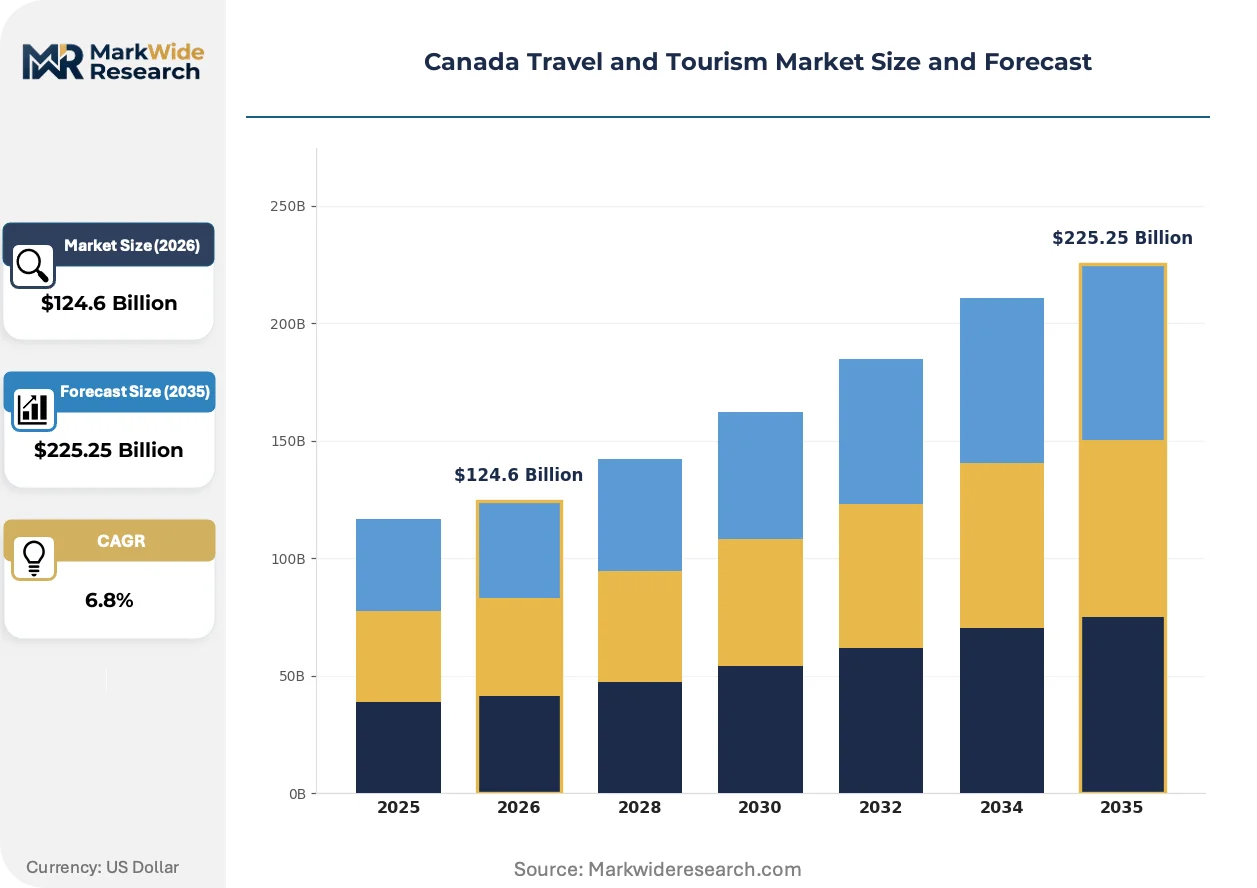
| Market Size in 2026 | $124.6 Billion |
| Market Size in 2035 | $225.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Domestic Travelers, International Tourists, Business Travelers, Adventure Seekers Service Type: Guided Tours, Eco-Tourism, Luxury Accommodation, Transportation Services Activity Type: Sightseeing, Outdoor Activities, Cultural Experiences, Culinary Tours Seasonality: Summer Travel, Winter Sports, Holiday Season, Off-Peak Travel |
| Companies Covered | Air Canada, WestJet Airlines Ltd, Expedia Group, Marriott International, Accor SA, BC Ferries, Whistler Blackcomb, Hilton, Checkfront, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Travel and Tourism Market Trends and Innovations
Technology deployment and regulatory stringency are converging to reshape visitor flow management, carbon accountability, and booking channel economics across Canadian destination operators.
Biometric passenger processing systems are automating identity verification and boarding authorization at Toronto Pearson and Vancouver International terminals. Air Canada and WestJet are deploying facial recognition corridors to compress connection times and reduce ground staffing requirements. This infrastructure investment is automating throughput capacity expansion without proportional terminal footprint growth.
Health Canada infectious disease preparedness mandates are reshaping cruise terminal operations and large-event venue capacity protocols. Transport Canada marine passenger vessel certification requirements are elevating fleet eligibility standards for operators in the Gulf of St. Lawrence and Salish Sea corridors. British Columbia coastal operators are responding with enhanced ventilation retrofits and flexible ticketing architectures that accommodate rapid capacity modulation.
Corporate travel managers are consolidating booking volume through managed travel programs with sustainability reporting requirements. Traditional leisure wholesale channels are losing share to direct operator platforms and loyalty ecosystem redemption flows. This concentration is most visible in Toronto and Calgary corporate corridors where procurement teams prioritize carbon disclosure alignment over lowest-fare selection.
Canada Travel and Tourism Market Segmentation
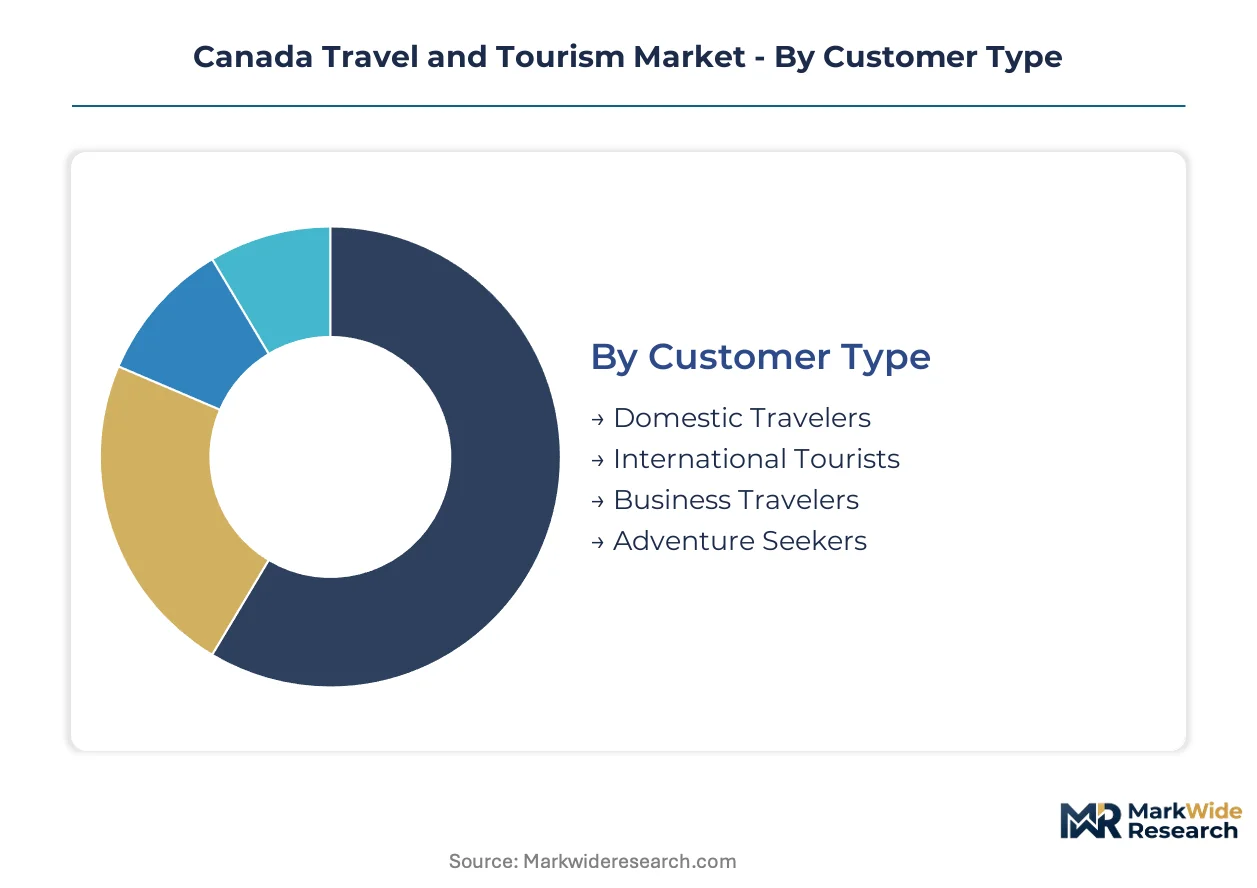
Segmentation in Canadian travel and tourism reveals how capital deployment, regulatory exposure, and seasonality risk concentrate differently across visitor profiles and service models. Operators must align infrastructure investment with segment-specific demand patterns to optimize asset utilization across compressed seasonal windows.
Customer Type:
Capital intensity varies sharply across visitor categories, with infrastructure requirements scaling from urban hotel portfolios to remote backcountry access systems.
- Domestic Travelers:Canadians generate recurring revenue through vehicle-based regional trips and short-haul air corridors. Demand concentrates in Ontario and Quebec urban centers, where weekend getaway patterns stabilize occupancy outside peak international windows.
- International Tourists:Overseas visitors require multilingual service infrastructure, customs processing capacity, and intermodal transfer systems at gateway airports. British Columbia and Alberta mountain destinations capture the bulk of long-haul spend due to protected-area access and ski infrastructure density.
- Business Travelers:Corporate booking flows prioritize mid-week urban capacity in Toronto and Vancouver financial districts.
- Adventure Seekers:Specialized guiding certifications and remote access logistics elevate operating costs for backcountry operators.
Domestic Travelers absorb the bulk of installed capacity; International Tourists are expanding most quickly as visa processing improvements and air route recovery accelerate inbound volumes.
Service Type:
Margin structures diverge based on certification requirements and exclusivity positioning, with sustainability credentials commanding premium pricing.
- Guided Tours:Itinerary packaging and interpreter staffing create scalable service models. Demand concentrates in cultural corridor destinations where Indigenous partnership frameworks unlock protected-area access permits.
- Eco-Tourism:Carbon-neutral certification and wildlife stewardship credentials require third-party auditing and offset procurement. British Columbia coastal operators capture margin premiums through bear-viewing and marine mammal protocols that differentiate against conventional mass-market offerings.
- Luxury Accommodation:Full-service urban towers and remote lodge properties compete on loyalty ecosystem integration and exclusive access arrangements.
- Transportation Services:Interprovincial motorcoach networks and marine ferry systems face carbon cost pressure from federal clean fuel regulations.
Guided Tours generate the highest transaction velocity; Eco-Tourism shows the steepest expansion trajectory as sustainability disclosure requirements reshape procurement priorities.
Activity Type:
Fixed asset requirements range from interpretive center investments to lift infrastructure and trail network maintenance.
- Sightseeing:Urban observation infrastructure and scenic corridor coach routes require moderate capital outlay with high turnover potential. Niagara Falls and Rocky Mountain corridor operators benefit from established demand flows and predictable seasonal patterns.
- Outdoor Activities:Ski lift systems, mountain bike trail networks, and marine vessel fleets demand substantial upfront investment with compressed revenue windows. Alberta and British Columbia operators are repurposing winter infrastructure for summer programming to improve capital recovery.
- Cultural Experiences:Museum partnerships and heritage site access depend on Parks Canada permit allocations and Indigenous co-management agreements.
- Culinary Tours:Agritourism integration and supply chain logistics create regional specialization around Okanagan wine corridors and Maritime seafood routes.
Outdoor Activities lock up the greatest fixed asset base; Culinary Tours are gaining share fastest as regional identity marketing differentiates against commodified sightseeing packages.
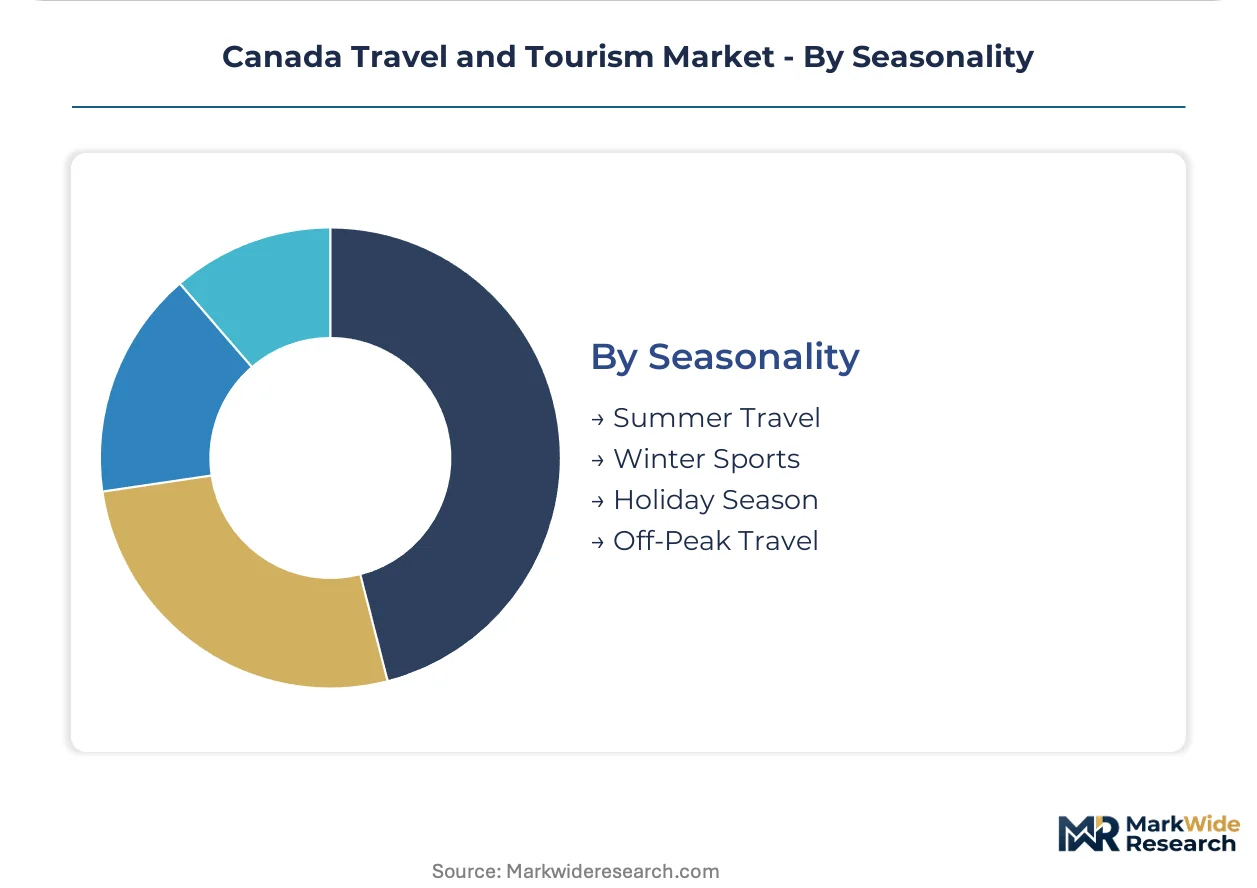
Seasonality:
Revenue concentration risk and labor recruitment challenges intensify as operators depend on narrow demand windows.
- Summer Travel:Peak capacity utilization across national park systems, marine ferry networks, and urban hotel portfolios. Parks Canada visitor permit caps in Banff and Jasper constrain supply expansion despite demand concentration.
- Winter Sports:Three-month revenue windows force dual-season programming strategies. Ski resort operators in Whistler, Banff, and Mont-Tremblant deploy lift infrastructure for alpine hiking and mountain biking to extend asset productivity.
- Holiday Season:Urban leisure and family visitation patterns create secondary peaks in Toronto and Vancouver accommodation markets.
- Off-Peak Travel:Shoulder season discounting and conference tourism targeting attempt to stabilize occupancy outside peak windows.
Summer Travel captures peak revenue concentration; Winter Sports operators are restructuring fastest through capital reinvestment in year-round programming infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Atlantic Investment Tax Credit and federal tourism infrastructure programs are concentrating operator expansion in designated economic zones. Provincial marketing organizations leverage these instruments to extend seasonal demand windows beyond traditional peak periods.
Ontario
Toronto's financial district generates sustained mid-week corporate demand that stabilizes urban hotel occupancy. Destination Ontario coordinates with Parks Canada to manage visitor flows at Niagara Falls and Thousand Islands corridors. The Greater Toronto Area anchors the country's largest convention infrastructure, where Metro Toronto Convention Centre bookings drive shoulder-season revenue.
British Columbia
Whistler and Vancouver Island marine routes capture premium eco-tourism spend through bear-viewing and whale-watching certifications. BC Ferries capacity allocations and terminal upgrades receive provincial transportation ministry coordination. The Sea-to-Sky corridor concentrates ski infrastructure investment where Whistler Blackcomb operates North America's largest lift-served terrain.
Alberta
Banff and Jasper national park gateways absorb concentrated international visitation despite Parks Canada permit caps. Travel Alberta partners with Indigenous Tourism Alberta to expand co-managed backcountry access. Calgary International Airport functions as the prairie hub where WestJet anchors transcontinental and sun-destination route density.
Quebec
Mont-Tremblant and Quebec City heritage corridors blend winter sports with cultural programming that extends visitor stays. Tourisme Québec administers sustainable tourism certification requirements tied to provincial grant eligibility. Montreal-Trudeau International sustains transatlantic connectivity that feeds Old Montreal's hospitality inventory.
Atlantic Canada
Nova Scotia's Cabot Trail and Newfoundland coastal routes present underdeveloped inventory outside western mountain corridors. Atlantic Canada Opportunities Agency infrastructure funding supports ferry network modernization and trail development. Halifax Stanfield International anchors regional air access where seasonal cruise terminal operations create secondary demand peaks.
Canada Travel and Tourism Market Competitive Landscape
Integrated flag carriers anchor one tier; independent destination operators and digital intermediaries hold specialized positions beneath. Market structure concentrates around three strategic archetypes: network airlines controlling slot portfolios at gateway airports, global hospitality chains leveraging loyalty ecosystems, and regional specialists commanding protected-area access permits. Dominant competitive moves include dual-season asset programming to compress fixed-cost recovery windows and Indigenous partnership frameworks that unlock federal infrastructure grants.
Within the network carrier tier, Air Canada and WestJet Airlines Ltd occupy positions shaped by hub geography and fleet configuration. Air Canada exemplifies the full-service flag carrier archetype through its dominant slot control at Toronto Pearson, Vancouver International, and Montreal-Trudeau. WestJet represents the leisure-focused challenger model anchored at Calgary International. Marriott International sits within the global hospitality tier where Bonvoy loyalty integration controls repeat booking flows across Canadian property footprints spanning urban towers to airport select-service properties.
| Leading Market Players |
|---|
| Air Canada |
| WestJet Airlines Ltd |
| Expedia Group |
| Marriott International |
| Accor SA |
| BC Ferries |
| Whistler Blackcomb |
| Hilton |
| Checkfront |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap lodge operators and Indigenous co-management partnerships anchor supply discipline across British Columbia and Alberta backcountry corridors, translating restricted permit access into rate premiums that compress price elasticity for experience-seeking travelers.
Pricing Analysis
Short lead-time premiums command substantial markups over advance-booking inventory across Whistler and Banff accommodation tiers, compressing margin recovery for operators dependent on spot-market fill rates. Three-tier pricing structure across luxury eco-lodges, standard mountain resorts, and economy motor-inn properties stratifies by carbon certification status and Indigenous partnership credentials. Pricing pressure stems from federal clean fuel regulations elevating aviation access costs for remote properties tethered to bush plane logistics. Corporate procurement teams demonstrate lowest price sensitivity when sustainability disclosure requirements override fare minimization, while leisure package travelers absorb highest elasticity.
Supply Chain Analysis
Wildlife stewardship certification and Parks Canada backcountry permits gate supplier eligibility, constraining qualified guiding capacity and elevating wage structures for certified operators. Supply concentrates in Canada, the United States, and select European outbound markets where tour packaging infrastructure feeds inbound volume. Specialized alpine equipment, marine vessel fleets, and carbon-offset inventory draw from limited manufacturer pools with extended procurement timelines. Single-source vulnerability runs through aviation fuel supply chains serving remote lodge networks. Distribution runs through direct-to-consumer platforms, loyalty ecosystem redemption flows, and traditional wholesale intermediaries with shifting share dynamics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's National Tourism Strategy functions as a cost-of-compliance narrative, with federal infrastructure grants contingent on sustainability certifications and Indigenous partnership frameworks that erect barrier-to-entry moats protecting compliant incumbent positions.
For Market Incumbents: Hedge against margin compression by securing dual-season programming infrastructure that repurposes winter lift assets for summer mountain biking activations, compressing fixed-cost recovery windows. Deepen channel control through loyalty ecosystem API integration that bypasses traditional wholesale intermediaries losing share to direct platforms. Counter emerging digital-native booking platforms by anchoring repeat booking flows through Bonvoy-style membership architectures. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Atlantic Canada marine tourism corridors presents white-space entry opportunity outside supply-constrained western mountain markets. Target Nova Scotia and Newfoundland coastal trail development zones where ferry network modernization unlocks underpenetrated inventory expansion. Pursue carbon-neutral itinerary certification as differentiated go-to-market positioning against conventional mass-market operators. For Investors and Strategic Acquirers: Distressed-cycle entries favor Indigenous co-management specialists in British Columbia and Alberta where federal funding flows and protected-area access permits create durable competitive positioning. Long-term viability across the analysis window rests on operators demonstrating year-round asset utilization and regulatory compliance infrastructure. Monitor Parks Canada permit allocation decisions as inflection indicator for supply expansion constraints in signature destination corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Season Asset Programming | Repurposes Whistler and Banff lift infrastructure for summer mountain biking, improving capital recovery. |
| Indigenous Partnership Framework | Unlocks federal infrastructure grants tied to co-management agreements in protected-area corridors. |
| Carbon-Neutral Certification | Captures margin premiums through wildlife-certified guiding operations in British Columbia coastal zones. |
| Digital Platform Convergence | Integrates dynamic packaging engines with loyalty APIs, bypassing traditional wholesale intermediaries. |
| Atlantic Canada Expansion | Develops Nova Scotia and Newfoundland marine tourism inventory outside western mountain corridors. |
Research Methodology
Destination Canada tourism statistics, Parks Canada visitor permit databases, and provincial marketing organization annual reports formed the secondary backbone, cross-referenced with operator financial disclosures and federal infrastructure grant allocations. Primary interviews with ski resort operations directors, Indigenous tourism partnership coordinators, aviation route planners, and hospitality revenue managers supplied forward-looking capacity and pricing intelligence. Bottom-up property-level capacity assessments and top-down national expenditure flows were triangulated to validate segment sizing.
Bottom-up modeling aggregated individual operator capacity, occupancy assumptions, and yield metrics across accommodation, transportation, and activity segments. Top-down verification cross-checked against national tourism expenditure surveys and international visitor volume trends. Segmentation dimensions included customer type, service category, activity focus, and seasonal concentration. CAGRs were derived from trend extrapolation moderated by regulatory constraint modeling, with federal carbon pricing trajectories and clean fuel regulation timelines incorporated as structural cost inputs.
Inputs from Parks Canada permit allocation records and provincial tourism boards were available through the study window; gaps in real-time operator yield data introduce uncertainty bands around accommodation pricing projections. Forecasts reflect documented assumptions regarding visa processing efficiency, air route recovery velocity, and Indigenous partnership negotiation timelines. A model refresh is warranted upon material change in federal sustainable tourism funding allocations or Parks Canada carrying capacity policy adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Yoga Tourism Market
Travel and Tourism
Pet Travel Services Market
Travel and Tourism
Group Travel Market
Travel and Tourism
UK Outbound Travel Market
Travel and Tourism
LAMEA Pet Travel Services Market
Travel and Tourism
US and Canada Travel Market
Travel and Tourism
France Culinary Tourism Market
Travel and Tourism
Educational Tourism Market
Travel and Tourism
China Online Travel Market
Travel and Tourism
MICE Travel Service Market
Travel and Tourism
Europe Driving Vacation Market
Travel and Tourism
Singapore Travel Retail Market
Travel and Tourism
Europe Wellness Tourism Market
Travel and Tourism
Wedding Tourism Market
Travel and Tourism
North America Travel Retail Market
Travel and Tourism
Vietnam Online Travel Market