
 Europe E-Commerce Apparel Market | 2026-2036
Europe E-Commerce Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe E-Commerce Apparel Market Insights
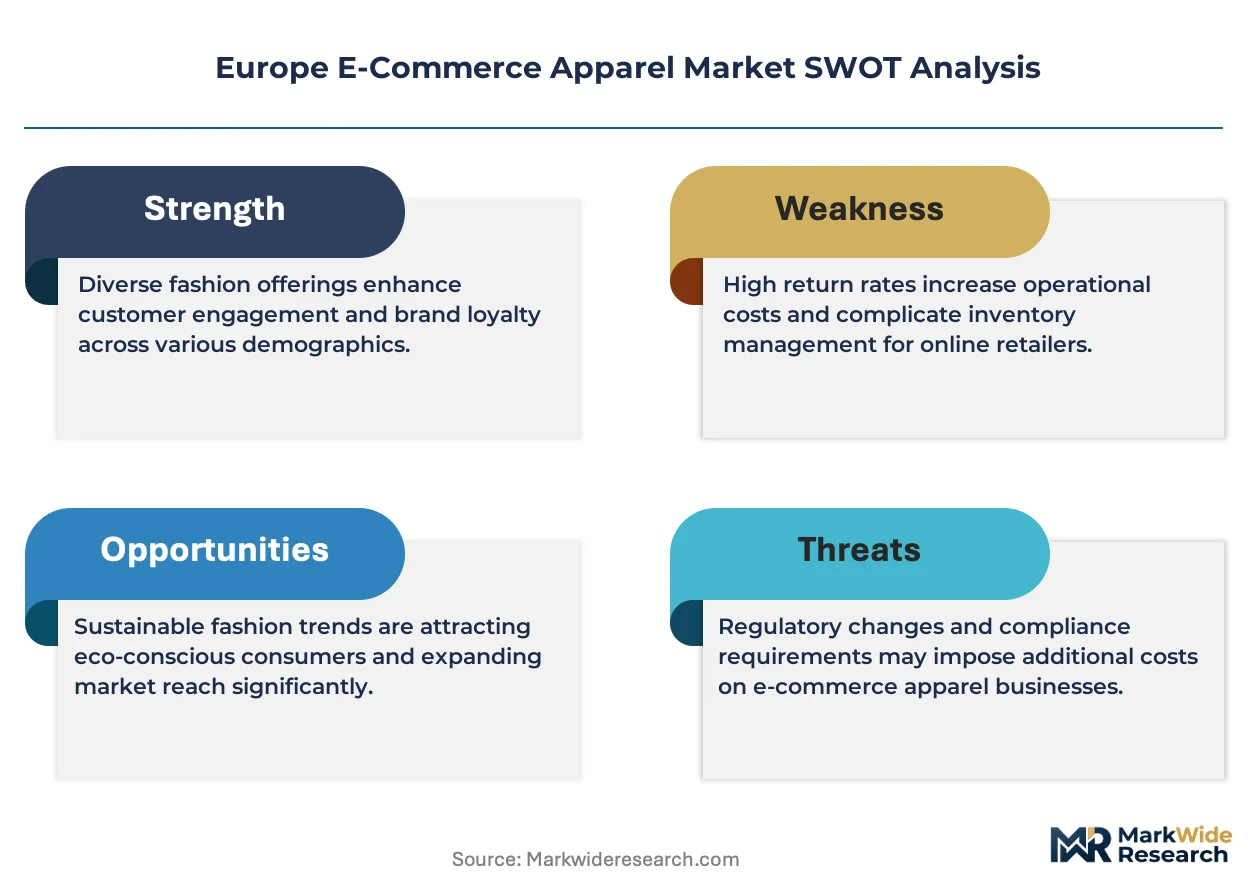
The EU Green Deal is pivoting compliance costs upward for every digital apparel merchant targeting European consumers. Zalando leverages its proprietary logistics network to absorb these regulatory burdens ahead of smaller rivals. ASOS sustains rapid inventory turnover through data-driven trend forecasting that minimizes dead stock exposure. Shein competes aggressively on price but faces escalating pressure to document supply chain provenance under emerging digital product passport rules.
Europe E-Commerce Apparel encompasses digitally distributed clothing and accessories retailed through web platforms and mobile applications, with garment specifications governed by EU textile labeling standards EN 13402 for sizing and ISO 3758 for care symbols. The category serves consumer wardrobes through algorithmic personalization, virtual try-on interfaces, and same-day fulfillment infrastructure. Activewear commands premium positioning as athletic lifestyle boundaries dissolve into everyday dressing codes. Social media distribution channels capture the fastest growth trajectory by converting content engagement directly into checkout flows. Luxury price tiers retain concentrated margin pools despite representing smaller transaction volumes than budget or mid-range segments.
EMA and ECHA frameworks intersect with apparel commerce through chemical restriction mandates under REACH that limit azo dyes and formaldehyde residues in textiles sold online. The EU AI Act imposes disclosure requirements on algorithmic recommendation engines that power product discovery across major platforms. Stakeholders must monitor how digital product passport implementation timelines reshape supplier qualification criteria and last-mile cost structures.
Market Dynamics
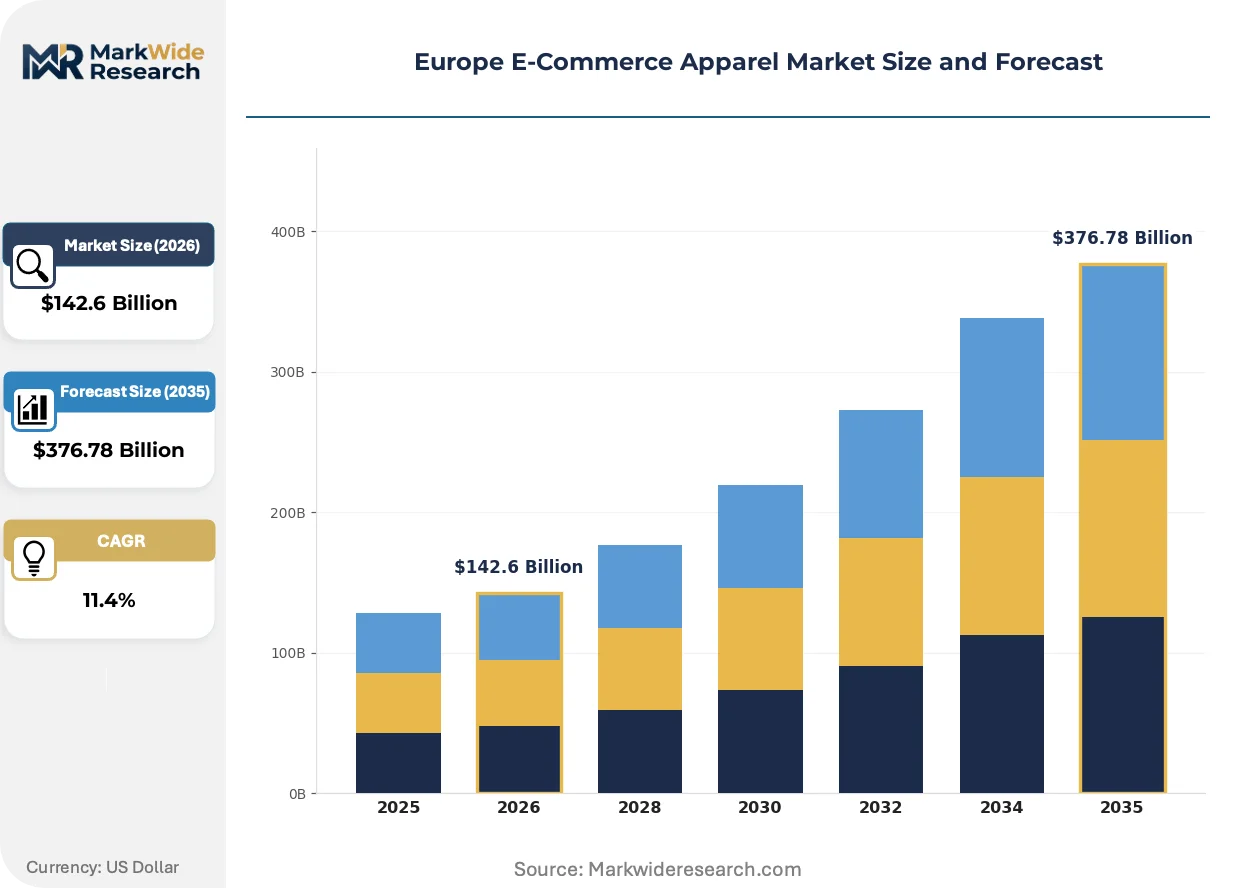
The EU Green Deal's digital product passport mandate is forcing apparel merchants to restructure supplier verification workflows and absorb compliance overhead before the 2027 enforcement window closes.
Growth Catalysts
- REACH chemical restrictions:ECHA's tightening azo dye and formaldehyde limits are accelerating certified supplier consolidation, favoring platforms with pre-qualified vendor networks.
- Gen Z purchasing velocity:Under-25 consumers across Germany, France, and the United Kingdom are compressing trend-to-purchase cycles through social commerce interfaces.
- Same-day fulfillment infrastructure:Urban micro-fulfillment centers in Amsterdam, Berlin, and Milan are shrinking delivery windows below four hours for premium segments.
Market Restraints
- Supplier concentration in Southeast Asian cut-make-trim:Vietnam and Bangladesh account for the majority of EU-bound apparel assembly, exposing merchants to single-origin disruption risk.
- CSRD reporting burdens:The Corporate Sustainability Reporting Directive mandates granular Scope 3 emissions disclosure that smaller marketplace vendors lack systems to compile.
- Last-mile diesel dependency:Courier fleets serving peripheral EU regions remain fossil-fuel dependent, constraining carbon-neutral delivery claims.
Strategic Opportunities
- Poland and Romania fulfillment expansion:These underpenetrated corridors offer lower warehousing costs and growing domestic e-commerce penetration for mid-range positioning.
- EU AI Act disclosure requirements:Early compliance with algorithmic transparency rules creates differentiation against non-EU platforms lacking comparable governance frameworks.
- Virtual try-on + sizing AI convergence:AR fitting rooms integrated with body-scan databases are reducing return rates in denim and formalwear categories.
Industry Challenges
- Textile chemist talent scarcity:REACH compliance auditing requires specialized expertise that outstrips available certification programs in Central and Eastern Europe.
- Legacy warehouse management system integration:Retrofitting pre-2015 facilities for real-time inventory visibility demands capital outlays that strain mid-tier operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe E-Commerce Apparel Market |
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $376.78 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Dresses, Jeans, Activewear Customer Type: Women, Men, Children, Unisex Distribution Channel: Online Retailers, Brand Websites, Marketplaces, Social Media Price Tier: Luxury, Mid-Range, Budget, Discount |
| Companies Covered | Zalando, ASOS, Inditex, Hennes & Mauritz, Amazon, Shein, Vinted, Next, Burberry Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe E-Commerce Apparel Market Trends and Innovations
Algorithmic personalization engines are displacing static category browsing as the primary discovery mechanism, while regulatory disclosure mandates and circular resale platforms reshape merchant infrastructure requirements.
Generative AI styling assistants are integrating natural language preference capture with inventory matching to compress search-to-checkout pathways. Fast-fashion adopters in the United Kingdom and Germany are deploying these tools at scale, reducing human stylist dependency while expanding average order values through algorithmic upselling.
The EU AI Act's recommendation engine disclosure rules are mandating transparency into how product rankings are generated. Apparel platforms serving French and Spanish consumers must now document training data sources and bias mitigation protocols, increasing engineering overhead but creating defensible moats against non-compliant competitors.
Peer-to-peer resale channels are capturing defecting volume from primary retail as Gen Z buyers prioritize garment longevity metrics. Depop and Vinted interfaces in London, Paris, and Berlin are displacing discount clearance cycles, forcing brands to architect take-back logistics and authentication workflows that were previously absent from direct-to-consumer operations.
Europe E-Commerce Apparel Market Segmentation
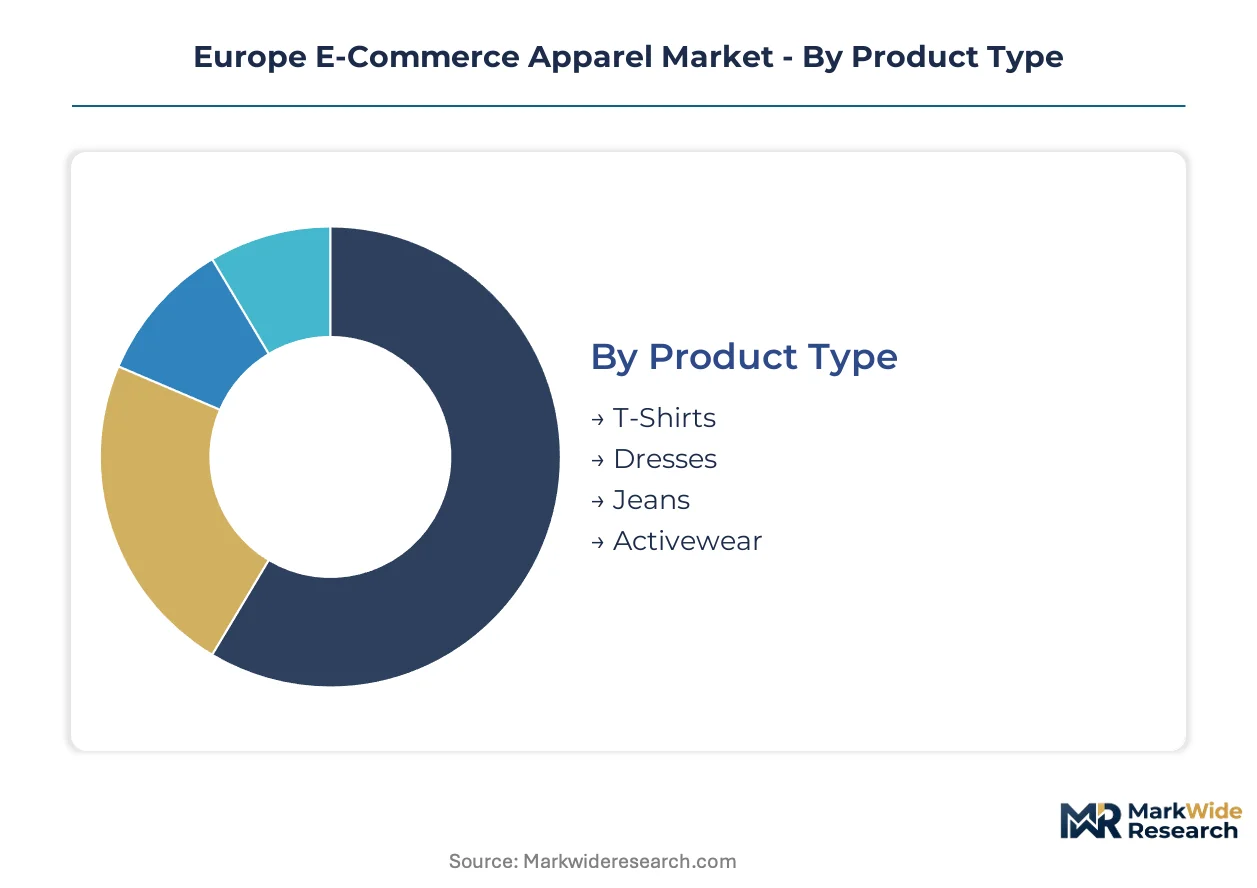
Segmentation in Europe's e-commerce apparel landscape reveals how regulatory pressure and fulfillment infrastructure reshape category economics. Distinct product, customer, and channel configurations demand specialized compliance workflows and logistics investments.
Product Type:
Integration depth varies sharply across garment categories, with some functioning as standalone purchase drivers while others embed within coordinated wardrobe systems.
- T-Shirts:Cotton-jersey basics with standardized EN 13402 sizing enable algorithmic personalization at scale. German and French consumers drive volume through subscription replenishment models that compress repurchase cycles.
- Activewear:Technical fabrics with moisture-wicking and compression specifications command premium positioning. United Kingdom demand concentrates among urban professionals blending athletic and office dress codes, though REACH-certified supplier scarcity constrains expansion.
- Dresses:Seasonal silhouettes with variable hem lengths and textile weights. Return rates exceed other categories due to fit uncertainty.
- Jeans:Denim with stretch blends and distressed finishes. Italian mills supply premium raw material to direct-to-consumer brands.
Volume placements concentrate in T-Shirts; the faster expansion belongs to Activewear.
Customer Type:
Cost tier stratification across demographic segments determines platform acquisition spend and lifetime value calculations.
- Women:The largest revenue pool spanning workwear, casual, and occasion categories. United Kingdom and German shoppers drive premium segment growth through social commerce discovery.
- Men:Lower browsing frequency but higher average order values when purchase intent crystallizes. Simplified sizing reduces return rates versus women's categories.
- Children:Rapid size turnover creates replenishment-driven demand patterns. Parents prioritize durability metrics under EU Green Deal transparency requirements.
- Unisex:Gender-neutral silhouettes with extended size runs. Gen Z adoption in Paris and Berlin outpaces older demographics.
Women's segments dominate current revenue capture; unisex positioning gains share fastest among under-30 cohorts.
Distribution Channel:
Application context—whether discovery happens through intent-driven search or passive content consumption—determines conversion architecture and margin structure.
- Online Retailers:Curated multi-brand platforms with editorial merchandising. Zalando's proprietary logistics network absorbs EU Green Deal compliance costs ahead of marketplace competitors.
- Brand Websites:Direct-to-consumer channels with full margin retention. ASOS deploys data-driven trend forecasting to minimize dead stock exposure.
- Marketplaces:Aggregated vendor environments with price transparency. Shein competes aggressively here but faces escalating digital product passport documentation requirements.
- Social Media:Content-native checkout flows through Instagram and TikTok. Depop and Vinted interfaces in London and Paris displace traditional clearance cycles.
Marketplaces hold the largest transaction volumes; social commerce channels climb the fastest as Gen Z purchasing velocity accelerates.
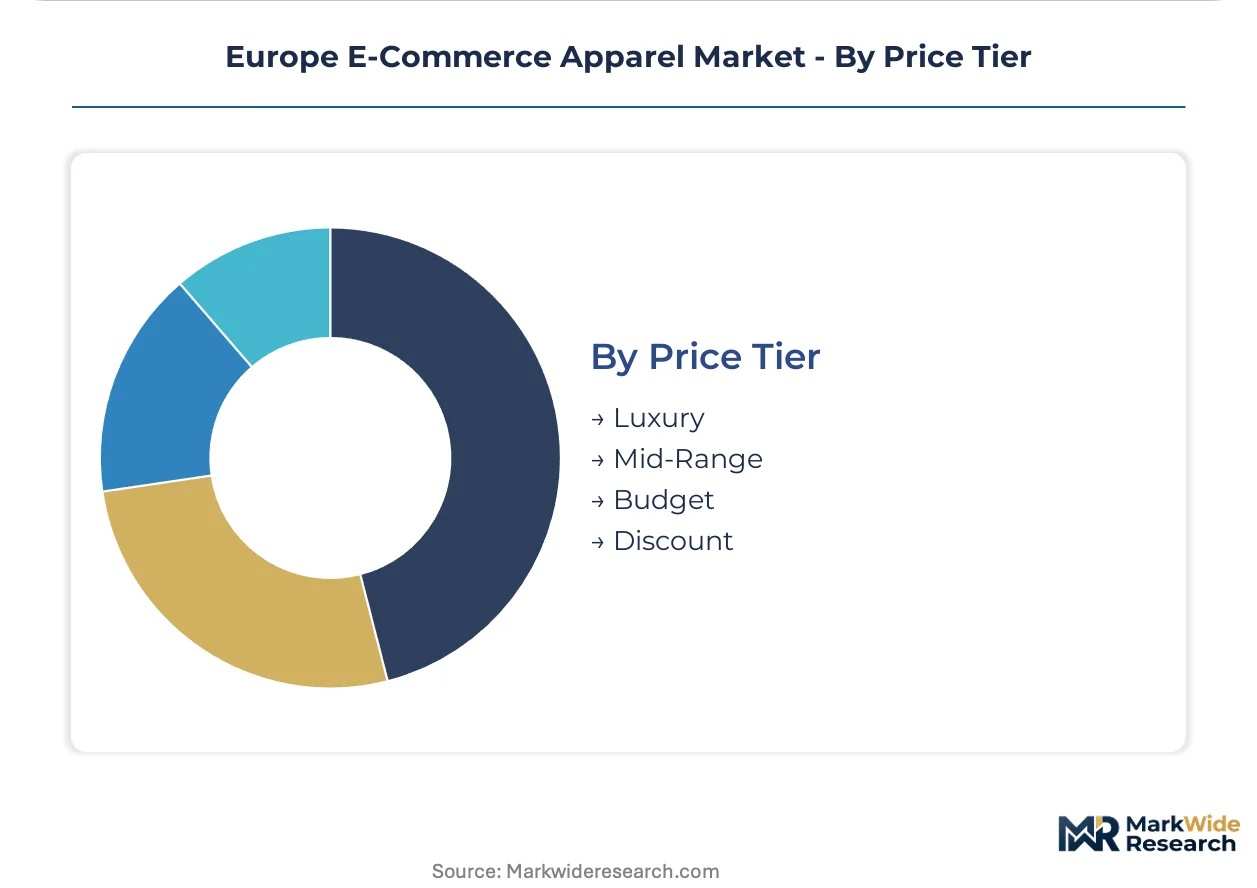
Price Tier:
Margin concentration and supply chain transparency obligations scale inversely across pricing strata.
- Luxury:Designer labels with artisan craftsmanship positioning and authentication protocols. Concentrated margin pools in Milan and Paris despite smaller transaction volumes.
- Mid-Range:Contemporary brands balancing quality signals with accessibility. German consumers show strongest loyalty to domestic labels in this bracket.
- Budget:Value-oriented basics with compressed lead times. Southeast Asian cut-make-trim concentration exposes merchants to single-origin disruption risk.
- Discount:Off-price inventory clearance and promotional bundling. CSRD reporting burdens disadvantage smaller marketplace vendors lacking Scope 3 emissions systems.
Mid-Range segments anchor platform profitability; luxury tiers expand most quickly through virtual try-on and sizing AI convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for digitally distributed apparel concentrates in Germany, France, and the United Kingdom, where Gen Z purchasing velocity and same-day fulfillment infrastructure create the densest e-commerce corridors. The EU Green Deal's digital product passport mandate is forcing supply chain restructuring across all major markets. Regulatory fragmentation between national implementations of REACH and CSRD reporting adds compliance complexity for cross-border merchants.
Germany
Subscription replenishment models for cotton-jersey basics drive volume through algorithmic personalization at scale. Berlin hosts Zalando's proprietary logistics network that absorbs EU Green Deal compliance costs ahead of marketplace competitors. ECHA's tightening azo dye limits accelerate certified supplier consolidation, favoring platforms with pre-qualified vendor networks in North Rhine-Westphalia.
France
Social commerce discovery through Instagram and TikTok converts content engagement directly into checkout flows among Parisian consumers. The EU AI Act's recommendation engine disclosure rules mandate transparency into product ranking generation for platforms serving French shoppers. Île-de-France concentrates luxury authentication protocols and virtual try-on technology deployment.
United Kingdom
Urban professionals blending athletic and office dress codes command premium positioning for technical activewear fabrics. ASOS deploys data-driven trend forecasting from London to minimize dead stock exposure across rapid inventory turnover cycles. CSRD reporting burdens disadvantage smaller marketplace vendors lacking Scope 3 emissions compilation systems.
Italy
Italian mills supply premium raw denim to direct-to-consumer brands targeting quality-conscious European shoppers. Milan's urban micro-fulfillment centers shrink delivery windows below four hours for premium segments. REACH-certified supplier scarcity constrains activewear expansion despite concentrated demand.
Poland
Underpenetrated e-commerce corridors offer lower warehousing costs for mid-range positioning strategies. Warsaw and Kraków logistics hubs serve growing domestic digital apparel penetration while connecting to broader EU fulfillment networks. Emerging digital product passport implementation timelines reshape supplier qualification criteria for Polish-based operations.
Europe E-Commerce Apparel Market Competitive Landscape
German and British platforms anchor one tier; Chinese ultra-fast-fashion specialists hold price-driven positioning. The vendor base separates into three strategic archetypes: vertically integrated logistics operators, data-native trend forecasters, and social-commerce-native aggregators. Dominant competitive moves include proprietary fulfillment network expansion and algorithmic personalization engine deployment.
Within the integrated logistics tier, Zalando exemplifies compliance-forward infrastructure investment. ASOS occupies a position among data-native forecasters compressing trend-to-purchase cycles. Shein represents the ultra-fast-fashion archetype facing escalating documentation requirements under emerging digital product passport rules.
| Leading Market Players |
|---|
| Zalando |
| ASOS |
| Inditex |
| Hennes & Mauritz |
| Amazon |
| Shein |
| Vinted |
| Next |
| Burberry Group |
| Others |
Pricing and Supply Chain Analysis
Textile chemist scarcity in Central and Eastern Europe widens labor-cost differentials between REACH-certified and uncertified supplier tiers, compressing margin spreads in budget apparel while amplifying premium-tier pricing power for compliant merchants.
Pricing Analysis
Volume concentrates in budget basics where Shein and marketplace aggregators compete on compressed margins; margin pools concentrate in luxury tiers where authentication protocols and virtual try-on technology justify premium positioning. Price differentiation rests on REACH certification status and same-day fulfillment capability, with German consumers showing highest willingness to pay for verified supply chain transparency. Pricing pressure stems from digital product passport compliance costs that smaller marketplace vendors cannot absorb. Budget-tier buyers exhibit extreme price sensitivity; luxury purchasers prioritize provenance documentation over absolute cost.
Supply Chain Analysis
Direct-to-consumer channels anchored by ASOS and Zalando handle premium buyer demand through proprietary logistics networks, while marketplace aggregators feed price-sensitive volume through third-party fulfillment. Raw material dependencies center on Italian denim mills, Turkish cotton processors, and Portuguese knitwear specialists. Assembly concentration in Vietnam and Bangladesh creates single-origin vulnerability to ECHA regulatory shifts. Distribution runs through Amsterdam and Berlin micro-fulfillment nodes for sub-four-hour delivery windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal compliance deadlines are forcing consolidation as smaller marketplace vendors lack capital to implement digital product passport infrastructure.
For Market Incumbents: Lock in supplier certification advantages by accelerating REACH-audited vendor consolidation ahead of enforcement windows. Acquire specialized textile chemistry talent in Poland and Romania before competitor hiring drives wage inflation. Control last-mile infrastructure through urban micro-fulfillment expansion in underpenetrated corridors. For New Entrants and Emerging Players: Capture white-space in unisex activewear positioning for Berlin and Paris Gen Z cohorts where incumbent catalog breadth remains thin. Exploit social commerce checkout flows through TikTok-native merchandising that bypasses traditional search-based discovery. Enter through subscription replenishment models for cotton-jersey basics where algorithmic personalization reduces customer acquisition costs. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated logistics operators given EU AI Act disclosure requirements that disadvantage non-compliant platforms. Five-to-ten-year viability favors merchants with captive warehousing networks and pre-qualified supplier databases. Watch digital product passport implementation timelines as the inflection signal separating acquisition-ready targets from stranded assets.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Certified Supplier Consolidation | Pre-qualified vendor networks absorb ECHA compliance costs ahead of marketplace competitors. |
| Urban Micro-Fulfillment Expansion | Berlin and Amsterdam nodes shrink delivery windows below four hours for premium segments. |
| Virtual Try-On Technology Deployment | AR fitting rooms integrated with body-scan databases reduce return rates in denim categories. |
| Social Commerce Platform Integration | TikTok-native checkout flows convert content engagement directly into transaction volume. |
| Digital Product Passport Infrastructure | Supply chain transparency systems satisfy EU Green Deal mandates before enforcement windows close. |
Research Methodology
Document review covered EU regulatory filings, ECHA chemical restriction updates, and customs trade data, complemented by interviews with supply chain directors at major apparel platforms, logistics operators in Amsterdam and Berlin, and textile certification auditors. Primary fieldwork engaged procurement leads at direct-to-consumer brands, warehouse management system vendors, and social commerce platform engineers. Secondary sources included Zalando and ASOS sustainability disclosures, REACH implementation guidance, and EU AI Act technical documentation. Bottom-up transaction modeling triangulated against top-down market sizing.
Segment-level outputs reflect disaggregation across product type, customer demographic, distribution channel, and price tier dimensions throughout the forecast period. CAGRs derive from trend extrapolation of Gen Z purchasing velocity, same-day fulfillment penetration curves, and regulatory compliance cost absorption rates. Input assumptions incorporate digital product passport implementation timelines and REACH-certified supplier availability constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA enforcement intensity and social commerce platform algorithm changes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Dropshipping Market
E-Commerce Solutions
Global Subscription E Commerce Market
E-Commerce Solutions
IT Consumer Electronics E-Commerce Market
E-Commerce Solutions
North America E-Commerce Watch Market
E-Commerce Solutions
Chile E-Commerce Market
E-Commerce Solutions
Latvia E-Commerce Market
E-Commerce Solutions
E-Commerce Ecosystem Market
E-Commerce Solutions
Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Panama E-Commerce Market
E-Commerce Solutions
Global Shopping Cart Market
E-Commerce Solutions
Switzerland E-Commerce Market
E-Commerce Solutions
Express and Parcel Market
E-Commerce Solutions
India Quick Commerce Market
E-Commerce Solutions
United States E-Invoicing Market
E-Commerce Solutions
E-Commerce App Market
E-Commerce Solutions
Europe Dropshipping Market