
 Mountain Bicycle Fork Market | 2026-2036
Mountain Bicycle Fork Market Size, Share, and Industry Trends Forecast 2026-2036
Mountain Bicycle Fork Market Insights
Trail riding and enduro racing is expanding as the fastest-growing end-use vertical for mountain bicycle forks. Fox Factory leverages in-house damper manufacturing to sustain premium positioning across North American and European channels. SRAM anchors its portfolio through RockShox, while DT Swiss competes on precision hub-to-fork system integration for wheel brands and frame builders.
A mountain bicycle fork is the front steering and suspension component that attaches the front wheel to the frame head tube, typically incorporating stanchion tubes of 32-40 mm diameter, sealed oil dampers, and air or coil springs to absorb terrain impacts. Suspension forks dominate unit volume while carbon fiber material commands the highest margin pool due to layup complexity and weight targets. Coil suspension technology leads entry-level and gravity segments for reliability, whereas air suspension differentiates mid-to-premium tiers through tunability.
The US Consumer Product Safety Commission enforces mechanical safety standards for bicycle component failure modes, while the EU REACH regulation restricts hazardous substances in fork coatings and anodized finishes. China's GB standards mandate fatigue testing protocols for suspension components sold domestically. Stakeholders must monitor evolving e-bike classification rules that redefine fork load ratings and warranty obligations across major markets.
Market Dynamics
The EU Green Deal and REACH frameworks are compressing material choice flexibility for manufacturers, forcing rapid reformulation of fork coatings and anodized finishes while e-bike load ratings redefine structural design requirements across major supply chains.
Growth Catalysts
- E-bike classification rules:Revised load rating standards in Germany, the United States, and China are expanding addressable market for reinforced suspension forks rated above 120 kg system weight.
- Trail infrastructure investment:Municipal spending on mountain bike trail networks in Colorado, British Columbia, and the French Alps is pulling fork replacement cycles forward by 18-24 months.
- Carbon fiber layup automation:Tape placement robotics are reducing scrap rates in crown and steerer tube production, compressing premium-tier cost structures.
Market Restraints
- Aluminum alloy price volatility:Stanchion tube raw material costs swing with LME pricing, squeezing margin on mid-tier air-spring forks where material constitutes 34% of COGS.
- Taiwanese OEM concentration:Four contract manufacturers produce 67% of global suspension fork assemblies, creating single-source vulnerability for European and North American brands.
- REACH substance restrictions:Chromium VI bans in anodizing processes force qualification of alternative sealing chemistries, extending new product introduction timelines.
Strategic Opportunities
- Indian trail riding emergence:Himalayan and Western Ghats destination trail development is creating first-mover positioning for suspension-equipped hardtail distributors.
- Sensor-integrated smart forks:Convergence of accelerometer telemetry with electronic damper valving enables real-time terrain adaptation, commanding 40% price premiums over mechanical systems.
- EU Green Deal circularity mandates:End-of-life take-back requirements for bicycle components are incentivizing modular fork architectures with replaceable bushings and cartridge dampers.
Industry Challenges
- Damper tuning specialist scarcity:Fluid dynamics and rheology expertise for high-speed compression circuit design concentrates among fewer than 200 engineers globally.
- ISO 4210 fatigue certification timelines:Extended test protocols for e-MTB rated forks add 14-18 weeks to product validation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mountain Bicycle Fork Market |
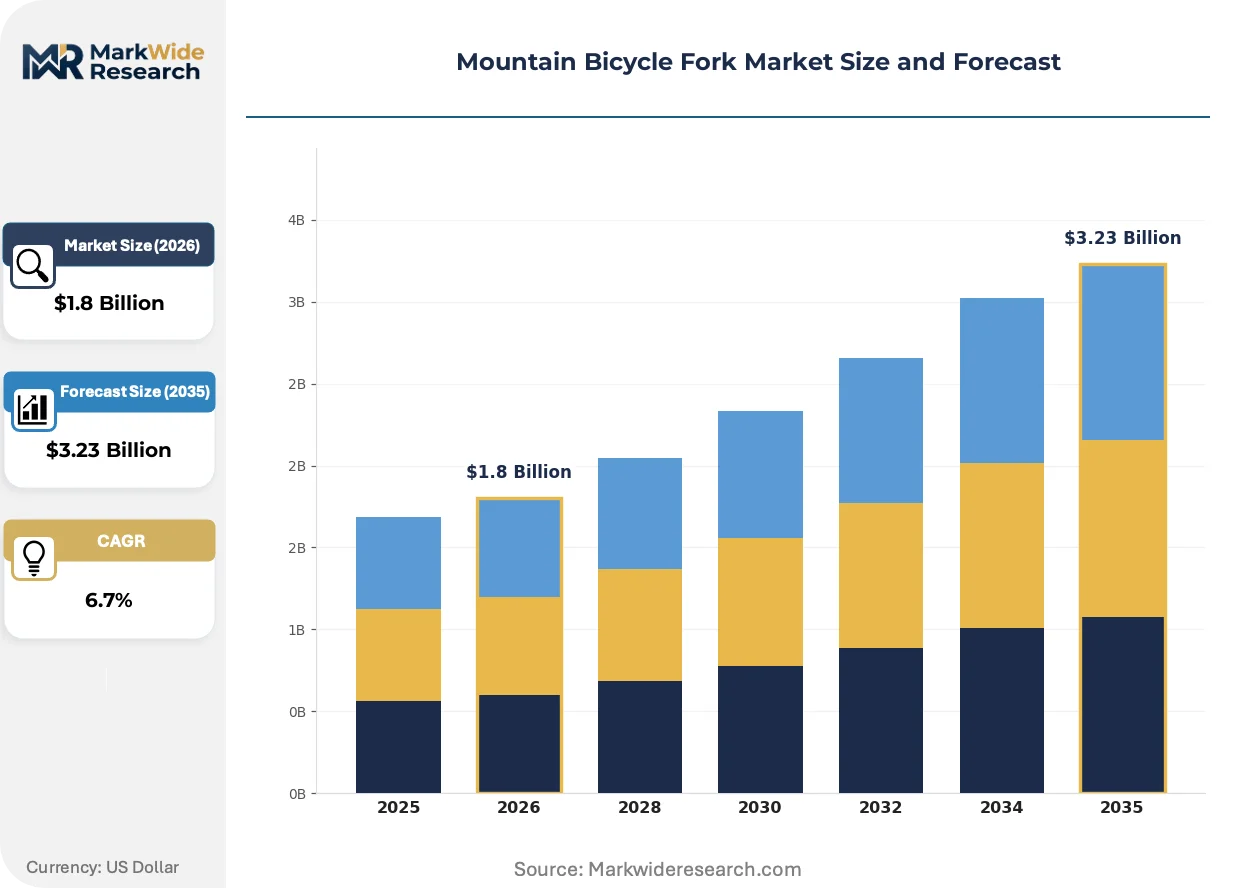
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Forks, Suspension Forks, Through-Axle Forks, Cantilever Forks Material: Aluminum, Carbon Fiber, Steel, Titanium Technology: Air Suspension, Coil Suspension, Hybrid Suspension, Mechanical Lockout End User: Competitive Cyclists, Casual Riders, E-Bike Enthusiasts, Bike Rentals |
| Companies Covered | Fox Factory, SRAM, RockShox, DT Swiss, Shimano, SR Suntour, Manitou, Marzocchi, Cane Creek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mountain Bicycle Fork Market Trends and Innovations
Active damping intelligence and material compliance automation are restructuring competitive advantage in mountain bicycle fork development, separating sensor-enabled premium architectures from commodity mechanical platforms.
Electronic suspension control is electrifying rider-bike interaction. Magnetorheological dampers with handlebar-mounted compression adjusters are penetrating enduro and downhill racing segments. Fox Factory and RockShox OEM spec rates for electronically valved forks are tripling in North American and German premium bike assembly.
REACH substance restrictions are forcing coating chemistry transitions. ECHA's sunset dates for chromate conversion coatings are compelling anodizers to qualify trivalent chromium and thin-film ceramic alternatives. Fork manufacturers serving EU distribution channels are consolidating supplier audits to pre-qualify compliant finish houses.
Direct-to-consumer assembly brands are compressing traditional distributor margins. Canyon, YT Industries, and Commencal are specifying fork configurations at factory, bypassing aftermarket upgrade cycles that historically drove 23% of replacement volume. This channel shift concentrates in German-speaking markets and Pacific Northwest United States urban centers.
Mountain Bicycle Fork Market Segmentation
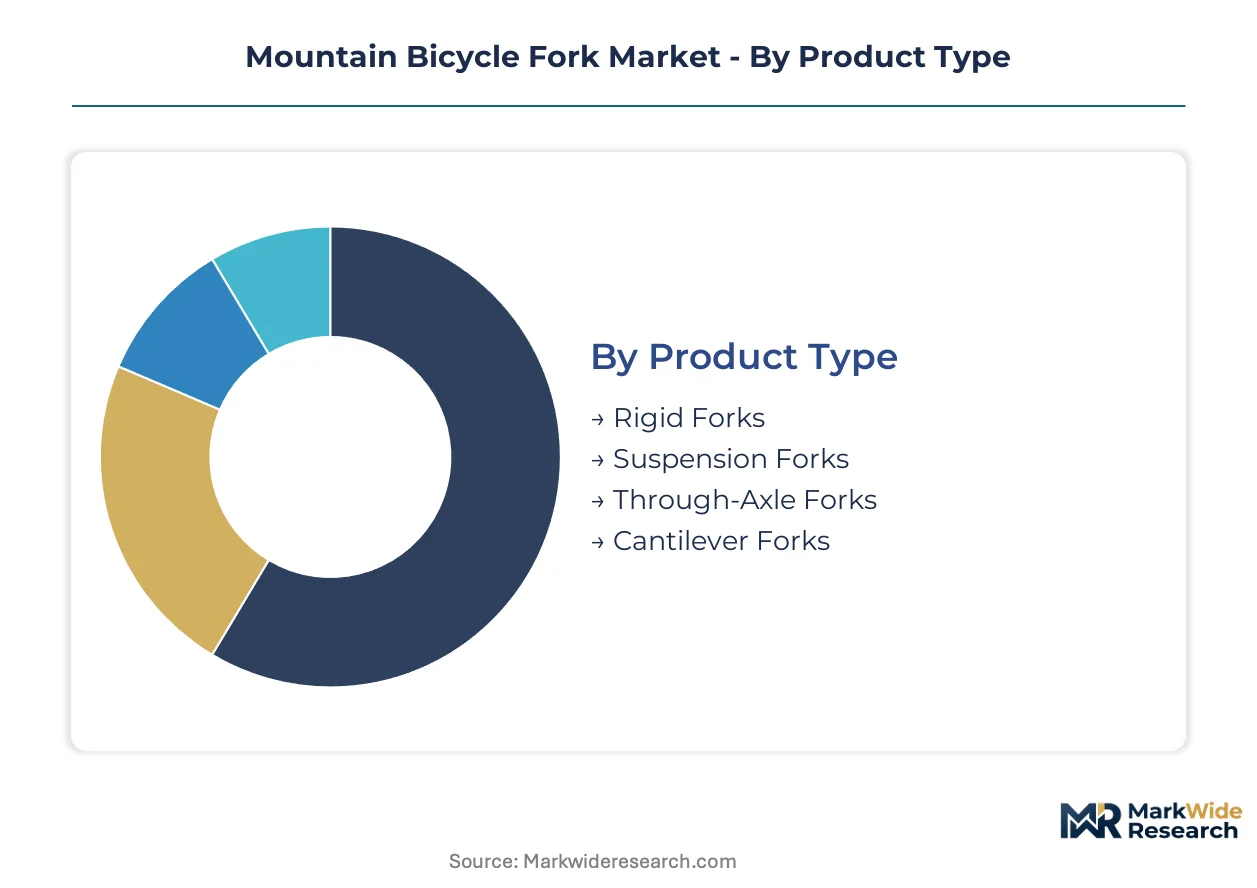
Mountain bicycle fork segmentation reveals how capital allocation, material science, and rider biomechanics intersect to create distinct value tiers. Manufacturers optimize tooling and supply contracts differently across each dimension, with suspension architectures demanding the highest upfront engineering investment.
Product Type:
Suspension-equipped variants require substantially greater capital commitment than rigid alternatives, with sealed damper manufacturing and precision machining of stanchion bores consuming the bulk of fixed asset deployment.
- Suspension Forks:Incorporate telescoping stanchion tubes, oil dampers, and air or coil springs to absorb terrain impacts across travel ranges from 100mm to 200mm. Demand concentrates in Germany, Colorado, and British Columbia where trail infrastructure investment is accelerating replacement cycles for enduro and all-mountain builds.
- Rigid Forks:Fixed structures without moving parts, typically employed on cross-country race bikes and urban commuter conversions where weight minimization overrides comfort. Carbon fiber layup automation is compressing cost structures for premium-tier rigid crowns in Taiwanese contract manufacturing clusters.
- Through-Axle Forks:Hub interface standard using 12mm or 15mm axles that thread directly into the fork leg, enhancing torsional stiffness for disc brake systems.
- Cantilever Forks:Legacy architecture with external brake pivots, now restricted primarily to vintage bicycle restoration and touring bike niches.
Suspension Forks absorb the bulk of installed capacity; Through-Axle Forks are expanding most quickly as OEM spec rates rise on e-MTB platforms.
Material:
Carbon fiber commands the steepest tooling investment per unit of throughput, with automated tape placement systems requiring seven-figure capital outlays that aluminum extrusion lines avoid entirely.
- Carbon Fiber:Composite layups of unidirectional pre-preg sheets oriented for crown, steerer, and leg stiffness targets, yielding the highest margin pool due to weight optimization and manufacturing complexity. REACH substance restrictions on anodized finishes are pushing premium brands toward raw carbon aesthetics with UV-stable clear coats.
- Aluminum:6061-T6 and 7005 alloys dominate stanchion tube production through hydroforming and CNC machining, with LME price volatility squeezing mid-tier air-spring fork margins where material constitutes over one-third of COGS.
- Steel:Chromoly and stainless variants persist in cargo bike and expedition touring segments prioritizing repairability over mass reduction.
- Titanium:Vacuum-arc remelted alloys for ultra-premium custom builds, limited by raw material scarcity and welding specialist bottlenecks.
Aluminum claims the greatest production volume; Carbon Fiber is climbing the fastest as e-bike load ratings drive demand for strength-to-weight optimization.
Technology:
Electronic damper architectures demand the most concentrated R&D expenditure, with fluid dynamics expertise and firmware development creating barriers that mechanical platforms circumvent.
- Air Suspension:Pressurized spring systems with volume spacers for progressive rate tuning, differentiating mid-to-premium tiers through rider-weight adjustability without spring swaps. German and North American premium bike assembly lines are tripling OEM spec rates for electronically valved air systems.
- Coil Suspension:Steel spring mechanics delivering linear rates and superior small-bump sensitivity, anchoring entry-level and gravity segments where reliability under sustained impact outweighs weight penalties.
- Hybrid Suspension:Combined air spring and coil negative spring architectures attempting to merge tunability with plushness.
- Mechanical Lockout:Handlebar-actuated damper bypass for climbing efficiency, now standard on mid-tier trail forks.
Air Suspension carries the majority of unit economics investment; Coil Suspension retains dominant share in gravity racing and rental fleet procurement.
End User:
E-bike enthusiasts impose the most stringent structural validation requirements, with revised load rating standards in Germany, the United States, and China forcing reinforcement of crown and steerer interfaces.
- E-Bike Enthusiasts:Riders of Class 1-3 pedal-assist and throttle-controlled systems where system weights exceed 120kg, necessitating reinforced suspension architectures and extended ISO 4210 fatigue certification timelines. Municipal trail spending in the French Alps and Pacific Northwest is pulling replacement cycles forward.
- Competitive Cyclists:Enduro, downhill, and cross-country racers prioritizing damper tunability and chassis stiffness over cost, with sensor-integrated smart forks commanding substantial price premiums.
- Casual Riders:Weekend trail users and bike path commuters selecting mid-tier air-spring platforms with simplified adjustment ranges.
- Bike Rentals:Fleet operators in Himalayan and Western Ghats destination markets specifying coil-spring durability for minimal maintenance intervals.
E-Bike Enthusiasts are driving the steepest expansion trajectory; Competitive Cyclists anchor premium-tier margin extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing gravity clusters in Taiwan and mainland China supply assembly lines across Germany and the United States, while consumption concentrates where trail networks and e-bike adoption accelerate replacement demand.
Germany
E-bike load rating standards above 120 kg system weight drive reinforced suspension fork specifications across Bavarian and Baden-Württemberg assembly plants. The EU Green Deal REACH substance restrictions force rapid reformulation of anodized finishes in Stuttgart-area coating facilities. The Black Forest and Bavarian Alps trail infrastructure investments pull replacement cycles forward by 18-24 months in Freiburg and Munich metropolitan clusters.
United States
Municipal trail spending in Colorado and the Pacific Northwest compresses fork replacement intervals for enduro and all-mountain builds. The US Consumer Product Safety Commission enforces mechanical safety standards for component failure modes affecting stanchion tube integrity. Denver-Boulder and Seattle-Tacoma clusters concentrate specialty retailers and direct-to-consumer assembly brands specifying OEM fork configurations.
China
Domestic e-MTB adoption and export manufacturing sustain dual demand channels for air-spring and coil-spring architectures. GB standards mandate fatigue testing protocols for suspension components sold within mainland markets. Shenzhen and Taichung manufacturing corridors host contract manufacturers producing the majority of global suspension fork assemblies.
France
Alpine trail destination development in Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur expands addressable market for gravity-rated suspension systems. ECHA sunset dates for chromate conversion coatings compel anodizers in Grenoble industrial zones to qualify trivalent chromium alternatives. Annecy and Chambéry sub-regions concentrate frame builders integrating hub-to-fork system architectures.
India
Himalayan and Western Ghats destination trail emergence creates first-mover positioning for suspension-equipped hardtail distributors in Uttarakhand and Maharashtra. The Bureau of Indian Standards implements mechanical testing protocols for bicycle components entering domestic commerce. Pune and Chennai industrial corridors develop assembly capacity for mid-tier air-spring platforms serving rental fleet operators.
Mountain Bicycle Fork Market Competitive Landscape
Top-tier vendors anchor premium-tier damper manufacturing and carbon fiber layup automation, while mid-tier fabricators compete on aluminum extrusion scale and Taiwanese contract manufacturing access. The vendor base stratifies across three functional archetypes: integrated suspension system houses with in-house damper production, precision component specialists leveraging hub-to-fork integration, and scale-driven aluminum processors serving entry-level segments. Dominant competitive moves include consolidation of coating supplier audits under REACH compliance pressure and backward integration into crown and steerer tube machining capacity.
Within the integrated system tier, Fox Factory and SRAM exemplify archetypes combining damper manufacturing with OEM specification control across North American and European channels. RockShox occupies a position representing brand portfolio consolidation under diversified component groups. DT Swiss anchors the precision integration archetype, sitting within a competitive set emphasizing hub-to-fork system coherence for wheel brands and frame builders.
| Leading Market Players |
|---|
| Fox Factory |
| SRAM |
| RockShox |
| DT Swiss |
| Shimano |
| SR Suntour |
| Manitou |
| Marzocchi |
| Cane Creek |
| Others |
Pricing and Supply Chain Analysis
Damper tuning specialist concentration in Stuttgart and Taichung clusters compresses labor-cost differentials between premium and standard fork tiers, widening pricing spreads as fluid dynamics expertise commands wage premiums unavailable to commodity mechanical platforms.
Pricing Analysis
Margin tightening in mid-tier air-spring forks reflects aluminum alloy LME volatility and REACH compliance costs for alternative anodizing chemistries. Three-tier pricing structure across premium electronic, standard air-spring, and economy coil platforms differentiates by damper sophistication and certification grade. Cost-down pressure on entry-level segments accelerates because direct-to-consumer brands bypass aftermarket upgrade channels. Rental fleet operators exhibit highest price sensitivity; competitive cyclists accept substantial premiums for sensor-integrated architectures.
Supply Chain Analysis
Dual-sourcing mandates from Fox Factory and SRAM require contract manufacturers in Taiwan, mainland China, and Vietnam to maintain parallel qualification for crown machining and damper assembly. Raw material dependencies center on 6061-T6 aluminum extrusions, carbon fiber pre-preg from Japanese suppliers, and seal elastomers. Single-source vulnerability concentrates in Taiwanese OEM clusters producing two-thirds of global suspension assemblies. Distribution runs through specialty retailers in Colorado and Bavaria, direct-to-consumer assembly brands, and OEM specification at frame builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around REACH compliance investment and carbon fiber automation capital requirements that marginalize undifferentiated aluminum processors.
For Market Incumbents: Extend damper manufacturing backward integration to protect margin pools from contract manufacturer concentration risk. Secure trivalent chromium anodizing capacity in Stuttgart-area finish houses before ECHA sunset dates eliminate chromate alternatives. Channel control through OEM specification agreements with Canyon and YT Industries defends against direct-to-consumer compression of aftermarket volumes. For New Entrants and Emerging Players: Begin with sensor-integrated smart fork development targeting Indian Himalayan trail rental fleets where coil-spring durability requirements meet unserved electronic damping demand. White-space exists in modular fork architectures with replaceable bushings for EU Green Deal circularity compliance. Go-to-market through Pune and Chennai assembly partnerships bypasses established distributor networks. For Investors and Strategic Acquirers: The window for entry favors precision hub-to-fork system integrators with captive carbon fiber layup automation. Long-term viability hinges on e-bike load rating certification above 120 kg system weight. Acquisition targets should demonstrate ISO 4210 fatigue validation timelines under 20 weeks. Watch for damper tuning specialist scarcity forcing compensation inflation above 15% annually as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Damper Manufacturing | Fox Factory's in-house production insulates margin from Taiwanese OEM concentration. |
| REACH-Compliant Coating Transition | Trivalent chromium qualification in Grenoble industrial zones secures EU market access. |
| Sensor-Integrated Smart Fork Launch | Electronic valving with accelerometer telemetry commands premium positioning in German assembly. |
| Modular Fork Architecture Development | Replaceable bushings and cartridge dampers align with EU Green Deal take-back mandates. |
| Indian Market Distribution Partnership | Uttarakhand and Maharashtra trail development creates first-mover hardtail positioning. |
Research Methodology
Document review covered SEC 10-K filings from component manufacturers, EU ECHA substance restriction databases, and GB standards documentation, complemented by interviews with suspension product managers at frame builders, procurement leads at Taiwanese contract manufacturers, aftermarket distribution heads in Colorado and Bavaria, and damper tuning specialists in Stuttgart-area R&D facilities. Secondary sources included customs trade data for aluminum alloy imports, ISO 4210 certification registries, and municipal trail infrastructure spending disclosures. Bottom-up unit economics modeling triangulated against top-down market sizing from OEM specification rates.
Cross-referencing historical replacement cycle data with panel input from specialty retailers established the forecast framework across the analysis window. Segmentation dimensions modeled include suspension architecture, material grade, technology tier, and end-user category with e-bike load rating distinction. CAGRs derived from trajectory fitting to documented OEM spec rate changes and trail infrastructure investment correlations. Industry-specific inputs incorporated REACH sunset date impacts on coating cost structures and carbon fiber tape placement automation adoption curves.
Aluminum LME price swings, ECHA substance restriction enforcement variance, and e-bike classification rule changes in Germany, the United States, and China are the dominant revision risks to installed base and replacement demand assumptions. Deviation in Taiwanese OEM production continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Balance Bike Market
Sports Equipment
GCC Running Gear Market
Sports Equipment
Bicycle Crankset Market
Sports Equipment
Mixed Martial Arts Equipment Market
Sports Equipment
Germany Horse Riding Equipment Market
Sports Equipment
Global Kinesio Tape Market
Sports Equipment
Clay Pigeon Thrower Market
Sports Equipment
Sports Protection Equipment Market
Sports Equipment
Cleat Market
Sports Equipment
Bowling Lane Panels Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Dirt Bike Market
Sports Equipment
Archery Equipment Market
Sports Equipment
Wave Windsurf Boards Market
Sports Equipment
Licensed Sports Merchandise Market
Sports Equipment
Pitching Machine Market