
 Global Wakeboarding Equipment Market | 2026-2036
Global Wakeboarding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wakeboarding Equipment Market Outlook
Capital-intensity divergence between in-house composite manufacturing and outsourced assembly is bifurcating competitive tiers. Hyperlite leverages captive production of fiberglass layups to control board consistency and margin capture. Ronix Wakeboards differentiates through proprietary foam core formulations that reduce weight without sacrificing flex durability. Liquid Force anchors its position by operating dedicated binding mold facilities that shorten iteration cycles for pro-model releases.
Wakeboarding equipment comprises boards, bindings, ropes, and protective vests engineered for hydrodynamic performance and impact absorption, with boards typically built from layered fiberglass or carbon fiber over polyurethane or PVC foam cores pressed under vacuum-bag consolidation. This equipment serves competitive athletes, recreational riders, instructional schools, and rental fleets requiring calibrated flex patterns, buoyancy ratings, and tensile strength for safe towed-water sport execution. Boards and bindings together command the dominant value share, while carbon fiber constructions represent the fastest-growing material tier as riders prioritize reduced swing weight. Distribution through specialty stores retains the highest service-attachment rates for fitting and customization, though online retail channels are gaining share among replacement-ropes and accessory purchases.
ISO 12402 personal flotation device standards, REACH chemical compliance for foam additives, and U.S. Coast Guard buoyancy certifications shape product design mandates and market access conditions across manufacturing jurisdictions. The EU Green Deal's emerging restrictions on persistent organic compounds in water-sport textiles will cascade into binding strap and vest fabric specifications within European supply chains. Stakeholders must monitor regulatory divergence between North American and European safety certification paths when configuring regional product portfolios and testing budgets.
Market Dynamics
Cable park infrastructure expansion across the United States, Australia, and Germany is compressing replacement cycles and redirecting equipment procurement toward rental-grade durability specifications.
Growth Catalysts
- REACH-compliant foam formulations:ECHA-mandated chemical safety standards are accelerating R&D investment in bio-based polyurethane alternatives, opening premium positioning for compliant manufacturers.
- Cable park proliferation:Purpose-built tow infrastructure in Florida, Queensland, and Bavaria is generating concentrated equipment demand from recreational user segments.
- Carbon fiber layup automation:Vacuum-bag consolidation robotics are reducing board-weight variance and enabling scalable production of high-performance constructions.
Market Restraints
- Petrochemical input volatility:Polyurethane and PVC foam core materials expose margins to crude oil derivative price swings without long-term supply contracts.
- Asian composite concentration:Fiberglass and carbon fiber pre-preg sourcing clusters in China create geopolitical and logistics vulnerability for Western assemblers.
- ISO 12402 certification timelines:Extended buoyancy testing protocols delay new vest launches by 8-14 months, constraining seasonal inventory positioning.
Strategic Opportunities
- Brazilian coastal expansion:Underdeveloped wake school density in Rio de Janeiro and Florianopolis presents first-mover equipment placement potential.
- EU Green Deal textile restrictions:Emerging persistent organic compound limits for binding straps and vest fabrics will reward early reformulation adopters with regulatory preference.
- Direct-to-consumer binding customization:3D foot-scanning integration with modular mold systems enables mass-customization at standard price points.
Industry Challenges
- Composite technician scarcity:Vacuum-bag layup expertise concentration among aging craftspeople in Florida and California limits production scaling.
- Multi-jurisdiction certification burden:Parallel U.S. Coast Guard, ISO, and CE marking requirements fragment testing budgets and delay unified product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wakeboarding Equipment Market |
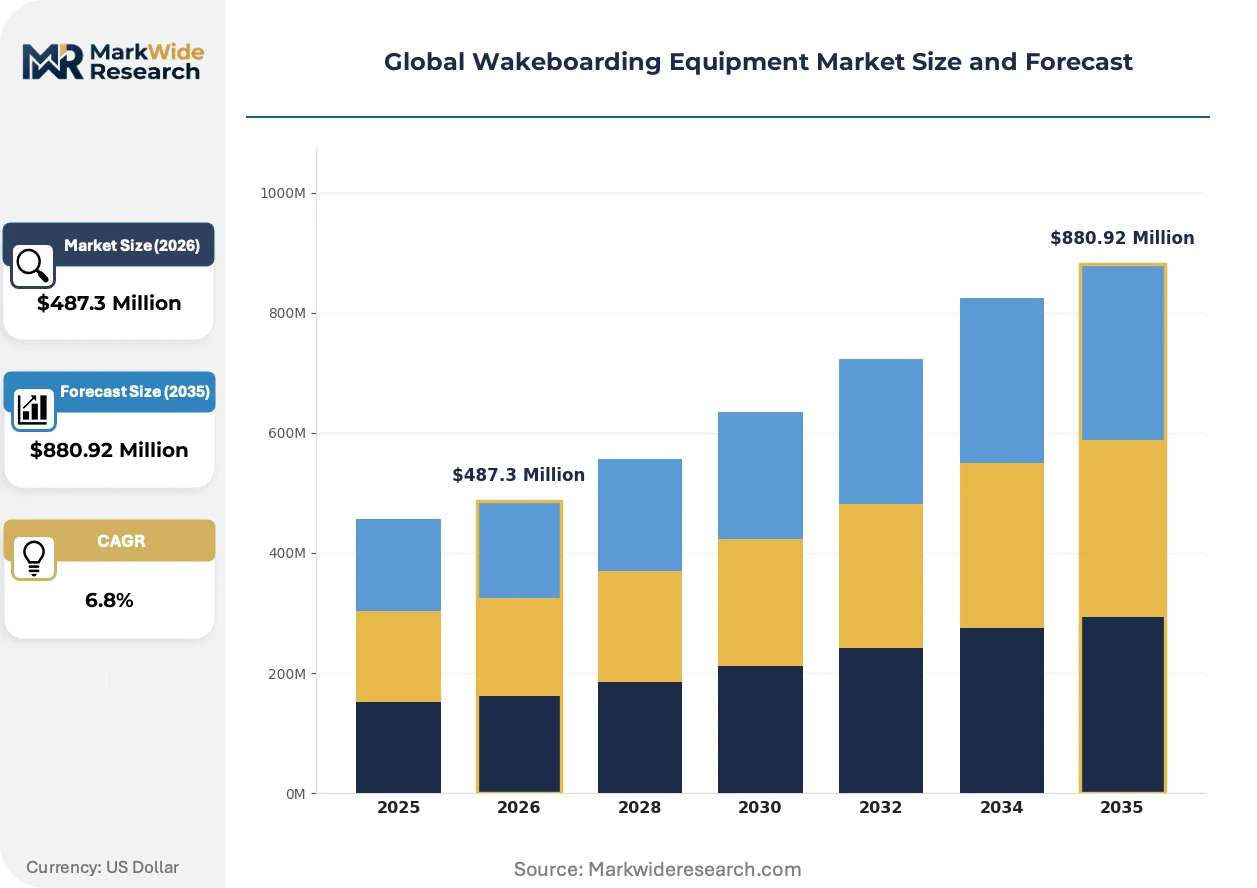
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boards, Bindings, Ropes, Vests Customer Type: Professional Athletes, Recreational Users, Schools, Rental Services Material: Fiberglass, Foam, Carbon Fiber, Plastic Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Hyperlite, Ronix Wakeboards, Liquid Force, HO Sports, O’Brien Watersports, Slingshot Sports, Airhead, Boardriders, Jobe Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wakeboarding Equipment Market Strategic Shifts
Material substitution and regulatory chemistry mandates are compressing traditional manufacturing timelines while opening differentiation pathways for compliant producers.
Pre-impregnated carbon fiber sheets with optimized resin-to-fiber ratios are supplanting hand-laid fiberglass in high-end board constructions. Competitive athletes and cable park rental fleets are accelerating adoption to reduce swing weight and extend equipment service intervals. This shift is compressing margin structures for fiberglass-dependent assemblers unable to retool layup operations.
ECHA's evolving REACH annex restrictions on isocyanate-based foam catalysts are forcing core supplier reformulations across European supply chains. Manufacturers serving EU distribution channels must requalify polyurethane and PVC foam specifications or risk market exclusion. German and French wake school operators are already specifying REACH-compliant equipment in procurement tenders.
Rental fleet operators are consolidating vendor relationships and demanding performance guarantees over raw unit economics. Specialty retailers with fitting expertise are losing share to direct manufacturer partnerships for high-volume cable park accounts. This concentration is most visible in Florida and Queensland where multi-location operators standardize across single-supplier frameworks.
Global Wakeboarding Equipment Market Segmentation
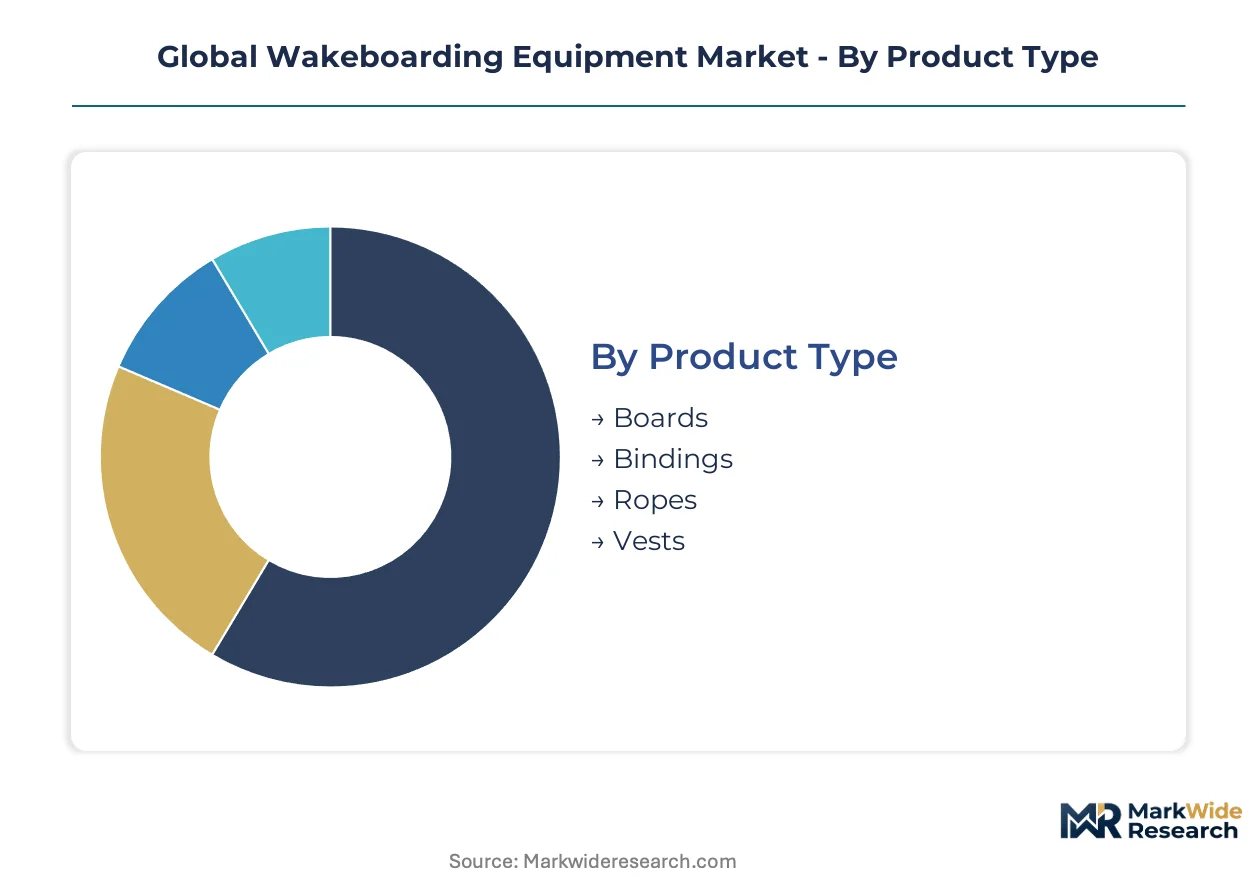
Wakeboarding equipment segmentation reveals divergent compliance burdens and margin structures across product categories. Material specifications and distribution channel economics create distinct competitive battlegrounds that reward specialized positioning.
Product Type:
ISO 12402 buoyancy mandates and REACH foam catalyst restrictions split certification timelines and R&D allocation across equipment categories.
- Boards:Vacuum-bag consolidated fiberglass or carbon fiber over polyurethane cores defines construction. Cable parks in Florida and Queensland drive volume toward rental-grade durability specifications with extended flex-cycle warranties.
- Bindings:Modular plate systems with thermoplastic or composite chassis enable stance customization. German wake schools specify REACH-compliant strap polymers ahead of EU Green Deal textile enforcement, compressing supplier qualification windows.
- Ropes:Spectra or Dyneema braided lines with EVA foam handles for grip absorption.
- Vests:Segmented foam panels with zippered or pullover closures meeting U.S. Coast Guard buoyancy ratings.
Established volume favors Boards; emerging adoption favors Bindings as customization specifications tighten.
Customer Type:
Procurement authority concentrates differently across user categories, with institutional buyers wielding consolidated volume leverage against fragmented individual purchases.
- Recreational Users:Individual riders purchasing through specialty retailers or direct channels. Australian cable park membership growth is redirecting this segment toward rental-first trial before ownership commitment.
- Rental Services:Fleet operators at multi-location cable parks demanding standardized equipment with performance guarantees. Bavarian operators now consolidate vendor relationships across 3-5 locations to extract volume pricing.
- Professional Athletes:Sponsored riders receiving pro-model releases with custom flex patterns.
- Schools:Instructional programs requiring durable beginner-grade boards with forgiving edge profiles.
Procurement consolidation favors Rental Services; margin capture favors Professional Athletes through sponsorship-linked premium positioning.
Material:
Petrochemical input exposure and automation readiness differentiate material tiers on cost stability and scalable precision.
- Carbon Fiber:Pre-impregnated sheets with optimized resin-to-fiber ratios pressed under automated vacuum-bag consolidation. Competitive athletes and high-end recreational riders in the United States prioritize reduced swing weight, accelerating substitution from hand-laid alternatives.
- Fiberglass:E-glass or S-glass woven cloth with polyester or epoxy resin hand layup. Technician scarcity in Florida and California constrains production scaling for this labor-intensive tier.
- Foam:Polyurethane or PVC core materials subject to REACH isocyanate catalyst restrictions.
- Plastic:Injection-molded binding chassis and rope handle components.
Performance differentiation favors Carbon Fiber; cost accessibility favors Fiberglass amid composite technician constraints.
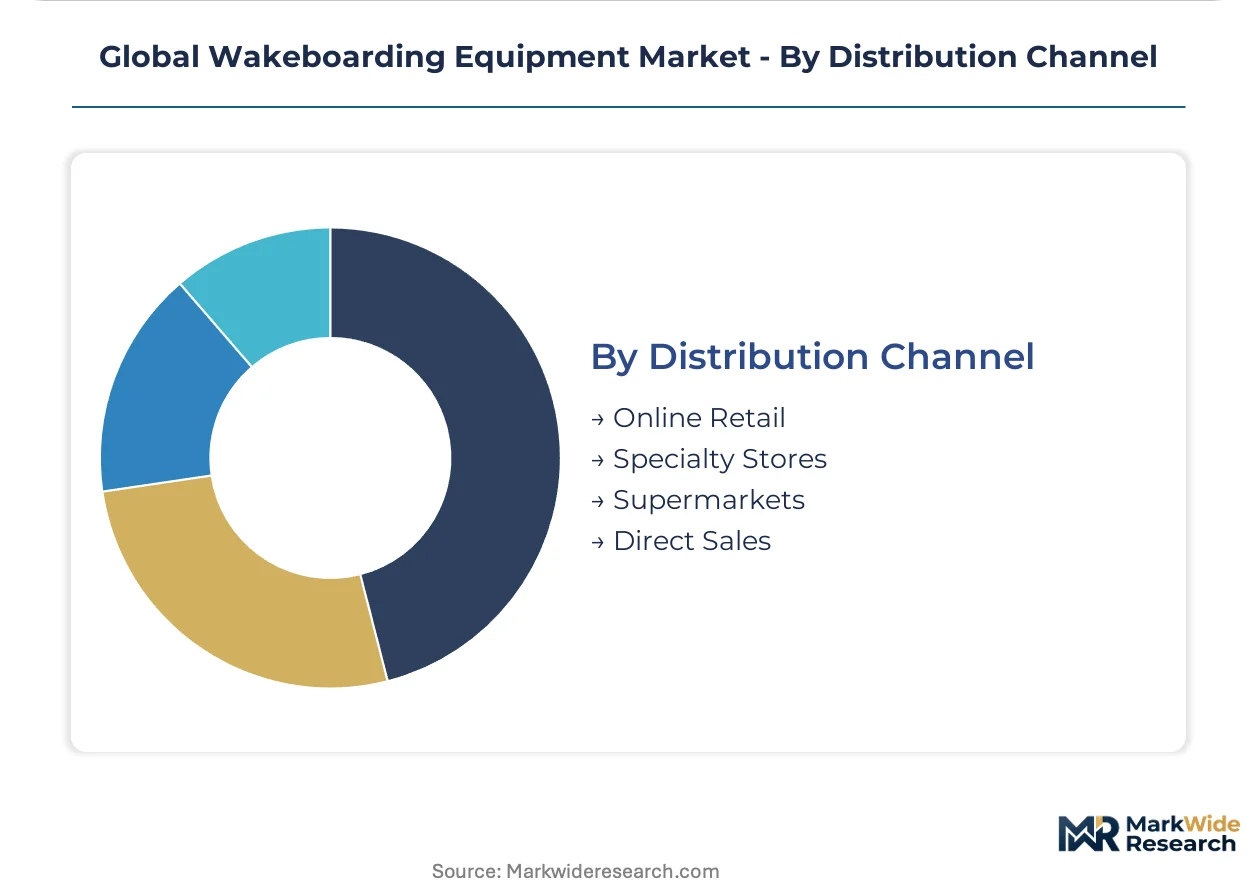
Distribution Channel:
Service attachment rates and inventory velocity separate channel economics, with fitting expertise commanding premium capture against transactional efficiency.
- Specialty Stores:Staffed fitting bays with stance measurement and boot heat-molding services. United States coastal markets retain this channel for binding customization despite online encroachment on replacement ropes.
- Online Retail:Direct-to-consumer platforms with 3D foot-scanning integration for modular binding configuration. German and Australian riders adopt this channel fastest for accessory replenishment.
- Direct Sales:Manufacturer partnerships with cable park operators for fleet standardization.
- Supermarkets:Mass retail with limited SKU depth for entry-level recreational purchases.
Service revenue favors Specialty Stores; volume scaling favors Online Retail as replacement purchase behavior shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Australia where cable park density supports premium equipment turnover, while emerging markets compete on entry-grade volume. Regulatory divergence between U.S. Coast Guard buoyancy mandates and EU REACH chemical restrictions fragments certification costs across manufacturing jurisdictions.
United States
Florida's cable park corridor and California's competitive event calendar sustain replacement demand for high-performance boards and bindings. The U.S. Coast Guard enforces Type III personal flotation device standards that extend vest certification timelines by 8-14 months. Orlando and Tampa Bay operators now consolidate fleet procurement across multi-location frameworks to extract volume pricing from specialized manufacturers.
Germany
Bavarian wake school networks and Berlin-Brandenburg recreational lakes anchor European equipment demand with stringent durability specifications. ECHA's REACH annex restrictions on isocyanate-based foam catalysts force core supplier reformulations across domestic supply chains. Munich-based distributors increasingly specify REACH-compliant equipment in procurement tenders ahead of EU Green Deal textile enforcement.
Australia
Queensland's cable park membership growth and New South Wales coastal rental fleets redirect individual riders toward trial-before-ownership models. The country's national water safety regulator aligns with ISO 12402 buoyancy standards while maintaining separate import inspection protocols. Gold Coast manufacturers face technician scarcity in vacuum-bag layup operations that constrains carbon fiber board scaling.
Brazil
Rio de Janeiro and Florianopolis wake school underpenetration presents first-mover placement potential for rental-grade equipment suppliers. ANVISA oversees personal flotation device import registrations that parallel U.S. Coast Guard testing requirements without mutual recognition agreements. São Paulo distributors are establishing direct partnerships with cable park operators to bypass fragmented specialty retail channels.
United Arab Emirates
Dubai's artificial lagoon developments and Abu Dhabi waterfront tourism investments generate concentrated demand for instructional school equipment. MOHAP regulates recreational water sport safety gear through conformance with Gulf Standardization Organization buoyancy benchmarks. Jebel Ali manufacturing free zones attract composite assemblers seeking duty-efficient re-export positioning toward African markets.
Global Wakeboarding Equipment Market Competitive Environment
Concentration sits with vertically integrated board manufacturers and specialized binding fabricators that control critical production stages. The vendor base stratifies across three tiers: captive composite producers, outsourced assemblers with design ownership, and pure distribution brands without manufacturing assets. Dominant competitive moves include backward integration into foam core production and exclusive partnerships with cable park chains for fleet standardization.
Among U.S.-based specialists, Hyperlite, Ronix Wakeboards, and Liquid Force occupy positions across the integrated manufacturing spectrum. Hyperlite exemplifies captive production archetypes through in-house fiberglass layup control. Ronix Wakeboards represents proprietary formulation specialists with differentiated core chemistry capabilities. Liquid Force anchors the dedicated tooling tier through specialized mold facility operations that compress pro-model iteration cycles.
| Leading Market Players |
|---|
| Hyperlite |
| Ronix Wakeboards |
| Liquid Force |
| HO Sports |
| O'Brien Watersports |
| Slingshot Sports |
| Airhead |
| Boardriders |
| Jobe Sports |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at automated vacuum-bag consolidation facilities in Florida and Bavaria compresses unit economics for carbon fiber board production while elevating price floors for hand-laid fiberglass alternatives. This scale asymmetry concentrates margin capture among integrated manufacturers with captive layup operations and forces smaller assemblers toward outsourced production models with thinner pricing power.
Pricing Analysis
The customization-premium spread between configured-to-order pro-model releases and standard retail SKUs spans three performance tiers anchored by material grade and certification level. Carbon fiber constructions with U.S. Coast Guard Type III buoyancy ratings command premium positioning against REACH-compliant rental-grade specifications in European procurement tenders. Cost compression in fiberglass-dependent tiers is intensifying because composite technician scarcity in Gold Coast and California constrains production scaling. Rental fleet operators exhibit lowest price sensitivity due to performance guarantee requirements, while individual recreational riders in Australian trial-before-ownership channels show highest elasticity.
Supply Chain Analysis
Strait of Malacca transit risk for pre-impregnated carbon fiber sheets sourced from Chinese and Taiwanese composite mills exposes Western assemblers to logistics disruption without dual-source qualification. Raw material dependencies rest on polyurethane foam cores from German chemical suppliers, fiberglass woven cloth from Chinese state-owned enterprises, and Spectra fiber rope braids from U.S. specialty polymer producers. Single-source vulnerability concentrates in E-glass pre-preg supply where three mills serve the global wakeboarding equipment base. Distribution runs through direct manufacturer partnerships with multi-location cable park operators for fleet standardization, bypassing fragmented specialty retail in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cable park infrastructure expansion across Florida, Queensland, and Bavaria signals early-cycle equipment penetration with recreational user adoption accelerating ahead of saturation thresholds. This infrastructure buildout creates sustained replacement demand as rental fleet operators consolidate vendor relationships and compress procurement cycles.
For Market Incumbents: Compound defensive positioning through backward integration into REACH-compliant foam core production and exclusive fleet standardization contracts with multi-location cable park operators. Emerging Brazilian coastal expansion threatens first-mover advantage for established brands without localized distribution partnerships. Certification investment in ISO 12402 buoyancy testing capabilities preserves seasonal inventory positioning against 8-14 month approval timelines.
For New Entrants and Emerging Players: Differentiate on modular binding customization with 3D foot-scanning integration targeting German and Australian direct-to-consumer channels. Brazilian wake school underpenetration in Rio de Janeiro and Florianopolis offers the most penetrable geography for rental-grade equipment placement. Go-to-market execution should anchor on direct partnerships with cable park operators to bypass fragmented specialty retail infrastructure.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated board manufacturers with captive carbon fiber layup capabilities and proprietary foam formulations. Long-term viability over a 5-10 year horizon rests on regulatory compliance agility as EU Green Deal textile restrictions cascade into binding strap specifications. The signal to watch is consolidation velocity among Bavarian and Queensland rental fleet operators as procurement standardization accelerates.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Foam Core Reformulation | ECHA-mandated catalyst restrictions force supplier requalification across European supply chains. |
| Automated Vacuum-Bag Consolidation Deployment | Robotics investment reduces board-weight variance for carbon fiber high-performance constructions. |
| Direct Cable Park Fleet Partnerships | Multi-location operator consolidation in Florida and Queensland extracts volume pricing leverage. |
| 3D Foot-Scanning Binding Customization | Mass-configuration capabilities capture German and Australian direct-to-consumer channel growth. |
| Brazilian Coastal Distribution Buildout | First-mover placement in Rio de Janeiro and Florianopolis wake school networks secures rental-grade share. |
Study Parameters
Desk research of trade customs data, SEC filings from watersport equipment manufacturers, and ECHA regulatory submissions preceded structured interviews with cable park fleet procurement managers, composite manufacturing engineers, and specialty retail buyers across the United States, Germany, and Australia. Primary fieldwork with wake school operators and rental fleet directors validated secondary demand estimates. Bottom-up equipment unit economics triangulated against top-down market value reconstruction.
Variance decomposition across material tiers, distribution channels, and customer segments structured the analytical framework over the projection horizon. Segmentation dimensions modeled include product category, material construction, procurement authority, and regional regulatory cluster. CAGRs derived from historical replacement cycle analysis and infrastructure investment pipelines. Industry-specific inputs incorporated cable park membership growth trajectories and REACH compliance transition timelines.
Decision-makers should treat outputs as directional under assumptions of sustained cable park infrastructure investment and stable petrochemical input pricing; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA foam catalyst restrictions and U.S. Coast Guard certification timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Tennis Equipment Market
Sports Equipment
Kickboxing Equipment Market
Sports Equipment
Global Darts Market
Sports Equipment
Global Basketball Shoes Market
Sports Equipment
Bicycle Helmet Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Tennis Racquet Market
Sports Equipment
Backboard Market
Sports Equipment
Winter Sporting Goods Market
Sports Equipment
Soccer Gear Market
Sports Equipment
Trail Shoes Market
Sports Equipment
Mouthguard Market
Sports Equipment
Bicycle Drivetrain Cassette Market
Sports Equipment
Kneeboard Market
Sports Equipment
Europe Ski Gear and Equipment Market
Sports Equipment
Boxing Gloves Market