
 Command and Control Systems Market | 2026-2036
Command and Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Command and Control Systems Market Intelligence
Multi-domain operations (MDO) compatibility is redrawing the competitive landscape for command and control systems. RTX Corporation leverages its extensive portfolio in aerospace and defense electronics to deliver integrated platforms. Thales Group differentiates through its strong presence in European and international markets with a focus on civilian and military applications. L3Harris Technologies specializes in secure communications and sensor integration, critical components for modern C2 systems.
Command and control systems are integrated networks of hardware, software, and procedures used by organizations to gather, process, and disseminate information for decision-making. These systems often incorporate IP Networking for data transmission and sophisticated data fusion algorithms to create a unified operational picture from multiple sensor inputs. While fixed command centers remain the largest system type by value, mobile command units are showing rapid uptake for tactical and disaster response scenarios. Defense agencies constitute the primary customer base, but demand from transportation authorities for critical infrastructure protection is expanding.
Interoperability is governed by standards from organizations like NATO, such as STANAGs, which ensure compatibility between allied forces' systems. In the United States, Department of Defense directives on cybersecurity and data architecture dictate procurement requirements, while in countries like India, BIS certification influences hardware sourcing. Vendors must navigate these complex, country-specific compliance pathways while investing in next-generation capabilities like autonomous system integration.
Market Dynamics
The fundamental shift from proprietary, hardware-centric architectures to open, software-defined networks is the central force shaping the command and control systems market. This transition prioritizes data interoperability and rapid capability insertion over the static, siloed systems of the past.
Growth Catalysts
- Defense Modernization:National initiatives, such as India's push for integrated defense platforms, are compelling military forces to replace legacy command structures with networked, multi-domain operational systems, creating sustained government-funded demand.
- Public Safety Coordination:An increasing frequency of large-scale emergencies and natural disasters is driving adoption by civilian agencies, which require sophisticated C2 systems for effective, multi-agency response and resource management.
- IP Networking Adoption:The widespread transition to Internet Protocol networking provides a common, flexible transport layer, simplifying the integration of diverse sensors, communication devices, and command platforms from different manufacturers.
Market Restraints
- High Integration Costs:The expense associated with integrating new C2 platforms with a diverse array of legacy sensors, communication systems, and databases presents a significant financial barrier for many organizations.
- Legacy System Interoperability:Many existing military and civilian systems were not designed for cross-platform communication, creating substantial technical hurdles and performance risks when attempting to build a unified operational picture.
- Complex Compliance Pathways:Vendors face long and expensive certification processes to meet varying standards, such as NATO STANAGs for allied interoperability and stringent US Department of Defense cybersecurity directives for system procurement.
Strategic Opportunities
- Critical Infrastructure Protection:Expanding systems beyond military use to civilian transportation authorities, energy grid operators, and port authorities offers a significant growth vector for protecting essential national infrastructure.
- Autonomous Systems Integration:The convergence of C2 platforms with unmanned aerial, ground, and maritime systems creates an opportunity to develop next-generation capabilities for autonomous reconnaissance, logistics, and tactical operations.
- Emerging Market Upgrades:Nations in Southeast Asia and Latin America are modernizing their defense and public safety capabilities, creating new market opportunities for vendors offering scalable and cost-effective command and control solutions.
Industry Challenges
- Specialized Talent Scarcity:A shortage of personnel with combined expertise in military operations, data science, cybersecurity, and software engineering hinders the development and effective operation of advanced C2 systems.
- Legacy Equipment Integration:The operational necessity of connecting modern, IP-based C2 systems to decades-old analog radios and sensor platforms creates profound engineering and software development challenges.
- Cybersecurity Vulnerabilities:The networked nature of modern C2 systems expands the attack surface for state-sponsored actors and cybercriminals, demanding continuous investment in advanced threat detection and resilient network architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Command and Control Systems Market |
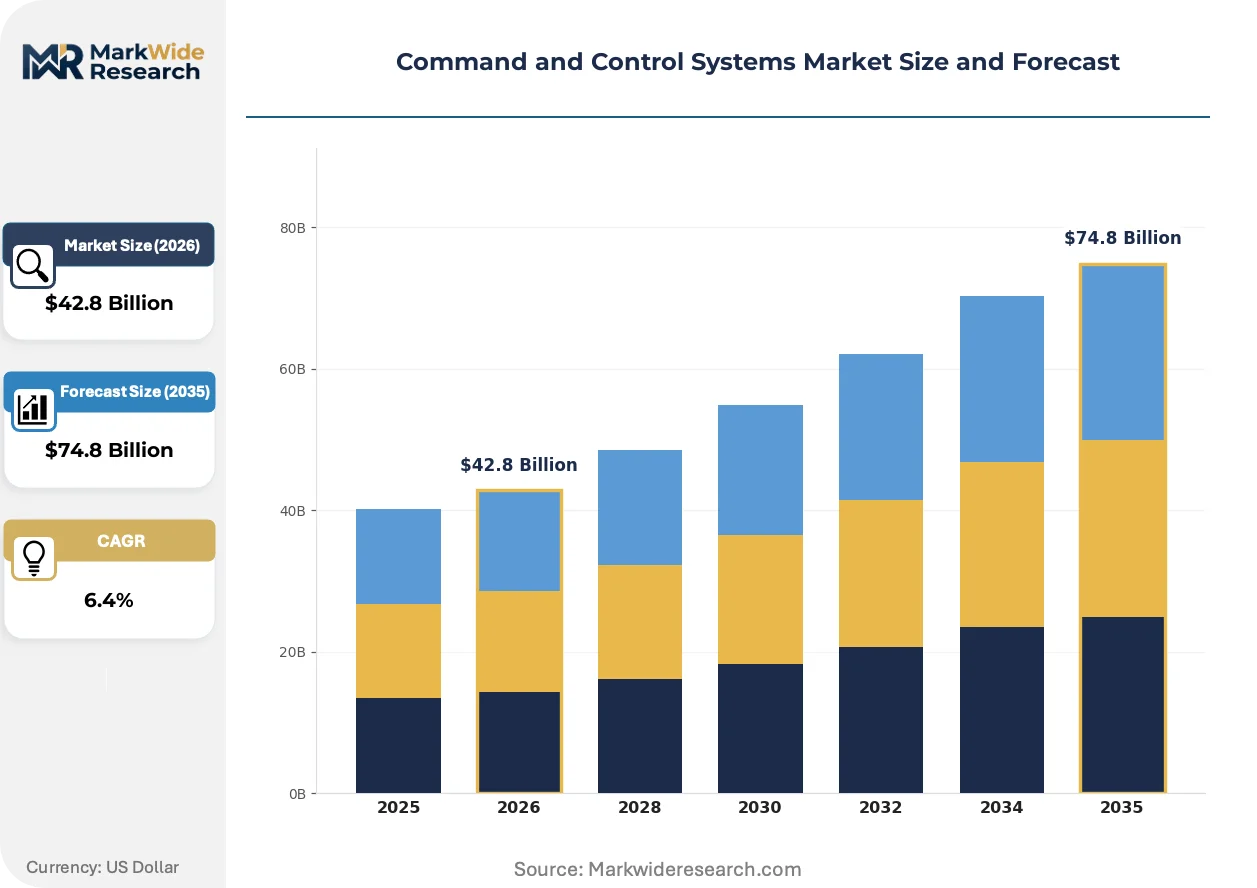
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Fixed Command Centers, Mobile Command Units, Remote Operation Systems, Integrated Control Platforms, Tactical Operations Hubs Technology: Radio Frequency, Satellite Communication, IP Networking, Data Fusion, Sensor Integration Use Case: Emergency Management, Border Surveillance, Maritime Security, Critical Infrastructure Protection, Public Safety Coordination Customer Type: Defense Agencies, Law Enforcement, Disaster Response Teams, Space Mission Control, Transportation Authorities |
| Companies Covered | L3Harris Technologies, RTX Corporation, Lockheed Martin Corporation, General Dynamics Corporation, Thales Group, BAE Systems, Northrop Grumman Corporation, Leonardo, Elbit Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Command and Control Systems Market Strategic Shifts & Innovations
The evolution of command and control is marked by a decisive pivot towards AI-driven decision support and software-defined architectures. This change prioritizes modularity and algorithmic superiority over the monolithic, hardware-dependent systems that previously dominated the field.
AI-powered data fusion algorithms provide the core function of synthesizing a unified operational picture from numerous, often conflicting, sensor inputs. Defense and intelligence agencies are rapidly adopting this technology to reduce cognitive load on operators and accelerate decision-making cycles. This software-led approach is decomposing the traditional, hardware-locked command system into modular, interoperable services that can be upgraded independently.
European Union's AI Act introduces a risk-based framework that directly impacts C2 systems deployed within the bloc. This regulation compels vendors to ensure their AI-driven decision support tools are transparent, explainable, and subject to human oversight, particularly in military or law enforcement applications. Consequently, suppliers targeting European security contracts are embedding robust audit and explainability features into their software architectures to prove compliance.
A significant behavioral shift is underway as government buyers move from single-vendor, multi-decade development programs to more agile acquisition models. The traditional procurement cycle is being disrupted by frameworks that favor open standards and continuous software updates from a diverse supplier ecosystem. This trend is most advanced within the United States Department of Defense and allied NATO forces, aiming to accelerate technology insertion and reduce long-term vendor lock-in.
Command and Control Systems Market Segmentation
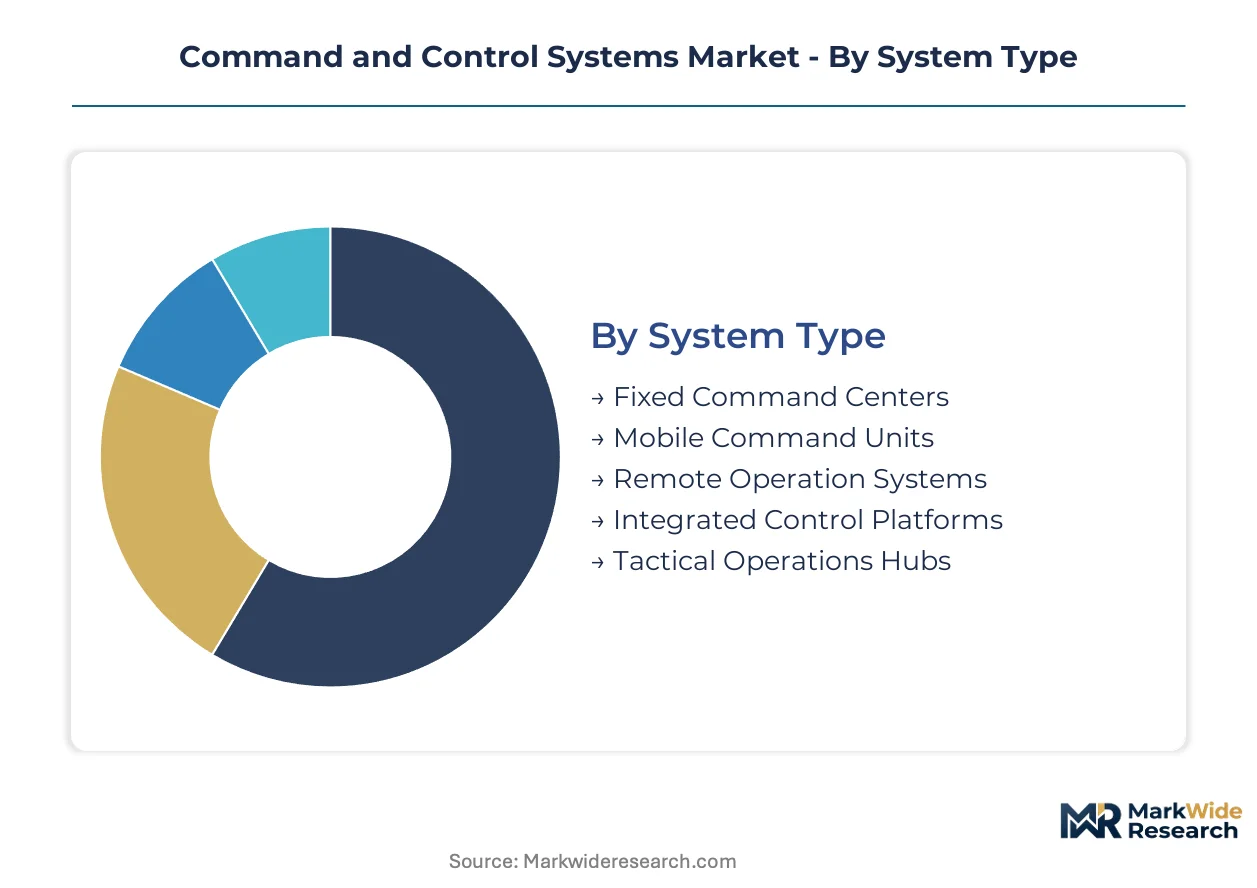
The Command and Control Systems market segmentation reveals distinct operational requirements and technological preferences across various end-user environments. Understanding these segments is critical for vendors to tailor solutions that meet specific functional demands and compliance mandates.
System Type:
Different system types exhibit varying degrees of global versus localized deployment, influenced by national defense strategies and disaster response priorities.
- Fixed Command Centers:These are permanent, hardened facilities equipped with extensive communication, data processing, and visualization tools, serving as central hubs for strategic oversight and long-term operations in countries like the United States and India. Demand concentrates in established defense and national security infrastructure, driven by the need for continuous, resilient command capabilities.
- Mobile Command Units:Self-contained, deployable systems often housed in vehicles or shelters, providing C2 capabilities for tactical operations or disaster response scenarios. These units see high demand from emergency services and military forces in regions prone to natural disasters, such as Japan and the Philippines, where rapid deployment and operational flexibility are paramount.
- Remote Operation Systems:These systems enable command and control of distant assets, such as unmanned vehicles or geographically dispersed sensors, from a centralized or distributed network.
- Integrated Control Platforms:Software and hardware architectures designed to unify disparate C2 components, sensors, and communication networks into a single operational picture.
- Tactical Operations Hubs:Smaller, often temporary, command posts established close to the front lines or incident sites for immediate, localized decision-making and resource coordination.
Fixed Command Centers holds the largest share; momentum sits with Mobile Command Units.
Technology:
Technology differentiation often correlates with development costs, impacting system affordability and market penetration across different economic regions.
- IP Networking:This technology forms the backbone for modern C2 systems, facilitating high-speed, secure data exchange between diverse platforms, sensors, and command centers. The widespread adoption of IP Networking in both military and civilian applications, including NATO forces and critical infrastructure operators, drives its market leadership.
- Data Fusion:Algorithms and processes that combine information from multiple, disparate sources to produce a more accurate and comprehensive operational picture. Data fusion capabilities are increasingly sought after by intelligence agencies and defense ministries in countries like France and Germany to enhance situational awareness and reduce decision-making time.
- Radio Frequency:Traditional communication methods utilizing radio waves for voice and data transmission, often used for tactical communications and in environments where IP networks are unavailable or compromised.
- Satellite Communication:Provides long-range, secure communication capabilities for C2 systems, essential for operations in remote areas or across vast geographical distances.
- Sensor Integration:The process of connecting and harmonizing various sensor types (e.g., radar, optical, acoustic) to a central C2 system for comprehensive data collection and analysis.
IP Networking maintains a dominant position, while Data Fusion capabilities are expanding most quickly.
Use Case:
The diverse use cases for command and control systems reflect their adaptability across a spectrum of operational requirements, from national security to civilian protection.
- Emergency Management:C2 systems are vital for coordinating multi-agency responses to natural disasters, public health crises, and large-scale incidents. Agencies in countries such as Australia and Canada rely on these systems for efficient resource allocation and communication during emergencies.
- Critical Infrastructure Protection:Deployment of C2 solutions to monitor and manage security for essential assets like power grids, transportation networks, and water treatment facilities. Transportation authorities in the United Kingdom and Singapore are integrating C2 for real-time threat detection and response.
- Border Surveillance:Utilized by national border agencies to monitor and control vast land and maritime borders, integrating sensor data and communication platforms for threat detection.
- Maritime Security:C2 systems enhance situational awareness and response capabilities for naval forces and coast guards, managing surveillance, interdiction, and search and rescue operations.
- Public Safety Coordination:Supports law enforcement and public safety agencies in managing large events, daily operations, and responding to criminal activities.
Emergency Management represents the largest application area, with Critical Infrastructure Protection gaining share fastest.
Customer Type:
Customer types drive demand volumes based on their operational scale and budget allocations, influencing procurement patterns for C2 solutions.
- Defense Agencies:Military organizations, navies, and air forces globally constitute the primary customer base, requiring sophisticated C2 systems for multi-domain operations, intelligence gathering, and weapon system control. Defense modernization programs in nations such as South Korea and Brazil continuously fuel demand for advanced integrated platforms.
- Transportation Authorities:Entities responsible for managing and securing national transportation networks, including airports, seaports, and railway systems. These authorities, such as those in Germany and the United Arab Emirates, procure C2 systems for traffic management, security monitoring, and incident response.
- Law Enforcement:Police forces and other security agencies utilize C2 systems for dispatch, incident management, and coordinated response to criminal activity and public order situations.
- Disaster Response Teams:Specialized governmental or non-governmental organizations focused on providing immediate relief and coordination during natural or man-made disasters.
- Space Mission Control:Agencies and private companies involved in space exploration and satellite operations, requiring precise C2 for spacecraft, launch vehicles, and ground support systems.
Defense Agencies remain the primary customer base, and Transportation Authorities are showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration in the command and control systems market primarily resides within nations possessing advanced defense industries and significant public safety infrastructure. These countries often lead in research, development, and deployment of sophisticated C2 platforms. Strategic investments in national security and disaster preparedness further solidify their market positions.
United States
Demand for C2 systems in the United States is driven by extensive Department of Defense modernization and critical infrastructure protection. DoD directives on cybersecurity and data architecture heavily influence procurement. Washington D.C. and surrounding areas host defense contractors and government agencies, fostering C2 technology innovation.
India
India's significant defense modernization programs propel demand for integrated command and control platforms. BIS certification influences hardware sourcing, ensuring national standards for critical components. Major defense manufacturing hubs like Bengaluru and Hyderabad actively develop indigenous C2 solutions for military applications.
Germany
European demand for C2 systems in Germany stems from defense requirements and expanding needs from transportation authorities. Data fusion capabilities are particularly sought by intelligence agencies and defense ministries to enhance situational awareness. Cities such as Munich and Berlin are centers for aerospace and defense technology, attracting C2 system development.
France
Thales Group's strong presence in France contributes to a robust market for civilian and military C2 applications, focusing on advanced data fusion. The EU AI Act introduces a risk-based framework impacting AI-driven decision support tools. Paris and Toulouse are key centers for defense electronics and aerospace industries, driving C2 innovation.
Japan
Rapid uptake of mobile command units for tactical and disaster response drives the C2 market in Japan, reflecting vulnerability to natural disasters. Government focus on disaster preparedness and public safety coordination necessitates sophisticated C2 systems. Tokyo and other major urban centers are hubs for emergency services and technology companies developing deployable C2 solutions.
Command and Control Systems Market Key Industry Players
Concentration sits with established aerospace and defense electronics firms, leveraging extensive portfolios and long-standing government contracts. The market structure exhibits characteristics of both consolidation among top-tier system integrators and fragmentation among specialized software and sensor providers. Strategic archetypes include large-scale prime contractors, niche technology specialists, and regional solution providers. Dominant competitive moves involve portfolio diversification into adjacent technologies and strategic partnerships for complex system integration.
Specialists in secure communications and sensor integration, such as L3Harris Technologies, exemplify the focus on critical C2 system components. RTX Corporation, through its extensive portfolio in aerospace and defense electronics, represents a prime contractor archetype delivering integrated platforms. Thales Group, with its strong presence in European and international markets, anchors the segment for both civilian and military C2 applications. These companies maintain significant market positions by continuously innovating in data fusion and multi-domain operations compatibility.
| Leading Market Players |
|---|
| L3Harris Technologies |
| RTX Corporation |
| Lockheed Martin Corporation |
| General Dynamics Corporation |
| Thales Group |
| BAE Systems |
| Northrop Grumman Corporation |
| Leonardo |
| Elbit Systems |
| Others |
Cost & Logistics Intelligence
Extended lead times for specialized sensor components directly influence pricing power for integrated platforms, shaping the supply chain towards regionalized manufacturing hubs. This dynamic forces vendors to balance customization needs with component availability and cost efficiencies.
Pricing Analysis
US Department of Defense directives dictate the pricing tier structure for advanced C2 systems, emphasizing performance-based contracts for complex integrations. The dominant pricing model is project-based, often incorporating long-term service agreements and licensing fees. Price differentiation drivers include the level of customization required for multi-domain operations and the certification level for secure communications. Pricing softness reflects intensified competition among prime contractors for large government tenders. Defense agencies exhibit the least price sensitivity, prioritizing capability and security, while transportation authorities are more price-sensitive, seeking cost-effective infrastructure protection.
Supply Chain Analysis
The United States and Germany anchor the production of high-end C2 software and advanced data fusion algorithms, leveraging their strong defense technology bases. Raw material and component dependencies include specialized microprocessors for data processing and secure communication modules. A structural supply chain risk is single-source vulnerability for proprietary cryptographic hardware, which can impact system integrity and availability. Distribution runs through direct-to-government contracts and specialized system integrators, ensuring secure delivery and implementation for sensitive applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The command and control systems market represents a high-growth disruption, driven by the fundamental shift towards open, software-defined networks and AI-driven decision support.
For Market Incumbents: Fortify core platform offerings by integrating advanced AI for data fusion and ensuring multi-domain operations compatibility. Invest heavily in cybersecurity capabilities to counter evolving threats and maintain trust with defense agencies. This strategy defends against agile software specialists and leverages existing government contracts for long-term R&D in autonomous system integration.
For New Entrants and Emerging Players: Unaddressed interoperability gaps between legacy systems and modern IP-based platforms present a significant entry point for specialized software firms. Target civilian emergency management and critical infrastructure protection sectors, particularly in emerging markets like Southeast Asia, with scalable and cost-effective solutions. A strong go-to-market angle involves developing open-source API platforms that simplify integration and reduce vendor lock-in for diverse customer bases.
For Investors and Strategic Acquirers: Carve-out targets emerge from large defense conglomerates shedding non-core C2 software divisions to streamline portfolios. The long-term viability of the C2 market, essential for national security and public safety for decades, makes these assets attractive. Focus on acquiring niche C2 software providers specializing in AI-driven decision support or secure communications. A key signal to watch is increased M&A activity in firms offering explainable AI and cybersecurity resilience for critical national systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Streamlines integration across diverse military and civilian C2 systems. |
| AI-Driven Data Fusion Investment | Enhances real-time situational awareness for defense agencies. |
| Cybersecurity Resilience Development | Protects critical national infrastructure from state-sponsored attacks. |
| Strategic Partnerships for Interoperability | Ensures compatibility between allied forces' C2 technologies. |
| Expansion into Civilian Critical Infrastructure | Diversifies revenue streams beyond traditional defense spending. |
Research Approach
Operator-level perspectives from defense procurement officers, emergency management directors, C2 system engineers, and cybersecurity specialists anchored the qualitative base of this study. Primary interviews with industry stakeholders were validated against secondary data from NATO STANAGs, US Department of Defense directives, BIS certification documents, and company annual reports. This approach employed both bottom-up market sizing and top-down validation to ensure comprehensive data triangulation.
Sensitivity analysis informed the quantitative model, evaluating market responses to varying technological adoption rates and geopolitical scenarios across the analysis window. The analytical framework segmented the market by system type, technology, use case, customer type, and regional adoption patterns. Compound annual growth rates were derived from historical data extrapolation and future demand projections, with defense spending and critical infrastructure investment serving as key forecast inputs.
Forecasts assume regulatory continuity in US Department of Defense and EU AI Act regimes; material policy shifts would require re-modeling market dynamics. The analysis reflects assumptions regarding technological advancements and procurement cycles within the global defense and public safety sectors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
United States Defense Market
Defense and Military Systems and Equipment
Mergers and Acquisitions (Manda) in Aerospace and Defense Market
Defense and Military Systems and Equipment
India Defense Market
Defense and Military Systems and Equipment
Military Parachute Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market
Defense and Military Systems and Equipment
Bio-Defense Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal Market
Defense and Military Systems and Equipment
Counter-IED Systems Market
Defense and Military Systems and Equipment
Defense Tactical Computers Market
Defense and Military Systems and Equipment
Battle Management System (BMS) Market
Defense and Military Systems and Equipment
Soldier System Market
Defense and Military Systems and Equipment
Anti-Drone Guns Market
Defense and Military Systems and Equipment
Military Laser Systems Market
Defense and Military Systems and Equipment
Middle East and Africa Defense Market
Defense and Military Systems and Equipment
Asia-Pacific Digital Battlefield Market
Defense and Military Systems and Equipment
Global Military Defense Vehicle Intercom System Market