
 Infiniband Market | 2026-2036
Infiniband Market Size, Share, and Industry Trends Forecast 2026-2036
Infiniband Market Intelligence
The CHIPS and Science Act in the United States is hardening the supply chain security requirements for high-performance computing components, affecting vendor selection. NVIDIA Corporation leverages its comprehensive software stack to create a powerful ecosystem around its hardware. Intel Corporation competes by offering integrated solutions that span from processors to interconnects. Hewlett Packard Enterprise positions its offerings for large-scale supercomputing projects and enterprise data centers, specializing in system-level integration.
Infiniband is a computer networking communications standard designed for high-performance computing environments. The technology utilizes a switched fabric topology and Remote Direct Memory Access (RDMA) to achieve high throughput and extremely low latency, often measured in microseconds. Its primary commercial purpose is to provide a high-speed interconnect for servers, storage systems, and processing nodes in data centers and supercomputers. Next Data Rate (NDR) technology leads new deployments, while High Performance Computing remains the core application, with scientific simulation demanding maximum interconnect bandwidth.
Hardware interoperability and safety are guided by standards from the International Electrotechnical Commission (IEC). In China, market access for switches and adapters requires compliance with national GB standards. Data protection regulations like the EU's GDPR indirectly shape network architecture design in facilities processing personal data. Stakeholders must now weigh the performance benefits against the total cost of ownership and ecosystem maturity when choosing between Infiniband and competing high-speed Ethernet solutions.
Market Dynamics
The central tension in the Infiniband market is between the insatiable bandwidth demand from artificial intelligence workloads and the increasing viability of high-speed Ethernet as a competing interconnect technology for large-scale data centers.
Growth Catalysts
- Artificial Intelligence Workloads:The exponential growth of large language models and complex scientific simulations requires the ultra-low latency and high throughput that Infiniband provides for inter-node communication.
- Government Initiatives:Policies like the CHIPS and Science Act in the United States aim to secure the high-performance computing supply chain, favoring specialized and secure components for national infrastructure.
- Supercomputing Expansion:New national supercomputing centers in Germany, Japan, and the United States are being built around Infiniband fabrics to support large-scale, data-intensive research projects.
Market Restraints
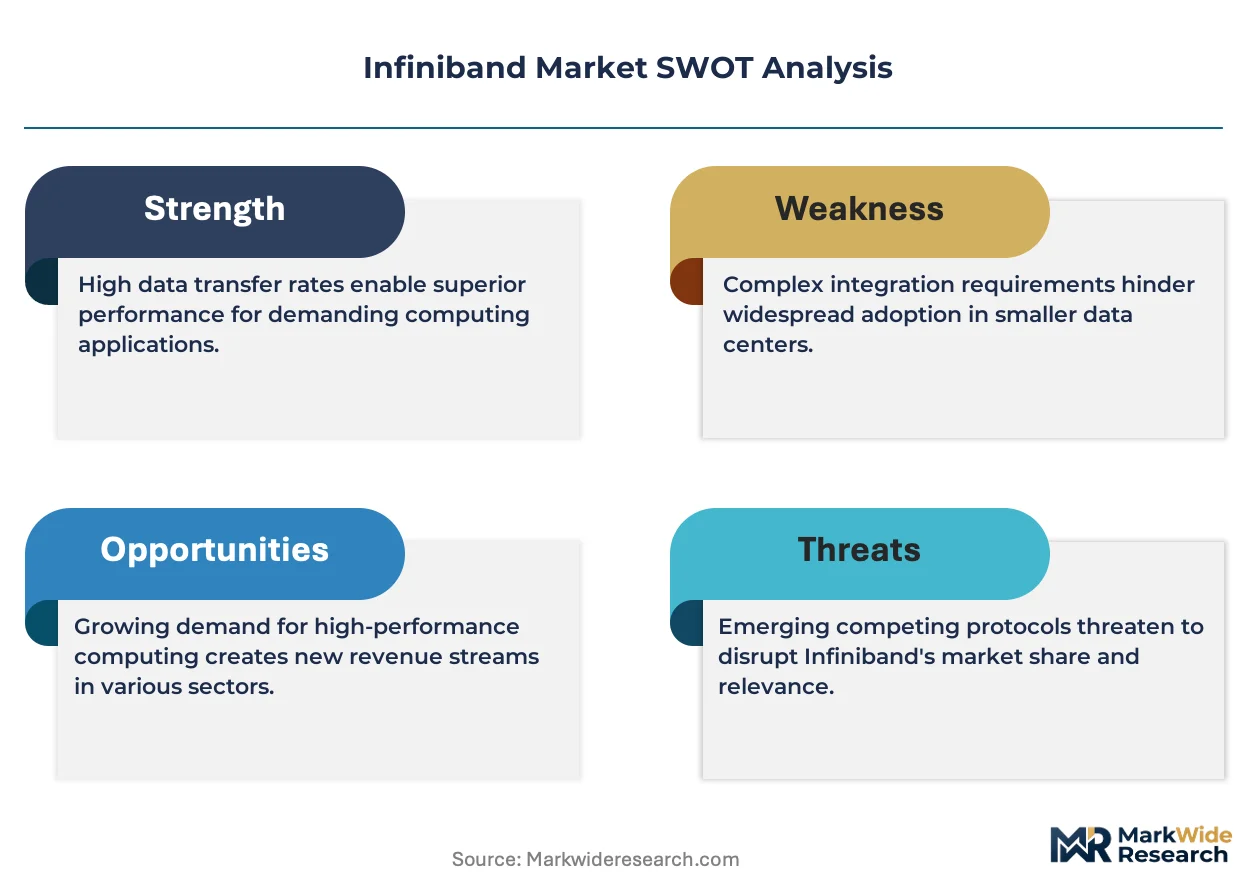
- Ethernet Competition:The primary restraint is the strong substitution threat from high-speed Ethernet, which benefits from a larger ecosystem, broader enterprise familiarity, and a more diverse vendor landscape.
- Cost Structure:A higher total cost of ownership, encompassing specialized adapters, switches, and cables, limits Infiniband adoption primarily to performance-critical applications, excluding many general enterprise workloads.
- Ecosystem Maturity:Compared to the vast and open Ethernet ecosystem, the more concentrated Infiniband vendor space can create buyer concerns regarding interoperability and long-term supply chain risk.
Strategic Opportunities
- Enterprise AI Pods:The deployment of smaller, dedicated AI training clusters within enterprises represents a significant growth vector beyond traditional academic and government high-performance computing environments.
- Sovereign Cloud Infrastructure:National initiatives to build sovereign clouds create demand for high-performance, secure networking fabrics that can be controlled within national borders, aligning with Infiniband's strengths.
- Storage Fabric Convergence:Tightly integrating Infiniband with next-generation storage solutions offers a pathway to create highly efficient, converged data center architectures optimized for data-intensive tasks.
Industry Challenges
- Specialized Skill Scarcity:Managing, tuning, and troubleshooting Infiniband fabrics requires a deep level of networking expertise that is not widely available, creating an operational bottleneck for some organizations.
- Integration Complexity:Integrating high-performance Infiniband clusters with existing enterprise Ethernet networks presents significant technical and architectural complexity for IT infrastructure teams.
- Compliance Documentation:Adhering to regulations like the EU AI Act for high-risk systems adds a layer of documentation and validation overhead for the network infrastructure supporting those applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infiniband Market |
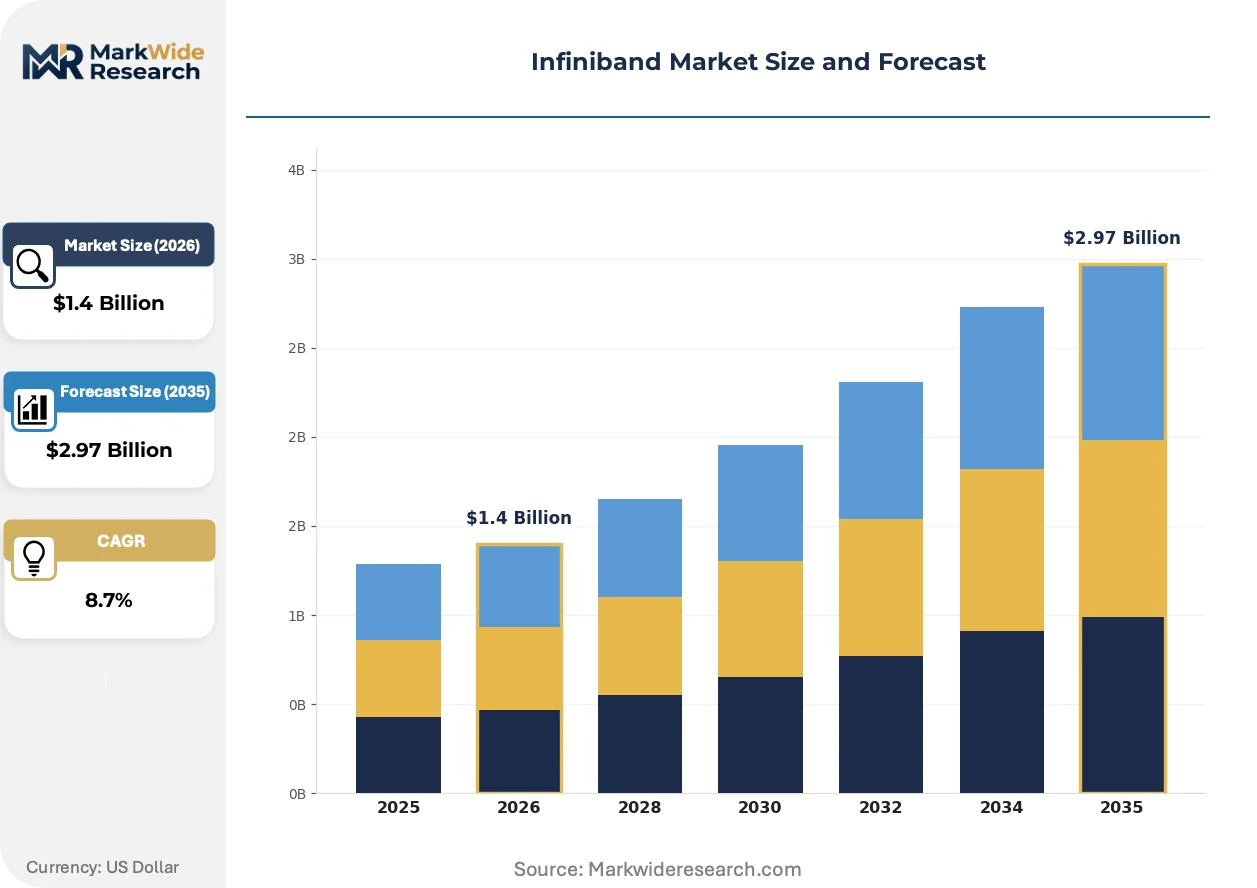
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Switches, Host Channel Adapters, Cables, Routers, Bridges Technology: HDR, FDR, EDR, NDR, SDR Application: High Performance Computing, Cloud Data Centers, Machine Learning, Scientific Simulation, Financial Modeling End User: Supercomputing Facilities, Research Institutions, Cloud Service Providers, Financial Firms, Telecommunications |
| Companies Covered | NVIDIA Corporation, Intel Corporation, Cisco Systems, Hewlett Packard Enterprise, IBM Corporation, Oracle Corporation, Dell Technologies, Broadcom Inc., Arista Networks, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infiniband Market Strategic Shifts & Innovations
Ecosystem-level integration is defining the market trajectory, as vendors build complete hardware and software stacks to simplify the deployment and management of complex AI and high-performance computing environments.
Next Data Rate (NDR) technology provides unprecedented bandwidth and reduced network latency for compute-intensive tasks. Supercomputing facilities and hyperscale cloud providers are the primary adopters, seeking to maximize performance for AI model training. This advancement is electrifying performance benchmarks, enabling the development of larger and more complex scientific simulations and AI models.
The EU AI Act introduces stringent requirements for systems classified as high-risk, impacting the underlying infrastructure. This regulation forces data center operators within the European Union to prioritize network fabrics that offer verifiable reliability, security, and auditable performance. High-performance computing clusters used for critical research or public services are most directly affected by these compliance demands.
A notable shift in acquisition strategy involves moving from individual component procurement to purchasing fully integrated, rack-scale systems. This trend disrupts the traditional role of in-house IT teams in system integration, favoring pre-validated solutions from system manufacturers. This pattern is particularly strong in government and academic procurements in the United States and Germany.
Infiniband Market Segmentation
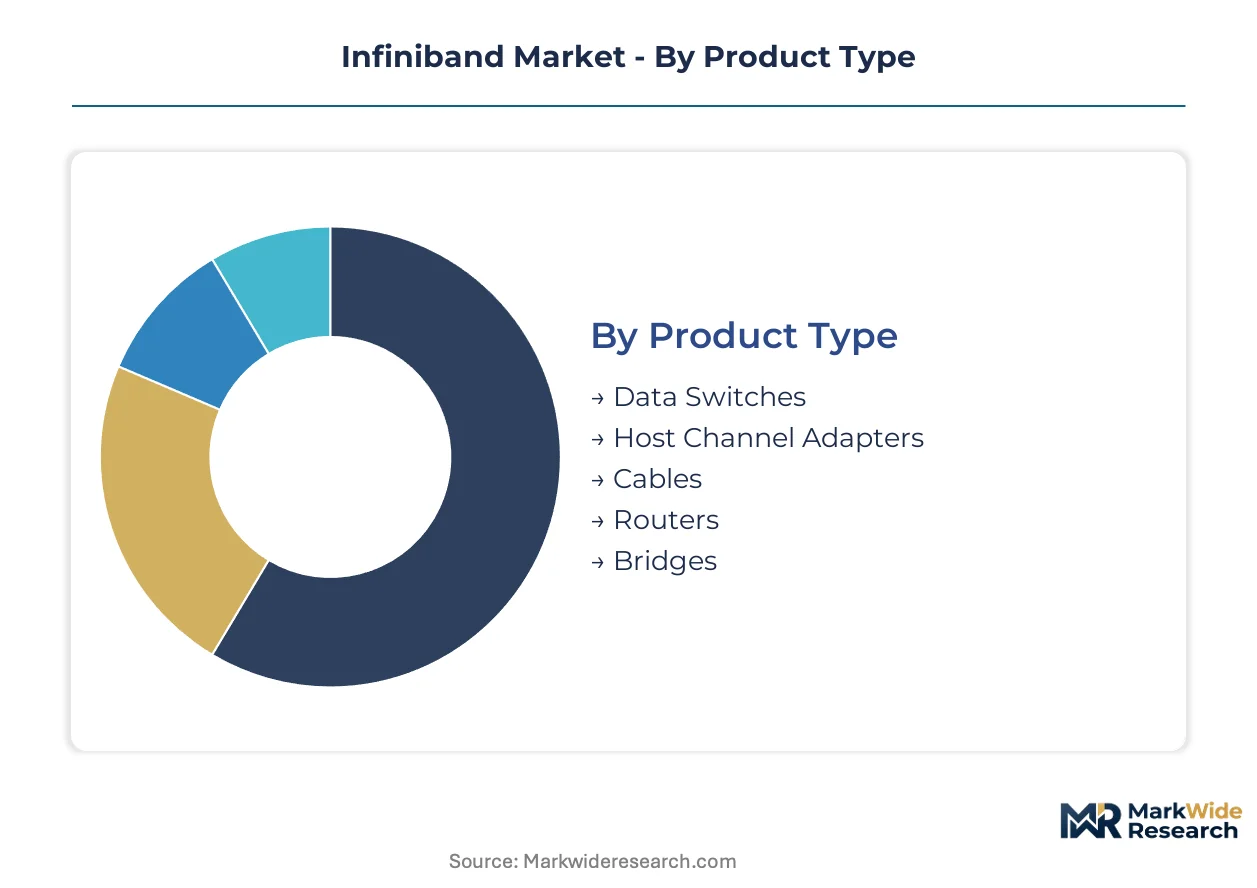
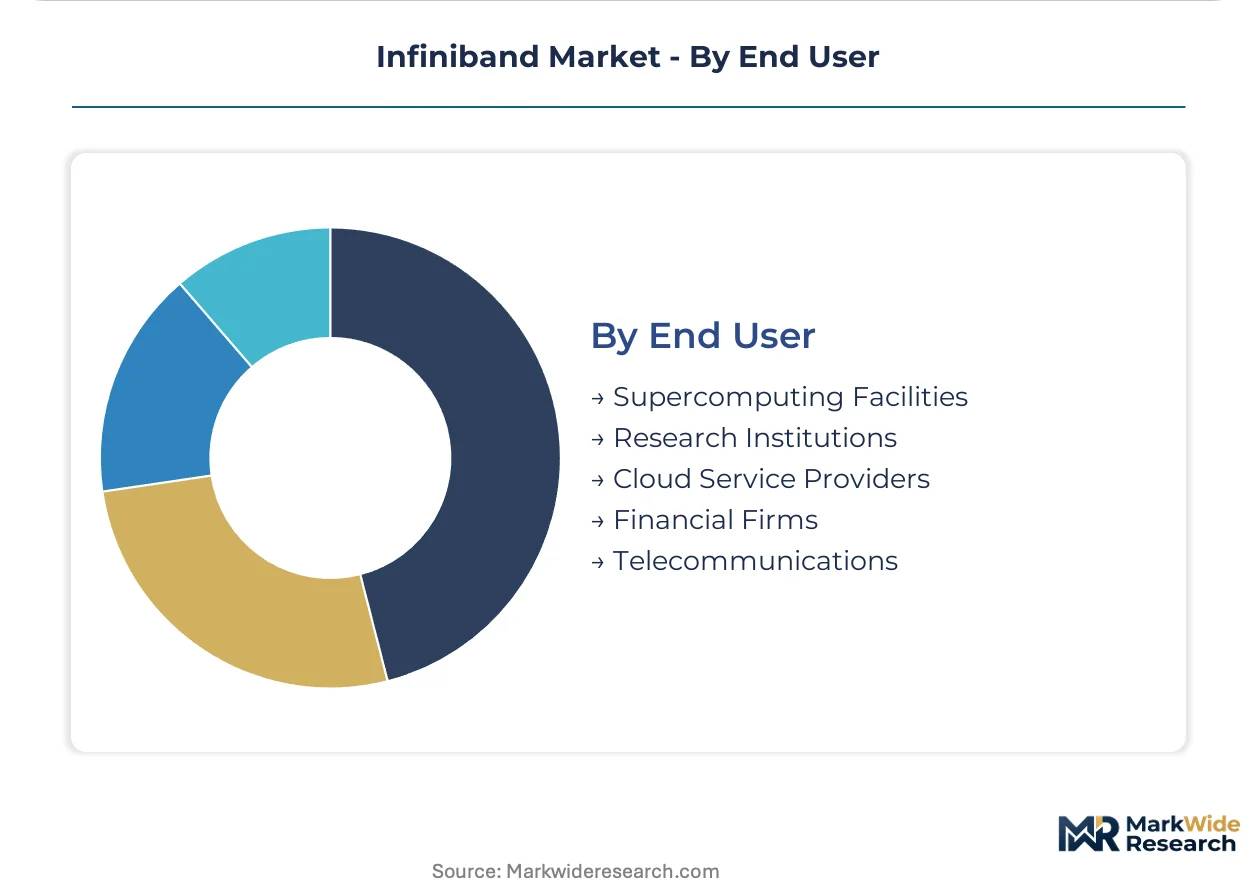
The Infiniband market's segmentation reveals the precise components, technological iterations, and end-use cases driving its specialized growth. Understanding these distinctions is critical for vendors to align product development with evolving performance demands in high-performance computing environments.
Product Type:
The Infiniband market's product segmentation highlights the specialized hardware components essential for high-speed data transfer.
- Data Switches:These form the backbone of an Infiniband fabric, directing data packets between connected nodes with ultra-low latency. Supercomputing facilities and large-scale AI clusters heavily rely on robust data switches for inter-node communication efficiency.
- Host Channel Adapters:HCAs are network interface cards that enable servers and storage systems to connect to the Infiniband fabric. Their advanced offload capabilities and RDMA support are crucial for maximizing application performance in data-intensive workloads.
- Cables:Specialized copper and optical cables provide the physical connectivity for Infiniband networks, ensuring signal integrity over various distances.
- Routers:Infiniband routers facilitate communication between different Infiniband subnets or connect Infiniband fabrics to external Ethernet networks.
- Bridges:Bridges allow Infiniband networks to interoperate with other network technologies, such as Fibre Channel, for storage connectivity.
Data Switches lead on scale; Host Channel Adapters lead on momentum.
Technology:
Technology advancements within Infiniband directly influence the performance capabilities for demanding applications.
- NDR:Next Data Rate (NDR) is the latest generation, offering 400 Gb/s per port, significantly reducing latency and boosting throughput. New supercomputing facilities in the United States and Germany are rapidly deploying NDR technology to support cutting-edge AI and scientific simulations.
- HDR:High Data Rate (HDR) provides 200 Gb/s per port and remains a prevalent technology in many high-performance computing clusters. Many existing cloud data centers continue to expand their infrastructure with HDR solutions due to its proven reliability.
- FDR:Fourteen Data Rate (FDR) offers 56 Gb/s and is found in an extensive installed base within research institutions and older supercomputers.
- EDR:Enhanced Data Rate (EDR) delivers 100 Gb/s per port and is commonly used in enterprise AI pods for dedicated training clusters.
- SDR:Single Data Rate (SDR) is an older standard, providing 10 Gb/s, typically present in legacy systems or less demanding applications.
NDR technology represents the fastest-growing trajectory in terms of deployment.
Application:
User demand for specific computational outcomes drives the adoption of Infiniband across various application domains.
- High Performance Computing:HPC applications, including scientific modeling and complex engineering simulations, are the foundational users of Infiniband for its unparalleled speed. National laboratories in Japan and Europe rely on Infiniband for their large-scale research projects.
- Machine Learning:The training of large language models and deep neural networks requires massive inter-node communication, making Infiniband ideal for AI workloads. Enterprise AI pods are increasingly leveraging Infiniband for their dedicated training clusters.
- Cloud Data Centers:Hyperscale cloud providers utilize Infiniband for specific high-performance tiers or specialized AI services within their vast infrastructure.
- Scientific Simulation:This segment includes climate modeling, molecular dynamics, and astrophysics, all requiring maximum interconnect bandwidth.
- Financial Modeling:High-frequency trading and complex risk analysis in financial firms demand ultra-low latency networking to gain competitive advantages.
High Performance Computing forms the foundational demand, while Machine Learning applications are expanding most quickly.
End User:
Infrastructure investment patterns by different entities shape the end-user landscape for Infiniband solutions.
- Supercomputing Facilities:These national and academic centers are the primary consumers, building vast Infiniband fabrics for petascale and exascale computing. New facilities in the United States are concentrating their deployments around Infiniband.
- Research Institutions:Universities and specialized research labs deploy Infiniband for their computational clusters supporting various scientific disciplines. These institutions often prioritize performance for specific project requirements.
- Cloud Service Providers:Select CSPs integrate Infiniband into their offerings to provide high-performance computing as a service for their most demanding clients. Sovereign cloud initiatives are also driving demand for secure, high-speed fabrics.
- Financial Firms:Investment banks and trading houses use Infiniband for their critical low-latency trading platforms and data analytics engines.
- Telecommunications:Telcos may deploy Infiniband in specialized data processing units or for network function virtualization infrastructure requiring high throughput.
Supercomputing Facilities remain the largest end-user segment, with Cloud Service Providers showing significant expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Infiniband market's lineage traces back to foundational high-performance computing initiatives, primarily concentrated in academic and government research centers. These early deployments in key global regions established the technological benchmarks for ultra-low latency networking. Today, demand continues to concentrate in countries investing heavily in advanced computational infrastructure.
United States
Artificial intelligence workloads and national security applications drive Infiniband demand in the United States. The CHIPS and Science Act hardens supply chain security for HPC components. New supercomputing facilities at Oak Ridge and Argonne National Laboratories concentrate deployments.
Germany
Germany's scientific research sector and industrial AI initiatives fuel high-performance computing needs for Infiniband. The EU AI Act introduces compliance requirements for high-risk AI systems. The Jülich Supercomputing Centre rapidly deploys Next Data Rate (NDR) technology for cutting-edge simulations.
Japan
Scientific simulation, particularly in climate modeling and materials science, underpins Infiniband adoption across Japan. METI initiatives promote advanced HPC infrastructure for national competitiveness. RIKEN Center for Computational Science in Kobe remains a hub for large-scale Infiniband-based supercomputing.
China
China's expansive cloud data centers and accelerating domestic AI development require high-speed interconnects like Infiniband. Market access for switches and adapters in China requires compliance with national GB standards. Technology hubs in Beijing and Shanghai build large-scale AI clusters, driving demand for advanced fabrics.
France
European scientific collaboration and defense research projects increase demand for Infiniband in France. Data protection regulations like GDPR, alongside the EU AI Act, indirectly shape network architecture. The CEA operates significant HPC clusters for critical national research.
Infiniband Market Key Industry Players
The competitive structure tilts toward integrated solution providers, offering comprehensive hardware and software stacks. Diversified technology giants leverage extensive portfolios to cater to varied high-performance computing needs, from cloud to on-premise deployments. Specialized networking vendors also occupy positions, focusing on interconnect technologies and specific fabric components. Ecosystem development and strategic partnerships are dominant competitive moves among these players, alongside continuous technological innovation.
Integrated solution providers such as NVIDIA Corporation and Intel Corporation exemplify the market's emphasis on comprehensive offerings. NVIDIA leverages its software stack to create a powerful ecosystem around its hardware, simplifying deployment and management. Intel Corporation competes by offering integrated solutions spanning from processors to interconnects, targeting end-to-end performance. Hewlett Packard Enterprise (HPE) positions its offerings for large-scale supercomputing projects, specializing in system-level integration for enterprise data centers and government procurements.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Intel Corporation |
| Cisco Systems |
| Hewlett Packard Enterprise |
| IBM Corporation |
| Oracle Corporation |
| Dell Technologies |
| Broadcom Inc. |
| Arista Networks, Inc. |
Cost & Logistics Intelligence
Specialized component costs, particularly for high-speed optical transceivers, significantly influence the final pricing of Infiniband switches and adapters sold to supercomputing facilities and enterprise AI clusters. This cost structure flows directly from the concentrated manufacturing base for these advanced components.
Pricing Analysis
Project-based and long-term contract pricing dominates for large-scale Infiniband deployments in national supercomputing centers and hyperscale environments. Pricing differentiation stems from the performance tier, such as Next Data Rate (NDR) capabilities, and the extent of system-level integration provided by vendors. Pricing softness emerges in older technology generations like HDR and FDR due to increasing competition from high-speed Ethernet alternatives. Research institutions often exhibit higher price sensitivity compared to national laboratories or financial firms requiring ultra-low latency.
Supply Chain Analysis
Refurbishment programs for Infiniband components, especially switches and Host Channel Adapters, extend product lifecycles and manage electronic waste. Geographic supply concentration for critical components centers in Taiwan, the United States, and Japan. The supply chain relies heavily on specialized semiconductor fabrication and advanced optical transceiver modules. Single-source vulnerability for cutting-edge interconnect chips presents a significant structural risk. Distribution runs through specialized system integrators and direct sales channels targeting large enterprise and government clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Infiniband market offers geographic arbitrage opportunities, leveraging lower operational costs for data center infrastructure in some regions compared to the stringent compliance requirements of the EU AI Act in Europe.
For Market Incumbents: Cement leadership through continuous research and development in next-generation technologies, pushing beyond current NDR capabilities to maintain a performance edge. Strengthen ecosystem lock-in with comprehensive software stacks and specialized professional services, mitigating the threat from high-speed Ethernet. Investing in vertical integration for critical component manufacturing can further secure supply and enhance cost control.
For New Entrants and Emerging Players: Launch via niche application focus, targeting enterprise AI pods or sovereign cloud initiatives with specialized, cost-effective solutions. Focus on specific segments where Infiniband's performance edge is non-negotiable, such as high-frequency trading or smaller scientific simulations. Partner with system integrators offering pre-validated, rack-scale solutions to simplify integration for less experienced IT teams.
For Investors and Strategic Acquirers: Roll-up economics work for specialized component manufacturers because the market exhibits concentrated demand for high-performance interconnects. The market remains viable over a 5-10 year window driven by persistent demand from AI and supercomputing workloads. Seek out innovative Host Channel Adapter and switch developers with strong intellectual property in RDMA and low-latency fabrics. Monitor the adoption rate of NDR-equivalent Ethernet solutions as an inflection indicator for competitive pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Ecosystem Integration | Enhances vendor lock-in and simplifies deployment for complex AI environments. |
| Next-Gen Interconnect R&D | Maintains performance leadership against competing high-speed Ethernet technologies. |
| Supply Chain Hardening | Secures critical component availability, especially for national security applications. |
| Specialized AI Fabric Solutions | Captures growth in enterprise AI pods and dedicated machine learning clusters. |
| Compliance-Driven Offerings | Addresses stringent regulatory requirements like the EU AI Act for high-risk systems. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Engaged CTOs, data center architects, HPC facility managers, and procurement leads across key regions provided direct industry perspectives. Reviewed government HPC funding reports, SEC filings of major vendors, IEC standards documentation, and national AI strategies. Bottom-up market sizing was triangulated with top-down industry expenditure analyses.
The forecast period was anchored to established historical data points, providing a robust foundation for future projections across the analysis window. The market was modeled by product type, technology generation (NDR, HDR), application (HPC, Machine Learning), end-user, and regional supercomputing investment patterns. Compound annual growth rates were derived from a multi-factor regression analysis, incorporating technological adoption curves. Forecast inputs included projected AI compute demand and planned supercomputing facility expansions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid technological shifts or unforeseen regulatory changes. Projections reflect current market understanding and assumptions regarding competitive dynamics. Practitioners should monitor hyperscale cloud provider interconnect strategies for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
5G Radio Unit Market
Telecom Hardware
Laser Communications Terminals (Lcts) Market
Telecom Hardware
Set-Top Box Market
Telecom Hardware
Telecom Electronic Manufacturing Services (EMS) Market
Telecom Hardware
Digital TV Soc Market
Telecom Hardware
Very Small Aperture Terminal (VSAT) Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
Europe Set-Top Box Market
Telecom Hardware
OTN Hardware Market
Telecom Hardware
Broadcast Antenna Market
Telecom Hardware
Global Microwave Transmission Equipment Market
Telecom Hardware
Repeaters Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
Global Virtualized Evolved Packet Core (VEPC) Market
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
Satellite Communication Terminal Market