
 Two-Wheeler Battery Market | 2026-2036
Two-Wheeler Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Two-Wheeler Battery Market Outlook
Electric scooter fleet deployment is recalibrating procurement patterns across the two-wheeler battery supply chain. Exide Industries Ltd leverages its lead-acid manufacturing scale to anchor replacement demand in India's vast motorcycle service network. GS Yuasa Corporation competes through deep specialization in absorbed glass mat technology for premium motorcycle OEM channels. Panasonic Corporation differentiates by controlling cylindrical cell supply for high-performance electric scooter platforms in East Asian markets.
Two-wheeler batteries store and discharge electrical energy through electrochemical cells housed in vibration-resistant casings, typically rated between 12V and 72V depending on vehicle class, with lithium-ion packs achieving 150-200 Wh/kg energy density for extended urban range requirements. Lead-acid products still occupy the bulk of motorcycle replacement cycles due to cost sensitivity and established recycling infrastructure, while lithium-ion chemistry is accelerating fastest among electric scooters where weight reduction and cycle life determine total ownership economics. Battery Management Systems technology is concentrating margin pools as OEMs and fleet operators demand real-time state-of-health monitoring to optimize asset utilization and prevent thermal incidents.
India's BIS certification mandates and PLI scheme for advanced chemistry cell production are reshaping local supply chain requirements and import substitution trajectories. China's GB standards for lithium-ion traction batteries and the EU's F-Gas Regulation on fluorinated greenhouse gases impose divergent compliance burdens on manufacturers serving multiple markets. Stakeholders must monitor how regulatory fragmentation between India's CEA safety protocols and Europe's REACH chemical restrictions influences cell chemistry selection and pack design standardization across export portfolios.
Market Dynamics
Lithium-ion chemistry is compressing lead-acid replacement cycles as electric scooter fleet operators in Southeast Asian cities impose new performance specifications on procurement tenders.
Growth Catalysts
- India's PLI scheme for advanced chemistry cells:Domestic manufacturing incentives are accelerating local cell production capacity and reducing import dependency for electric two-wheeler OEMs.
- Fleet electrification mandates:Urban last-mile delivery operators in Vietnam and Indonesia are specifying lithium-ion packs with minimum cycle-life thresholds in bulk procurement contracts.
- Battery Management Systems penetration:Real-time state-of-health monitoring is becoming a standard fleet requirement, pulling embedded electronics into pack economics.
Market Restraints
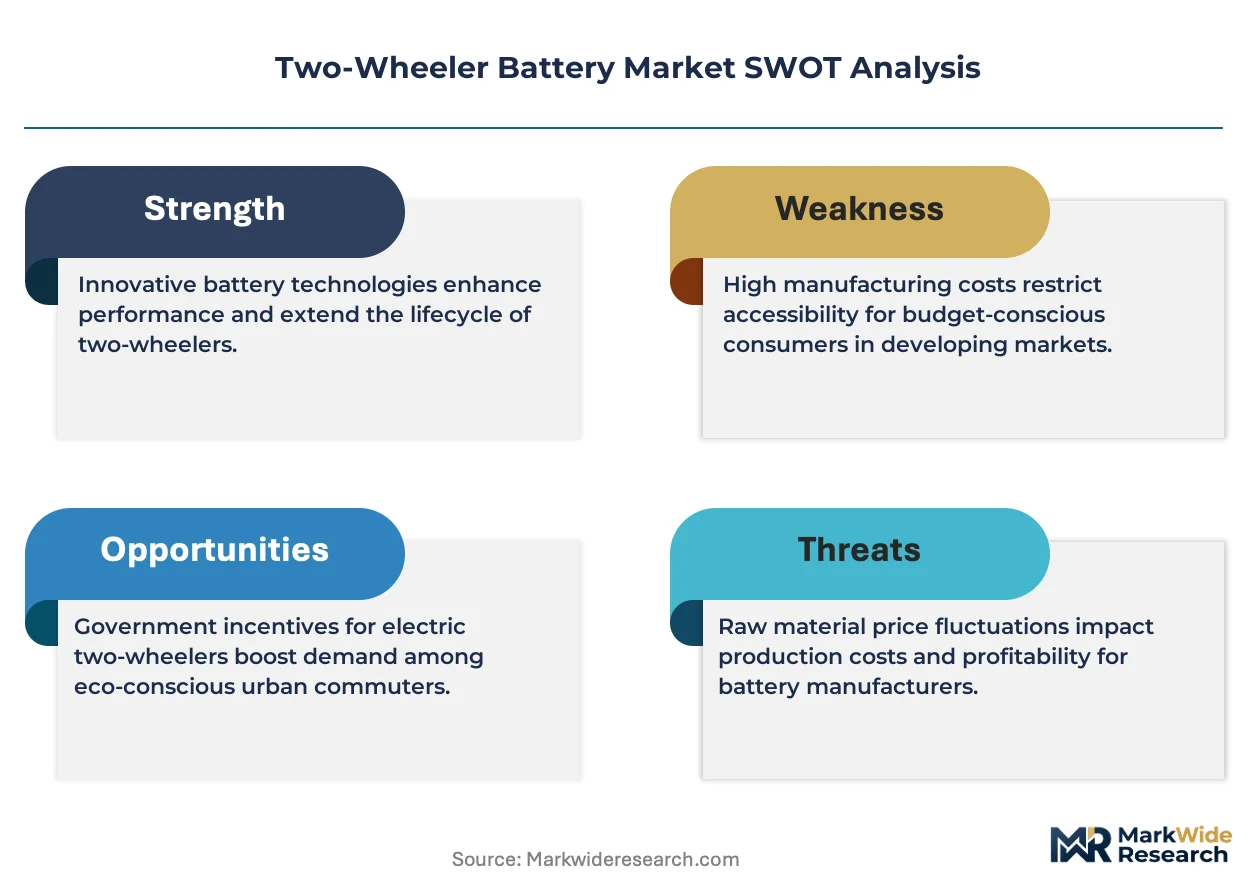
- Lithium carbonate price volatility:Raw material cost swings compress margin visibility for pack assemblers serving price-sensitive motorcycle replacement channels.
- Recycling infrastructure concentration:Lead-acid recovery networks remain concentrated in China and India, creating logistics friction for end-of-life lithium-ion packs elsewhere.
- CEA safety protocol fragmentation:Divergent thermal testing requirements between Indian central and state regulators delay product certification timelines.
Strategic Opportunities
- Indonesia's nickel processing expansion:Upstream cathode material integration offers cell manufacturers cost positioning for regional electric motorcycle supply.
- Swap-station network buildout:Battery-as-a-service models are opening asset-light entry paths for powertrain suppliers without direct vehicle OEM relationships.
- EU F-Gas Regulation compliance:Fluorinated gas restrictions on thermal management systems create first-mover advantage for air-cooled pack designs in European export markets.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell characterization and pack thermal modeling expertise concentrates in East Asian research clusters, constraining R&D scaling elsewhere.
- Dual chemistry certification burden:Manufacturers serving both lead-acid replacement and lithium-ion electric scooter segments face duplicative testing overhead under BIS and GB standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two-Wheeler Battery Market |
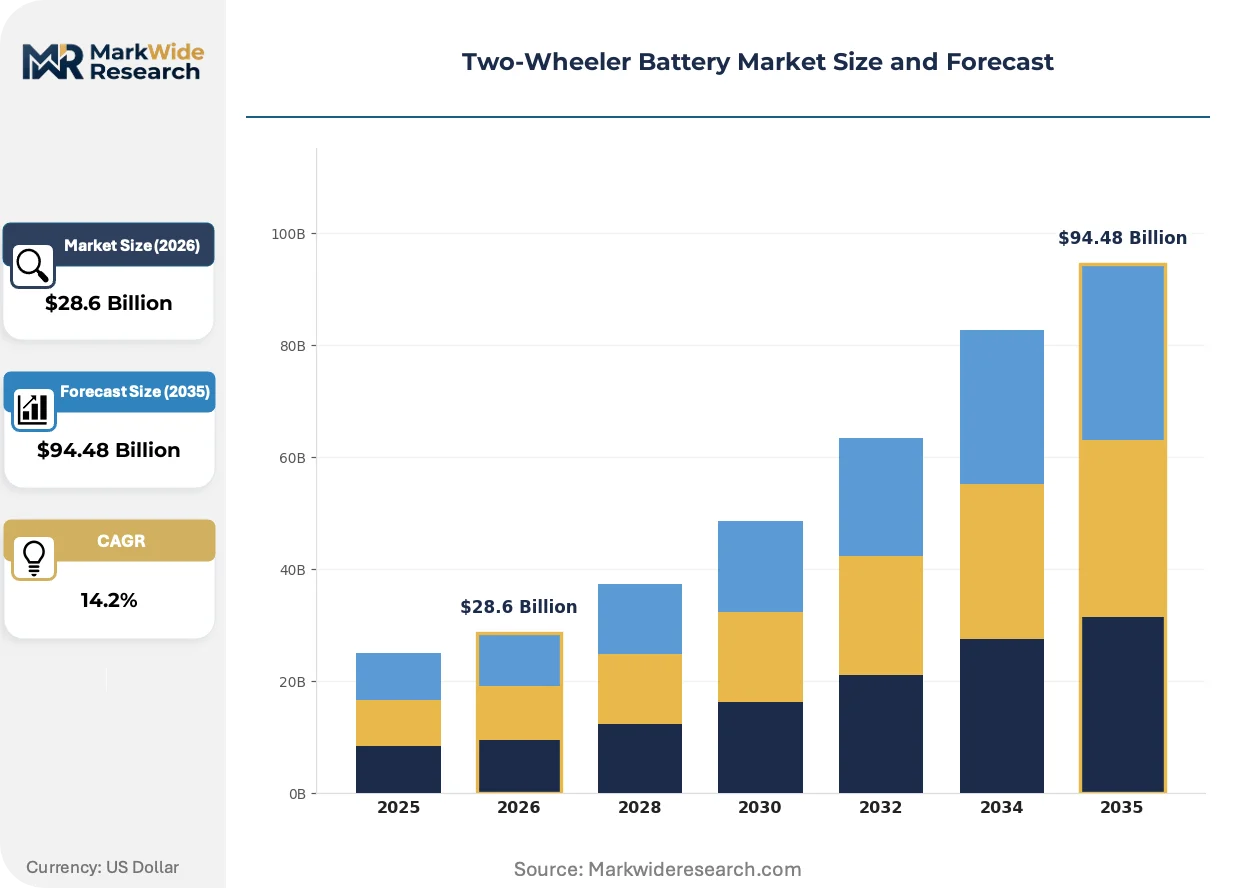
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Acid, Lithium-ion, Nickel-Metal Hydride, Gel End User: Private Users, Fleet Operators, Delivery Services, OEMs Application: Electric Scooters, Motorcycles, E-Bikes, Rideshare Technology: Smart Batteries, Fast Charging, Solar Integration, Battery Management Systems |
| Companies Covered | Exide Industries Ltd, Amara Raja Batteries Limited, GS Yuasa Corporation, Panasonic Corporation, Clarios, Robert Bosch GmbH, Tianneng Power International, DYNAVOLT Power, Leoch International Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two-Wheeler Battery Market Strategic Shifts
Electrification is fragmenting the traditional replacement cycle model as asset ownership structures diverge between private riders and fleet-managed pools.
Solid-state electrolyte research is integrating ceramic separator layers into prototype cells for high-voltage electric motorcycle platforms. Tier 1 suppliers in South Korea and Japan are piloting these configurations for premium sportbike OEMs. The technology is integrating thermal runaway suppression directly into cell architecture, compressing external BMS redundancy requirements.
India's BIS certification mandates for lithium-ion traction batteries are tightening cell-to-pack traceability requirements. The industrial consequence is a forced migration toward domestic module assembly to satisfy documentation protocols. Electric scooter OEMs serving government fleet tenders are most affected, with several restructuring supplier qualification programs to maintain bid eligibility.
Fleet operators are consolidating procurement decisions at the holding-company level rather than individual city depots. This buyer concentration is compressing supplier margins through volume-tiered contracting. The shift is most visible in Vietnam and Indonesia, where ride-hailing platforms are centralizing battery specification authority to negotiate unified service-level agreements across urban operating territories.
Two-Wheeler Battery Market Segmentation
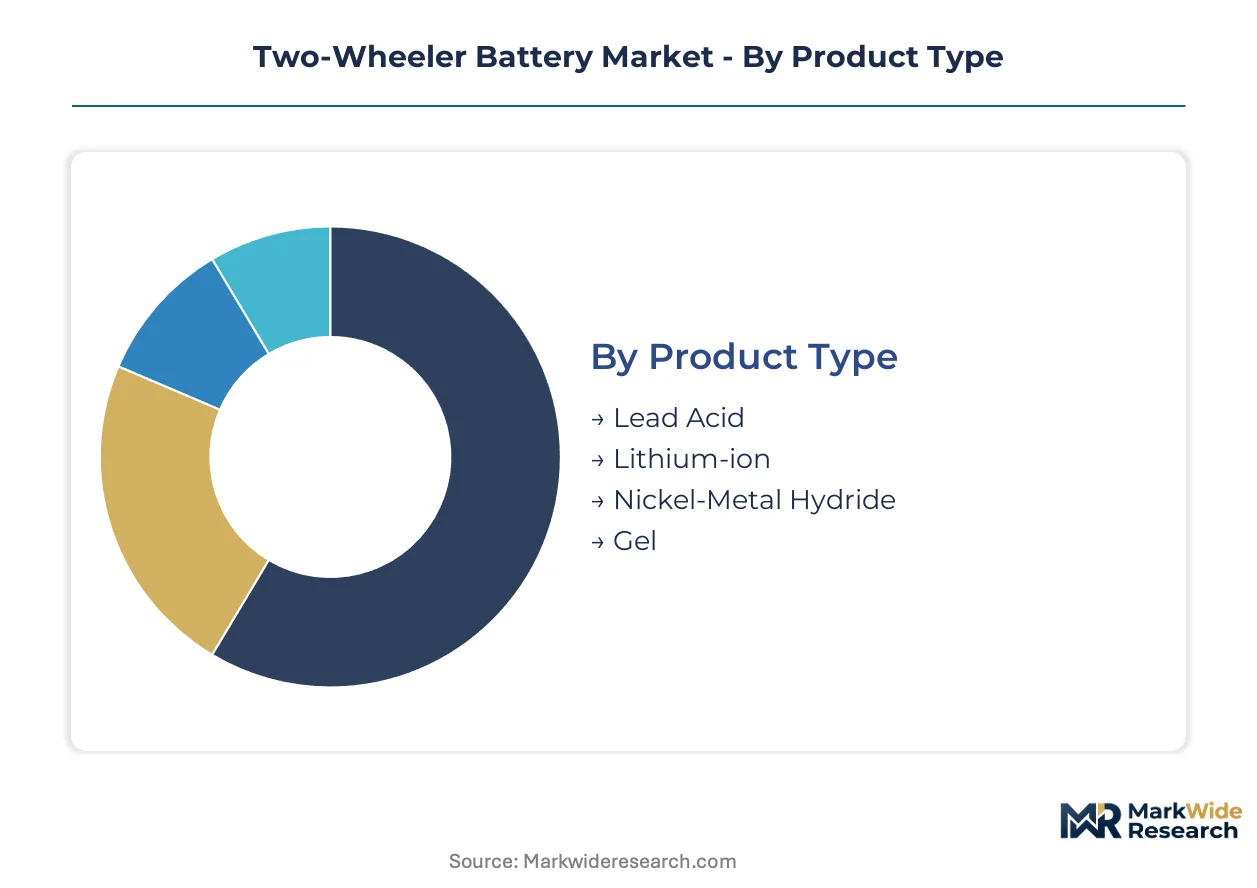
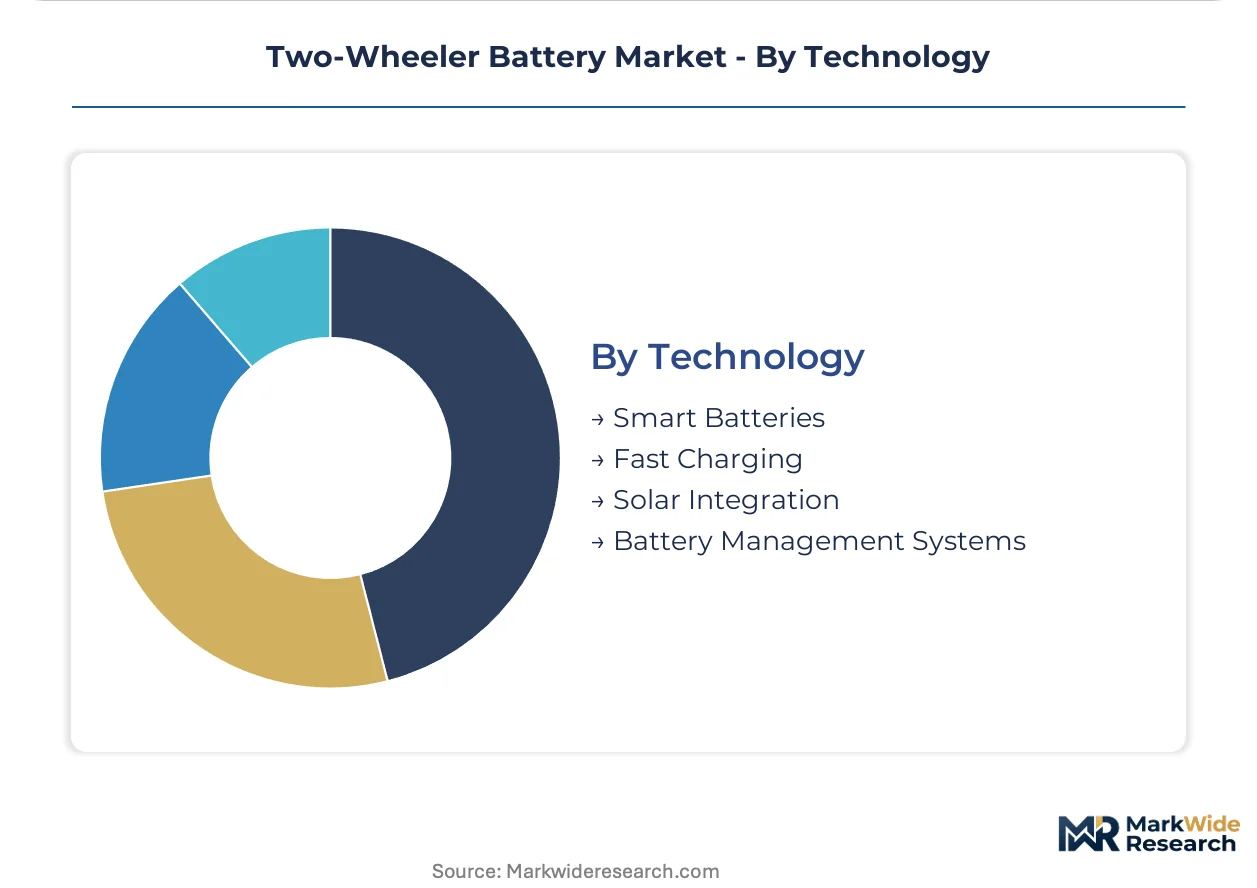
Two-wheeler battery procurement patterns diverge sharply across chemistry types, user profiles, and technical specifications. Fleet operators impose performance thresholds that private owners ignore, while OEM integration demands collide with aftermarket replacement economics.
Product Type:
Chemistry selection determines energy density, cycle life, and total ownership cost across vehicle classes.
- Lead Acid:Flooded and absorbed glass mat constructions dominate motorcycle replacement channels in India and Southeast Asia due to established recycling networks and service infrastructure. Cost sensitivity in informal repair markets preserves demand despite weight penalties and shorter cycle life.
- Lithium-ion:NMC and LFP cell chemistries are gaining share fastest among electric scooter fleets in Vietnam and Indonesia where operators specify minimum 1,500-cycle warranties. Panasonic and CATL cylindrical cell supply anchors premium platform sourcing.
- Nickel-Metal Hydride:Legacy chemistry persists in select hybrid two-wheeler prototypes from Japanese OEMs, though manufacturing scale has shifted entirely to lithium-ion.
- Gel:Valve-regulated designs serve deep-cycle applications in commercial three-wheeler conversions where vibration resistance outweighs energy density requirements.
Lead Acid leads on scale; Lithium-ion leads on momentum.
End User:
Procurement authority concentrates differently across ownership structures and volume tiers.
- Private Users:Individual owners prioritize upfront cost over lifecycle economics, sustaining lead-acid replacement demand through India's vast motorcycle service network. Exide Industries leverages this channel through distributor exclusivity arrangements.
- Fleet Operators:Ride-hailing platforms in Jakarta and Ho Chi Minh City centralize battery specifications at holding-company level, negotiating unified service-level agreements across urban territories. Cycle-life thresholds and swap-station compatibility dominate tender criteria.
- Delivery Services:Last-mile logistics operators in Indian metro corridors specify lithium-ion packs with real-time state-of-health monitoring to optimize asset utilization and prevent thermal incidents.
- OEMs:Electric scooter manufacturers integrate Battery Management Systems as standard equipment to satisfy BIS certification mandates and government fleet tender requirements.
Fleet Operators concentrate procurement authority; Delivery Services expand most quickly.
Application:
Vehicle architecture dictates voltage ranges, thermal management, and pack form factors.
- Electric Scooters:48V-72V lithium-ion configurations dominate Southeast Asian urban mobility where weight reduction determines range and handling. Swap-station network buildout in Indonesia enables battery-as-a-service models.
- Motorcycles:Internal combustion engine starting-lighting-ignition applications sustain 12V lead-acid demand across India's replacement market, though electric motorcycle platforms are emerging in premium segments.
- E-Bikes:Pedal-assist configurations in European export markets face EU F-Gas Regulation compliance requirements for thermal management systems, favoring air-cooled pack designs.
- Rideshare:High-utilization fleet assets impose the most stringent cycle-life and fast-charging specifications, driving chemistry selection toward high-nickel cathode formulations.
Electric Scooters anchor volume; Rideshare pushes specification boundaries.
Technology:
Embedded electronics and charging infrastructure are restructuring pack economics and supplier margin pools.
- Smart Batteries:Cellular-connected packs enable remote diagnostics and over-the-air firmware updates, becoming mandatory for fleet operator insurance coverage in Vietnamese urban markets.
- Fast Charging:30-minute to 80% capability requires advanced thermal management and cell balancing algorithms, concentrating procurement among Tier 1 suppliers with BMS integration expertise.
- Solar Integration:Photovoltaic trickle-charging accessories serve rural Indian markets with unreliable grid access, though penetration remains limited by cost and panel durability concerns.
- Battery Management Systems:Real-time state-of-health monitoring is becoming standard fleet equipment, pulling embedded electronics into pack economics and compressing pure cell supplier margins.
Battery Management Systems concentrate value capture; Fast Charging climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping cell manufacturing geography as India's PLI scheme for advanced chemistry cells creates a cost-of-compliance gap against China's GB standards and Europe's F-Gas Regulation. Pack assemblers are migrating module assembly capacity toward jurisdictions offering production-linked incentives while maintaining cell import relationships.
India
Urban last-mile delivery corridors in Delhi-NCR and Bengaluru are driving lithium-ion procurement volumes as fleet operators specify minimum 1,500-cycle warranties. The CEA's safety protocols and BIS certification mandates for traction batteries are forcing domestic module assembly migration to satisfy traceability requirements. Tamil Nadu's industrial corridor around Chennai is concentrating cell-to-pack integration facilities serving electric scooter OEMs.
Vietnam
Ride-hailing platforms in Ho Chi Minh City and Hanoi are centralizing battery procurement at holding-company level to negotiate unified service-level agreements. The country's national automotive regulator imposes thermal testing requirements that favor established pack suppliers with BMS integration expertise. Northern industrial zones around Hai Phong are attracting swap-station infrastructure investment from regional powertrain suppliers.
Indonesia
Jakarta's fleet electrification mandates are compressing lead-acid replacement cycles as operators specify lithium-ion chemistry for high-utilization assets. The government's nickel processing expansion in Sulawesi and Maluku is enabling upstream cathode material integration for regional cell manufacturers. Surabaya's logistics corridor is emerging as a battery-as-a-service testbed with swap-station network buildout.
China
GB standards for lithium-ion traction batteries impose compliance burdens that differentiate export-oriented pack assemblers from domestic-market suppliers. The Yangtze River Delta around Shanghai and Suzhou concentrates cylindrical cell production for premium electric scooter platforms. Shenzhen's electronics manufacturing ecosystem anchors BMS firmware development and smart battery connectivity modules.
Japan
Premium motorcycle OEM channels sustain demand for absorbed glass mat technology as METI efficiency standards tighten thermal management requirements. The Kansai industrial region around Osaka hosts specialized cell characterization facilities serving solid-state electrolyte research programs. Nagoya's automotive supplier cluster is piloting high-voltage pack configurations for emerging electric sportbike platforms.
Two-Wheeler Battery Market Competitive Environment
Capacity expansion dominates the current landscape as incumbent lead-acid manufacturers and emerging lithium-ion specialists race to secure positioning ahead of chemistry transition inflections. The vendor base stratifies across three tiers: legacy battery manufacturers with established recycling networks, electronics conglomerates with cell supply control, and pure-play electric powertrain specialists. Two strategic archetypes define competitive positioning: scale-driven manufacturers leveraging manufacturing depth to anchor replacement demand, and technology-focused integrators capturing BMS-enabled margin pools. Geographic expansion and portfolio diversification represent the dominant competitive moves as participants seek to bridge lead-acid replacement and lithium-ion electric scooter segments.
Within the legacy manufacturer tier, Exide Industries Ltd and Amara Raja Batteries Limited exemplify scale-driven positioning through established distribution networks. GS Yuasa Corporation occupies a specialization position in premium absorbed glass mat applications. Panasonic Corporation anchors the electronics-integrated tier with cylindrical cell supply relationships for high-performance platforms. These three named entities represent distinct competitive archetypes without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Exide Industries Ltd |
| Amara Raja Batteries Limited |
| GS Yuasa Corporation |
| Panasonic Corporation |
| Clarios |
| Robert Bosch GmbH |
| Tianneng Power International |
| DYNAVOLT Power |
| Leoch International Technology |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between BIS-mandated lithium-ion packs and informal lead-acid replacement channels creates parallel pricing architectures that reshape procurement authority and supplier margin capture across India's two-wheeler battery landscape.
Pricing Analysis
Distributor margin stacking in India's replacement market compresses cell-level supplier returns while fleet-direct contracts bypass channel layers entirely. Three-tier pricing structure across premium, standard, and economy levels reflects BIS certification status, cycle-life warranty thresholds, and embedded BMS complexity. Pricing pressure stems from lithium carbonate volatility and fleet buyer consolidation in Vietnam and Indonesia. Private motorcycle owners in informal repair markets exhibit highest price sensitivity; electric scooter fleet operators with swap-station integration show lowest sensitivity due to total-ownership-cost modeling.
Supply Chain Analysis
Dual-sourcing requirements from Indonesian and Vietnamese fleet operators mandate multi-supplier qualification programs that fragment cell procurement across CATL, Panasonic, and emerging domestic pack assemblers. Cathode active material supply concentrates in China's Yangtze River Delta, South Korea's industrial southeast, and Indonesia's nickel-rich eastern islands. Raw material dependencies span lithium carbonate from South American salares, nickel laterite from Sulawesi, and separator films from Japanese specialty chemical producers. Single-source vulnerability in cylindrical cell supply creates qualification bottlenecks for premium platform OEMs. Distribution runs through Exide Industries' replacement network in India and direct OEM supply agreements for electric scooter manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where India's PLI scheme for advanced chemistry cells and tightening BIS certification mandates continuously escalate compliance investment thresholds, accelerating consolidation among suppliers capable of domestic module assembly.
For Market Incumbents: Lock in fleet operator relationships through swap-station infrastructure partnerships and captive BMS firmware development capabilities. Defend against pure-play lithium-ion specialists by leveraging lead-acid recycling network density for hybrid chemistry portfolio breadth. Prioritize certification investment in India's CEA thermal testing protocols to maintain bid eligibility for government fleet tenders. For New Entrants and Emerging Players: Swap-station operators represent the most penetrable channel partner type for asset-light market entry without direct OEM relationships. Target Indonesia's Surabaya logistics corridor and Vietnam's northern industrial zones around Hai Phong where battery-as-a-service models are scaling fastest. White-space opportunities sit in air-cooled pack designs for EU F-Gas Regulation compliance and rural Indian solar-integrated trickle-charging accessories. Go-to-market angle: modular pack architectures compatible with multi-brand swap-station protocols. For Investors and Strategic Acquirers: Asymmetric upside sits with BMS-integrated pack assemblers controlling firmware development and real-time diagnostics capabilities rather than pure cell suppliers facing margin compression. Long-term viability favors participants with backward integration into nickel processing or cathode material production. Acquisition target archetype: mid-cap specialists with CEA certification and existing fleet operator relationships. Signal to watch: consolidation of procurement authority at holding-company level among Southeast Asian ride-hailing platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Module Assembly Migration | India's BIS traceability mandates force cell-to-pack integration within Tamil Nadu's industrial corridor. |
| Swap-Station Network Buildout | Battery-as-a-service models in Indonesia enable powertrain suppliers to bypass direct vehicle OEM relationships. |
| Air-Cooled Pack Design Development | EU F-Gas Regulation compliance creates first-mover positioning for European electric two-wheeler exports. |
| Backward Integration into Nickel Processing | Indonesia's Sulawesi and Maluku deposits offer cathode material cost positioning for regional cell supply. |
| BMS Firmware and Connectivity Investment | Real-time state-of-health monitoring is becoming mandatory for fleet operator insurance coverage in Vietnamese markets. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with battery pack assemblers, fleet procurement directors, OEM platform engineers, and aftermarket distributors with secondary validation. Primary sources included cell characterization facilities in Japan's Kansai region, swap-station operators in Indonesia, and India's BIS certification laboratories. Secondary data drew from customs records tracking lithium-ion cell imports, CEA safety protocol filings, PLI scheme beneficiary disclosures, and electric vehicle registration databases. Bottom-up fleet deployment tracking and top-down chemistry transition modeling were triangulated against regional production capacity announcements.
Segment-weighting approaches applied chemistry-type splits, end-user procurement authority concentration, and application-specific voltage requirements across the projection horizon. The analytical framework modeled lead-acid replacement cycle compression against lithium-ion penetration rates in fleet versus private ownership structures. CAGRs derived from vehicle sales projections, battery pack sizing assumptions, and chemistry mix transitions. Industry-specific forecast inputs included India's PLI scheme capacity commissioning timelines and Indonesia's nickel processing expansion announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium carbonate price volatility, regulatory fragmentation between Indian state-level CEA implementations, and fleet operator consolidation pace. Deviation in swap-station network deployment speed or BIS certification timeline enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Battery Recycling
EV Battery Recycling Services Market
Transportation Battery Recycling
South Korea Transportation Battery Recycling Market
Transportation Battery Recycling
Asia-Pacific Transportation Battery Recycling Market
Transportation Battery Recycling
China Transportation Battery Recycling Market
Transportation Battery Recycling
Europe Automotive Start-Stop Battery Market
Transportation Battery Recycling
Transportation Battery Market
Transportation Battery Recycling
Transportation Battery Recycling Market
Transportation Battery Recycling
ASEAN Electric Vehicle Battery Anode Market
Transportation Battery Recycling
Automobile Storage Battery Market
Transportation Battery Recycling
Automotive Battery Recycling Market
Transportation Battery Recycling
Europe Train Battery Market
Transportation Battery Recycling
Automotive Energy Recovery System Market