
 China Transportation Battery Recycling Market | 2026-2036
China Transportation Battery Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
China Transportation Battery Recycling Market Insights
Battery-as-a-service subscription models for residual value recovery is hardening as the dominant commercial layer in China's transportation battery recycling sector. GEM Co., Ltd. leverages hydrometallurgical refining scale to anchor cathode precursor supply for domestic EV makers. Zhejiang Huayou Cobalt Co., Ltd. sustains vertical integration from black mass to cobalt sulfate through captive smelting in Zhejiang province. Contemporary Amperex Technology Co., Limited competes by extending closed-loop collection contracts directly with commercial fleet operators.
China transportation battery recycling encompasses the disassembly, shredding, and chemical extraction of spent traction batteries from electric vehicles, buses, and commercial trucks to recover lithium, cobalt, nickel, and manganese at purity grades exceeding 99.5% for re-entry into cathode active material production. Hydrometallurgical processing dominates operational capacity due to lower energy intensity and superior lithium recovery rates compared to pyrometallurgical routes. Automotive manufacturers represent the most concentrated end-user channel, as OEMs face binding extended producer responsibility quotas under national regulations that mandate minimum recycled content thresholds. Mechanical processing segments are gaining share for direct recycling pathways that preserve cathode crystal structures, though this route remains technically constrained to batteries with state-of-health above 80%.
China's Ministry of Ecology and Environment enforces hazardous waste licensing and cross-province transfer permits that shape facility siting and operational compliance costs for recyclers. GB/T standards for battery traceability and the SAMR-administered recycling industry access conditions define technical thresholds for market entry and material quality certification. The central bank's green financing facilities and the NDRC's circular economy investment guidelines direct capital toward hydrometallurgical capacity expansion. Stakeholders must monitor how provincial implementation of national extended producer responsibility rules varies in enforcement intensity and subsidy allocation across manufacturing clusters.
Market Dynamics
Extended producer responsibility mandates from China's Ministry of Ecology and Environment are compressing collection timelines and forcing OEMs to internalize recycling costs, restructuring competitive advantage toward integrated operators with licensed hazardous waste handling capabilities.
Growth Catalysts
- GB/T Traceability Standards:Mandatory battery passport systems create data infrastructure that streamlines feedstock verification and reduces black mass arbitrage losses for certified processors.
- Yangtze River Delta Clustering:Co-location of cathode refiners, cell manufacturers, and recycling infrastructure in Jiangsu and Zhejiang provinces minimizes logistics costs and enables just-in-time material loops.
- Hydrometallurgical Scale:Lower energy intensity and superior lithium recovery rates compared to pyrometallurgical routes attract green financing from central bank facilities.
Market Restraints
- Cobalt Price Volatility:Black mass valuation swings destabilize feedstock procurement economics for independent recyclers lacking long-term cathode offtake agreements.
- Cross-Province Transfer Permits:MEE hazardous waste licensing creates geographic moats that fragment operational scale and inflate compliance overhead for multi-facility operators.
- Direct Recycling Technical Ceiling:Mechanical cathode preservation pathways remain constrained to batteries above 80% state-of-health, limiting addressable feedstock volume.
Strategic Opportunities
- Closed-Loop Fleet Contracts:Battery-as-a-service subscription models with commercial EV operators lock in predictable feedstock streams and residual value capture.
- Mechanical Processing Expansion:Direct recycling pathways that preserve cathode crystal structures offer margin expansion as battery quality data improves sorting precision.
- NDRC Circular Economy Guidelines:Capital allocation toward hydrometallurgical capacity expansion accelerates for operators meeting SAMR recycling industry access conditions.
Industry Challenges
- Hydrometallurgical Talent Scarcity:Shortage of process engineers with lithium-nickel separation expertise constrains plant commissioning timelines and operational ramp rates.
- Certification Lag:GB standards compliance testing for recycled cathode precursor purity creates 6-12 month qualification delays with automotive OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Transportation Battery Recycling Market |
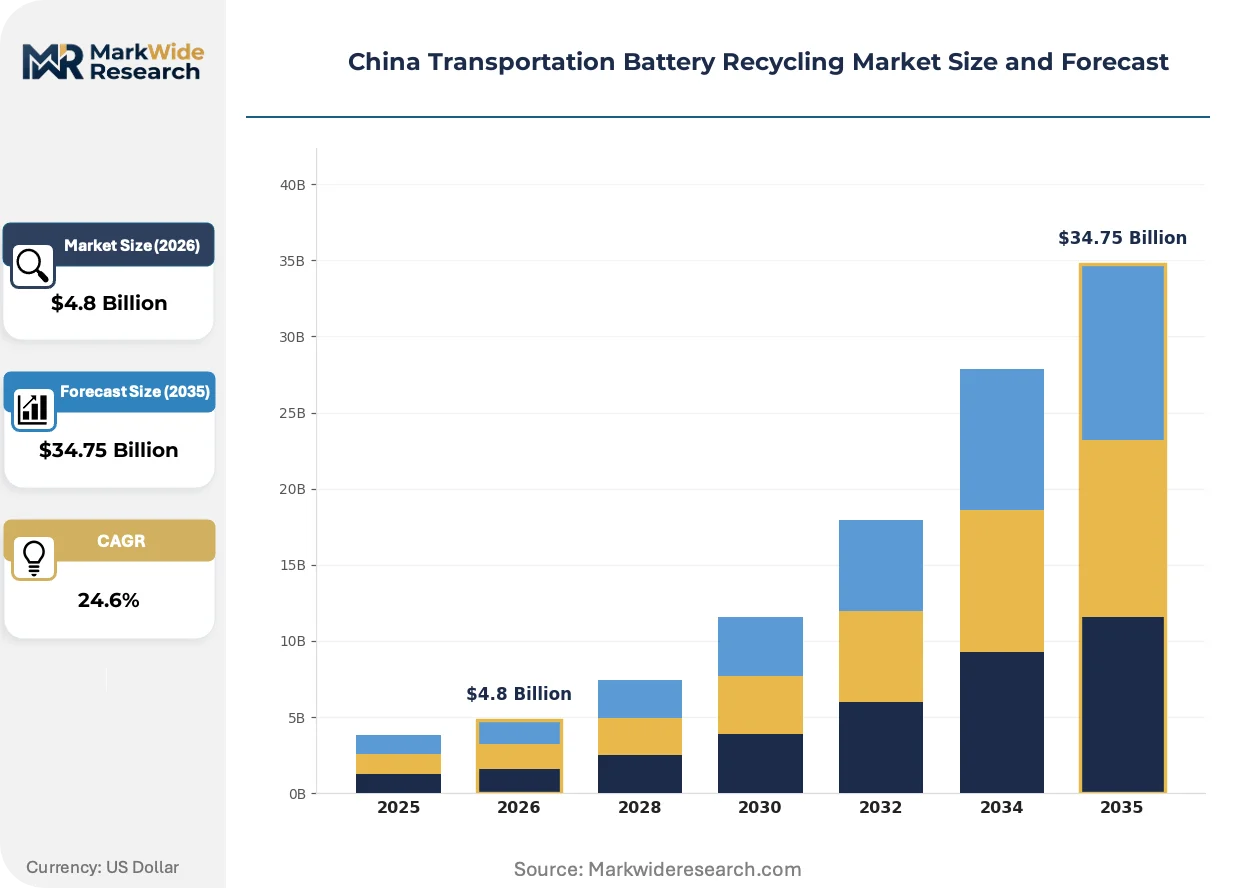
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $34.75 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Lead-acid, Nickel-cadmium, Flow batteries Recycling Method: Hydrometallurgical, Pyrometallurgical, Biotechnological, Mechanical processing End User: Automotive Manufacturers, Retailers, Recycling Facilities, Government Agencies Regulatory Framework: National Standards, Environmental Regulations, Safety Guidelines, Industry Practices |
| Companies Covered | Ganfeng Lithium, GEM Co., Ltd., Zhejiang Huayou Cobalt Co., Ltd., Guangdong Guanghua Sci-Tech Co., Ltd., Contemporary Amperex Technology Co., Limited, Camel Group Co., Ltd., CNGR Advanced Material Co., Ltd., Tianqi Automation Engineering Co., Ltd., Anhui Chaoyue Environmental Protection Technology Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Transportation Battery Recycling Market Trends and Innovations
Processing technology and procurement architecture are simultaneously evolving, with mechanical separation advances compressing the pathway from end-of-life battery to cathode-ready material.
Direct recycling through mechanical shredding and selective separation is rewriting the economics of battery material recovery. Cathode crystal structure preservation eliminates hydrometallurgical re-synthesis steps, cutting energy consumption by half. Fleet operators with battery health data are piloting feedstock segregation to route higher-SOH packs toward direct pathways, compressing payback periods for mechanical processing investments.
China's extended producer responsibility rules are tightening material recovery obligations through binding recycled content thresholds. OEMs now face quota enforcement that escalates annually, forcing vertical coordination with licensed recyclers. The Yangtze River Delta manufacturing corridor is experiencing the most intensive provincial implementation, with Jiangsu and Zhejiang authorities linking subsidy allocation to closed-loop contract verification.
Commercial fleet operators are consolidating procurement around residual value guarantees rather than upfront cell purchases. Battery-as-a-service contracts transfer ownership and end-of-life liability to recyclers or OEM financing arms, replacing spot-market black mass transactions. This restructuring is most visible in Shenzhen and Shanghai municipal bus electrification programs, where service contracts now span 8-10 year asset lifecycles with embedded recycling clauses.
China Transportation Battery Recycling Market Segmentation
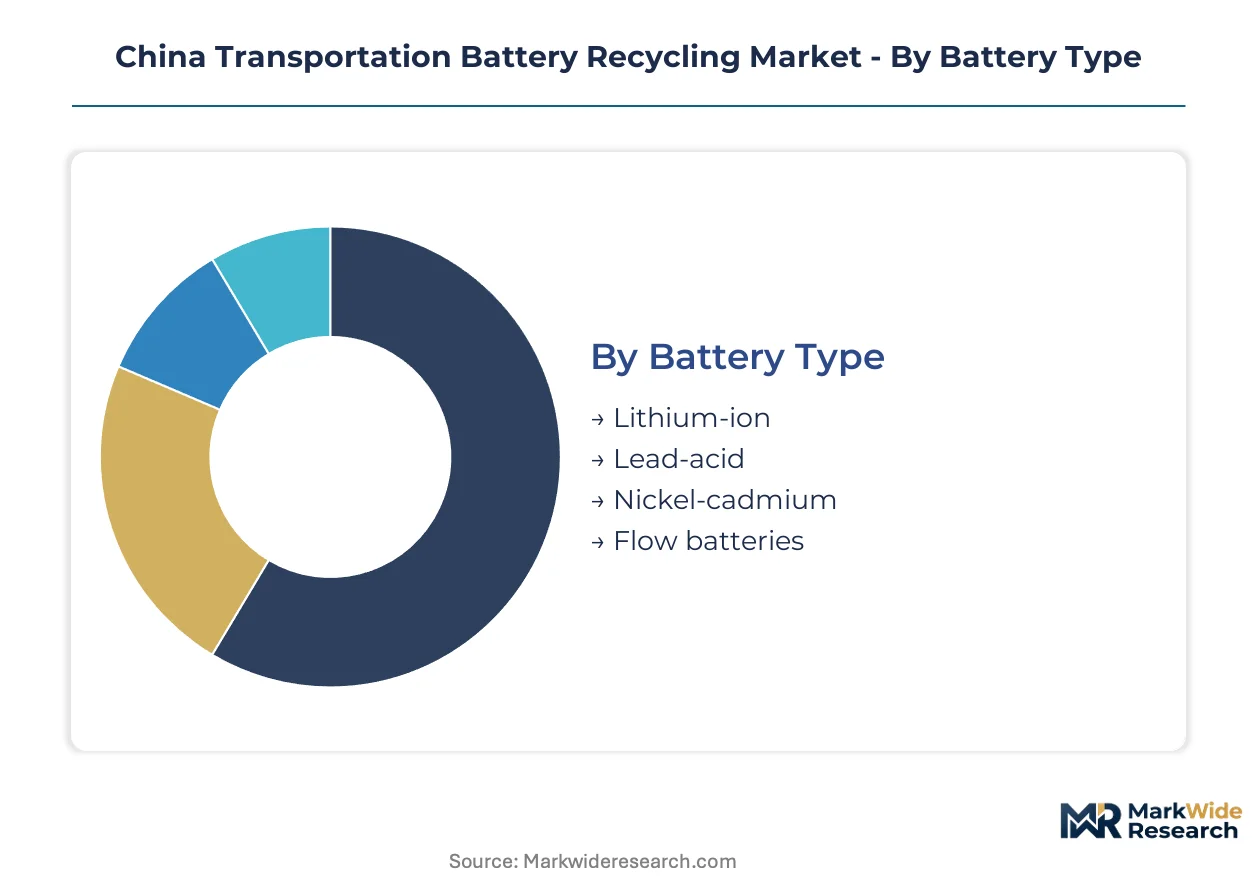
Segmentation in China's transportation battery recycling market reveals how processing economics, regulatory compliance burdens, and feedstock quality thresholds distribute value across distinct operational configurations. Each category exposes where capital concentrates and which technical pathways command premium positioning.
Battery Type:
Standalone battery systems dominate recycling economics due to modular disassembly and cleaner material streams, while embedded traction packs in commercial vehicles require specialized extraction protocols.
- Lithium-ion:NCM and LFP chemistries constitute the primary feedstock for hydrometallurgical refiners in Jiangsu province, with fleet operators in Shenzhen and Shanghai generating concentrated end-of-life volumes from bus electrification programs. MEE traceability mandates under GB/T standards lock processors into certified collection networks.
- Lead-acid:Mature collection infrastructure and simpler metallurgical recovery sustain this segment across secondary smelters in Hebei and Shandong provinces, though lithium-ion displacement is compressing growth trajectories in passenger vehicle applications.
- Nickel-cadmium:Declining transportation relevance restricts volumes primarily to legacy rail and aviation ground support equipment, with hazardous waste licensing requirements concentrating processing at a handful of MEE-permitted facilities.
- Flow batteries:Vanadium redox systems from grid-scale pilot projects generate minimal end-of-life feedstock currently, with aqueous electrolyte chemistry enabling direct refurbishment rather than full material recovery.
Volume placements concentrate in Lithium-ion; the faster expansion belongs to Lithium-ion as EV penetration deepens.
Recycling Method:
Cost tier stratification separates capital-intensive hydrometallurgical scale operators from mechanical processing ventures targeting premium cathode preservation economics.
- Hydrometallurgical:Acid leaching and solvent extraction circuits achieve superior lithium recovery rates exceeding 90% while operating at lower energy intensity than pyrometallurgical alternatives, attracting NDRC green financing for capacity expansion in Zhejiang province.
- Pyrometallurgical:High-temperature smelting remains viable for cobalt-rich black mass with minimal preprocessing requirements, though lithium volatilization losses and carbon intensity are displacing investment toward hydrometallurgical retrofits.
- Biotechnological:Bioleaching using acidophilic bacteria for selective metal solubilization remains at pilot scale with Chinese Academy of Sciences partnerships, constrained by processing speed limitations versus chemical routes.
- Mechanical processing:Direct recycling through shredding and physical separation preserves cathode crystal structures for batteries above 80% state-of-health, cutting re-synthesis energy demands by half for qualifying feedstock streams.
Capacity additions cluster around Hydrometallurgical; Mechanical processing is climbing the fastest as battery quality data improves sorting precision.
End User:
Procurement authority concentration determines contract structure, with OEMs wielding extended producer responsibility quotas to enforce closed-loop terms that independent recyclers cannot match.
- Automotive Manufacturers:Binding MEE mandates for minimum recycled content thresholds force BYD, NIO, and XPeng to internalize recycling costs through licensed processor partnerships or captive hydrometallurgical investments in the Yangtze River Delta.
- Retailers:Authorized dealer networks handle warranty returns and trade-in volumes for passenger vehicles, though fragmented collection logistics limit scale versus fleet operator consolidation.
- Recycling Facilities:Independent processors compete for black mass feedstock on spot markets, facing margin compression from cobalt price volatility and cross-province hazardous waste transfer permit constraints.
- Government Agencies:Municipal bus operators in Beijing and Guangzhou are consolidating procurement around battery-as-a-service contracts with embedded recycling clauses spanning 8-10 year asset lifecycles.
Contract value pools deepest with Automotive Manufacturers; Government Agencies are expanding most quickly as municipal electrification accelerates.
Regulatory Framework:
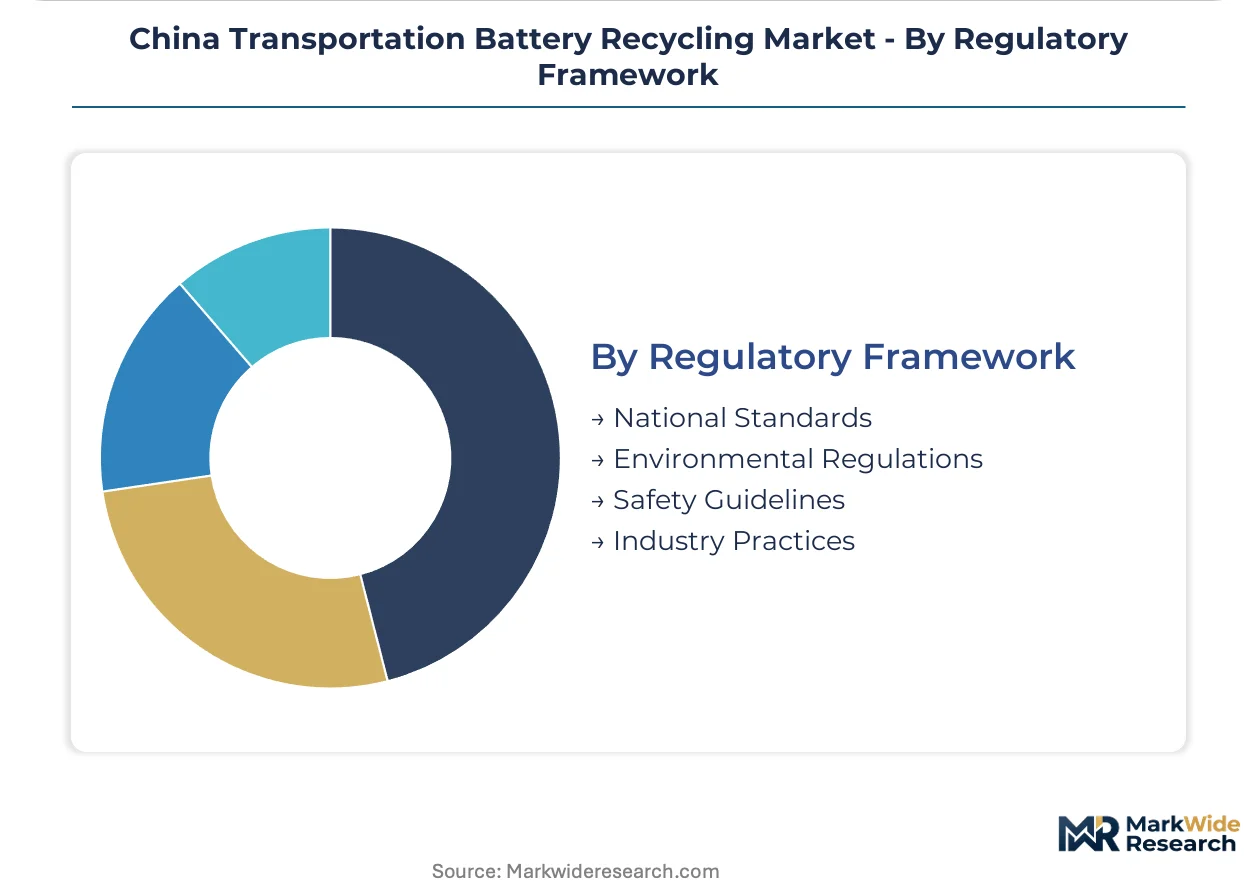
Compliance tier differentiation creates operational moats, with national standard certification unlocking automotive OEM qualification while provincial environmental enforcement varies in subsidy linkage intensity.
- National Standards:GB/T battery passport systems and SAMR recycling industry access conditions define technical thresholds for market entry, with purity certification for recycled cathode precursors creating 6-12 month qualification delays.
- Environmental Regulations:MEE hazardous waste licensing and extended producer responsibility rules enforce binding recovery quotas that escalate annually, restructuring competitive advantage toward integrated operators with multi-province permit portfolios.
- Safety Guidelines:State-of-charge management protocols for spent battery transport and storage shape facility siting requirements, particularly for high-nickel chemistries with elevated thermal runaway risks.
- Industry Practices:Voluntary consortium standards from the China Automotive Technology and Research Center supplement mandatory frameworks, though adoption concentrates among export-oriented OEMs facing EU Battery Regulation alignment pressures.
Enforcement intensity peaks under Environmental Regulations; Industry Practices are gaining share fastest as dual carbon goals tighten supply chain disclosure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's transportation battery recycling capacity concentrates in manufacturing belts where cathode refiners and cell producers co-locate, while feedstock generation clusters in coastal megacities with dense commercial EV fleets. Provincial implementation of MEE extended producer responsibility rules varies in enforcement intensity, creating compliance moats that reshape operational scale.
Yangtze River Delta
Jiangsu and Zhejiang provinces host the densest recycling infrastructure concentration, driven by cathode precursor demand from CATL and BYD cell plants. MEE hazardous waste licensing in these provinces links subsidy allocation to closed-loop contract verification, tightening feedstock access. Zhejiang's Huayou Cobalt anchors hydrometallurgical scale in Quzhou, while Suzhou mechanical processors pilot direct recycling for bus batteries above 80% state-of-health.
Pearl River Delta
Guangdong province generates concentrated end-of-life volumes from Shenzhen's municipal bus electrification program and Guangzhou's commercial fleet operators. The provincial ecology department enforces stricter cross-city transfer permit requirements than neighboring Fujian, fragmenting multi-facility operator scale. Dongguan hosts black mass preprocessing hubs that supply Zhejiang refiners via Yangtze waterway logistics.
Beijing-Tianjin-Hebei
Hebei province's secondary smelters process lead-acid battery streams from northern logistics corridors, though lithium-ion displacement compresses growth trajectories. Beijing municipal authorities mandate battery passport data integration into fleet procurement platforms, creating feedstock traceability infrastructure that downstream processors leverage for GB/T certification. Tianjin's port facilities handle imported black mass from Korean battery producers.
Sichuan-Chongqing
Western China's lithium mining corridor in Sichuan province feeds hydrometallurgical refiners in Chengdu with spodumene concentrate, though transportation battery recycling capacity remains underdeveloped versus coastal clusters. Chongqing's automotive manufacturing base generates warranty return volumes that independent processors compete for on spot markets. Provincial MEE enforcement lags Jiangsu in subsidy linkage intensity.
Shandong Peninsula
Shandong province sustains legacy lead-acid recycling infrastructure across secondary smelters in Zibo and Dongying, with lithium-ion retrofit investments accelerating under NDRC circular economy guidelines. Qingdao's port logistics enable black mass export to Korean and Japanese refiners, bypassing domestic cross-province permit constraints. Local environmental bureaus prioritize air quality compliance over recycling quota enforcement.
China Transportation Battery Recycling Market Competitive Landscape
Top-tier vendors anchor the integrated refiner tier, while independent processors compete for black mass feedstock on volatile spot markets. The competitive structure stratifies across three operational archetypes: hydrometallurgical scale operators with SAMR recycling access conditions, mechanical processing ventures targeting direct recycling premiums, and OEM-captive recyclers internalizing extended producer responsibility costs. Dominant competitive moves include backward integration into cathode precursor production and strategic partnerships with fleet operators for closed-loop contract lock-in.
Within the integrated refiner tier, GEM Co., Ltd. and Zhejiang Huayou Cobalt Co., Ltd. exemplify scale-driven positioning through hydrometallurgical capacity in Zhejiang province. Contemporary Amperex Technology Co., Limited occupies a distinct archetype as an OEM-captive operator extending collection contracts directly with commercial fleet customers. Among regional specialists, Anhui Chaoyue Environmental Protection Technology Co., Ltd. represents mechanical processing ventures targeting direct recycling pathways for higher-state-of-health batteries. Ganfeng Lithium anchors the upstream-integrated segment with lithium extraction expertise feeding into recycling circuit design.
| Leading Market Players |
|---|
| Ganfeng Lithium |
| GEM Co., Ltd. |
| Zhejiang Huayou Cobalt Co., Ltd. |
| Guangdong Guanghua Sci-Tech Co., Ltd. |
| Contemporary Amperex Technology Co., Limited |
| Camel Group Co., Ltd. |
| CNGR Advanced Material Co., Ltd. |
| Tianqi Automation Engineering Co., Ltd. |
| Anhui Chaoyue Environmental Protection Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
MEE extended producer responsibility mandates gate qualified supply access and premium-tier pricing for certified recyclers meeting GB/T traceability standards and SAMR recycling industry access conditions. Automotive OEMs internalize recycling costs through closed-loop contracts, compressing spot-market black mass arbitrage for independent processors lacking hazardous waste licensing.
Pricing Analysis
Margin tightening in mechanical processing reflects cobalt price volatility and feedstock quality uncertainty. Pricing stratifies across SAMR-certified hydrometallurgical refiners, GB/T-compliant mechanical processors, and unlicensed spot-market operators. Cost-down pressure on independent recyclers accelerates because OEMs consolidate procurement around battery-as-a-service residual value guarantees. Fleet operators exhibit lowest price sensitivity due to embedded recycling clauses spanning 8-10 year asset lifecycles.
Supply Chain Analysis
Black mass feedstock rests on Yangtze River Delta cathode refiners, Pearl River Delta fleet operators, and Korean battery producers exporting via Tianjin port facilities. Lithium carbonate, cobalt sulfate, and nickel-manganese-cobalt precursors anchor material dependencies. Single-source vulnerability concentrates in Zhejiang province hydrometallurgical capacity. Distribution runs through closed-loop OEM contracts and spot-market transactions to independent processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated operators with multi-province hazardous waste licensing, as MEE enforcement intensity forces independent recyclers into distressed exits or acquisition.
For Market Incumbents: To counter cobalt price volatility and feedstock procurement instability, deepen backward integration into cathode precursor production and secure exclusive collection contracts with Shenzhen and Shanghai municipal bus operators. Expand hydrometallurgical capacity in Jiangsu province to capture NDRC circular economy green financing. For New Entrants and Emerging Players: Commercial fleet operators with battery health data represent the most penetrable channel for direct recycling pathway pilots. Target mechanical processing ventures for batteries above 80% state-of-health in Sichuan-Chongqing, where MEE enforcement lags coastal clusters. Lead with residual value guarantee propositions rather than spot-market black mass bidding. For Investors and Strategic Acquirers: SAMR recycling industry access condition certification delays exceeding 6-12 months is the leading indicator that qualified operational capacity scarcity will intensify. Five-to-ten year viability favors acquiring mechanical processing ventures with proprietary sorting technology and existing GB/T compliance infrastructure. Watch for provincial subsidy allocation shifts linking closed-loop contract verification to hazardous waste permit renewal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Production | Huayou Cobalt's Quzhou smelting operations demonstrate margin capture from black mass to cobalt sulfate. |
| Closed-Loop Fleet Contract Expansion | CATL's direct collection agreements with commercial operators lock in predictable feedstock streams. |
| Mechanical Processing Capacity Buildout | Anhui Chaoyue's direct recycling pilots cut re-synthesis energy demands by half for qualifying feedstock. |
| Multi-Province Hazardous Waste Permit Portfolio | GEM Co.'s licensed facility network navigates cross-province transfer constraints fragmenting competitor scale. |
| GB/T Traceability System Integration | Battery passport data infrastructure streamlines feedstock verification and reduces black mass arbitrage losses. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with MEE-licensed facility operators, cathode refinery procurement managers, and commercial fleet asset directors combined with secondary validation from SAMR recycling industry access condition disclosures and NDRC circular economy investment guidelines. Bottom-up capacity modeling and top-down feedstock generation estimates triangulated market sizing.
Segment-level granularity modeled battery chemistry, recycling method, and end-user procurement authority across the projection horizon. Hydrometallurgical, pyrometallurgical, and mechanical processing routes were disaggregated by energy intensity and lithium recovery rates. CAGRs derived from installed EV fleet projections, battery replacement cycle assumptions, and provincial EPR quota escalation trajectories.
Caveats apply where MEE enforcement intensity variations across provinces or sudden cobalt price dislocations could materially shift the outlook. Forecasts reflect assumptions about SAMR certification timelines and fleet electrification program acceleration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Battery Recycling
Europe Train Battery Market
Transportation Battery Recycling
Automobile Storage Battery Market
Transportation Battery Recycling
Transportation Battery Recycling Market
Transportation Battery Recycling
Automotive Energy Recovery System Market
Transportation Battery Recycling
Asia-Pacific Transportation Battery Recycling Market
Transportation Battery Recycling
Transportation Battery Market
Transportation Battery Recycling
Automotive Battery Recycling Market
Transportation Battery Recycling
South Korea Transportation Battery Recycling Market
Transportation Battery Recycling
Europe Automotive Start-Stop Battery Market
Transportation Battery Recycling
Two-Wheeler Battery Market
Transportation Battery Recycling
EV Battery Recycling Services Market
Transportation Battery Recycling
ASEAN Electric Vehicle Battery Anode Market