
 Asia-Pacific Transportation Battery Recycling Market | 2026-2036
Asia-Pacific Transportation Battery Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Transportation Battery Recycling Market Analytics
Skilled battery dismantling labor is rotating from informal scrap channels into certified preprocessing facilities across the region. GEM Co. Ltd. leverages its integrated smelter-refiner footprint in central China to dominate black mass-to-cathode precursor output. Umicore sustains hydrometallurgical capacity expansion through technology licensing partnerships with regional operators. Contemporary Amperex Technology Co. Limited anchors closed-loop recycling via direct cell-to-cell material return programs with domestic automakers.
Asia-Pacific transportation battery recycling encompasses the collection, dismantling, and chemical recovery of spent traction batteries from electric mobility applications, with hydrometallurgical routes achieving over 95% cobalt and nickel recovery rates at commercial scale. The primary purpose is to return recovered lithium, cobalt, and nickel into battery-grade compounds, reducing virgin mining dependence for electric vehicle supply chains. Lithium-ion battery types command the dominant feedstock volume given electric vehicle penetration, while hydrometallurgical processes attract capital fastest due to lower energy intensity and higher metal selectivity compared with pyrometallurgical alternatives. OEM end users are consolidating reverse logistics contracts to secure captive recycling streams, shifting margin pools away from independent collectors toward vertically integrated battery producers.
China's MEE enforces extended producer responsibility rules requiring automakers to establish recycling networks or partner with licensed processors. Japan's METI and South Korea's MFDS coordinate cross-border standards for black mass classification and hazardous waste transit, shaping regional trade corridors for intermediate materials. India's BIS is drafting battery waste management rules mandating minimum recovery rates for lithium and cobalt. Stakeholders must monitor regulatory divergence on recovered material purity standards, as incompatible specifications between national frameworks will fragment arbitrage opportunities across the region.
Market Dynamics
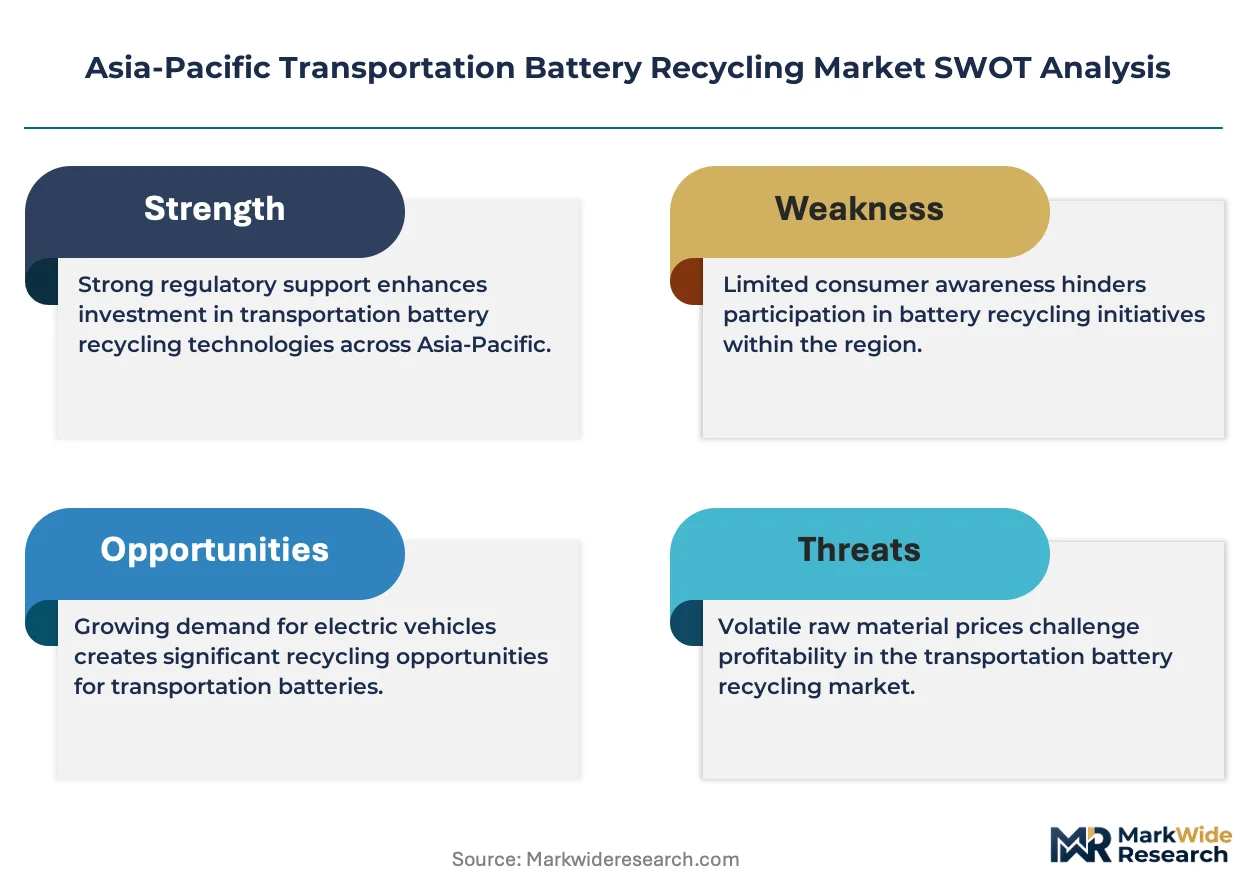
China's MEE extended producer responsibility mandates are forcing automakers to internalize end-of-life battery costs, redirecting capital flows from virgin material procurement toward captive recycling infrastructure and licensed processor partnerships.
Growth Catalysts
- Dual carbon goals:China's national decarbonization targets mandate minimum recycled content thresholds for new battery production, creating guaranteed offtake for refined cathode materials.
- Electric vehicle fleet operators:Regional logistics companies in Guangdong and Jiangsu are deploying dedicated collection vehicles to aggregate spent traction batteries at scale.
- Hydrometallurgical recovery:This chemical extraction route achieves superior lithium and nickel selectivity compared with thermal alternatives, attracting capital from material refiners.
Market Restraints
- Lithium price volatility:Spodumene and brine spot market fluctuations compress preprocessing margins when recovered material trades at persistent discounts to virgin equivalents.
- Feedstock concentration:End-of-life battery generation clusters in China's coastal provinces, leaving inland processors with elevated logistics costs or supply deficits.
- Cross-border black mass transit:Japan's METI and South Korea's MFDS maintain incompatible hazardous waste classifications, fragmenting arbitrage corridors for intermediate materials.
Strategic Opportunities
- India's BIS draft rules:Pending battery waste management regulations will mandate minimum recovery rates, opening licensed processing capacity gaps for early entrants.
- Southeast Asia collection networks:Thailand and Vietnam lack established reverse logistics infrastructure, creating first-mover advantages for integrated automaker-processor partnerships.
- Direct cell-to-cell programs:Closed-loop material return agreements between battery producers and domestic automakers bypass independent collector margins entirely.
Industry Challenges
- Skilled dismantling labor:Certified preprocessing facilities face recruitment competition from informal scrap channels that operate without environmental compliance costs.
- Cathode precursor purity certification:Divergent national standards for battery-grade compound specifications delay customer qualification timelines and lock processors into single-market offtake.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Transportation Battery Recycling Market |
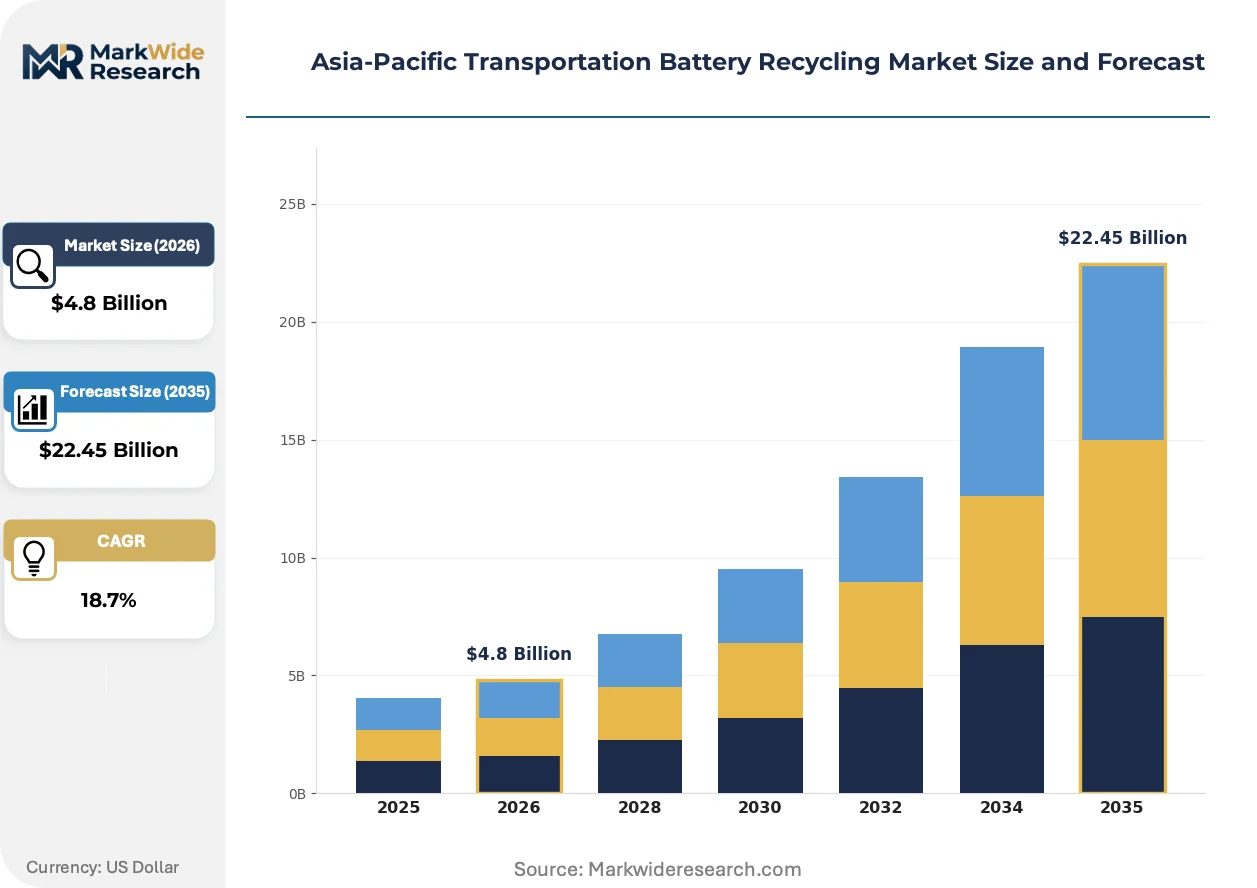
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Lead-acid, Nickel-cadmium, Flow Batteries End User: OEMs, Aftermarket Providers, Recycling Facilities, Government Entities Recycling Process: Pyrometallurgical, Hydrometallurgical, Direct Recycling, Biotechnological Application: Electric Vehicles, Energy Storage Systems, Consumer Electronics, Industrial Equipment |
| Companies Covered | GEM Co. Ltd., Umicore, Contemporary Amperex Technology Co. Limited, LG Energy Solution, Exide Industries Limited, Samsung SDI Co., GS Yuasa International Ltd, Neometals Ltd, TES, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Transportation Battery Recycling Market Evolving Landscape
Recovery technology economics and regulatory material mandates are compressing the interval between battery retirement and re-entry into active cathode supply chains across the region.
Direct physical recycling via cathode reconstruction is supplanting full hydrometallurgical dissolution for certain lithium iron phosphate streams. Chinese battery producers are piloting this route at commercial scale to preserve crystalline structure and reduce re-lithiation costs. The approach is compressing processing energy intensity and enabling faster qualification for automotive-grade material return.
Japan's METI battery circularity directives now require disclosed recycled content percentages in public procurement tenders. Industrial consequence includes mandatory supply chain documentation from collection through refining. South Korean cathode material producers are most affected, accelerating investment in domestic preprocessing capacity to maintain eligibility for Japanese offtake contracts.
Automakers are consolidating reverse logistics contracts under single-source processor agreements rather than fragmented collector networks. This procurement concentration displaces independent dismantlers and transfers margin pools toward vertically integrated refiners with proven black mass-to-precursor capabilities. The shift is most visible in China's Jiangsu province, where domestic EV manufacturers have executed exclusive feedstock arrangements with licensed facilities.
Asia-Pacific Transportation Battery Recycling Market Segmentation
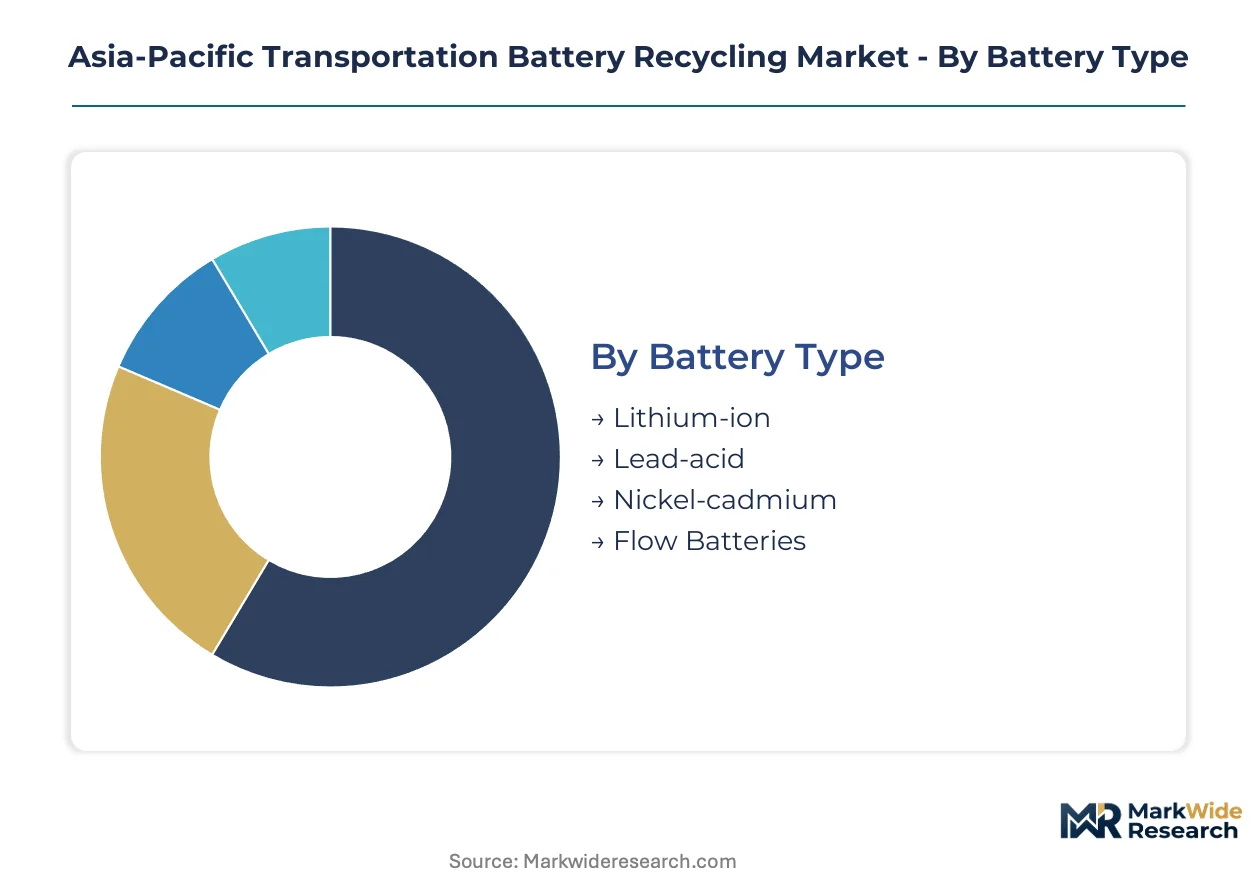
Segmentation in Asia-Pacific transportation battery recycling reveals where capital deployment, regulatory pressure, and feedstock availability intersect. Process economics and end-user procurement concentration determine which segments attract processor investment versus which face margin compression from substitute technologies.
Battery Type:
Substitution pressure from emerging chemistries and alternative energy storage technologies reshapes the competitive viability of each battery type in regional recycling networks.
- Lithium-ion:Dominant feedstock chemistry encompassing NMC, LFP, and NCA variants with cobalt and nickel recovery values driving processor economics. Guangdong and Jiangsu province refiners concentrate hydrometallurgical capacity here to serve CATL and BYD closed-loop programs.
- Lead-acid:Mature recycling infrastructure with established pyrometallurgical smelters across India and Southeast Asia, though declining automotive adoption limits growth trajectory. Secondary lead demand from India's unorganized battery manufacturing sector sustains informal collection channels.
- Nickel-cadmium:Restricted commercial aviation and rail applications limit feedstock volume; cadmium toxicity triggers stringent MEE hazardous waste handling requirements in China.
- Flow Batteries:Vanadium and zinc-bromine chemistries from grid-scale storage installations generate nascent recycling demand with unproven commercial recovery pathways.
Lithium-ion retains volume leadership; flow batteries hold the steepest expansion curve as utility-scale storage deployment accelerates.
End User:
Procurement consolidation patterns determine whether margin pools accumulate with integrated producers or fragment across independent service providers.
- OEMs:Automakers and battery producers building captive recycling infrastructure under China's extended producer responsibility mandates. NIO and XPeng execute exclusive feedstock agreements with licensed Jiangsu processors to secure cathode precursor supply.
- Aftermarket Providers:Independent dismantlers and second-life battery operators facing margin compression as OEMs internalize collection networks. Thailand and Vietnam logistics companies lack established reverse logistics, creating partnership opportunities.
- Recycling Facilities:Licensed processors with MEE permits dominating black mass-to-precursor conversion; GEM Co. Ltd. leverages integrated smelter-refiner footprint for cathode material output.
- Government Entities:Municipal fleet operators and state procurement agencies in Japan driving recycled content disclosure requirements under METI circularity directives.
Recycling facilities command processing margin control; government entities are gaining procurement leverage fastest through mandatory recycled content thresholds.
Recycling Process:
Capital intensity and energy cost differentials create divergent expansion economics across metallurgical and emerging biological recovery routes.
- Pyrometallurgical:High-temperature smelting routes with established equipment supply chains but elevated energy costs and lithium loss to slag. India's informal sector dominates lead-acid recovery via this pathway.
- Hydrometallurgical:Chemical leaching achieving superior lithium and nickel selectivity with lower energy intensity; Umicore expands regional capacity through technology licensing partnerships with Chinese operators.
- Direct Recycling:Cathode reconstruction preserving crystalline structure for LFP streams; Chinese battery producers pilot commercial-scale deployment to reduce re-lithiation costs.
- Biotechnological:Bioleaching using acidophilic bacteria for metal recovery remains laboratory-scale with unproven commercial throughput economics.
Hydrometallurgical routes dominate current capacity additions; direct recycling is climbing the fastest as cathode reconstruction technology matures.
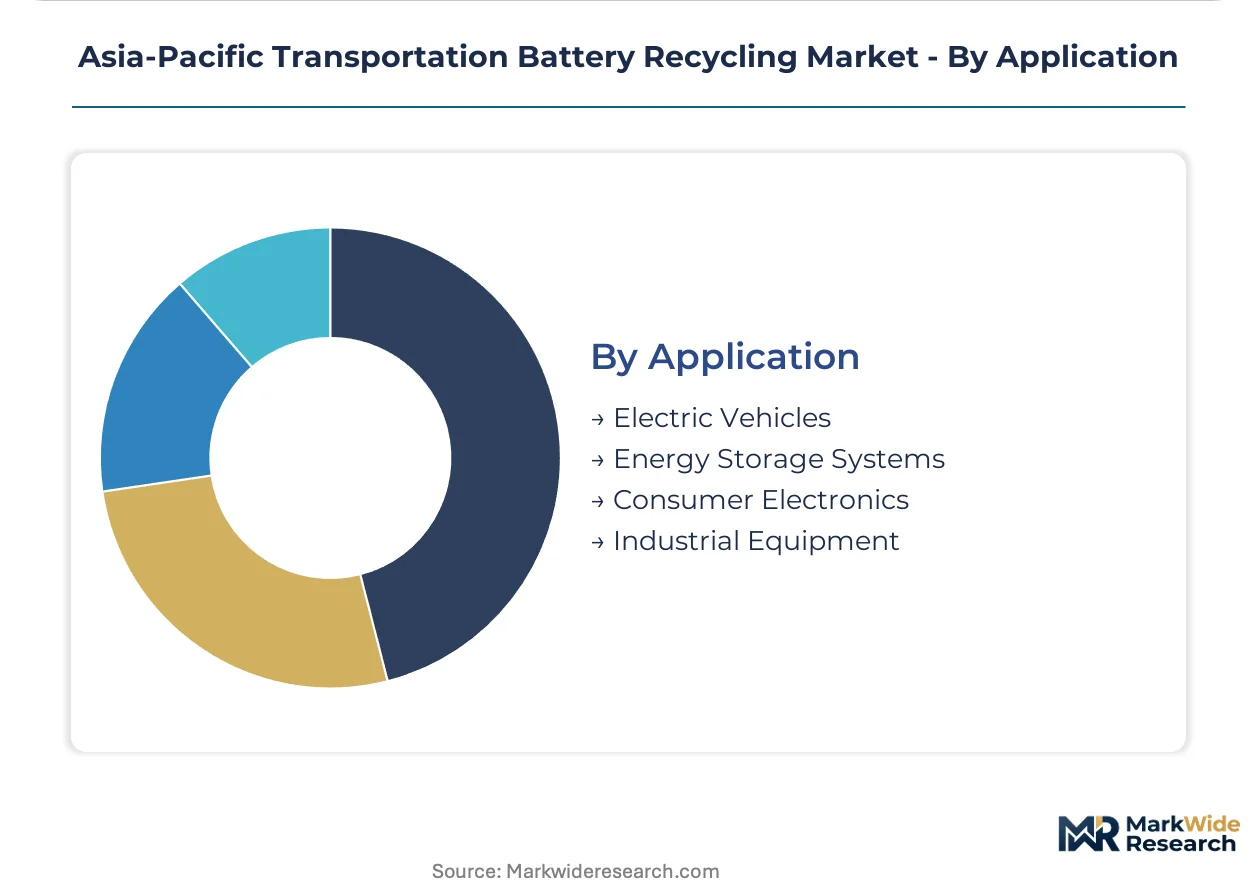
Application:
End-of-life volume timing and material value concentration determine which applications justify dedicated preprocessing infrastructure investment.
- Electric Vehicles:Traction batteries from passenger and commercial fleets generating the dominant feedstock volume; China's dual carbon goals mandate minimum recycled content for new EV production.
- Energy Storage Systems:Grid and commercial stationary batteries with longer lifecycles delaying retirement wave; LFP chemistry predominance favors direct recycling over full dissolution.
- Consumer Electronics:Fragmented collection logistics and mixed chemistry streams challenge economies of scale; portable device batteries route through informal channels in Southeast Asia.
- Industrial Equipment:Forklift and mining vehicle batteries with predictable replacement cycles but geographically dispersed fleet operators complicating reverse logistics aggregation.
Electric vehicles anchor feedstock volume; energy storage systems are gaining share fastest as early utility-scale installations approach end-of-life.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes end-of-life batteries through integrated smelter-refiner complexes that feed directly into cathode precursor production, while Southeast Asian markets rely on fragmented collection networks that route materials toward licensed preprocessing hubs in Thailand and Vietnam.
China
Guangdong and Jiangsu province refiners cluster near port infrastructure to aggregate spent traction batteries from domestic EV fleet operators. MEE extended producer responsibility mandates force automakers to establish recycling networks or partner with licensed processors. GEM Co. Ltd. leverages its integrated central China footprint to dominate black mass-to-cathode precursor output.
Japan
METI battery circularity directives tighten recovery mandates and require disclosed recycled content percentages in public procurement tenders. Cross-border standards coordination with South Korea's MFDS shapes regional trade corridors for black mass classification and hazardous waste transit. Industrial consequence includes mandatory supply chain documentation from collection through refining.
South Korea
Cathode material producers accelerate investment in domestic preprocessing capacity to maintain eligibility for Japanese offtake contracts under METI disclosure requirements. MFDS hazardous waste classifications currently fragment arbitrage corridors with Japan. Seoul-based battery producers pilot direct cell-to-cell material return programs with domestic automakers.
India
BIS draft battery waste management rules will mandate minimum recovery rates for lithium and cobalt, opening licensed processing capacity gaps for early entrants. Secondary lead demand from the unorganized battery manufacturing sector sustains informal collection channels for lead-acid streams. Maharashtra and Gujarat industrial corridors position for hydrometallurgical capacity expansion.
Thailand and Vietnam
Regional logistics companies lack established reverse logistics infrastructure, creating first-mover advantages for integrated automaker-processor partnerships. Informal scrap channels compete with certified preprocessing facilities for skilled dismantling labor. Port-adjacent industrial zones in Bangkok and Ho Chi Minh City attract preliminary collection network investment.
Asia-Pacific Transportation Battery Recycling Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated smelter-refiner complexes commanding black mass-to-precursor conversion margins while independent dismantlers face procurement concentration pressure. Three archetypes define competitive positioning: vertically integrated battery producers with captive recycling streams, licensed processors with MEE permits dominating chemical recovery, and technology licensors expanding regional capacity through partnership structures. Dominant competitive moves include exclusive feedstock arrangements between automakers and licensed facilities, and strategic technology licensing partnerships that transfer hydrometallurgical process expertise.
Within the integrated processor tier, GEM Co. Ltd. and Umicore occupy positions that exemplify divergent expansion models—Chinese smelter-refiner integration versus European technology licensing partnerships. Contemporary Amperex Technology Co. Limited anchors the battery producer archetype through closed-loop material return programs. These three entities collectively represent how procurement consolidation transfers margin pools toward vertically integrated players with proven precursor capabilities.
| Leading Market Players |
|---|
| GEM Co. Ltd. |
| Umicore |
| Contemporary Amperex Technology Co. Limited |
| LG Energy Solution |
| Exide Industries Limited |
| Samsung SDI Co. |
| GS Yuasa International Ltd |
| Neometals Ltd |
| TES |
| Others |
Value Network & Pricing Analysis
China's MEE extended producer responsibility certification gates both processor qualification and price differentiation simultaneously, forcing automakers to pay premiums for licensed facilities while unlicensed operators compete on raw material recovery rates alone. This regulatory bifurcation concentrates pricing power with permitted refiners in Jiangsu and Guangdong provinces.
Pricing Analysis
Long-term offtake contracts dominate cathode precursor procurement, with NIO and XPeng executing exclusive feedstock agreements that lock in volume discounts against spot-market volatility. Price differentiation hinges on black mass purity grades and MEE permit status, with certified processors commanding 15-20% premiums over informal channels. Cost compression in standard-grade recovery is intensifying because lithium spot discounts to virgin material persist. Fleet operators and aftermarket dismantlers show highest price sensitivity, while integrated battery producers absorb premiums for closed-loop material security.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane elevate inbound logistics costs for European hydrometallurgical equipment imports, compressing preprocessing margins at greenfield facilities. Supply concentrates in China, South Korea, and Japan, with cathode material refiners drawing from spent traction batteries aggregated through automaker collection networks. The supply chain rests on cobalt and nickel sulfate dependencies from black mass intermediates. Single-source vulnerability in lithium chemical processing creates structural risk. Distribution runs through licensed preprocessing hubs toward integrated smelter-refiner complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against direct physical recycling technology that threatens to displace full hydrometallurgical dissolution for LFP streams.
For Market Incumbents: Secure exclusive feedstock arrangements with Guangdong and Jiangsu fleet operators before BIS rules open Indian capacity gaps. Backward integration into collection vehicle fleets defends margin pools against independent dismantlers. METI disclosure requirements for Japanese offtake create certification leverage that licensed processors must exploit to maintain pricing premiums over emerging direct recycling competitors. For New Entrants and Emerging Players: Lead with Thailand and Vietnam collection network partnerships where reverse logistics infrastructure remains undeveloped. The most penetrable segment lies in second-life battery operators lacking MEE-equivalent permitting pathways. A go-to-market angle anchored in port-adjacent preprocessing zones near Bangkok and Ho Chi Minh City bypasses inland logistics deficits that constrain Chinese competitors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across direct recycling pilot programs as cathode reconstruction technology matures. Long-term viability favors processors with proven black mass-to-precursor capabilities over technology licensors without captive feedstock. Acquisition targets should display integrated smelter-refiner footprints or exclusive automaker agreements. The signal to watch is BIS final rule implementation timing, which will trigger licensed capacity scramble in Maharashtra and Gujarat corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Feedstock Agreements | NIO and XPeng contracts with Jiangsu processors lock in cathode precursor supply security. |
| Hydrometallurgical Licensing Partnerships | Umicore technology transfers expand regional capacity without capital-heavy greenfield construction. |
| Direct Cell-to-Cell Programs | CATL closed-loop agreements with domestic automakers bypass independent collector margins entirely. |
| Port-Adjacent Collection Infrastructure | Bangkok and Ho Chi Minh City zones aggregate Southeast Asian spent batteries for preprocessing scale. |
| India Preprocessing Capacity Buildout | Maharashtra and Gujarat industrial corridors position for BIS-mandated recovery rate compliance. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with MEE-licensed facility managers, automaker sustainability officers, cathode material procurement leads, and black mass trading desk operators. Secondary validation drew from MEE regulatory filings, METI circularity directive documentation, BIS draft rule consultations, customs trade data for lithium chemical imports, and SEC disclosures from listed battery producers. Bottom-up feedstock volume estimates triangulated against top-down cathode precursor demand projections.
Across the analysis window, the forecasting framework modeled segmentation by battery chemistry, recycling process route, end-user procurement type, and application sector. CAGRs derived from installed EV fleet retirement curves, battery lifecycle degradation assumptions, and regional regulatory mandate implementation schedules. Key inputs included hydrometallurgical recovery rate benchmarks and direct recycling technology maturation timelines.
The analysis sits within stated boundaries; outcomes outside sustained electric vehicle penetration rates, lithium price band stability, or regulatory enforcement consistency would require recalibration. Forecasts reflect documented assumptions on technology adoption curves and cross-border black mass trade liberalization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Battery Recycling
Transportation Battery Market
Transportation Battery Recycling
Europe Train Battery Market
Transportation Battery Recycling
Automobile Storage Battery Market
Transportation Battery Recycling
South Korea Transportation Battery Recycling Market
Transportation Battery Recycling
Automotive Energy Recovery System Market
Transportation Battery Recycling
Europe Automotive Start-Stop Battery Market
Transportation Battery Recycling
EV Battery Recycling Services Market
Transportation Battery Recycling
Two-Wheeler Battery Market
Transportation Battery Recycling
Transportation Battery Recycling Market
Transportation Battery Recycling
ASEAN Electric Vehicle Battery Anode Market
Transportation Battery Recycling
China Transportation Battery Recycling Market
Transportation Battery Recycling
Automotive Battery Recycling Market