
 ASEAN Electric Vehicle Battery Anode Market | 2026-2036
ASEAN Electric Vehicle Battery Anode Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Electric Vehicle Battery Anode Market Insights
Project finance tied to integrated nickel-to-battery corridors is tilting competitive advantage toward firms with upstream resource access. BTR New Material Group Co., Ltd. leverages its graphite processing scale to supply ASEAN cell plants directly from China. Panasonic Corporation anchors regional demand through partnerships with Thai and Indonesian OEM assembly lines. LG Energy Solution Ltd competes by licensing its silicon-anode formulations to local battery joint ventures.
ASEAN Electric Vehicle Battery Anode refers to the negative electrode material in lithium-ion cells, typically comprising synthetic or natural graphite with layered carbon structures that intercalate lithium ions during charge cycles; manufacturers engineer particle size, porosity, and surface coatings to optimize Coulombic efficiency and cycle life for tropical climates. Graphite Anode retains the dominant share across passenger vehicle applications due to established supply chains and cost structures, though Silicon Composite formulations are gaining traction in premium BEV platforms where energy density targets exceed 300 Wh per kilogram. Battery Manufacturers represent the most concentrated end-user channel, with OEMs increasingly demanding long-term offtake contracts that lock in volume and specification tiers.
Thailand's Board of Investment incentives and Indonesia's downstream mineral processing rules are reshaping where anode precursor refining occurs, compelling suppliers to locate graphite spheronization and coating facilities within ASEAN tariff zones. METI technical cooperation frameworks between Japan and ASEAN member states further influence quality certification pathways for anode materials entering integrated regional supply chains. Stakeholders must track how Indonesia's export restrictions on unprocessed nickel and Thailand's evolving EV tax incentives redirect capital flows across the anode value chain.
Market Dynamics
ASEAN Electric Vehicle Battery Anode procurement patterns are compressing as Thailand's Board of Investment incentives and Indonesia's downstream mineral processing mandates force suppliers to relocate graphite spheronization and coating facilities within regional tariff zones. The interplay between nickel export restrictions and EV tax incentives is redrawing where precursor refining occurs.
Growth Catalysts
- Indonesia's downstream mineral processing mandates:Localized nickel-to-battery corridors are compelling anode precursor producers to establish spheronization plants within Morowali industrial park boundaries.
- Thailand's Eastern Economic Corridor battery cluster:Mass-market fleet operators across Bangkok and Rayong provinces are intensifying procurement of high-capacity synthetic graphite anodes for commercial EV platforms.
- METI technical cooperation frameworks:Japanese-ASEAN quality certification pathways are accelerating anode material acceptance into integrated regional supply chains serving Thai and Indonesian cell plants.
Market Restraints
- Graphite feedstock concentration:Overreliance on Chinese spherical graphite supplies exposes ASEAN cell manufacturers to tariff volatility and export licensing disruptions.
- Silicon expansion limitations:Silicon composite anodes face cycle life degradation in tropical humidity conditions, constraining adoption in Indonesia's ambient climate range.
- Indonesia's unprocessed nickel export bans:Restrictions on raw ore shipments have elevated precursor input costs for anode producers lacking integrated smelter partnerships.
Strategic Opportunities
- Vietnam's emerging EV manufacturing base:VinFast's expanding cell production in Haiphong creates uncontracted anode offtake demand currently served by distant suppliers.
- Philippines nickel laterite integration:Untapped hydrometallurgical processing capacity in Surigao offers alternative precursor sourcing outside Indonesia's regulatory perimeter.
- Malaysia's national EV roadmap:Tax incentives for battery assembly in Penang and Kulim are attracting anode coating facilities to serve ASEAN's premium passenger segment.
Industry Challenges
- Spheronization technician scarcity:ASEAN labor pools lack sufficient trained personnel for precision particle engineering and surface coating operations at commercial scale.
- Dual certification timelines:Simultaneous compliance with Japan's JIS standards and Indonesia's national battery regulations extends product qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Electric Vehicle Battery Anode Market |
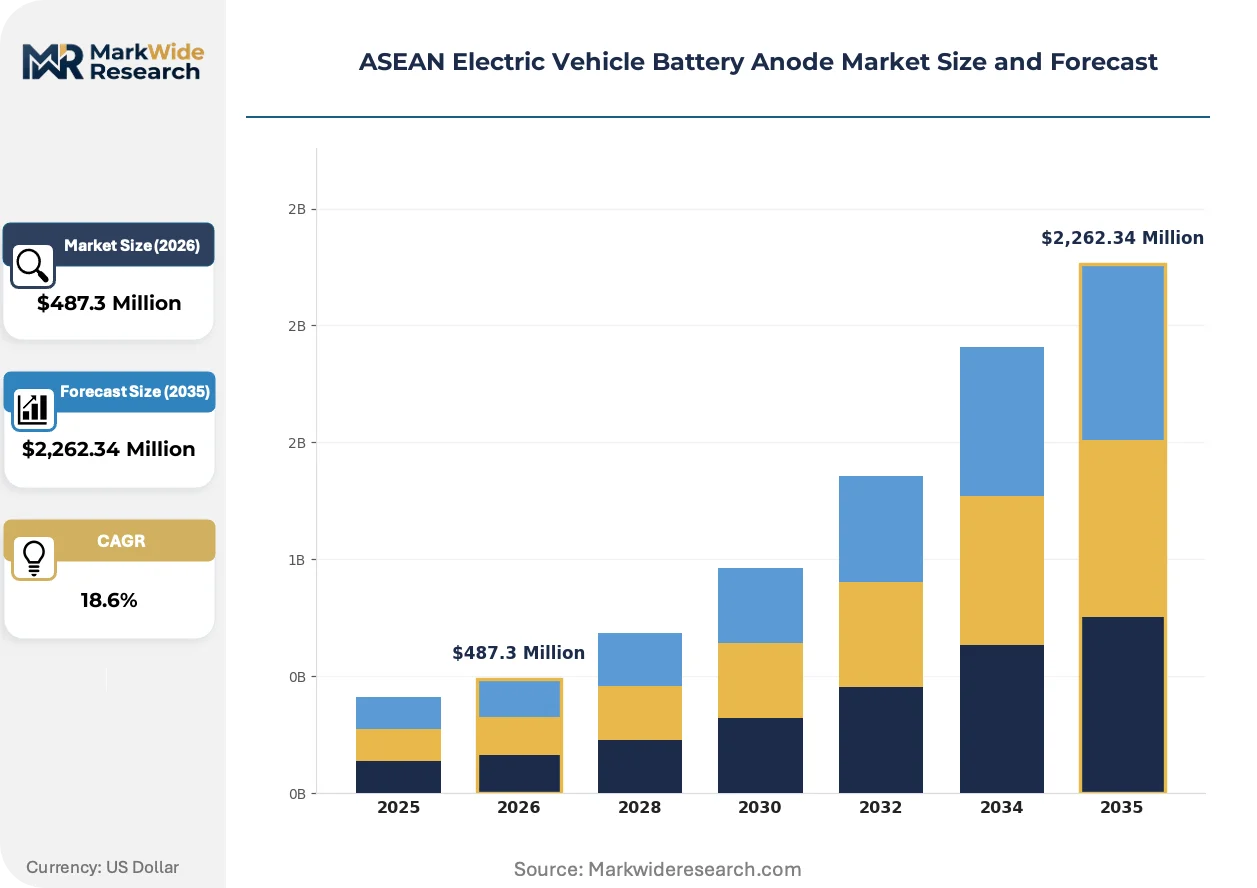
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphite Anode, Lithium Titanate, Silicon Composite, Hard Carbon End User: OEMs, Aftermarket Providers, Battery Manufacturers, Research Institutions Technology: PHEV, BEV, Solid-State, Hybrid Technology Application: Passenger Vehicles, Commercial Fleets, E-Bikes, Energy Storage Systems |
| Companies Covered | Shenzhen Dynanonic Co., Ltd., Mitsubishi Chemical Group Corporation, Targray Technology International Inc., Samsung SDI Co Ltd, LG Energy Solution Ltd, Hitachi Chemical Company Ltd, BTR New Material Group Co., Ltd., Contemporary Amperex Technology Co Ltd, Panasonic Corporation, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Electric Vehicle Battery Anode Market Trends and Innovations
Silicon-doped graphite formulations and dry electrode coating processes are actively reshaping how ASEAN cell plants specify anode materials. The convergence of tropical climate engineering requirements with cost-down pressures from mass-market EV programs is accelerating process innovation across the value chain.
Synthetic graphite with silicon oxide surface coatings is migrating from premium BEV platforms to mid-range passenger applications as Thai and Indonesian OEMs pursue 300 Wh per kilogram cell targets. Fleet operators in Bangkok's commercial EV programs are piloting these formulations for route buses. The technology shift is compressing qualification timelines for traditional pure-graphite suppliers.
Indonesia's downstream mineral processing rules are mandating that nickel sulfate and cobalt precursor refining occur within national boundaries before export or further processing. Cell manufacturers in Morowali industrial park must now source hydroxide inputs from locally permitted smelters. Thai anode producers are responding by negotiating tolling agreements with Indonesian nickel processors.
Long-term offtake contracting is displacing spot market purchasing as the dominant procurement mode among ASEAN battery manufacturers. OEMs in Thailand's Eastern Economic Corridor are locking five-year volume commitments with specification tiers tied to Coulombic efficiency thresholds. This pattern is most visible in negotiations between Thai cell plants and Chinese graphite processors seeking tariff-advantaged ASEAN production bases.
ASEAN Electric Vehicle Battery Anode Market Segmentation
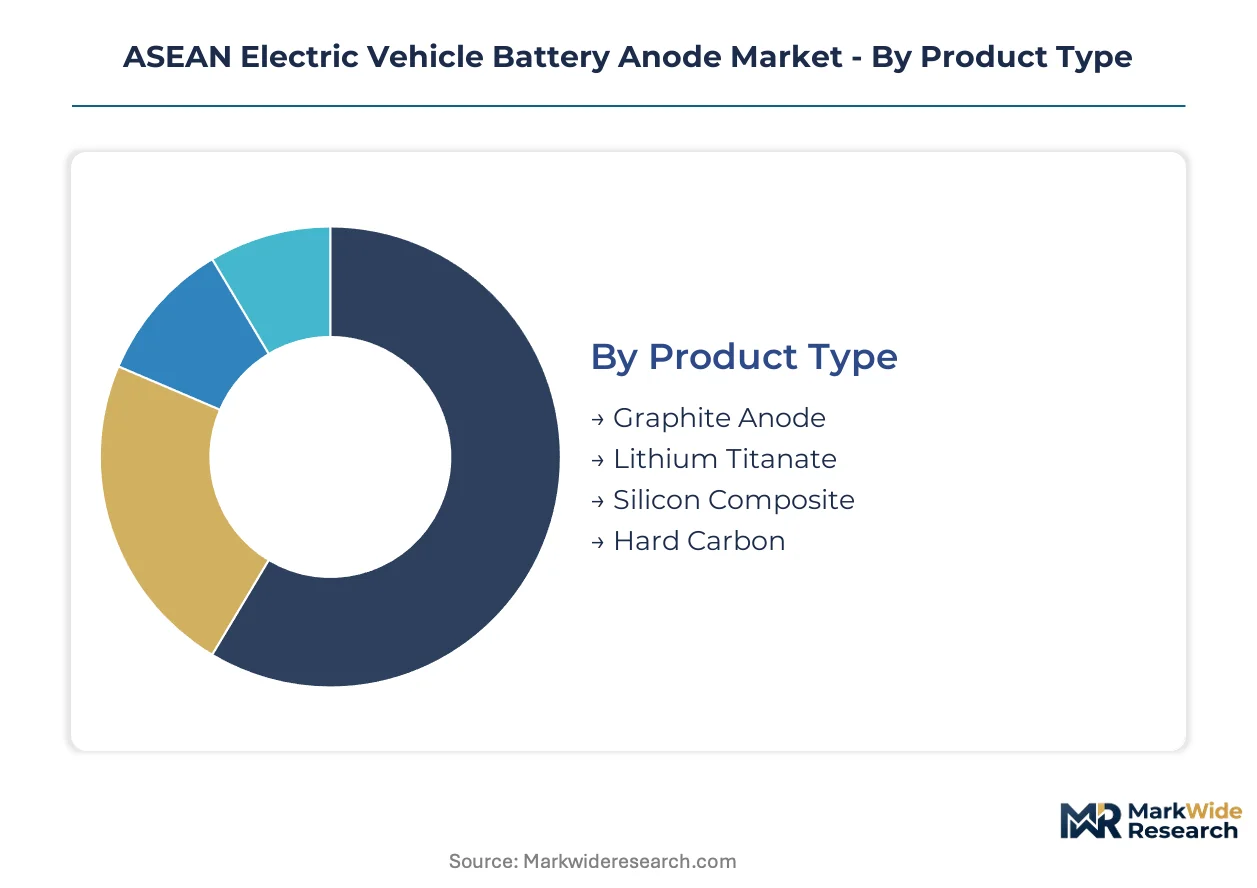
Segmentation reveals how procurement specifications diverge across ASEAN's emerging battery supply chain. Thai and Indonesian cell plants impose distinct technical requirements based on end-use climate exposure and OEM integration depth.
Product Type:
After-sales service intensity varies sharply by anode chemistry, with silicon composite formulations demanding specialized technical support for cycle life optimization in tropical humidity.
- Graphite Anode:Synthetic and natural graphite with layered carbon structures intercalate lithium ions during charge cycles. Thai OEMs in the Eastern Economic Corridor specify spherical graphite with controlled porosity for commercial fleet applications facing Bangkok's ambient humidity. Established supply chains from Chinese processors dominate procurement.
- Silicon Composite:Silicon-doped formulations achieve energy density above 300 Wh per kilogram through oxide surface coatings. Indonesian premium BEV platforms in Morowali industrial park are piloting these materials despite cycle degradation risks in uncontrolled tropical storage conditions.
- Lithium Titanate:Spinel oxide structure delivers exceptional cycle stability for high-frequency charging applications. Thai route bus operators favor this chemistry for rapid-charge depot infrastructure.
- Hard Carbon:Amorphous carbon structure from biomass precursors offers sodium-ion compatibility. Research institutions in Malaysia's national EV roadmap trials evaluate this for cost-sensitive e-mobility.
By volume, Graphite Anode leads. By growth pace, Silicon Composite is ahead.
End User:
Cost tier stratification separates specification-intensive OEM contracts from price-sensitive aftermarket procurement channels.
- Battery Manufacturers:Cell plants in Thailand's Eastern Economic Corridor and Indonesia's Morowali industrial park concentrate demand through five-year offtake contracts with Coulombic efficiency thresholds. These buyers lock volume commitments to secure tariff-advantaged ASEAN production bases.
- OEMs:Thai and Indonesian vehicle assemblers specify anode materials directly for integrated battery pack production. METI technical cooperation frameworks accelerate their quality certification pathways.
- Aftermarket Providers:Independent replacement cell suppliers serve secondary vehicle markets with standardized graphite formulations. Price sensitivity dominates procurement decisions.
- Research Institutions:Malaysian and Vietnamese technical universities evaluate next-generation anode chemistries for tropical climate adaptation. Funding ties to national EV roadmaps shape project priorities.
Battery Manufacturers capture the largest procurement volume. OEMs are expanding their direct sourcing fastest.
Technology:
Application maturity determines qualification timeline compression, with solid-state platforms demanding extended validation cycles.
- BEV:Pure battery electric platforms drive high-capacity anode demand across Thai commercial fleets and Indonesian passenger segments. Energy density targets above 300 Wh per kilogram favor advanced graphite and silicon composite formulations.
- PHEV:Plug-in hybrid systems balance electric range with combustion backup, specifying moderate-capacity anodes for cost-optimized cell designs. Thai mass-market passenger applications concentrate this demand.
- Hybrid Technology:Conventional hybrid electric vehicles utilize smaller battery packs with power-optimized anode specifications. Indonesian domestic market models feature prominently.
- Solid-State:Emerging lithium-metal anode compatibility requirements are reshaping material qualification protocols. Japanese-ASEAN technical cooperation frameworks influence regional development priorities.
BEV technology commands the largest installed base. Solid-State is climbing the fastest despite extended timelines.
Application:
Customer type segmentation separates fleet procurement with centralized technical support from dispersed consumer vehicle markets.
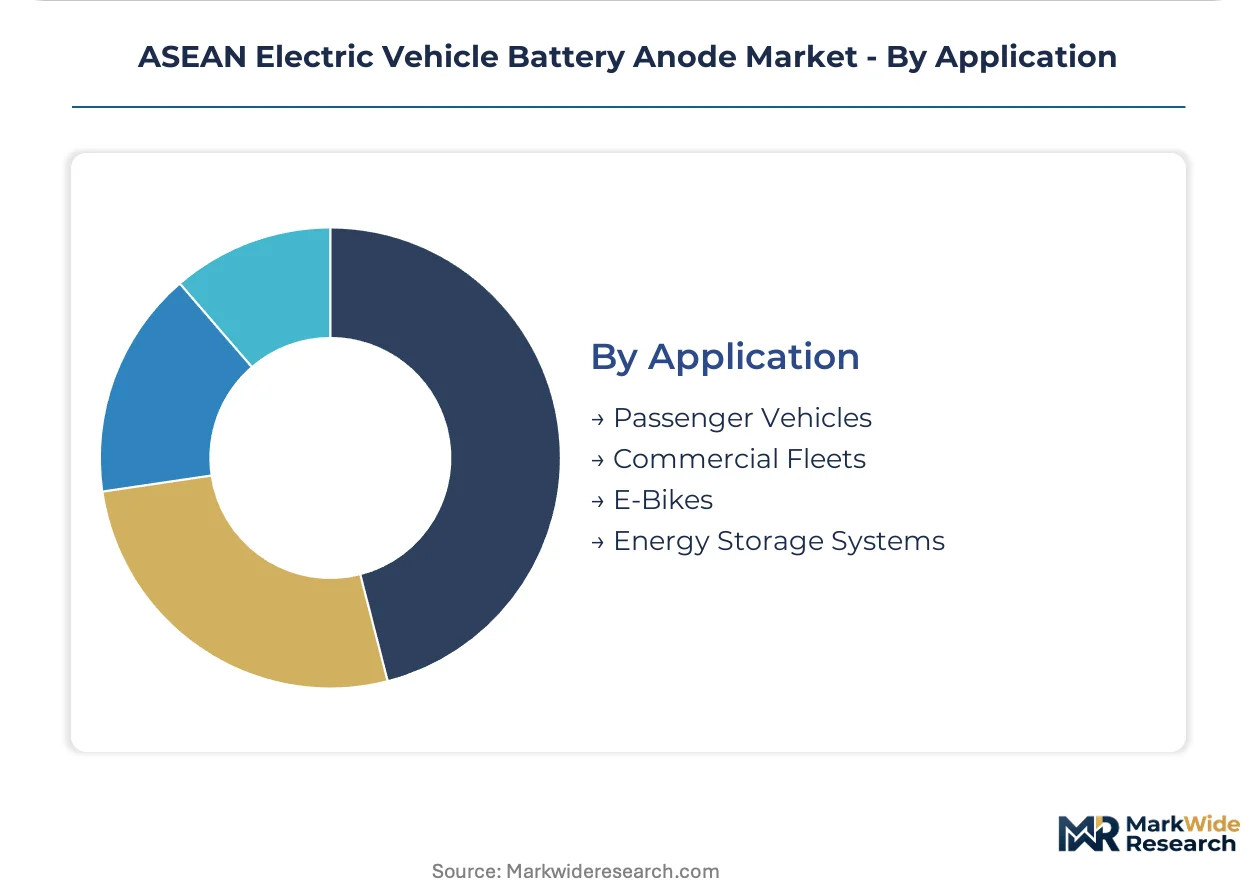
- Passenger Vehicles:Thai and Indonesian OEM assembly lines specify anode materials for private ownership models across economy to premium tiers. Range anxiety drives energy density priorities in urban Bangkok and Jakarta markets.
- Commercial Fleets:Route bus and logistics operators in Thailand's Eastern Economic Corridor pilot high-capacity silicon composite anodes for depot-charge optimization. Fleet-scale procurement enables direct supplier negotiations.
- E-Bikes:Two-wheel electric mobility in Vietnamese and Indonesian urban centers utilizes cost-optimized graphite anodes with simplified thermal management. Volume concentration in Ho Chi Minh City and Jakarta shapes supplier focus.
- Energy Storage Systems:Grid-scale battery installations for renewable integration specify cycle-life optimized anode materials. Malaysian solar-plus-storage projects in Penang represent emerging demand.
Passenger Vehicles lead by current volume. Commercial Fleets are gaining share fastest through fleet electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ASEAN Electric Vehicle Battery Anode Market exhibits a pronounced import dependency for graphite feedstock, with regional cell manufacturers sourcing spherical graphite predominantly from Chinese processors while exporting finished battery cells to European and North American automotive OEMs. This trade asymmetry is compelling anode precursor producers to relocate spheronization and coating capacity within ASEAN tariff zones to capture value-added processing margins.
Thailand
Fleet electrification mandates across Bangkok's commercial bus networks and Rayong province logistics corridors are intensifying procurement of high-capacity synthetic graphite anodes. Thailand's Board of Investment offers eight-year tax holidays for battery material manufacturing investments exceeding specified capital thresholds. The Eastern Economic Corridor battery cluster in Chonburi and Rayong provinces hosts expanding cell plants that negotiate five-year offtake contracts with Coulombic efficiency specifications.
Indonesia
Downstream mineral processing mandates are compelling nickel sulfate and cobalt precursor refining to occur within Morowali industrial park boundaries before export or further processing. Indonesia's unprocessed nickel export bans have elevated input costs for anode producers lacking integrated smelter partnerships. The Morowali industrial park in Central Sulawesi concentrates cell manufacturing capacity that must source hydroxide inputs from locally permitted smelters under national battery regulations.
Malaysia
Tax incentives for battery assembly in Penang and Kulim are attracting anode coating facilities to serve ASEAN's premium passenger vehicle segment. Malaysia's national EV roadmap prioritizes local cell production capacity to reduce import dependency for electric mobility platforms. The Kulim High-Tech Park in Kedah state hosts emerging battery joint ventures that specify anode materials through Japanese-ASEAN technical cooperation frameworks.
Vietnam
VinFast's expanding cell production in Haiphong creates uncontracted anode offtake demand currently served by distant suppliers from China and South Korea. Vietnam's emerging EV manufacturing base lacks domestic anode precursor capacity, exposing procurement to shipping cost volatility and extended lead times. The Haiphong industrial zone in northern Vietnam concentrates VinFast's battery operations that pilot silicon composite formulations for premium BEV platforms.
ASEAN Electric Vehicle Battery Anode Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying refined anode materials to cell plants under long-term offtake arrangements. The vendor base stratifies across three tiers: integrated battery manufacturers with captive anode development, independent material processors with spheronization scale, and regional trading houses facilitating feedstock logistics. Dominant competitive moves include backward integration into nickel smelting partnerships and technology licensing agreements for silicon-anode formulations.
Within the integrated battery manufacturer tier, LG Energy Solution Ltd and Samsung SDI Co Ltd exemplify platform integrators that license advanced anode chemistries to ASEAN joint ventures. Panasonic Corporation anchors Japanese-ASEAN supply chain integration through METI technical cooperation frameworks. Among Chinese material processors, BTR New Material Group Co., Ltd. occupies a position representing graphite processing scale that supplies ASEAN cell plants directly through established logistics corridors.
| Leading Market Players |
|---|
| Shenzhen Dynanonic Co., Ltd. |
| Mitsubishi Chemical Group Corporation |
| Targray Technology International Inc. |
| Samsung SDI Co Ltd |
| LG Energy Solution Ltd |
| Hitachi Chemical Company Ltd |
| BTR New Material Group Co., Ltd. |
| Contemporary Amperex Technology Co Ltd |
| Panasonic Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese spherical graphite processing is compressing margins across ASEAN anode procurement channels, forcing regional cell manufacturers to renegotiate contract terms while suppliers absorb logistics cost escalations. Thai and Indonesian buyers exploit this utilization imbalance to secure Coulombic efficiency guarantees without price premiums, reshaping how graphite spheronization facilities value their ASEAN tariff-zone positioning.
Pricing Analysis
Industrial OEM buyers anchor long-term offtake contracting as the dominant pricing structure across ASEAN cell plants. Price differentiation rests on certification tier under METI-JIS frameworks and volume scale commitments exceeding five-year horizons. Cost compression in synthetic graphite feedstocks is intensifying because Chinese processors compete for ASEAN tolling agreements. Fleet operators in Thailand's Eastern Economic Corridor demonstrate highest price sensitivity, while premium BEV platforms in Indonesia's Morowali park accept silicon composite premiums for energy density above 300 Wh per kilogram.
Supply Chain Analysis
Extended payment terms from Thai and Indonesian cell plants are straining working capital for Chinese graphite processors seeking ASEAN production bases. Geographic supply concentration centers on China for spherical graphite feedstock, Indonesia for nickel sulfate precursors, and Japan for silicon-anode licensing. Raw material dependencies draw from petroleum coke needle stocks, nickel laterite ores, and cobalt hydroxide intermediates. Single-source vulnerability to Chinese export licensing disruptions represents the dominant structural risk. Distribution runs through regional battery joint ventures with captive tolling arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN Electric Vehicle Battery Anode procurement cycles track nickel price volatility and fleet electrification mandate timing, positioning the market for cyclical recovery as Indonesia's downstream processing rules mature and Thai commercial EV subsidies stabilize.
For Market Incumbents: Insulate margin structures by securing captive nickel smelter partnerships in Morowali industrial park before precursor input costs escalate further. Accelerate JIS certification investment to maintain specification tier premiums against emerging Chinese processors with tariff-advantaged ASEAN facilities. Lock five-year offtake volumes with Thai fleet operators now entering procurement cycles.
For New Entrants and Emerging Players: Vietnam's uncontracted anode demand from VinFast's Haiphong operations offers the most penetrable white-space target in the regional landscape. Target Philippines Surigao nickel laterite integration as alternative precursor sourcing outside Indonesia's regulatory perimeter. Pursue tolling agreements with established Chinese spheronization specialists rather than greenfield capacity builds.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among anode coating facilities with captive ASEAN cell plant relationships and METI-JIS dual certification. Five-to-ten year viability favors processors with backward integration into nickel hydroxide supply and silicon-anode licensing rights. Watch Indonesian export restriction enforcement intensity as the inflection signal for precursor cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Smelting | Morowali industrial park partnerships secure precursor supply under Indonesia's downstream processing mandates. |
| Silicon-Anode Technology Licensing | Japanese-ASEAN METI frameworks accelerate qualification timelines for premium BEV energy density targets. |
| ASEAN Tariff-Zone Production Relocation | Thai Board of Investment incentives capture value-added margins from Chinese feedstock processing. |
| Long-Term Offtake Contracting | Five-year volume commitments with Coulombic efficiency tiers lock procurement relationships with Eastern Economic Corridor cell plants. |
| Dual Certification Investment | Simultaneous JIS and Indonesian national battery compliance compresses product qualification cycles for regional supply chains. |
Research Methodology
Cross-validation between primary interviews with ASEAN cell plant procurement directors, graphite processing technical leads, and nickel smelter operators anchors the qualitative findings against secondary validation. Battery manufacturer supply chain managers, METI technical cooperation framework coordinators, and Thai Board of Investment incentive program administrators provided operational perspective. Secondary sources include Indonesia's mineral export regulation filings, Thai customs battery material trade data, JIS standard certification registries, and ASEAN automotive production databases. Bottom-up cell plant capacity builds and top-down EV fleet deployment targets triangulate market sizing.
Calibration against historical anode material procurement cycles and nickel price correlation patterns shapes the analytical framework across the projection horizon. Segmentation dimensions span anode chemistry type, end-user procurement channel, vehicle propulsion architecture, and regional production cluster regulatory environment. CAGRs derive from installed cell capacity ramp rates and fleet electrification mandate implementation schedules. Silicon composite adoption curves and tropical climate degradation factors inform technology transition modeling.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Chinese graphite processors or accelerated solid-state battery development would shift outcomes. Macroeconomic deviation in nickel commodity markets, regulatory enforcement intensity variations across Indonesian export restrictions, or breakthrough silicon-anode cycle life improvements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Battery Recycling
Automotive Energy Recovery System Market
Transportation Battery Recycling
Asia-Pacific Transportation Battery Recycling Market
Transportation Battery Recycling
Automotive Battery Recycling Market
Transportation Battery Recycling
China Transportation Battery Recycling Market
Transportation Battery Recycling
Transportation Battery Recycling Market
Transportation Battery Recycling
Europe Train Battery Market
Transportation Battery Recycling
Europe Automotive Start-Stop Battery Market
Transportation Battery Recycling
Automobile Storage Battery Market
Transportation Battery Recycling
EV Battery Recycling Services Market
Transportation Battery Recycling
South Korea Transportation Battery Recycling Market
Transportation Battery Recycling
Transportation Battery Market
Transportation Battery Recycling
Two-Wheeler Battery Market