
 Transportation Battery Recycling Market | 2026-2036
Transportation Battery Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Transportation Battery Recycling Market Outlook
Project finance tied to offtake agreements for recovered battery metals is rewriting competitive entry conditions in transportation battery recycling. Li-Cycle Corp leverages tolling partnerships with automakers to secure feedstock without owning collection fleets. Umicore anchors its position through in-house production of cathode precursors from recycled streams. Redwood Materials controls a closed-loop model spanning end-of-life vehicle intake to refined battery-grade materials.
Transportation battery recycling encompasses the collection, dismantling, and material recovery of spent traction batteries from electric and hybrid vehicles, typically involving processes that achieve recovery rates exceeding 95% for cobalt and nickel through hydrometallurgical circuits designed to produce battery-grade sulfates. The primary purpose is to reintroduce critical minerals into cathode manufacturing, reducing dependence on mined primary supply. Lithium-ion recycling leads value capture due to soaring electric vehicle retirement volumes, while lead-acid processing sustains margin stability through mature reverse logistics serving internal combustion fleet operators. Hydrometallurgical technology dominates new capacity investments because it yields higher purity outputs suited to direct cathode remanufacturing, whereas pyrometallurgical routes occupy a shrinking role limited to mixed-waste feedstocks with lower lithium recovery efficiency.
The EU Battery Regulation and REACH compliance frameworks in Europe mandate minimum recycled content thresholds and restricted substance declarations, compelling OEMs to integrate certified recycling partners into supply agreements. The EPA oversees hazardous waste classification for spent lithium-ion batteries in the United States, while China's MIIT and GB standards govern recycling facility licensing and discharge limits. Stakeholders must monitor how evolving extended producer responsibility schemes reshape cost allocation between vehicle manufacturers and independent recyclers.
Market Dynamics
EU Battery Regulation mandates are forcing electric vehicle OEMs to secure certified recycling partnerships ahead of 2030 recycled content thresholds, compressing the timeline for feedstock access negotiations and facility commissioning.
Growth Catalysts
- EU Battery Regulation:Minimum recycled content mandates for lithium, cobalt, and nickel in new traction batteries create binding offtake demand for certified recyclers across Germany, France, and Poland manufacturing corridors.
- LFP chemistry proliferation:Iron-phosphate battery retirements from Chinese-built electric buses and entry-level passenger vehicles are diversifying feedstock streams beyond cobalt-rich chemistries.
- Tianjin-Ningbo corridor:Hydrometallurgical processing clusters concentrated around these port cities achieve economies of scale in lithium carbonate recovery that European greenfield projects cannot yet match.
Market Restraints
- Spent battery logistics:UN 38.3 hazmat classification and limited UN-certified container availability constrain cross-border feedstock movement from collection points to processing facilities.
- Black mass pricing volatility:Uncertainty in nickel and cobalt London Metal Exchange pricing transmits directly to recycler feedstock acquisition costs, compressing margin visibility for tolling contract negotiations.
- Pyrometallurgical legacy:Smelter-based recovery routes suffer lithium volatilization losses exceeding 30%, rendering them uneconomic for next-generation cathode remanufacturing specifications.
Strategic Opportunities
- India PLI scheme extension:Cell manufacturing incentives under the country's production-linked incentive framework create parallel demand for domestic recycling capacity to satisfy local content requirements.
- Direct recycling:Cathode regeneration without full elemental dissolution preserves crystal structure and reduces reagent consumption by half compared to conventional hydrometallurgical flowsheets.
- Automaker captive collection:Reverse logistics partnerships with dealership networks unlock proprietary feedstock access without competing for independent scrap aggregator volumes.
Industry Challenges
- Battery passport implementation:Digital twin documentation requirements under EU Battery Regulation demand data architecture investments that smaller recyclers lack capital to deploy.
- Electrolyte handling protocols:Fluorinated salt decomposition and toxic gas management during dismantling require specialized ventilation infrastructure absent from lead-acid recycling retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transportation Battery Recycling Market |
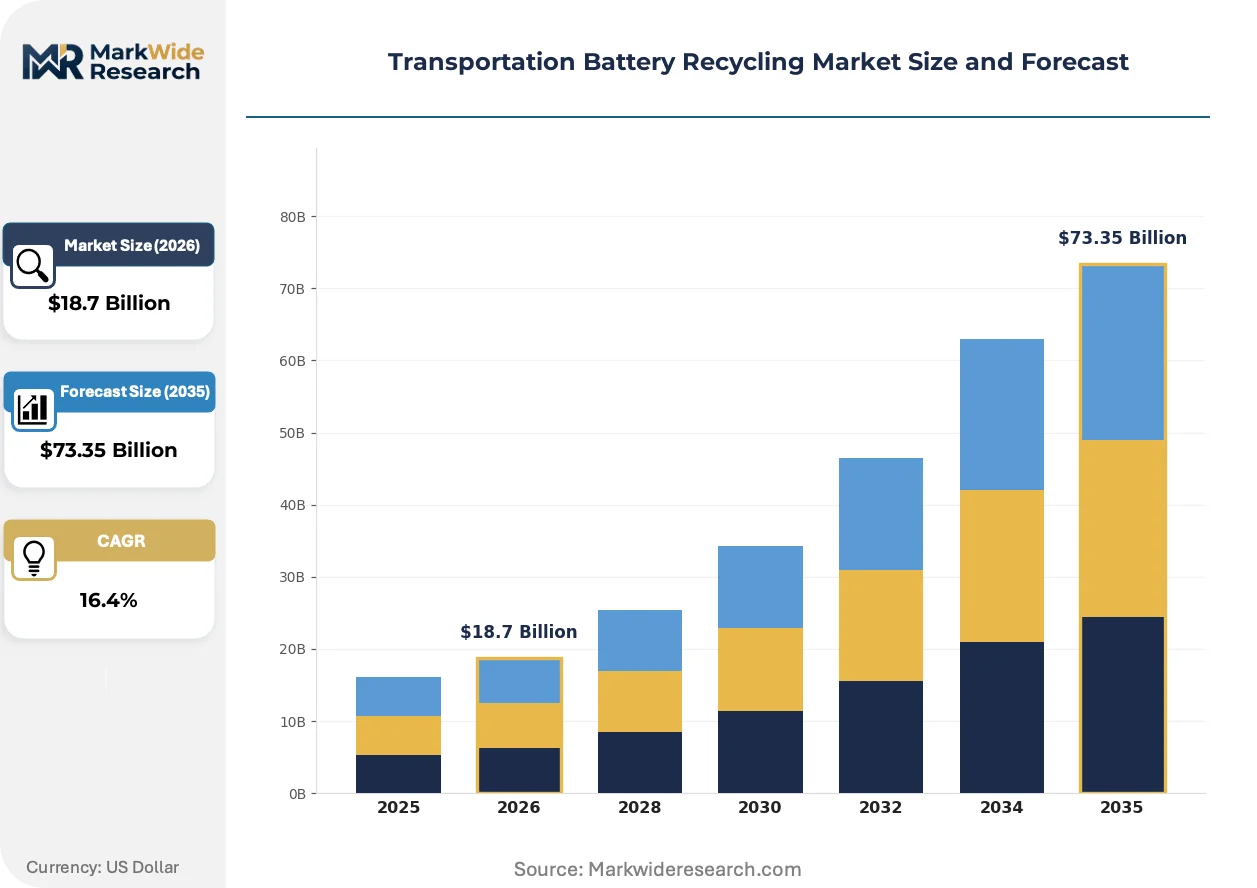
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Others End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Service Type: Collection Services, Processing Services, Logistics Services, Consulting Services Technology: Hydrometallurgical, Pyrometallurgical, Biotechnological, Mechanical |
| Companies Covered | Umicore, Li-Cycle Corp, Aqua Metals, Exide Technologies, Call2Recycle, Battery Solutions, Ecobat, GEM Co. Ltd., Redwood Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transportation Battery Recycling Market Strategic Shifts
Processing technology maturation and regulatory data requirements are converging to reshape competitive capabilities across the recycling value chain.
Automated disassembly systems equipped with machine vision and robotic sorting arms are digitizing black mass preparation workflows. Tier-1 recyclers in South Korea and Germany are deploying these lines to handle format diversity from cylindrical 18650 cells to large-format pouch architectures. The technology is digitizing workforce requirements and throughput consistency, compressing the labor cost gap between established and emerging recycling jurisdictions.
China's MIIT has tightened GB/T 34014-2023 standards for recycling facility licensing, mandating closed-loop water systems and air emission monitoring that match European environmental benchmarks. The regulation is accelerating consolidation among smaller processors in Jiangsu and Guangdong provinces. Battery-grade material producers are responding by integrating recycling subsidiaries to secure compliant feedstock streams.
Automakers are unbundling end-of-life service contracts from vehicle sales, creating direct recycling procurement relationships separate from traditional aftermarket channels. BMW and Volkswagen have established separate legal entities for battery collection in Germany and the United States. The shift is most visible in Nordic markets where extended producer responsibility schemes assign clear cost allocation between manufacturers and independent recyclers.
Transportation Battery Recycling Market Segmentation
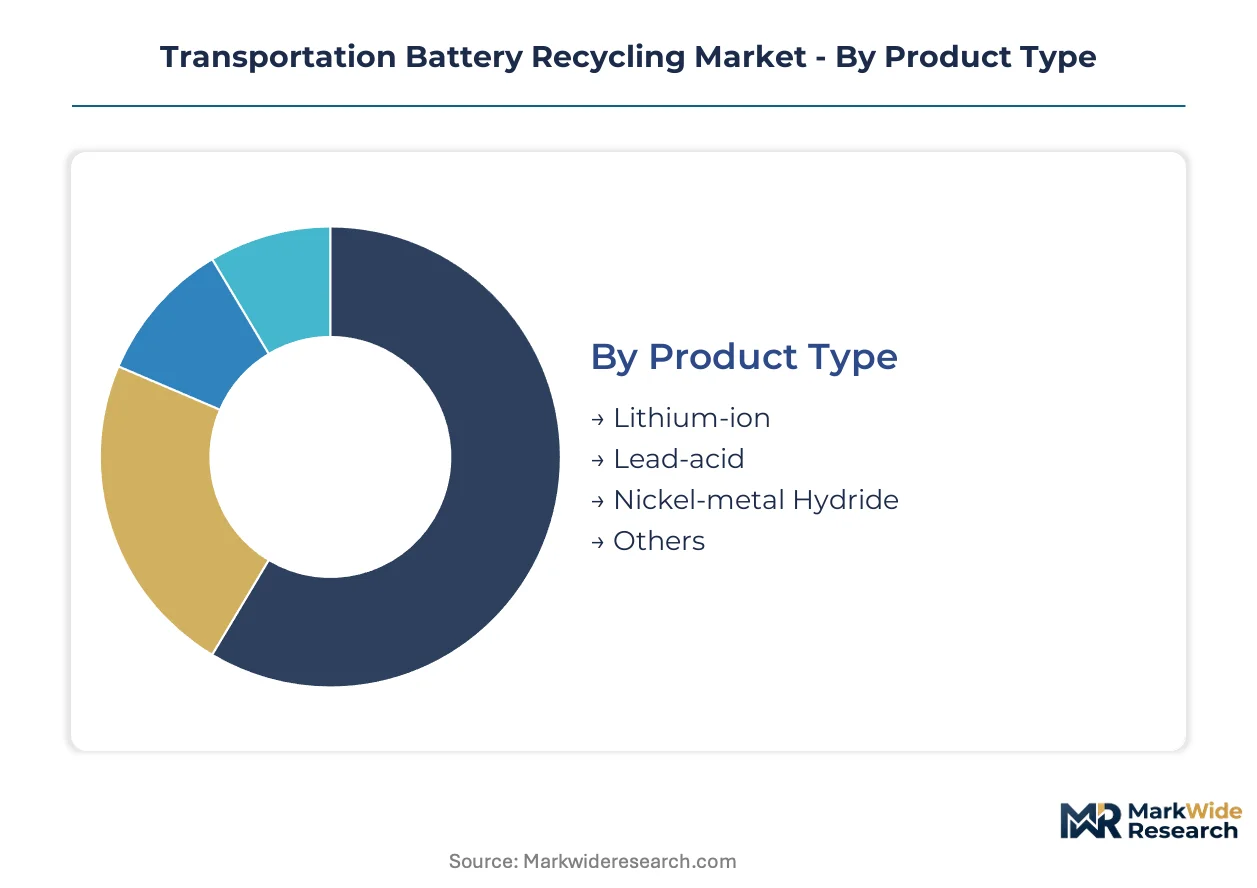
Segmentation in transportation battery recycling reveals how value pools concentrate across chemistry types, customer relationships, and processing technologies. Each dimension carries distinct margin profiles and capital intensity requirements that shape competitive positioning.
Product Type:
Chemistry composition determines recovery economics and regulatory treatment across collection and refining stages.
- Lithium-ion:Spent traction batteries from electric vehicles deliver cobalt, nickel, and lithium concentrates through hydrometallurgical circuits. Retirements from Chinese-built passenger vehicles and European bus fleets are concentrating feedstock availability around Tianjin and Ningbo industrial zones.
- Lead-acid:Mature reverse logistics networks serving internal combustion engine fleets sustain stable margin structures through established smelter infrastructure. Processing concentrates in United States Midwest and Indian industrial corridors where automotive aftermarket density supports collection route efficiency.
- Nickel-metal Hydride:Hybrid vehicle battery packs from Japanese and Korean manufacturers require specialized dismantling protocols.
- Others:Emerging solid-state and sodium-ion chemistries present unproven recovery pathways for pilot-scale recyclers.
Lithium-ion holds installed capacity. Lead-acid is rotating up the share rankings in absolute volume terms through fleet turnover cycles.
End User:
Customer type dictates contract structure, feedstock security, and pricing power in feedstock procurement.
- OEMs:Electric vehicle manufacturers under EU Battery Regulation mandates are building captive collection networks to satisfy recycled content thresholds. Volkswagen and BMW have established separate legal entities for end-of-life battery management in Germany and United States markets.
- Aftermarket Providers:Independent scrap aggregators and dismantlers compete for fragmented feedstock across dealership networks and insurance salvage channels. Margin pressure intensifies as automakers unbundle service contracts from vehicle sales.
- Vehicle Assemblers:Contract manufacturers for electric bus and truck platforms seek tolling partnerships to manage warranty-related battery returns.
- Fleet Operators:Municipal transit authorities and logistics companies with centralized depots offer consolidated collection points for high-volume recyclers.
OEMs are consolidating procurement relationships. Fleet operators are gaining negotiating leverage through volume aggregation.
Service Type:
Value chain position determines capital requirements and margin exposure to commodity price volatility.
- Collection Services:Reverse logistics operators manage UN 38.3 hazmat-compliant transport from collection points to processing facilities. Limited certified container availability constrains cross-border movement between European member states.
- Processing Services:Black mass preparation and hydrometallurgical refining command the highest value capture in the recycling chain. Tianjin-Ningbo corridor processors achieve scale economies that European greenfield projects cannot yet replicate.
- Logistics Services:Specialized carriers handle electrolyte containment and thermal runaway mitigation during transport.
- Consulting Services:Technical advisory on battery passport implementation and regulatory compliance supports smaller recyclers lacking in-house data architecture.
Processing services command margin concentration. Collection services are climbing fastest as feedstock access becomes the binding constraint.
Technology:
Recovery method selection determines purity outputs, lithium yields, and environmental compliance costs.
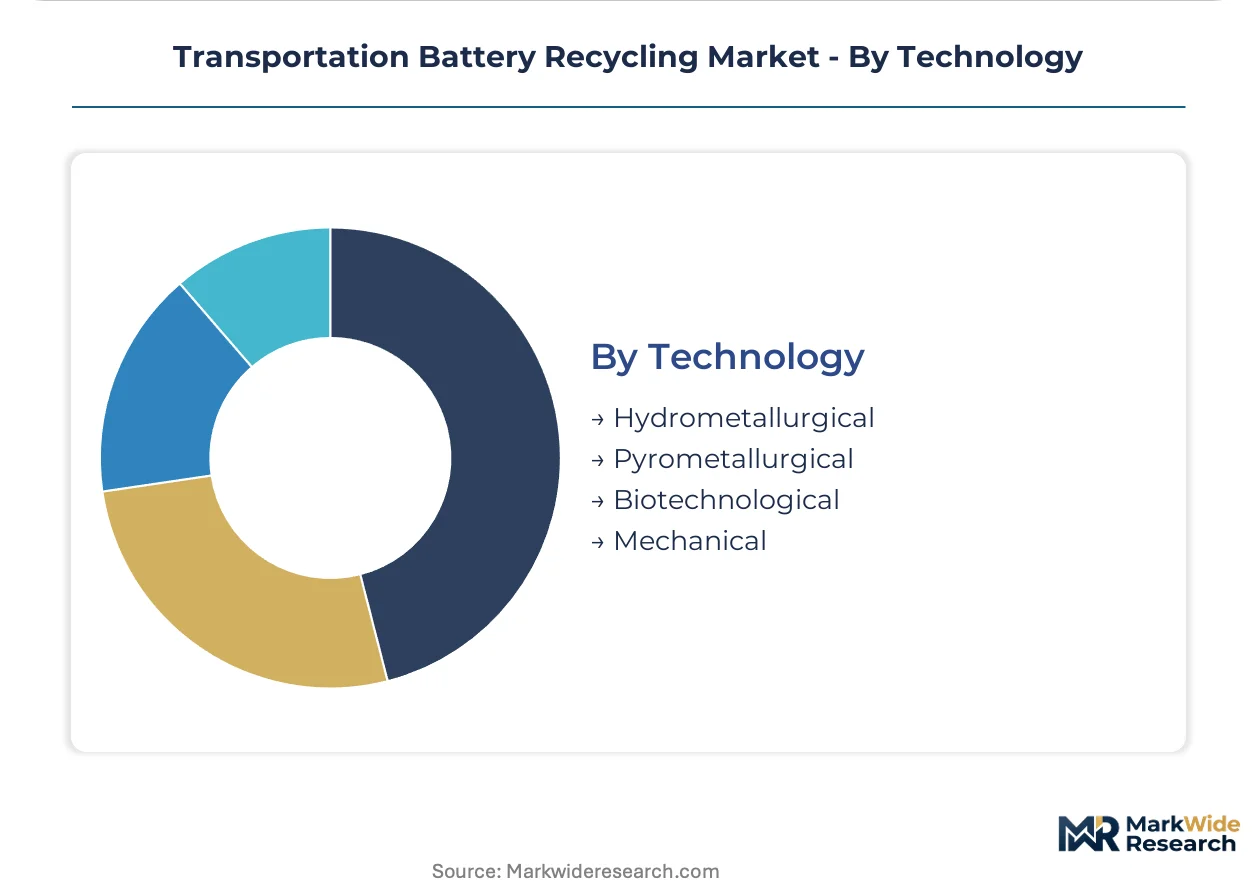
- Hydrometallurgical:Acid-leaching circuits achieve battery-grade sulfate purity exceeding 99.5% for direct cathode remanufacturing. New capacity investments concentrate in South Korea and Germany where automated disassembly lines integrate with chemical refining.
- Pyrometallurgical:High-temperature smelting suffers lithium volatilization losses exceeding 30%, rendering routes uneconomic for next-generation cathode specifications. Legacy capacity persists for mixed-waste feedstocks with lower recovery requirements.
- Biotechnological:Bioleaching using acidophilic bacteria reduces reagent consumption but remains at pilot scale.
- Mechanical:Shredding and physical separation prepares black mass for downstream refining without chemical dissolution.
Hydrometallurgical dominates new investment. Mechanical processing is expanding most quickly as a pre-treatment step for integrated facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Battery Regulation mandates are accelerating facility investments across Germany, France, and Poland as automakers race to secure certified recycling partnerships ahead of 2030 recycled content thresholds. China's MIIT licensing reforms are consolidating processing capacity around Tianjin and Ningbo port clusters. The United States EPA hazardous waste classification creates compliance barriers that favor integrated operators with established reverse logistics networks.
China
Retirement volumes from domestic electric vehicle fleets are concentrating feedstock availability around Yangtze River Delta manufacturing corridors. MIIT's tightened GB/T 34014-2023 standards mandate closed-loop water systems and air emission monitoring that match European environmental benchmarks. Tianjin and Ningbo hydrometallurgical clusters achieve economies of scale in lithium carbonate recovery that greenfield projects elsewhere cannot yet replicate.
Germany
BMW and Volkswagen have established separate legal entities for end-of-life battery management to satisfy EU Battery Regulation recycled content mandates. The country's national automotive regulator KBA enforces type-approval documentation that streamlines battery passport data architecture requirements. Bavaria and North Rhine-Westphalia host integrated processing facilities serving cathode precursor remanufacturing for European OEM supply chains.
United States
Reverse logistics partnerships with dealership networks are unlocking proprietary feedstock access for tolling contract operators. The EPA oversees hazardous waste classification for spent lithium-ion batteries under RCRA subtitle C requirements. Nevada and California industrial zones concentrate hydrometallurgical pilot projects targeting battery-grade sulfate production for domestic cathode manufacturing.
South Korea
Automated disassembly lines equipped with machine vision and robotic sorting arms are digitizing black mass preparation workflows for cylindrical and pouch cell architectures. The country's national industrial regulator METI coordinates standards alignment with EU Battery Regulation documentation requirements. Seoul Capital Area and Busan-Ulsan corridors integrate recycling subsidiaries with battery-grade material production for captive supply to cell manufacturers.
Transportation Battery Recycling Market Competitive Environment
On the supply side, the industry is consolidating around three strategic archetypes: integrated materials producers with captive cathode precursor manufacturing, tolling specialists securing feedstock through automaker partnerships, and regional processors leveraging port-proximate logistics advantages. Competitive positioning depends on securing UN 38.3 hazmat-certified container fleets for cross-border feedstock movement and achieving battery-grade purity exceeding 99.5% for direct cathode remanufacturing. Dominant competitive moves include backward integration into collection networks and technology licensing for automated disassembly systems.
Among Belgian-based integrated materials producers, Umicore exemplifies the archetype of in-house cathode precursor production from recycled streams. Within the tolling partnership tier, Li-Cycle Corp represents feedstock security through automaker contracts without fleet ownership. At the scale-driven end, Redwood Materials anchors closed-loop positioning spanning end-of-life vehicle intake to refined battery-grade materials.
| Leading Market Players |
|---|
| Umicore |
| Li-Cycle Corp |
| Aqua Metals |
| Exide Technologies |
| Call2Recycle |
| Battery Solutions |
| Ecobat |
| GEM Co. Ltd. |
| Redwood Materials |
| Others |
Value Chain & Pricing Dynamics
Tianjin and Ningbo industrial clusters concentrate hydrometallurgical processing capacity that European greenfield projects cannot yet replicate, granting Chinese operators downstream pricing power over battery-grade lithium carbonate and sulfate concentrates. This geographic asymmetry compresses margin visibility for tolling contract negotiations while EU Battery Regulation mandates create binding offtake demand that sustains premium pricing for certified recyclers.
Pricing Analysis
Certification level under EU Battery Regulation and China's GB/T 34014-2023 standards creates the primary spread between premium and commodity-grade black mass. Contract-based long-term offtake agreements dominate, with price differentiation resting on battery-grade purity thresholds exceeding 99.5% and UN 38.3 hazmat certification status. Cost compression in standard-grade processing is intensifying because nickel and cobalt London Metal Exchange pricing transmits directly to feedstock acquisition costs. Aftermarket providers show highest price sensitivity due to fragmented feedstock competition, while OEMs under recycled content mandates exhibit lowest sensitivity.
Supply Chain Analysis
Contract manufacturing concentration in China's Yangtze River Delta and South Korea's Seoul Capital Area anchors global hydrometallurgical capacity. Geographic supply concentration centers on China, Germany, and South Korea for integrated processing, with raw material dependencies on lithium carbonate, cobalt sulfate, and nickel concentrates. Single-source vulnerability around Tianjin-Ningbo port logistics creates chokepoint exposure for European and North American cathode manufacturers. Distribution runs through automaker captive collection networks and independent scrap aggregator channels in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transportation battery recycling represents a high-growth disruption as EU Battery Regulation mandates and China's MIIT licensing reforms simultaneously compress facility commissioning timelines and consolidate processing capacity around compliant operators.
For Market Incumbents: Entrench feedstock security through backward integration into automaker reverse logistics partnerships before independent scrap aggregators lose access to dealership networks. Automaker unbundling of end-of-life service contracts threatens tolling specialists lacking proprietary collection infrastructure. Priority lever: automated disassembly technology licensing to compress labor cost gaps with emerging jurisdictions.
For New Entrants and Emerging Players: Build out direct recycling pilot capacity targeting LFP chemistry proliferation from Chinese-built electric buses and entry-level passenger vehicles, a segment incumbent hydrometallurgical operators have underweighted. India's PLI scheme extension for cell manufacturing creates parallel domestic recycling demand with limited established competition. Go-to-market angle: tolling partnerships with fleet operators offering centralized depot collection points.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated materials producers with captive cathode precursor manufacturing and certified EU Battery Regulation partnerships. Long-term viability across the projection horizon rests on securing battery passport data architecture capabilities and closed-loop water systems compliance. Signal to watch: automaker legal entity spin-offs for end-of-life battery management as captive procurement inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | UN 38.3 hazmat certification unlocks proprietary feedstock access without aggregator competition. |
| Hydrometallurgical Capacity Expansion | GB/T 34014-2023 compliance in Tianjin-Ningbo clusters matches European environmental benchmarks. |
| Automated Disassembly Technology Licensing | Machine vision integration compresses labor cost gaps between established and emerging jurisdictions. |
| Direct Recycling Pilot Development | Cathode regeneration without full elemental dissolution halves reagent consumption versus conventional flowsheets. |
| Battery Passport Data Architecture Investment | EU Battery Regulation digital twin requirements demand capabilities smaller recyclers lack capital to deploy. |
Study Parameters
The analysis maps lithium-ion, lead-acid, and nickel-metal hydride recycling sub-sectors, each validated through primary interviews with recycling facility operators, OEM sustainability directors, and cathode precursor procurement managers. Secondary sources include MIIT licensing disclosures, EU Battery Regulation implementation guidance, EPA hazardous waste classification rulings, and London Metal Exchange pricing data. Bottom-up facility capacity modeling triangulates against top-down electric vehicle retirement volume projections.
Assumptions held fixed include EU Battery Regulation recycled content thresholds and China's GB/T 34014-2023 environmental benchmarks, while variables span nickel-cobalt-lithium price volatility and UN-certified container availability. Segmentation dimensions modeled cover chemistry type, service type, processing technology, and end-user category across the analysis window. CAGRs derive from feedstock availability curves and capacity commissioning timelines, with industry-specific inputs including electric bus fleet turnover cycles and LFP chemistry adoption rates.
Practitioners should monitor black mass pricing volatility and automaker captive collection network expansion for early signals of margin compression or feedstock access constraint. Forecasts reflect assumptions about regulatory enforcement consistency and hydrometallurgical technology maturation. Quarterly review of MIIT licensing actions and EU Battery Regulation delegated act updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Battery Recycling
ASEAN Electric Vehicle Battery Anode Market
Transportation Battery Recycling
Automobile Storage Battery Market
Transportation Battery Recycling
Two-Wheeler Battery Market
Transportation Battery Recycling
Transportation Battery Market
Transportation Battery Recycling
China Transportation Battery Recycling Market
Transportation Battery Recycling
Automotive Battery Recycling Market
Transportation Battery Recycling
Asia-Pacific Transportation Battery Recycling Market
Transportation Battery Recycling
South Korea Transportation Battery Recycling Market
Transportation Battery Recycling
Automotive Energy Recovery System Market
Transportation Battery Recycling
EV Battery Recycling Services Market
Transportation Battery Recycling
Europe Train Battery Market
Transportation Battery Recycling
Europe Automotive Start-Stop Battery Market