
 Automotive Energy Recovery System Market | 2026-2036
Automotive Energy Recovery System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Energy Recovery System Market Analysis
OEM direct procurement channels for energy recovery hardware is fragmenting as vehicle electrification diversifies sourcing pathways. Robert Bosch GmbH leverages its integrated powertrain division to supply regenerative braking modules directly to European and Asian assemblers. Continental AG anchors its position through captive production of inverters and control units for hybrid architectures. ZF Friedrichshafen AG competes by extending its mechatronics portfolio into flywheel-based kinetic recovery systems for commercial transport.
An automotive energy recovery system captures kinetic or thermal energy normally dissipated during braking, coasting, or exhaust cycles and converts it into reusable electrical or mechanical power through generators, turbo-compound turbines, or high-speed flywheels operating at rotational speeds exceeding 60,000 RPM. Regenerative braking dominates installed volume across passenger and electric vehicle applications, though flywheel energy storage commands premium margins in motorsport and heavy-duty commercial segments where rapid charge-discharge cycles outperform chemical batteries. Turbocharging applications sustain steady replacement demand from aftermarket providers serving legacy internal combustion fleets, while KERS technology leads R&D intensity among Tier-1 suppliers targeting next-generation hybrid platforms.
The EPA tailpipe standards and Euro 7 emissions frameworks mandate measurable reductions in CO2 and NOx output, forcing OEMs to adopt energy recovery as a compliance pathway rather than an optional efficiency feature. NHTSA fuel economy rules in the United States further tighten the cost-benefit calculus for manufacturers deciding between mild-hybrid architectures and full electrification. Stakeholders must monitor how divergent regulatory timelines across Washington, Brussels, and Beijing reshape platform standardization and component interoperability requirements.
Market Dynamics
The transition from mechanical to electromechanical recovery architectures is compressing supplier margins while fragmenting procurement channels across passenger, commercial, and motorsport vehicle platforms.
Growth Catalysts
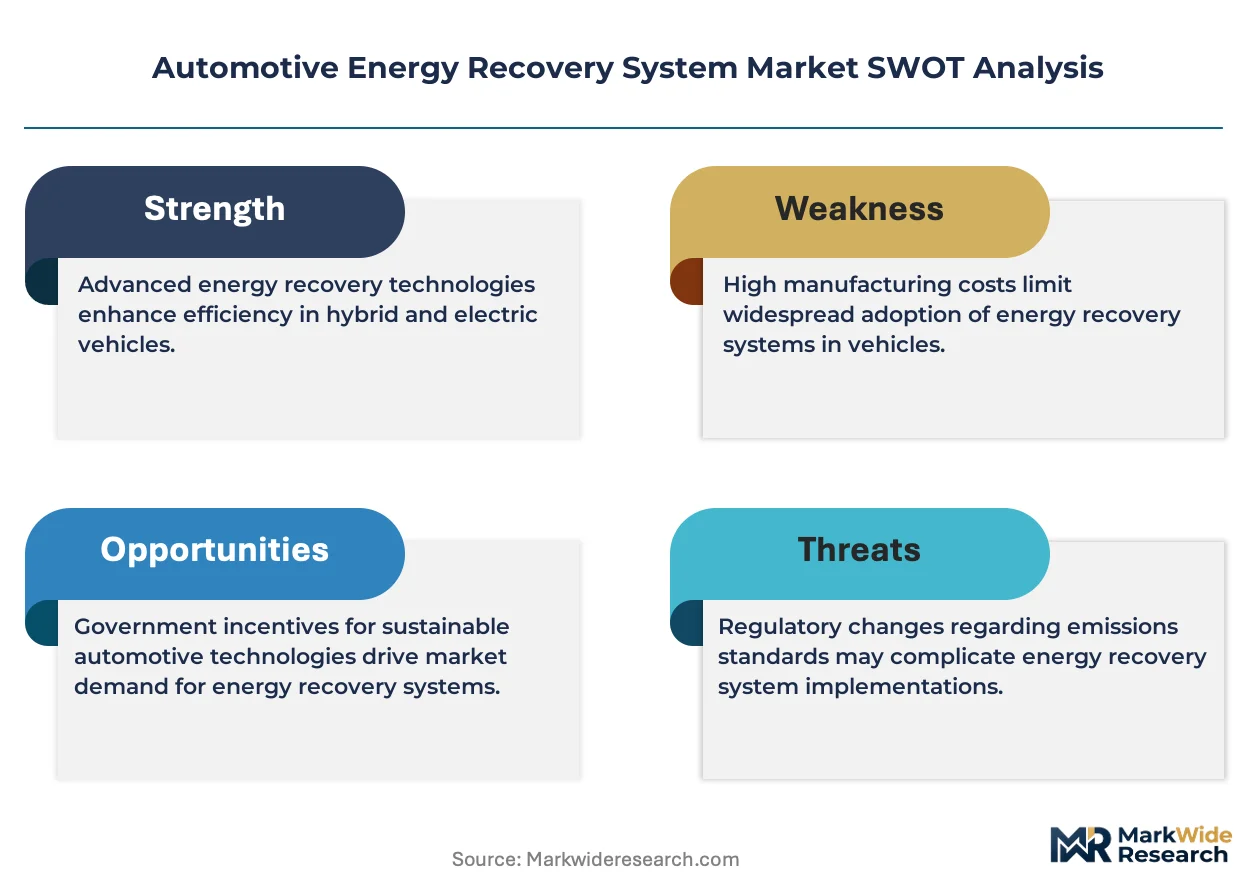
- EPA tailpipe standards:The United States mandates measurable CO2 reductions, compelling OEMs to integrate regenerative braking as a compliance pathway rather than optional efficiency feature.
- Electric vehicle manufacturers:This buyer segment pursues thermal and kinetic waste recovery to extend driving range, creating pull-through demand for high-voltage inverter modules and flywheel storage systems.
- Exhaust heat recovery:Turbo-compound turbine technology captures thermal energy from diesel powertrains in heavy-duty commercial fleets, addressing fuel economy targets in long-haul transport.
Market Restraints
- Rare earth magnet supply concentration:China controls processing of neodymium and dysprosium essential for high-speed flywheel motors, exposing European and North American assemblers to input cost volatility and export restriction risk.
- Flywheel rotational speed limits:Mechanical bearings and vacuum containment systems face material fatigue thresholds above 60,000 RPM, constraining energy density in commercial vehicle applications.
- Euro 7 implementation timeline uncertainty:Proposed NOx and particulate thresholds remain under negotiation, delaying platform standardization decisions and freezing R&D budgets at multiple OEMs.
Strategic Opportunities
- India commercial vehicle retrofit:The country's Bureau of Indian Standards (BIS) is drafting efficiency mandates for existing diesel fleets, creating aftermarket demand for exhaust heat recovery kits.
- Regenerative braking-battery convergence:Integration of silicon carbide inverters with solid-state battery architectures enables faster charge-discharge cycles in next-generation hybrid platforms.
- Direct-to-fleet procurement channels:Logistics operators in Germany and the United States are bypassing traditional Tier-1 suppliers to source kinetic recovery systems for tractor-trailer electrification programs.
Industry Challenges
- Power electronics talent scarcity:Design engineers with expertise in wide-bandgap semiconductors and thermal management are concentrated at a handful of automotive suppliers, constraining in-house development at emerging OEMs.
- Homologation timeline compression:Divergent certification requirements between NHTSA, KBA, and China's MIIT force parallel testing programs that extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Energy Recovery System Market |
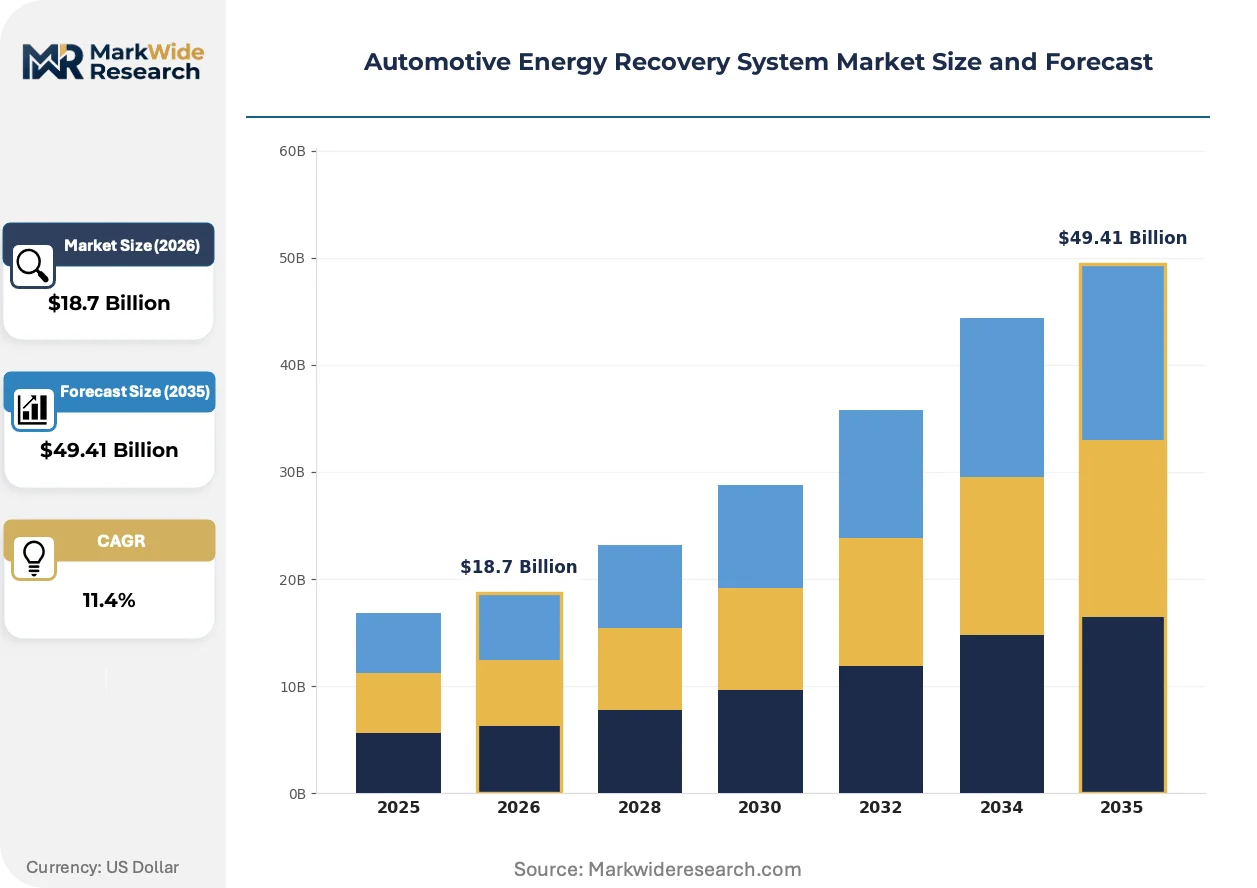
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Regenerative Braking, Turbocharging, KERS, Flywheel Energy Storage End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Component: Electrical Motors, Energy Storage Systems, Inverters, Control Units Application: Passenger Vehicles, Commercial Vehicles, Hybrid Vehicles, Electric Vehicles |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, BorgWarner Inc., DENSO Corporation, Hyundai Mobis, Valeo, Mitsubishi Heavy Industries, Garrett Motion Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Energy Recovery System Market Emerging Trajectories
Digital control architectures are displacing analog feedback loops across energy recovery subsystems, enabling real-time optimization of capture efficiency and predictive maintenance protocols.
Silicon carbide MOSFETs are digitizing inverter control in regenerative braking modules by replacing silicon IGBTs with faster-switching wide-bandgap semiconductors. Passenger EV assemblers in Germany and South Korea are adopting these devices for 800-volt architectures. This transition is digitizing thermal management strategies and compressing the competitive window for legacy silicon suppliers.
REACH substance restrictions are tightening material disclosure requirements for power electronics sold into European vehicle platforms. The regulation forces suppliers to document full chemical composition of capacitors, substrates, and thermal interface materials. Hybrid powertrain divisions at major assemblers are responding by qualifying alternative dielectric fluids and ceramic substrates ahead of 2026 enforcement milestones.
Fleet operators are unbundling energy recovery hardware from full-vehicle procurement contracts, creating direct sourcing relationships with flywheel and turbo-compound specialists. This pattern disrupts traditional captive supply arrangements between OEMs and Tier-1 powertrain divisions. The shift is most visible in United States long-haul trucking, where operators specify recovery systems separately from chassis purchases to optimize total cost of ownership calculations.
Automotive Energy Recovery System Market Segmentation
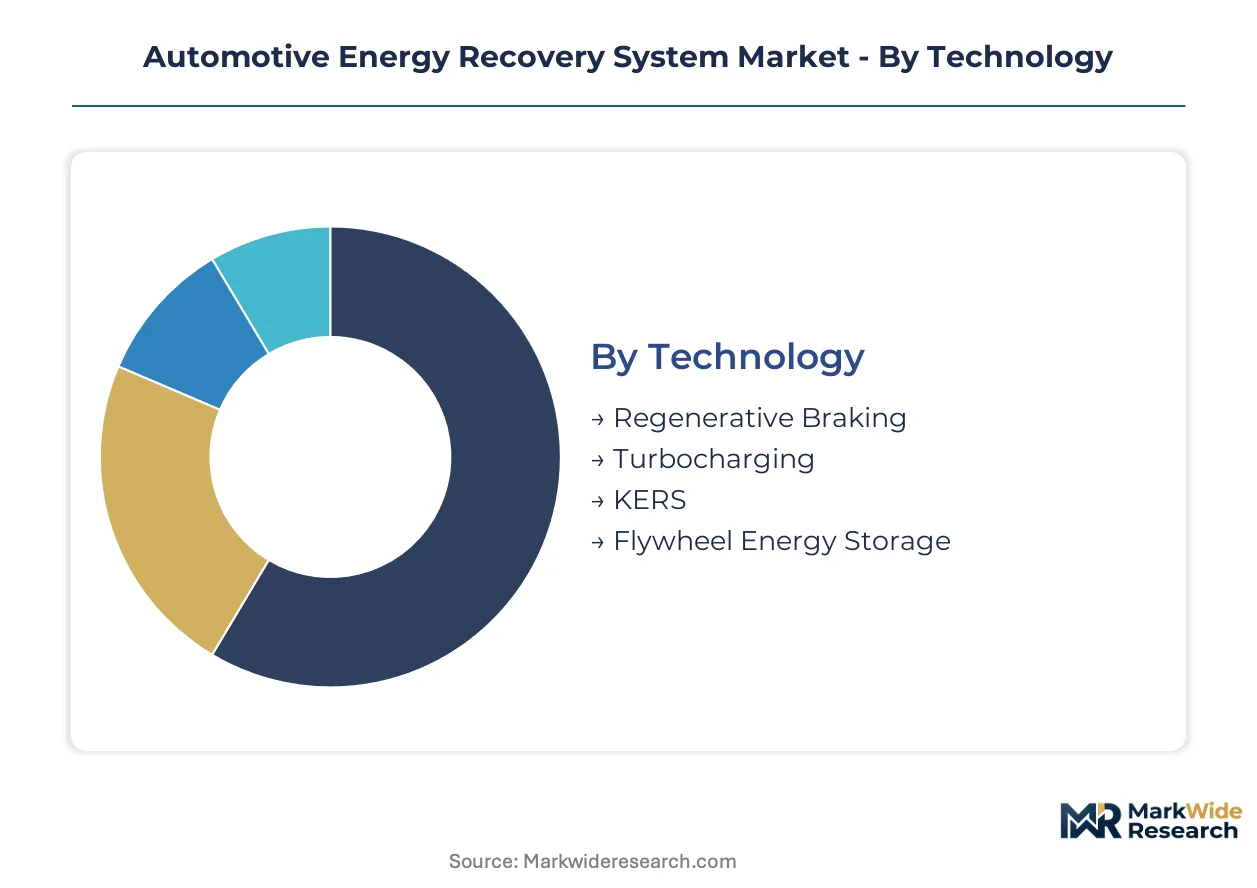
Energy recovery system segmentation reveals divergent margin profiles across technology architectures and procurement channels. After-sales service intensity varies sharply between flywheel-based kinetic systems requiring specialized maintenance and plug-and-play regenerative braking modules.
Technology:
After-sales service intensity peaks with flywheel systems demanding vacuum containment inspections and bearing replacements at 50,000-hour intervals, while regenerative braking modules require minimal dealer intervention.
- Regenerative Braking:Electromechanical systems convert kinetic energy into electrical power through motor-generators integrated with brake calipers and friction surfaces. Demand concentrates in Germany and South Korea where 800-volt passenger EV architectures require high-voltage inverter pairing. EPA tailpipe compliance deadlines accelerate OEM integration timelines.
- Flywheel Energy Storage:High-speed rotating mass systems store mechanical energy in carbon-fiber composite rotors operating above 60,000 RPM within vacuum housings. Motorsport and heavy-duty commercial fleets in the United States specify these for rapid charge-discharge cycles exceeding lithium-ion capabilities. Material fatigue thresholds constrain service intervals.
- Turbocharging:Exhaust-driven turbine systems capture thermal energy from diesel powertrains to boost intake air density and improve combustion efficiency.
- KERS:Kinetic energy recovery systems deploy flywheel or battery storage for motorsport applications and performance hybrid platforms.
Regenerative braking holds the largest share; momentum sits with flywheel energy storage.
End User:
Cost tier stratification separates direct OEM procurement of integrated systems from aftermarket retrofit kits targeting existing fleet assets.
- OEMs:Original equipment manufacturers specify complete energy recovery architectures during platform development, capturing design-in cost advantages and warranty control. European and Asian assemblers dominate procurement volume for passenger electrification programs.
- Tier-1 Suppliers:Captive powertrain divisions at Bosch, Continental, and ZF supply integrated modules directly to vehicle assembly lines, controlling inverter and control unit production in-house.
- Aftermarket Providers:Independent distributors serve exhaust heat recovery retrofit demand from legacy commercial fleets facing efficiency mandates.
- Vehicle Assemblers:Contract manufacturers without captive component production source complete recovery systems from external suppliers.
OEMs command the largest procurement volume; Tier-1 suppliers are climbing the fastest as electrification deepens captive integration.
Component:
Volume concentration favors electrical motors and inverters where manufacturing scale drives unit cost reduction across hybrid and electric platforms.
- Inverters:Power electronics modules convert DC battery output to AC motor drive signals, with silicon carbide MOSFETs displacing silicon IGBTs in 800-volt architectures. German and South Korean passenger EV programs specify these devices for thermal efficiency gains.
- Electrical Motors:Permanent magnet synchronous machines and induction motors provide regenerative braking torque and propulsion power. Rare earth magnet supply concentration in China exposes European and North American assemblers to input cost volatility.
- Energy Storage Systems:Battery packs and flywheel assemblies buffer recovered energy for redeployment during acceleration cycles.
- Control Units:Embedded software modules manage energy flow optimization and predictive maintenance protocols.
Inverters hold the largest share; electrical motors are expanding most quickly with platform electrification.
Application:
Customer type differentiation separates passenger vehicle efficiency optimization from commercial vehicle total cost of ownership calculations.
- Electric Vehicles:Battery-electric platforms maximize range extension through regenerative braking and thermal management recovery. Manufacturers in China, Germany, and the United States pursue kinetic and waste heat capture to reduce charging frequency.
- Commercial Vehicles:Long-haul trucking and urban delivery fleets in the United States and Germany specify turbo-compound and flywheel systems for fuel economy compliance. Fleet operators unbundle recovery hardware from chassis procurement to optimize lifecycle costs.
- Hybrid Vehicles:Mild and full hybrid architectures balance internal combustion with electric assist through integrated starter-generators.
- Passenger Vehicles:Conventional internal combustion platforms adopt limited regenerative braking for stop-start systems.
Electric vehicles hold the largest share; commercial vehicles are gaining share fastest as fleet electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates asymmetrically between Germany and China as regulatory stringency and manufacturing scale diverge across major demand centers. Component suppliers command premium margins in European markets where Euro 7 compliance deadlines compress procurement timelines. Asian manufacturing hubs leverage volume efficiencies to offset thinner margins on standardized regenerative braking modules.
United States
Long-haul trucking electrification and passenger EV range extension dominate procurement priorities. NHTSA fuel economy rules tighten the cost-benefit calculus for OEMs choosing between mild-hybrid and full-electric architectures. Detroit-area powertrain engineering clusters concentrate flywheel system development for commercial vehicle applications.
Germany
800-volt passenger EV architectures from Stuttgart and Munich drive demand for silicon carbide inverters and high-voltage motor-generators. KBA homologation requirements enforce parallel testing protocols that extend product launch cycles. Baden-Württemberg supplier parks integrate regenerative braking module production with transmission assembly lines.
China
Domestic EV manufacturers pursue kinetic and thermal recovery to reduce charging frequency in battery-electric platforms. MIIT certification standards for new energy vehicles mandate minimum energy recovery efficiency thresholds. Yangtze River Delta manufacturing corridors concentrate rare earth magnet processing for high-speed flywheel motors.
Japan
Hybrid powertrain heritage sustains demand for integrated starter-generator systems and compact regenerative braking modules. METI carbon neutrality roadmaps accelerate R&D investment in next-generation kinetic recovery architectures. Nagoya-area automotive clusters coordinate inverter development with semiconductor fabrication partnerships.
South Korea
Battery-electric platform expansion creates pull-through demand for thermal management recovery and high-voltage power electronics. MFDS automotive safety standards influence control unit software validation protocols. Seoul Capital Area engineering centers specialize in solid-state battery integration with regenerative braking systems.
Automotive Energy Recovery System Market Vendor Landscape
Integrated powertrain conglomerates and specialized mechatronics suppliers split the market between captive production and modular sourcing pathways. Tier-1 divisions at major automotive groups control inverter and control unit manufacturing in-house, while independent specialists capture flywheel and turbo-compound niches requiring distinct engineering competencies. Dominant competitive moves include backward integration into semiconductor sourcing and geographic expansion through joint ventures with regional EV assemblers.
Among German-based diversified suppliers, Robert Bosch GmbH, Continental AG, and ZF Friedrichshafen AG occupy positions spanning electromechanical recovery architectures. These companies exemplify the integrated conglomerate archetype through captive powertrain divisions supplying regenerative braking modules and kinetic recovery systems directly to vehicle assembly lines. Their geographic concentration in Stuttgart, Hanover, and Friedrichshafen reflects historical automotive manufacturing clustering rather than emergent positioning.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| BorgWarner Inc. |
| DENSO Corporation |
| Hyundai Mobis |
| Valeo |
| Mitsubishi Heavy Industries |
| Garrett Motion Inc. |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta manufacturing corridors concentrate rare earth magnet processing capacity for high-speed flywheel motors, creating asymmetric pricing power that favors Chinese suppliers in inverter module negotiations with European and North American assemblers. This geographic concentration compresses margins for non-integrated buyers while amplifying volatility in component procurement costs.
Pricing Analysis
The customization-premium spread between configured-to-order flywheel systems and standard regenerative braking modules runs wide, with project-based pricing dominating kinetic recovery architectures while per-unit transactional models prevail for high-volume inverter supply. Price differentiation hinges on silicon carbide certification tiers and volume scale commitments from OEM procurement divisions. Cost compression in standardized regenerative braking modules is intensifying because South Korean and Chinese manufacturers are flooding 400-volt architectures with undifferentiated product. Fleet operators exhibit the highest price sensitivity, while motorsport teams tolerate premium positioning for rapid charge-discharge performance.
Supply Chain Analysis
Contract manufacturing concentration for power electronics rests with Taiwanese and South Korean foundries holding silicon carbide wafer capacity, while German and Chinese facilities dominate motor-generator assembly. The supply chain draws from neodymium and dysprosium rare earths, copper windings, and ceramic substrate materials. Single-source vulnerability in Chinese rare earth processing exposes European assemblers to export restriction risk. Distribution runs through captive Tier-1 channels for OEM integration and direct-to-fleet procurement for commercial retrofit applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in automotive energy recovery are approaching an inflection where 800-volt electrical architectures are forcing interoperability standardization across previously siloed inverter and motor-generator ecosystems.
For Market Incumbents: Pre-empt margin erosion in silicon IGBT legacy supply by accelerating backward integration into silicon carbide wafer sourcing through joint ventures with Taiwanese foundries. Defend captive powertrain relationships at Stuttgart and Munich OEMs against emerging Chinese inverter specialists by embedding control software deeper into vehicle operating systems. Certify modules early under Euro 7 draft protocols to freeze competitor qualification timelines. For New Entrants and Emerging Players: Establish a beachhead in United States long-haul trucking flywheel retrofits where fleet operators are unbundling recovery hardware from chassis procurement and bypassing traditional Tier-1 relationships. Target the India commercial vehicle aftermarket where BIS efficiency mandates for existing diesel fleets are creating exhaust heat recovery kit demand without entrenched supplier competition. Lead with direct sales teams and lifecycle cost modeling rather than OEM channel dependence. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists with silicon carbide inverter design capabilities and established KBA or NHTSA homologation track records over diversified conglomerates with legacy silicon exposure. Long-term viability in this market rests on qualification breadth across multiple OEM platforms rather than single-vehicle program dependence. Watch for inflection in MIIT certification standard updates that would force redesign cycles and consolidate supplier qualification lists.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Platform Standardization | Reduces thermal losses in 800-volt architectures from Hyundai Mobis and Bosch powertrain divisions. |
| Rare Earth Magnet Supply Agreement | Secures dysprosium and neodymium processing capacity from Yangtze River Delta refiners for European motor production. |
| Flywheel Vacuum Containment Patent Portfolio | Extends service intervals beyond 50,000 hours in United States commercial fleet applications. |
| Direct-to-Fleet Procurement Channel | Bypasses Tier-1 markups for German logistics operators specifying kinetic recovery separately from chassis. |
| Euro 7 Pre-Certification Investment | Freezes competitor homologation timelines at KBA and accelerates OEM design-in decisions. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distributors, and fleet operations managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings from powertrain conglomerates, IHS Markit vehicle production databases, EPA regulatory dockets, and MIIT new energy vehicle certification records. Bottom-up component demand modeling and top-down OEM platform electrification forecasts were triangulated to bracket volume estimates.
Scenario-bracketing around Euro 7 implementation timing and silicon carbide adoption curves shaped the analytical framework across the analysis window. Segmentation dimensions modeled include propulsion architecture, vehicle class, technology type, and regional regulatory cluster. CAGRs were derived from installed base growth rates and content-per-vehicle trajectories rather than top-line market extrapolation. Forecast inputs incorporated rare earth magnet price volatility indices and NHTSA fuel economy rule stringency assumptions.
Macroeconomic conditions sit as an overlay; deviation in battery raw material costs, semiconductor foundry utilization rates, or trade policy enforcement would shift the trajectory of platform electrification and energy recovery adoption. Forecasts reflect assumptions about regulatory timeline adherence and technology cost curves that may require revision if Euro 7 negotiations extend or silicon carbide yields disappoint. Quarterly review of OEM platform announcements, MIIT certification batch releases, and rare earth export quota declarations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Battery Recycling
Transportation Battery Recycling Market
Transportation Battery Recycling
Two-Wheeler Battery Market
Transportation Battery Recycling
ASEAN Electric Vehicle Battery Anode Market
Transportation Battery Recycling
Transportation Battery Market
Transportation Battery Recycling
South Korea Transportation Battery Recycling Market
Transportation Battery Recycling
Asia-Pacific Transportation Battery Recycling Market
Transportation Battery Recycling
EV Battery Recycling Services Market
Transportation Battery Recycling
Europe Train Battery Market
Transportation Battery Recycling
Automobile Storage Battery Market
Transportation Battery Recycling
Europe Automotive Start-Stop Battery Market
Transportation Battery Recycling
China Transportation Battery Recycling Market
Transportation Battery Recycling
Automotive Battery Recycling Market