
 South Korea Transportation Battery Recycling Market | 2026-2036
South Korea Transportation Battery Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Transportation Battery Recycling Market Insights
Lithium is shifting from virgin mining dependency toward closed-loop cathode recovery in South Korea's transportation battery recycling sector. POSCO Chemical leverages its integrated steel-to-chemistry infrastructure to secure precursor supply chains. Korea Zinc anchors pyrometallurgical capacity at its Onsan refinery complex. SungEel HiTech specializes in hydrometallurgical black mass processing for nickel and cobalt extraction.
South Korea transportation battery recycling encompasses the collection, dismantling, and chemical recovery of spent traction batteries from electric and hybrid vehicles, typically operating at recovery efficiencies exceeding 95 percent for cobalt and nickel through hydrometallurgical circuits. The primary industrial purpose is regenerating battery-grade metal salts for domestic cathode active material production, reducing raw material import exposure. Pyrometallurgical recycling dominates current installed capacity due to its compatibility with existing non-ferrous smelters, though hydrometallurgical methods are capturing margin pools through higher purity outputs and lower energy intensity. Direct recycling approaches for lithium iron phosphate chemistries are accelerating as cell designs standardize, while cobalt recovery from nickel manganese cobalt formulations sustains premium pricing in component material segments.
MFDS guidelines govern workplace exposure limits at recycling facilities, while the Ministry of Environment enforces extended producer responsibility mandates requiring automakers to fund end-of-life battery collection networks. KTL certification standards for recycled content traceability are tightening market access for non-compliant processors. Stakeholders must monitor how the national carbon neutrality roadmap alters energy cost structures for pyrometallurgical operators and whether municipal governments accelerate permitting for urban recycling hubs near Seoul.
Market Dynamics
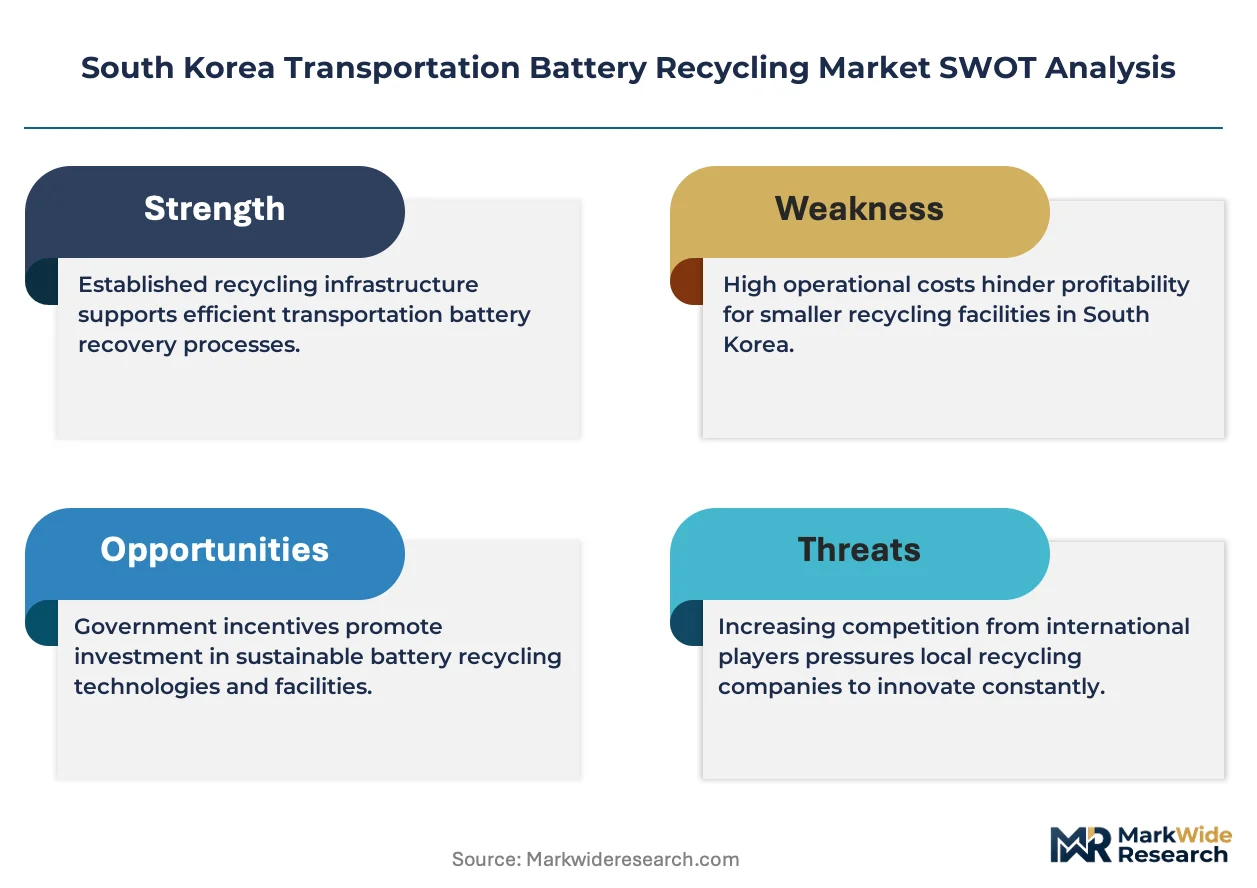
The Ministry of Environment's extended producer responsibility framework tightens collection quotas annually, forcing automakers to fund dedicated collection networks and reshaping competitive positioning toward integrated logistics capabilities.
Growth Catalysts
- EPR Mandate Escalation:The Ministry of Environment's annual quota increases compel Hyundai Motor and Kia to expand recycler partnerships, ensuring predictable feedstock flows to hydrometallurgical facilities.
- Seoul Metropolitan Concentration:Battery manufacturing clusters in Gyeonggi province generate spent cell volumes within 50 kilometers of major processing capacity, minimizing reverse logistics costs.
- Black Mass Standardization:Uniform dismantling protocols for nickel manganese cobalt cells enable SungEel HiTech and competitors to achieve consistent hydrometallurgical feedstock quality.
Market Restraints
- Lithium Price Volatility:Spodumene concentrate import costs from Australian miners fluctuate, eroding margins for recyclers competing against virgin material in cathode precursor markets.
- Pyrometallurgical Lock-in:Korea Zinc's Onsan smelter complex anchors existing capacity, creating path dependency that slows hydrometallurgical adoption despite superior lithium recovery rates.
- KTL Certification Barriers:Traceability standards for recycled content exclude smaller processors lacking audit infrastructure, consolidating market access among capital-intensive operators.
Strategic Opportunities
- Busan Port Hub Development:Municipal permitting for urban recycling infrastructure near Korea's primary battery export gateway enables direct-to-ship cathode precursor logistics.
- LFP Direct Recycling:Lithium iron phosphate chemistry standardization in commercial vehicle segments creates feedstock suitable for direct cathode regeneration without full hydrometallurgical dissolution.
- Carbon Neutrality Roadmap:National targets for industrial emissions intensify cost advantages for hydrometallurgical circuits against energy-intensive pyrometallurgical alternatives.
Industry Challenges
- Electrochemical Engineer Scarcity:Universities produce insufficient talent versed in both battery chemistry and industrial metallurgy, constraining process optimization at scale-up facilities.
- MFDS Workplace Compliance:Exposure limit enforcement for cobalt and nickel compounds at recycling facilities requires continuous monitoring infrastructure that smaller operators struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Transportation Battery Recycling Market |
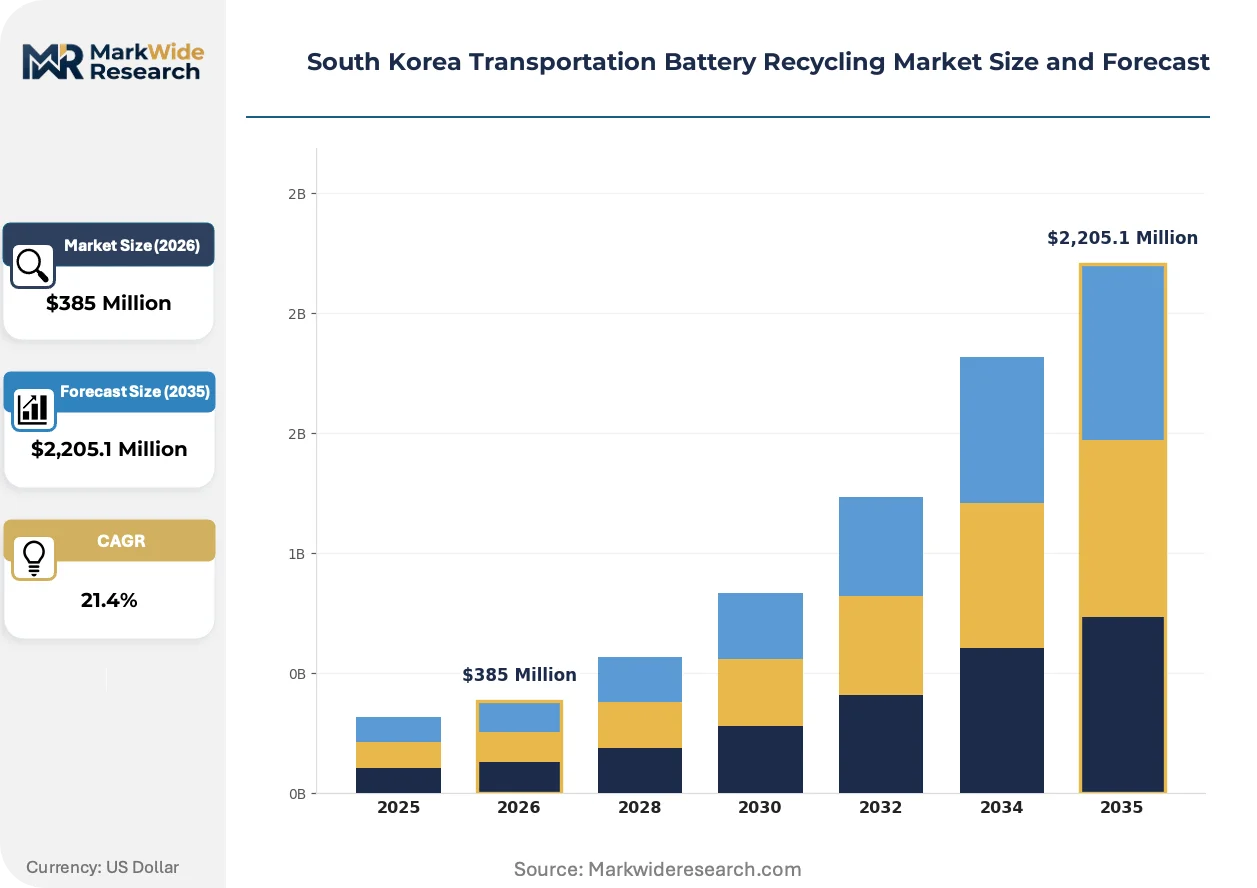
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $2,205.1 Million |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel Metal Hydride, Lead-acid, Others Recycling Method: Pyrometallurgical, Hydrometallurgical, Direct Recycling, Biotechnological End User: Automotive Manufacturers, Electronic Vehicle Producers, Battery Manufacturers, Scrap Collectors Component Material: Cobalt, Nickel, Lithium, Manganese |
| Companies Covered | POSCO Chemical, Korea Zinc, LG Energy Solution, SungEel HiTech, Umicore Korea, Samsung SDI, Hyundai Steel, Ecopro BM, SK Innovation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Transportation Battery Recycling Market Trends and Innovations
Technology convergence between battery dismantling automation and hydrometallurgical purification is compressing processing timelines and enabling urban facility siting near Seoul's manufacturing core.
Direct cathode regeneration for lithium iron phosphate formulations is converging with standardized cell designs from domestic automakers. Commercial vehicle manufacturers are adopting this approach at pilot scale. The technology is converging with closed-loop supply contracts that bypass intermediate black mass trading.
The Ministry of Environment's carbon footprint disclosure requirements for EPR compliance are forcing automakers to document recycling pathway emissions. Industrial consequence includes preferential contracting with hydrometallurgical processors. Battery divisions of Hyundai and Kia are responding by integrating recycler selection into initial supplier qualification.
Long-term offtake agreements are replacing spot market transactions for black mass procurement. Large cathode material producers are securing dedicated feedstock pipelines directly from dismantlers. This pattern is most visible in Gyeonggi province where POSCO Chemical co-located precursor facilities near SungEel HiTech processing plants.
South Korea Transportation Battery Recycling Market Segmentation
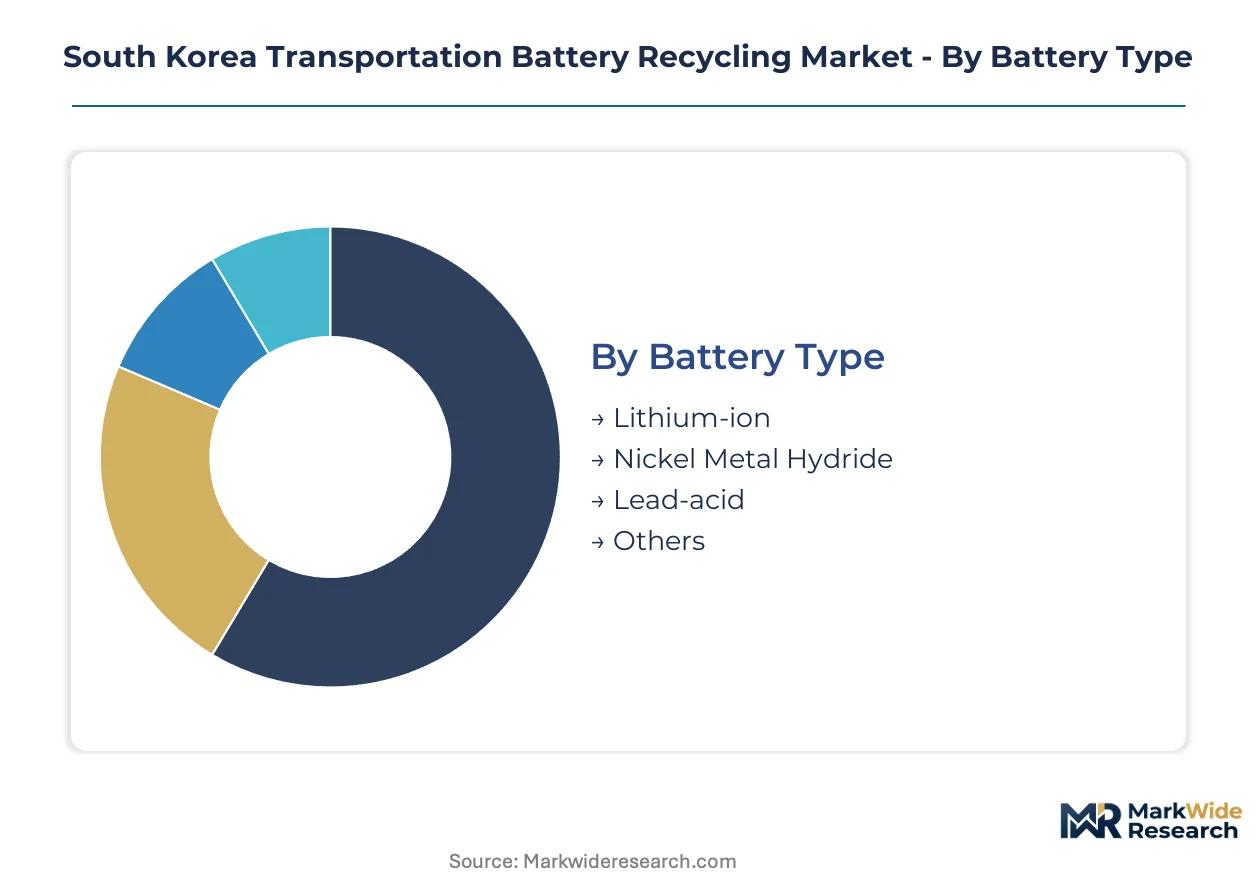
Segmentation in South Korea's transportation battery recycling market reveals how capital allocation and technology choices determine competitive positioning. Each dimension exposes different barriers to entry and margin structures for processors serving Hyundai Motor, Kia, and domestic cathode material producers.
Battery Type:
Capital intensity varies sharply across chemistries, with lithium-ion requiring specialized dismantling infrastructure and nickel metal hydride demanding simpler mechanical separation.
- Lithium-ion:Nickel manganese cobalt and lithium iron phosphate cells dominate feedstock volumes from Gyeonggi province manufacturing clusters. Seoul metropolitan dismantlers prioritize this stream for hydrometallurgical recovery of cobalt and nickel precursors.
- Nickel Metal Hyride:Legacy hybrid vehicle batteries from early Kia and Hyundai models generate predictable but declining volumes. Mechanical shredding and magnetic separation suffice, limiting processor margins compared to lithium-ion circuits.
- Lead-acid:Conventional smelter infrastructure handles starter battery recovery with minimal technology differentiation.
- Others:Solid-state and sodium-ion experimental cells constitute negligible current volumes but attract pilot funding from POSCO Chemical.
Lithium-ion absorbs the bulk of installed capacity; direct recycling of lithium iron phosphate variants is expanding most quickly.
Recycling Method:
Technology selection determines energy costs, recovery purity, and eligibility for automaker offtake contracts under carbon disclosure mandates.
- Pyrometallurgical:High-temperature smelting at Korea Zinc's Onsan complex processes mixed feedstocks with existing non-ferrous infrastructure. Energy intensity exceeds hydrometallurgical alternatives, creating regulatory exposure under national carbon neutrality targets.
- Hydrometallurgical:Acid leaching and solvent extraction circuits at SungEel HiTech facilities achieve battery-grade metal salt purity exceeding 99.5 percent. Lower energy consumption and superior lithium recovery rates attract EPR-mandated automaker partnerships.
- Direct Recycling:Cathode regeneration without full dissolution preserves crystalline structure, cutting reprocessing costs for standardized lithium iron phosphate cells.
- Biotechnological:Bioleaching using acidophilic bacteria remains at laboratory scale with no commercial deployment in South Korea.
Pyrometallurgical processing still handles the greatest tonnage; hydrometallurgical capacity is climbing the fastest as carbon accounting tightens.
End User:
Customer type dictates feedstock security, contract duration, and technical specifications for recovered materials.
- Automotive Manufacturers:Hyundai Motor and Kia fund dedicated collection networks under Ministry of Environment EPR quotas, securing long-term dismantler partnerships with volume guarantees.
- Electronic Vehicle Producers:Commercial vehicle manufacturers specify direct recycling pathways for lithium iron phosphate batteries, bypassing intermediate black mass trading.
- Battery Manufacturers:LG Energy Solution and Samsung SDI procure recycled precursors for cathode active material production, requiring KTL-certified traceability.
- Scrap Collectors:Independent dismantlers supply fragmented feedstock to larger processors, facing consolidation pressure from automaker-integrated networks.
Automotive manufacturers anchor contract volumes; battery manufacturers are driving the steepest expansion in closed-loop offtake agreements.
Component Material:
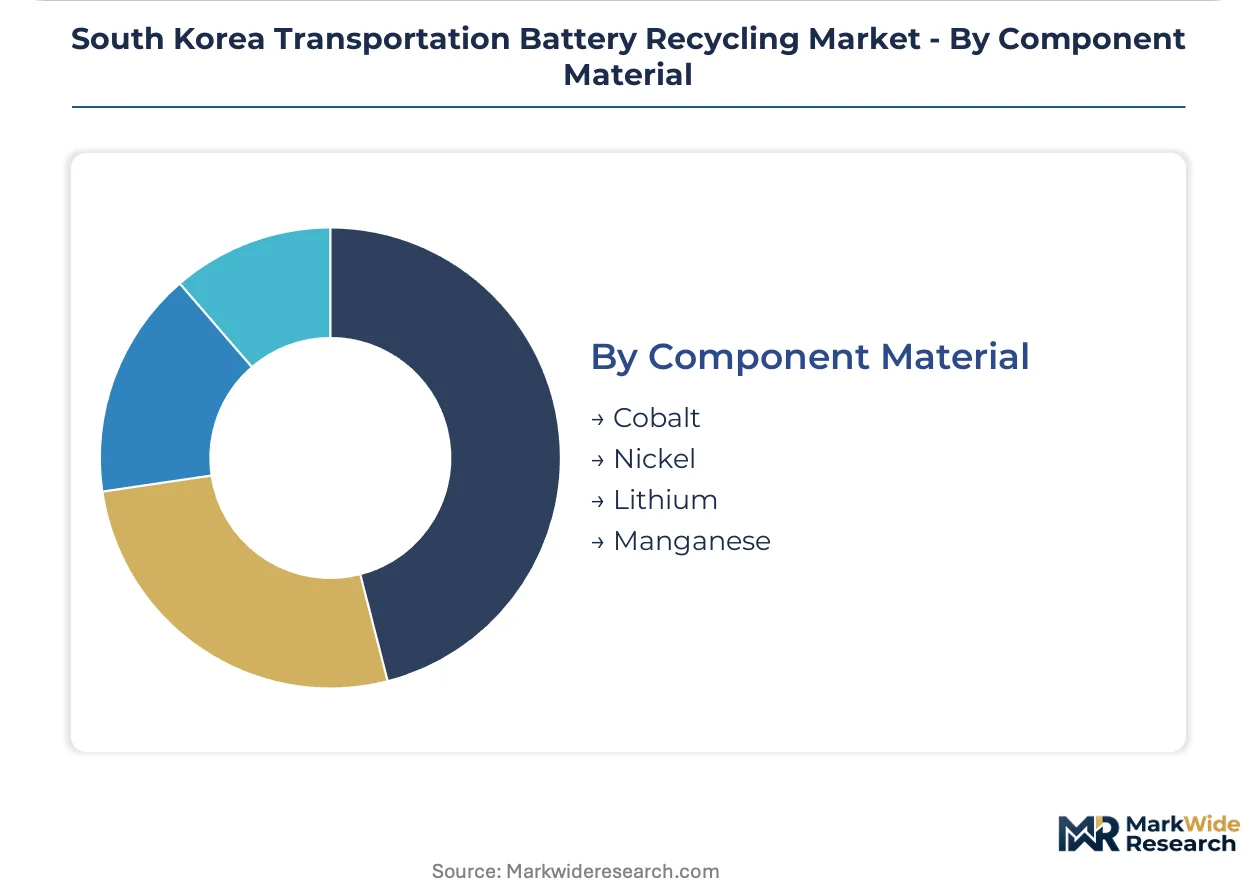
Recovery value and technical difficulty diverge across metal streams, shaping processor specialization and equipment investment priorities.
- Cobalt:Highest value-per-kilogram recovery from nickel manganese cobalt cells sustains premium pricing in precursor markets. Hydrometallurgical circuits achieve recovery efficiencies exceeding 95 percent, justifying capital expenditure for dedicated solvent extraction lines.
- Nickel:Demand from domestic cathode production concentrates in POSCO Chemical's Gyeonggi facilities. Sulfate specification requirements favor integrated hydrometallurgical processors over merchant smelters.
- Lithium:Carbonate and hydroxide recovery from spent electrolytes and cathodes remains technically challenging, with direct recycling approaches gaining traction for lithium iron phosphate chemistries.
- Manganese:Lower value recovery as byproduct of nickel and cobalt circuits, with limited standalone processing economics.
Cobalt and nickel together absorb dominant processing capacity; lithium recovery is gaining share fastest as direct recycling technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in South Korea's Seoul Capital Area and Gyeonggi province where battery manufacturing clusters generate spent cell volumes within 50 kilometers of major processing capacity. The Ministry of Environment's extended producer responsibility framework tightens collection quotas annually, forcing automakers to fund dedicated collection networks. This geographic and regulatory configuration shapes regional competitive positioning toward integrated logistics capabilities.
Seoul Capital Area
Hyundai Motor and Kia headquarters anchor corporate procurement decisions for recycler partnerships, while metropolitan dismantlers prioritize nickel manganese cobalt streams for hydrometallurgical recovery. MFDS workplace exposure limits govern facility siting within dense urban zones. Songdo and Incheon free economic zones host pilot direct recycling facilities serving commercial vehicle manufacturers.
Busan-Ulsan
Korea's primary battery export gateway enables direct-to-ship cathode precursor logistics for international cathode material offtake. Municipal permitting for urban recycling infrastructure accelerates near port terminals. Ulsan industrial complex hosts Korea Zinc's non-ferrous smelting capacity that processes mixed feedstocks from maritime collection routes.
Daegu-Gyeongbuk
Secondary battery manufacturing heritage creates skilled workforce pools for dismantling automation deployment. Regional economic development agencies coordinate industrial park conversions for mid-scale hydrometallurgical facilities. Pohang steel-chemistry integration supports precursor supply chain development for domestic cathode producers.
Daejeon-Sejong
National research institutes concentrate electrochemical engineering talent for process optimization at scale-up facilities. Government-funded pilot programs test bioleaching and direct recycling technologies before commercial deployment. Sejong administrative city hosts Ministry of Environment policy coordination for EPR quota enforcement mechanisms.
Gwangju-Honam
Automotive supplier networks from historic Kia manufacturing bases generate legacy nickel metal hydride volumes requiring mechanical separation. Regional processors face consolidation pressure from automaker-integrated collection networks. Honam industrial corridor offers lower-cost land for pyrometallurgical capacity expansion under national carbon neutrality roadmap timelines.
South Korea Transportation Battery Recycling Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated steel-to-chemistry conglomerates commanding precursor supply chains while pure-play recyclers capture hydrometallurgical margin pools. The vendor base concentrates among capital-intensive operators capable of KTL certification compliance, excluding smaller processors lacking audit infrastructure. Three archetypes dominate: steel-chemistry integrators leveraging existing non-ferrous infrastructure, dedicated battery recyclers specializing in black mass processing, and cathode material producers securing backward integration into feedstock recovery. Competitive moves center on long-term offtake agreements replacing spot market transactions, and co-location strategies minimizing reverse logistics costs between dismantlers and precursor facilities.
Among steel-chemistry integrators, POSCO Chemical and Hyundai Steel exemplify archetypes leveraging metallurgical heritage for precursor supply chain control. Korea Zinc occupies a position representing pyrometallurgical capacity anchoring at existing smelter complexes. Within dedicated recycling specialists, SungEel HiTech sits within the hydrometallurgical tier achieving battery-grade metal salt purity. These named entities represent strategic positioning patterns rather than exhaustive market coverage, with actual competitive dynamics extending across additional domestic and multinational operators.
| Leading Market Players |
|---|
| POSCO Chemical |
| Korea Zinc |
| LG Energy Solution |
| SungEel HiTech |
| Umicore Korea |
| Samsung SDI |
| Hyundai Steel |
| Ecopro BM |
| SK Innovation |
| Others |
Pricing and Supply Chain Analysis
The Ministry of Environment's extended producer responsibility framework gates both qualified supply and premium-tier pricing access, as automakers under annual quota escalation fund only certified dismantlers while KTL traceability standards exclude non-compliant processors from cathode precursor contracts.
Pricing Analysis
Volume commitments dominate contract structures for Hyundai Motor and Kia collection networks, while margin capture concentrates in hydrometallurgical processors achieving battery-grade purity. Price differentiation rests on KTL certification tier and carbon disclosure compliance under national neutrality targets. Cost compression in pyrometallurgical tiers is intensifying because energy intensity exposes operators to rising industrial electricity rates. Scrap collectors and independent dismantlers exhibit highest price sensitivity due to automaker-integrated network consolidation.
Supply Chain Analysis
KTL certification and MFDS workplace compliance standards gate market access, concentrating qualified feedstock among capital-intensive operators. Raw material sourcing draws from Australian spodumene concentrate, Indonesian nickel laterite, and Chilean lithium brine for virgin cathode production competing against recycled streams. Single-source vulnerability concentrates in black mass trading routes from Gyeonggi province dismantlers to precursor facilities. Distribution runs through long-term offtake agreements replacing spot transactions, with Busan port infrastructure enabling direct-to-ship cathode logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea transportation battery recycling market functions as a vertical-integration race, with cathode material producers pursuing backward integration into feedstock recovery to secure qualified supply under tightening EPR mandates.
For Market Incumbents: Anchor pyrometallurgical capacity at existing smelter complexes against hydrometallurgical margin capture by retrofitting for lithium recovery efficiency. Defend against SungEel HiTech and pure-play specialists through co-location with POSCO Chemical precursor facilities in Gyeonggi province. Prioritize KTL certification infrastructure investment to maintain automaker contract eligibility as quota enforcement tightens.
For New Entrants and Emerging Players: Commercial vehicle manufacturers represent the most penetrable channel partner type, as lithium iron phosphate standardization enables direct recycling pilots without full hydrometallurgical capital expenditure. Target Songdo and Incheon free economic zones for urban facility permitting near Seoul manufacturing clusters. Pursue pilot partnerships with battery divisions seeking carbon footprint disclosure compliance under Ministry of Environment mandates.
For Investors and Strategic Acquirers: Hyundai and Kia integration of recycler selection into initial supplier qualification is the leading indicator that long-term offtake contracting is displacing spot market fragmentation. Position for five-to-ten year horizon consolidation around integrated steel-to-chemistry conglomerates and certified hydrometallurgical specialists. Monitor municipal permitting acceleration for Busan port hub development as inflection signal for logistics-advantaged assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Recovery | POSCO Chemical and cathode producers secure captive black mass supply under EPR-mandated automaker quotas. |
| Hydrometallurgical Capacity Expansion | Lower energy intensity aligns with national carbon neutrality roadmap while achieving battery-grade metal salt purity. |
| KTL Certification Infrastructure Investment | Traceability compliance gates market access as automakers document recycling pathway emissions for disclosure mandates. |
| Co-location with Precursor Facilities | Reverse logistics cost minimization between SungEel HiTech processors and POSCO Chemical Gyeonggi plants compresses supply chain. |
| Direct Recycling Technology Deployment | Cathode regeneration for lithium iron phosphate chemistries bypasses intermediate black mass trading in commercial vehicle segments. |
Research Methodology
Multi-period observation of Ministry of Environment quota escalations, KTL certification adoption rates, and automaker collection network expansions anchored the trend analysis, supplemented by interviews with recycling facility plant managers, cathode material procurement leads at LG Energy Solution and Samsung SDI, EPR compliance officers at Hyundai Motor and Kia, and hydrometallurgical process engineers. Secondary validation drew from MFDS workplace exposure filings, Ministry of Environment EPR enforcement disclosures, Korea Zinc and POSCO Chemical SEC submissions, and national carbon neutrality roadmap policy documents. Bottom-up dismantler capacity modeling triangulated against top-down cathode precursor demand projections.
Input-output matrices structured feedstock flow analysis from Gyeonggi province manufacturing clusters through processing capacity to precursor offtake, with segmentation across battery chemistry type, recycling method technology tier, and end-user contract structure. CAGRs were derived through exponential smoothing of annual quota-driven collection volume growth against hydrometallurgical capacity buildout timelines. Forecast inputs incorporated spodumene concentrate import cost volatility and industrial electricity rate trajectories under emissions reduction targets.
Caveats apply where lithium price volatility eroding recycler competitiveness against virgin material, or pyrometallurgical lock-in delaying hydrometallurgical adoption despite superior recovery rates, could materially shift the outlook. A model refresh is warranted upon material change in municipal permitting timelines for urban recycling infrastructure near Seoul.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Battery Recycling
EV Battery Recycling Services Market
Transportation Battery Recycling
Europe Automotive Start-Stop Battery Market
Transportation Battery Recycling
Europe Train Battery Market
Transportation Battery Recycling
Transportation Battery Recycling Market
Transportation Battery Recycling
Automotive Energy Recovery System Market
Transportation Battery Recycling
Transportation Battery Market
Transportation Battery Recycling
ASEAN Electric Vehicle Battery Anode Market
Transportation Battery Recycling
China Transportation Battery Recycling Market
Transportation Battery Recycling
Asia-Pacific Transportation Battery Recycling Market
Transportation Battery Recycling
Automotive Battery Recycling Market
Transportation Battery Recycling
Automobile Storage Battery Market
Transportation Battery Recycling
Two-Wheeler Battery Market