
 Transportation Battery Market | 2026-2036
Transportation Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Transportation Battery Market Analysis
Solid-state electrolyte chemistry is rewriting the cost-performance tradeoffs that have governed lithium-ion cell design for two decades. CATL leverages its vertical integration into cathode materials and raw material refining to sustain cost leadership across passenger EV contracts. LG Energy Solution anchors its position through dedicated joint ventures with North American and European automakers, while BYD dominates through captive demand from its own vehicle manufacturing and in-house blade cell architecture.
Transportation batteries are electrochemical storage systems engineered to deliver sustained high-current discharge cycles under variable thermal and mechanical loads, with energy densities now exceeding 250 Wh/kg in mass-market lithium-ion formats and solid-state prototypes targeting 400 Wh/kg. Their primary commercial purpose is to convert stored chemical energy into propulsion power for electric drivetrains, auxiliary systems, and regenerative braking energy recovery. Lithium-ion chemistry occupies the dominant share of current production capacity due to established supply chains and manufacturing scale, while solid-state technology represents the fastest-growing development pipeline as manufacturers target enhanced safety margins and energy density thresholds. End-user segmentation tilts heavily toward electric vehicles, where OEM long-range contracts concentrate margin pools, though hybrid vehicle applications retain substantial volume in markets where charging infrastructure remains uneven.
China's MIIT enforces GB standards for cell safety and recycling traceability, while the EU Green Deal and F-Gas Regulation impose carbon-footprint disclosure and fluorinated gas restrictions on imported battery systems. The US IRA directs production tax credits toward domestic cell and module assembly, reshaping where manufacturers locate cathode active material plants. Stakeholders must monitor how regulatory divergence across these three jurisdictions affects cell certification costs and supply chain qualification timelines.
Market Dynamics
Solid-state electrolyte chemistry is collapsing the safety-energy density tradeoff that constrained lithium-ion architectures for two decades, forcing incumbents to retool manufacturing lines before pilot-scale validation completes.
Growth Catalysts
- US IRA Production Tax Credits:Domestic cell and module assembly incentives are pulling cathode active material plants toward Michigan, Tennessee, and Kentucky to qualify for qualification timelines.
- Fleet electrification mandates:California's Advanced Clean Trucks regulation and New York's companion rules are compelling commercial vehicle operators to convert procurement specifications to electric drivetrains.
- Sodium-ion chemistry maturation:Prussian white cathode formulations are reaching commercial scale for stationary and short-range applications, diversifying chemistry portfolios beyond lithium dependence.
Market Restraints
- Lithium carbonate price volatility:Chilean and Australian spodumene concentrate supply disruptions transmit directly to cell cost structures, compressing margins for non-integrated assemblers.
- Single-source graphite dependence:Anode material refining concentrates in Shandong and Heilongjiang provinces, creating geographic chokepoints that qualify as critical mineral vulnerabilities under US and EU trade frameworks.
- Fluorinated electrolyte solvent restrictions:EU F-Gas Regulation phase-down schedules are forcing reformulation of electrolyte recipes before alternative solvents achieve equivalent ionic conductivity.
Strategic Opportunities
- India PLI scheme for ACC storage:Production-linked incentive thresholds for advanced chemistry cell manufacturing are attracting joint venture proposals from Korean and Japanese electrode suppliers.
- Second-life stationary storage:Retired EV packs with 70-80% remaining capacity are finding application in grid-scale buffering, creating circular revenue streams independent of virgin material supply.
- Silicon nanowire anode convergence:Silicon-carbon composite architectures paired with dry electrode coating processes are enabling 20% energy density gains without liquid electrolyte reformulation.
Industry Challenges
- Cell formation technician scarcity:Electrochemical engineering talent capable of managing formation cycling protocols remains concentrated at incumbent Korean and Chinese producers, constraining greenfield plant staffing.
- UN 38.3 certification timeline compression:Lithium-ion cell transport safety testing queues at accredited laboratories now extend 14-18 weeks, delaying product launch schedules for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transportation Battery Market |
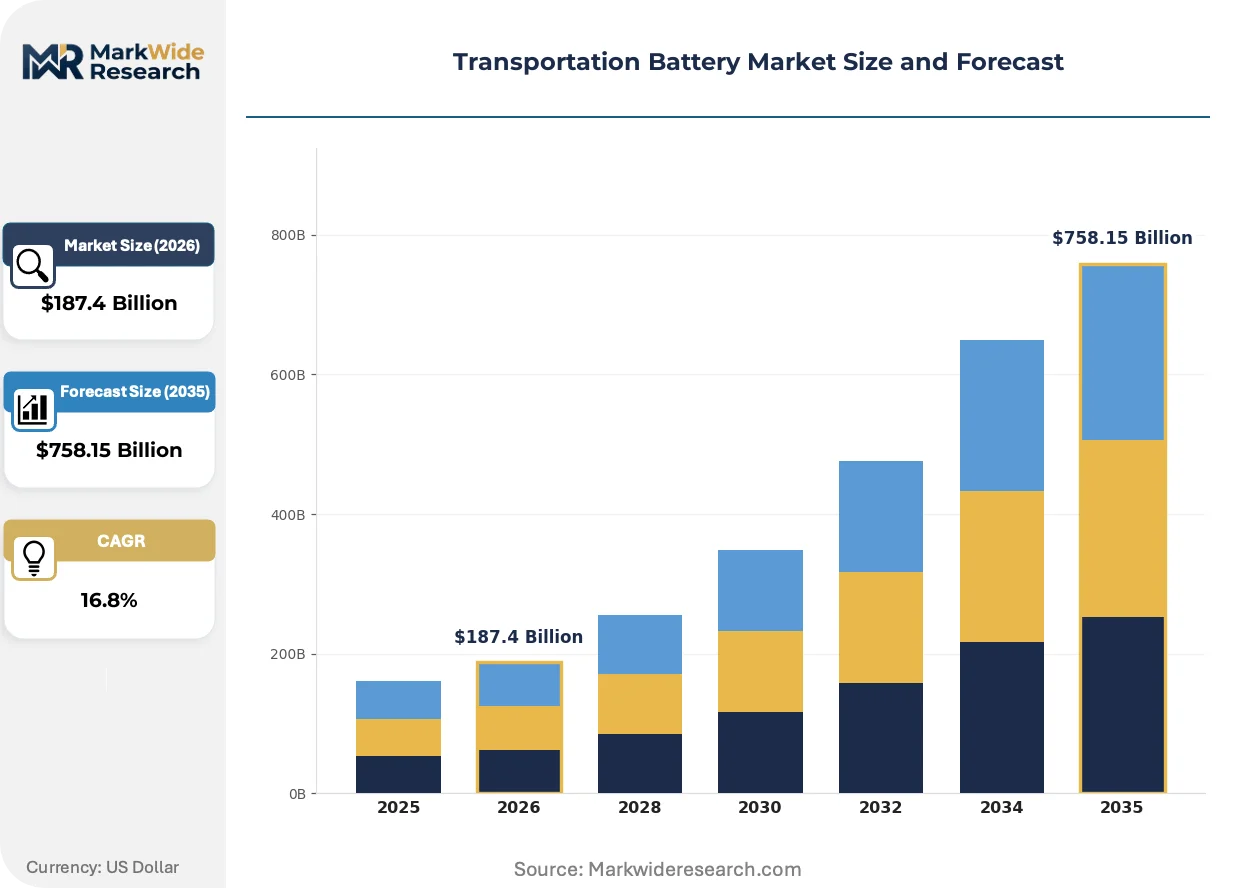
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $758.15 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Lead-acid, Solid State End User: Electric Vehicles, Hybrid Vehicles, Public Transport, Aerospace Application: Energy Storage, Emergency Backup, Power Tools, Marine Technology: Fast Charging, Wireless Charging, Battery Management Systems, Regenerative Braking |
| Companies Covered | CATL, LG Energy Solution, BYD, Panasonic, Samsung SDI, GS Yuasa Corporation, SK On, Johnson Controls, Exide Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transportation Battery Market Emerging Trajectories
Electrode manufacturing processes and pack integration architectures are undergoing simultaneous transformation, with dry coating techniques and cell-to-pack designs eliminating historical processing steps and structural components.
Solid-state ceramic electrolyte architectures are collapsing the separator-electrolyte interface complexity that drove thermal runaway risks in liquid systems. Automotive OEMs in Germany and Japan are qualifying sulfide and oxide solid electrolyte prototypes for 2027-2028 platform launches. This transition is compressing the competitive window for incumbent liquid electrolyte suppliers to establish licensing positions before chemistry lock-in occurs.
EU Battery Regulation mandatory carbon footprint disclosure rules are forcing cell manufacturers to document Scope 3 emissions from mining through refining. Chinese exporters to European automotive customers are retrofitting supply chain traceability systems to meet 2027 compliance deadlines. The regulation is segmenting supplier tiers between those with verified low-carbon nickel and those facing carbon border adjustment exposure.
Fleet operators are consolidating procurement authority from regional subsidiaries to central engineering groups, compressing vendor qualification cycles and demanding unified service level agreements across multiple vehicle platforms. This concentration is displacing fragmented distributor networks in North America and Western Europe with direct OEM-to-fleet contracting models. The shift is most visible in California and Germany where municipal and corporate fleet electrification targets concentrate volume commitments.
Transportation Battery Market Segmentation
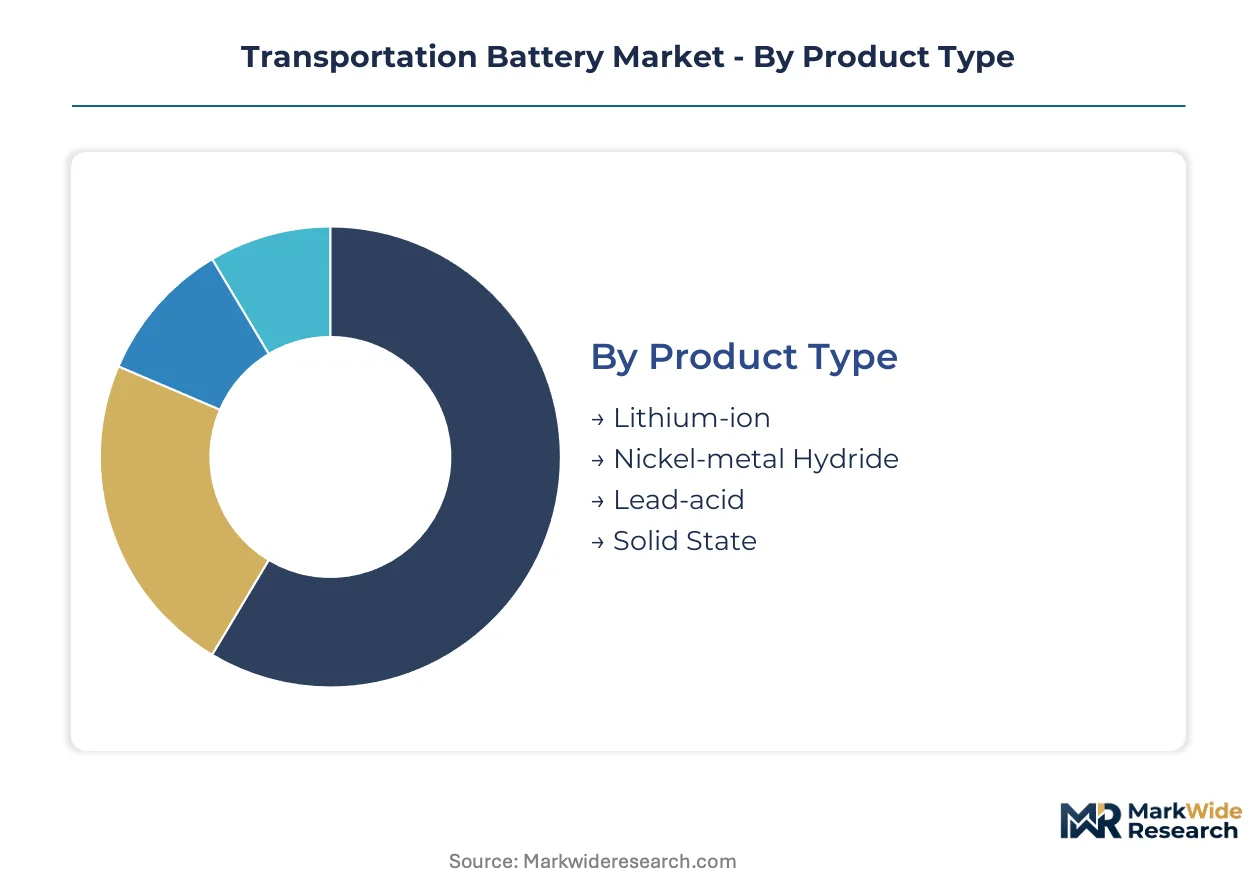
Transportation battery procurement patterns diverge sharply across chemistry platforms, vehicle architectures, and charging modalities. Cell manufacturers must align production capacity with distinct thermal management, cycle life, and power density specifications that each segment demands.
Product Type:
Chemistry selection determines energy density ceilings, safety margins, and raw material exposure for transportation applications.
- Lithium-ion:Nickel-cobalt-manganese and lithium-iron-phosphate cathode formulations dominate current production, delivering 250-300 Wh/kg energy density for passenger EV platforms. CATL and LG Energy Solution concentrate manufacturing in China, Germany, and the United States near automotive assembly clusters to minimize logistics costs.
- Solid State:Ceramic and sulfide electrolyte architectures eliminate flammable liquid components while targeting 400+ Wh/kg density thresholds. German and Japanese automakers are qualifying prototypes for premium platform launches, though manufacturing scale remains constrained by dry room infrastructure requirements and ceramic processing yield rates.
- Nickel-metal Hydride:Mature chemistry retains position in hybrid vehicle applications where moderate energy density tolerates lower material costs.
- Lead-acid:Flooded and absorbed glass mat formats persist in auxiliary power and starter functions for commercial vehicle fleets.
Lithium-ion commands the established base. The steepest expansion runs through Solid State.
End User:
Vehicle electrification mandates and duty cycle intensity create divergent performance requirements across mobility modes.
- Electric Vehicles:Battery electric platforms require 60-100 kWh packs for 300+ mile range targets, with cell-to-pack architectures eliminating module housings to improve volumetric efficiency. OEM procurement concentrates in China, Germany, and California where fleet electrification deadlines compress qualification timelines.
- Hybrid Vehicles:Parallel and series-hybrid configurations utilize smaller 1-2 kWh packs optimized for high-rate charge acceptance during regenerative braking cycles.
- Public Transport:Electric bus and rail applications demand 200-400 kWh systems with 10+ year cycle life under continuous high-current discharge.
- Aerospace:Urban air mobility prototypes and electric regional aircraft impose strict gravimetric density requirements above 300 Wh/kg with aviation-grade thermal runaway containment.
Electric Vehicles anchor current volume. Public Transport is climbing the fastest as municipal fleet mandates activate.
Application:
Deployment context shapes duty cycle profiles and integration complexity for battery system design.
- Energy Storage:Second-life EV packs and purpose-built stationary systems buffer renewable intermittency for charging infrastructure and grid services.
- Emergency Backup:Uninterruptible power systems for transit depots and maintenance facilities require rapid discharge capability with 15-30 minute runtime targets.
- Power Tools:Cordless equipment for vehicle assembly and maintenance operations utilizes compact 18-36V packs with high cycle durability.
- Marine:Electric propulsion for harbor vessels and short-route ferries demands saltwater corrosion resistance and modular scalability for 500+ kWh installations.
Energy Storage represents the fastest-growing trajectory as retired automotive packs enter circular supply chains.
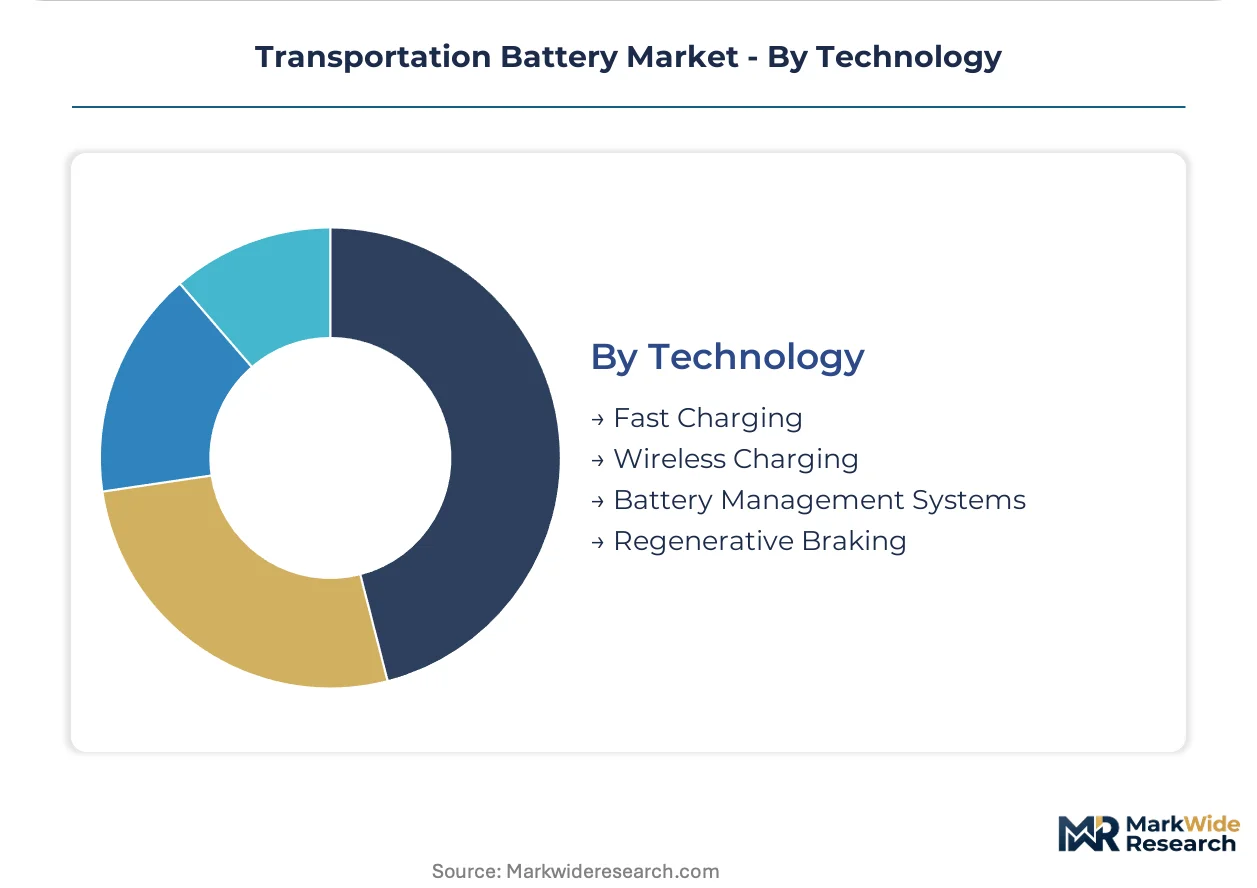
Technology:
Charging speed and energy recovery efficiency increasingly differentiate competitive positioning in transportation electrification.
- Fast Charging:350+ kW DC architectures reduce dwell time for commercial fleet operators, though lithium plating risks at low temperatures require sophisticated anode preconditioning algorithms.
- Wireless Charging:Inductive pad systems enable opportunity charging at bus depots and taxi stands, eliminating connector wear in high-frequency cycling environments.
- Battery Management Systems:Cell-level voltage and temperature monitoring with predictive state-of-health algorithms extend operational life and enable warranty risk pricing.
- Regenerative Braking:High-rate energy recovery during deceleration reduces net energy consumption 15-25% in urban driving cycles.
Fast Charging commands the established base. Wireless Charging is gaining share fastest as infrastructure deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese cell exports flow predominantly to European automotive assembly plants and North American EV fleets, with Germany and the United States serving as the largest destination markets for lithium-ion module shipments.
China
CATL and BYD anchor domestic production capacity exceeding 800 GWh annually, serving both captive vehicle demand and export contracts. MIIT enforces GB standards for cell safety and recycling traceability, tightening qualification timelines for overseas shipments. Cell gigafactories cluster in Fujian and Guangdong provinces near raw material refining operations and port infrastructure.
Germany
BMW, Mercedes-Benz, and Volkswagen procurement teams source cells from Korean and Chinese suppliers for European platform launches. EU Green Deal carbon-footprint disclosure rules and F-Gas Regulation fluorinated solvent restrictions reshape import qualification protocols. Production facilities concentrate in Lower Saxony and Baden-Württemberg, with cathode active material plants locating near Stuttgart and Wolfsburg assembly clusters.
United States
Ford, General Motors, and Tesla long-range contracts concentrate margin pools for 60-100 kWh passenger EV packs. IRA production tax credits pull cathode active material plants toward Michigan, Tennessee, and Kentucky to qualify for domestic content thresholds. Cell assembly operations cluster in Nevada, Texas, and the Midwest near vehicle manufacturing hubs.
South Korea
LG Energy Solution and Samsung SDI anchor electrode supply to European and North American automakers through dedicated joint ventures. Korean trade regulators coordinate with METI on battery supply chain resilience frameworks. Manufacturing concentrates in Ochang and Ulsan industrial complexes, with R&D facilities in Daejeon targeting solid-state electrolyte prototypes.
Japan
Panasonic and GS Yuasa supply cylindrical and prismatic formats for hybrid and premium EV platforms. METI directs funding toward solid-state ceramic electrolyte commercialization through 2027-2028 qualification windows. Production and research activities concentrate in Osaka-Kobe and Nagoya industrial corridors, with Toyota and Honda procurement teams co-locating engineering staff.
Transportation Battery Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Consolidation concentrates around vertically integrated conglomerates with captive vehicle demand and dedicated joint ventures with automotive OEMs. Strategic archetypes include raw-material-integrated cell producers, electrode-specialist joint ventures, and vehicle-captive battery divisions. Dominant competitive moves encompass cathode active material plant relocation to qualify for regional content credits and dry electrode coating technology licensing.
Among Chinese producers, CATL and BYD exemplify the vertically integrated archetype through upstream control over cathode materials and raw material refining. LG Energy Solution occupies a position within the Korean joint-venture specialist tier, anchoring electrode supply relationships across North American and European automotive customers. These three entities represent distinct strategic postures: raw-material integration, vehicle-captive demand absorption, and partnership-based geographic expansion.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| BYD |
| Panasonic |
| Samsung SDI |
| GS Yuasa Corporation |
| SK On |
| Johnson Controls |
| Exide Technologies |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese cell manufacturing is compressing spot pricing for lithium-ion modules while forcing Korean producers toward long-term offtake contracts with index-linked raw material clauses. This utilization divergence rewards integrated cathode producers with cost buffers while squeezing non-integrated assemblers into margin-negative bidding for OEM volume.
Pricing Analysis
Cost-plus contracts with London Metal Exchange lithium carbonate indexation dominate procurement between cell manufacturers and automotive OEMs. Price differentiation rests on cathode chemistry grade and UN 38.3 certification tier, with NCM811 cells commanding premiums over LFP formats. Cost compression in standard-range passenger EV packs is intensifying because of Chinese oversupply, though premium solid-state prototypes retain pricing power. Fleet operators exhibit the highest price sensitivity, while luxury automakers prioritize energy density over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates at CATL's Fujian facilities, LG Energy Solution's Nanjing and Michigan plants, and BYD's in-house blade cell operations across Guangdong. Raw material refining draws from Chilean lithium brine, Australian spodumene concentrate, and Indonesian nickel laterite. Single-source graphite dependence on Shandong and Heilongjiang anode processors creates chokepoint vulnerability under US critical mineral frameworks. Distribution runs through direct OEM-to-plant logistics corridors rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transportation battery market is cycling through a capacity-led recovery as OEM procurement accelerates ahead of fleet electrification mandates. Lithium carbonate price stabilization and IRA qualification timelines are restoring margin visibility for qualified producers.
For Market Incumbents: Entrench cathode active material production in Michigan, Tennessee, and Kentucky to capture IRA domestic content credits before competitor qualification. Secure long-term offtake agreements with Chilean and Australian mining operators to isolate against lithium carbonate volatility. Deepen backward integration into precursor refining to defend margin structure against Chinese oversupply.
For New Entrants and Emerging Players: Build out sodium-ion cell capacity for stationary storage and short-range commercial vehicle applications where performance requirements tolerate lower energy density. India's PLI scheme for advanced chemistry cells offers the most penetrable geography for joint venture entry with Korean electrode suppliers. Target direct fleet procurement relationships in California and Germany to bypass established OEM-supplier lock-in.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cell manufacturers with captive vehicle demand and long-term OEM service contracts. Five-to-ten-year viability favors producers with verified low-carbon nickel supply chains and solid-state pilot-scale validation. Monitor cathode active material plant relocation announcements as the signal for IRA qualification inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Active Material Plant Relocation | IRA qualification thresholds pull refining capacity toward Kentucky and Tennessee assembly corridors. |
| Solid-State Electrolyte Licensing | Sulfide and oxide prototypes from Japanese and German automakers compress competitive windows for liquid incumbents. |
| Second-Life Pack Circular Integration | Retired EV batteries with 70-80% capacity enter grid-scale buffering independent of virgin material supply. |
| Dry Electrode Coating Scale-Up | Elimination of solvent-based processing reduces formation cycling costs and facility energy intensity. |
| Direct Fleet Procurement Channel | California and Germany municipal mandates concentrate volume authority with central engineering groups. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of MIIT production filings, EU Battery Regulation carbon footprint disclosures, and OEM procurement contract registries. Interviews with cell formation technicians, cathode material procurement leads, automotive platform engineers, and fleet electrification directors informed demand assumptions. SEC 10-K filings from electrode suppliers and customs data from Chilean and Australian export authorities provided supply-side validation. Bottom-up cell shipment estimates and top-down automotive electrification targets were cross-referenced for triangulation.
Forecast inputs include vehicle production schedules across passenger, commercial, and public transport segments, plus chemistry-specific energy density roadmaps and charging infrastructure deployment rates. Segmentation dimensions span lithium-ion, solid-state, sodium-ion, and nickel-metal hydride chemistries; electric, hybrid, and fuel-cell vehicle architectures; and fast charging, wireless charging, and battery management system technologies. CAGRs were derived from installed base growth and replacement cycle analysis across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed producers or accelerated solid-state commercialization by Japanese automakers would shift outcomes. Quarterly review of lithium carbonate futures curves, IRA qualification announcement flows, and EU carbon border adjustment implementation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Battery Recycling
ASEAN Electric Vehicle Battery Anode Market
Transportation Battery Recycling
Automobile Storage Battery Market
Transportation Battery Recycling
China Transportation Battery Recycling Market
Transportation Battery Recycling
Europe Automotive Start-Stop Battery Market
Transportation Battery Recycling
Automotive Battery Recycling Market
Transportation Battery Recycling
South Korea Transportation Battery Recycling Market
Transportation Battery Recycling
Asia-Pacific Transportation Battery Recycling Market
Transportation Battery Recycling
Transportation Battery Recycling Market
Transportation Battery Recycling
Automotive Energy Recovery System Market
Transportation Battery Recycling
EV Battery Recycling Services Market
Transportation Battery Recycling
Two-Wheeler Battery Market
Transportation Battery Recycling
Europe Train Battery Market