
 Automobile Storage Battery Market | 2026-2036
Automobile Storage Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Automobile Storage Battery Market Analysis
Automotive battery distribution is tilting toward direct OEM supply contracts and dedicated EV service networks. GS Yuasa Corporation anchors the aftermarket channel through dense dealer partnerships across Asia. Panasonic Corporation leverages its captive relationships with electric vehicle manufacturers to secure long-term offtake agreements. Johnson Controls sustains scale advantages in conventional lead-acid replacement cycles through vertically aligned recycling infrastructure.
An automobile storage battery is an electrochemical device engineered to store and deliver direct current for engine starting, lighting, ignition, and auxiliary power functions, typically employing lead-acid, lithium-ion, or nickel-metal hydride chemistries with nominal voltages from 12V to 800V depending on application. Its primary industrial purpose centers on providing reliable cold-cranking amperage and deep-cycle endurance under variable thermal and vibration loads. Lithium-ion product types command the fastest expansion trajectory as energy density thresholds rise and pack costs compress. Start-stop technology applications in internal combustion platforms retain substantial volume but face margin compression from commoditization. Electric vehicle end users represent the dominant demand concentration where cell-to-pack architectures and thermal management integration create premium pricing tiers.
China's MIIT enforces GB standards for battery safety and recycling traceability, while the EPA in the United States governs lead smelter emissions and hazardous waste handling across the lead-acid value chain. The EU Green Deal and F-Gas Regulation constrain fluorinated electrolyte formulations and mandate circular economy protocols for end-of-life collection. Stakeholders must monitor how regulatory divergence across these jurisdictions reshapes certification burdens and local content requirements for new manufacturing investments.
Market Dynamics
Electrification mandates across major automotive markets are compressing development cycles and forcing chemistry transitions from lead-acid to lithium-ion architectures, reshaping supplier relationships and capital allocation priorities throughout the value chain.
Growth Catalysts
- EU Green Deal battery passport requirements:Mandates for full lifecycle traceability are accelerating investments in closed-loop recycling infrastructure and digital product documentation systems.
- Commercial logistics electrification:Fleet operators in last-mile delivery and urban freight are specifying high-cycle-life lithium-ion packs to minimize total cost of ownership.
- Cell-to-pack architecture advances:Elimination of module housings reduces mass and assembly complexity, enabling higher energy density thresholds for passenger vehicle integration.
Market Restraints
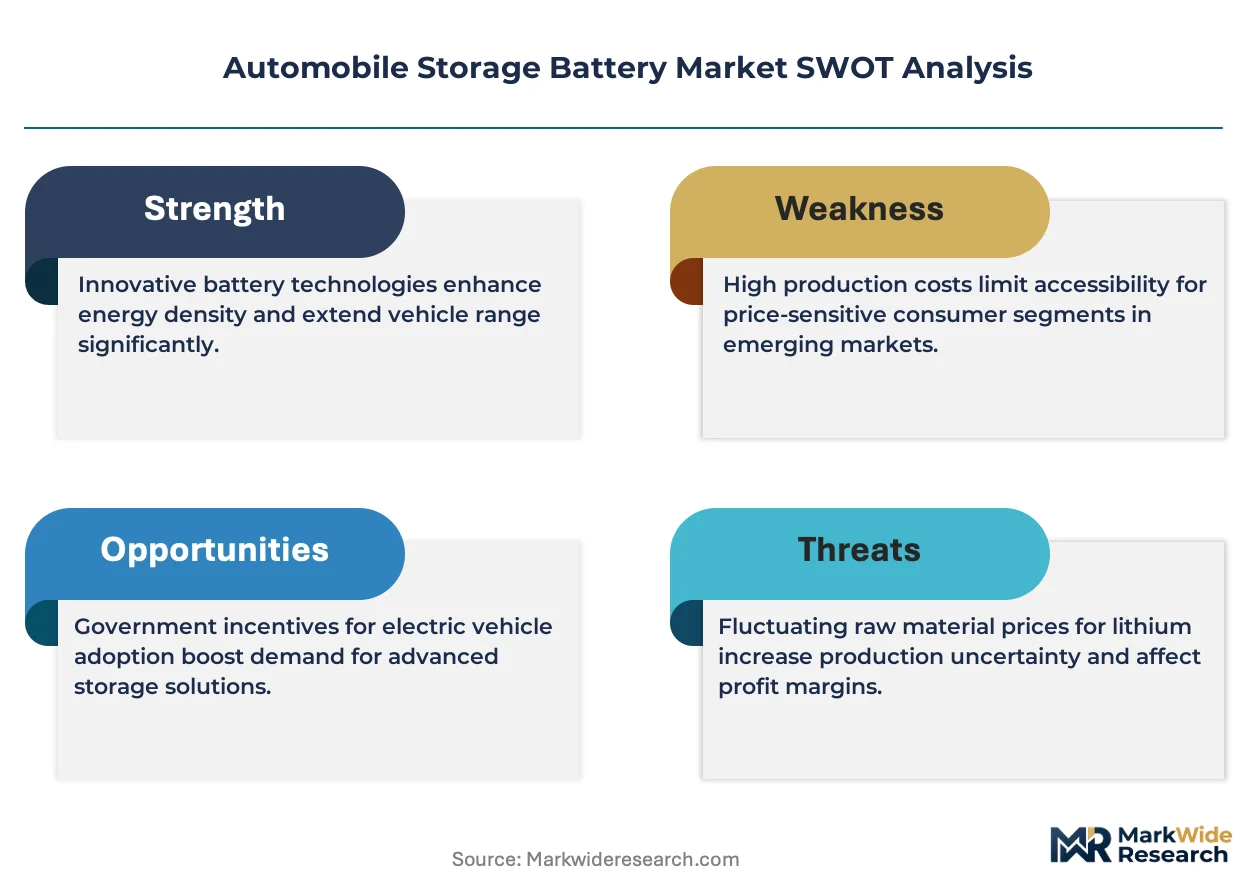
- Lithium carbonate price volatility:Concentrated South American and Australian supply exposes cell manufacturers to input cost swings that compress margin visibility.
- Lead-acid replacement cycle compression:Extended service intervals in modern internal combustion engines reduce aftermarket turnover frequency for conventional starter batteries.
- GB standards certification timelines:China's MIIT testing protocols for thermal runaway propagation create extended approval windows for new pack designs.
Strategic Opportunities
- Second-life stationary storage:Retired electric vehicle packs with residual capacity are repurposing for grid stabilization and renewable firming applications.
- India PLI scheme incentives:Production-linked subsidies for advanced chemistry cell manufacturing are attracting greenfield investments in Gujarat and Tamil Nadu.
- Solid-state electrolyte convergence:Ceramic and polymer solid-state technologies promise enhanced safety profiles and simplified thermal management for next-generation architectures.
Industry Challenges
- Battery management system firmware integration:OEMs require proprietary communication protocols that fragment software development resources across multiple platform specifications.
- End-of-life logistics coordination:Hazardous material transport regulations complicate reverse supply chain design for collection and preprocessing of spent packs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automobile Storage Battery Market |
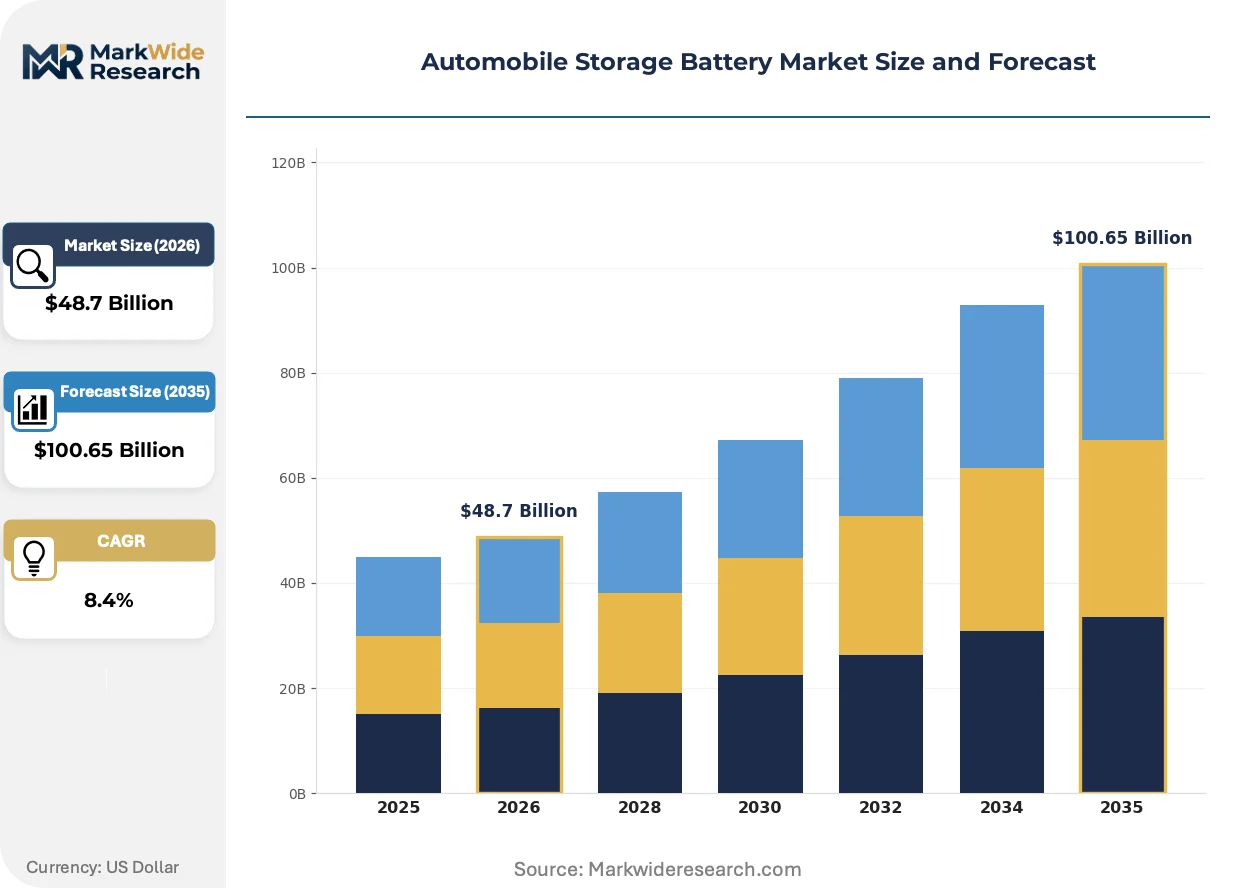
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Metal Hydride, Gel Battery Technology: Start-Stop Technology, Advanced Lead-Acid, AGM, EFB End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Vehicles Distribution Channel: Online Retail, Offline Retail, Distributors, Direct Sales |
| Companies Covered | Exide Technologies, GS Yuasa Corporation, Johnson Controls, Robert Bosch GmbH, East Penn Manufacturing Co., Toshiba Corporation, Hitachi Ltd, AC Delco, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automobile Storage Battery Market Emerging Trajectories
Digital twin technology and predictive analytics are penetrating battery system design and fleet management, reducing physical testing burdens while enabling real-time degradation monitoring across distributed vehicle populations.
Solid-state battery research is virtualizing conventional liquid electrolyte formulations by replacing flammable organic solvents with ceramic or glassy ionic conductors. Toyota Motor Corporation and Samsung SDI are advancing pilot production lines for sulfide-based architectures. This transition is virtualizing the need for complex thermal management hardware and enabling simplified pack geometries.
EPA hazardous waste regulations under RCRA Subtitle C are tightening cradle-to-grave documentation for lead-acid recycling operations. Smelters must now demonstrate verified collection chain-of-custody. The aftermarket replacement channel faces elevated compliance costs as independent distributors absorb additional tracking infrastructure investments.
Fleet operators are consolidating procurement through direct manufacturer relationships rather than traditional parts distribution networks. Commercial buyers in California and Germany are negotiating volume-based service agreements that bundle hardware, installation, and predictive maintenance. This pattern is most visible in municipal transit and airport ground support equipment segments where uptime guarantees dominate vendor selection criteria.
Automobile Storage Battery Market Segmentation
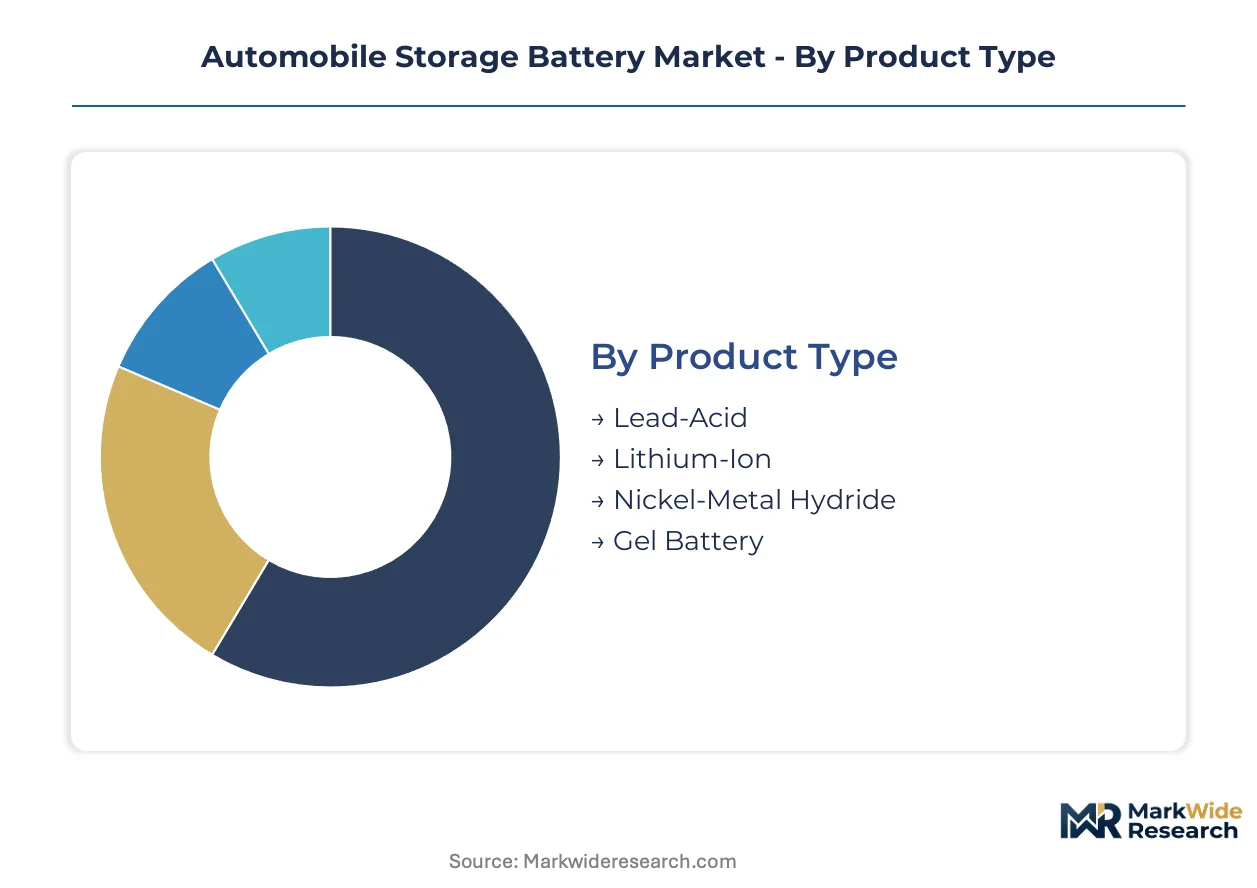
Segmentation in the automobile storage battery market reveals how chemistry transitions, electrification intensity, and channel economics reshape supplier priorities. Each dimension carries distinct margin profiles, certification burdens, and capital requirements that determine competitive positioning.
Product Type:
The maturity spectrum spans century-old lead-acid architectures to emerging solid-state research platforms, with lithium-ion occupying the critical growth inflection point.
- Lithium-Ion:Cells employ layered oxide cathodes and graphite anodes achieving 250-300 Wh/kg energy density, with cell-to-pack designs eliminating module housings. Demand concentrates in China's NEV fleet and Germany's premium passenger EV platforms, driven by MIIT subsidy tiers and EU CO2 fleet mandates. Cell manufacturers face lithium carbonate cost volatility from concentrated South American brine operations.
- Lead-Acid:Flooded and valve-regulated designs using lead dioxide positive plates and sponge lead negative electrodes deliver 30-50 Wh/kg with established recycling loops. Replacement cycles dominate India's two-wheeler aftermarket and US commercial fleet starter applications, constrained by extended service intervals in modern internal combustion engines.
- Nickel-Metal Hydride:Toyota's hybrid systems remain the primary demand concentration for this chemistry, with limited new platform adoption outside legacy hybrid architectures.
- Gel Battery:Silica-thickened electrolyte formulations serve deep-cycle marine and recreational vehicle applications in coastal US markets and Mediterranean leisure craft segments.
Lead-acid handles the majority of throughput; lithium-ion is expanding most quickly on share.
Technology:
Cost tier differentiation separates commodity starter batteries from integrated powertrain components requiring proprietary thermal management.
- Start-Stop Technology:Enhanced cycling endurance supports engine-off coasting in mild-hybrid architectures, with EFB and AGM variants specified by European OEMs to meet WLTP efficiency targets. Johnson Controls and GS Yuasa anchor supply contracts for Volkswagen Group and Stellantis platforms.
- AGM:Absorbed glass mat separators enable higher charge acceptance for regenerative braking energy recovery, concentrating in German premium sedan and SUV segments where stop-start duty cycles are most severe.
- Advanced Lead-Acid:Carbon-enhanced negative electrodes extend partial state-of-charge operation for entry-level hybrid systems in India and Southeast Asia.
- EFB:Enhanced flooded battery designs offer intermediate cycling performance for cost-sensitive start-stop applications in Japanese domestic market compacts.
Start-stop technology captures the largest installed base; AGM commands the steepest expansion trajectory in value terms.
End User:
Application intensity varies from shallow-cycling starter loads to deep-discharge traction duty, dictating cell chemistry and thermal system specifications.
- Electric Vehicles:400V and 800V pack architectures with liquid cooling circuits and active cell balancing dominate cell procurement volumes, with BYD and Tesla vertical integration strategies reshaping supplier relationships.
- Commercial Vehicles:Heavy-duty trucking electrification in California's CARB-regulated corridors and EU urban freight zones drives demand for high-cycle-life packs with megawatt-hour-scale charging compatibility.
- Passenger Vehicles:Conventional internal combustion platforms retain substantial lead-acid volumes in emerging markets with limited charging infrastructure.
- Two-Wheelers:India's electric scooter transition under FAME-II subsidies and Southeast Asian last-mile delivery fleets specify compact lithium-ion packs with swappable battery architectures.
Electric vehicles absorb the dominant share of advanced cell output; commercial vehicles are climbing the fastest on electrification investment.
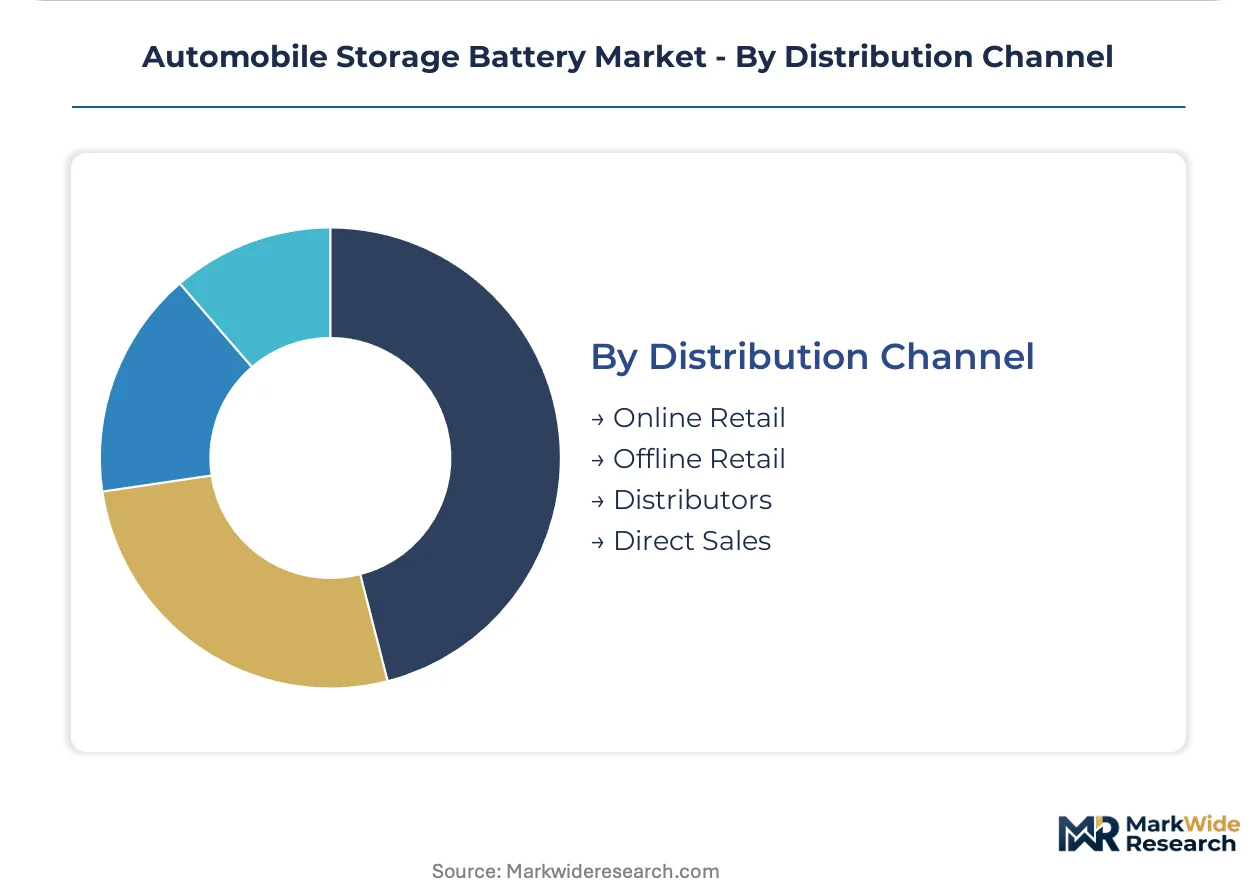
Distribution Channel:
Customer type bifurcation separates fleet procurement professionals from individual replacement buyers, fragmenting pricing power and service bundling opportunities.
- Direct Sales:OEM supply contracts and fleet service agreements bundle hardware, installation, and predictive maintenance, concentrating in California municipal transit and German airport ground support equipment.
- Distributors:Independent warehouse networks serve fragmented aftermarket demand across India's tier-2 cities and Latin American urban centers, absorbing compliance costs from EPA RCRA chain-of-custody requirements.
- Offline Retail:Dealer-affiliated service bays handle warranty replacements and emergency roadside assistance for conventional starter batteries.
- Online Retail:E-commerce platforms gain traction in consumer EV accessory segments and DIY enthusiast markets with standardized fitment databases.
Direct sales channels command the highest contract values; online retail is gaining share fastest among non-critical replacement segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT subsidy tiers and the EU Green Deal's battery passport mandates are compressing development cycles across major automotive markets. National electrification targets in India and the United States are reshaping where cell manufacturing capacity anchors.
China
NEV fleet expansion and cell-to-pack architecture adoption dominate procurement volumes. MIIT enforces GB standards for thermal runaway propagation testing, extending approval timelines for new designs. The Yangtze River Delta cluster around Shanghai concentrates CATL and BYD gigafactory operations supplying domestic OEMs.
Germany
Premium passenger EV platforms from BMW and Mercedes-Benz drive high-voltage pack demand. The EU Green Deal mandates circular economy protocols and full lifecycle traceability through digital battery passports. North Rhine-Westphalia hosts Volkswagen Group's Salzgitter cell factory and BASF cathode material operations.
United States
IRA production tax credits are attracting Korean cell manufacturers to joint venture with Detroit automakers. EPA RCRA Subtitle C governs hazardous waste documentation for lead-acid recycling chains. Michigan and Ohio anchor Midwest battery corridor investments from SK Innovation and LG Energy Solution.
India
FAME-II subsidies and state-level EV policies are accelerating two-wheeler and three-wheeler electrification. The PLI scheme for advanced chemistry cells offers production-linked incentives attracting greenfield investments. Gujarat and Tamil Nadu are emerging as manufacturing hubs with Reliance and Ola Electric facility commitments.
Japan
Hybrid vehicle production sustains nickel-metal hydride demand while solid-state research advances. METI funding supports sulfide-based electrolyte pilot lines at Toyota and Samsung SDI partnerships. The Nagoya-Tokyo corridor concentrates Panasonic's cylindrical cell production for Tesla supply agreements.
Automobile Storage Battery Market Vendor Landscape
On the supply side, the industry is consolidating around chemistry-specific capabilities with lithium-ion specialists capturing premium contract values. Tiered competitive dynamics separate integrated cell-pack manufacturers from component suppliers and recycling operators. Strategic archetypes include captive OEM partnerships, aftermarket channel anchors, and materials-integrated recyclers. Capacity expansion and strategic partnerships dominate competitive moves as firms secure offtake agreements and mineral supply chains.
Among diversified industrial conglomerates, Panasonic Corporation and Toshiba Corporation exemplify technology licensors with established OEM relationships. GS Yuasa Corporation occupies a position within the aftermarket channel anchor archetype through dense dealer networks. Johnson Controls represents the vertically integrated recycler archetype with closed-loop lead-acid infrastructure. Exide Technologies and East Penn Manufacturing Co. sit within the regional scale-player tier serving conventional replacement cycles.
| Leading Market Players |
|---|
| Exide Technologies |
| GS Yuasa Corporation |
| Johnson Controls |
| Robert Bosch GmbH |
| East Penn Manufacturing Co. |
| Toshiba Corporation |
| Hitachi Ltd |
| AC Delco |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Yangtze River Delta cell manufacturing cluster compresses contract pricing power while forcing Korean and Japanese suppliers toward premium niche positioning and captive OEM relationships.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with fleet operators securing bundled hardware-installation-maintenance contracts at 15-20% below spot replacement rates. Price differentiation rests on certification grade—GB standards compliance for Chinese NEV subsidies versus UL 2580 for North American liability coverage—and vertical integration depth in cathode precursor production. Cost compression in entry-level lithium-ion modules is intensifying because of sodium-ion chemistry emergence and recycled content mandates. Commercial logistics buyers exhibit lowest price sensitivity due to total-cost-of-ownership framing, while independent aftermarket distributors face margin erosion from EPA RCRA compliance overhead.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic sourcing decisions, accelerating Korean cell manufacturer joint ventures with Detroit automakers under IRA production tax credit frameworks. Geographic supply concentration centers on China for processed cathode materials, South Korea for high-nickhel cell assembly, and Australia for spodumene concentrate. Raw material dependencies draw from Chilean and Argentine lithium brine, Indonesian nickel laterite, and Chinese graphite spheroidization capacity. Single-source vulnerability in electrolyte salt production—particularly LiPF6—creates procurement contingency planning. Distribution runs through direct OEM supply contracts for EV platforms and fragmented independent warehouse networks for lead-acid replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across last-mile logistics and municipal transit segments is shifting procurement leverage toward volume-based service agreements with uptime guarantees.
For Market Incumbents: Entrench position through backward integration into cathode active material production and closed-loop recycling infrastructure. Secure long-term offtake agreements with lithium brine operators to offset carbonate price volatility. Prioritize GB standards pre-certification for Chinese NEV subsidy eligibility. Defend against sodium-ion substitution threats by emphasizing energy density performance in premium passenger EV segments. For New Entrants and Emerging Players: Establish a beachhead in India's two-wheeler and three-wheeler electrification wave under FAME-II subsidy tiers. Target second-life stationary storage applications where residual capacity verification protocols remain underdeveloped. Pursue solid-state electrolyte pilot production partnerships with Japanese automotive OEMs. Lead with swappable battery architecture solutions for Southeast Asian last-mile delivery fleets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet service providers bundling predictive maintenance and residual value guarantees. Long-term viability favors materials-integrated recyclers with hydrometallurgical processing capabilities and verified collection chain-of-custody systems. Acquisition target archetype: mid-scale cell-pack integrators with established OEM qualification status and underutilized production lines. Monitor solid-state pilot production yield rates as inflection indicator for next-generation chemistry commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Adoption | CATL and BYD designs eliminate module housings, reducing mass and assembly complexity for OEM integration. |
| Closed-Loop Recycling Infrastructure | |
| Solid-State Electrolyte Pilot Production | Toyota and Samsung SDI sulfide-based lines promise simplified thermal management and enhanced safety profiles. |
| Direct Fleet Service Agreements | California municipal transit operators bundle hardware, installation, and predictive maintenance under uptime guarantee contracts. |
| India PLI Scheme Manufacturing Commitments | Reliance and Ola Electric Gujarat facilities attract production-linked subsidies for advanced chemistry cell output. |
Methodological Framework
Cross-validation between OEM platform engineering disclosures and customs trade data anchors the qualitative findings on cell procurement volumes and chemistry transitions. Primary interviews with Tier 1 supplier procurement leads, aftermarket distribution network managers, battery recycling facility operators, and OEM electrification strategy directors combined with secondary validation from MIIT subsidy filings, EPA RCRA enforcement records, EU battery passport documentation, and IHS Markit vehicle production databases. Bottom-up cell demand modeling and top-down fleet electrification scenario analysis triangulate market sizing across the projection horizon.
Calibration against historical lithium-ion pack cost curves and lead-acid replacement cycle compression patterns shapes the analytical framework. Segmentation dimensions modeled span vehicle class, propulsion architecture, cell chemistry family, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections and capacity expansion announcements. Forecast inputs incorporate FAME-II subsidy phase-out schedules and IRA domestic content threshold escalations.
Sensitivities concentrate around lithium carbonate price volatility, solid-state commercialization delays, and subsidy regime discontinuities. Forecasts reflect documented assumptions on fleet electrification penetration rates and recycling yield improvements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Battery Recycling
China Transportation Battery Recycling Market
Transportation Battery Recycling
ASEAN Electric Vehicle Battery Anode Market
Transportation Battery Recycling
Asia-Pacific Transportation Battery Recycling Market
Transportation Battery Recycling
Two-Wheeler Battery Market
Transportation Battery Recycling
Transportation Battery Market
Transportation Battery Recycling
EV Battery Recycling Services Market
Transportation Battery Recycling
Automotive Energy Recovery System Market
Transportation Battery Recycling
Transportation Battery Recycling Market
Transportation Battery Recycling
Automotive Battery Recycling Market
Transportation Battery Recycling
Europe Automotive Start-Stop Battery Market
Transportation Battery Recycling
Europe Train Battery Market
Transportation Battery Recycling
South Korea Transportation Battery Recycling Market