
 US Specialty Injectable Generics Market | 2026-2036
US Specialty Injectable Generics Market Size, Share, and Industry Trends Forecast 2026-2036
US Specialty Injectable Generics Market Insights
India is fragmenting as a manufacturing base for US-bound sterile injectables as FDA inspection backlogs and tariff exposure prompt sponsors to diversify geographic risk. Pfizer, Inc. anchors its position through captive fill-finish capacity and active pharmaceutical ingredient integration across North American sites. Teva Pharmaceutical Industries Ltd. competes through high-volume antibiotic injectable portfolios and long-standing hospital GPO relationships. Hikma Pharmaceuticals PLC differentiates via emergency injectable shortages and therapeutic categories where supply continuity commands premium positioning.
US specialty injectable generics comprise sterile, complex parenteral drug products that replicate innovator formulations in lyophilized powder, liquid, or premixed bag configurations, requiring aseptic processing, endotoxin control, and particulate matter thresholds below USP limits. These products serve oncology, anti-infective, and critical care protocols where intravenous or subcutaneous administration demands bioequivalence to reference listed drugs. Chemotherapy agents represent the deepest margin pool within product type segmentation, while specialty pharmacies emerge as the fastest-growing end-user channel as reimbursement shifts toward site-neutral payment models. Intravenous delivery mode retains volume dominance, though subcutaneous formulations gain share as self-administration protocols expand in rheumatology and endocrinology.
FDA governs abbreviated new drug applications for complex parenterals through bioequivalence waivers and quality-by-design manufacturing standards, while USP sets sterility assurance and container-closure integrity benchmarks that shape facility capital requirements. State boards of pharmacy and 503B compounding oversight create additional compliance layers for hospital and clinic purchasers sourcing admixture-ready products. Stakeholders must monitor FDA facility inspection prioritization, USP chapter revisions on particulate matter, and site-of-care reimbursement rulemaking to anticipate supply constraints and channel profit migration.
Market Dynamics
Hospital formulary committees are consolidating supplier panels around manufacturers with captive API supply and redundant sterile fill-finish lines, compressing vendor counts while elevating technical qualification barriers for new entrants.
Growth Catalysts
- Site-neutral reimbursement:Medicare's outpatient prospective payment system revisions incentivize migration of infused oncology therapies from hospital outpatient departments to freestanding infusion centers, expanding addressable volume for admixture-ready bag presentations.
- EMA/FDA mutual recognition:Streamlined facility inspections between European and US regulators accelerate cross-Atlantic manufacturing network approvals, reducing time-to-market for complex parenteral filings.
- Texas oncology corridor:Houston and Dallas-Fort Worth metropolitan clusters anchor the densest concentration of community-based cancer centers in the US, generating concentrated demand for high-volume chemotherapy injectable procurement.
Market Restraints
- API import concentration:Active pharmaceutical ingredient sourcing for sterile injectables remains concentrated among Indian and Chinese manufacturers, exposing sponsors to tariff volatility and FDA inspection backlog delays.
- Lyophilization capacity scarcity:Freeze-dry processing for unstable biologic generics requires specialized equipment with 18-24 month lead times, constraining supply expansion for high-margin oncology products.
- Container-closure integrity validation:USP Chapter 1207 testing protocols for elastomeric closure systems impose capital-intensive qualification requirements that deter mid-scale facility investments.
Strategic Opportunities
- Florida ambulatory infusion expansion:Retiree demographic concentration and favorable state scope-of-practice regulations position Tampa and Miami metro areas for rapid specialty pharmacy clinic network buildout.
- Dual-chamber mixing systems:Device-drug combination platforms that separate lyophilized powder from diluent until point-of-use address stability limitations and differentiate against conventional vial presentations.
- IRA price negotiation carve-outs:Small-molecule oncology injectables with abbreviated new drug application pathways face delayed Medicare price controls relative to oral solid dosage forms, preserving margin runway through 2031.
Industry Challenges
- Aseptic processing technician scarcity:FDA's updated guidance on personnel qualification and media fill requirements intensifies competition for operators with isolator and restricted access barrier system experience.
- Legacy enterprise resource planning integration:Serialization and track-and-trace mandates under the Drug Supply Chain Security Act force costly upgrades to manufacturing execution systems at contract fill-finish sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Specialty Injectable Generics Market |
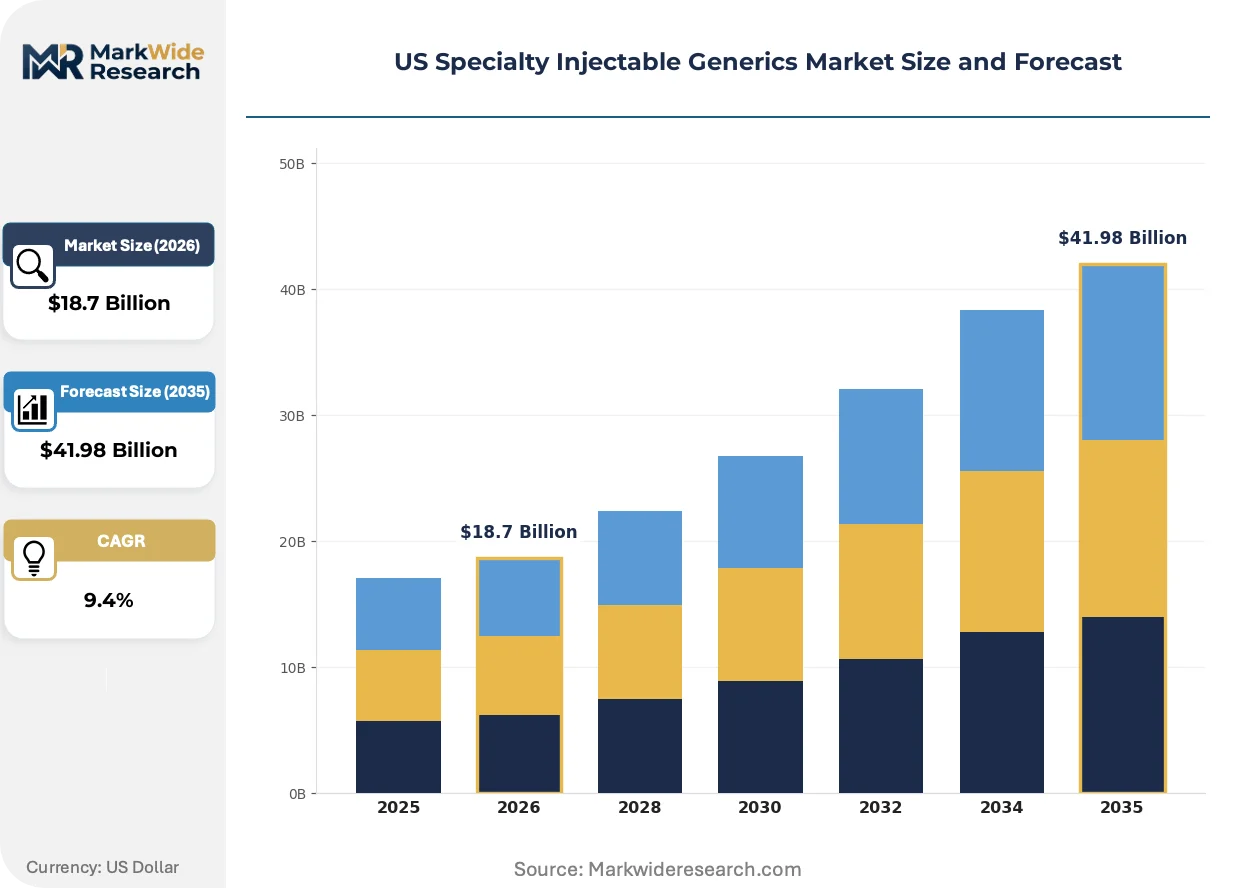
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Chemotherapy Agents, Hormones, Enzymes End User: Hospitals, Clinics, Homecare, Specialty Pharmacies Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Intra-articular Therapy Area: Oncology, Rheumatology, Endocrinology, Infectious Diseases |
| Companies Covered | Pfizer, Inc., Teva Pharmaceutical Industries Ltd., Baxter International, Fresenius SE & Co. KGaA, Hikma Pharmaceuticals PLC, Dr. Reddy's Laboratories, Par Pharmaceutical, Sagent Pharmaceuticals, Inc., Mylan N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Specialty Injectable Generics Market Trends and Innovations
Continuous manufacturing platforms and closed-system drug-device combinations are compressing batch cycle times while expanding self-administration protocols outside traditional infusion center settings.
Single-use bioreactor systems for sterile injectable API production are rendering obsolete stainless steel vessel campaigns that require lengthy cleaning validation and changeover protocols. Contract manufacturers in North Carolina and Massachusetts are adopting these disposable technologies to compress campaign turnaround from weeks to days. This shift is rendering obsolete the capital-intensive fixed-asset models that previously anchored competitive positioning in high-volume antibiotic generics.
FDA's Quality Management Maturity program establishes tiered inspection risk classifications that reward sponsors with robust quality systems through reduced surveillance frequency and expedited review pathways. Facilities achieving Level 3 maturity ratings gain competitive advantage in hospital GPO supplier scorecards that weight regulatory compliance heavily. Oncology-focused sponsors with California and New Jersey manufacturing footprints are prioritizing program enrollment to defend preferred vendor status.
Hospital purchasing cooperatives are consolidating annual contract negotiations around sole-source agreements for therapeutic categories with limited qualified suppliers, displacing multi-source bidding for commodity injectables. This concentration elevates supply continuity and disaster recovery capabilities above unit price in evaluation criteria. The phenomenon is most visible in Texas and California health systems where integrated delivery networks control substantial oncology infusion volume.
US Specialty Injectable Generics Market Segmentation
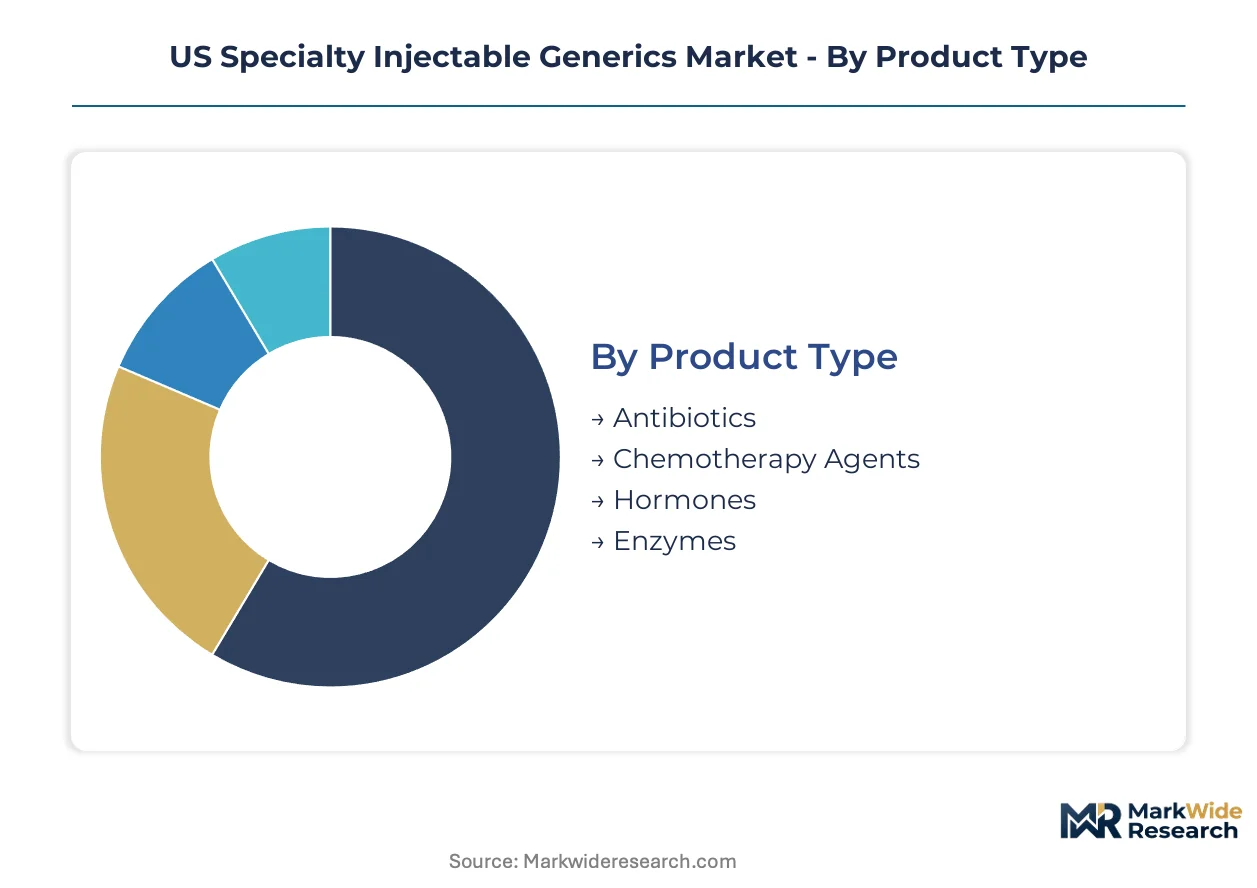
Specialty injectable generics require precise segmentation to match formulation complexity with channel economics. Each dimension—product chemistry, care setting, administration route, and therapeutic indication—carries distinct regulatory burdens and margin profiles that shape procurement behavior.
Product Type:
After-sales service intensity varies sharply across product categories, with chemotherapy agents demanding 24-hour cold chain monitoring and antibiotic lots requiring rapid sterility testing turnaround.
- Chemotherapy Agents:Lyophilized and liquid cytotoxic formulations replicate innovator oncology portfolios with bioequivalence waivers for complex parenterals. Demand concentrates in Texas and Florida infusion center networks where site-neutral reimbursement accelerates migration from hospital outpatient departments.
- Antibiotics:High-volume beta-lactam and glycopeptide injectables serve sepsis protocols with short shelf-life constraints and frequent shortage vulnerability. Hospital GPOs in California prioritize redundant fill-finish sourcing for these products given supply continuity mandates.
- Hormones:Peptide and steroid injectables for endocrine replacement require precise potency validation across batch releases.
- Enzymes:Biologic-origin parenterals with complex protein folding specifications face extended FDA analytical review timelines.
Chemotherapy agents hold the largest share; momentum sits with antibiotics as shortage-driven premium pricing expands.
End User:
Channel cost structures diverge based on reimbursement mechanics and inventory carrying requirements, with specialty pharmacies capturing the steepest expansion trajectory.
- Specialty Pharmacies:Independent and health-system-affiliated infusion providers manage admixture-ready bag presentations under site-neutral Medicare payment rules. Florida's Tampa and Miami metro areas anchor the fastest clinic network buildout given retiree density and favorable scope-of-practice regulations.
- Hospitals:Integrated delivery networks consolidate formulary panels around sole-source agreements for therapeutic categories with limited qualified suppliers. Texas health systems weight disaster recovery capabilities above unit price in oncology injectable procurement.
- Clinics:Community-based administration sites require just-in-time delivery models with minimal lot-size flexibility.
- Homecare:Self-administration protocols for subcutaneous formulations demand patient training infrastructure and remote monitoring capabilities.
Specialty pharmacies represent the fastest-growing channel; hospitals retain the dominant volume position.
Delivery Mode:
Administration route determines container-closure complexity and stability validation requirements, with subcutaneous formulations gaining share through patient convenience protocols.
- Intravenous:Large-volume bag and syringe presentations dominate oncology and anti-infective protocols with established compounding workflows. California and Texas cancer centers drive concentrated procurement for IV chemotherapy generics given infusion center network density.
- Subcutaneous:Prefilled syringe and auto-injector formats expand in rheumatology and endocrinology as self-administration protocols reduce facility dependency. FDA device-drug combination pathways add regulatory layers but differentiate against commoditized vial presentations.
- Intramuscular:Depot formulations for hormonal and psychiatric indications require extended release validation studies.
- Intra-articular:Joint-space injectables for osteoarthritis carry sterility assurance thresholds above standard parenteral limits.
Intravenous delivery holds the largest share; subcutaneous administration is climbing the fastest on self-injection protocol expansion.
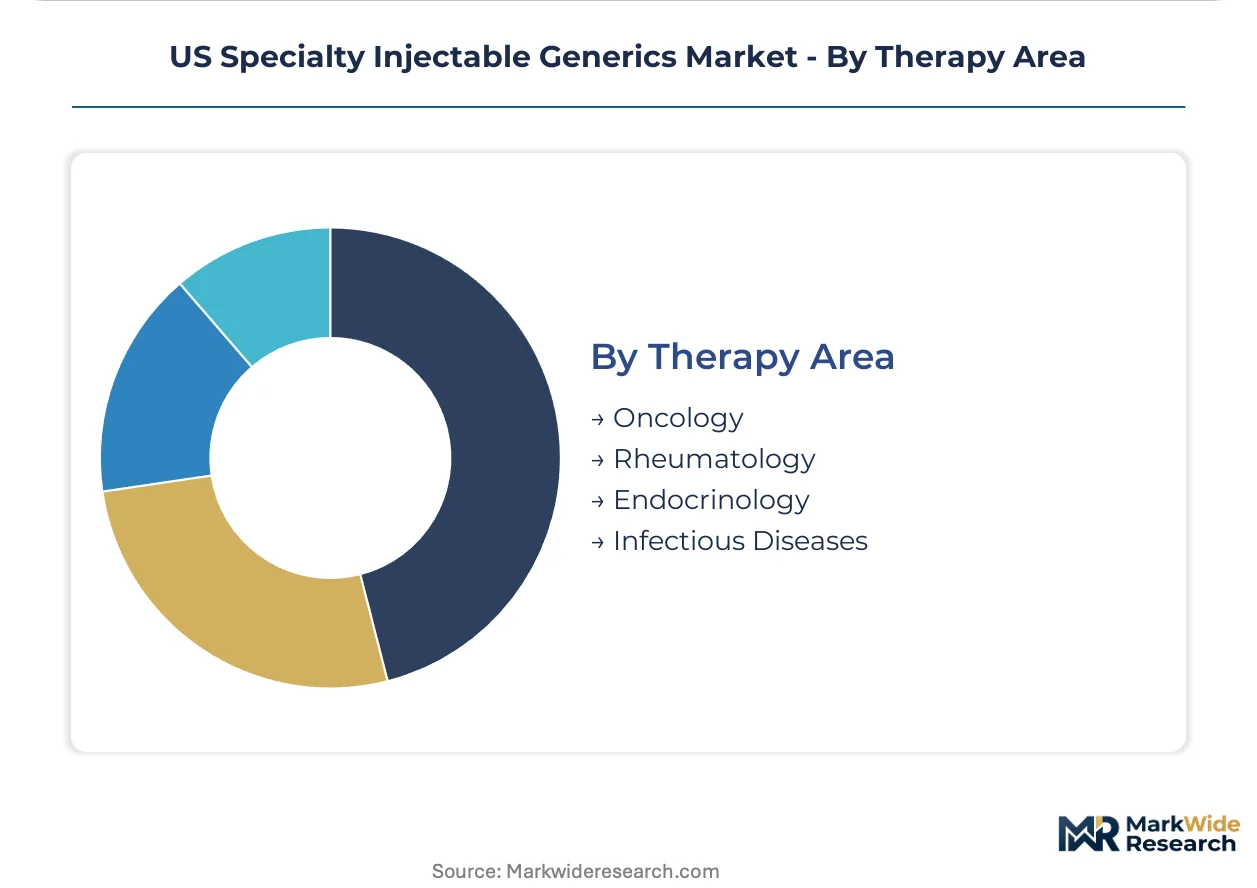
Therapy Area:
Therapeutic focus shapes API sourcing strategies and manufacturing facility qualification priorities, with oncology commanding the deepest technical barriers.
- Oncology:Cytotoxic and supportive care injectables replicate complex innovator formulations with lyophilization requirements and particulate matter thresholds below USP limits. Houston and Dallas-Fort Worth metropolitan clusters generate the densest US demand concentration for high-volume chemotherapy procurement.
- Infectious Diseases:Anti-infective parenterals face recurring shortage cycles that elevate supply continuity premiums in hospital supplier scorecards. FDA inspection backlogs for Indian API manufacturers expose sponsors to geographic concentration risk.
- Rheumatology:Biologic-origin injectables for autoimmune protocols require cold chain integrity across distribution networks.
- Endocrinology:Insulin and peptide hormone generics compete against reference listed drugs with established patient switching patterns.
Oncology holds the largest share; infectious diseases is gaining share fastest on shortage-driven procurement urgency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fill-finish capacity for sterile injectables clusters in coastal states with established pharmaceutical manufacturing ecosystems, while demand concentrates in metropolitan cancer corridors where infusion center networks have achieved critical density.
Texas
Houston and Dallas-Fort Worth anchor the densest concentration of community-based cancer centers in the US, generating concentrated procurement demand for high-volume chemotherapy injectables. State Medicaid reimbursement policies favor site-neutral payment models that accelerate migration from hospital outpatient departments to freestanding infusion facilities. The Texas Medical Center in Houston coordinates bulk purchasing agreements that prioritize supply continuity and disaster recovery capabilities over unit price.
California
Integrated delivery networks in Los Angeles and San Francisco Bay Area weight redundant fill-finish sourcing heavily in oncology injectable procurement decisions. State board of pharmacy oversight of 503B compounding creates additional compliance layers for hospital and clinic purchasers sourcing admixture-ready products. San Diego's biotech corridor hosts contract manufacturing organizations adopting single-use bioreactor systems to compress campaign turnaround times.
Florida
Tampa and Miami metropolitan areas anchor the fastest specialty pharmacy clinic network buildout, driven by retiree demographic concentration and favorable scope-of-practice regulations for nurse-administered infusion. State licensing frameworks for ambulatory infusion centers reduce regulatory friction compared to certificate-of-need states. Orlando's health system consolidation has produced sole-source agreements for therapeutic categories with limited qualified suppliers.
New York Metro
Academic medical centers in Manhattan and Long Island drive demand for complex lyophilized formulations requiring extended analytical validation. State Medicaid Drug Rebate Program negotiations compress margins on high-volume antibiotic injectables while preserving oncology premium positioning. Northern New Jersey manufacturing sites supply the metro area with captive API-integrated production that reduces import dependency.
North Carolina
Research Triangle Park contract manufacturers are adopting continuous manufacturing platforms for sterile injectable API production. State economic development incentives for pharmaceutical manufacturing have attracted fill-finish investments from sponsors seeking geographic diversification from Indian and Chinese supply bases. Durham and Raleigh metro areas host quality management maturity programs that reward robust quality systems with reduced FDA surveillance frequency.
US Specialty Injectable Generics Market Competitive Landscape
Vertically integrated multinationals and high-volume generic specialists split the market between captive API-fill-finish ecosystems and hospital GPO-anchored distribution networks. Three archetypes dominate: North American manufacturing-integrated sponsors with redundant sterile lines, Indian API-dependent firms with US fill-finish partnerships, and emergency shortage responders with therapeutic category concentration. Competitive moves center on geographic manufacturing diversification and sole-source contract capture through supply continuity guarantees.
Among North American manufacturing-integrated sponsors, Pfizer, Inc. and Teva Pharmaceutical Industries Ltd. exemplify the captive capacity archetype. Hikma Pharmaceuticals PLC occupies a position within the emergency shortage response tier, differentiating through supply continuity premiums in therapeutic categories with recurring vulnerability. These three entities anchor the competitive structure through divergent strategic postures on API sourcing, geographic manufacturing footprint, and hospital purchasing cooperative engagement intensity.
| Leading Market Players |
|---|
| Pfizer, Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Baxter International |
| Fresenius SE & Co. KGaA |
| Hikma Pharmaceuticals PLC |
| Dr. Reddy's Laboratories |
| Par Pharmaceutical |
| Sagent Pharmaceuticals, Inc. |
| Mylan N.V. |
| Others |
Pricing and Supply Chain Analysis
Indian API concentration for sterile injectables funnels margin pools toward North American fill-finish sponsors with captive manufacturing capabilities, while hospital GPOs weaponize supply continuity guarantees to extract price concessions from import-dependent competitors. FDA inspection backlogs and tariff exposure on active pharmaceutical ingredients compress margins for sponsors lacking geographic diversification, elevating premiums for redundant domestic production lines.
Pricing Analysis
IRA price negotiation carve-outs dictate the pricing tier structure for small-molecule oncology injectables, preserving premium positioning through 2031 relative to oral solid dosage forms. Three-tier pricing structure across premium, standard, and economy levels separates FDA Level 3 Quality Management Maturity-rated facilities from commodity fill-finish operations and emergency shortage responders. Cost compression in standard-tier antibiotic injectables is intensifying because hospital GPOs consolidate formulary panels around sole-source agreements. Integrated delivery networks in Texas and California demonstrate least price sensitivity, prioritizing disaster recovery capabilities and redundant sourcing above per-unit costs.
Supply Chain Analysis
Export-control scrutiny on pharmaceutical manufacturing equipment constrains capacity expansion for lyophilization and isolator systems, tightening supply of complex parenteral production assets. Active pharmaceutical ingredient sourcing draws from Indian and Chinese manufacturers, with North American fill-finish operations providing final sterile processing. Single-use bioreactor systems and elastomeric closure components constitute critical input dependencies. Tariff exposure on imported APIs presents the dominant structural risk, compounded by FDA inspection prioritization delays. Distribution runs through hospital GPOs and specialty pharmacy networks, with site-neutral reimbursement accelerating migration toward ambulatory infusion channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital formulary consolidation around sole-source agreements fragments competitive space, creating niches for sponsors with differentiated supply continuity credentials and captive API integration. Site-neutral Medicare payment rules accelerate demand migration toward freestanding infusion centers, opening white-space opportunities in admixture-ready bag presentations.
For Market Incumbents: Build regulatory quality moats through FDA Quality Management Maturity Level 3 certification to secure preferred vendor status in hospital GPO scorecards. Expand redundant sterile fill-finish capacity in North Carolina and Massachusetts to offset Indian API concentration risk. Defend against emerging device-drug combination platforms by accelerating dual-chamber mixing system development. Prioritize enrollment in FDA expedited review pathways to compress ANDA approval timelines for complex parenterals.
For New Entrants and Emerging Players: Florida ambulatory infusion corridors offer the most penetrable geographic entry point, given retiree demographic concentration and favorable scope-of-practice regulations. Target Tampa and Miami metro specialty pharmacy clinic buildouts with just-in-time delivery models for admixture-ready chemotherapy presentations. Exploit lyophilization capacity scarcity by partnering with Research Triangle Park contract manufacturers adopting continuous processing platforms. Lead with supply continuity guarantees rather than price competition to differentiate against established hospital GPO relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sterile fill-finish capacity expansion, driven by USP Chapter 1207 container-closure validation requirements and isolator system lead times. Long-term viability across the analysis window favors sponsors with backward integration into API production and geographic diversification from Indian supply bases. Acquisition target archetypes include emergency shortage responders with therapeutic category concentration and North Carolina-based contract manufacturers adopting single-use technologies. Monitor FDA facility inspection prioritization schedules as the critical inflection signal for supply-constrained product premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Quality Management Maturity Certification | FDA Level 3 ratings unlock expedited ANDA reviews and reduce surveillance inspection frequency for sponsors. |
| Geographic Manufacturing Diversification | North Carolina and Massachusetts fill-finish investments reduce tariff exposure from Indian API concentration. |
| Dual-Chamber Device Development | Point-of-use mixing systems address lyophilized product stability limitations and differentiate against conventional vials. |
| Specialty Pharmacy Channel Expansion | Florida clinic network buildouts capture site-neutral reimbursement migration from hospital outpatient departments. |
| Captive API Integration | In-house active pharmaceutical ingredient production insulates sponsors from FDA inspection backlog delays and supply disruption. |
Research Methodology
A standing panel of hospital formulary directors, GPO contracts managers, sterile manufacturing executives, and regulatory affairs specialists provided ongoing calibration against secondary validation from FDA ANDA filings, USP chapter revision notices, CMS reimbursement rulemaking, and hospital procurement database trends. Bottom-up volume estimates by therapeutic category and delivery mode were cross-checked against top-down market sizing from sponsor revenue disclosures and trade data. Triangulation across primary stakeholder interviews and secondary regulatory sources anchored segmentation-specific growth assumptions.
Scenario-bracketing around FDA inspection throughput, tariff implementation timelines, and site-neutral reimbursement adoption rates bounded the projection horizon. Segmentation dimensions modeled include product chemistry, care setting, administration route, therapeutic indication, and geographic manufacturing footprint. CAGRs were derived from trend extrapolation of historic approval volumes, capacity expansion announcements, and channel migration patterns. Forecast inputs incorporated lyophilization capacity constraints, 503B compounding oversight evolution, and Quality Management Maturity program enrollment trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Indian API-dependent sponsors toward North American fill-finish partnerships would shift outcomes. Material shifts in FDA facility inspection prioritization, IRA price negotiation implementation timelines, or tariff structures on pharmaceutical imports would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generics and Biosimilars
West Africa Generic Drug Market
Generics and Biosimilars
GCC Generic Drug Market
Generics and Biosimilars
Europe Specialty Generics Market
Generics and Biosimilars
Adalimumab Market
Generics and Biosimilars
Latin America Generic Drug Market
Generics and Biosimilars
Global Adalimumab Drugs Market
Generics and Biosimilars
Europe Branded Generics Market
Generics and Biosimilars
Super Generics Market