
 West Africa Generic Drug Market | 2026-2036
West Africa Generic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
West Africa Generic Drug Market Intelligence
Unit-dose blister packaging is broadening patient access across rural dispensaries and urban hospital chains alike. Emzor Pharmaceutical Industries leverages backward integration into active pharmaceutical ingredient sourcing to protect margin pools. Fidson Healthcare anchors its position through dedicated antibiotic and antihypertensive manufacturing lines. Aspen Pharmacare Holdings competes via distribution control across Anglophone West African corridors.
West Africa generic drugs are chemically equivalent copies of originator medicines, manufactured after patent expiry and meeting pharmacopeial standards for bioequivalence, stability, and dissolution profiles; they deliver essential therapy at reduced cost to health systems with constrained budgets. Tablet formulations occupy the largest volume share due to manufacturing simplicity and ambient storage tolerance, while injection segments command premium positioning through sterility assurance requirements. Retail pharmacy channels dominate last-mile access, though hospital pharmacy procurement governs bulk volume allocation across the region.
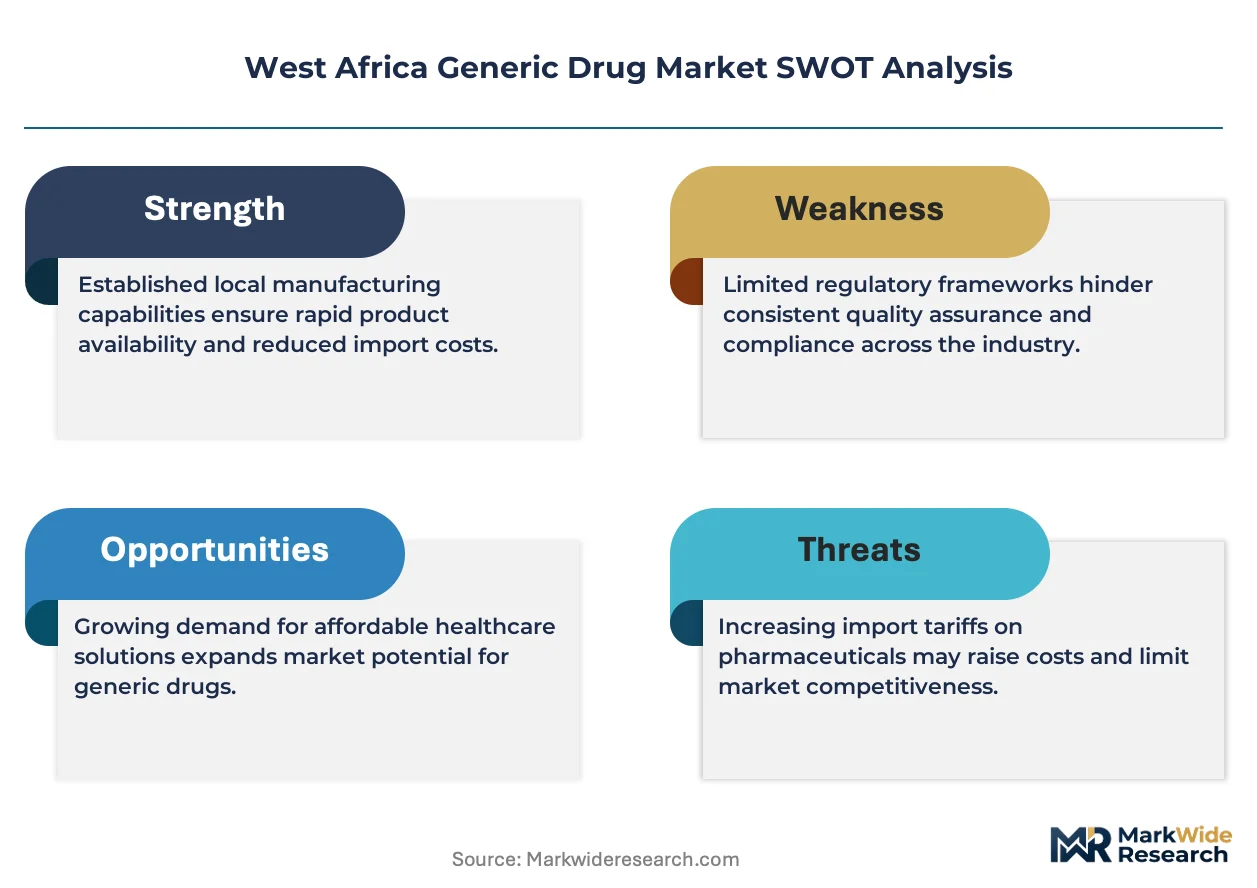
Nigeria's National Agency for Food and Drug Administration and Control enforces mandatory pre-shipment verification, while Ghana's Food and Drugs Authority operates the West African-focused joint inspection program with ECOWAS counterparts. These frameworks shape product registration timelines, batch release protocols, and import documentation burdens for manufacturers seeking multi-country market access. Stakeholders must monitor evolving bioequivalence study requirements and local content mandates that will determine manufacturing investment viability.
Market Dynamics
ECOWAS regulatory harmonization is compressing cross-border registration timelines and redrawing competitive boundaries for manufacturers serving Nigeria, Ghana, and Francophone neighbors. This structural force is accelerating market consolidation while raising compliance barriers for single-country operators.
Growth Catalysts
- NAFDAC Pre-Shipment Verification:Nigeria's mandatory destination inspection protocol is filtering substandard imports and elevating quality-assured generic volumes in public hospital tenders.
- Antiretroviral Procurement Scale-Up:PEPFAR and Global Fund programming is expanding fixed-dose combination demand across Lagos and Abuja treatment centers.
- Active Pharmaceutical Ingredient Sourcing:Regional manufacturers securing Indian and Chinese API supply contracts are insulating production costs from currency volatility.
Market Restraints
- Excipient Import Dependency:West African formulators rely entirely on European and Asian suppliers for binders and coatings, exposing margins to freight cost spikes.
- Single-Country Registration Burden:Ghana's Food and Drugs Authority maintains separate bioequivalence requirements despite ECOWAS harmonization rhetoric, duplicating study costs.
- Thermal Chain Gaps:Injectable generics requiring cold storage face last-mile distribution failures in Niger and Mali hinterlands.
Strategic Opportunities
- Senegal Francophone Hub:Dakar's port infrastructure and French-language regulatory familiarity offers gateway positioning for Mauritania and Guinea-Bissau expansion.
- Unit-Dose Repackaging:Blister conversion lines serving rural dispensaries are capturing patient adherence premiums previously lost to bulk tablet sales.
- Local Content Mandates:Nigeria's pharmaceutical manufacturing incentives under industrial policy frameworks are attracting greenfield tableting investments.
Industry Challenges
- Bioequivalence Study Capacity:Contract research organizations with WHO-prequalification are concentrated in South Africa and India, extending study timelines for regional applicants.
- Skilled Production Technicians:Tableting line operators with GMP certification command premium wages in Lagos and Accra, constraining shift expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Africa Generic Drug Market |
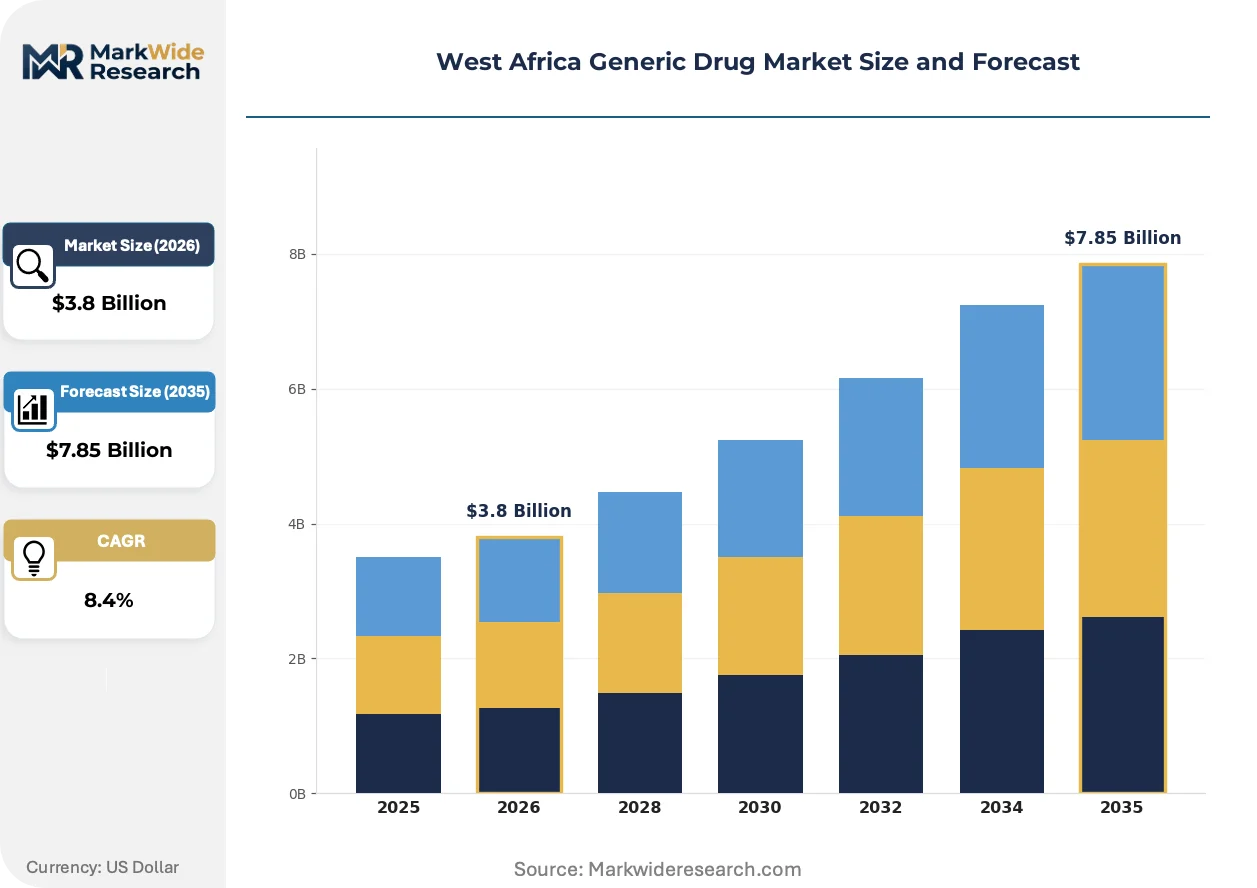
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Syrups, Injections Therapy Area: Cardiovascular, Antidiabetic, Antibiotic, Antihypertensive Distribution Channel: Retail Pharmacy, Hospital Pharmacy, Online Pharmacy, Wholesalers End User: Hospitals, Clinics, Private Practitioners, Home Care |
| Companies Covered | Emzor Pharmaceutical Industries, Fidson Healthcare, Aurobindo Pharma, Aspen Pharmacare Holdings, Abbott Laboratories, AbbVie, AstraZeneca, Bristol Myers Squibb, Alfasigma, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Africa Generic Drug Market Strategic Shifts & Innovations
Digital traceability systems and modular manufacturing platforms are compressing quality assurance cycles while enabling smaller batch production for niche therapeutic categories. These shifts are redistributing competitive advantage toward technology-adopting mid-scale formulators.
Continuous manufacturing is consolidating solid-dose production economics for high-volume antihypertensives and antibiotics. Nigerian hospital procurement consortia are specifying real-time release testing capabilities in tender documents. This technology is consolidating quality control functions into production lines, reducing batch failure rates and shortening delivery windows to public sector buyers.
Ghana's Food and Drugs Authority joint inspection program with ECOWAS counterparts is standardizing GMP audit protocols across Anglophone and Francophone members. Manufacturers achieving mutual recognition status are accessing multi-country tenders without redundant facility inspections. Nigerian and Ghanaian regulators are co-developing bioequivalence study guidelines that will accelerate generic substitution approvals for chronic disease therapies.
Hospital pharmacy consortia in Lagos and Abuja are consolidating procurement through centralized tender platforms, displacing fragmented distributor relationships. These buying coalitions are extracting volume discounts and demanding extended payment terms from generic suppliers. The shift is most visible in oncology and cardiovascular therapeutic categories where public sector spending concentrates.
West Africa Generic Drug Market Segmentation
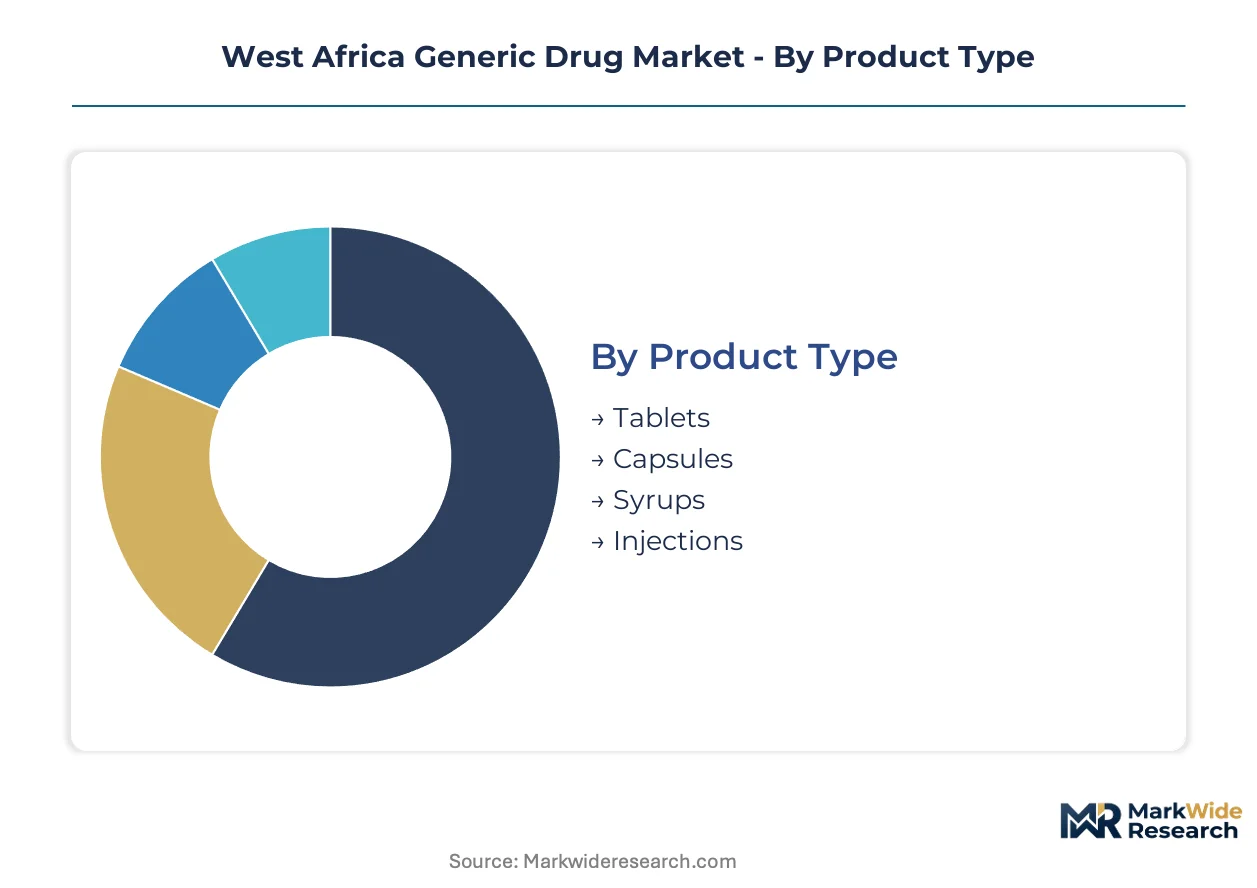
Segmentation in West Africa's generic drug market reveals how capital deployment, regulatory exposure, and distribution economics concentrate competitive advantage. Understanding these fault lines exposes where procurement scale, margin protection, and quality compliance intersect for manufacturers and distributors alike.
Product Type:
Capital intensity varies sharply across formulation technologies, with sterile manufacturing demanding tenfold higher upfront investment than solid-dose lines.
- Tablets:Compressed solid-dose forms dominate procurement volumes due to ambient stability and high-speed production economics. Nigeria's public hospital tenders concentrate tablet demand, where generic substitution policies and bulk purchasing extract maximum cost efficiency from manufacturers.
- Injections:Sterile liquid formulations requiring aseptic filling and terminal sterilization command premium positioning through quality assurance complexity. Cold chain gaps in Niger and Mali hinterlands constrain last-mile distribution, limiting addressable market despite therapeutic necessity.
- Capsules:Gelatin or HPMC shells containing powder or granule fills offer bioavailability advantages for certain APIs. Regional formulators source empty capsules entirely from Indian suppliers, exposing production schedules to import lead time variability.
- Syrups:Liquid oral suspensions serve pediatric and geriatric populations with swallowing difficulties. Ghana's Food and Drugs Authority maintains stricter stability testing requirements for aqueous formulations than ECOWAS harmonization guidelines prescribe.
Tablets absorb the bulk of installed capacity; injections are expanding most quickly as oncology and antiretroviral protocols intensify.
Therapy Area:
Prescription volume concentrates where chronic disease burden intersects with procurement program scale and prescriber familiarity.
- Cardiovascular:Antihypertensive and antiplatelet therapies address rising ischemic heart disease prevalence across urban Nigeria. Lagos hospital pharmacy consortia specify bioequivalence documentation for statin and beta-blocker tenders, elevating compliance costs for entrants.
- Antibiotic:Systemic antibacterial agents face procurement scale from infectious disease protocols but margin pressure from resistance-driven stewardship restrictions. PEPFAR and Global Fund programming channels substantial antibiotic co-prescription through HIV treatment centers.
- Antidiabetic:Oral hypoglycemics and insulin analogs serve accelerating type 2 diabetes prevalence linked to dietary transition. Cold storage requirements for insulin restrict distribution to hospital pharmacies and major retail chains with refrigeration capacity.
- Antihypertensive:ACE inhibitors, ARBs, and calcium channel blockers anchor chronic disease management programs. Nigerian industrial policy frameworks incentivize local tableting of these high-volume molecules through import substitution credits.
Cardiovascular commands the largest procurement expenditure; antidiabetic is climbing the fastest as screening programs expand diagnostic capture.
Distribution Channel:
Channel economics diverge based on working capital intensity, credit risk exposure, and regulatory documentation burdens.
- Hospital Pharmacy:Institutional procurement governed by centralized tender platforms consolidates volume and extends payment terms. Abuja and Lagos buying coalitions extract price concessions through multi-year supply agreements with quality-assured manufacturers.
- Retail Pharmacy:Community-based dispensaries provide last-mile access but fragment demand across thousands of independent operators. NAFDAC pre-shipment verification requirements filter substandard imports before products reach retail shelves.
- Wholesalers:Regional distributors aggregate demand from smaller pharmacies and rural dispensaries, bearing inventory risk and currency exposure. Cross-border trade within ECOWAS corridors depends on harmonized registration timelines now compressing under joint inspection protocols.
- Online Pharmacy:Digital platforms emerging in Nigerian urban centers face regulatory ambiguity around prescription verification and cold chain maintenance. Current volumes remain marginal against institutional and traditional retail channels.
Hospital pharmacy governs bulk volume allocation; retail pharmacy is gaining share fastest as unit-dose blister repackaging penetrates rural access points.
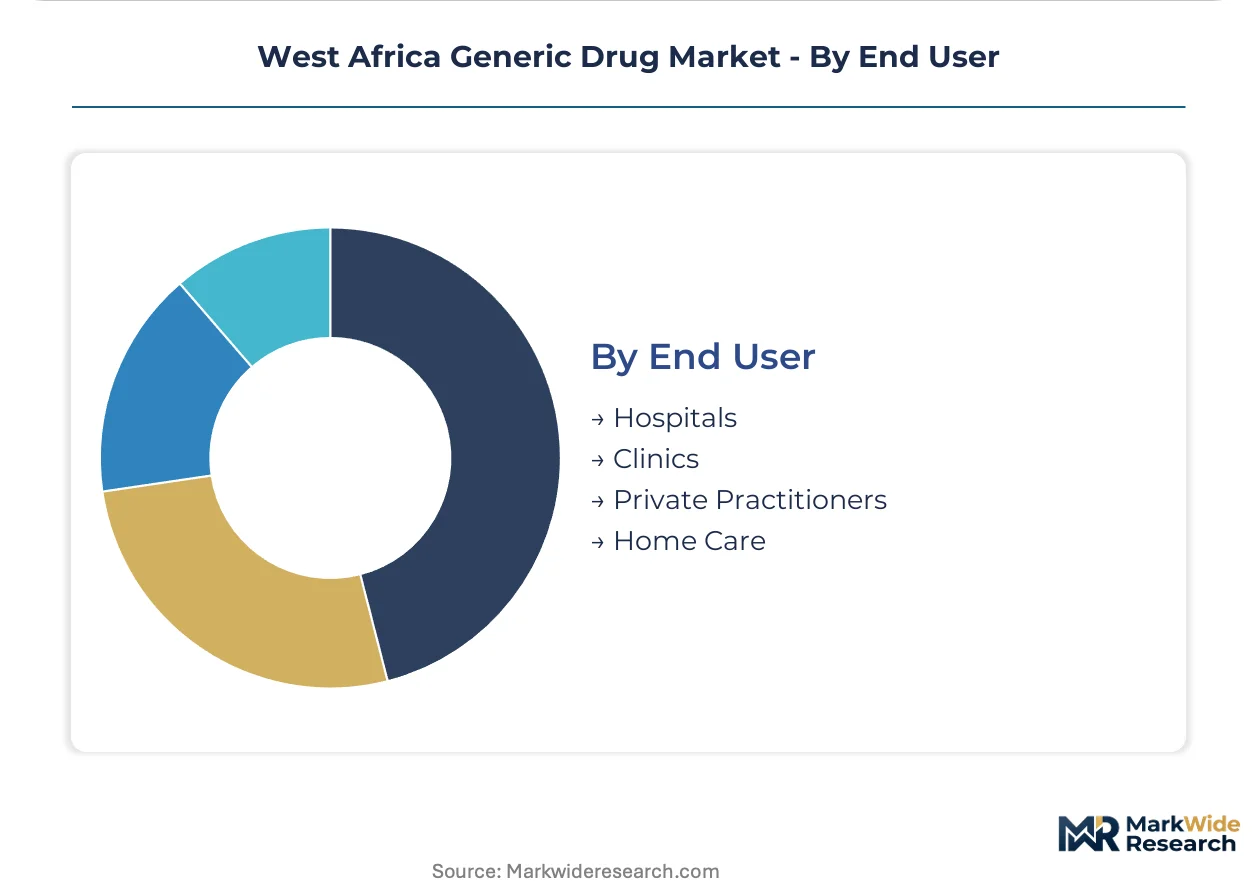
End User:
Patient access patterns map to facility infrastructure, prescriber density, and out-of-pocket payment capacity across the region.
- Hospitals:Tertiary and secondary facilities with in-house pharmacies concentrate chronic disease therapy initiation and complex case management. Nigeria's federal teaching hospitals anchor procurement volumes for oncology and cardiovascular generics.
- Clinics:Primary health centers and diagnostic facilities extend access to semi-urban populations with limited hospital reach. Ghana's National Health Insurance Scheme reimbursement structures shape clinic prescribing patterns toward preferred generic formularies.
- Private Practitioners:Individual physician practices in Lagos and Accra commercial districts serve insured populations with brand-sensitive prescribing habits. Generic substitution policies are tightening through professional education and formulary restrictions.
- Home Care:Self-administered chronic therapies and family-managed palliative care depend on retail pharmacy access and caregiver training. Unit-dose packaging innovations are improving adherence for antiretroviral and antihypertensive regimens outside supervised settings.
Hospitals retain the dominant procurement position; home care is expanding most quickly as chronic disease protocols emphasize community-based management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
West Africa's generic drug production capacity concentrates in Nigeria and Ghana while consumption spreads across fifteen ECOWAS member states. This geographic mismatch creates logistics-intensive distribution corridors and regulatory arbitrage opportunities for manufacturers with multi-country registration capabilities.
Nigeria
Lagos and Abuja hospital pharmacy consortia drive procurement volumes for antihypertensive and antiretroviral generics. NAFDAC's mandatory pre-shipment verification protocol filters substandard imports before products enter public hospital tenders. Emzor Pharmaceutical Industries anchors domestic tableting capacity through backward integration into active pharmaceutical ingredient sourcing from Indian suppliers.
Ghana
Accra's Food and Drugs Authority operates the West African-focused joint inspection program with ECOWAS counterparts, accelerating cross-border registration timelines. The National Health Insurance Scheme reimbursement structures shape clinic prescribing patterns toward preferred generic formularies. Tema's port infrastructure serves as a distribution hub for landlocked Burkina Faso and Mali markets.
Senegal
Dakar's Francophone regulatory familiarity and port access offer gateway positioning for Mauritania and Guinea-Bissau expansion. The country's national pharmaceutical regulator maintains French-language documentation standards that reduce friction for European-sourced generics. Local manufacturing remains limited, creating import dependency for essential medicines.
Côte d'Ivoire
Abidjan's urban hospital networks concentrate demand for oncology and cardiovascular generics as chronic disease prevalence rises. The national medicines regulatory authority participates in ECOWAS harmonization initiatives while maintaining distinct bioequivalence study requirements. Retail pharmacy chains in the Plateau district serve as last-mile access points for insured populations.
Cameroon
Douala's commercial corridors link Anglophone and Francophone distribution networks across the regional border. Public hospital procurement operates through centralized tender platforms with extended payment terms that strain manufacturer working capital. Yaoundé's teaching hospitals anchor specialized therapeutic demand for injectable generics requiring cold chain integrity.
West Africa Generic Drug Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across West Africa's generic drug market. The vendor base stratifies into three tiers: multinational pharmaceutical corporations with regional headquarters, mid-scale African formulators with dedicated manufacturing lines, and Indian exporters with established distribution partnerships. Strategic moves concentrate on regulatory pre-qualification achievements and hospital procurement consortium penetration rather than price competition alone.
Within the African formulator tier, Emzor Pharmaceutical Industries and Fidson Healthcare exemplify backward-integrated production strategies. Among Indian exporters serving the region, Aurobindo Pharma occupies a position built on API-to-finished-dose supply chain control. Aspen Pharmacare Holdings represents the South Africa-based multinational archetype competing through distribution network density across Anglophone corridors. Abbott Laboratories and AbbVie sit within the research-derived portfolio segment, leveraging established hospital relationships for generic substitution opportunities.
| Leading Market Players |
|---|
| Emzor Pharmaceutical Industries |
| Fidson Healthcare |
| Aurobindo Pharma |
| Aspen Pharmacare Holdings |
| Abbott Laboratories |
| AbbVie |
| AstraZeneca |
| Bristol Myers Squibb |
| Alfasigma |
| Others |
Cost & Logistics Intelligence
Quality-assured certification tiers create a pronounced bifurcation between hospital procurement premiums and retail pharmacy commodity pricing, with NAFDAC pre-shipment verification requirements concentrating margin protection among verified manufacturers while unverified imports compete on price in fragmented dispensary channels. This divergence manifests in supply chain configurations where verified producers maintain direct hospital contracts while commodity distributors aggregate volume through Lagos and Accra wholesale corridors.
Pricing Analysis
Margin tightening in the retail pharmacy tier reflects excipient import dependency and currency volatility exposure, while hospital procurement premiums hold steady for bioequivalence-documented suppliers. Three-tier pricing structure across WHO-prequalified, NAFDAC-verified, and unverified economy levels separates tender-eligible from cash-market products. Cost-down pressure on tablet formulations accelerates because Nigerian industrial policy incentives attract new domestic tableting capacity. Public hospital buyers exhibit highest price sensitivity through consolidated tender platforms, while private practitioners in Lagos commercial districts retain brand-premium tolerance.
Supply Chain Analysis
Direct-to-hospital channels handle bulk antiretroviral and cardiovascular demand, while wholesale distributors aggregate fragmented retail pharmacy orders across ECOWAS corridors. Active pharmaceutical ingredient supply concentrates in India and China, with regional formulators drawing from Mumbai and Shanghai trading hubs. Empty gelatin capsules, tablet coatings, and sterile vials represent critical input dependencies entirely sourced from Asian and European suppliers. Single-source vulnerability in excipient supply exposes production schedules to freight cost spikes and import documentation delays. Distribution runs through Tema and Lagos port infrastructure with last-mile extension via accredited wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous manufacturing technology is displacing batch-production legacy systems, compressing quality assurance cycles and enabling real-time release testing that Nigerian hospital consortia now specify in tender documents.
For Market Incumbents: Deploy backward integration into API sourcing to defend margin pools against currency volatility and Indian exporter price competition. Secure WHO-prequalification status for antiretroviral and antihypertensive portfolios to maintain eligibility for PEPFAR and Global Fund programming. Expand shift capacity at Lagos tableting facilities despite premium wages for GMP-certified operators, as demand concentration in hospital procurement justifies fixed-cost absorption. For New Entrants and Emerging Players: Enter via unit-dose blister repackaging lines serving rural dispensaries in Niger and Mali hinterlands, where patient adherence premiums capture value previously lost to bulk tablet sales. Target the Senegal Francophone hub for gateway positioning into Mauritania and Guinea-Bissau markets with limited local manufacturing. Pursue ECOWAS joint inspection program mutual recognition to access multi-country tenders without redundant facility audits. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale African formulators achieving NAFDAC verification and backward API supply contracts, given Nigerian local content mandate acceleration and industrial policy incentives. Long-term viability centers on manufacturers with demonstrated hospital consortium penetration and cold chain distribution capabilities for injectable generics. Monitor bioequivalence study guideline finalization between Nigerian and Ghanaian regulators as inflection indicator for generic substitution approval velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Sourcing | Emzor Pharmaceutical Industries protects margin pools from rupee-naira volatility through Indian supplier contracts. |
| Continuous Manufacturing Platform Deployment | Real-time release testing capabilities satisfy Abuja hospital consortium tender specifications for antihypertensive supply. |
| ECOWAS Joint Inspection Program Certification | Mutual recognition status eliminates redundant facility audits for Ghana-to-Nigeria cross-border registration. |
| Unit-Dose Blister Repackaging Investment | Rural dispensary penetration captures patient adherence premiums in Niger and Mali cold chain gap zones. |
| WHO Prequalification Pathway Completion | PEPFAR and Global Fund eligibility unlocks fixed-dose combination antiretroviral procurement scale. |
Research Approach
Document review covered NAFDAC registration databases, Ghana FDA inspection reports, and ECOWAS harmonization protocols, complemented by interviews with pharmaceutical manufacturing executives, hospital procurement managers, and regulatory affairs specialists. Secondary validation drew from WHO prequalification listings, Global Fund tender documents, and Nigerian industrial policy frameworks. Bottom-up demand modeling triangulated against top-down health expenditure estimates across the analysis window.
Segmentation outputs reflect product type, therapy area, distribution channel, and end user dimensions modeled across the projection horizon. CAGRs were derived from procurement volume trajectories, patent expiry schedules, and policy implementation timelines. Forecast inputs incorporated bioequivalence study capacity constraints, excipient import lead time variability, and hospital consortium consolidation patterns.
Revisions become necessary when ECOWAS regulatory harmonization stalls, currency volatility exceeds historical bands, or local content mandates accelerate faster than domestic manufacturing capacity can respond. Forecasts reflect assumptions about tender platform adoption rates and cold chain infrastructure investment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generics and Biosimilars
Adalimumab Market
Generics and Biosimilars
Global Adalimumab Drugs Market
Generics and Biosimilars
Europe Specialty Generics Market
Generics and Biosimilars
Latin America Generic Drug Market
Generics and Biosimilars
GCC Generic Drug Market
Generics and Biosimilars
Europe Branded Generics Market
Generics and Biosimilars
Super Generics Market
Generics and Biosimilars
US Specialty Injectable Generics Market