
 GCC Generic Drug Market | 2026-2036
GCC Generic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Generic Drug Market Intelligence
Subscription-based pharmacovigilance reporting is repositioning how manufacturers maintain regulatory compliance across Gulf markets. Julphur Pharmaceuticals leverages its UAE manufacturing base to anchor distribution networks across the Emirates. Teva Pharmaceutical Industries sustains competitive presence through specialized injectable portfolios serving hospital systems. Hikma Pharmaceuticals differentiates via vertical control over active pharmaceutical ingredient sourcing for regional oral solid production.
Generic drugs are chemically equivalent copies of branded medicines, containing identical active pharmaceutical ingredients, dosage forms, and bioequivalence profiles validated through dissolution testing and pharmacokinetic studies; they serve primarily to reduce healthcare expenditure while maintaining therapeutic parity. Oral delivery mode dominates volume flows across GCC hospital and pharmacy channels, reflecting patient preference for self-administered regimens and established reimbursement pathways. Injectable segments capture concentrated margin pools in oncology and critical care settings where cold-chain infrastructure and aseptic manufacturing requirements limit supplier proliferation. Cardiovascular therapy area leads absolute demand scale, driven by hypertension and dyslipidemia prevalence across aging Gulf populations.
The Saudi Food and Drug Authority enforces bioequivalence protocols that determine market access eligibility, while the UAE Ministry of Health and Prevention oversees GMP inspections that shape manufacturing site approvals across Dubai and Abu Dhabi. The GCC Central Committee for Drug Registration harmonizes technical standards that reduce redundant filing burdens but elevate documentation intensity for cross-border suppliers. Stakeholders must monitor evolving pharmacovigilance mandates and tender restructuring across national health insurance schemes to anticipate procurement rhythm shifts.
Market Dynamics
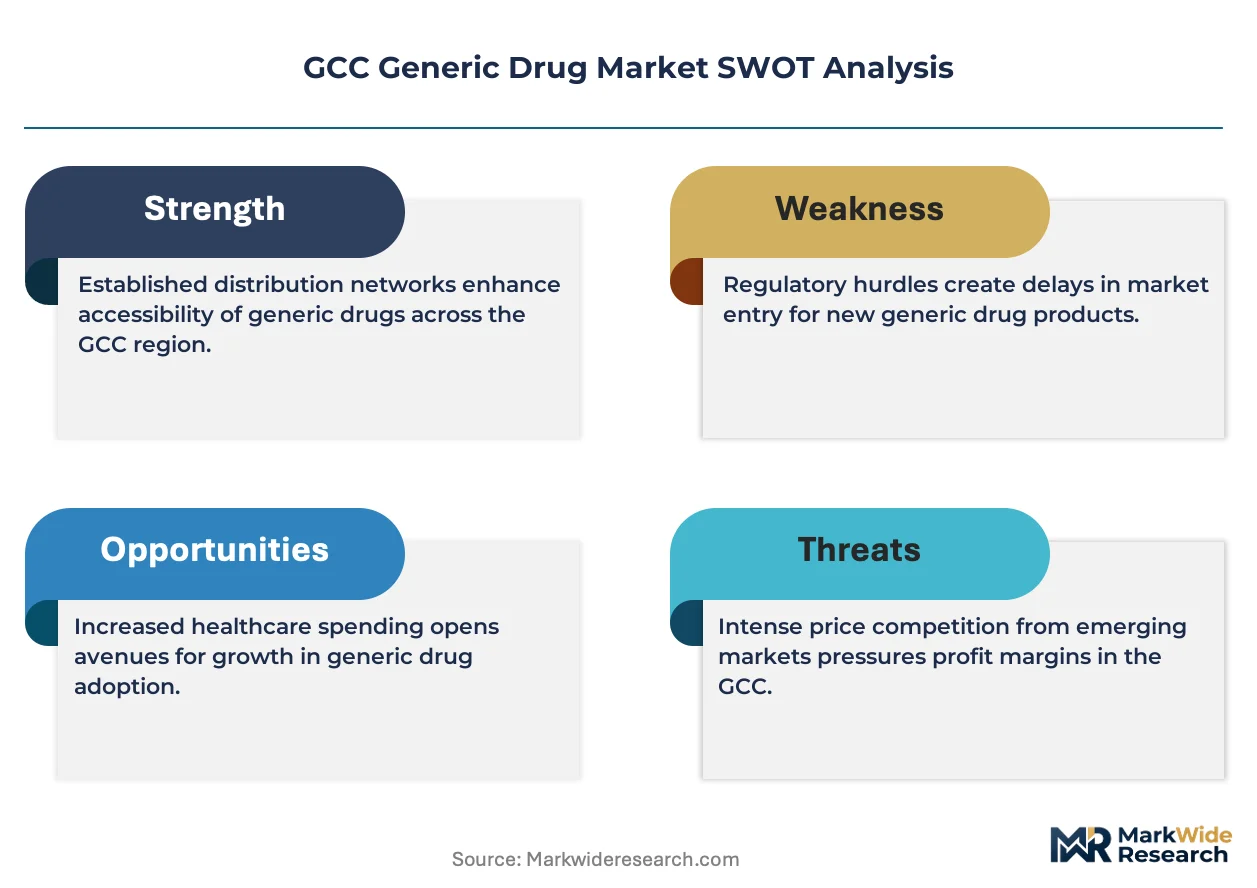
Saudi Arabia's hospital procurement centralization is compressing supplier margins while elevating volume commitments for compliant manufacturers. The SFDA's bioequivalence protocol tightening has created a two-tier market where certified facilities capture tender flows and non-compliant sites face exclusion from government formularies.
Growth Catalysts
- SFDA Bioequivalence Mandates:Tighter dissolution testing requirements are filtering out substandard manufacturers and consolidating tender awards to verified suppliers across Saudi hospital networks.
- Diabetes Prevalence Clusters:Gulf aging demographics are expanding chronic disease management programs that prioritize cost-effective generic metformin and statin therapies in outpatient settings.
- MOHAP GMP Harmonization:UAE manufacturing site certifications are streamlining cross-border approvals across Dubai and Abu Dhabi distribution hubs, reducing redundant inspection cycles.
Market Restraints
- API Import Dependency:Regional formulation facilities rely on Indian and Chinese active pharmaceutical ingredient suppliers, exposing margin structures to currency volatility and shipping disruptions.
- Cold-Chain Infrastructure Gaps:Injectable oncology generics require temperature-controlled logistics that remain underdeveloped in secondary Saudi cities and northern Emirates.
- SFDA Inspection Backlogs:Manufacturing site approval queues are extending market entry timelines for new entrants by twelve to eighteen months.
Strategic Opportunities
- Kuwait Ministry of Health Tenders:Underpenetrated hospital procurement in Kuwait City and Al Jahra is opening volume commitments for Saudi-certified suppliers with existing GCC Central Committee registrations.
- Biosimilar Convergence:Monoclonal antibody manufacturing capabilities are migrating from chemical synthesis to bioreactor platforms, enabling regional players to capture oncology margin pools.
- Direct-to-Pharmacy Distribution:Bypassing wholesale intermediaries is reducing working capital cycles for oral solid dosage forms in UAE retail channels.
Industry Challenges
- Bioequivalence Study Talent Scarcity:Clinical pharmacology expertise for pharmacokinetic validation remains concentrated in Riyadh and Dubai, constraining expansion into secondary manufacturing zones.
- Legacy ERP Integration:Hospital procurement systems in Qatar and Oman require custom API connections for real-time inventory tracking, delaying supplier onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Generic Drug Market |
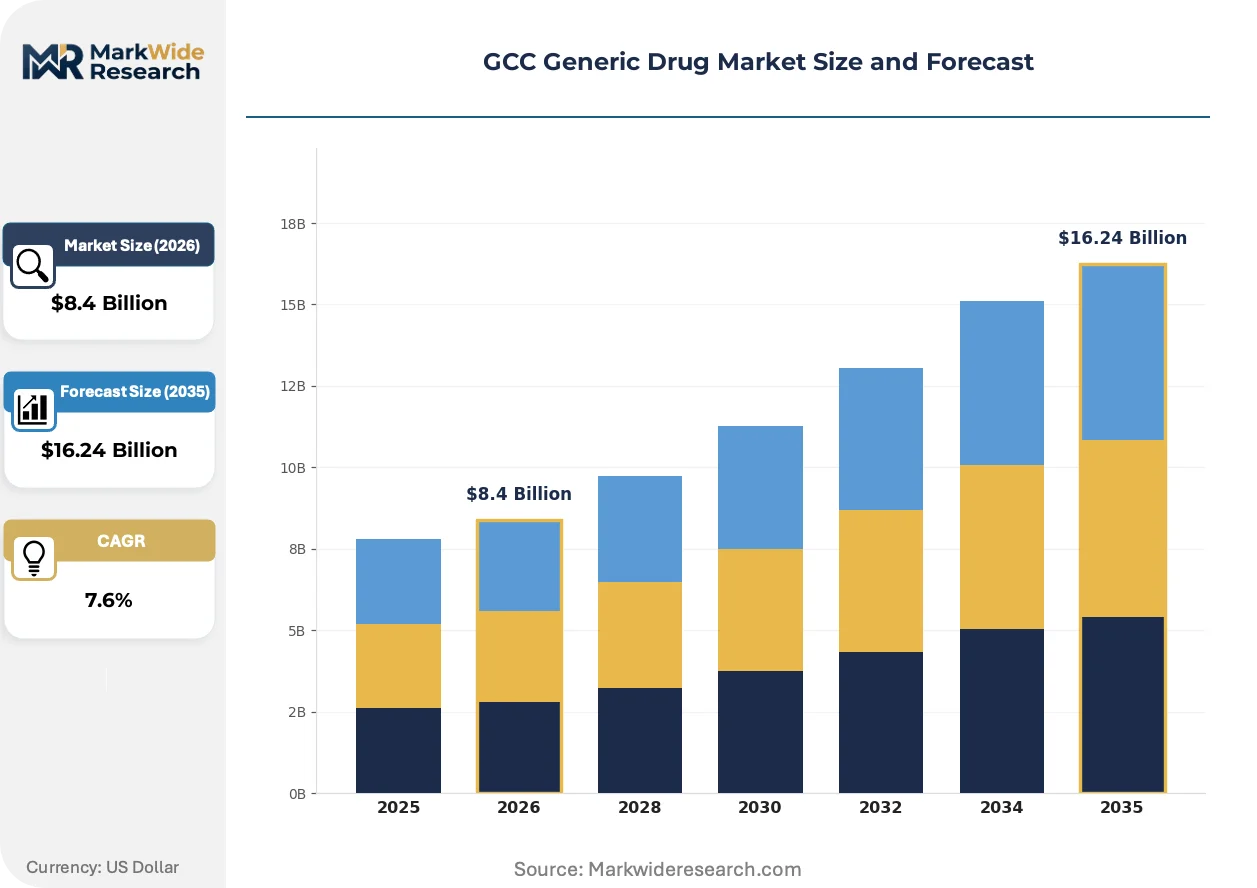
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.24 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injections, Topicals End User: Hospitals, Pharmacies, Clinics, Distributors Delivery Mode: Oral, Injectable, Transdermal, Sublingual Therapy Area: Cardiovascular, Oncology, Diabetes, Neurology |
| Companies Covered | Julphur Pharmaceuticals, Teva Pharmaceutical Industries, Hikma Pharmaceuticals, Sun Pharmaceutical Industries, Sandoz, Tabuk Pharmaceuticals, Neopharma, SPIMACO, SPIMACO Addwaeih, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Generic Drug Market Strategic Shifts & Innovations
Continuous manufacturing platforms are displacing batch processing in regional oral solid facilities, compressing production cycles and reducing cross-contamination risks. This shift is reconfiguring capital deployment patterns and regulatory filing strategies across Gulf manufacturing zones.
Hot-melt extrusion technology is overtaking conventional wet granulation for poorly soluble APIs, enabling higher bioavailability in cardiovascular and diabetes generics. Saudi formulation specialists are adopting these platforms to meet SFDA dissolution profile requirements. The technology is overtaking legacy equipment investments and forcing mid-scale facilities into upgrade cycles or contract manufacturing arrangements.
The GCC Central Committee for Drug Registration is harmonizing technical documentation standards across member states, reducing redundant stability study submissions. Manufacturers can now file once for multi-country approval, though the documentation intensity has increased for cross-border suppliers. UAE and Saudi sites are consolidating regulatory affairs functions to manage this centralized pathway.
Hospital buying consortia in Riyadh and Jeddah are consolidating annual tender awards into multi-year framework agreements with volume guarantees. Traditional spot purchasing through wholesale distributors is losing share to direct manufacturer contracts with penalty clauses for stock-outs. This concentration is most visible in Saudi Arabia's Ministry of Health central procurement, where three-year agreements now dominate cardiovascular generic sourcing.
GCC Generic Drug Market Segmentation
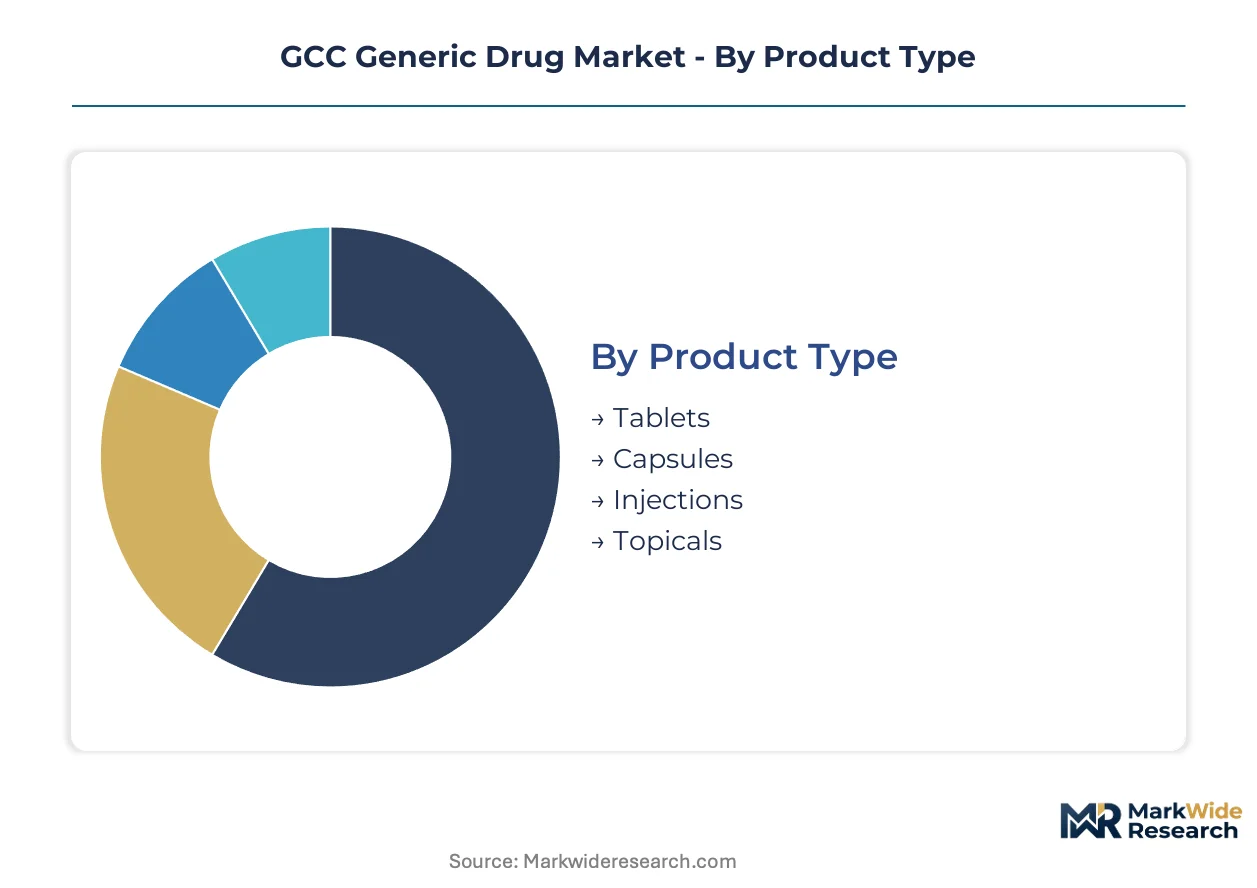
Segmentation in the GCC generic drug market reveals how procurement power, reimbursement pathways, and therapeutic priorities reshape competitive positioning across Gulf health systems. Understanding these divides exposes where margin pools concentrate and where volume commitments flow.
Product Type:
Hospital procurement officers and retail pharmacists diverge sharply in their technical specifications, with tender requirements driving formulation choices in institutional channels while patient convenience governs pharmacy shelves.
- Tablets:Compressed solid dosage forms dominate chronic disease management programs across Saudi Arabia's Ministry of Health tenders. Riyadh and Jeddah hospital consortia prioritize immediate-release and extended-release tablet specifications for hypertension and diabetes protocols, with SFDA dissolution testing requirements filtering supplier eligibility.
- Injections:Sterile parenteral preparations command premium positioning in oncology and critical care settings where cold-chain integrity and aseptic manufacturing determine supplier selection. Abu Dhabi and Dubai hospital networks concentrate demand for cytotoxic and biologic injectable generics, though secondary Saudi cities face distribution infrastructure constraints.
- Capsules:Gelatin and HPMC shell formulations serve patients with swallowing difficulties and APIs requiring enteric protection. UAE retail pharmacies move significant capsule volumes for proton pump inhibitors and antibiotics.
- Topicals:Creams, ointments, and gels address dermatological and localized pain conditions with lower regulatory barriers than systemic formulations. Saudi community pharmacies and private clinics in Kuwait drive regional demand.
Volume sits with tablets; growth tilts toward injections as oncology biosimilars expand regional manufacturing capabilities.
End User:
Procurement centralization across Gulf health ministries has restructured how manufacturers allocate sales resources, with direct tender participation now outweighing wholesale relationships.
- Hospitals:Institutional purchasers in Saudi Arabia, UAE, and Qatar execute centralized tenders for chronic disease formularies, with three-year framework agreements replacing spot purchasing. SFDA-certified suppliers capture volume through direct manufacturer contracts with stock-out penalty clauses.
- Pharmacies:Retail channels across Dubai, Abu Dhabi, and Riyadh serve outpatient prescription fulfillment and over-the-counter substitution, with reimbursement pathways favoring bioequivalent generics over originator brands. Direct-to-pharmacy distribution models are compressing wholesale margins.
- Clinics:Outpatient facilities in secondary Saudi cities and northern Emirates handle specialized therapeutic administration and chronic disease monitoring, sourcing through regional distributors rather than direct manufacturer relationships.
- Distributors:Wholesale intermediaries maintain relevance in cross-border logistics and inventory financing, though their margin share is eroding as hospital consortia and pharmacy chains consolidate procurement.
Hospital tenders anchor absolute volume; pharmacy direct distribution is climbing the fastest as retail chains consolidate purchasing power.
Delivery Mode:
Patient self-administration preferences and reimbursement structures have entrenched oral dominance, while clinical settings sustain injectable demand for acute and biologic therapies.
- Oral:Self-administered tablets, capsules, and liquids capture the majority of chronic disease prescriptions across GCC outpatient settings. Saudi Arabia's aging demographics and diabetes prevalence expand metformin and statin volumes through pharmacy channels.
- Injectable:Parenteral administration in hospital oncology wards and critical care units requires specialized manufacturing and cold-chain logistics. MOHAP GMP certifications for UAE production sites are streamlining approvals for regional suppliers.
- Transdermal:Patch-based delivery for pain management and hormone replacement bypasses gastrointestinal metabolism, finding niche adoption in private clinics across Kuwait and Qatar.
- Sublingual:Rapid-onset absorption under the tongue serves acute cardiovascular events and emergency protocols, with limited but stable demand in hospital emergency departments.
Oral delivery commands volume share; injectable segments show steepest expansion trajectory as biologic manufacturing migrates to regional bioreactor platforms.
Therapy Area:
Disease burden demographics and government health priorities determine where procurement budgets concentrate, with chronic conditions outranking acute interventions in tender volume.
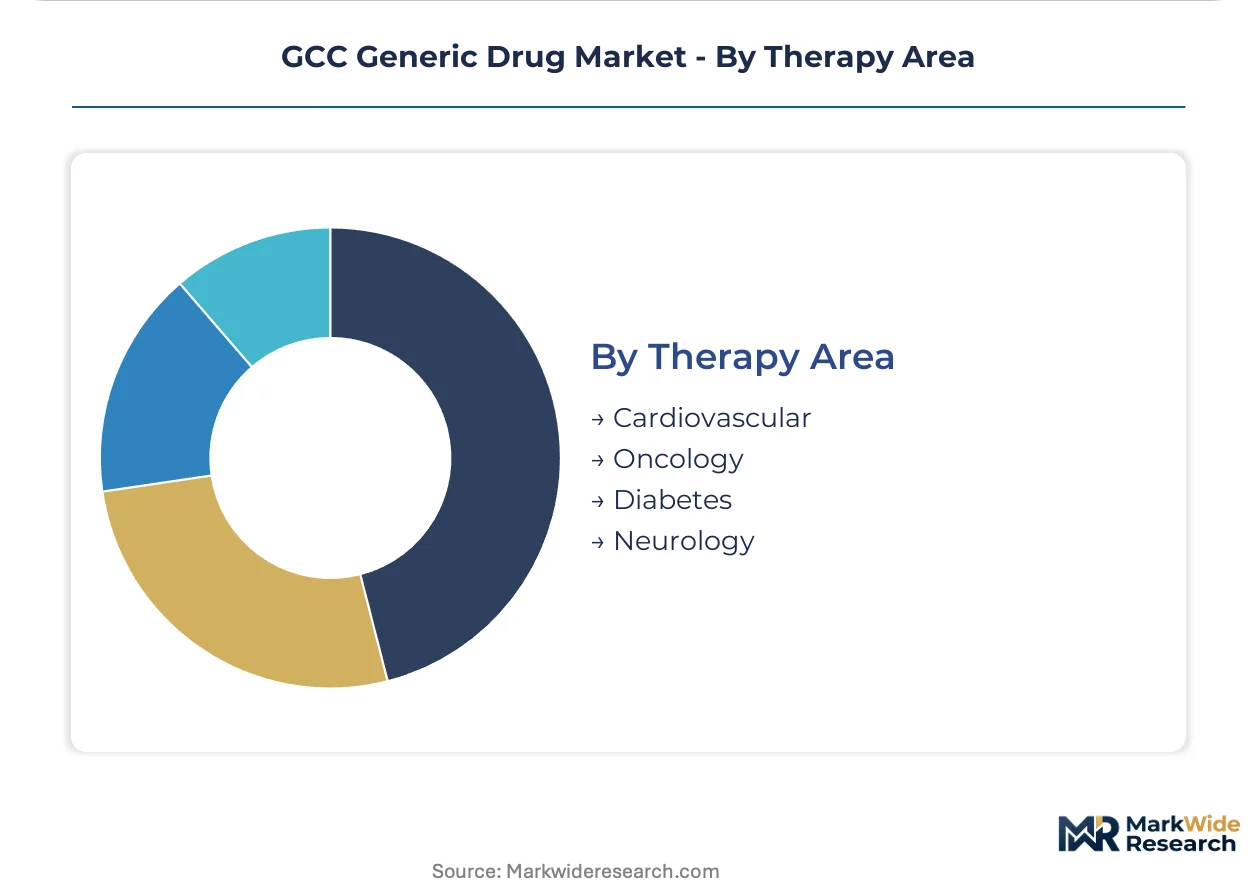
- Cardiovascular:Hypertension and dyslipidemia therapies lead absolute demand scale across GCC populations, with Saudi Arabia's central procurement allocating substantial tender volumes to generic statins, ACE inhibitors, and beta-blockers for outpatient chronic disease programs.
- Diabetes:Metformin and insulin analog generics serve Gulf aging demographics and lifestyle disease clusters, with government formularies prioritizing cost-effective glucose management in Saudi and UAE health systems.
- Oncology:Cytotoxic and supportive care generics command concentrated margins in hospital infusion centers, though cold-chain requirements and bioequivalence complexity limit supplier proliferation compared to oral solid categories.
- Neurology:Antiepileptics, antiparkinson agents, and migraine therapies serve specialized patient populations with stricter bioequivalence scrutiny for narrow therapeutic index compounds.
Cardiovascular therapies anchor procurement budgets; oncology is gaining share fastest as biosimilar manufacturing capabilities expand across Saudi and UAE production sites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh anchors generic drug procurement across the Gulf Cooperation Council, with Saudi Arabia's Ministry of Health centralizing hospital tenders for cardiovascular and diabetes therapies. The Saudi Food and Drug Authority enforces bioequivalence protocols that filter supplier eligibility across the region's largest pharmaceutical market.
Saudi Arabia
Jeddah and Riyadh hospital consortia execute multi-year framework agreements for chronic disease formularies, with three-year contracts replacing spot purchasing. The SFDA's tightened dissolution testing requirements are consolidating tender awards to certified manufacturers. Tabuk Pharmaceuticals and SPIMACO operate production facilities in the kingdom's emerging manufacturing zones.
United Arab Emirates
Dubai and Abu Dhabi distribution hubs serve as re-export gateways for GCC Central Committee-registered products. The Ministry of Health and Prevention streamlines GMP inspections across manufacturing sites in the Emirates. Julphur Pharmaceuticals leverages its UAE production base to anchor distribution networks across the federation.
Kuwait
Kuwait City and Al Jahra hospital procurement remains underpenetrated relative to Saudi and UAE volumes, opening tender opportunities for cross-border suppliers. The Ministry of Health issues centralized tenders favoring manufacturers with existing GCC Central Committee registrations. Regional distributors maintain working capital financing relationships with pharmacy chains in the emirate.
Qatar
Doha's Hamad Medical Corporation centralizes procurement for institutional generic demand, though legacy ERP systems require custom API connections for supplier onboarding. The country's national pharmaceutical regulator harmonizes technical standards with GCC Central Committee protocols. Hospital buying consortia prioritize cold-chain integrity for injectable oncology generics.
Oman
Muscat's Ministry of Health tenders concentrate demand for oral solid dosage forms serving chronic disease management programs. Secondary cities face distribution infrastructure constraints for temperature-sensitive formulations. Regional players with Saudi SFDA certification capture volume through cross-border supply arrangements.
GCC Generic Drug Market Key Industry Players
Capital-heavy producers with integrated manufacturing assets compete with asset-light distributors relying on contract formulation partnerships. The market structure consolidates around three to five vertically integrated regional players and a fragmented tier of import-dependent wholesalers. Strategic archetypes include: domestic manufacturers with SFDA-certified facilities, multinational subsidiaries with specialized injectable portfolios, and Indian exporters with cost-optimized oral solid supply. Competitive moves center on backward integration into active pharmaceutical ingredient sourcing and direct-to-pharmacy distribution bypassing wholesale intermediaries.
Among multinational pharmaceutical corporations, Teva Pharmaceutical Industries and Hikma Pharmaceuticals occupy positions exemplifying the specialized-injectable and vertical-integration archetypes respectively. Teva sustains competitive presence through hospital system relationships, while Hikma differentiates via upstream control over active pharmaceutical ingredient sourcing. Sun Pharmaceutical Industries represents the Indian export model with cost-optimized manufacturing. Regional specialists including Julphur Pharmaceuticals anchor UAE-based production and distribution networks. Sandoz operates within the multinational generic subsidiary tier serving institutional procurement channels.
| Leading Market Players |
|---|
| Julphur Pharmaceuticals |
| Teva Pharmaceutical Industries |
| Hikma Pharmaceuticals |
| Sun Pharmaceutical Industries |
| Sandoz |
| Tabuk Pharmaceuticals |
| Neopharma |
| SPIMACO |
| SPIMACO Addwaeih |
| Others |
Cost & Logistics Intelligence
Active pharmaceutical ingredient costs originating from Indian and Chinese manufacturing clusters cascade through three distinct pricing tiers before reaching Gulf hospital procurement officers. SFDA bioequivalence certification requirements segment manufacturers into premium-certified, standard-compliant, and economy-import categories, with each tier commanding divergent margin structures across Saudi tender processes.
Pricing Analysis
Value-based pricing anchors on therapeutic outcomes validated through pharmacokinetic studies rather than manufacturing cost alone. Three-tier pricing structure across premium-certified, standard-compliant, and economy-import levels reflects SFDA dissolution testing grades and GMP inspection histories. Pricing pressure stems from Saudi Ministry of Health tender centralization demanding multi-year volume commitments with penalty clauses. Hospital procurement officers exhibit highest price sensitivity for chronic disease oral solids, while oncology injectable buyers prioritize cold-chain reliability over unit cost.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive oncology injectables remain underdeveloped across secondary Saudi cities and northern Emirates, forcing write-offs when cold-chain integrity fails. API sourcing concentrates in India, China, and Switzerland for specialized cardiovascular and diabetes compounds. Regional formulation facilities draw from Far Eastern chemical synthesis and European fine-chemical suppliers. Single-source vulnerability pervades certain oncology API categories where sole manufacturers control global output. Distribution runs through Dubai and Abu Dhabi re-export hubs serving Kuwait, Qatar, and Oman markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC generic drug market operates as a cost-of-compliance story where SFDA bioequivalence mandates erect formidable barriers to tender participation, consolidating awards among certified manufacturers while excluding undercapitalized competitors from government formularies.
For Market Incumbents: Deepen backward integration into active pharmaceutical ingredient sourcing to insulate margin structures from currency volatility and shipping disruptions affecting Indian and Chinese suppliers. Expand production capacity in Saudi Arabia's emerging manufacturing zones to capture proximity advantages for Ministry of Health tenders. The threat of Indian export cost optimization demands captive supply security.
For New Entrants and Emerging Players: Hospital buying consortia in Kuwait City and Al Jahra represent the most penetrable procurement channel for cross-border suppliers with existing GCC Central Committee registrations. Direct-to-pharmacy distribution models in UAE retail chains offer working capital efficiency advantages over wholesale-dependent competitors. A specialized injectable portfolio targeting oncology biosimilars provides differentiation against oral-solid-dominated competition.
For Investors and Strategic Acquirers: Manufacturing site approval queue reduction at the SFDA is the leading indicator that market entry timelines will compress, improving acquisition multiples for regional players with certified facilities. Long-term viability centers on vertically integrated producers with in-house API capabilities and multi-country GCC registrations. Watch for MOHAP GMP harmonization completion as the signal for UAE manufacturing asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Bioequivalence Certification Investment | Unlocks Saudi Ministry of Health tender eligibility and three-year framework agreement participation. |
| API Backward Integration | Reduces exposure to Indian and Chinese supplier currency volatility and shipping disruption risks. |
| Continuous Manufacturing Platform Adoption | Compresses oral solid production cycles while meeting SFDA dissolution profile requirements. |
| Direct-to-Pharmacy Distribution Expansion | Bypasses wholesale intermediaries in UAE retail channels to accelerate working capital cycles. |
| Oncology Biosimilar Manufacturing Buildout | Captures premium margin pools in hospital infusion centers as bioreactor capabilities migrate regional. |
Research Approach
Document review covered SFDA regulatory filings, GCC Central Committee registration databases, and Ministry of Health tender documentation, complemented by interviews with regulatory affairs leads, hospital procurement managers, formulary directors, and pharmaceutical manufacturing executives. Secondary validation drew from customs trade records, pharmaceutical import statistics, and bioequivalence study registries. Bottom-up demand modeling across therapy areas and dosage forms was triangulated against top-down market sizing from production capacity assessments.
Cross-referencing historical tender award patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included therapy area, delivery mode, end-user channel, and regulatory certification tier. CAGRs were derived from volume trajectory analysis incorporating tender restructuring timelines and chronic disease prevalence demographics. Forecast inputs encompassed SFDA inspection queue dynamics and MOHAP GMP harmonization progress.
Caveats apply where SFDA bioequivalence protocol amendments, API supply disruptions, or Gulf currency peg adjustments could materially shift the outlook. Forecasts reflect assumptions around tender centralization continuity and chronic disease management program expansion rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generics and Biosimilars
Adalimumab Market
Generics and Biosimilars
Europe Branded Generics Market
Generics and Biosimilars
US Specialty Injectable Generics Market
Generics and Biosimilars
West Africa Generic Drug Market
Generics and Biosimilars
Global Adalimumab Drugs Market
Generics and Biosimilars
Latin America Generic Drug Market
Generics and Biosimilars
Super Generics Market
Generics and Biosimilars
Europe Specialty Generics Market